
 Car Canopies Market | 2026-2036
Car Canopies Market Size, Share, and Industry Trends Forecast 2026-2036
Car Canopies Market Analysis
Residential application demand is pivoting toward weather-resistant permanent installations as homeowners prioritize vehicle protection and outdoor workspace flexibility. LEER Group anchors its position through specialized fiberglass composite manufacturing for durable residential and commercial enclosures. ShelterLogic Group competes through broad retail distribution and rapid-install fabric canopy systems targeting seasonal consumers. Knapheide Manufacturing dominates fleet and utility vehicle upfitting with steel canopy solutions for commercial and municipal buyers.
A car canopy is a freestanding or attached shelter structure engineered to protect vehicles from precipitation, ultraviolet radiation, and windborne debris, typically fabricated from powder-coated steel frames, extruded aluminum members, or tensioned polymer membranes with specified load ratings for snow and wind. Its primary commercial purpose spans residential parking coverage, automotive retail display protection, and temporary event infrastructure requiring rapid deployment and weather resilience. Fixed and retractable type categories command the largest existing revenue pool due to permanent installation preference among property owners, while portable configurations represent the fastest structural expansion as outdoor recreation and event industries adopt modular shelter systems. Aluminum material segments sustain premium positioning through corrosion resistance and architectural integration, whereas fabric alternatives occupy volume leadership in cost-sensitive consumer channels.
Building code enforcement by municipal authorities in the United States, CE marking requirements under European Union construction product regulations, and GB standards administered by China's SAMR collectively determine structural load specifications, fire resistance classifications, and installation permit thresholds for canopy products. EPA stormwater management guidelines and state-level solar access laws in California and Arizona further influence permitted canopy dimensions and placement on residential lots. Stakeholders must monitor evolving energy-efficiency certifications and localized wind zone reclassifications that will determine which material and feature combinations retain market access across jurisdictions.
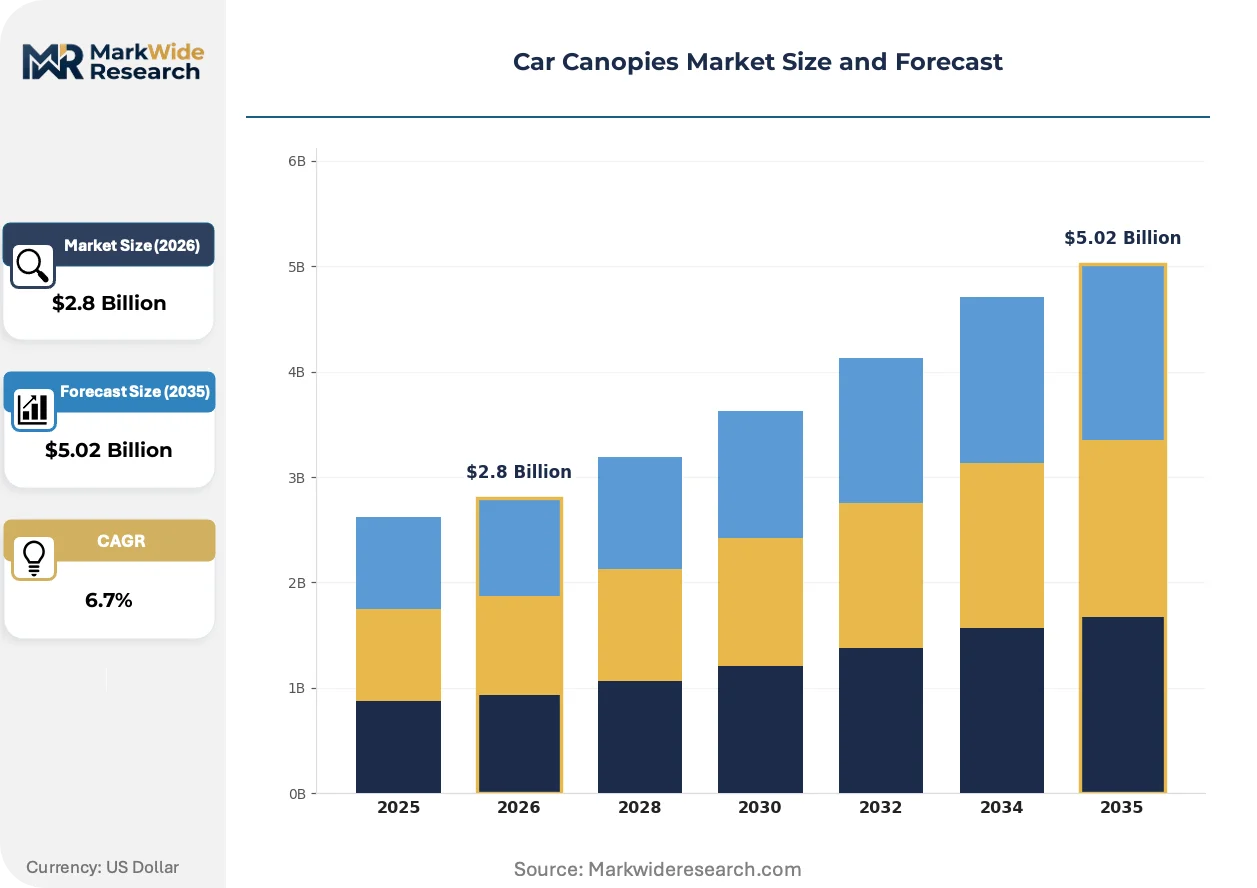
Market Dynamics
Residential property owners across suburban United States markets are accelerating permanent canopy installations as vehicle protection shifts from discretionary upgrade to essential household infrastructure, compressing replacement cycles and elevating material specifications.
Growth Catalysts
- CE marking requirements:European Union construction product regulations mandating structural load documentation are filtering substandard imports and rewarding certified aluminum fabricators with premium positioning in German and French retail channels.
- Polycarbonate glazing technology:UV-stabilized multiwall panels delivering thermal insulation and impact resistance are displacing acrylic alternatives in upscale residential segments seeking year-round workspace functionality.
- Suburban development concentration:Single-family home construction clusters in Texas, Florida, and Arizona are generating contiguous demand corridors that reduce customer acquisition costs for regional canopy installers.
Market Restraints
- Aluminum price volatility:LME aluminum contract fluctuations are compressing margins for extruded frame manufacturers unable to pass through input cost swings to price-sensitive retail channels.
- Steel supply concentration:Domestic steel canopy production depends heavily on Midwest mill capacity, exposing fabricators to regional logistics disruptions and tariff-driven price spikes.
- Permit threshold friction:Municipal zoning departments in California and Arizona enforce varying setback and height restrictions that delay installation timelines and increase compliance engineering costs.
Strategic Opportunities
- GB standards modernization:China's SAMR is revising wind load and fire resistance classifications for outdoor structures, creating certification pathways for aluminum-polycarbonate hybrid designs in tier-one city residential compounds.
- RV and marine recreation expansion:Portable canopy systems are penetrating campground and marina infrastructure as modular shelter demand tracks outdoor hospitality investment cycles.
- Solar integration mandates:California solar access laws and evolving IRA residential energy credits are incentivizing canopy designs that accommodate photovoltaic panel mounting without structural modification.
Industry Challenges
- Installation labor scarcity:Qualified contractors capable of engineered foundation work and electrical integration for lighted canopies command premium wages that inflate total project costs beyond consumer expectations.
- Code harmonization delays:Inconsistent snow load specifications between IRC editions and ASCE 7 standards force manufacturers to maintain multiple product variants, complicating inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Canopies Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Retractable, Fixed, Portable, Custom Material: Fabric, Aluminum, Polycarbonate, Steel Application: Residential, Commercial, Automotive Showrooms, Events Feature: Waterproof, UV Resistant, Windproof, Easy Installation |
| Companies Covered | Truck Hero, Alu-Cab, LEER Group, Arrow Truck Caps, Carryboy, A.R.E. Mobile, Knapheide Manufacturing, RSI SmartCap, ShelterLogic Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Canopies Market Emerging Trajectories
Fabrication methods and buyer expectations are converging around durability metrics and installation speed, compressing the traditional trade-off between permanent structural integrity and modular flexibility.
Integrated LED lighting and smart home connectivity modules are rewriting the functional definition of residential canopies from passive shelter to active outdoor living infrastructure. High-end property developers in Arizona and Texas are specifying these systems as standard amenities, forcing mid-market manufacturers to accelerate electronics partnerships or cede positioning. The technology is rewriting competitive advantage toward electrical engineering capabilities rather than pure metal fabrication scale.
EPA stormwater management guidelines are mandating permeable surface ratios and drainage integration for structures exceeding specific footprint thresholds, altering foundation design requirements across residential installations. Canopy manufacturers must now coordinate with civil engineers on runoff calculations previously outside their scope. Suburban developments in Florida and coastal California are experiencing the most intensive enforcement, with permit rejections rising for non-compliant proposals.
Direct-to-consumer configuration platforms are displacing traditional dealer networks as primary purchase channels for portable and light-duty residential canopies. Buyers now expect real-time visualization tools and freight-direct delivery, compressing the role of brick-and-mortar retailers to installation-only services. This behavioral shift is most pronounced among millennial homeowners in Texas and North Carolina, where digital-native purchasing patterns dominate outdoor product categories.
Car Canopies Market Segmentation
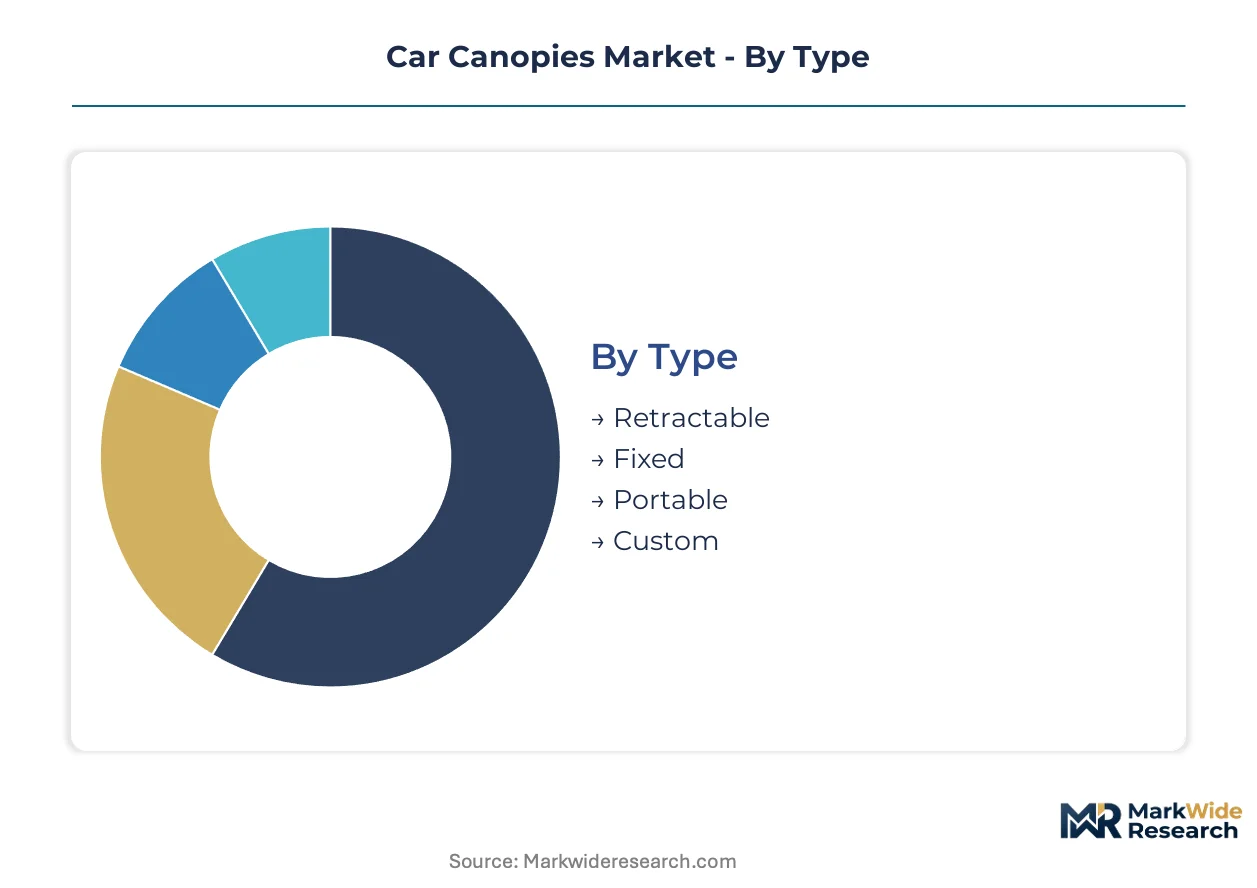
Car canopy purchasing decisions hinge on permanence expectations, climate exposure severity, and installation authority requirements. Segmentation reveals how material specifications and structural formats align with distinct buyer risk tolerances and property investment horizons.
Type:
Permanence preference drives initial buyer screening between temporary shelter and capital improvement categories.
- Fixed:Permanent anchor systems with engineered foundations and municipal permitting requirements dominate suburban residential compounds in Texas and Florida. Property owners treat these installations as taxable home improvements, elevating material durability specifications and contractor qualification standards.
- Portable:Modular frame systems with tool-free assembly target outdoor recreation infrastructure and seasonal automotive protection. Campground operators in Arizona and marina facilities in coastal Florida are expanding procurement of these units to track hospitality investment cycles.
- Retractable:Motorized or manual folding mechanisms accommodate variable weather exposure and solar access compliance.
- Custom:Architect-specified dimensions and finish matching serve high-end residential developments and automotive retail display requirements.
Volume sits with Fixed; growth tilts toward Portable.
Material:
Corrosion resistance and thermal performance specifications separate premium architectural integration from cost-driven consumer channels.
- Aluminum:Extruded alloy frames with powder-coated finishes deliver corrosion immunity and structural longevity under coastal humidity and freeze-thaw cycling. German and French retail channels reward CE-marked fabricators with premium positioning as building code enforcement tightens.
- Fabric:Tensioned polymer membranes with specified tear strength and UV stabilization occupy high-volume seasonal consumer markets. ShelterLogic Group and similar distributors dominate this tier through mass retail placement and rapid-install value propositions.
- Polycarbonate:Multiwall glazing panels provide thermal insulation and impact resistance for workspace-functional residential installations.
- Steel:Galvanized or powder-coated structural members serve fleet upfitting and heavy-duty commercial applications.
Revenue concentrates in Aluminum; Fabric captures shipment volume leadership.
Application:
End-use context determines load rating requirements, aesthetic integration standards, and regulatory compliance scope.
- Residential:Single-family property owners in suburban United States markets are accelerating permanent installations as vehicle protection shifts from discretionary upgrade to essential household infrastructure. Texas, Florida, and Arizona development clusters generate contiguous demand corridors.
- Commercial:Fleet operators and facility managers prioritize steel-framed durability and standardized maintenance protocols.
- Automotive Showrooms:Branded display infrastructure requires custom dimensions and finish matching to corporate identity standards.
- Events:Rapid-deployment modular systems serve temporary hospitality and exhibition infrastructure with minimal ground disturbance requirements.
Residential commands absolute revenue; Events demonstrates steepest expansion trajectory.
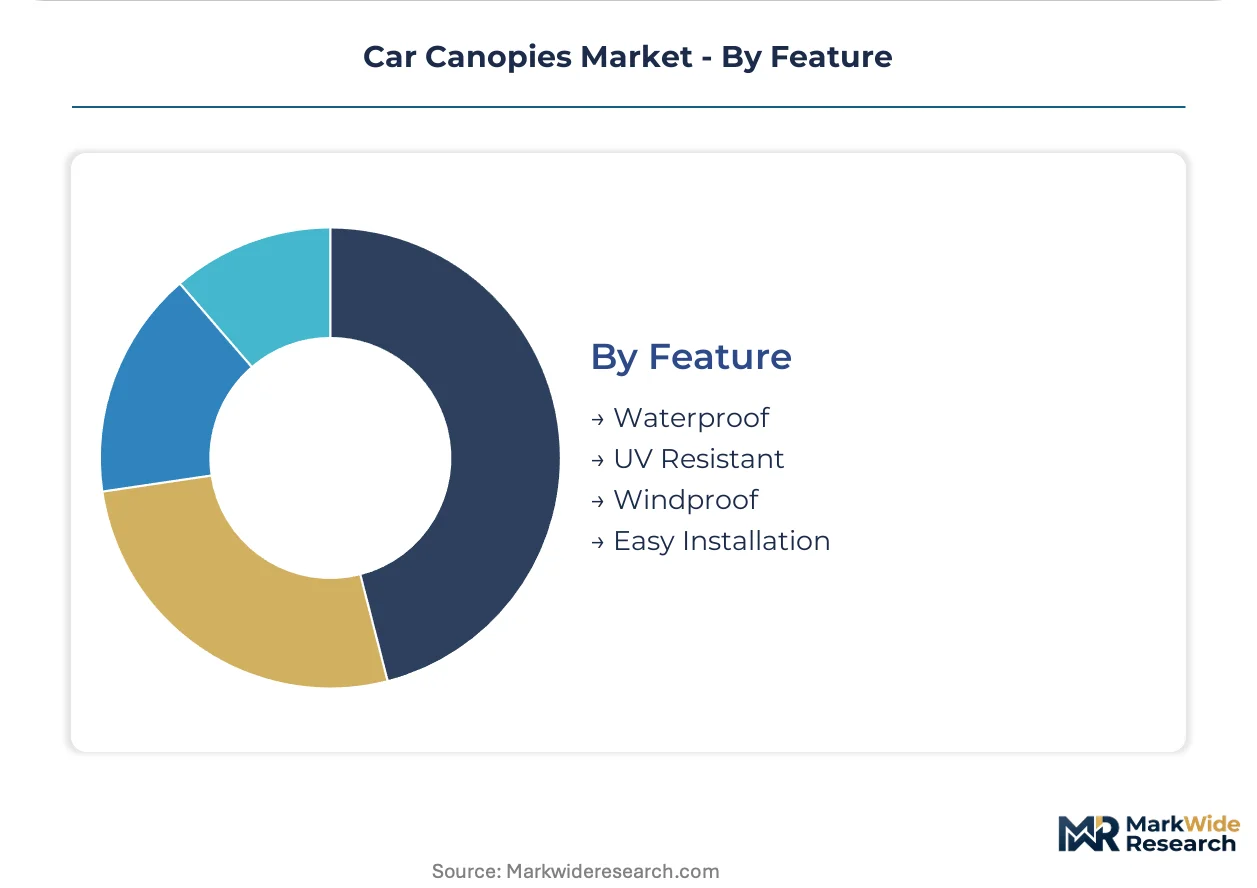
Feature:
Performance certification and installation convenience function as primary screening criteria in retail and specification channels.
- Waterproof:Seam-sealed membrane systems and integrated gutter drainage satisfy EPA stormwater management guidelines in Florida and coastal California enforcement zones.
- UV Resistant:Stabilized polymer formulations prevent degradation under Arizona and Texas solar exposure conditions.
- Windproof:Engineered anchor systems with specified load ratings comply with ASCE 7 standards and IRC wind zone classifications.
- Easy Installation:Tool-free assembly and freight-direct delivery align with millennial homeowner purchasing patterns in Texas and North Carolina digital-native channels.
Waterproof certification anchors baseline requirements; Easy Installation features gain share fastest in direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in suburban Texas and Florida accelerate residential canopy installations through property tax incentives and streamlined permitting. These zones concentrate demand corridors that reduce logistics costs for aluminum fabricators and polycarbonate panel suppliers serving the North American market.
United States
Single-family construction clusters in Texas, Florida, and Arizona generate contiguous demand for permanent fixed canopies. EPA stormwater management guidelines and state-level solar access laws in California and Arizona influence permitted dimensions and placement. Dallas-Fort Worth and Phoenix metro areas see elevated installation activity as homeowners treat vehicle protection as essential infrastructure.
Germany
CE marking requirements under EU construction product regulations filter substandard imports and reward certified aluminum fabricators. German retail channels prioritize structural load documentation and fire resistance classifications. Industrial concentrations in Bavaria and North Rhine-Westphalia host fabrication facilities supplying premium residential and commercial canopy systems across Central Europe.
China
GB standards administered by SAMR are revising wind load and fire resistance classifications for outdoor structures. Tier-one city residential compounds in Shanghai and Beijing drive demand for aluminum-polycarbonate hybrid designs. Yangtze River Delta manufacturing clusters supply extruded aluminum frames meeting updated certification pathways.
France
EU Green Deal implementation and REACH compliance requirements shape material specifications for residential outdoor structures. French retail channels reward CE-marked fabricators with premium positioning as building code enforcement tightens. Lyon and Marseille metropolitan areas see growing procurement of weather-resistant permanent installations.
Japan
METI energy-efficiency guidelines and JIS standards for structural materials influence canopy product development. Kanto and Kansai regions concentrate demand for compact residential parking solutions in dense urban environments. Osaka-based distributors prioritize corrosion-resistant aluminum systems suited to humid coastal conditions.
Car Canopies Market Vendor Landscape
Top-tier vendors anchor premium aluminum and polycarbonate fabrication, while mid-tier fabricators compete on installation speed and retail distribution breadth. The vendor base separates into three distinct tiers based on material specialization and channel access. Strategic archetypes include integrated composite manufacturers, rapid-install fabric specialists, and fleet-focused steel fabricators. Dominant competitive moves center on CE marking certification acquisition and direct-to-consumer platform development.
Within the integrated manufacturing tier, LEER Group and Knapheide Manufacturing represent contrasting specialization models. ShelterLogic Group occupies a position exemplifying mass-market fabric canopy distribution. These three anchors illustrate how material choice—fiberglass composite, steel, and tensioned polymer—determines competitive territory rather than geographic scale alone.
| Leading Market Players |
|---|
| Truck Hero |
| Alu-Cab |
| LEER Group |
| Arrow Truck Caps |
| Carryboy |
| A.R.E. Mobile |
| Knapheide Manufacturing |
| RSI SmartCap |
| ShelterLogic Group |
| Others |
Supply Flow & Price Mechanics
EPA stormwater management guidelines governing permeable surface ratios and drainage integration for residential structures exceeding footprint thresholds gate both qualified supply and premium-tier pricing access. Compliance engineering costs and certified contractor scarcity compress margins for non-compliant fabricators while elevating price realization for CE-marked aluminum extruders and polycarbonate panel suppliers meeting German and French building code enforcement.
Pricing Analysis
Short lead-time premiums for rapid-install fabric canopy systems and spot-inventory discounts for seasonal aluminum frame stock shape transactional dynamics across retail channels. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and installation complexity, with CE-marked architectural systems commanding sustained premiums in German retail. Cost compression in economy fabric tiers intensifies because LME aluminum contract volatility and Midwest steel mill concentration limit margin recovery. Seasonal consumers in mass retail channels exhibit highest price sensitivity, while property developers in Arizona and Texas commercial projects demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates under evolving Buy American provisions for municipal fleet upfitting contracts are reshaping sourcing toward North American aluminum extrusion and steel fabrication capacity. Raw material dependencies center on LME-traded aluminum ingot, polycarbonate resin from Yangtze River Delta chemical complexes, and galvanized steel coil from Midwest integrated mills. Single-source vulnerability concentrates in polycarbonate multiwall panel supply, where German and Chinese manufacturers dominate technical-grade production. Distribution runs through direct-to-consumer configuration platforms displacing traditional dealer networks for portable and light-duty residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation labor scarcity for qualified contractors capable of engineered foundation work and electrical integration props pricing power across permanent residential installations. This supply-constrained dynamic rewards capacity holders with certified installer networks.
For Market Incumbents: Anticipate code harmonization delays between IRC editions and ASCE 7 standards forcing maintenance of multiple product variants, and respond by consolidating certification pathways around CE marking and GB standards modernization to reduce inventory complexity. Backward integration into extruded aluminum production secures margin control against LME volatility while captive supply of polycarbonate panels insulates from German-Chinese supply concentration. For New Entrants and Emerging Players: The price-point gap between premium CE-marked aluminum systems and economy fabric canopies creates entry space for hybrid aluminum-polycarbonate designs targeting China's tier-one city residential compounds under SAMR's revised wind load classifications. White-space concentrates in portable canopy systems for Arizona campground and Florida marina infrastructure, where modular shelter demand tracks outdoor hospitality investment cycles. A direct-to-consumer platform with real-time visualization tools captures millennial homeowner purchasing patterns in Texas and North Carolina. For Investors and Strategic Acquirers: California solar access law amendments mandating photovoltaic-ready canopy structures without structural modification are the leading indicator that electrical engineering capabilities will displace pure metal fabrication scale as the primary value driver. Long-term viability favors targets with integrated LED and smart home connectivity modules, installer network density in suburban Texas and Florida development corridors, and CE marking certification already secured. Tier-one city procurement acceleration under China's GB standards revision signals inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Certification Acquisition | Unlocks premium positioning in German and French retail channels enforcing EU construction product regulations. |
| Direct-to-Consumer Platform Development | Captures millennial homeowner segments in Texas and North Carolina through freight-direct delivery models. |
| Installer Network Expansion | Addresses labor scarcity bottlenecks delaying permanent residential installations in Florida and Arizona. |
| Polycarbonate Panel Backward Integration | Reduces exposure to Yangtze River Delta supply concentration for thermal insulation-grade glazing. |
| Solar Integration Engineering Partnership | Positions for California solar access law compliance and IRA residential energy credit eligibility. |
Methodological Framework
SEC 10-K filings, customs and trade data, and building permit databases formed the secondary backbone, supplemented by EPA stormwater management guidelines and SAMR GB standards documentation. Primary interviews with canopy installation contractors, aluminum extrusion plant managers, residential property developers, and municipal zoning officials combined with secondary validation. Bottom-up and top-down triangulation cross-checked shipment volumes against construction permit flows and retail channel inventory data.
Bottom-up modeling anchored in type-material-application-feature segmentation across fixed, portable, retractable, and custom categories, with aluminum, fabric, polycarbonate, and steel material tiers. Residential, commercial, automotive showroom, and event applications tracked separately against waterproof, UV resistant, windproof, and easy installation feature bundles. CAGRs derived from regression analysis of historical permit data and forward projection of suburban development clusters in Texas, Florida, and Arizona over the analysis window.
Inputs from municipal zoning departments and contractor licensing boards were available through the study window; gaps in real-time aluminum LME contract volatility and polycarbonate resin pricing introduce uncertainty bands around margin forecasts. Regulatory acceleration in California solar access laws and SAMR GB standards revision represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Sealants Market
Automotive Interior & Exterior
Automotive Laser Lighting Market
Automotive Interior & Exterior
Automotive Portable Refrigerator Market
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Global Luxury Car Coachbuilding Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Automotive Mudguards Market
Automotive Interior & Exterior
Auto Internal Connector Market
Automotive Interior & Exterior
Automotive Rocker Panel Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Power Sunroof Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Bonnet Lock Plate and Latch Market
Automotive Interior & Exterior
Automotive Clear Coat Paint Market