
 North America Automotive Flooring Market | 2026-2036
North America Automotive Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Flooring Market Analytics
Modular floor system bundling is realigning how OEMs and fleet buyers specify automotive flooring across trim levels and vehicle platforms. Lear Corporation leverages its seat-and-interior integration expertise to bundle flooring with adjacent cabin components, reducing supplier touchpoints for Detroit Three automakers. Toyota Boshoku anchors its North American position through captive supply relationships with Japanese OEM transplants in Kentucky and Indiana. 3M Company differentiates via adhesive and acoustic material technology that OEMs embed during flooring installation.
North America automotive flooring encompasses interior surface materials engineered for occupant comfort, acoustic dampening, and durability under cyclic loading and thermal stress; typical constructions layer needle-punched carpet face fibers onto thermoplastic olefin backing with integrated mass-barrier substrates for NVH control. Carpet retains the largest value share among material types due to premium-truck and SUV penetration, while vinyl accelerates in commercial fleet applications where cleanability and replacement cost drive specification. The OEM end-user channel commands the deepest margin pools because long-term supply agreements embed tooling amortization and design collaboration fees that aftermarket providers cannot replicate.
EPA fuel-economy mandates and NHTSA safety standards shape material selection by penalizing weight accumulation and mandating flammability resistance in passenger compartments. The US Department of Transportation's Buy America provisions for federal fleet procurement restrict sourcing geography, compelling suppliers to maintain domestic conversion capacity. Stakeholders must monitor how California Air Resources Board zero-emission vehicle rules reshape interior material specifications as battery-electric platforms eliminate engine-bay noise and alter acoustic engineering priorities.
Market Dynamics
EPA fuel-economy mandates are compressing material specifications across the North America automotive flooring value chain, forcing suppliers to reengineer carpet and vinyl constructions around thermoplastic olefin backings that shed mass without sacrificing acoustic performance.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:These regulations penalize vehicle weight accumulation, compelling OEMs to source needle-punched carpet face fibers with lighter mass-barrier substrates that maintain NVH control.
- Zero-emission vehicle platform proliferation:Battery-electric architectures from Detroit Three and Japanese transplant OEMs eliminate engine-bay noise sources, creating demand for recalibrated acoustic flooring engineered for cabin-specific frequencies.
- Midwest automotive belt concentration:Tier-1 supplier clustering around Detroit and Chicago assembly corridors reduces logistics costs and enables just-in-sequence delivery for high-volume truck and SUV platforms.
Market Restraints
- Petrochemical input volatility:Thermoplastic olefin and vinyl resin costs fluctuate with propylene and ethylene feedstock prices, compressing margin predictability for backing substrate manufacturers.
- Buy America sourcing restrictions:US Department of Transportation provisions for federal fleet procurement limit offshore conversion capacity, forcing suppliers to maintain redundant domestic production lines.
- Flammability compliance burdens:NHTSA safety standards mandate rigorous flame-resistance testing for passenger compartment materials, extending qualification timelines for novel fiber compositions.
Strategic Opportunities
- California Air Resources Board zero-emission rules:These mandates accelerate battery-electric platform rollouts, opening specification windows for flooring systems optimized for altered thermal and acoustic cabin profiles.
- Commercial fleet vinyl penetration:Cleanability and replacement cost priorities among logistics and rental fleet operators create pull-through demand for vinyl constructions in previously carpet-dominated segments.
- Modular floor system bundling:Integration of flooring with adjacent cabin components enables suppliers to capture design collaboration fees and reduce OEM supplier touchpoints across trim levels.
Industry Challenges
- Acoustic engineering talent scarcity:Battery-electric platform proliferation requires NVH specialists capable of recalibrating mass-barrier substrates for cabin-specific frequency profiles without legacy engine masking.
- Tooling amortization compression:Long-term supply agreements with Detroit Three automakers embed capital recovery schedules that strain cash flow when platform volumes underperform forecasts.
- California-versus-federal regulatory divergence:CARB interior material specifications increasingly outpace federal baselines, forcing suppliers to maintain dual certification pathways for single market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Flooring Market |
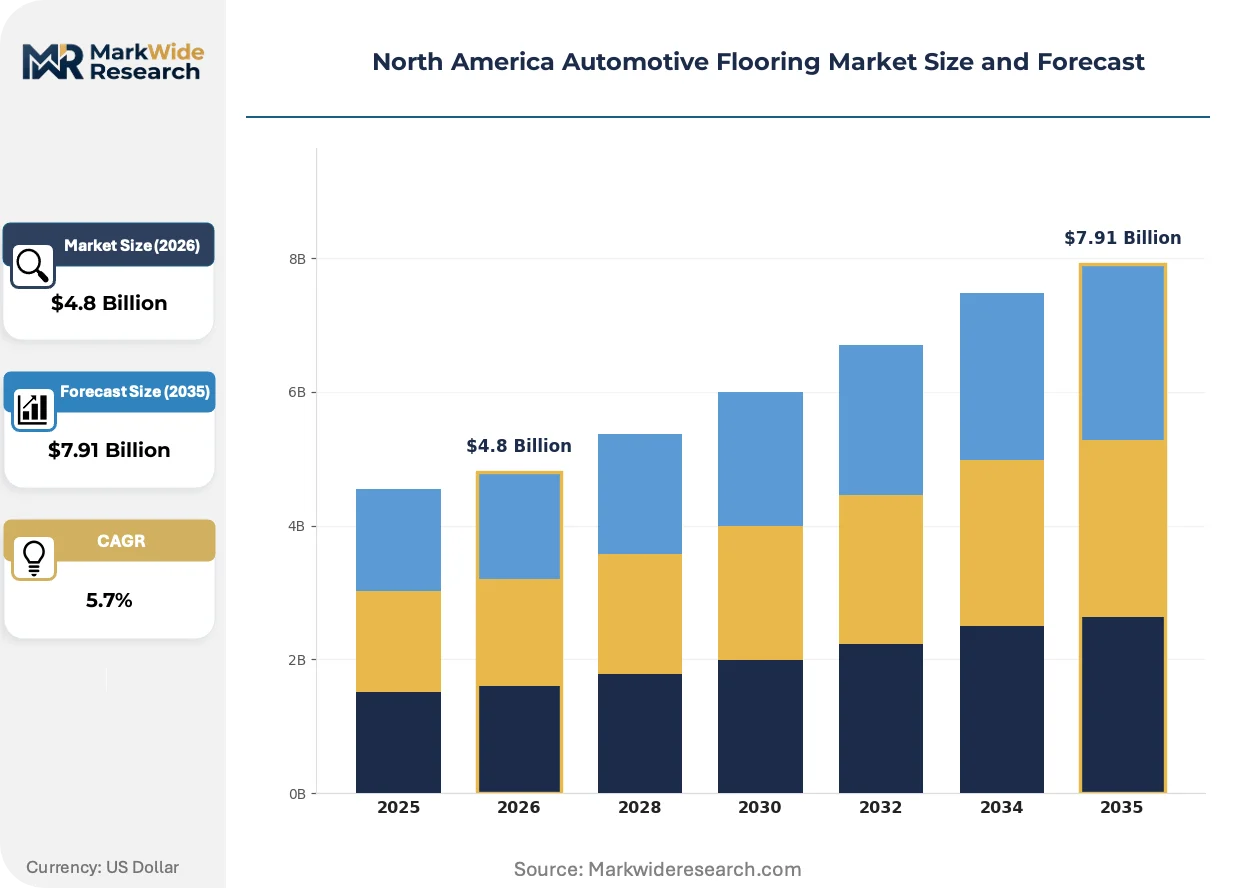
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Carpet, Vinyl, Rubber, Foam Vehicle Type: SUV, Sedan, Truck, Hatchback Installation Method: Adhesive, Snap-in, Clip, Direct Lay End User: OEMs, Aftermarket Providers, Dealerships, Fleet Operators |
| Companies Covered | 3M Company, Lear Corporation, Husky Liners, Inc., Thermotex Corporation, Racemark International LLC, Covercraft Industries LLC, Auto Custom Carpet, Inc., Toyota Boshoku Corporation, Suminoe Textile Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Flooring Market Evolving Landscape
Material science advances and procurement model evolution are simultaneously reweighting competitive advantage in North America automotive flooring, with lightweighting mandates and electric platform proliferation rewriting specification priorities faster than legacy supply relationships can adapt.
Recycled-content needle-punched face fibers are decentralizing material sourcing strategies across the value chain. These fibers incorporate post-consumer polyethylene terephthalate without sacrificing tuft bind strength or abrasion resistance. Tier-1 suppliers in Indiana and Kentucky are qualifying these constructions for mid-trim SUV applications where sustainability credentials influence fleet procurement decisions. The technology is decentralizing virgin polymer dependence, compressing exposure to petrochemical price cycles while opening specification pathways with sustainability-focused OEMs.
NHTSA flammability resistance standards are tightening test protocols for passenger compartment materials, extending qualification timelines for novel fiber-backings combinations. The industrial consequence is a widening gap between incumbent suppliers with amortized test data libraries and entrants facing multi-year certification burdens. Commercial fleet vinyl specifications are most affected, as cleanability-driven material choices must now navigate more rigorous horizontal burn rate requirements before platform integration.
Fleet procurement officers are consolidating supplier relationships around full cabin system integrators capable of bundling flooring with seating and trim components. This pattern disrupts standalone flooring specialists who previously sold direct to OEM commodity buyers. The consolidation is most visible among Detroit Three automakers, where platform chief engineers increasingly award interior system contracts to single-source integrators rather than managing discrete flooring, seat, and headliner suppliers separately.
North America Automotive Flooring Market Segmentation
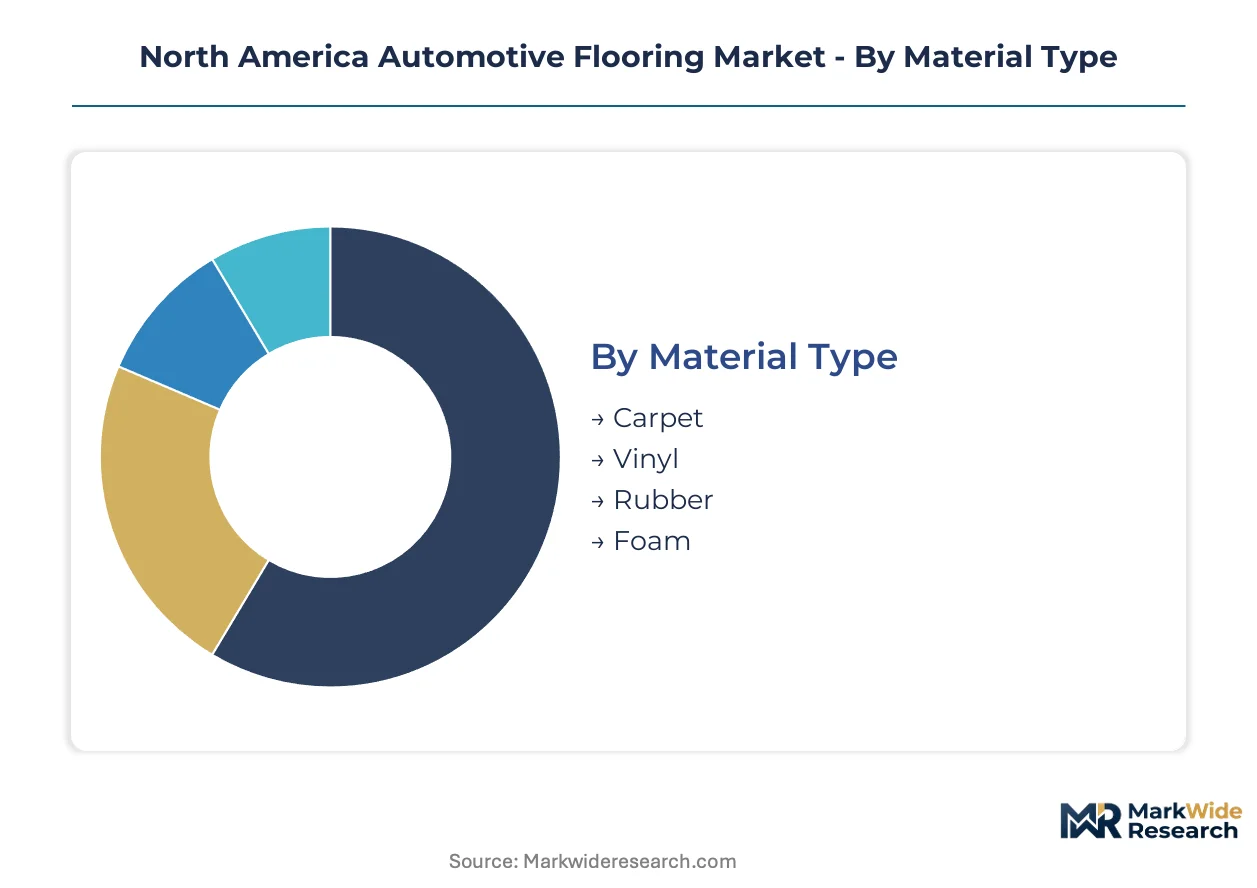
North America automotive flooring procurement diverges sharply across material grades and vehicle platforms, with EPA fuel-economy mandates and fleet cleanability requirements fragmenting specification pathways. OEMs now source distinct constructions for battery-electric SUVs versus commercial fleet trucks, forcing suppliers to maintain parallel product architectures.
Material Type:
Supply concentration clusters around thermoplastic olefin backing technologies in Indiana and Kentucky conversion facilities, where captive resin supply agreements insulate major suppliers from propylene volatility.
- Carpet:Needle-punched face fibers layered onto thermoplastic olefin backing with integrated mass-barrier substrates for NVH control. Demand concentrates in US Midwest premium-truck and SUV assembly corridors where Detroit Three OEMs specify tufted constructions for occupant comfort and acoustic dampening.
- Vinyl:Polyvinyl chloride or thermoplastic olefin sheet constructions engineered for cleanability and chemical resistance. Fleet operators in Chicago and Detroit logistics hubs specify vinyl for rental and commercial truck applications where replacement cost and maintenance intervals dominate procurement decisions.
- Rubber:Heavy-duty molded or extruded compounds for cargo areas and commercial vehicle load floors. Tier-1 suppliers in Ohio qualify rubber constructions for fleet upfitter channels.
- Foam:Polyurethane or polyethylene closed-cell substrates for lightweight underlayment and acoustic decoupling. Kentucky transplant OEMs embed foam layers in battery-electric platform flooring to compensate for eliminated engine-bay noise masking.
Today's leader: Carpet. Tomorrow's challenger: Vinyl.
Vehicle Type:
Platform volume distribution across the US Midwest automotive belt determines tooling amortization schedules and supplier capacity allocation.
- SUV:Mid-size and full-size sport utility vehicles command the deepest specification tiers, with multi-layer carpet systems and integrated acoustic packages. Detroit Three platforms in Michigan and Ohio drive demand for premium-trim flooring with recycled-content face fibers.
- Truck:Full-size pickup and commercial chassis cab applications split between carpet for retail consumers and vinyl for fleet operators. Chicago-area fleet upfitters specify cleanable constructions for vocational applications.
- Sedan:Declining production volumes in US assembly plants compress supplier margins, with simplified two-layer carpet constructions dominating residual platform commitments.
- Hatchback:Compact and subcompact passenger cars, primarily from Japanese transplant OEMs in Kentucky and Indiana, utilize lightweight snap-in flooring systems for assembly efficiency.
SUV and truck platforms absorb the majority of supplier R&D investment, while sedan sourcing contracts face renewal compression.
Installation Method:
Assembly line throughput requirements in high-volume Midwest plants are accelerating adhesive and snap-in qualification at the expense of labor-intensive alternatives.
- Adhesive:Permanent bonding with proprietary backing substrates enables integrated acoustic performance and eliminates fastener rattles. 3M and Henkel supply chemistries to Kentucky and Indiana transplant assembly lines.
- Snap-in:Modular retention systems enable rapid installation and service replacement, gaining share in battery-electric platforms where reduced NVH requirements permit lighter mechanical fastening.
- Clip:Mechanical retention for heavy-duty commercial applications requiring field serviceability without adhesive degradation.
- Direct Lay:Loose-laid constructions for aftermarket replacement and fleet refurbishment channels, bypassing OEM tooling amortization.
Adhesive retains the specification majority; snap-in methods are climbing the fastest in electric platform integration.
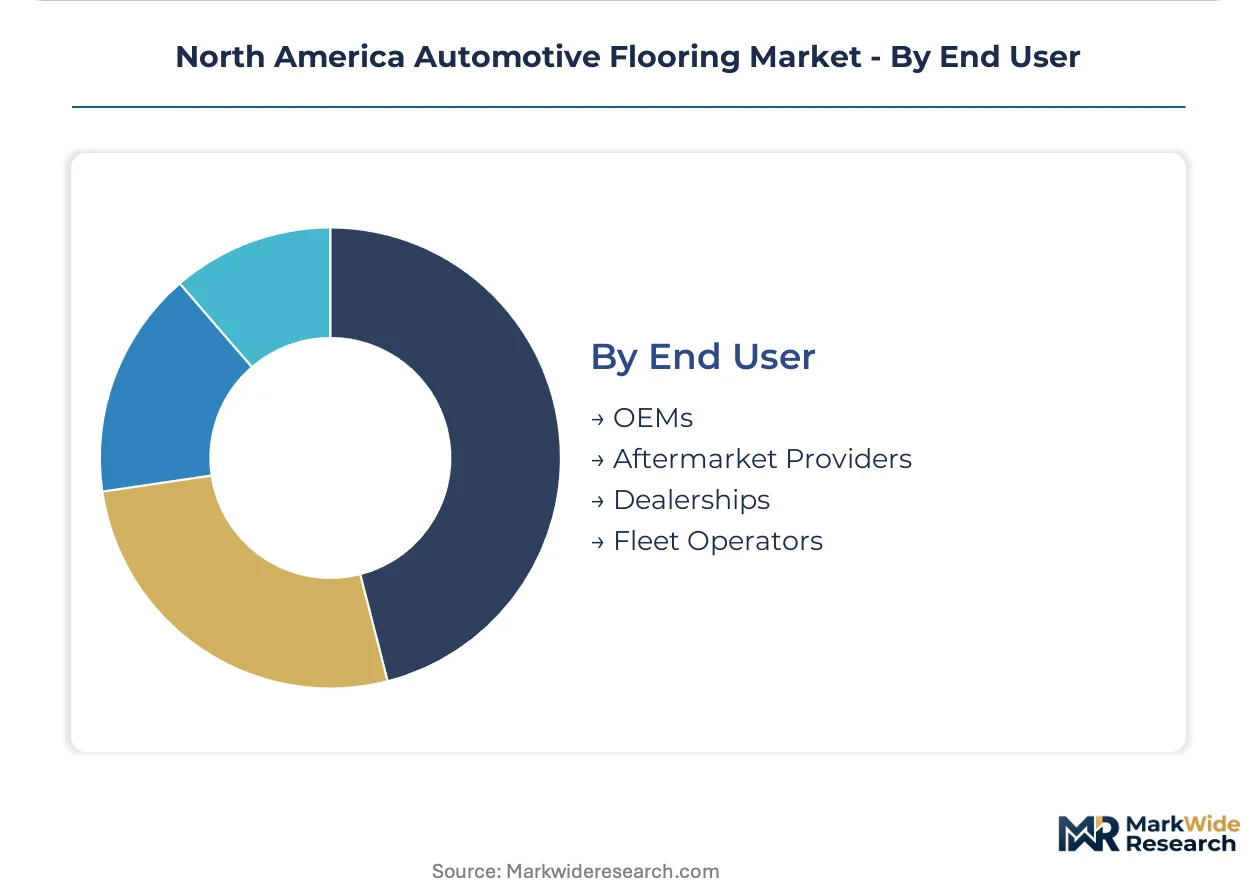
End User:
Procurement authority concentration separates long-term supply agreement holders from price-sensitive spot buyers.
- OEMs:Detroit Three and Japanese transplant automakers in Michigan, Ohio, Kentucky, and Indiana award multi-year contracts embedding design collaboration fees and tooling amortization. Lear Corporation and Toyota Boshoku anchor these relationships through seat-and-interior integration capabilities.
- Fleet Operators:Commercial logistics and rental fleet managers in Chicago and Detroit corridors specify vinyl constructions for cleanability, consolidating volume through national procurement agreements.
- Aftermarket Providers:Independent distributors and installers serve vehicle refurbishment and collision repair channels, sourcing through tier-2 converters without OEM design collaboration access.
- Dealerships:Franchised retailer service departments handle warranty replacements and customer-pay upgrades, operating on spot purchasing terms with regional distributors.
OEMs command the deepest margin pools; fleet operators represent the fastest volume expansion trajectory in vinyl specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive flooring manufacturing scaled from early Detroit assembly operations into a specialized component sector concentrated around Great Lakes industrial corridors and Mexican border assembly zones.
United States
EPA fuel-economy mandates and NHTSA safety standards drive specification priorities for lightweight acoustic systems across Michigan, Ohio, and Kentucky assembly plants. The Department of Transportation's Buy America provisions restrict federal fleet sourcing geography, compelling domestic conversion capacity maintenance. Tier-1 suppliers cluster around Detroit and Chicago corridors to enable just-in-sequence delivery for high-volume truck and SUV platforms.
Canada
Ontario-based assembly operations serving Detroit Three automakers generate steady demand for carpet and vinyl flooring systems integrated into cross-border supply chains. Environment and Climate Change Canada vehicle emission regulations align with US EPA standards, simplifying material qualification across the integrated North American market. Windsor-Toronto industrial corridor suppliers specialize in modular floor system bundling for mid-size SUV production.
Mexico
Bajío Region and Nuevo León assembly plants attract flooring supplier investment through USMCA trade agreement provisions and proximity to US distribution networks. Mexican federal environmental regulations under SEMARNAT establish flammability and emissions baselines for interior materials. Querétaro and San Luis Potosí supplier parks host thermoplastic olefin backing conversion facilities serving transplant OEM operations.
North America Automotive Flooring Market Competitive Landscape
Premium-margin players sit above commodity-margin players across design collaboration and tooling amortization capabilities, with long-term OEM supply agreements separating integrated system providers from standalone component fabricators. The vendor base organizes into three strategic archetypes: full cabin integrators bundling flooring with seating and trim, specialized flooring manufacturers with captive resin supply agreements, and aftermarket distributors serving refurbishment channels. Dominant competitive moves include modular system bundling to reduce OEM supplier touchpoints and geographic co-location with high-volume assembly corridors to compress logistics costs.
Within the full cabin integration tier, Lear Corporation and Toyota Boshoku exemplify archetypes leveraging seat-and-interior expertise to capture design collaboration fees. Among material technology specialists, 3M Company occupies a position defined by adhesive and acoustic substrate capabilities that OEMs embed during flooring installation. These three entities represent distinct competitive positioning vectors: integration scale, captive OEM relationships, and functional material specialization.
| Leading Market Players |
|---|
| 3M Company |
| Lear Corporation |
| Husky Liners, Inc. |
| Thermotex Corporation |
| Racemark International LLC |
| Covercraft Industries LLC |
| Auto Custom Carpet, Inc. |
| Toyota Boshoku Corporation |
| Suminoe Textile Co., Ltd. |
| Others |
Value Network & Pricing Analysis
EPA fuel-economy mandates gate qualified supply and premium-tier pricing access by forcing OEMs to source lightweight thermoplastic olefin backings from suppliers with amortized NVH test data libraries. Buyers lacking long-term Detroit Three supply agreements face compressed margin pools and extended qualification timelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM design collaboration contracts from fleet procurement agreements and aftermarket spot purchases. Price differentiation hinges on acoustic certification grade and volume scale commitments. Cost compression in economy-tier vinyl runs through petrochemical input volatility. Fleet operators exhibit highest price sensitivity; OEM platform engineers prioritize performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Detroit Three automakers compel Tier-1 suppliers to maintain parallel conversion lines across Indiana, Kentucky, and Ohio. Raw material flows draw from propylene feedstock networks and recycled polyethylene terephthalate streams. Single-source vulnerability concentrates in captive resin supply agreements. Distribution runs through just-in-sequence corridors linking Midwest supplier parks to Michigan and Chicago assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Mexican conversion capacity under USMCA provisions captures labor cost advantages against US Buy America compliance burdens for federal fleet sourcing.
For Market Incumbents: Deploy modular floor system bundling to entrench seat-and-interior integration relationships against standalone flooring specialists. Deepen backward integration into thermoplastic olefin resin production to insulate margin pools from propylene volatility. Capture design collaboration fees through early-stage platform engineering engagement. For New Entrants and Emerging Players: Fleet procurement officers represent the most penetrable channel partner type for vinyl specification growth in Chicago and Detroit logistics corridors. Target commercial upfitter networks with cleanability-optimized constructions. Accelerate CARB zero-emission platform qualification to bypass incumbent acoustic test data advantages. For Investors and Strategic Acquirers: Roll-up economics work for regional Tier-2 converters with captive OEM relationships because tooling amortization schedules create sticky revenue streams resistant to volume volatility. Platform standardization across battery-electric SUV architectures signals long-term viability. Watch for CARB-federal regulatory divergence as inflection indicator for dual-certification cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweight Backing Material Transition | EPA fuel-economy compliance hinges on thermoplastic olefin mass reduction without NVH degradation. |
| Modular Floor System Bundling | Lear Corporation and Toyota Boshoku capture design fees through seat-and-interior integration. |
| Recycled Content Fiber Qualification | Post-consumer PET sourcing opens specification pathways with sustainability-focused OEM procurement. |
| Battery-Electric Platform Recalibration | Cabin-specific acoustic engineering replaces legacy engine-bay noise masking priorities. |
| USMCA Manufacturing Footprint | Mexican Bajío Region supplier parks access US distribution networks with labor cost advantages. |
Research Methodology
Direct dialogue with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers grounded qualitative findings. Secondary validation drew from EPA regulatory filings, NHTSA safety standard databases, USDOT procurement records, and vehicle production data from IHS Markit. Bottom-up segment sizing triangulated against top-down market value estimates.
Market value and volume trajectories across the analysis window reflect segment-level modeling across material type, vehicle class, installation method, and end-user channel. CAGRs derived from platform volume forecasts and content-per-vehicle assumptions. Propylene price indices and OEM production schedules fed industry-specific forecast sensitivity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CARB regulatory divergence and battery-electric platform adoption curves. Deviation in federal fleet electrification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Automotive Multi-Layer Display Market
Automotive Interior & Exterior
Automotive Lighting Molds Market
Automotive Interior & Exterior
Automotive Insulation Market
Automotive Interior & Exterior
Automotive Climate Control Market
Automotive Interior & Exterior
India Automotive Door Seals Market
Automotive Interior & Exterior
Automotive Steering Wheel Covers Market
Automotive Interior & Exterior
Automotive Door Latch Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
Automotive Liftgate Market
Automotive Interior & Exterior
Two Wheeler Backrest Market
Automotive Interior & Exterior
Automotive Exterior LED Lighting Market
Automotive Interior & Exterior
Automotive Door Handles Market
Automotive Interior & Exterior
Light Weight Automotive Body Panels Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market