
 Automotive Inside Rearview Mirrors (IRVM) Market | 2026-2036
Automotive Inside Rearview Mirrors (IRVM) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Inside Rearview Mirrors (IRVM) Market Outlook
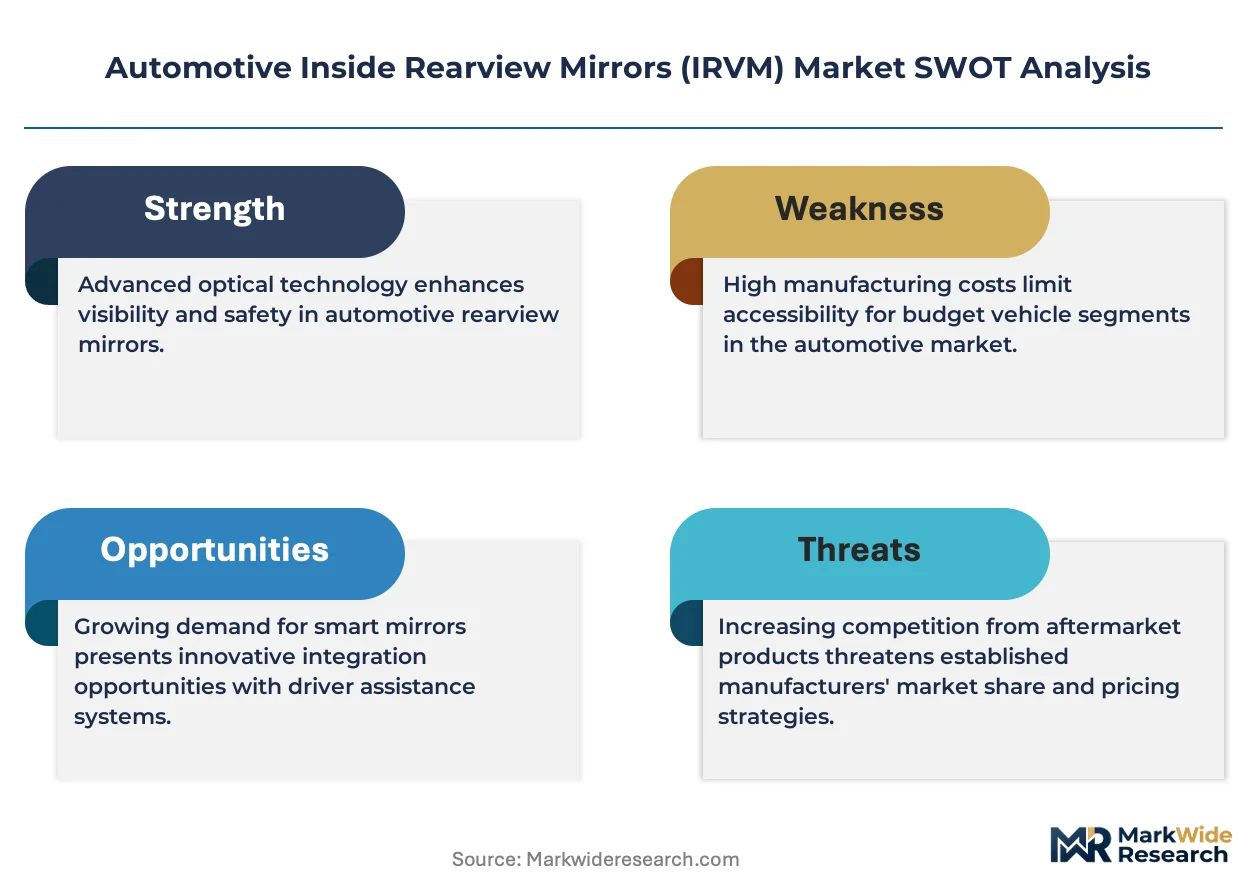
ECE R46 compliance certification is rotating supplier eligibility across the European supply base. Gentex Corporation leverages its electrochromatic technology leadership to sustain premium OEM relationships in North America. Magna International anchors production scale through integrated mirror-electronics manufacturing in Ontario and Bavaria. Ficosa International competes on mechatronics integration, positioning its Barcelona engineering center as a hub for digital mirror development.
Automotive inside rearview mirrors are optical safety devices mounted to the vehicle windshield or headliner, typically incorporating glass substrates with reflective coatings, electrochromatic gel layers, or camera-display systems to eliminate rear blind spots. Their primary commercial purpose is to provide drivers with compliant rearward field-of-view per regulatory mandates while enabling advanced driver assistance system integration. Electrochromatic mirrors now command the strongest margin pools as autodimming functionality migrates from luxury into mid-segment vehicles. Digital mirrors represent the fastest-expanding technology category, though LCD and OLED variants face cost barriers in mass-market OEM programs. Fleet operators are emerging as a distinct end-user channel, prioritizing universal-fit aftermarket solutions for commercial vehicle retrofit.
FDA oversight applies to mirrors incorporating biometric sensors, while NHTSA FMVSS 111 governs field-of-view and reflectivity standards for US-market vehicles. EPA fuel-economy regulations indirectly shape demand by encouraging aerodynamic mirror designs that reduce drag coefficients. ECE R46 and the EU's General Safety Regulation collectively mandate automatic dimming and expanded viewing angles, forcing technology upgrades across European OEM supply chains. Stakeholders must monitor divergence between camera-based mirror exemptions and traditional optical requirements as regulators reconcile safety standards with display-replacement technologies.
Market Dynamics
Electrochromatic gel-layer technology is compressing traditional prism-mirror architectures as mid-segment OEMs adopt autodimming functionality previously confined to luxury vehicles, forcing suppliers to retool coating lines and recertify optical stacks.
Growth Catalysts
- ECE R46 visibility mandates:Europe's automatic dimming and expanded viewing-angle requirements are compelling technology upgrades across German, French, and Italian OEM supply chains.
- Fleet operator retrofit demand:Commercial vehicle operators in North America are procuring universal-fit aftermarket electrochromatic mirrors to reduce glare-related accident liability.
- Camera-display convergence:Digital mirror systems integrating LCD and OLED panels are creating new specification tiers for premium passenger vehicle programs.
Market Restraints
- Indium-tin-oxide cost volatility:Electrochromatic mirror production depends on transparent conductive oxide substrates subject to rare-earth supply fluctuations.
- Stuttgart-Munich supplier concentration:European production gravity centers on Bavaria and Baden-Württemberg, creating single-source vulnerability for integrated mirror-electronics modules.
- Camera-exemption regulatory divergence:NHTSA FMVSS 111 field-of-view standards conflict with emerging camera-replacement exemptions, freezing some digital mirror deployments.
Strategic Opportunities
- India mid-segment penetration:BIS automotive safety standards are tightening visibility requirements, opening electrochromatic adoption in domestically manufactured passenger vehicles.
- Biometric sensor integration:Driver monitoring systems merging IRVM mounting positions with drowsiness detection create new FDA-regulated device categories.
- Commercial vehicle channel expansion:Fleet management platforms are bundling mirror upgrades with telematics subscriptions, bypassing traditional Tier-1 supply relationships.
Industry Challenges
- Optical stack certification timelines:ECE R46 homologation for electrochromatic variants requires 18-24 month validation cycles, compressing model-year integration windows.
- Mechatronics skill scarcity:Mirror-electronics integration demands expertise spanning gel chemistry, thin-film deposition, and camera ISP tuning that concentrates in Barcelona and Ontario engineering clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Inside Rearview Mirrors (IRVM) Market |
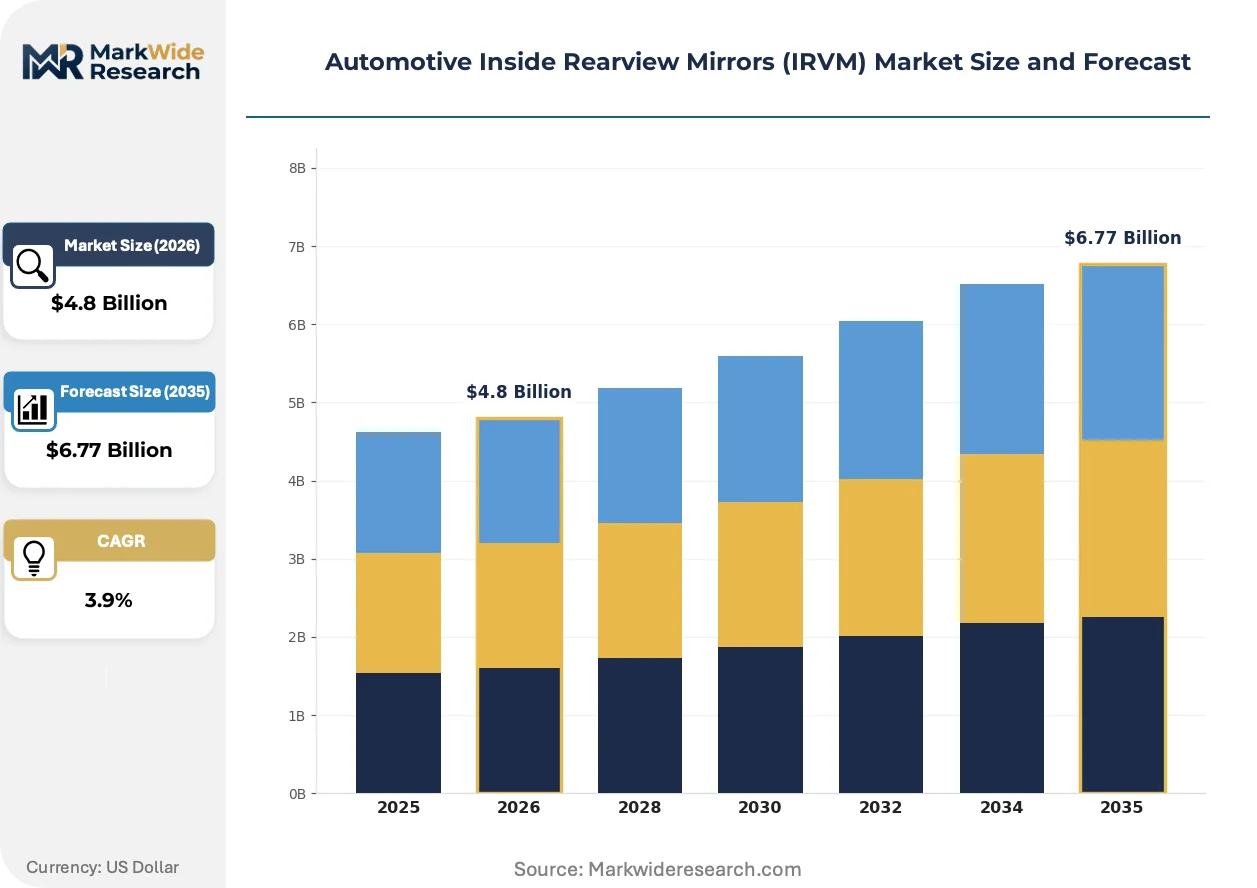
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Mirrors, Electrochromatic Mirrors, Digital Mirrors, Adaptive Mirrors Technology: LCD, OLED, Glass, Autodimming End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Installation Type: Integrated, Universal Fit, Custom Fit, Clip-On |
| Companies Covered | Ficosa International, SL Corporation, Gentex Corporation, Burco Inc., FLABEG Automotive Glass Group, Magna International, Murakami Corporation, Valeo, Samvardhana Motherson Reflectec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Inside Rearview Mirrors (IRVM) Market Strategic Shifts
Digital display technologies are fragmenting the traditional glass-mirror supply base while regulatory agencies reconcile camera-based replacement systems with century-old optical safety standards.
Electrochromatic mirror technology uses gel-layer electrochemical reaction to modulate reflectivity automatically in response to rearward glare detection. Mid-segment OEMs in Germany and Japan are adopting this functionality two vehicle generations earlier than prior luxury-only deployment patterns. The technology is decomposing the historical premium-mass boundary, collapsing margin structures for prism-mirror suppliers unable to fund coating-line conversion.
EPA fuel-economy regulations are indirectly accelerating aerodynamic mirror housing designs that reduce vehicle drag coefficients. Mirror suppliers must now co-develop exterior housing shapes with OEM aerodynamics teams, adding CFD validation costs to development programs. This regulatory pressure most affects North American full-size truck and SUV platforms where mirror frontal area significantly impacts fleet-average compliance.
Fleet procurement departments are consolidating mirror specification authority away from maintenance divisions into centralized asset-management functions. Large commercial operators in the United States are negotiating direct frame-agreement supply relationships with mirror-electronics integrators, disintermediating traditional aftermarket distributors. This channel compression concentrates volume with suppliers offering telematics-compatible mounting hardware and standardized wiring harnesses.
Automotive Inside Rearview Mirrors (IRVM) Market Segmentation
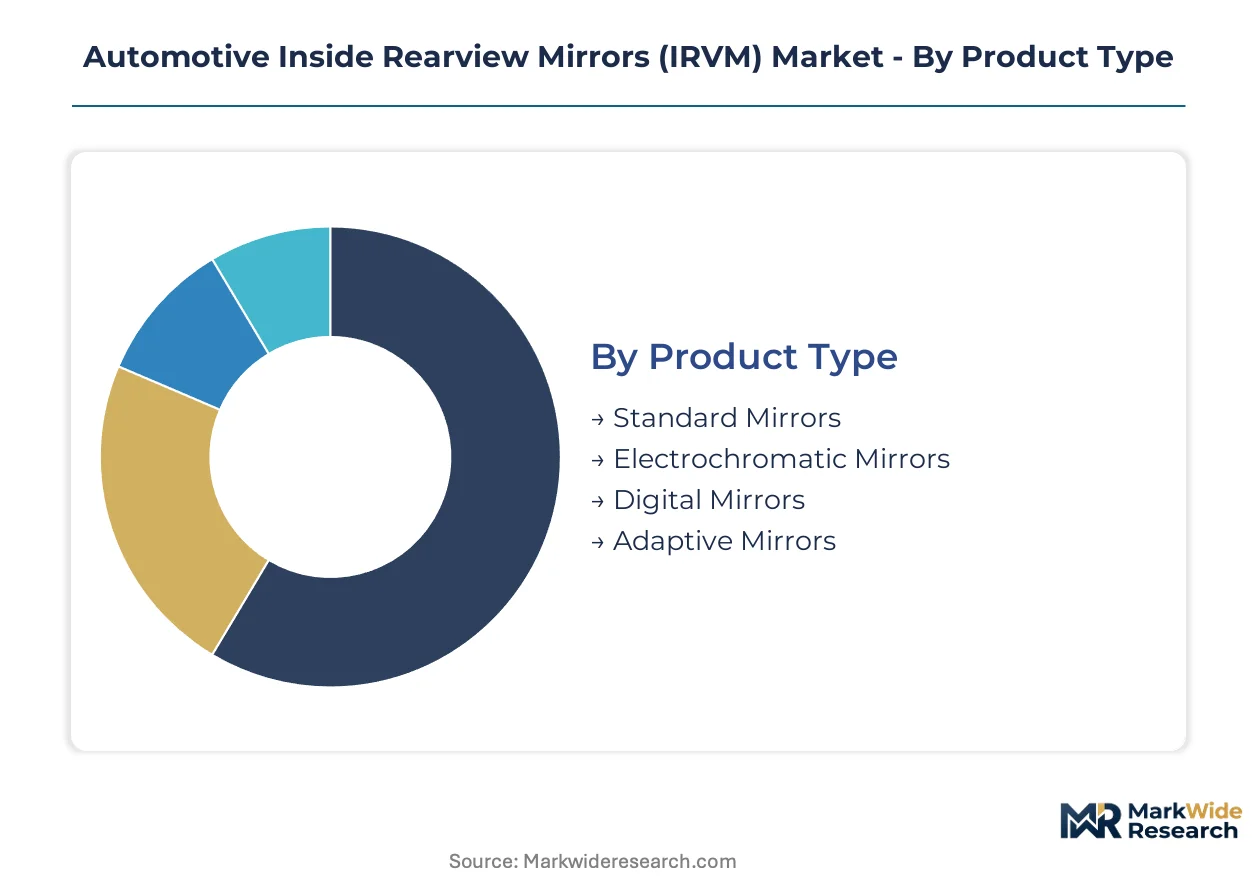
Channel dynamics in the IRVM market diverge sharply between captive OEM supply and fragmented aftermarket procurement. Technology selection and installation complexity determine which segments flow through integrated Tier-1 relationships versus independent distributor networks.
Product Type:
Standard and electrochromatic mirrors dominate OEM channel volume, while digital variants concentrate in premium direct-supply programs. Aftermarket distributors handle universal-fit standard mirrors for fleet retrofit channels.
- Standard Mirrors:Prism-based optical assemblies using wedge-shaped glass with manual tilt functionality. Demand concentrates in entry-level passenger vehicle programs from Indian and Southeast Asian OEMs where cost floors exclude electrochromatic gel chemistry. BIS visibility mandates are tightening specifications without triggering technology migration.
- Electrochromatic Mirrors:Gel-layer electrochemical cells modulating reflectivity through voltage-controlled ion intercalation. German and Japanese mid-segment OEMs are adopting this functionality two vehicle generations ahead of prior luxury-only deployment patterns. ECE R46 automatic dimming mandates are compressing prism-mirror architectures across European supply chains.
- Digital Mirrors:Camera-display systems replacing optical glass with LCD or OLED panels. Premium passenger vehicle programs in Japan and Germany specify these for flagship sedans and electric crossovers.
- Adaptive Mirrors:Multi-axis positioning systems with integrated blind-spot indicators and turn-signal repeaters. North American full-size truck platforms specify these for towing configurations.
Standard mirrors dominate installed base. Electrochromatic variants are where expansion concentrates.
Technology:
Cost tier determines technology selection, with glass substrates anchoring economy programs and OLED commanding premium specification tiers. LCD intermediates for mid-market digital mirror deployments.
- LCD:Transmissive liquid-crystal panels with LED backlighting for digital mirror applications. Mid-segment OEM programs in South Korea specify these as cost-optimized alternatives to OLED.
- OLED:Organic light-emitting diode panels enabling thinner form factors and superior contrast ratios. Premium German and Japanese OEMs specify these for flagship digital mirror programs where display quality justifies unit cost premiums.
- Glass:Soda-lime or borosilicate substrates with vacuum-deposited reflective coatings. Entry-level vehicle assemblers in India and Brazil specify these for cost-constrained programs.
- Autodimming:Electrochromatic gel-layer systems with ambient light sensors and rearward glare detection. Fleet operators in the United States procure aftermarket variants to reduce glare-related accident liability.
Glass substrates anchor volume production. OLED panels are climbing the fastest.
End User:
Customer type shapes procurement authority, with OEMs consolidating specification control while fleet operators disintermediate traditional distribution.
- OEMs:Original equipment manufacturers with captive Tier-1 supply relationships and model-year integration timelines. German premium OEMs specify electrochromatic variants through multi-year frame agreements.
- Aftermarket Providers:Independent distributors and retailers serving collision repair and accessory upgrade channels. These entities concentrate standard mirror volume for North American and European replacement demand.
- Vehicle Assemblers:Contract manufacturers and regional production joint ventures without full R&D autonomy. Indian domestic manufacturers source standard mirrors through localized supply agreements.
- Fleet Operators:Commercial vehicle asset managers with centralized procurement functions. Large North American logistics operators negotiate direct supply relationships for electrochromatic retrofit programs.
OEMs dominate specification authority. Fleet operators are gaining share fastest.
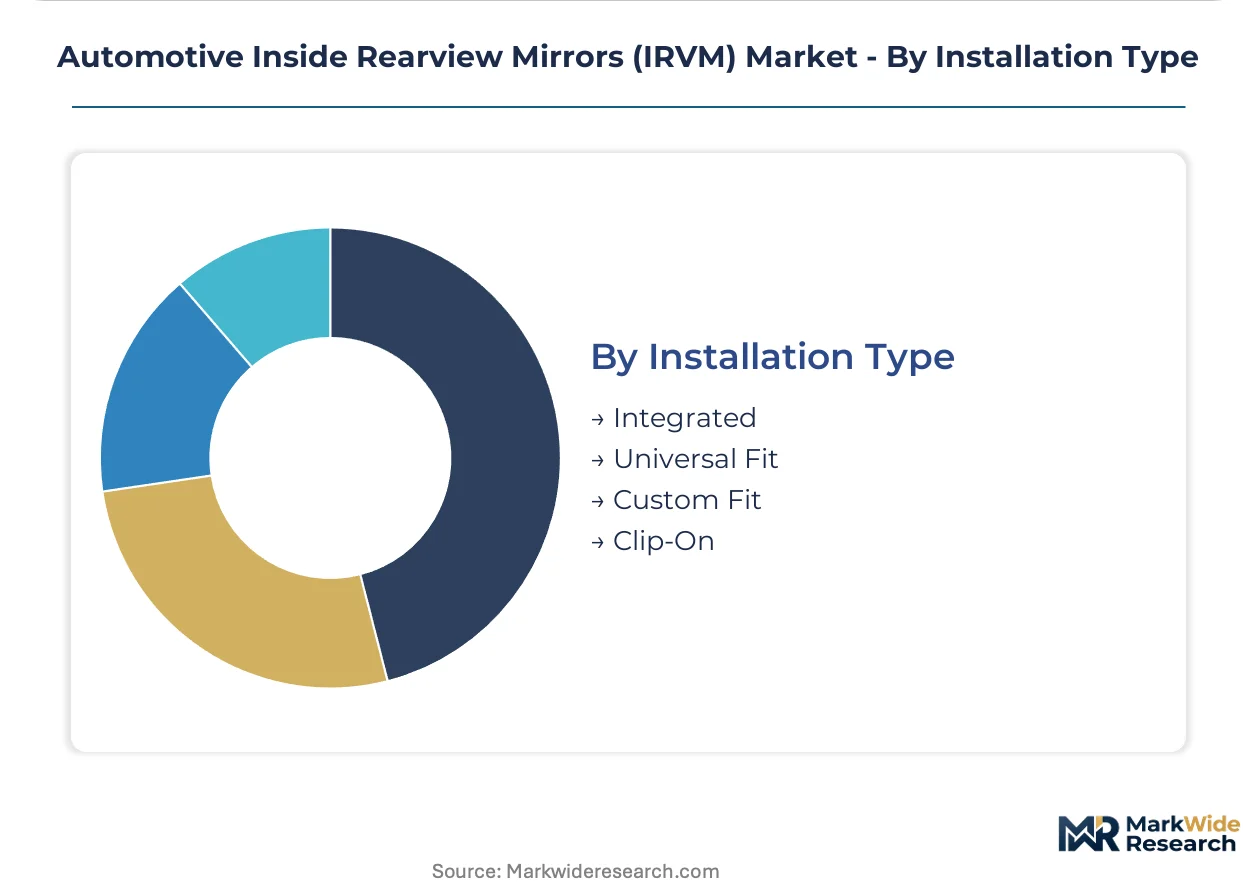
Installation Type:
Integration depth determines channel placement, with factory-integrated modules flowing through Tier-1 relationships and clip-on variants saturating e-commerce aftermarket.
- Integrated:Windshield-mounted or headliner-embedded modules with vehicle harness connectivity and ADAS sensor co-location. Premium OEM programs specify these for electrochromatic and digital variants.
- Universal Fit:Standardized mounting interfaces compatible with multiple vehicle platforms. Fleet retrofit channels concentrate demand for these variants in North American commercial vehicle segments.
- Custom Fit:Vehicle-specific brackets and wiring adapters for model-year-precise replacement. European aftermarket distributors stock these for collision repair programs.
- Clip-On:Temporary mounting solutions for rental fleets and short-term visibility upgrades. These saturate e-commerce channels with minimal technical support requirements.
Integrated modules dominate OEM supply. Universal fit is where aftermarket expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's automotive logistics throughput underwrites Germany's central role in European mirror supply chains. Stuttgart's manufacturing corridor and Munich's electronics clusters form the continent's densest concentration of integrated mirror-electronics production. Rail freight links from Bavaria to Bremerhaven anchor export capacity for premium OEM programs.
Germany
ECE R46 compliance mandates are compressing prism-mirror architectures across Baden-Württemberg and Bavaria. Stuttgart's supplier ecosystem around Daimler and BMW specifications drives electrochromatic adoption two vehicle generations ahead of prior luxury-only patterns. KBA homologation requirements enforce 18-24 month certification cycles that favor established coating-line operators.
United States
NHTSA FMVSS 111 field-of-view standards govern reflectivity requirements while EPA fuel-economy regulations indirectly shape aerodynamic housing designs. Michigan's automotive engineering base and Ontario's cross-border electronics manufacturing support integrated mirror-ADAS module development. Fleet operators in the Great Lakes region negotiate direct frame agreements for aftermarket electrochromatic retrofit programs.
Japan
METI industrial standards and JIS certification requirements structure technology migration timelines for domestic OEMs. Nagoya's Toyota supply corridor and Tokyo's electronics design houses concentrate digital mirror development for flagship sedan programs. Camera-display convergence in premium electric crossovers creates specification tiers distinct from European regulatory frameworks.
India
BIS automotive safety standards are tightening visibility requirements without triggering full electrochromatic migration. Maharashtra and Tamil Nadu vehicle assembly clusters source standard mirrors through localized supply agreements. Domestic manufacturers balance cost floors against incremental specification upgrades mandated by central government safety notifications.
South Korea
MFDS oversight applies to biometric sensor integration while MIIT-aligned export standards govern display quality for China-bound production. Seoul Capital Area electronics fabricators supply LCD panels for mid-market digital mirror programs. Hyundai-Kia specification authority drives technology selection across domestic and export vehicle platforms.
Automotive Inside Rearview Mirrors (IRVM) Market Competitive Environment
Listed leaders compete with private specialists across electrochromatic gel chemistry and mechatronics integration. The supplier base organizes into three tiers: multinational integrators with captive OEM relationships, regional electronics fabricators serving second-tier vehicle assemblers, and aftermarket distributors handling fleet retrofit channels. Two dominant competitive moves are reshaping positioning: backward integration into transparent conductive oxide substrate supply, and geographic expansion through engineering center placement in Barcelona and Ontario clusters.
Within the multinational integrator tier, Gentex Corporation and Magna International exemplify divergent scale strategies. Ficosa International occupies a position bridging mechatronics specialization with digital mirror development capacity. These three anchors represent distinct archetypes: electrochromatic technology leadership, production scale through integrated manufacturing, and Barcelona-centered engineering hub positioning.
| Leading Market Players |
|---|
| Ficosa International |
| SL Corporation |
| Gentex Corporation |
| Burco Inc. |
| FLABEG Automotive Glass Group |
| Magna International |
| Murakami Corporation |
| Valeo |
| Samvardhana Motherson Reflectec |
| Others |
Value Chain & Pricing Dynamics
Electrochromatic gel-layer chemistry displacing prism-mirror architectures simultaneously redistributes supplier leverage toward coating-line operators in Bavaria and Ontario while compressing margin structures for legacy glass-substrate producers unable to fund ECE R46 recertification investments.
Pricing Analysis
Certification level creates the primary spread, with KBA-homologated electrochromatic modules commanding premium positioning over uncertified aftermarket variants. Pricing stratifies across premium OEM frame agreements, mid-segment bundled supply, and economy universal-fit tiers. Cost compression in standard mirror segments intensifies as Indian vehicle assemblers source localized glass substrates. Fleet operators exhibit highest price sensitivity, while German premium OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate OEM supply relationships, with strategic stockpiling limited to indium-tin-oxide substrates vulnerable to rare-earth volatility. Production gravity centers on Germany, Japan, and Ontario, with gel chemistry and thin-film deposition expertise concentrating in Stuttgart and Nagoya corridors. Supply chains rest on transparent conductive oxide substrates, electrochromatic gel formulations, and camera ISP components. Single-source vulnerability in Bavarian integrated mirror-electronics modules creates structural risk. Distribution runs through captive Tier-1 relationships for OEM channels and direct frame agreements for fleet retrofit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camera-display digital mirror systems threaten optical glass-mirror incumbents, forcing established suppliers to defend technology positioning while regulatory divergence between NHTSA field-of-view standards and camera-exemption pathways creates strategic uncertainty.
For Market Incumbents: Compound electrochromatic technology leadership through backward integration into transparent conductive oxide substrate supply and accelerated ECE R46 certification timelines to lock out prism-mirror competitors. Prioritize coating-line conversion investments in Ontario and Bavaria manufacturing clusters before mid-segment adoption waves saturate capacity. Digital mirror entrants and indium-tin-oxide cost volatility represent dual threats requiring simultaneous defense. For New Entrants and Emerging Players: Aftermarket fleet telematics integration presents underserved white-space where incumbent Tier-1 suppliers lack direct commercial vehicle relationships. Target North American logistics operators with bundled electrochromatic retrofit and connectivity hardware bypassing traditional distributor networks. Pursue BIS certification pathways for Indian domestic vehicle assembler supply as the most penetrable geography outside established OEM captive relationships. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors electrochromatic specialists with proven coating-line scale over digital mirror development-stage ventures. Long-term viability hinges on regulatory reconciliation between camera-replacement exemptions and optical safety mandates. Acquisition targets should demonstrate ECE R46 homologation track records and gel-chemistry IP portfolios. Monitor NHTSA FMVSS 111 exemption rulemaking as the critical inflection signal for digital mirror deployment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Electrochromatic Coating-Line Conversion | ECE R46 compliance mandates force prism-mirror suppliers to fund gel-chemistry retooling or exit. |
| Backward Integration into TCO Substrates | Indium-tin-oxide supply control insulates margins from rare-earth price volatility affecting electrochromatic production. |
| Fleet Telematics Bundling | Direct frame agreements with logistics operators disintermediate aftermarket distributors and capture retrofit volume. |
| Biometric Sensor FDA Pathway | Driver monitoring integration creates new device categories with higher regulatory barriers and pricing power. |
| Barcelona Engineering Hub Expansion | Mechatronics talent concentration supports digital mirror development for premium Japanese and German OEM programs. |
Study Parameters
Initial hypotheses were tested against primary input from Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operations managers and refined through secondary validation. Sources included vehicle production databases, IHS Markit registration data, KBA homologation records, and SEC filings from listed mirror-electronics integrators. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates.
Variance decomposition across product type, technology, end user, installation type, and regional production cluster shaped the analytical framework. CAGRs were derived from segment-level growth trajectories applied across the projection horizon. Forecast inputs incorporated ECE R46 implementation timelines, NHTSA exemption pathway probabilities, and electrochromatic adoption curves by vehicle segment.
Underlying assumptions cover regulatory compliance schedules, raw material cost stability, and OEM technology migration patterns, with deviation risk concentrated in camera-display exemption rulings and rare-earth supply disruptions. Revision becomes warranted when regulatory divergence between optical and camera-based standards crosses enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Automotive Air Suspension System Market
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Automotive OEM Interior Coatings Market
Automotive Interior & Exterior
Automotive Center Stack Display Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Automotive Liftgate Market
Automotive Interior & Exterior
Laser Headlight Market
Automotive Interior & Exterior
Automotive Portable Refrigerator Market
Automotive Interior & Exterior
India Automotive Door Seals Market
Automotive Interior & Exterior
Automotive Door Frame Market
Automotive Interior & Exterior
Automotive Chromium Finishing Market
Automotive Interior & Exterior
Door Panel Market
Automotive Interior & Exterior
Windscreen Washer System Market