
 LED Fog Lamp Market | 2026-2036
LED Fog Lamp Market Size, Share, and Industry Trends Forecast 2026-2036
LED Fog Lamp Market Outlook
Aftermarket distributors and independent repair networks is collapsing the historical OEM-dominant procurement model for LED fog lamps. KOITO MANUFACTURING CO., LTD. anchors Japanese automaker supply chains through captive production lines in Yokohama and Tianjin. Valeo competes across European premium platforms with modular lamp assemblies that reduce wiring complexity. HELLA GmbH & Co. KGaA specializes in thermal management substrates that extend LED diode life in high-humidity climates.
An LED fog lamp is a vehicular forward-illumination device employing semiconductor light-emitting diodes operating in the 3000K to 6000K color temperature range, engineered to project a wide, low beam pattern that minimizes glare reflection in aerosol-laden atmospheric conditions. The assembly typically integrates aluminum-backed printed circuit boards, polycarbonate lenses with anti-fog coatings, and pulse-width modulation drivers to sustain output during voltage fluctuations. Dual Beam and Adaptive product types now command the margin pool as automakers consolidate fog and cornering functions into single housings. Aftermarket channels for Passenger Cars represent the fastest-growing end-user dimension, fueled by retrofit demand in regions with aging vehicle fleets and lenient modification rules.
Federal Motor Vehicle Safety Standard No. 108 administered by NHTSA governs photometric performance and color boundaries in the United States, while ECE Regulation 19 shapes homologation requirements across European type-approval regimes. China's GB 4599 standard enforced by SAMR mandates specific luminous intensity distributions that favor localized supplier development. Stakeholders must monitor divergence between regional certification protocols and the cost of maintaining parallel design variants.
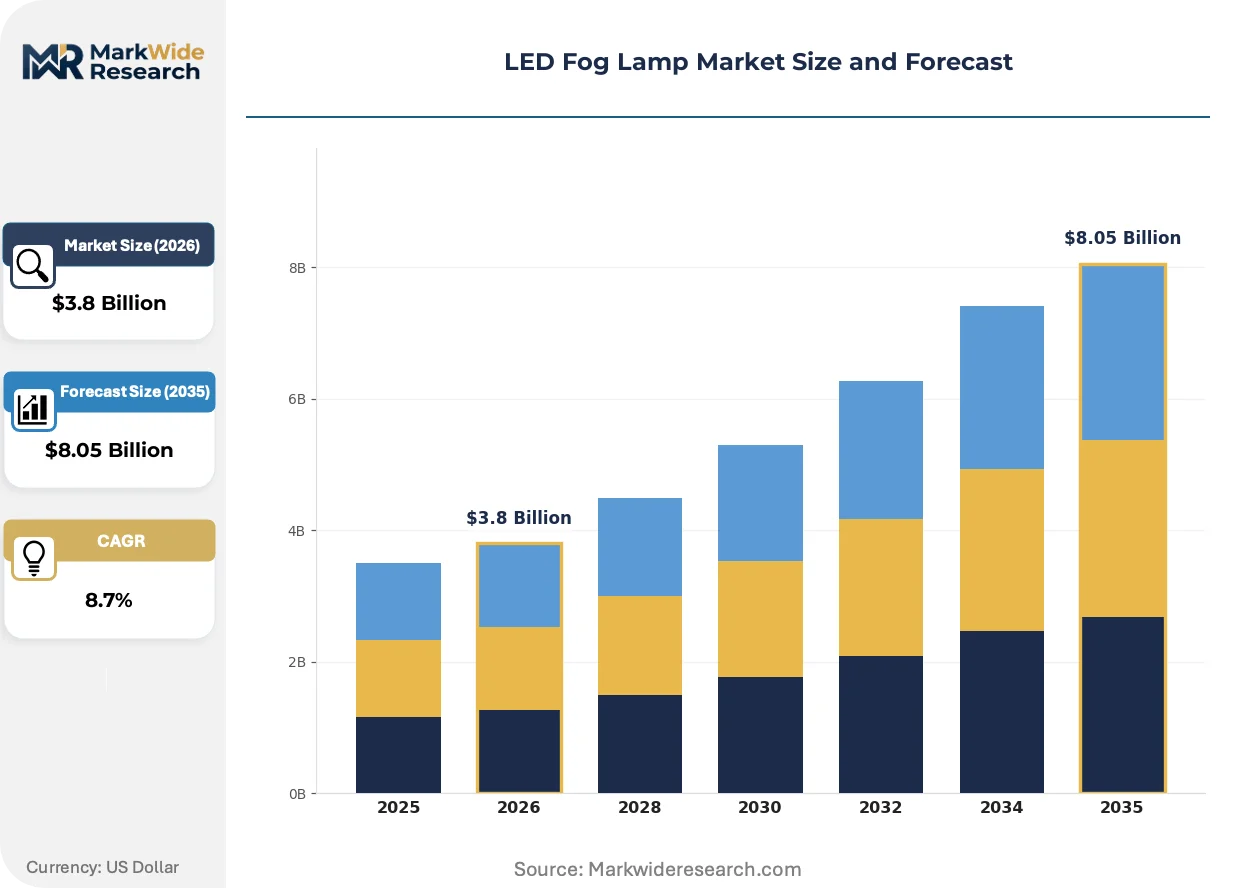
Market Dynamics
Multi-LED array architectures are collapsing the single-housing paradigm as automakers consolidate fog, cornering, and daytime running functions into unified modules, compressing supplier margins while expanding performance specifications.
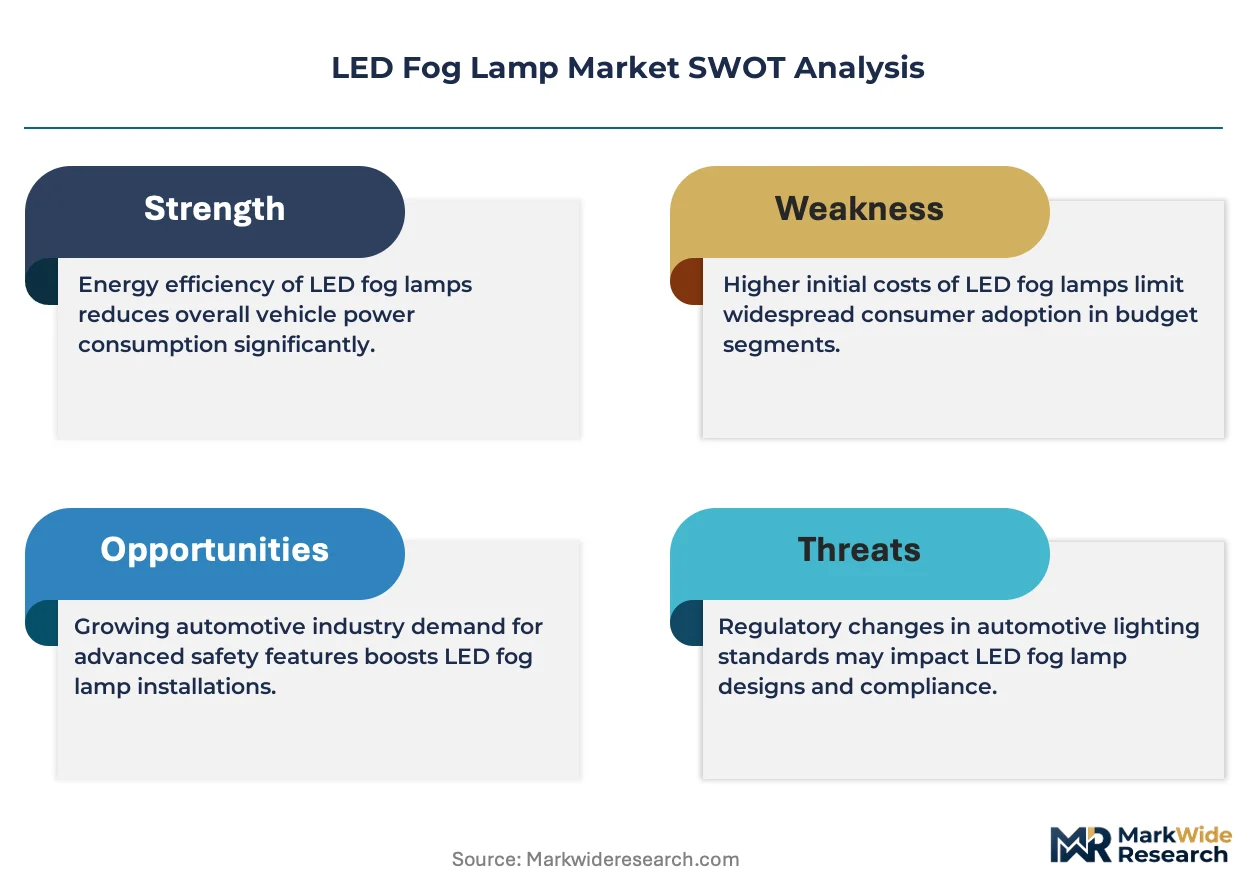
Growth Catalysts
- ECE Regulation 19 compliance:European type-approval requirements for beam pattern precision and color temperature boundaries are accelerating replacement cycles in aging vehicle fleets across Germany, France, and Italy.
- Retrofit channel expansion:Independent repair networks in North America and Southeast Asia now stock plug-and-play LED fog lamp kits that bypass dealer service departments entirely.
- Polycarbonate lens coatings:Anti-fog and hydrophobic surface treatments developed for high-humidity climates are extending product lifecycles and reducing warranty claims in coastal markets.
Market Restraints
- Aluminum substrate cost volatility:Thermal management PCBs require high-purity aluminum backed by copper traces, exposing assemblers to London Metal Exchange price swings.
- Driver IC supply concentration:Pulse-width modulation controllers for automotive lighting concentrate among Taiwanese and South Korean foundries, creating single-source vulnerability.
- Halogen residual stock:Remaining inventory of tungsten-halogen fog lamps in distributor warehouses delays full LED conversion in price-sensitive aftermarket segments.
Strategic Opportunities
- Adaptive beam integration:Sensor-fused fog lamps that adjust intensity based on precipitation density represent unpenetrated white space in premium passenger car segments.
- India BIS certification pathway:India's Bureau of Indian Standards automotive lighting regulations are creating first-mover advantage for suppliers establishing local testing facilities.
- Direct-to-installer platforms:Digital procurement portals connecting Chinese LED module manufacturers with European independent garages are compressing traditional distributor markups.
Industry Challenges
- Photometric calibration expertise:Precision alignment of multi-diode arrays to meet ECE and NHTSA intensity distribution requirements demands scarce optical engineering talent.
- Homologation timeline compression:Parallel certification tracks for GB 4599, FMVSS 108, and ECE Regulation 19 variants extend product development cycles and strain testing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Fog Lamp Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Beam, Dual Beam, Adaptive, Integrated Technology: Halogen, Xenon, LED, OLED End User: OEMs, Aftermarket, Commercial Vehicles, Passenger Cars Installation: Front Mount, Rear Mount, Custom Fit, Universal Fit |
| Companies Covered | Koninklijke Philips N.V., Marelli, Osram, IPF Corporation, Robert Bosch GmbH, HELLA GmbH & Co. KGaA, KOITO MANUFACTURING CO., LTD., SL Corporation, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Fog Lamp Market Strategic Shifts
Active matrix LED drivers and chip-scale packaging are redrawing the boundary between semiconductor and lighting assembly, enabling functions that previously required separate control modules.
Chip-on-board LED technology is miniaturizing thermal pathways by eliminating traditional package substrates and wire bonds, allowing diode densities above 200 chips per square centimeter. Tier 1 suppliers in Japan and Germany are adopting these configurations for next-generation adaptive fog lamps. The resulting form factor reduction is enabling lamp housings that integrate directly into bumper fascias without separate mounting brackets.
China's GB 4599 standard revisions under SAMR oversight are mandating stricter luminous intensity uniformity across the beam pattern, forcing redesigns of optic arrays that previously prioritized center-hotspot performance. Domestic suppliers in Jiangsu and Zhejiang provinces are investing in goniophotometer testing equipment to accelerate compliance. The regulatory pressure is accelerating consolidation among smaller assemblers unable to absorb certification costs.
Independent repair networks now account for the majority of LED fog lamp volume in North American and European aftermarket channels, displacing traditional automotive dealer service departments as the primary installation point. These installers favor modular plug-and-play designs that reduce labor time and eliminate coding requirements. The channel shift is most pronounced in Germany and the United Kingdom, where right-to-repair legislation strengthens independent garage market access.
LED Fog Lamp Market Segmentation
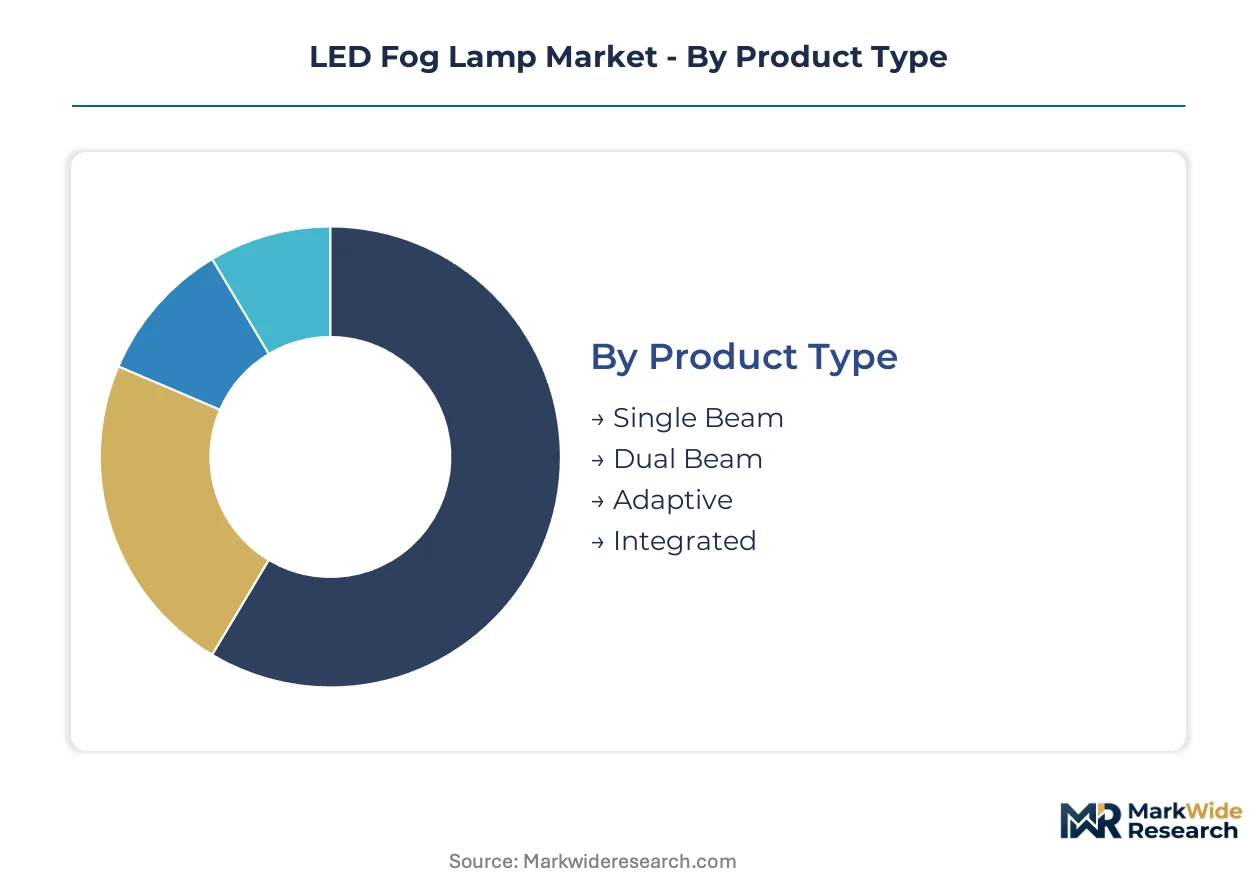
Segmentation in LED fog lamps exposes divergent margin structures across procurement channels and mounting configurations. Product architecture choices directly determine thermal management requirements and homologation pathways. Understanding these divides clarifies where supplier resources generate returns versus commodity exposure.
Product Type:
Single Beam and Dual Beam variants dominate export flows from Chinese manufacturing clusters, while Adaptive and Integrated systems serve domestic premium assembly programs in Germany and Japan.
- Single Beam:Fixed-pattern LED arrays projecting one consistent beam shape without dynamic adjustment. Demand concentrates in Southeast Asian aftermarket channels where cost sensitivity overrides feature complexity and retrofit simplicity drives volume.
- Dual Beam:Housings that switch between fog and cornering illumination through secondary diode activation or mechanical shielding. European OEMs in Stuttgart and Munich specify these for C-segment platforms seeking consolidated lighting modules.
- Adaptive:Sensor-linked arrays modulating intensity and spread based on precipitation density or steering angle.
- Integrated:Fog functions merged into multi-purpose daytime running or headlamp assemblies.
Single Beam commands the established base. The steepest expansion runs through Adaptive.
Technology:
Cost tiers separate legacy filament sources from semiconductor architectures, with OLED occupying a narrow premium niche.
- LED:Semiconductor diodes operating in 3000K to 6000K color temperatures with aluminum-backed PCBs and PWM drivers. Jiangsu and Zhejiang province suppliers ship these modules to European and North American retrofit distributors under ECE Regulation 19 and NHTSA FMVSS 108 certifications.
- Halogen:Tungsten-halogen filaments in borosilicate envelopes with standardized H8, H11, or H16 bases. Aging vehicle fleets in Eastern European markets sustain residual demand despite efficiency disadvantages.
- Xenon:High-intensity discharge arc sources requiring ballast ignition and high-voltage cabling.
- OLED:Organic electroluminescent panels enabling thin-form surface illumination without reflector optics.
LED holds the revenue core. OLED claims the margin frontier.
End User:
Procurement authority is shifting from captive OEM supply agreements toward independent distribution networks.
- Aftermarket:Independent repair networks and direct-to-installer platforms sourcing plug-and-play LED fog lamp kits. German and United Kingdom garages now account for majority volume in European channels, accelerated by right-to-repair legislation weakening dealer service monopolies.
- OEMs:Original equipment manufacturers specifying lamp assemblies through tiered supply contracts with thermal management and photometric performance guarantees.
- Passenger Cars:Private vehicle owners pursuing retrofit upgrades or replacement cycles.
- Commercial Vehicles:Fleet operators with standardized maintenance protocols and durability requirements.
OEMs retain specification control. Aftermarket captures volume acceleration.
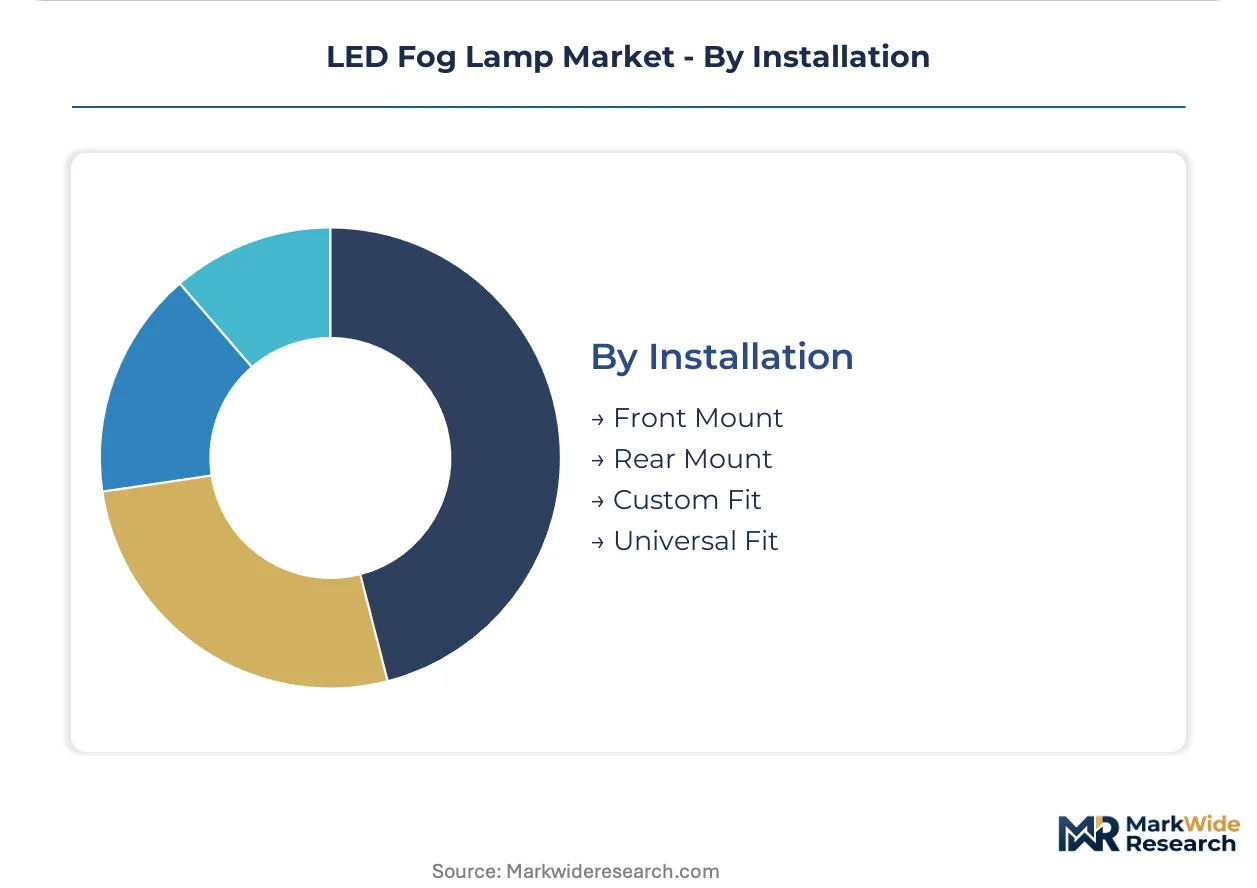
Installation:
Mounting geometry dictates housing design complexity and regulatory testing scope.
- Front Mount:Bumper-integrated or fascia-cutout installations in conventional forward-facing positions. Chinese domestic suppliers optimize these for local assembly plants while parallel export programs serve European premium platforms requiring ECE type-approval.
- Universal Fit:Standardized bracket systems accommodating multiple vehicle geometries without model-specific tooling. North American distributors favor these for inventory efficiency across heterogeneous vehicle fleets.
- Rear Mount:Supplementary reverse or trailer illumination configurations.
- Custom Fit:Vehicle-specific housings requiring precise bumper modification.
Front Mount anchors production scale. Universal Fit enables channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aftermarket distributors and independent repair networks concentrate procurement authority across distinct national regulatory environments. Buyer archetypes vary sharply between German right-to-repair garages, Chinese export-oriented assemblers, and US direct-to-installer platforms.
China
Domestic suppliers in Jiangsu and Zhejiang provinces feed both local assembly plants and European export programs under GB 4599 standard revisions. SAMR oversight mandates stricter luminous intensity uniformity, forcing goniophotometer investments among smaller assemblers. Yangtze River Delta manufacturing clusters now consolidate as certification costs accelerate exit of sub-scale competitors.
Germany
Right-to-repair legislation strengthens independent garage market access, displacing dealer service departments as primary installation points. ECE Regulation 19 type-approval requirements govern beam pattern precision for retrofit kits entering from Chinese suppliers. Stuttgart and Munich OEMs specify Dual Beam configurations for C-segment platform consolidation.
United States
NHTSA FMVSS 108 governs photometric performance and color boundaries for aftermarket retrofit channels. Independent repair networks in Southeast and Midwest regions stock plug-and-play LED fog lamp kits that bypass dealer service departments. Direct-to-installer digital platforms compress traditional distributor markups across heterogeneous vehicle fleets.
Japan
KOITO MANUFACTURING CO., LTD. anchors domestic automaker supply chains through captive production lines in Yokohama. METI industrial policy supports chip-on-board LED technology adoption for next-generation adaptive fog lamp architectures. Kanto region Tier 1 suppliers pursue miniaturized thermal pathways enabling bumper-integrated housings without separate mounting brackets.
India
Bureau of Indian Standards automotive lighting regulations create first-mover advantage for suppliers establishing local testing facilities. Aging vehicle fleets in Maharashtra and Gujarat sustain retrofit demand among independent repair networks. Domestic assemblers invest in BIS certification pathways to capture premium passenger car segments before multinational incumbents localize.
LED Fog Lamp Market Competitive Environment
Player mix skews toward diversified lighting conglomerates with captive thermal management capabilities and specialized Japanese Tier 1 suppliers with automaker-captive relationships. Market structure exhibits moderate consolidation around five to seven entities controlling critical LED driver IC and substrate supply chains. Two strategic archetypes dominate: integrated automotive lighting systems providers with full-stack optic-to-electronics capabilities, and focused LED module specialists serving aftermarket retrofit channels. Competitive moves concentrate on backward integration into aluminum substrate production and geographic expansion through local certification facilities in India and China.
Among diversified European lighting conglomerates, HELLA GmbH & Co. KGaA and Valeo exemplify the integrated systems archetype with thermal management and modular assembly competencies. KOITO MANUFACTURING CO., LTD. represents the Japanese Tier 1 captive-supply model with production lines anchored in Yokohama and Tianjin. These three entities occupy positions spanning OEM specification control and aftermarket channel access, with differentiation residing in substrate engineering expertise versus automaker relationship depth.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Marelli |
| Osram |
| IPF Corporation |
| Robert Bosch GmbH |
| HELLA GmbH & Co. KGaA |
| KOITO MANUFACTURING CO., LTD. |
| SL Corporation |
| Valeo |
| Others |
Value Chain & Pricing Dynamics
ECE Regulation 19 certification gates both supplier qualification and price stratification across European aftermarket channels, forcing parallel design variants that segment pricing by homologation tier rather than component cost alone. Chinese exporters to Germany and France must maintain separate SKU lines for ECE-compliant modules versus non-certified alternatives, compressing margin pools for assemblers lacking testing infrastructure.
Pricing Analysis
London Metal Exchange-linked aluminum substrate contracts index pricing volatility directly into module costs, with Taiwanese PWM driver IC shortages amplifying spot-market premiums for automotive-grade components. Three-tier pricing structure across premium adaptive systems, standard dual-beam modules, and economy single-beam kits reflects certification grade and thermal management complexity rather than raw diode counts. Cost compression in the economy tier intensifies as Jiangsu province suppliers absorb goniophotometer investments to meet GB 4599 revisions. Independent repair networks in Germany exhibit lowest price sensitivity due to right-to-repair labor arbitrage, while Southeast Asian distributors prioritize per-unit acquisition cost above lifecycle value.
Supply Chain Analysis
Taiwan Strait shipping lanes concentrate risk for automotive LED driver ICs fabricated at TSMC and UMC foundries, with single-source dependency extending to Seoul-based packaging houses for high-reliability automotive grades. Jiangsu and Zhejiang provinces in China, plus Yokohama manufacturing clusters in Japan, anchor global module assembly capacity. High-purity aluminum thermal substrates, polycarbonate optical-grade resins, and copper-clad PCB laminates constitute critical input dependencies. Tariff exposure on Chinese-origin lighting modules entering North American channels threatens distributor margin structures. Distribution runs through layered networks: direct-to-installer platforms disintermediate traditional European distributors, while OEM captive supply chains bypass aftermarket channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket channel consolidation among German and United Kingdom independent garage networks is shifting procurement leverage toward installer collectives, fragmenting historical distributor pricing power and compressing available margin for non-integrated suppliers.
For Market Incumbents: Shield specification control by deepening captive relationships with Stuttgart and Munich OEM platform engineers, while backward integration into aluminum substrate production mitigates London Metal Exchange volatility that erodes module profitability. Valeo and HELLA GmbH & Co. KGaA demonstrate the defensive value of thermal management substrate expertise as a lock-in mechanism against Chinese cost competitors. For New Entrants and Emerging Players: Differentiate on adaptive beam calibration services for premium passenger car retrofit channels, where photometric alignment expertise remains scarce and ECE Regulation 19 compliance creates service-based recurring revenue. India's BIS certification pathway offers the most penetrable geography, with Maharashtra and Gujarat garage networks underserved by localized testing-capable suppliers. Direct-to-installer digital procurement platforms provide the optimal go-to-market angle, bypassing distributor markups that disadvantage new entrants. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across adaptive LED fog lamp sub-segments as sensor fusion and active matrix driver requirements demand semiconductor competency beyond traditional lighting assembly. Long-term viability favors targets with captive thermal management IP and established ECE or NHTSA homologation track records. The signal to watch is consolidation velocity among Jiangsu province assemblers unable to absorb GB 4599 goniophotometer investments, which indicates distressed acquisition availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Substrates | Captive thermal management supply locks in margin against London Metal Exchange volatility. |
| BIS Certification Facility Establishment | First-mover positioning in India's Maharashtra and Gujarat aftermarket channels preempts multinational localization. |
| Direct-to-Installer Platform Launch | Digital procurement disintermediation captures German and United Kingdom garage network volume acceleration. |
| Adaptive Beam Sensor Fusion Development | Precipitation-responsive intensity modulation opens premium passenger car white space beyond commodity modules. |
| Chip-on-Board LED Packaging Scale-Up | Miniaturized thermal pathways enable bumper-integrated housings that eliminate separate mounting brackets. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the LED fog lamp value chain, including Tier 1 supplier procurement managers, OEM platform lighting engineers, aftermarket distributor category heads, independent garage installation technicians, and regulatory compliance specialists at SAMR and KBA. Secondary validation drew from ECE Regulation 19 type-approval databases, NHTSA FMVSS 108 photometric filings, Chinese customs export statistics for lighting modules, and aluminum substrate trade flow data. Bottom-up volume estimates from Jiangsu and Zhejiang province production clusters were triangulated against top-down OEM platform content-per-vehicle assumptions.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product architecture (single beam through adaptive integrated systems), procurement channel (OEM captive versus aftermarket independent), vehicle class tier, and regional regulatory cluster. CAGRs were derived from production volume trajectories weighted by average selling price evolution across certification tiers. Industry-specific inputs included GB 4599 revision implementation timelines, right-to-repair legislative penetration rates in European markets, and chip-on-board LED adoption curves from Japanese Tier 1 supplier disclosures.
The analysis sits within stated boundaries; outcomes outside sustained ECE and NHTSA regulatory stability or absent aluminum price normalization would require recalibration. Forecasts reflect assumptions regarding aftermarket channel share gains and Chinese export program continuity, with specific risk factors including Taiwan Strait logistics disruption, divergent regional photometric standards, and halogen residual inventory absorption delays. Practitioners should keep alternative scenarios live as certification timeline compression and driver IC supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
Global Car Air Purifier Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Automotive Door Sills Market
Automotive Interior & Exterior
Automotive Soft Trim Interior Materials Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
Automotive Heaters Market
Automotive Interior & Exterior
Automotive Auto Dimming Mirror Market
Automotive Interior & Exterior
Europe Automotive Seat Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Laser Lighting Market