
 Global Automotive Intelligent Seats Market | 2026-2036
Global Automotive Intelligent Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Intelligent Seats Market Intelligence
The ISO 26262 functional safety standard for road vehicles is collapsing the distinction between traditional seat suppliers and electronics specialists. Lear Corporation leverages its deep expertise in seating systems to integrate complex electronics. Magna International Inc. competes by offering modular systems that combine seating with other interior components. Forvia SE differentiates through its advanced human-machine interface technologies integrated into the seat structure.
Automotive intelligent seats are vehicle seating systems integrated with electronic components and software. They incorporate elements like embedded pressure sensors and microcontrollers to actively monitor occupant status and adjust seat properties. Massage and ventilated seats represent high-margin features, primarily in luxury vehicles and electric vehicles. The integration of voice control technology is becoming a standard expectation in passenger cars, moving beyond a premium-only feature.
Regulations from bodies like the NHTSA in the United States and the EU's General Safety Regulation influence the integration of safety-related seat functions. Concurrently, China's GB standards for vehicle components set specific performance and material requirements for market entry. Suppliers must decide whether to develop full-stack software and hardware capabilities in-house or pursue partnerships with technology specialists.
Market Dynamics
The convergence of mechanical engineering and software development represents the central force shaping the automotive intelligent seats market. Functional safety standards like ISO 26262 are compelling traditional suppliers to build deep electronics and systems integration capabilities to remain competitive in a software-defined vehicle architecture.
Growth Catalysts
- Electric Vehicle Adoption:The EV segment's focus on premium interiors and high-margin features accelerates the inclusion of intelligent seats with massage and ventilation.
- Safety Regulations:Mandates from the EU's General Safety Regulation and NHTSA for improved occupant detection drive the integration of sensor-based systems.
- Gesture Recognition Technology:The integration of gesture controls for seat adjustment enhances user experience and aligns with the industry's move toward minimizing physical buttons.
Market Restraints
- High Bill of Materials:The cost of specialized microcontrollers, actuators, and pressure sensors limits the adoption of advanced features in economy and mid-range vehicles.
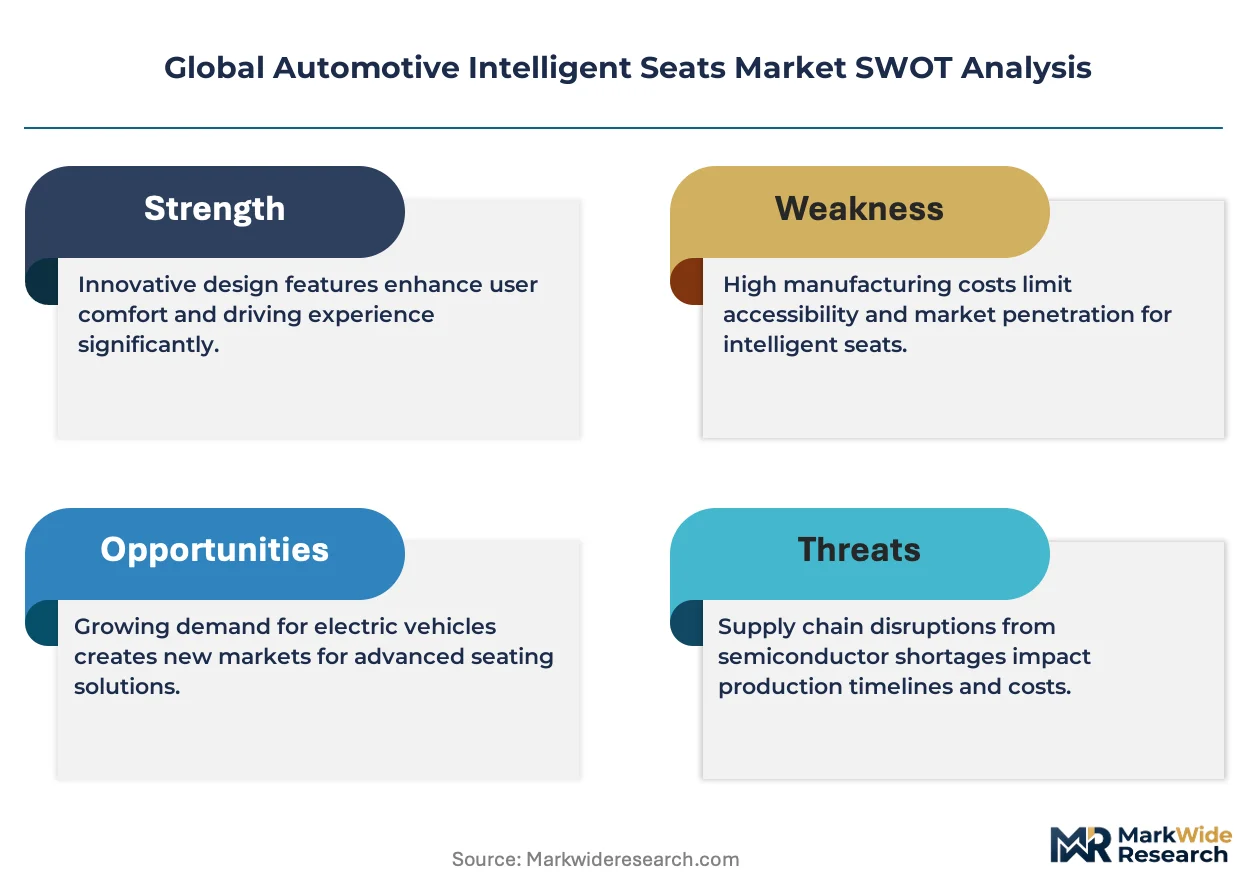
- Semiconductor Dependency:Production schedules are vulnerable to supply chain disruptions for automotive-grade semiconductors, creating manufacturing bottlenecks for seat electronics.
- Software Integration Complexity:Ensuring bug-free, secure operation and seamless communication between the seat's software and the vehicle's main network presents a significant technical hurdle.
Strategic Opportunities
- Biometric Monitoring:Integrating sensors to track occupant health metrics like heart rate variability offers a new frontier for wellness features in passenger cars.
- Commercial Vehicle Segment:There is significant potential in long-haul trucks, where advanced seats can improve driver alertness, reduce fatigue, and comply with operator safety rules.
- Sustainable Materials:Developing intelligent seats using lightweight, recyclable, and bio-based materials presents an opportunity to meet OEM sustainability targets under regulations like the EU's CSRD.
Industry Challenges
- Software Talent Scarcity:A shortage of engineers skilled in both embedded systems programming and the nuances of automotive functional safety slows down development cycles.
- Interoperability Standards:The absence of a universal standard for data communication between different seat modules and vehicle ECUs creates integration complexity for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Intelligent Seats Market |
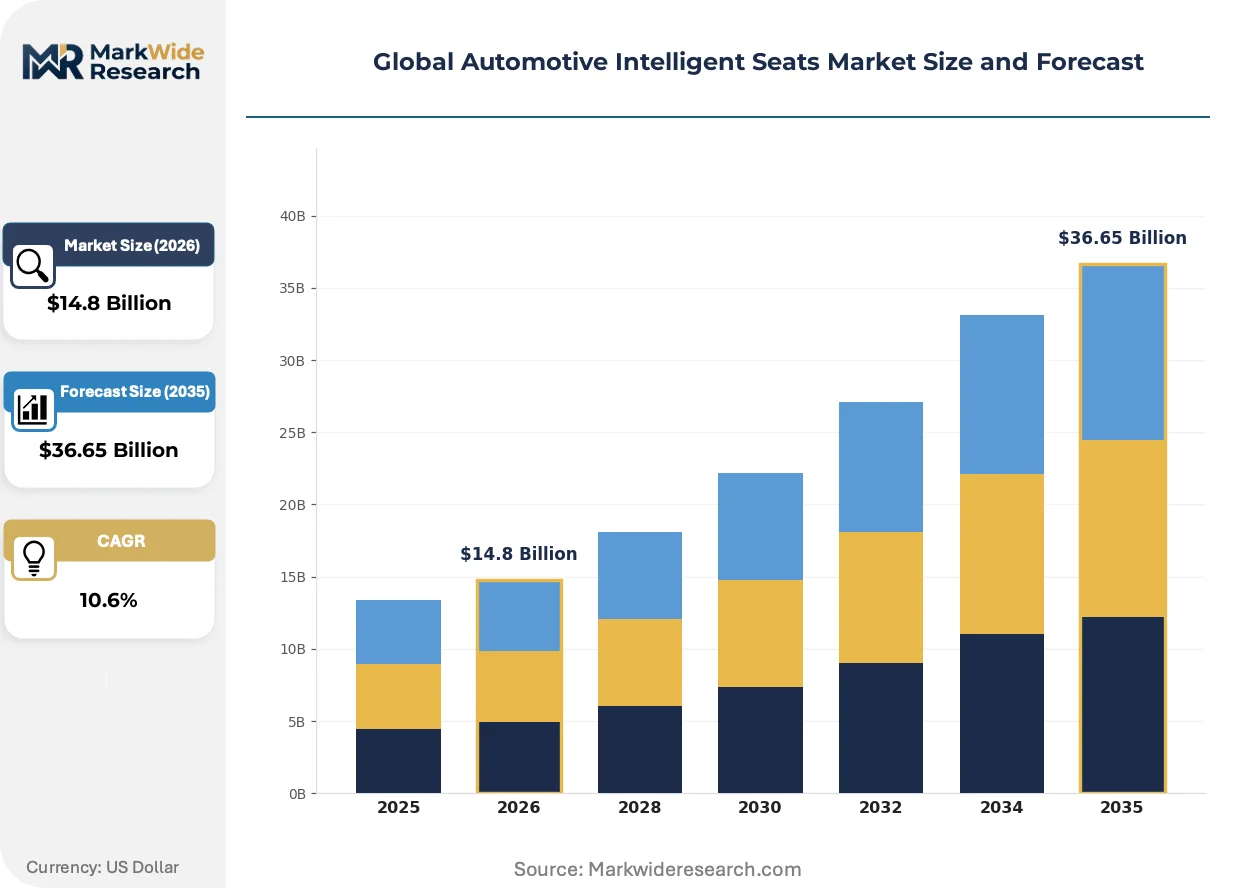
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $36.65 Billion |
| CAGR (2026 – 2036) | 10.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
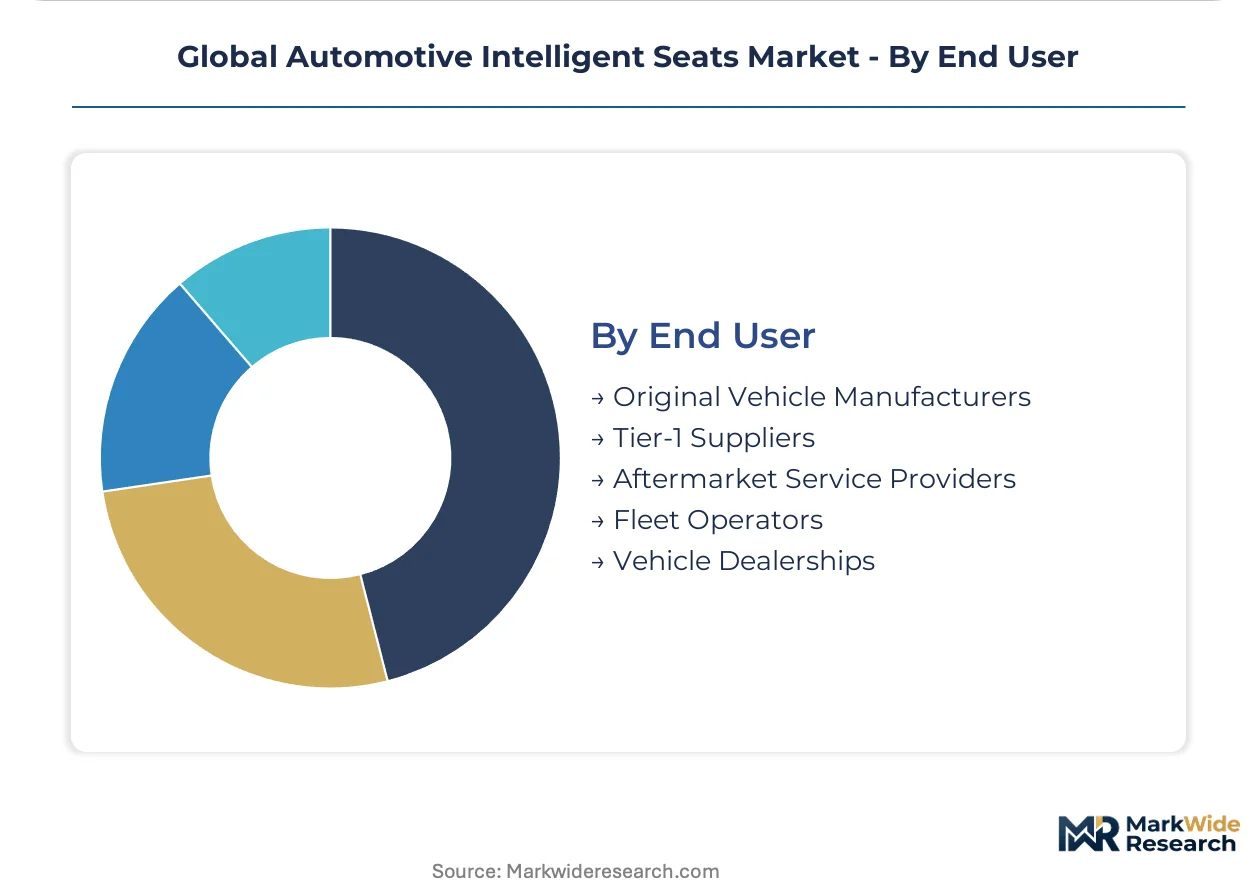
| Segmentation | Product Type: Heated Seats, Ventilated Seats, Massage Seats, Memory Foam Seats, Adjustable Lumbar Support Technology: Pressure Sensors, Temperature Sensors, Gesture Recognition, Voice Control, Wireless Charging Application: Passenger Cars, Commercial Trucks, Electric Vehicles, Luxury Limousines, Autonomous Vehicles End User: Original Vehicle Manufacturers, Tier-1 Suppliers, Aftermarket Service Providers, Fleet Operators, Vehicle Dealerships |
| Companies Covered | Toyota Boshoku Corporation, Gentherm Incorporated, Lear Corporation, Brose Fahrzeugteile, TS Tech, Adient PLC, Magna International Inc, Aisin Seiki Co. Ltd., Forvia SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Intelligent Seats Market Strategic Shifts & Innovations
The market is shifting from offering discrete electronic features toward creating a holistic, software-defined cabin environment. In this model, the seat functions as an active, data-gathering node central to the vehicle's overall user experience and safety architecture, moving beyond simple comfort.
Modular software architecture allows automakers to add or update seat functions via over-the-air updates, a key feature for software-defined vehicles. Luxury and electric vehicle brands are the primary adopters, seeking to offer continuous product improvement throughout the vehicle's life. This trend is fragmenting the traditional hardware-centric development model, forcing suppliers to compete on software flexibility and lifecycle management.
The ISO 26262 functional safety standard is becoming a de facto requirement for electronic seat components tied to safety systems. This standard imposes strict design, validation, and documentation protocols on both hardware and software development. Its impact is most significant for suppliers of systems with high Automotive Safety Integrity Level (ASIL) ratings, necessitating major investments in process compliance and specialized engineering talent.
A behavioral shift sees automotive OEMs demanding fully integrated seating systems rather than procuring individual components. This disrupts the supply chain for smaller specialists in motors or sensors, who must now function as Tier 2 suppliers to large system integrators. The practice is most prominent in China, where vehicle manufacturers prioritize rapid development cycles and streamlined supply chains to gain a competitive edge.
Global Automotive Intelligent Seats Market Segmentation
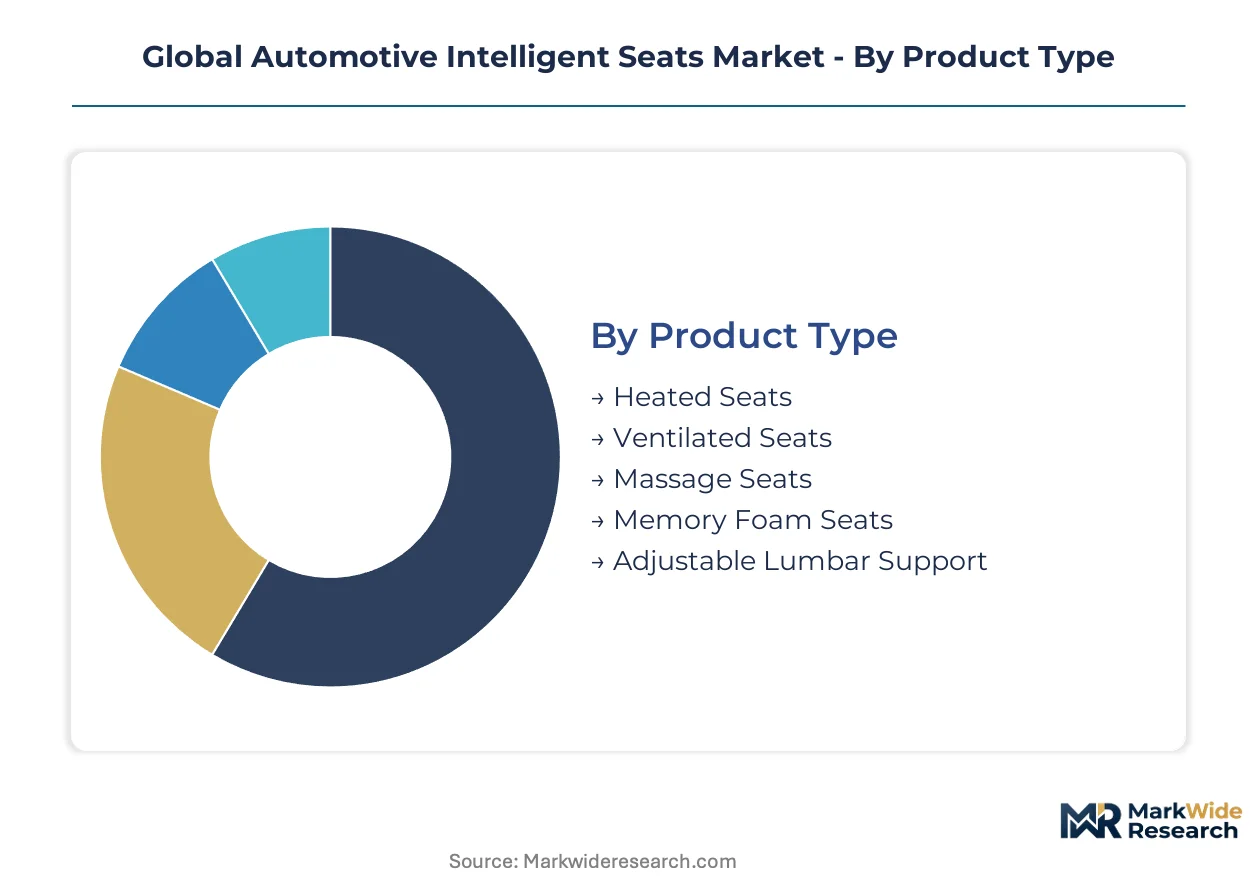
The automotive intelligent seats market categorizes based on distinct product types, enabling technologies, diverse applications, and varied end-user groups. This granular segmentation reveals how specific features and functionalities drive adoption across different vehicle classes and supply chain participants. Understanding these divisions helps pinpoint areas of concentrated demand and technological evolution.
Product Type:
Substitution pressure is most evident in the product type segment, where basic comfort features face competition from advanced, integrated systems.
- Ventilated Seats:Ventilated seats use active cooling systems, often fans through perforations, enhancing occupant comfort. Demand is strong in electric vehicles and luxury cars, driven by premium cabin experiences.
- Massage Seats:Massage seats integrate pneumatic bladders or mechanical rollers for therapeutic functions. These high-margin features see significant adoption in luxury limousines and premium electric vehicles, enhancing occupant well-being.
- Heated Seats:Heated seats embed resistive elements for occupant warmth. Passenger cars widely adopt this feature across various climate zones.
- Memory Foam Seats:Memory foam seats use viscoelastic foam conforming to body shape for ergonomic support. Commercial trucks and luxury vehicles adopt this.
- Adjustable Lumbar Support:Adjustable lumbar support systems allow lower back customization, improving posture and reducing fatigue. Passenger cars and commercial vehicles integrate this.
Heated Seats retain volume leadership; Ventilated Seats hold the steepest expansion curve.
Technology:
The technology segment reflects varying cost tiers, influencing adoption rates across vehicle categories.
- Pressure Sensors:Pressure sensors in seat cushions detect occupant presence, weight, and posture, crucial for airbag deployment and seatbelt reminders. Mandated by NHTSA, they integrate across passenger cars.
- Gesture Recognition:Gesture recognition allows occupants to control seat functions via hand movements, minimizing physical buttons and enhancing user experience. This innovation finds adoption in electric vehicles and luxury segments.
- Temperature Sensors:Temperature sensors monitor seat surface temperatures, enabling precise control for heated and ventilated seats. These are critical for optimal thermal comfort.
- Voice Control:Voice control enables hands-free adjustment of seat settings, improving convenience and reducing driver distraction. This feature is becoming a standard expectation in modern passenger cars.
- Wireless Charging:Wireless charging modules in intelligent seats offer convenient power for mobile devices. Luxury and electric vehicles integrate this for connected cabins.
Advanced sensor technologies form the foundation for intelligent seat functionalities; intuitive human-machine interface technologies unlock new user experiences.
Application:
The application segment highlights varying volume demands and feature sets required by different vehicle categories.
- Passenger Cars:Passenger cars represent the largest application segment, integrating features from basic heating to advanced occupant detection. Demand is driven by consumer expectations for comfort, safety, and personalization across global markets.
- Electric Vehicles:Electric vehicles rapidly adopt intelligent seats, leveraging advanced electrical architectures for massage, ventilation, and biometric monitoring. Focus on premium interiors accelerates high-margin solution integration.
- Commercial Trucks:Commercial trucks integrate intelligent seats to enhance driver comfort, reduce fatigue, and monitor alertness. This improves safety and operational efficiency.
- Luxury Limousines:Luxury limousines feature highly customized intelligent seats with extensive massage, climate control, and entertainment. They prioritize ultimate passenger comfort.
- Autonomous Vehicles:Autonomous vehicles will redefine seat functionality, shifting to multi-modal occupant experiences and reconfigurable layouts. Health monitoring will be central.
While traditional passenger cars drive current volume, electric vehicles and autonomous vehicles represent the primary growth frontiers for innovation.
End User:
Supply concentration heavily influences the end-user segments, particularly in the automotive manufacturing ecosystem.
- Original Vehicle Manufacturers:Original Vehicle Manufacturers (OEMs) integrate intelligent seats directly into new vehicle designs, dictating specifications and driving advancements. OEMs increasingly demand fully integrated systems, influencing supplier strategies and partnerships.
- Tier-1 Suppliers:Tier-1 suppliers design, develop, and manufacture complete intelligent seating systems, acting as primary integrators for OEMs. They leverage expertise in mechanical and electronic systems, partnering to meet functional safety standards.
- Aftermarket Service Providers:Aftermarket service providers offer repair, maintenance, and upgrade services for intelligent seat components. Their role extends the lifespan of existing seats.
- Fleet Operators:Fleet operators prioritize intelligent seats for driver comfort, safety monitoring, and operational efficiency. Durability and reliability are key for commercial fleets.
- Vehicle Dealerships:Vehicle dealerships sell new and used vehicles with intelligent seats, demonstrating features to customers. They are a critical touchpoint for adoption.
The complex interplay between Original Vehicle Manufacturers and Tier-1 Suppliers defines the innovation roadmap; Aftermarket Service Providers ensure long-term functionality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extensive global shipping lanes and advanced manufacturing infrastructure underpin the worldwide distribution and production of automotive intelligent seats. These critical logistical networks facilitate the timely delivery of specialized components and finished seating systems across continents. Major automotive production hubs leverage these assets to meet diverse market demands efficiently.
China
China's rapid electric vehicle adoption and expanding automotive manufacturing sector drive significant demand for intelligent seats. The country's GB standards for vehicle components mandate specific performance and material requirements for market entry. The Yangtze River Delta region, including cities like Shanghai and Nanjing, focuses on advanced automotive electronics integration and mass production.
Germany
Germany's premium vehicle segment and stringent safety standards propel the integration of sophisticated intelligent seating systems. The EU's General Safety Regulation influences safety-related seat functions across the German automotive industry. The Stuttgart-Munich automotive corridor actively develops advanced human-machine interface (HMI) and functional safety systems.
United States
United States consumer demand for comfort features and NHTSA mandates for improved occupant detection stimulate the intelligent seats market. NHTSA regulations directly impact the integration of sensor-based systems in passenger vehicles. Michigan's automotive heartland specializes in sensor-based occupant monitoring and advanced comfort features for both traditional and electric vehicles.
Japan
Japan's high-tech vehicle interiors and export-oriented automotive industry foster innovation in intelligent seat technology. JIS standards for automotive components guide the design and manufacturing processes for Japanese suppliers. Toyota City and surrounding prefectures are innovating in lightweight, ergonomic, and highly integrated intelligent seating solutions.
South Korea
South Korea's advanced electric vehicle market and strong focus on connected car technologies accelerate intelligent seat development. Local automotive safety regulations ensure compliance for new seat functionalities. Gyeonggi Province pushes development in biometric monitoring and voice control integration for next-generation vehicle interiors.
Global Automotive Intelligent Seats Market Key Industry Players
Listed leaders compete with private specialists across innovation and market reach within the automotive intelligent seats sector. The market structure exhibits a tiered consolidation, where large Tier 1 suppliers integrate complex systems while smaller firms specialize in niche components. Strategic partnerships and technology licensing represent dominant competitive moves among industry participants.
On the premium-tier vector, Lear Corporation exemplifies a traditional seating system provider leveraging deep expertise in mechanical and electronic integration. Magna International Inc. represents a diversified automotive supplier offering modular systems combining seating with other interior components. Forvia SE occupies a position focused on differentiating through advanced human-machine interface technologies integrated directly into the seat structure.
| Leading Market Players |
|---|
| Toyota Boshoku Corporation |
| Gentherm Incorporated |
| Lear Corporation |
| Brose Fahrzeugteile |
| TS Tech |
| Adient PLC |
| Magna International Inc |
| Aisin Seiki Co. Ltd. |
| Forvia SE |
| Others |
Cost & Logistics Intelligence
Extended semiconductor lead times for automotive-grade components directly influence the supply chain's agility, subsequently impacting pricing power for advanced intelligent seat features.
Pricing Analysis
Volume-based contract pricing dominates the automotive intelligent seats market. Premium-mid-economy pricing differentiation reflects features like massage and ventilation, alongside the ISO 26262 functional safety certification level. Pricing pressure stems from OEM demands for fully integrated systems and cost-effective solutions for mass-market vehicles. Economy vehicle manufacturers exhibit the highest price sensitivity, while luxury and electric vehicle brands prioritize advanced features and are less sensitive to cost.
Supply Chain Analysis
Automotive-grade semiconductor inventory fluctuations present a significant challenge for intelligent seat production. Supply concentrates in China, Germany, and the United States, which are major automotive manufacturing hubs. The industry relies heavily on specialized microcontrollers, pressure sensors, and actuators. Semiconductor dependency creates a structural risk, leading to manufacturing bottlenecks and production delays for seat electronics. Distribution runs through Tier-1 suppliers, who integrate complex systems before delivery to Original Vehicle Manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intelligent seats market requires a robust substitution defense as traditional seating solutions face pressure from advanced, software-defined cabin environments. Incumbents must navigate this shift by integrating sophisticated electronics and software capabilities.
For Market Incumbents:Consolidate in-house software development capabilities to mitigate the threat of software integration complexity. Deepen vertical integration into specialized electronics manufacturing to secure supply chains for microcontrollers and sensors. Invest heavily in ISO 26262 compliance and specialized engineering talent to meet stringent functional safety standards. This defends against emerging software-centric competitors and ensures market relevance.
For New Entrants and Emerging Players:Lead with specialized biometric monitoring solutions targeting the autonomous vehicle segment, where health monitoring will be central. Focus on developing modular software architectures for over-the-air updates, appealing to electric vehicle manufacturers seeking continuous product improvement. The commercial vehicle segment presents a penetrable application, offering opportunities for driver alertness and fatigue reduction systems. A go-to-market angle involves partnerships with Tier-1 suppliers lacking advanced software expertise.
For Investors and Strategic Acquirers:Long-term, this sits as a technology integration play because the market is shifting towards software-defined vehicle architectures. Target acquisition profiles include small to mid-sized firms specializing in automotive-grade software, advanced sensor technology, or human-machine interface development. These specialists offer critical capabilities that complement established seating system providers. The signal to watch is the increasing share of vehicle bill of materials attributed to intelligent seat electronics.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Seat Platform Development | Developing modular software allows OEMs to offer continuous product improvement and over-the-air updates for intelligent seat functions. |
| Biometric Sensor Integration R&D | Integrating biometric sensors offers new wellness features, aligning with future autonomous vehicle health monitoring requirements. |
| Sustainable Material Supply Chain Partnership | Partnering for bio-based and recyclable materials helps meet OEM sustainability targets and EU CSRD regulations. |
| Functional Safety Standard Compliance Investment | Investing in ISO 26262 compliance is critical for electronic seat components tied to safety systems like occupant detection. |
| Commercial Vehicle Segment Expansion | Expanding into commercial vehicles addresses unmet demand for driver comfort, fatigue reduction, and operational efficiency. |
Research Approach
The analysis maps intelligent seat product types and application segments, each validated through extensive primary interviews. Conversations included automotive OEM platform engineers, Tier-1 supplier R&D directors, component specialists, and aftermarket service providers. Secondary validation drew from vehicle production databases, IHS Markit registration data, and regulatory filings from NHTSA and the EU. This approach employed both bottom-up and top-down triangulation to ensure data accuracy.
Forecast outputs were consistently cross-referenced against external industry benchmarks and market reports across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, and end-user, alongside regional adoption patterns. Compound annual growth rates were derived from historical data trends and projected technological advancements. Key forecast inputs included electric vehicle adoption rates and evolving functional safety regulations.
Forecasts assume regulatory continuity in key automotive regimes like the EU, US, and China; material policy shifts would require re-modeling. These projections reflect current technological trajectories and supply chain stability assumptions. Revision becomes warranted when major semiconductor supply disruptions or significant changes in vehicle electrification mandates cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
Automotive Floor Carpet Market
Automotive Interior & Exterior
Windscreen Washer System Market
Automotive Interior & Exterior
Automotive Rocker Panel Market
Automotive Interior & Exterior
Glazing for Automotive Market
Automotive Interior & Exterior
United Kingdom Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
Automotive Exterior LED Lighting Market
Automotive Interior & Exterior
Paint Protection Film Market
Automotive Interior & Exterior
Global Automotive Side Window Sunshades Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
Automotive Wooden Interior Decorative Market