
 Telematics and Connectivity Control Unit Systems Market | 2026-2036
Telematics and Connectivity Control Unit Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Telematics and Connectivity Control Unit Systems Market Insights
EU Green Deal vehicle-emission tracking mandates are realigning the cost-of-entry calculus for telematics hardware suppliers. Continental AG leverages its integrated sensor-to-cloud stack to sustain design wins across European commercial fleets. Robert Bosch anchors its position through captive semiconductor sourcing for connectivity modules. Harman International differentiates via premium infotainment-integrated control units for luxury OEM programs.
Telematics and Connectivity Control Unit Systems comprise embedded computing platforms that aggregate vehicle sensor data, manage wireless transmission protocols, and execute over-the-air update cycles through processors typically rated for AEC-Q100 Grade 2 temperature resilience. These systems serve the primary commercial purpose of enabling real-time vehicle monitoring, predictive maintenance scheduling, and regulatory compliance reporting for fleet operators and insurers. Embedded Control Units dominate current production volumes due to OEM factory-install preference, while Modular Control Units represent the fastest-expanding category as aftermarket retrofit demand from logistics companies accelerates. Cellular Connectivity leads technology adoption, though Dedicated Short-Range Communication is gaining traction where municipalities deploy V2X infrastructure.
FCC equipment authorization rules in the United States, ETSI spectrum harmonization standards across Europe, and Japan's MIC radio law collectively shape product certification timelines and module interoperability requirements for suppliers seeking multi-region market access. The EU AI Act introduces emerging compliance layers for autonomous decision-making functions within connected vehicle platforms. Stakeholders must monitor evolving cybersecurity certification schemes as regulators tie type approval to penetration-tested hardware architectures.
Market Dynamics
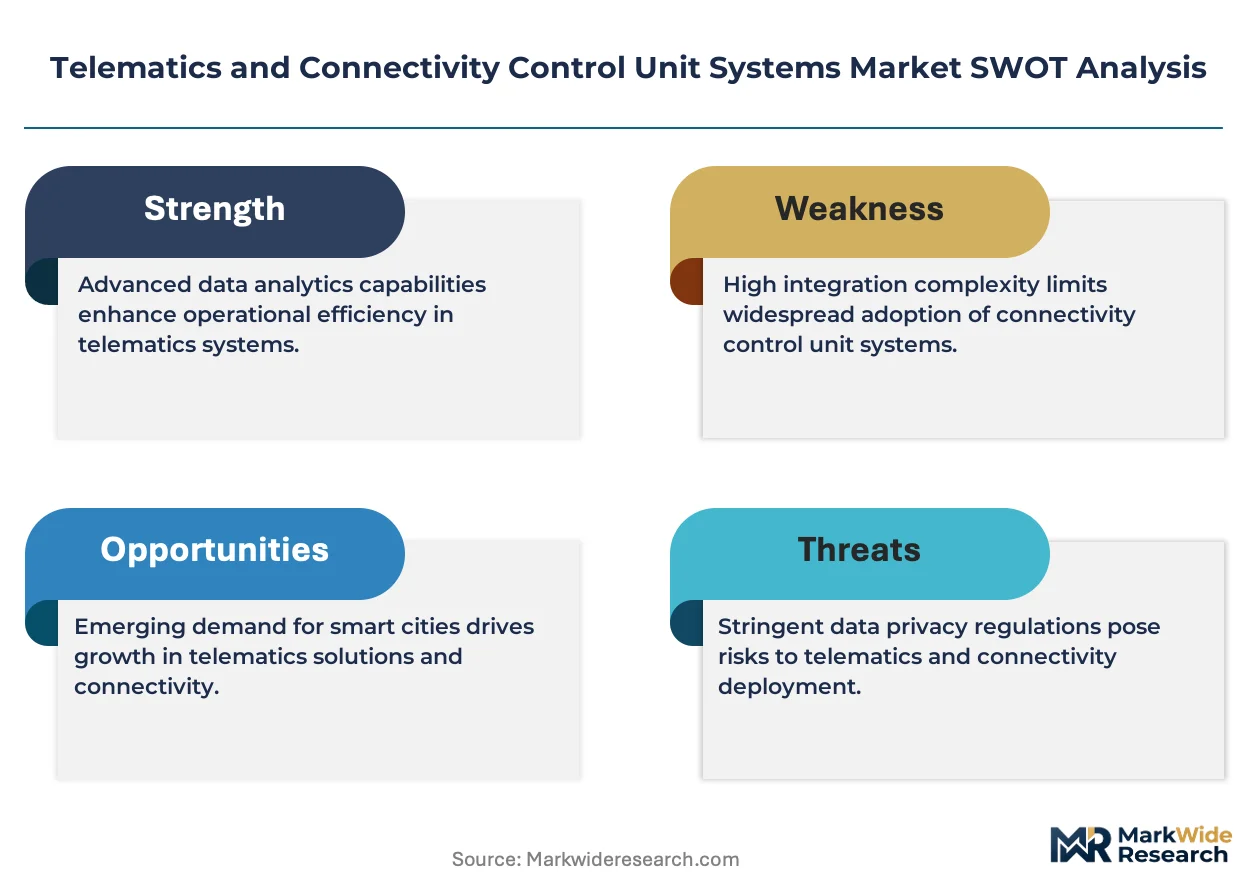
Cellular V2X mandates from the EU and Japan are forcing hardware suppliers to redesign control unit architectures around multi-protocol compatibility, compressing development cycles while expanding certification burdens.
Growth Catalysts
- Fleet electrification mandates:Commercial vehicle operators across Germany and France face binding CO2 reduction targets under EU Green Deal provisions. Telematics hardware enables real-time energy consumption monitoring and route optimization for electric drivetrains.
- 5G network deployment:Telecommunications infrastructure expansion in urban corridors supports low-latency vehicle-to-infrastructure communication. Municipalities in Japan and South Korea prioritize smart intersection deployments requiring compatible onboard units.
- Insurance telematics adoption:Usage-based coverage models penetrate commercial auto lines in the United States and United Kingdom. Underwriters mandate hardwired control units to verify driver behavior data integrity.
Market Restraints
- Semiconductor supply concentration:AEC-Q100 qualified automotive-grade processors depend on foundry capacity concentrated in Taiwan and South Korea. Geopolitical friction threatens allocation stability for control unit manufacturers.
- Multi-regional certification costs:FCC Part 15 rules in the United States, ETSI EN 302 571 in Europe, and Japan's MIC radio law impose non-harmonized testing protocols. Each distinct approval cycle adds months to product launch timelines.
- Embedded software liability exposure:Functional safety requirements under ISO 26262 extend to over-the-air update mechanisms. Suppliers face expanded warranty obligations when firmware defects affect vehicle operation.
Strategic Opportunities
- Aftermarket modular retrofit demand:Logistics operators in India and Brazil seek cellular-connected control units compatible with legacy diesel fleets. Local assembly partnerships reduce import duty exposure while accelerating deployment.
- Cybersecurity certification premiums:UN ECE R155 type approval requirements create tiered hardware categories. Suppliers achieving penetration-tested architectures command preference from OEMs targeting export markets.
- Edge computing integration:Convergence of telematics control units with cabin AI processors enables localized inference for driver monitoring. Tier-1 suppliers in Germany and Japan pioneer fused architectures reducing separate module count.
Industry Challenges
- Embedded systems cybersecurity talent scarcity:Penetration testing and secure boot architecture design require specialized firmware engineering capabilities. Recruitment competition from consumer electronics and financial technology sectors constrains automotive supplier hiring.
- Legacy fleet protocol fragmentation:Controller Area Network variants across commercial vehicle vintages complicate universal retrofit solutions. Control unit suppliers must maintain multiple hardware configurations serving J1939, OBD-II, and manufacturer-proprietary diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telematics and Connectivity Control Unit Systems Market |
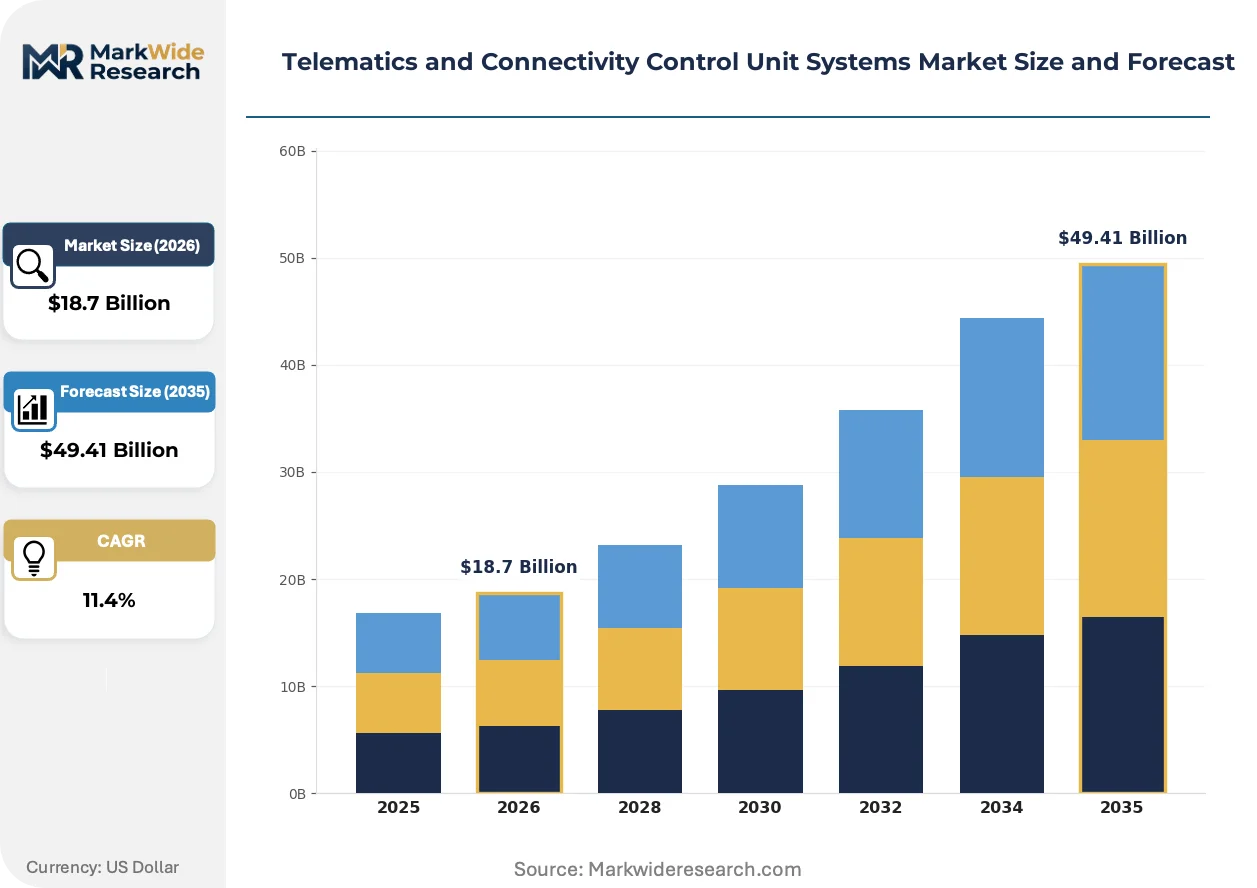
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Control Units, Standalone Control Units, Hybrid Control Units, Modular Control Units Technology: Cellular Connectivity, Satellite Communication, Wi-Fi, Bluetooth, Dedicated Short-Range Communication, Zigbee Application: Fleet Management, Usage-Based Insurance, Vehicle Tracking, Emergency Response, Remote Diagnostics, Infotainment Services End User: Logistics Companies, Public Transit Operators, Private Car Owners, Leasing Firms, Emergency Services |
| Companies Covered | Robert Bosch, Continental AG, Denso Corporation, Harman International, LG Electronics, Valeo SA, Visteon Corporation, Marelli, Qualcomm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telematics and Connectivity Control Unit Systems Market Trends and Innovations
Hardware-software decoupling is compressing product refresh cycles as over-the-air capabilities enable feature expansion without physical module replacement.
Multi-protocol baseband processors are consolidating discrete cellular, DSRC, and satellite connectivity functions into single-chip solutions. Tier-1 suppliers in Germany and Japan prioritize these integrated designs to reduce unit cost and PCB footprint for embedded control architectures. The consolidation is displacing modular radio designs that previously allowed field-swappable upgrades.
The EU AI Act introduces conformity assessment requirements for autonomous decision-making functions within connected vehicle platforms. Hardware suppliers must document algorithmic transparency and risk mitigation measures to maintain type approval eligibility. Premium OEM programs in Germany and Sweden are accelerating procurement of pre-certified control unit stacks to compress vehicle development timelines.
Commercial fleet operators are unbundling telematics hardware procurement from connectivity service contracts. Large logistics buyers in the United States and United Kingdom negotiate direct relationships with cellular network operators, then source control units through separate competitive tenders. This disintermediation pressures traditional bundled providers to demonstrate hardware cost transparency and open API architectures.
Telematics and Connectivity Control Unit Systems Market Segmentation
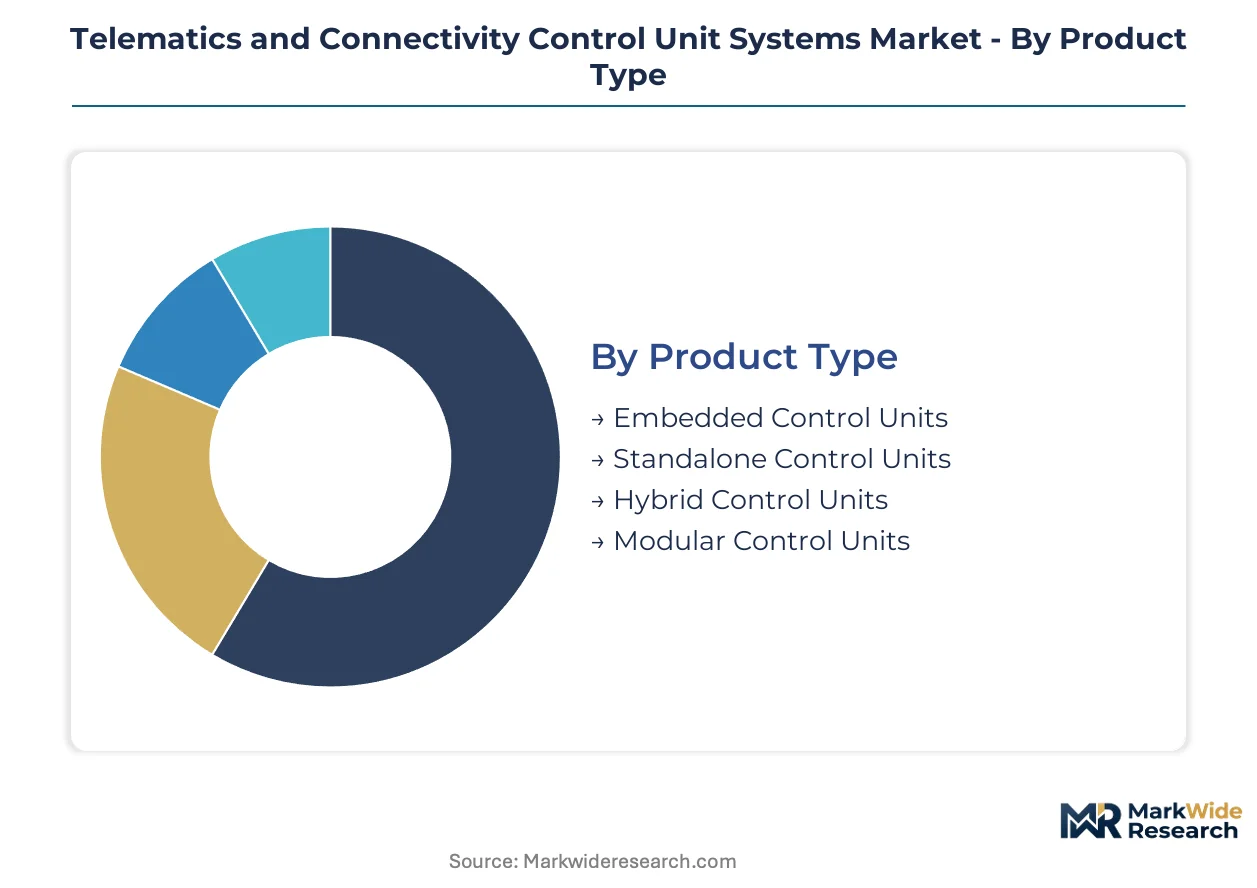
Segmentation in telematics and connectivity control unit systems reveals divergent capital deployment patterns across hardware architectures, transmission protocols, and customer procurement behaviors. Suppliers optimize manufacturing footprints differently for factory-embedded versus aftermarket-modular demand streams.
Product Type:
Capital intensity varies sharply across product architectures, with semiconductor integration depth and thermal management requirements driving upfront tooling investments.
- Embedded Control Units:Factory-integrated platforms featuring AEC-Q100 Grade 2 processors co-located with vehicle powertrain controllers. German commercial vehicle OEMs anchor procurement volumes for these architectures under EU Green Deal emission tracking mandates.
- Standalone Control Units:Self-enclosed modules with independent power regulation and antenna arrays. Aftermarket installers in Brazil and India favor these units for legacy diesel fleet retrofits where factory integration proves cost-prohibitive.
- Hybrid Control Units:Dual-mode architectures supporting both embedded and tethered operation through configurable firmware profiles.
- Modular Control Units:Field-swappable designs with standardized mounting interfaces and upgradeable radio subassemblies.
Embedded Control Units absorb the bulk of installed capacity; Modular Control Units are expanding most quickly.
Technology:
Radio frequency engineering complexity and spectrum licensing costs stratify supplier capabilities across transmission standards.
- Cellular Connectivity:LTE-M and 5G-NR baseband implementations with carrier-agnostic SIM provisioning. Municipal smart intersection deployments in Japan and South Korea prioritize these modules for vehicle-to-infrastructure latency requirements.
- Satellite Communication:L-band and Ku-band transceivers enabling coverage in cellular dead zones. Mining and forestry operators in remote Canadian provinces and Australian outback regions specify these for fleet safety compliance.
- Wi-Fi:802.11p and 802.11ax variants for high-bandwidth cabin hotspot services.
- Bluetooth:Low-energy stacks for smartphone pairing and wearable driver authentication.
- Dedicated Short-Range Communication:5.9 GHz DSRC chipsets for cooperative awareness messaging. EU C-ITS corridor deployments along German and Dutch highways mandate these for truck platooning trials.
- Zigbee:Mesh networking for in-vehicle sensor aggregation in commercial trailer monitoring applications.
Cellular Connectivity dominates current production volumes; Dedicated Short-Range Communication is climbing the fastest as V2X infrastructure matures.
Application:
Data sovereignty requirements and real-time processing demands differentiate solution architectures across use cases.
- Fleet Management:Multi-vehicle dashboard platforms aggregating location, fuel consumption, and driver behavior telemetry. Logistics operators in the United States and United Kingdom unbundle hardware procurement from connectivity contracts, demanding open API architectures.
- Usage-Based Insurance:Hardwired accelerometer and GPS modules verifying trip integrity for underwriter risk scoring. British and American commercial auto lines mandate these for premium adjustment verification.
- Vehicle Tracking:Asset recovery systems with geofencing and ignition-disable capabilities.
- Emergency Response:Automatic collision notification with eCall compliance for EU type approval.
- Remote Diagnostics:Predictive maintenance algorithms processing controller area network fault codes.
- Infotainment Services:Passenger-facing connectivity with over-the-air content streaming.
Fleet Management captures the largest share of deployed units; Usage-Based Insurance is gaining share fastest as underwriting models penetrate commercial lines.
End User:
Procurement scale and technical specification authority concentrate differently across buyer categories.
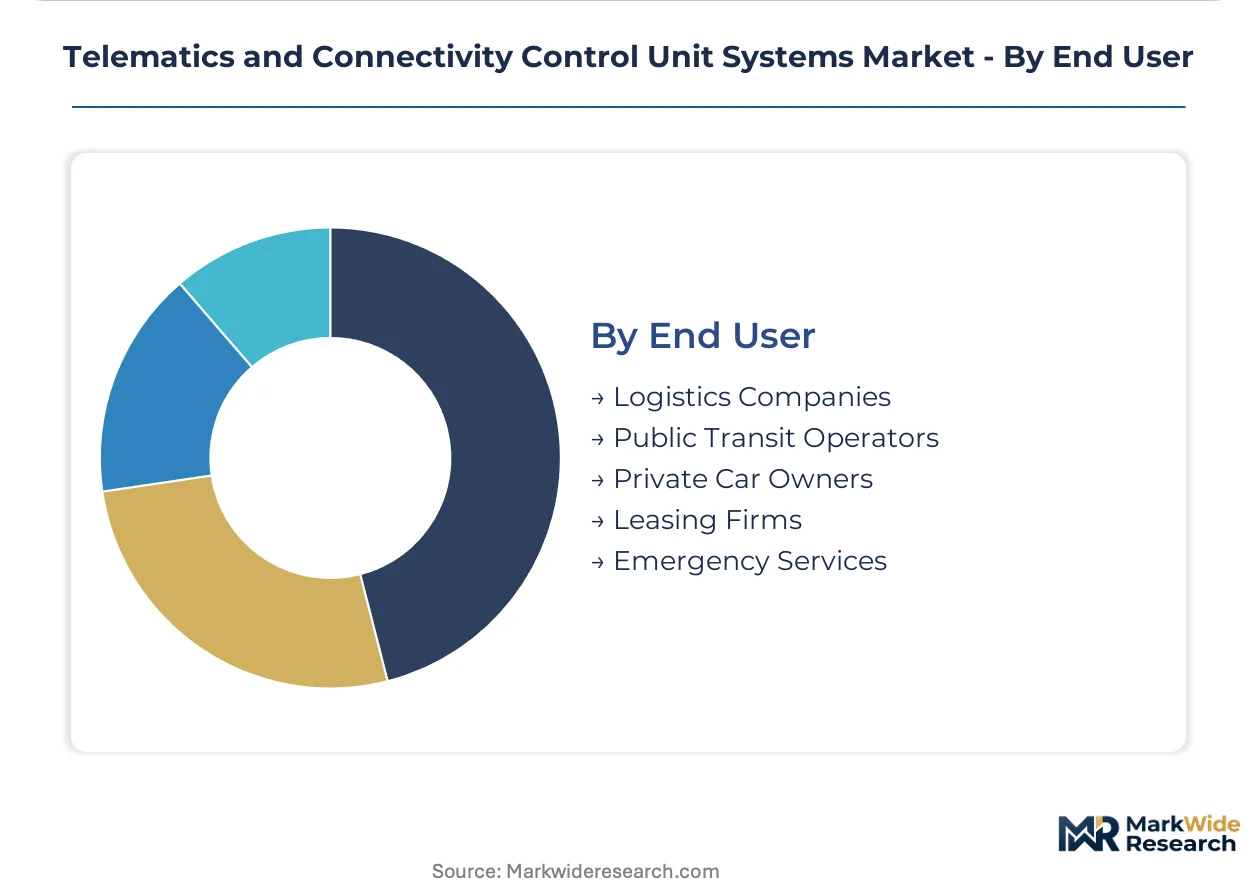
- Logistics Companies:Enterprise-scale tenders covering thousands of vehicles with centralized data lake integration. Large operators in the United States negotiate direct cellular carrier relationships, then source control units separately.
- Public Transit Operators:Municipal procurement with accessibility and passenger counting requirements. Urban bus fleets in Germany and France specify these under EU Green Deal public transport electrification timelines.
- Private Car Owners:Retail aftermarket purchases through automotive service chains.
- Leasing Firms:Residual value protection through mileage and condition monitoring.
- Emergency Services:Police, fire, and ambulance fleets with priority network access requirements.
Logistics Companies deploy the majority of installed base; Public Transit Operators are scaling fastest under municipal electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's Special Investment Region near Sanand anchors India's emerging telematics hardware assembly capacity, attracting component suppliers seeking proximity to automotive OEM plants.
Germany
Commercial vehicle OEMs in Baden-Württemberg and Lower Saxony drive embedded control unit procurement under EU Green Deal emission tracking mandates. The KBA enforces UN ECE R155 cybersecurity certification for type approval. Stuttgart's engineering corridor concentrates Tier-1 development of multi-protocol V2X architectures for truck platooning trials.
United States
Fleet operators across Texas and the Midwest unbundle hardware procurement from connectivity contracts, demanding open API architectures. The FCC enforces Part 15 equipment authorization rules for cellular modules. Michigan's automotive corridor hosts validation facilities for AEC-Q100 Grade 2 processor qualification.
Japan
METI's Cellular V2X mandates compress development cycles for control unit suppliers serving domestic OEMs. The MIC radio law governs spectrum licensing for 5.9 GHz DSRC implementations. Nagoya's Chubu region anchors production of integrated sensor-to-cloud stacks for commercial vehicle programs.
South Korea
Smart intersection deployments in Seoul Capital Area prioritize low-latency vehicle-to-infrastructure communication modules. The MFDS coordinates with transport regulators on autonomous vehicle platform safety. Busan-Ulsan's electronics cluster supplies baseband processors for multi-protocol connectivity subassemblies.
Telematics and Connectivity Control Unit Systems Market Competitive Landscape
German producers anchor the premium tier for embedded control architectures; South Korean and Japanese specialists hold positions in modular connectivity subsystems. The market exhibits tiered concentration with integrated Tier-1 suppliers controlling factory-install volumes and regional electronics specialists capturing aftermarket retrofit demand. Three archetypes dominate: semiconductor-integrated conglomerates, captive automotive electronics divisions, and contract manufacturers serving logistics unbundlers. Competitive moves concentrate on backward integration into AEC-Q100 qualified foundry relationships and multi-regional certification pre-positioning.
Within the integrated Tier-1 tier, Continental AG and Robert Bosch exemplify archetypes combining sensor-to-cloud stack control with captive semiconductor sourcing. Harman International occupies a position representing premium infotainment-integrated control unit specialization for luxury OEM programs. These three entities anchor distinct competitive vectors: factory-embedded dominance, supply chain security, and cabin experience convergence.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental AG |
| Denso Corporation |
| Harman International |
| LG Electronics |
| Valeo SA |
| Visteon Corporation |
| Marelli |
| Qualcomm |
| Others |
Pricing and Supply Chain Analysis
AEC-Q100 Grade 2 certification separates premium embedded control units from commodity modular alternatives, with this bifurcation driving divergent sourcing strategies across German OEM programs and Indian aftermarket channels. Certification-grade processors command captive foundry relationships in Taiwan and South Korea, while uncertified modular units draw from open-market component pools with compressed lead-time premiums.
Pricing Analysis
Lead-time compression premiums dominate pricing negotiations, with spot inventory for AEC-Q100 qualified processors trading at substantial markups against contract-scheduled deliveries. Pricing stratifies across UN ECE R155 penetration-tested architectures, volume-scale logistics tenders, and standard aftermarket retrofit units. Cost compression in modular control units is intensifying because Brazilian and Indian logistics operators unbundle hardware from connectivity contracts. Fleet operators in the United States demonstrate highest price sensitivity, while German commercial vehicle OEMs absorb certification premiums for factory-embedded architectures.
Supply Chain Analysis
AEC-Q100 automotive-grade processor supply rests on foundry capacity concentrated in Taiwan, South Korea, and select facilities in the United States. Baseband chip fabrication, multi-layer PCB substrates, and antenna array components feed from distinct supplier ecosystems. Single-source vulnerability concentrates in Taiwan Semiconductor Manufacturing capacity allocation for Grade 2 qualified silicon. Distribution runs through Tier-1 automotive electronics divisions serving OEM factory-install programs, with regional contract manufacturers capturing aftermarket retrofit demand in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is accelerating as multi-regional certification costs and semiconductor supply concentration force sub-scale modular suppliers toward exit or acquisition. UN ECE R155 cybersecurity mandates raise fixed compliance investments beyond smaller players' capital access.
For Market Incumbents: To counter disintermediation from logistics operators unbundling hardware and connectivity procurement, Tier-1 suppliers should deepen backward integration into AEC-Q100 qualified foundry relationships and accelerate pre-certification positioning across FCC, ETSI, and MIC radio law jurisdictions. Channel control through open API architectures retains fleet management platform relationships. For New Entrants and Emerging Players: Begin with cellular-connected modular control units for legacy diesel fleet retrofits in India and Brazil, where import duty exposure and local assembly partnerships create defensible entry positions. Target logistics operators seeking hardware-agnostic connectivity integration. A direct carrier-relationship go-to-market angle bypasses incumbent bundled-service lock-in. For Investors and Strategic Acquirers: Re-rating potential sits with semiconductor-integrated telematics specialists given EU AI Act conformity assessment requirements compressing vehicle development timelines for premium OEM programs. Long-term viability favors suppliers with captive processor sourcing and multi-protocol V2X architecture capabilities. Watch cellular V2X mandate enforcement velocity in Japan and South Korea as inflection indicator for control unit specification upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol V2X Architecture Development | EU C-ITS corridor deployments along German highways mandate DSRC compatibility for truck platooning trials. |
| Cybersecurity Certification Pre-Positioning | UN ECE R155 penetration-tested architectures command preference from OEMs targeting export markets. |
| Backward Integration into Foundry Capacity | AEC-Q100 qualified processor allocation stability separates Tier-1 suppliers from modular competitors. |
| Aftermarket Local Assembly Partnerships | Gujarat's Special Investment Region proximity to Indian OEM plants reduces import duty exposure. |
| Edge Computing Convergence Investment | Fused telematics-AI architectures reduce module count for cabin driver monitoring applications. |
Research Methodology
Independent corroboration across Tier-1 supplier procurement leads, fleet operator technology directors, and cellular carrier IoT platform managers underwrites the qualitative findings. Primary interviews with automotive electronics engineering heads, aftermarket distributor operations managers, and regulatory affairs specialists at control unit manufacturers combined with secondary validation from FCC equipment authorization databases, ETSI spectrum harmonization filings, and vehicle production registration data. Bottom-up installed base estimates and top-down market sizing triangulate across the analysis window.
Comparable historical reference periods anchored the projection horizon to pre-pandemic baseline capacity utilization and post-mandate procurement acceleration phases. The analytical framework modeled segmentation across embedded versus modular control architectures, cellular versus DSRC transmission protocols, fleet management versus usage-based insurance applications, and logistics company versus public transit operator end users. CAGRs derived from segment-level volume build-ups incorporating EU Green Deal electrification timelines and cellular V2X mandate enforcement schedules. Industry-specific inputs included AEC-Q100 processor allocation forecasts and smart intersection deployment pipelines.
Underlying measurement precision varies by segment; factory-embedded control units carry tighter precision than aftermarket modular categories due to OEM procurement visibility. Forecasts reflect assumptions regarding foundry capacity expansion, regulatory harmonization progress, and fleet electrification adoption curves. Geopolitical friction affecting Taiwan and South Korea semiconductor supply, plus cybersecurity certification scheme evolution, warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Global Car GPS Navigation System Market
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
In Car Infotainment System Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
Transport Data Logger Market
Telematics and Infotainment
Car Generated Data Market
Telematics and Infotainment
Global in Dash Navigation System Market
Telematics and Infotainment
V2X Communication Module Market
Telematics and Infotainment
Trailer Telematics Market
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
Automotive Navigation & Infotainment Systems Market
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
In-Car Infotainment Market
Telematics and Infotainment
GPS Tracker Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
Dashboard Camera Market