
 Contraceptive Pills Market | 2026-2036
Contraceptive Pills Market Size, Share, and Industry Trends Forecast 2026-2036
Contraceptive Pills Market Intelligence
Good Manufacturing Practice (GMP) certification, enforced by regulators including the FDA and EMA, is redrawing the competitive environment. Bayer AG leverages its extensive global distribution network and brand recognition in this space. Pfizer Inc. sustains its market position through significant R&D investment in next-generation hormonal therapies. Teva Pharmaceutical Industries Ltd. competes effectively through its large-scale production of generic progestin-only pills.
Contraceptive pills are oral hormonal medications containing synthetic versions of estrogen and progestin. Their primary function is to prevent pregnancy by inhibiting ovulation, thickening cervical mucus, and altering the uterine lining. Combined oral contraceptives continue to hold the largest share of the product segment due to their high efficacy and additional benefits. While pharmacies are the dominant end-user channel, family planning clinics are expanding their share most rapidly due to integrated care models.
Regulatory frameworks from bodies like the United States' FDA, Brazil's ANVISA, and China's NMPA govern product approval, manufacturing standards, and promotional activities. Inclusion on the WHO's Model List of Essential Medicines significantly influences public procurement and accessibility in developing nations. A critical decision for manufacturers involves assessing the strategic value and regulatory feasibility of pursuing prescription-to-over-the-counter status for certain formulations.
Market Dynamics
The interplay between stringent manufacturing regulations and expanding public health mandates defines the market's core dynamic. Enforcement of Good Manufacturing Practice (GMP) by bodies like the FDA and EMA elevates operational standards, while WHO support accelerates adoption in developing economies.
Growth Catalysts
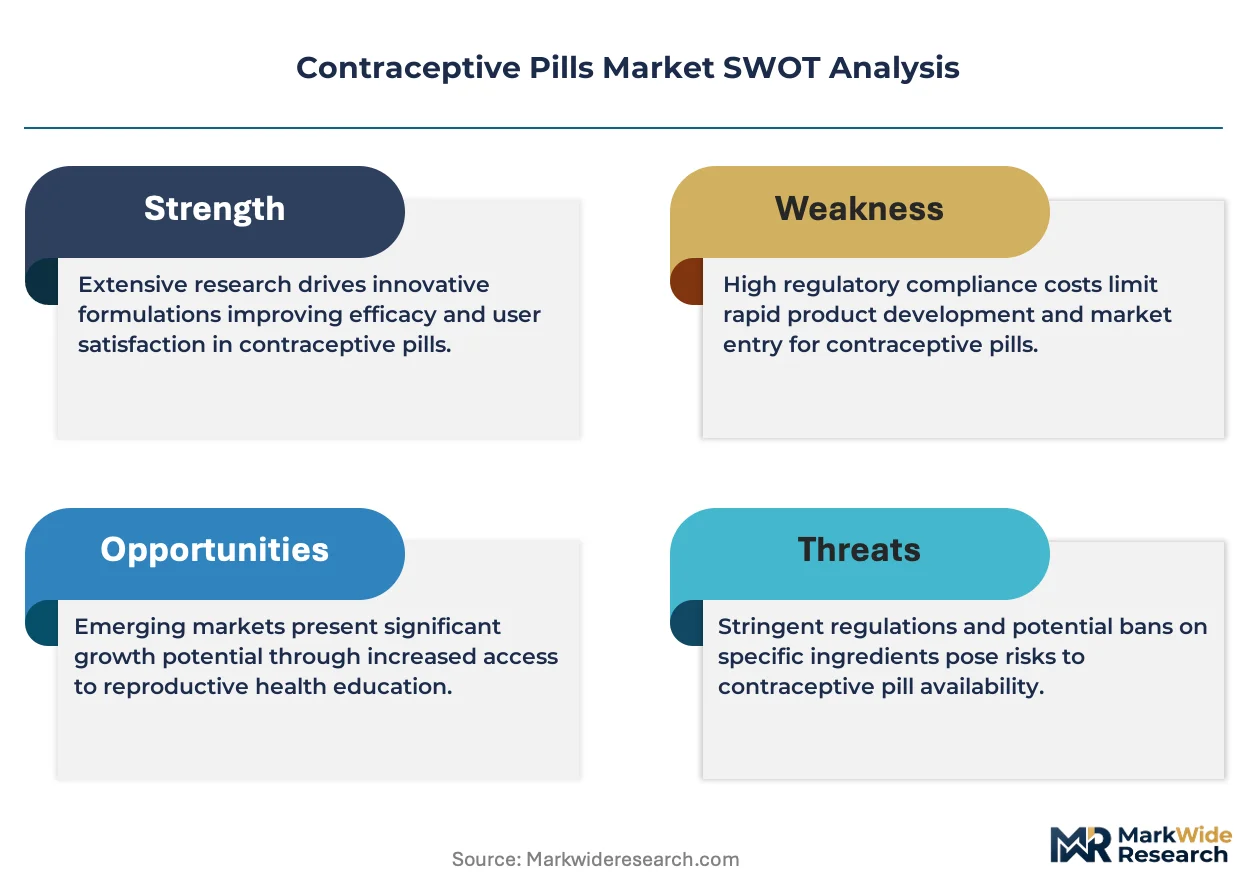
- Supportive Health Policies:Inclusion on the WHO's Model List of Essential Medicines and national family planning programs in countries like India and Brazil stimulate public sector procurement and improve accessibility.
- Telemedicine Expansion:The proliferation of digital health platforms provides discreet and convenient channels for consultations and prescription fulfillment, broadening patient reach beyond traditional clinics.
- Integrated Care Models:Family planning clinics are expanding their service offerings to include comprehensive reproductive health services, which drives consistent demand for oral contraceptives as part of a holistic care plan.
Market Restraints
- Regulatory Hurdles:The extensive and costly clinical trials required by regulators such as the FDA and EMA for new drug approvals or prescription-to-OTC switches create significant barriers to market entry.
- API Supply Concentration:A reliance on a limited number of specialized manufacturers for the active pharmaceutical ingredients (APIs), specifically synthetic progestins and estrogens, introduces supply chain vulnerability.
- Alternative Contraceptive Methods:The availability and promotion of long-acting reversible contraceptives (LARCs), such as intrauterine devices (IUDs) and implants, present a strong substitution threat for some patient segments.
Strategic Opportunities
- Over-the-Counter (OTC) Transition:Pursuing regulatory approval for OTC status for certain progestin-only pills in markets like the United States opens a vast new consumer channel, bypassing prescription requirements.
- Underpenetrated Market Development:Focusing on public-private partnerships to improve education and distribution infrastructure in high-population nations across Southeast Asia and Africa can unlock significant volume growth.
- Next-Generation Formulations:Investment in R&D for non-hormonal oral contraceptives or pills with novel delivery mechanisms can address unmet needs related to side effects and user convenience.
Industry Challenges
- Global Compliance Burden:Manufacturers face substantial operational overhead to maintain GMP certification and adhere to disparate labeling and reporting requirements across multiple regulatory jurisdictions like the EU, US, and China.
- Supply Chain Integrity:Ensuring product stability and preventing counterfeiting throughout complex global distribution networks, particularly in regions with less developed logistics, remains a persistent operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contraceptive Pills Market |
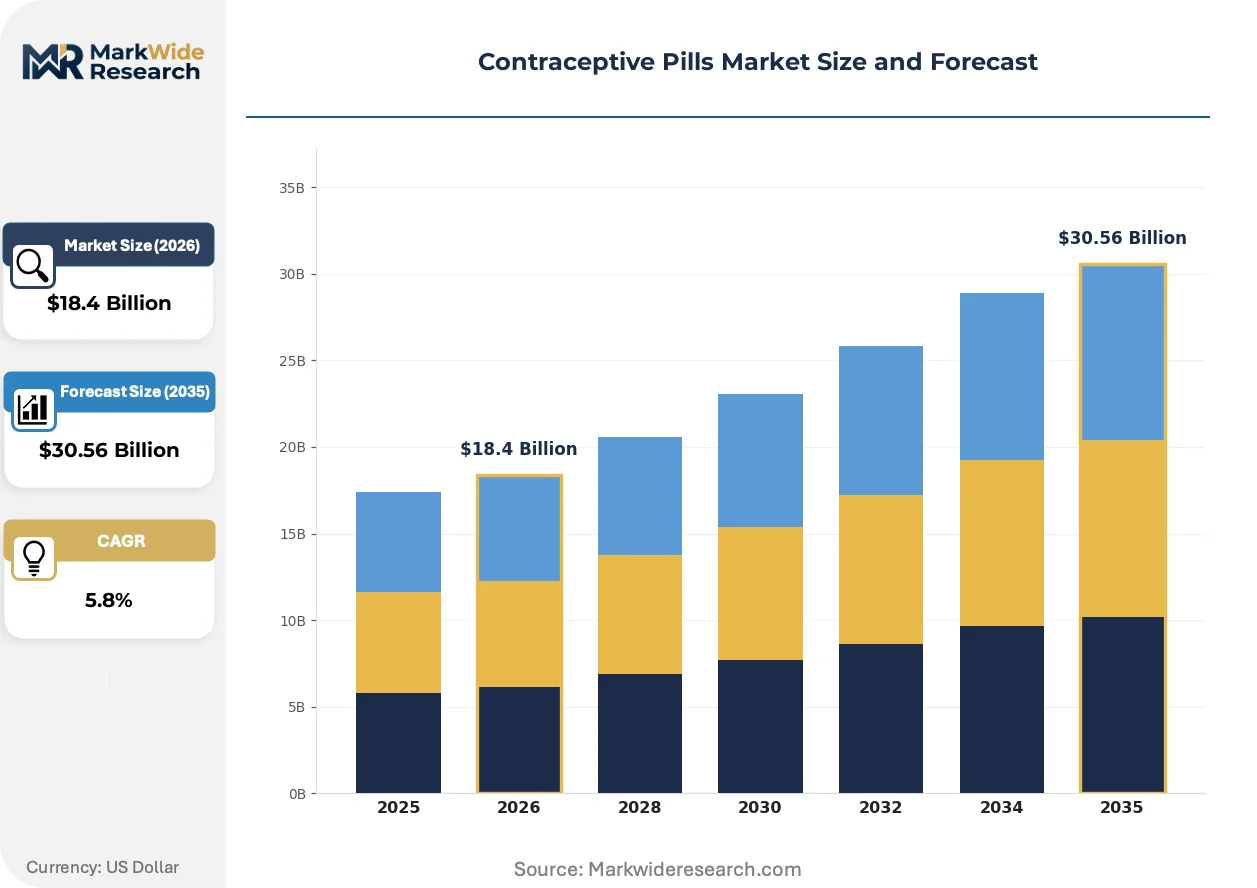
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $30.56 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Combined Oral Contraceptives, Progestin-Only Pills, Extended-Cycle Pills, Low-Dose Pills, Others Application: Birth Control, Menstrual Regulation, Acne Treatment, Endometriosis Management, Hormonal Imbalance End User: Pharmacies, Family Planning Clinics, Hospitals, Gynecology Centers, Online Retailers Distribution Channel: Prescription Drugstores, Over-The-Counter Sales, E-Commerce Platforms, Hospital Pharmacies, Private Clinics |
| Companies Covered | Pfizer Inc., Bayer AG, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Johnson & Johnson, AbbVie Inc., Viatris Inc., Mayne Pharma, Gedeon Richter Plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contraceptive Pills Market Strategic Shifts & Innovations
Product innovation is moving toward formulations with enhanced safety profiles and greater user choice. This evolution is driven by deeper biochemical understanding and a demand-side pull for personalized contraceptive options that minimize side effects and align with individual health needs.
Next-generation hormonal therapies featuring ultra-low-dose estrogens and novel progestins are gaining traction. Health-conscious consumers and younger patient demographics are the primary adopters, seeking options with improved tolerability. This advancement is decomposing the monolithic oral contraceptive category into a nuanced spectrum of products, each with a distinct risk-benefit profile tailored to specific user cohorts.
A pivotal regulatory shift is the pathway toward over-the-counter (OTC) availability for certain formulations, exemplified by recent FDA advisory committee reviews in the United States. This move significantly lowers barriers to access by enabling purchase without a prescription. The progestin-only pill segment is the most directly impacted, compelling manufacturers to develop new consumer-focused educational materials and retail-ready packaging.
Consumer behavior is shifting toward the use of digital health services for contraceptive consultations and prescription management. This disrupts the traditional model centered on in-person visits to clinics and physical pharmacies, with telemedicine platforms emerging as a primary interface. The trend is most pronounced in urban areas of North America and Europe, where high internet penetration and consumer comfort with app-based services accelerate adoption.
Contraceptive Pills Market Segmentation
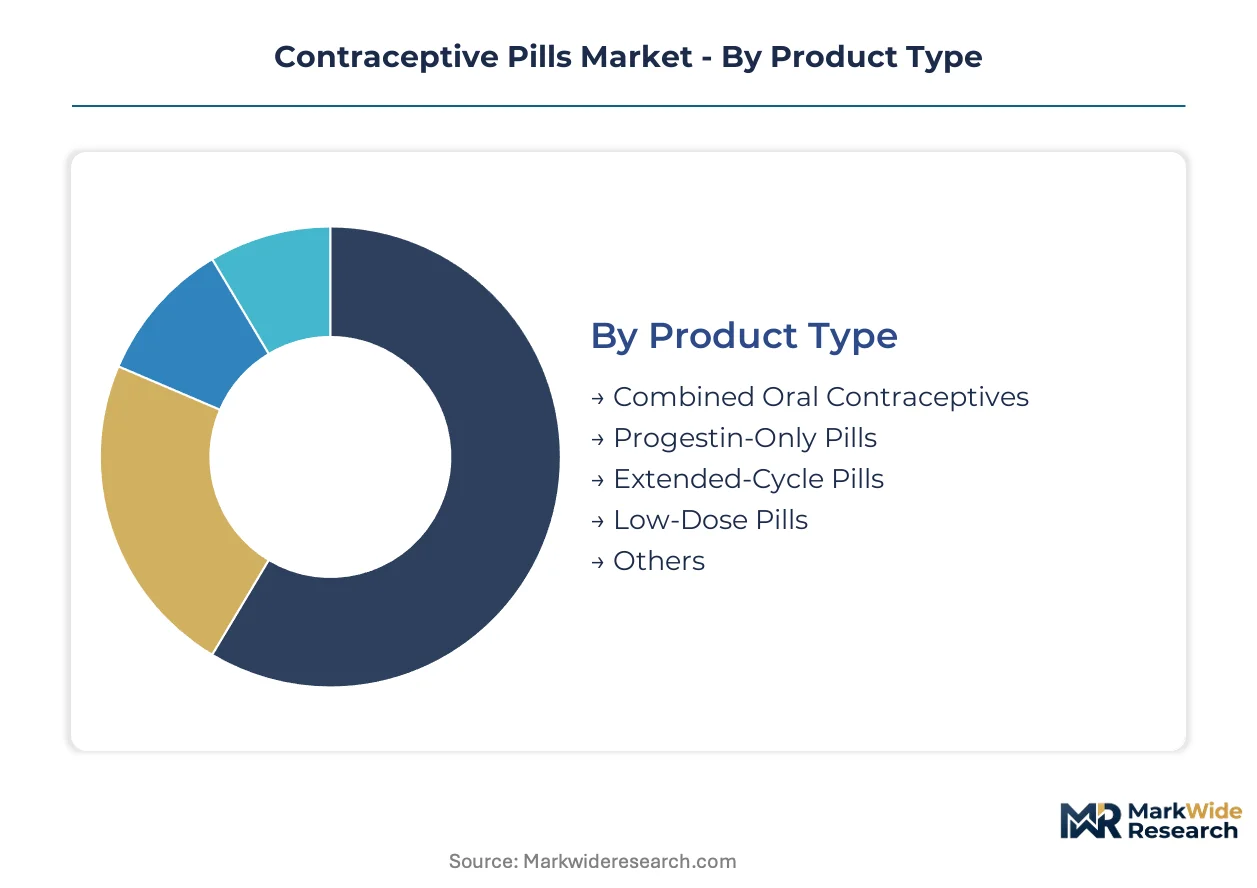
The Contraceptive Pills Market segments across product type, application, end user, and distribution channel. Understanding these distinctions helps manufacturers tailor formulations and access strategies to specific patient needs and regulatory environments. This detailed analysis highlights areas of concentrated demand and evolving market dynamics.
Product Type:
Regulatory bodies like the FDA and EMA differentiate contraceptive pills based on their hormonal composition and approval pathways. This distinction influences manufacturing standards and prescribing practices globally.
- Combined Oral Contraceptives:These pills contain synthetic estrogen and progestin, working synergistically to inhibit ovulation and modify cervical mucus. They hold the largest market share due to their high efficacy and additional non-contraceptive benefits, such as reduced menstrual symptoms.
- Progestin-Only Pills:Formulations with only synthetic progestin offer an alternative, particularly for women who cannot take estrogen. The potential for prescription-to-OTC status in markets like the United States significantly expands patient access and drives commercial interest.
- Extended-Cycle Pills:These formulations reduce the frequency of menstrual periods by extending the active pill intake cycle.
- Low-Dose Pills:Containing lower hormone concentrations, these pills aim to minimize side effects while maintaining contraceptive efficacy.
- Others:This category includes novel formulations and emergency contraceptive pills.
Combined Oral Contraceptives handle the majority of throughput; Progestin-Only Pills are the fastest mover on share.
Application:
The diverse applications of contraceptive pills extend beyond pregnancy prevention, addressing various reproductive health and hormonal conditions. Each application targets specific patient cohorts with distinct medical needs.
- Birth Control:This primary application focuses on preventing unintended pregnancies by inhibiting ovulation and altering the uterine environment. Public health initiatives in countries like India and Brazil significantly drive demand in this segment.
- Menstrual Regulation:Contraceptive pills effectively manage irregular, heavy, or painful menstrual cycles by stabilizing hormone levels. This application provides relief for many individuals experiencing debilitating symptoms.
- Acne Treatment:Hormonal oral contraceptives can reduce androgen levels, leading to an improvement in moderate to severe acne.
- Endometriosis Management:Pills can suppress the growth of endometrial tissue outside the uterus, alleviating pain and other symptoms of endometriosis.
- Hormonal Imbalance:These medications help balance hormones for conditions like Polycystic Ovary Syndrome (PCOS) or perimenopausal symptoms.
Birth Control applications constitute the largest volume; Menstrual Regulation is gaining adoption across various age groups.
End User:
The end-user landscape for contraceptive pills reflects varied patient access points and healthcare delivery models. Different customer types prioritize convenience, integrated care, or specialized consultation when seeking these products.
- Pharmacies:Retail pharmacies, including large chains and independent stores, serve as the most common point of access for prescription fulfillment. Their widespread presence ensures broad geographic reach for consumers.
- Family Planning Clinics:These specialized clinics offer comprehensive reproductive health services, including counseling and prescription of oral contraceptives. They are expanding their share rapidly due to integrated care models.
- Hospitals:Hospital pharmacies and outpatient clinics provide contraceptive pills, often as part of post-partum care or broader gynecological services.
- Gynecology Centers:Dedicated gynecology practices offer expert consultations and prescription services for a range of reproductive health needs.
- Online Retailers:E-commerce platforms facilitate discreet purchasing and home delivery, particularly for non-prescription or telemedicine-enabled options.
Pharmacies remain the primary channel for patient procurement; Family Planning Clinics are expanding most quickly.
Distribution Channel:
The distribution channels for contraceptive pills dictate how products reach end-users, influenced by regulatory controls and evolving consumer preferences. High volume channels often benefit from established infrastructure and broad consumer trust.
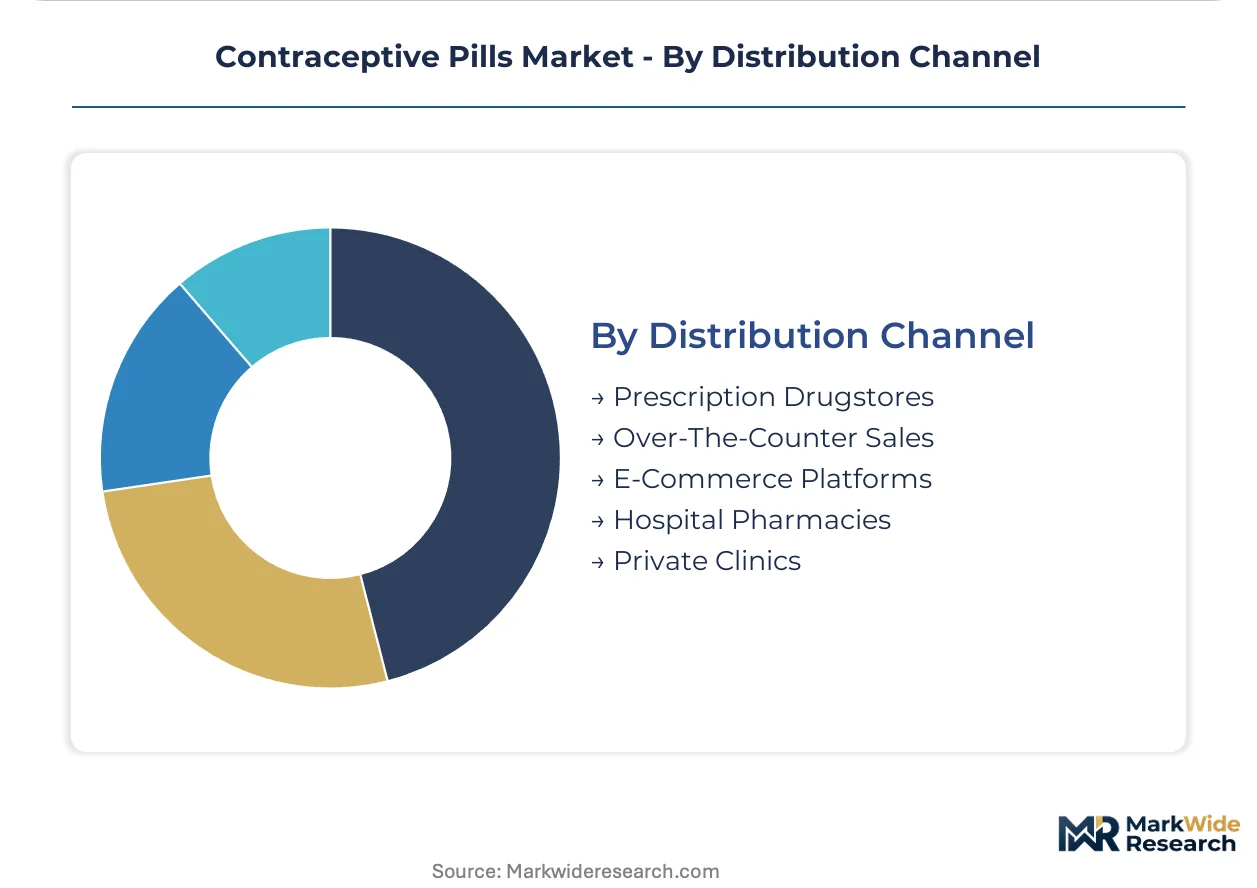
- Prescription Drugstores:These traditional channels account for the largest volume of sales, relying on physician prescriptions for dispensing. Their established presence and regulatory compliance are critical for market stability.
- Over-The-Counter Sales:This emerging channel, primarily for progestin-only pills, allows direct purchase without a prescription, significantly lowering access barriers. Recent FDA advisory committee reviews indicate a potential expansion of this segment.
- E-Commerce Platforms:Online platforms provide a convenient and discreet method for consumers to acquire contraceptive pills, especially with the rise of telemedicine. This channel facilitates broad patient reach in urban areas of North America and Europe.
- Hospital Pharmacies:Integrated within healthcare facilities, these pharmacies supply pills to inpatients and outpatients, often linked to specific medical procedures or follow-up care.
- Private Clinics:Independent clinics and private practices often dispense or prescribe oral contraceptives directly to their patients.
Prescription Drugstores maintain dominant volume; E-Commerce Platforms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supportive health policies from the WHO and national governments significantly influence the global Contraceptive Pills Market. Public sector procurement initiatives in high-population countries drive substantial volume. Telemedicine expansion further broadens access and convenience for patients.
United States
Demand for contraceptive pills in the United States is shifting with the push for over-the-counter (OTC) access. The FDA's advisory committee reviews for progestin-only pills highlight this regulatory evolution. Pharmaceutical innovation centers in regions like the Northeast corridor drive next-generation formulation development.
India
India's large population and robust public health initiatives sustain high demand for birth control applications. National family planning programs, overseen by the CDSCO, prioritize accessibility and affordability. Major pharmaceutical manufacturing hubs in cities like Hyderabad produce significant volumes of generic oral contraceptives.
Brazil
Public health initiatives in Brazil, particularly those focused on family planning, are expanding access to contraceptive pills. ANVISA's regulatory frameworks ensure product quality and market entry standards. Distribution networks across urban centers like São Paulo facilitate widespread patient procurement.
Germany
Health-conscious consumers in Germany seek advanced contraceptive options with improved safety profiles. EMA regulations govern product approvals and manufacturing standards across the European Union. Pharmaceutical research and development clusters around Frankfurt contribute to novel hormonal therapy innovations.
China
China's expanding urban populations and public health initiatives increase demand for oral contraceptives. The NMPA's stringent approval processes ensure product safety and efficacy for domestic use. Manufacturing capabilities in regions like the Yangtze River Delta support large-scale production for the local market.
Contraceptive Pills Market Key Industry Players
Player mix skews toward established multinational pharmaceutical companies with extensive portfolios and deep R&D capabilities. The market exhibits a tiered structure, encompassing innovator brands, large-scale generic producers, and specialized women's health firms. Dominant competitive moves include significant research and development investment for next-generation formulations and strategic expansion of global distribution networks. Companies also pursue regulatory pathways for over-the-counter transitions to broaden market access.
Among global pharmaceutical entities, Pfizer Inc., Bayer AG, and Teva Pharmaceutical Industries Ltd. exemplify distinct market approaches. Pfizer Inc. represents a significant investor in next-generation hormonal therapies, anchoring innovation in the space. German-based Bayer AG occupies a position of strong brand recognition and extensive global distribution. Teva Pharmaceutical Industries Ltd., an Israeli company, sits within the large-scale generic production archetype, particularly for progestin-only pills.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bayer AG |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Johnson & Johnson |
| AbbVie Inc. |
| Viatris Inc. |
| Mayne Pharma |
| Gedeon Richter Plc. |
| Others |
Cost & Logistics Intelligence
Six-month API lead times for synthetic progestins and estrogens directly influence the pricing power of major manufacturers. This extended supply chain, concentrated in specific regions, creates a structural dependency that impacts market stability.
Pricing Analysis
GMP certification, enforced by regulators like the FDA and EMA, creates the primary price differentiation across the Contraceptive Pills Market. The dominant pricing model remains per-unit transactional, where established brands command a premium over generic alternatives. Pricing softness stems from the expansion of large-scale generic production and public sector procurement initiatives in developing nations. Public health programs in countries like India are highly price-sensitive, while health-conscious consumers in Germany prioritize formulations with enhanced safety profiles, exhibiting lower price sensitivity.
Supply Chain Analysis
The concentration of critical API manufacturing in specific regions like India and China introduces significant supply chain vulnerabilities. Production relies heavily on a limited number of specialized manufacturers for synthetic progestins and estrogens. This single-source dependency creates a structural risk, particularly for generic producers. Downstream distribution primarily occurs through prescription drugstores and pharmacies, which maintain broad geographic reach for consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Contraceptive Pills Market presents a fragmentation opportunity, driven by the demand-side shift towards personalized contraceptive options that minimize side effects. This creates distinct niches for specialized product development and targeted market access strategies.
For Market Incumbents: Consolidate market position by accelerating R&D investment in next-generation hormonal and non-hormonal therapies, addressing unmet side effect needs. Expand global distribution networks, particularly in high-population developing nations, to counter LARC substitution. Strategic acquisitions of specialized women's health firms can bolster product pipelines and leverage existing GMP certification. Control over pharmacy and clinic distribution channels remains critical against generic entrants.
For New Entrants and Emerging Players: Underserved digital health service integration presents a significant entry point for new players. Focus on the rapidly expanding over-the-counter (OTC) progestin-only pill segment in markets like the United States. A strong go-to-market angle involves leveraging telemedicine platforms for discreet consultations and prescription management, particularly in urban areas of North America and Europe. Public-private partnerships in Southeast Asia can also unlock volume growth in underpenetrated markets.
For Investors and Strategic Acquirers: Long-term, this sits as a stable, essential healthcare play because of consistent underlying demand for family planning and reproductive health. Acquisition targets should include specialized women's health firms with strong R&D pipelines for novel formulations or API manufacturers to secure supply. The primary signal to watch for inflection is the progression of regulatory approvals for prescription-to-OTC switches for progestin-only pills, expanding market access and revenue potential.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Non-Hormonal Contraceptives | Addresses unmet patient needs for reduced side effects and broader user choice. |
| OTC Regulatory Pathway Pursuit | Significantly lowers access barriers for progestin-only pills in markets like the United States. |
| Telemedicine Platform Integration | Expands patient reach and provides discreet consultation channels for oral contraceptives. |
| Public-Private Partnerships | Improves education and distribution in high-population nations such as India and Brazil. |
| API Supply Chain Diversification | Mitigates single-source vulnerability for synthetic progestins and estrogens. |
Research Approach
A spread of perspectives from regulatory affairs leads, R&D directors, public health officials, and pharmacy procurement managers informed the working assumptions. Primary interviews with these stakeholders were rigorously validated against extensive secondary research. Key secondary sources included FDA filings, WHO reports, ANVISA regulations, and company financial disclosures. This approach integrated both bottom-up market intelligence and top-down strategic perspectives.
Segmentation dimensions modeled included product type, application, end user, distribution channel, and regional regulatory clusters. The analytical framework projected market dynamics across the analysis window, with compound annual growth rates derived from historical trends and anticipated shifts. Key forecast inputs included new drug approvals by bodies like the FDA and EMA, alongside public health funding allocations in high-population nations.
Material uncertainties — such as sudden regulatory changes impacting OTC status, API supply disruptions, or accelerated adoption of alternative contraceptive methods — sit outside the modeled envelope. Forecasts reflect assumptions at the time of publication. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Psychotropic Drugs Market
Pharmaceuticals
Leukotriene Inhibitors Market
Pharmaceuticals
Europe Pharmaceutical Warehousing Market
Pharmaceuticals
Croatia Pharmaceutical Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market
Pharmaceuticals
Global Exocrine Pancreatic Insufficiency (EPI) Market
Pharmaceuticals
Global Adult Vaccines Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market
Pharmaceuticals
Global Sterile Injectable Drugs Market
Pharmaceuticals
Disease-Modifying Agents Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Plasma Protein Therapeutics Market
Pharmaceuticals
Wilson Disease Drugs Market
Pharmaceuticals
Cyclosporine Drugs Market