
 Emergency Contraceptive Pills Market | 2026-2036
Emergency Contraceptive Pills Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Contraceptive Pills Market Analysis
Market Context with Strategic Players
FDA prescription-to-OTC switch pathways for hormonal contraceptives is realigning the cost-of-entry calculus for manufacturers seeking direct-to-consumer distribution. Bayer AG leverages its established hormonal therapy infrastructure to sustain shelf presence across European and North American retail channels. HRA Pharma specializes in ulipristal acetate formulations, anchoring its portfolio in the clinically differentiated 120-hour efficacy window. Teva Pharmaceutical Industries Ltd competes through broad generic levonorgestrel distribution, controlling pharmacy supply agreements across multiple continents.
Technical Definition and Structural Segments
Emergency contraceptive pills are synthetic hormonal formulations—primarily levonorgestrel (1.5 mg single dose) or ulipristal acetate (30 mg)—that inhibit or delay ovulation when administered within 72 to 120 hours after unprotected intercourse. These compounds function through progesterone receptor modulation, with no established effect on established pregnancy, and serve the primary commercial purpose of reducing unintended pregnancy incidence in ambulatory and self-care settings. The oral delivery mode dominates transaction volume, though blister pack configurations command margin premiums due to portability-driven consumer preference in travel and youth segments. Levonorgestrel products occupy the mature, price-competitive tier, while ulipristal acetate differentiates through extended efficacy windows and higher reimbursement positioning in clinic-based dispensing.
Regulatory Frame and Forward-Looking Close
The FDA, EMA, and WHO prequalification standards collectively govern active pharmaceutical ingredient purity, bioequivalence thresholds, and post-coital efficacy labeling claims across major markets. These frameworks shape demand by determining whether products require prescription status, pharmacist oversight, or unrestricted retail access, with each tier dramatically altering addressable population and margin structure. Stakeholders must monitor regulatory divergence between jurisdictions that permit proactive school-based distribution and those maintaining clinic-gatekeeping requirements, as this split will determine where manufacturers concentrate formulation development and packaging investments.
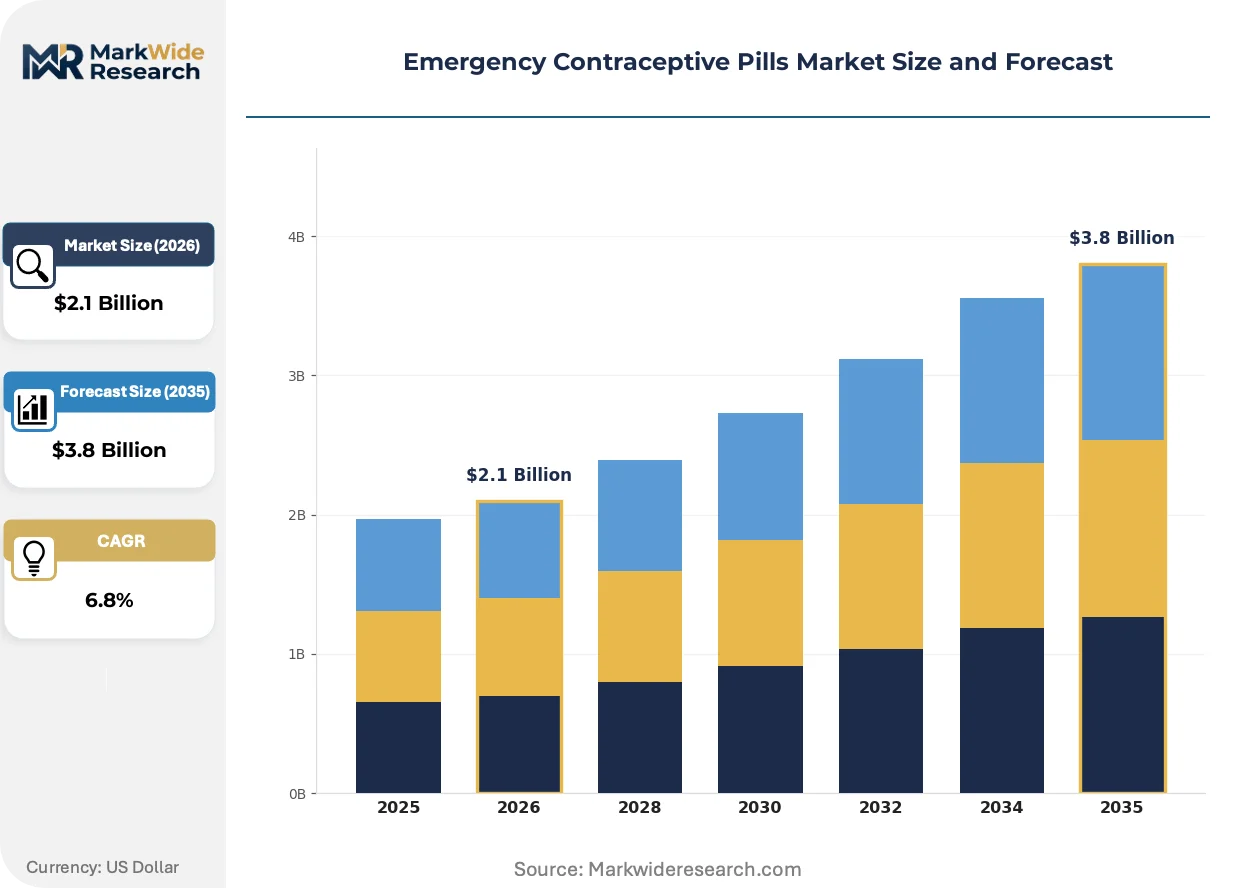
Market Dynamics
FDA prescription-to-OTC switch pathways are compressing distribution layers and forcing manufacturers to rebuild go-to-market economics around retail shelf placement rather than clinical detailing.
Growth Catalysts
- OTC Switch Pathways:The FDA's streamlined hormonal contraceptive reclassification is eliminating prescription bottlenecks in US retail channels, expanding addressable population by removing physician gatekeeping.
- Blister Pack Portability:Travel and youth segments are driving preference for discrete, single-dose packaging configurations that enable point-of-need purchase without pharmacy consultation.
- Domestic Manufacturing Scale:Indian API producers are achieving WHO prequalification status, unlocking procurement contracts across regulated and emerging markets simultaneously.
Market Restraints
- Levonorgestrel Price Compression:Generic saturation in mature markets has collapsed unit economics, forcing manufacturers to absorb API cost volatility without pricing power.
- Ulipristal Supply Concentration:Single-source API dependencies for acetate formulations create vulnerability to manufacturing disruptions at European synthesis facilities.
- Reimbursement Tier Lockout:Extended efficacy labeling for ulipristal products triggers prior authorization requirements in US Medicaid formularies, restricting clinic-based dispensing volumes.
Strategic Opportunities
- School-Based Distribution Pilots:California and Washington state health departments are testing campus dispensing programs that bypass traditional pharmacy infrastructure entirely.
- Telehealth Integration:Asynchronous consultation platforms are creating direct-to-patient subscription models for advance-provision emergency contraceptive stockpiling.
- Dual-Label Formulations:Fixed-dose combinations pairing levonorgestrel with STI prophylaxis agents are entering preclinical development for single-intervention post-exposure protocols.
Industry Challenges
- Bioequivalence Study Backlogs:Generic filers face 18-24 month queue delays at FDA clinical pharmacology review divisions, freezing pipeline progression.
- Cold Chain Integrity:Ulipristal acetate stability requirements demand validated 15-25°C distribution networks that exceed capabilities of last-mile pharmacy distributors in tropical climates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Contraceptive Pills Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Levonorgestrel, Ulipristal Acetate, Combination Pills, Others Delivery Mode: Oral, Injectable, Transdermal, Others End User: Pharmacies, Hospitals, Clinics, Online Platforms Packaging Type: Blister Packs, Vials, Bottles, Pouches |
| Companies Covered | Lupin Ltd, HRA Pharma, Bayer AG, Dr. Reddy's Laboratories Ltd, Cipla Ltd, Teva Pharmaceutical Industries Ltd, Gedeon Richter, Perrigo Company plc, Pfizer Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Contraceptive Pills Market Emerging Trajectories
Product architecture and access modalities are diverging sharply between mass-market OTC channels and clinically supervised dispensing, creating parallel innovation tracks with incompatible investment profiles.
Orally disintegrating tablet formulations are modularizing emergency contraceptive delivery by eliminating water requirements and enabling covert administration in restrictive environments. Campus health services and humanitarian aid procurement offices are piloting these formats for dormitory and conflict-zone distribution. The technology is compressing the infrastructure needed for effective post-coital intervention, reducing dependence on pharmacy access points.
EMA's revised guideline on clinical investigation of hormonal contraceptives is tightening efficacy endpoint requirements for new molecular entities, forcing developers to power superiority trials against established 72-hour benchmarks. Ulipristal acetate manufacturers face retrospective label amendment pressures to clarify mechanism-of-action language. European sponsors are responding by consolidating phase III programs across multiple member states to amortize trial costs.
Self-assessment algorithms embedded in pharmacy kiosks are displacing pharmacist counseling for levonorgestrel purchase decisions in French and UK retail settings. These digital screening tools reduce transaction time and labor cost while capturing consumer data for adherence follow-up. Regulatory acceptance of automated eligibility verification is most advanced in jurisdictions with centralized electronic health record infrastructure.
Emergency Contraceptive Pills Market Segmentation
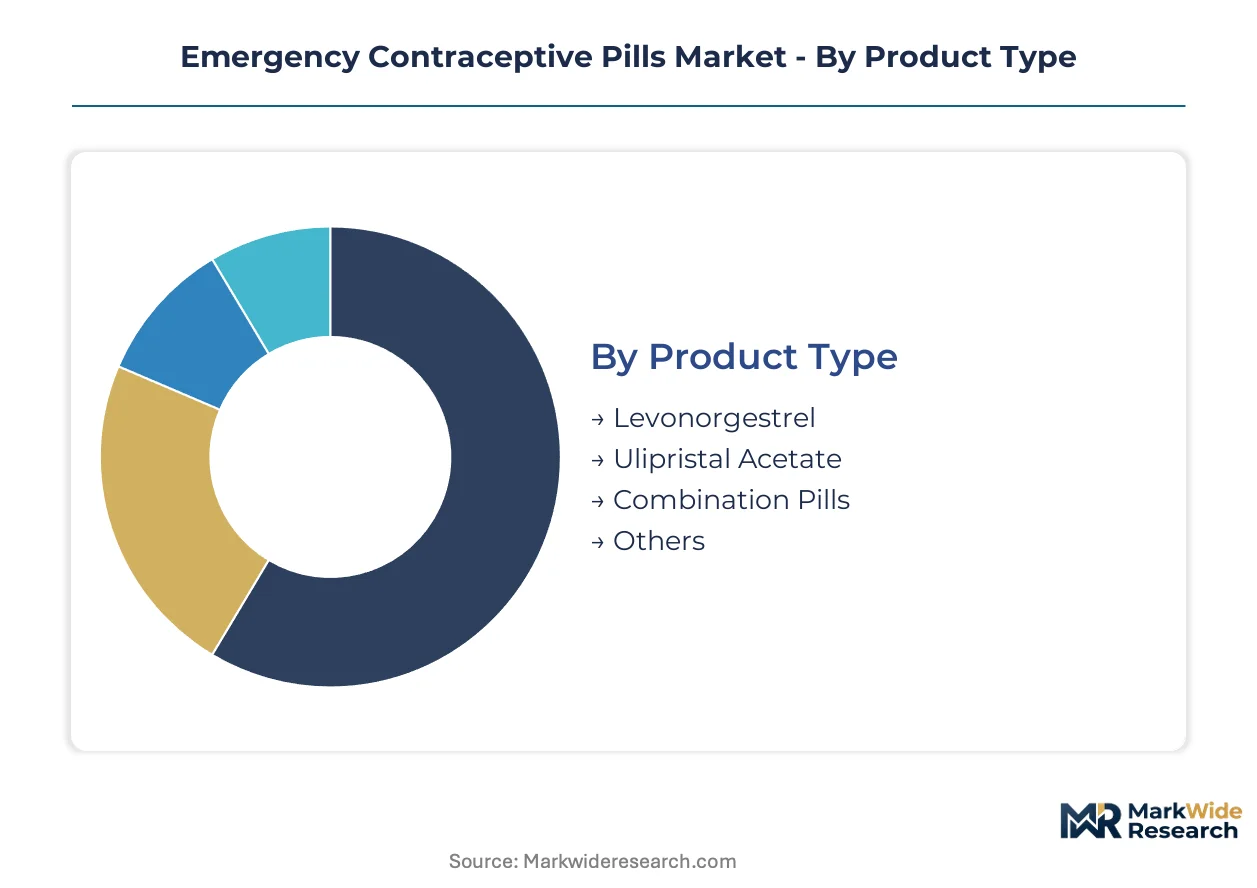
Emergency contraceptive pills fragment across four structural dimensions that determine margin capture and access modality. Product chemistry and delivery format together dictate regulatory pathway, while packaging and channel selection shape final-mile economics.
Product Type:
Volume concentrates in single-hormone generics, while premium positioning attaches to extended-efficacy formulations with differentiated labeling.
- Levonorgestrel:Synthetic progestin formulated as 1.5 mg single-dose tablets, functioning through progesterone receptor modulation to delay ovulation. Demand clusters in US and Indian retail channels where OTC status eliminates prescription friction. Generic saturation has collapsed unit pricing, forcing manufacturers toward high-volume, low-margin contracts.
- Ulipristal Acetate:Selective progesterone receptor modulator dosed at 30 mg with 120-hour efficacy window versus levonorgestrel's 72-hour ceiling. Clinic-based dispensing dominates in European markets where EMA labeling supports prescription-tier reimbursement. Prior authorization requirements in US Medicaid programs restrict volume despite clinical differentiation.
- Combination Pills:Yuzpe regimen combining ethinyl estradiol and levonorgestrel in multi-dose protocols, now largely displaced by single-dose alternatives. Remains relevant in humanitarian aid procurement where formulary flexibility outweighs efficacy optimization.
- Others:Mifepristone-based emergency protocols and investigational compounds in preclinical development, capturing niche demand in markets with restricted levonorgestrel access.
Today's leader: Levonorgestrel. Tomorrow's challenger: Ulipristal Acetate.
Delivery Mode:
Oral formats command transaction volume, while alternative modalities seek differentiation through administration speed or compliance assurance.
- Oral:Tablets and capsules representing the dominant commercial format, with disintegrating variants gaining traction in campus health and conflict-zone distribution. Water-independent administration expands addressable settings beyond traditional pharmacy infrastructure.
- Injectable:Depot formulations in development for advance-provision protocols, targeting populations with irregular healthcare contact. Clinical trial programs concentrate in sub-Saharan African research networks.
- Transdermal:Patch-based delivery systems in early-stage development, seeking to eliminate first-pass metabolism variability and improve pharmacokinetic predictability.
- Others:Intravaginal ring formulations and sublingual films in preclinical pipelines, driven by discrete administration requirements in restrictive regulatory environments.
Oral administration retains structural dominance. Injectable formats are gaining the fastest regulatory investment for advance-provision models.
End User:
Channel selection determines margin structure, with direct-to-consumer platforms compressing distribution layers while institutional procurement emphasizes volume guarantees.
- Pharmacies:Primary commercial channel spanning independent retailers and mass-market chains, with OTC switch pathways expanding self-selection in US and French markets. Shelf placement fees and pharmacist counseling requirements vary sharply by jurisdiction.
- Hospitals:Emergency department dispensing for sexual assault protocols and postpartum provision, capturing insured populations through bundled reimbursement. EHR integration enables automated eligibility screening.
- Clinics:Family planning and reproductive health centers serving Medicaid-eligible and uninsured populations, with 340B pricing programs in US federally qualified health centers.
- Online Platforms:Telehealth-integrated direct-to-patient models enabling advance stockpiling and subscription-based replenishment, bypassing traditional pharmacy gatekeeping entirely.
Pharmacy channels anchor current volume. Online platforms are climbing fastest as asynchronous consultation frameworks mature.
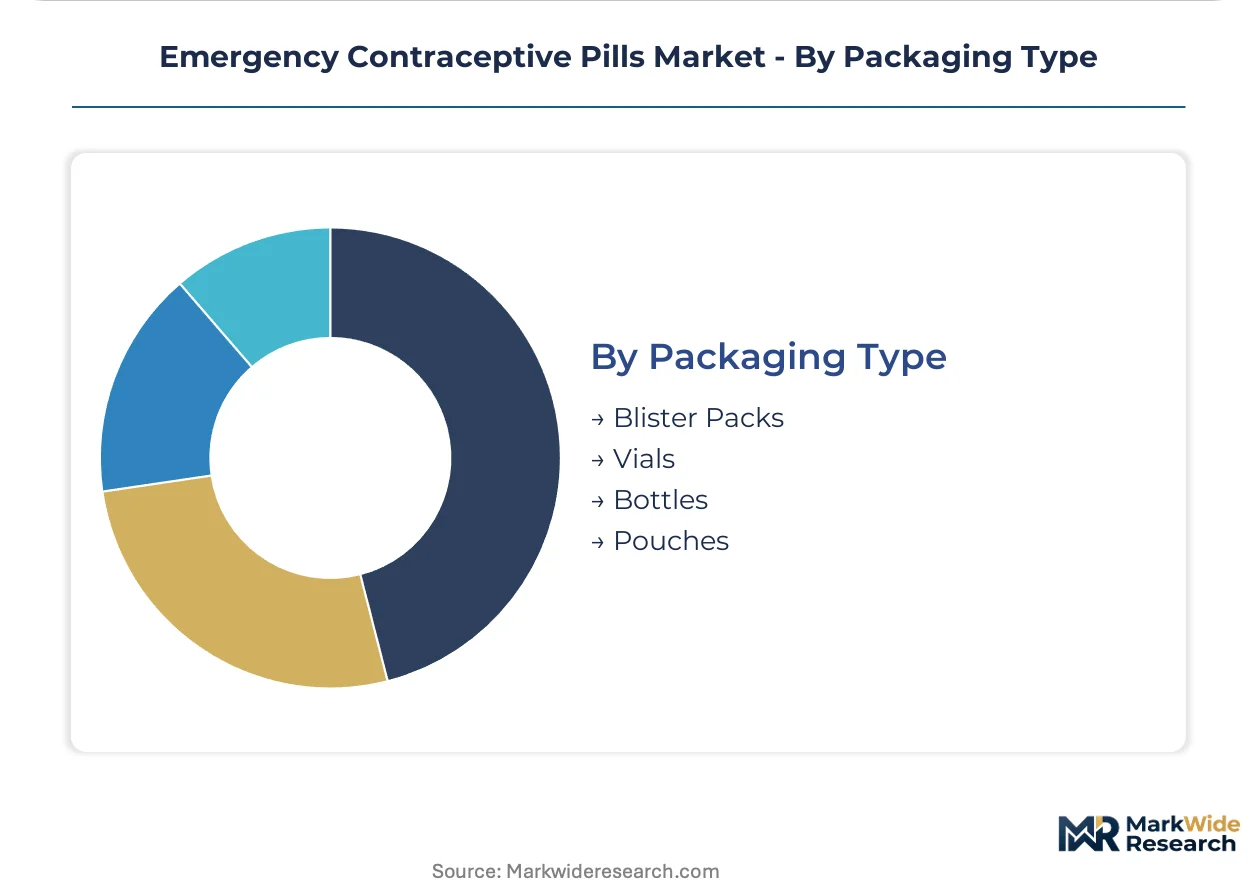
Packaging Type:
Portability requirements from travel and youth segments are reshaping format preference, with discrete single-unit configurations commanding margin premiums.
- Blister Packs:Individual dose units in foil-backed configurations, enabling covert carriage and point-of-need administration without pharmacy consultation. Youth and travel segments drive preference for pocket-sized formats.
- Vials:Multi-dose containers for clinic-based dispensing and institutional procurement, optimizing cost per dose for high-volume settings.
- Bottles:Standard pharmacy dispensing formats for 30-90 day supply protocols, relevant for advance-provision prescribing models.
- Pouches:Flexible single-dose sachets emerging in humanitarian aid and military procurement, optimizing cube efficiency for air-freight distribution.
Blister packs dominate consumer-facing positioning. Pouch formats are expanding most quickly in non-commercial procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical formulation talent clusters in Mumbai, Basel, and Research Triangle Park anchor manufacturing and regulatory strategy for emergency contraceptive developers.
United States
Retail pharmacy chains and telehealth platforms drive demand through OTC switch pathways and asynchronous consultation models. FDA prescription-to-OTC reclassification for levonorgestrel products eliminated physician gatekeeping in 2006, with ongoing expansion of pharmacist-authorized distribution. North Carolina's Research Triangle Park hosts clinical pharmacology units conducting bioequivalence studies for generic filers.
India
Domestic manufacturers supply regulated and emerging markets through WHO-prequalified API production and finished formulation exports. CDSCO streamlined manufacturing licensing for hormonal contraceptives under the 2019 New Drugs and Clinical Trials Rules. Mumbai-Pune corridor concentration includes Lupin Ltd and Cipla Ltd facilities serving African and Southeast Asian procurement contracts.
Germany
Specialty pharmaceutical development concentrates on ulipristal acetate formulations with extended efficacy labeling. EMA centralized procedure governs prescription-tier reimbursement positioning across member states. Frankfurt-Rhine-Main cluster hosts pharmacovigilance operations monitoring post-market safety data for progesterone receptor modulators.
France
Self-assessment pharmacy kiosks and school-based distribution pilots reshape access modalities outside traditional clinical settings. ANSM regulates pharmacist oversight requirements for emergency contraceptive dispensing, with automated eligibility verification advancing in regions with centralized EHR infrastructure. Lyon biomedical cluster supports formulation research for orally disintegrating tablet variants.
United Kingdom
Retail pharmacy deregulation and online platform integration expand point-of-need access without prescription requirements. MHRA oversees OTC status maintenance for levonorgestrel products following the 2001 pharmacy medicine reclassification. London-Oxford-Cambridge arc concentrates pharmacoeconomic research influencing NHS commissioning decisions for ulipristal versus levonorgestrel protocols.
Emergency Contraceptive Pills Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the emergency contraceptive pills market. Tiered concentration prevails, with multinational pharmaceutical groups commanding shelf presence and reimbursement networks while generic manufacturers capture volume through pharmacy supply agreements. Three archetypes dominate: hormonal therapy generalists extending portfolio reach, selective progesterone receptor modulator specialists defending clinical differentiation, and high-volume generic filers optimizing API sourcing economics. Competitive moves center on regulatory pathway navigation for OTC switches and strategic partnerships with telehealth platforms for direct-to-patient distribution.
Within the diversified pharmaceutical tier, Bayer AG and Pfizer Inc represent established hormonal therapy infrastructure leveraged across multiple indication areas. HRA Pharma exemplifies the focused specialist archetype through ulipristal acetate concentration. Teva Pharmaceutical Industries Ltd occupies the scale-driven generic position, with Indian counterparts Lupin Ltd and Dr. Reddy's Laboratories Ltd anchoring API-forward cost structures. Gedeon Richter and Cipla Ltd sit within regional manufacturing specialists supplying emerging market procurement channels. Perrigo Company plc represents consumer health spin-off structures optimizing retail shelf economics.
| Leading Market Players |
|---|
| Lupin Ltd |
| HRA Pharma |
| Bayer AG |
| Dr. Reddy's Laboratories Ltd |
| Cipla Ltd |
| Teva Pharmaceutical Industries Ltd |
| Gedeon Richter |
| Perrigo Company plc |
| Pfizer Inc |
| Others |
Supply Flow & Price Mechanics
WHO prequalification standards for active pharmaceutical ingredient purity gate both qualified supply access and premium-tier pricing positioning for emergency contraceptive formulations. Manufacturers without this certification face exclusion from institutional procurement channels while certified suppliers capture reimbursement-tier margins in regulated markets.
Pricing Analysis
Bundled clinic-dispensing services versus unbundled retail self-selection split the pricing architecture for emergency contraceptive pills. Three-tier pricing structure across premium, standard, and economy levels reflects ulipristal acetate's extended efficacy labeling, levonorgestrel's generic saturation, and humanitarian bulk procurement. Price differentiation hinges on prescription-tier reimbursement eligibility versus OTC shelf positioning. Cost compression in the levonorgestrel tier is intensifying because Indian API producers are flooding regulated markets with WHO-prequalified supply. Humanitarian procurement offices exhibit highest price sensitivity while clinic-based Medicaid dispensing shows lowest sensitivity due to prior authorization insulation.
Supply Chain Analysis
Reverse-logistics considerations for temperature-sensitive ulipristal acetate returns create specialized handling requirements that reshape distribution economics. API synthesis concentrates in India, China, and Germany for hormonal raw materials. Finished formulation draws from Indian domestic manufacturers, European specialty pharmaceutical facilities, and North American packaging operations. Single-source dependencies for acetate precursor chemicals create vulnerability to manufacturing disruptions at European synthesis hubs. Distribution runs through pharmacy wholesale networks in regulated markets and direct government procurement channels in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The emergency contraceptive pills market represents a late-cycle quality story as demand shifts toward ulipristal acetate's clinically differentiated 120-hour efficacy specifications over commoditized levonorgestrel alternatives.
For Market Incumbents: Extend formulary access moats by securing 340B pricing program eligibility at US federally qualified health centers before generic ulipristal filers erode clinic-tier margins. Deepen backward integration into progesterone receptor modulator API production to insulate against European synthesis facility concentration risk. Anchor shelf presence through exclusive pharmacy chain agreements that preempt competitor OTC switch pathways. For New Entrants and Emerging Players: Begin with orally disintegrating tablet formats for campus health and conflict-zone distribution channels where established manufacturers lack format-specific regulatory dossiers. Target telehealth-integrated advance-provision subscription models as the most penetrable access modality bypassing traditional pharmacy infrastructure. Lead with discrete packaging configurations optimized for youth segment portability requirements. For Investors and Strategic Acquirers: Roll-up economics work for Indian API-forward manufacturers because WHO prequalification status unlocks simultaneous access to regulated and emerging market procurement channels. Five-to-ten year viability favors sponsors with captive hormone synthesis capabilities and established CDSCO regulatory relationships. Monitor FDA clinical pharmacology review division queue lengths for bioequivalence study approvals as inflection indicator for generic pipeline velocity.| Strategic Initiative | Industry Significance |
|---|---|
| OTC Switch Pathway Navigation | FDA prescription-to-OTC reclassification eliminates physician gatekeeping and expands addressable population. |
| Dual-Label Formulation Development | Fixed-dose combinations pairing levonorgestrel with STI prophylaxis agents enable single-intervention post-exposure protocols. |
| Telehealth Platform Integration | Asynchronous consultation models create direct-to-patient subscription channels bypassing pharmacy infrastructure. |
| WHO Prequalification Investment | API certification unlocks institutional procurement contracts across regulated and emerging markets simultaneously. |
| Orally Disintegrating Tablet Launch | Water-independent administration expands addressable settings beyond traditional pharmacy access points. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build convergent validity across data streams. Primary engagement captured perspectives from regulatory affairs leads at pharmaceutical sponsors, formulary directors at US Medicaid programs, procurement managers at humanitarian aid organizations, and pharmacy benefit managers overseeing contraceptive coverage. Secondary validation drew from FDA filings for prescription-to-OTC switch applications, EMA centralized procedure documentation, WHO prequalification inspection reports, and ClinicalTrials.gov entries for hormonal contraceptive efficacy studies. Bottom-up volume modeling triangulated against top-down market sizing from API production capacity and finished formulation trade data.
Historical reference periods anchored the projection horizon through documented levonorgestrel OTC switch adoption curves and ulipristal acetate reimbursement tier expansion patterns. Segmentation dimensions modeled include product chemistry, delivery mode, packaging configuration, and channel access modality. CAGRs derived from fitted growth curves applied to volume and value outputs across the analysis window. Industry-specific forecast inputs incorporated FDA clinical pharmacology review division throughput rates and WHO prequalification approval timelines for Indian API producers.
Several conditions sit outside the modeled scope, including pending regulatory decisions on school-based distribution pilots and retrospective EMA label amendment pressures for ulipristal mechanism-of-action language. Forecasts reflect documented assumptions about telehealth platform regulatory acceptance and cold chain infrastructure expansion in tropical climates. Practitioners should monitor FDA bioequivalence study queue delays and European synthesis facility manufacturing disruption reports for early signals of supply constraint.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Small Molecule Innovator CDMO Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
North America Anesthesia Drugs Market
Pharmaceuticals
Anti-Infective Vaccines Market
Pharmaceuticals
Laxatives Market
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
Atorvastatin Diepoxide Calcium Salt Market
Pharmaceuticals
Middle-East and Africa Diabetes Drugs Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market
Pharmaceuticals
Spain Opioids Market
Pharmaceuticals
Hepatitis - B Therapeutics Market
Pharmaceuticals
Italy Pharmaceutical Market
Pharmaceuticals
Antiviral Drugs Market
Pharmaceuticals
Global Chickenpox Vaccine Market
Pharmaceuticals
Estrogen Replacement Therapy (ERT) Market