
 Global Raloxifene Hydrochloride Market | 2026-2036
Global Raloxifene Hydrochloride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Raloxifene Hydrochloride Market Foresight
Active pharmaceutical ingredient production in India and China is restructuring supply dynamics for raloxifene hydrochloride. Eli Lilly and Company leverages its originator expertise to sustain brand loyalty in osteoporosis therapy. Teva Pharmaceutical Industries Ltd. competes aggressively through generic scale, while Aurobindo Pharma anchors cost-efficient manufacturing for export markets.
Raloxifene hydrochloride is a selective estrogen receptor modulator with a benzothiophene core structure, formulated primarily as 60 mg oral tablets for the prevention and treatment of postmenopausal osteoporosis and reduction of invasive breast cancer risk. Tablet formulations dominate current revenue pools due to established dosing protocols and patient familiarity, while powder and granule segments serve compounding pharmacies and research laboratories with specialized formulation requirements. The therapy area segmentation reveals osteoporosis prevention as the mature volume base, with breast cancer risk reduction representing the faster-growing indication driven by expanded screening guidelines.
FDA bioequivalence standards, EMA quality guidelines under the EU pharmaceutical strategy, and NMPA drug registration requirements in China collectively shape market access and product approval timelines for manufacturers. These frameworks elevate compliance costs for new entrants while reinforcing quality differentiation among established producers. Stakeholders must monitor evolving pharmacovigilance requirements and biosimilar substitution policies across major prescribing markets to anticipate volume shifts and pricing pressures.
Market Dynamics
FDA and EMA bioequivalence standards are tightening approval pathways for generic entrants, elevating compliance costs while reinforcing quality differentiation among established producers. Pharmaceutical procurement from hospital pharmacies is intensifying as postmenopausal osteoporosis protocols expand across aging populations.
Growth Catalysts
- EMA quality guidelines under the EU pharmaceutical strategy:These standards accelerate substitution of originator products with quality-assured generics in European hospital formularies.
- Hospital pharmacy procurement intensification:Postmenopausal osteoporosis protocol expansion is driving sustained prescription volumes through institutional channels in the United States, Germany, and Japan.
- Active pharmaceutical ingredient production in India and China:Cost-efficient manufacturing capacity is restructuring supply dynamics and enabling competitive export pricing for finished dosage forms.
Market Restraints
- API supply concentration risk:Dependence on Indian and Chinese intermediate suppliers creates vulnerability to export license delays and environmental compliance shutdowns.
- FDA bioequivalence testing costs:Complex pharmacokinetic study requirements for 60 mg tablet formulations impose substantial capital barriers on prospective generic entrants.
- Fixed-dose substitution limitations:The single-strength 60 mg presentation restricts therapeutic flexibility compared to dose-titrated alternatives in osteoporosis management.
Strategic Opportunities
- Breast cancer risk reduction indication expansion:Updated screening guidelines in the United States are redirecting prophylactic therapy selection toward selective estrogen receptor modulators.
- Compounding pharmacy channel development:Powder and granule segments for specialized formulation requirements offer margin expansion beyond commoditized tablet markets.
- Japan's aging demographic acceleration:PMDA streamlined approval pathways for generic osteoporosis therapies align with national healthcare cost containment priorities.
Industry Challenges
- Pharmacovigilance reporting complexity:Venous thromboembolism signal detection requirements demand specialized safety surveillance infrastructure across multiple regulatory jurisdictions.
- Legacy manufacturing equipment retrofitting:Continuous processing adoption for benzothiophene core synthesis requires substantial capital reconfiguration of batch-oriented facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Raloxifene Hydrochloride Market |
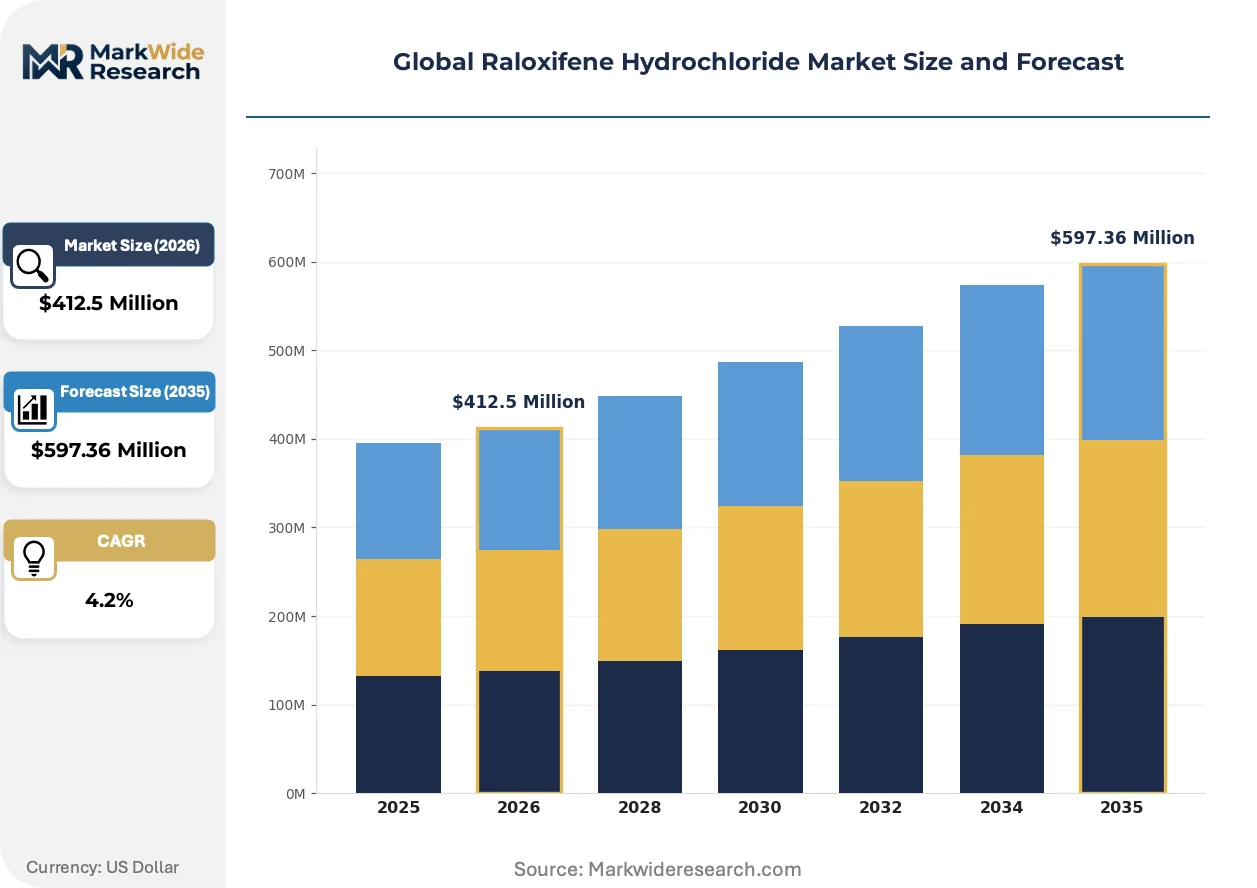
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $597.36 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Injectable, Powder, Granules Therapy Area: Osteoporosis Prevention, Breast Cancer Treatment, Cardiovascular Risk Reduction, Menopausal Symptoms Management End User: Pharmacies, Hospitals, Specialized Clinics, Research Laboratories Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Eli Lilly and Company, Teva Pharmaceutical Industries Ltd., Aurobindo Pharma, Glenmark Pharmaceuticals Ltd., Dr. Reddy’s Laboratories Ltd., ScieGen Pharmaceuticals, Apotex Corporation, Camber Pharmaceuticals, Inc., Jiangsu Hengrui Medicine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Raloxifene Hydrochloride Market Shifts & Advancements
Continuous processing technology and real-time release testing are reshaping active pharmaceutical ingredient manufacturing economics. Regulatory convergence around quality-by-design principles is compressing development timelines for complex generic formulations.
Continuous manufacturing platforms for benzothiophene ring synthesis are consolidating batch production economics across Indian and Chinese API suppliers. Mid-scale producers in Hyderabad and Zhejiang province are adopting flow chemistry to reduce solvent waste and accelerate cycle times. This technology shift is consolidating cost advantages for exporters serving FDA and EMA-regulated markets.
REACH authorization requirements for residual solvent specifications are tightening analytical qualification burdens for European-bound raloxifene hydrochloride shipments. ECHA substance evaluation protocols now mandate extended impurity profiling beyond ICH Q3A thresholds. Generic manufacturers serving Germany and France are responding by investing in in-house mass spectrometry capabilities rather than outsourcing release testing.
Hospital group purchasing organizations in the United States are consolidating formulary decisions through centralized therapeutic class reviews. Integrated delivery networks in Texas and Florida are replacing individual physician prescribing autonomy with protocol-driven osteoporosis therapy selection. This concentration is most visible in Medicare Advantage populations where capitated payment models incentivize generic substitution at the point of care.
Global Raloxifene Hydrochloride Market Segmentation
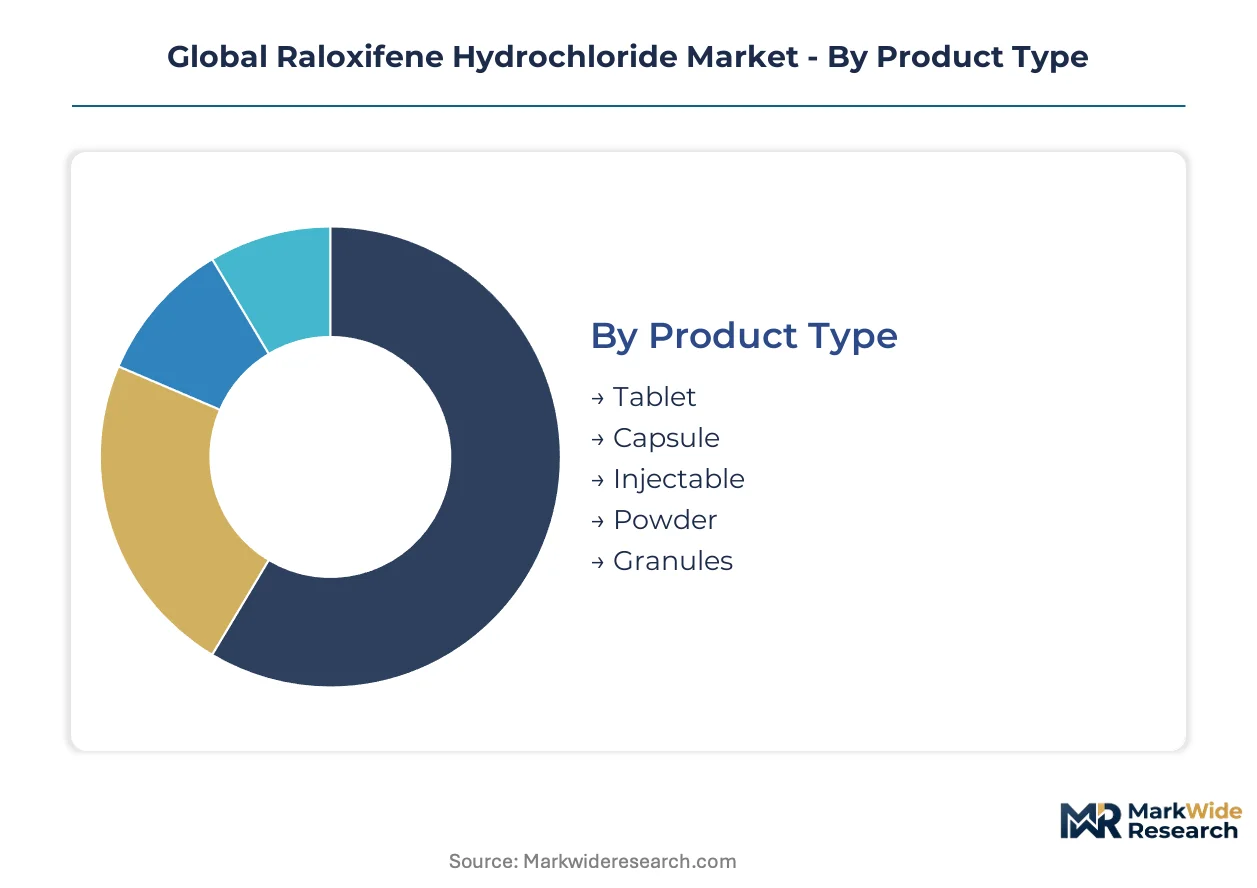
Raloxifene hydrochloride market dynamics fragment across formulation types, clinical applications, and procurement channels. Each segment carries distinct margin profiles, regulatory burdens, and competitive intensity that shape manufacturer positioning.
Product Type:
Formulation formats divide between finished dosage forms for direct dispensing and raw materials for compounding or research use.
- Tablet:The 60 mg oral tablet dominates commercial volume through established osteoporosis protocols and patient familiarity with once-daily dosing. Hospital formularies in the United States, Germany, and Japan concentrate procurement here due to bioequivalence documentation requirements and streamlined insurance reimbursement.
- Capsule:Alternative encapsulation serves markets with specific excipient tolerances or regional manufacturing preferences, though clinical equivalence to the reference tablet formulation demands additional pharmacokinetic validation. Demand clusters in compounding pharmacy networks seeking formulation flexibility.
- Injectable:Parenteral presentations remain developmental with limited commercial presence.
- Powder:Active pharmaceutical ingredient in bulk form supplies research laboratories and specialized compounding operations.
- Granules:Intermediate processing material enables regional formulation facilities to finish dosage forms locally.
Volume placements concentrate in Tablet; the faster expansion belongs to Powder as research applications multiply.
Therapy Area:
Clinical indications span preventive and therapeutic applications with divergent prescriber bases and reimbursement pathways.
- Osteoporosis Prevention:The mature volume base serving postmenopausal women drives sustained prescription flows through institutional protocols and primary care networks. Medicare Advantage formularies in the United States and Japan's national health insurance system anchor demand concentration here.
- Breast Cancer Treatment:Risk reduction for invasive breast cancer in high-risk postmenopausal women represents the application gaining share fastest, propelled by expanded screening guidelines and selective estrogen receptor modulator repositioning in oncology protocols.
- Cardiovascular Risk Reduction:Secondary vascular protection claims remain limited by mixed clinical evidence and restricted labeling.
- Menopausal Symptoms Management:Off-label use for vasomotor symptoms persists despite non-indicated status in major markets.
Prescription density peaks in Osteoporosis Prevention; Breast Cancer Treatment climbs the fastest on expanded prophylactic adoption.
End User:
Customer types reflect the care setting where clinical decisions and procurement authority converge.
- Pharmacies:Retail and community dispensaries handle the majority of outpatient prescription fulfillment.
- Hospitals:Integrated delivery networks and academic medical centers drive institutional procurement through therapeutic class reviews and protocol-driven selection. Texas and Florida hospital systems exemplify concentrated purchasing authority.
- Specialized Clinics:Osteoporosis and breast cancer centers deliver targeted therapy initiation with higher compliance monitoring.
- Research Laboratories:Academic and contract research organizations source API and reference materials for investigational programs.
Procurement authority centralizes in Hospitals; Research Laboratories expand most quickly on clinical trial activity.
Distribution Channel:
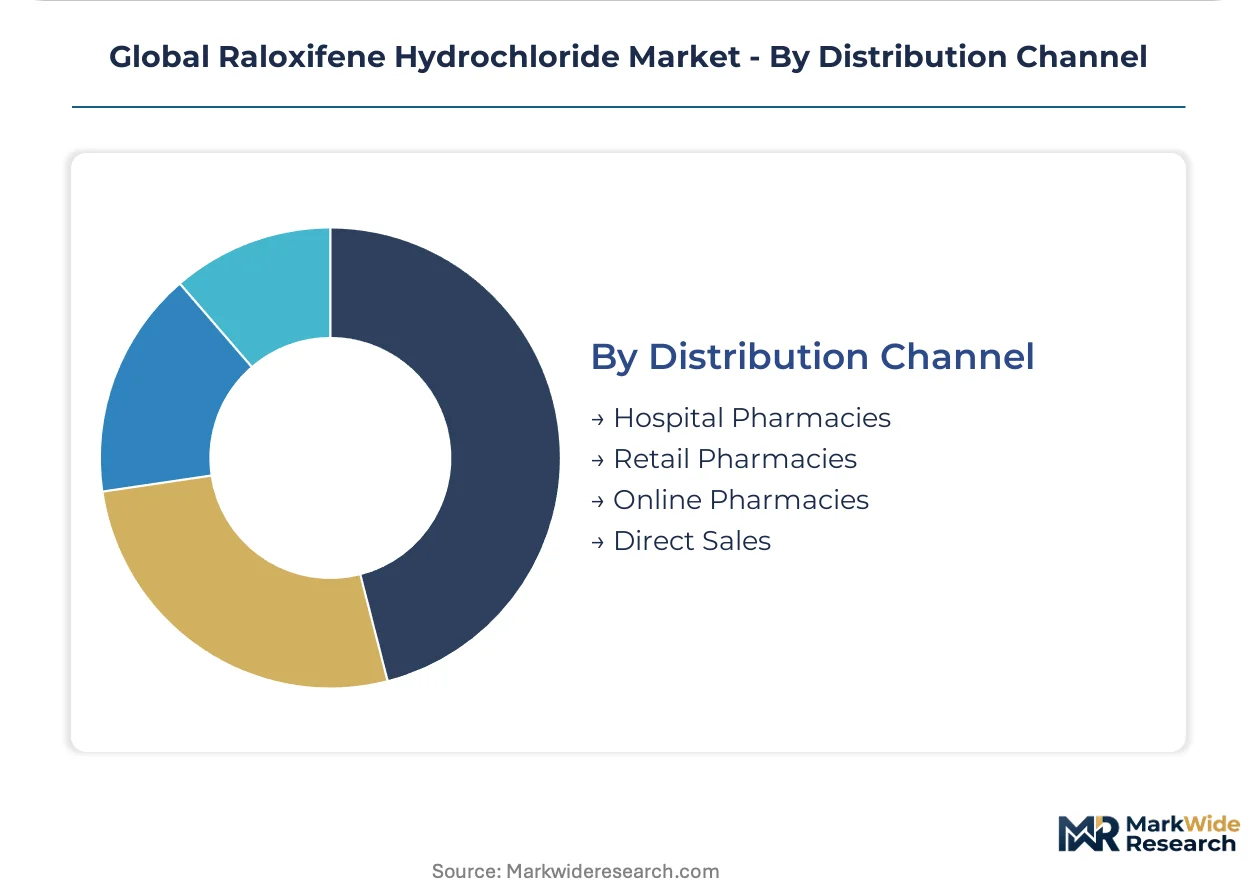
Product flow to end users separates through institutional, retail, digital, and direct pathways with distinct margin and service requirements.
- Hospital Pharmacies:In-house dispensaries within integrated health systems capture growing share through formulary consolidation and capitated payment incentives. Group purchasing organizations in the United States accelerate generic substitution at the point of care.
- Retail Pharmacies:Community chains and independent stores serve the residual outpatient market with established patient relationships.
- Online Pharmacies:Digital dispensaries gain traction for maintenance prescriptions and patient convenience.
- Direct Sales:Manufacturer-to-institution arrangements serve research and compounding accounts with specialized documentation needs.
Volume concentrates in Hospital Pharmacies; Online Pharmacies gain share fastest on digital health adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian and Chinese intermediate suppliers anchor raw material flows for raloxifene hydrochloride synthesis. Hyderabad and Zhejiang province concentrate active pharmaceutical ingredient capacity. Finished dosage form manufacturing clusters in the United States, Germany, and Japan convert these inputs into commercial supply.
United States
Medicare Advantage formularies and integrated delivery networks in Texas and Florida drive institutional procurement concentration. FDA bioequivalence standards for generic 60 mg tablets elevate compliance costs while reinforcing quality differentiation. Hospital group purchasing organizations in the Southeast and Southwest consolidate therapeutic class reviews to accelerate generic substitution.
Germany
EMA quality guidelines under the EU pharmaceutical strategy accelerate originator-to-generic substitution in hospital formularies. ECHA REACH authorization requirements for residual solvent specifications tighten analytical qualification burdens for inbound API shipments. Chemical manufacturing clusters in North Rhine-Westphalia and Bavaria invest in in-house mass spectrometry capabilities to meet extended impurity profiling mandates.
Japan
PMDA streamlined approval pathways for generic osteoporosis therapies align with national healthcare cost containment priorities. Aging demographic acceleration in Kanto and Kansai regions sustains prescription volume expansion through institutional channels. Domestic pharmaceutical manufacturers in Tokyo and Osaka metropolitan areas leverage these regulatory efficiencies to defend market position against Indian and Chinese exporters.
China
NMPA drug registration requirements shape market access timelines for finished dosage form producers serving domestic and export markets. Dual carbon goals and environmental compliance shutdowns create periodic vulnerability in benzothiophene intermediate supply. API manufacturing clusters in Jiangsu and Zhejiang provinces adopt continuous processing platforms to reduce solvent waste and accelerate cycle times for FDA and EMA-regulated shipments.
India
CDSCO export license frameworks and DGFT pharmaceutical trade policies govern API shipment authorization to regulated markets. Cost-efficient manufacturing capacity in Hyderabad and Ahmedabad enables competitive export pricing for finished dosage forms. Domestic formulators face increasing pressure from Chinese intermediate suppliers while consolidating backward integration into benzothiophene core synthesis.
Global Raloxifene Hydrochloride Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance and manufacturing scale dimensions. The vendor base separates into originator-dependent innovators, generic scale operators, and cost-focused API exporters. Three strategic archetypes dominate: brand-loyalty defenders leveraging clinical data heritage, high-volume manufacturers optimizing batch economics, and vertically integrated specialists controlling intermediate supply. Capacity expansion and geographic diversification represent the dominant competitive moves as players respond to procurement centralization in hospital systems.
Among originator-aligned entities, Eli Lilly and Company occupies a position exemplifying brand loyalty defense in osteoporosis therapy. Teva Pharmaceutical Industries Ltd. and Aurobindo Pharma represent contrasting scale archetypes—Israeli-headquartered generic manufacturing at volume versus Indian-based cost-efficient production for export markets. These three anchors illustrate how competitive positioning fragments across regulatory sophistication, manufacturing geography, and vertical integration depth.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Teva Pharmaceutical Industries Ltd. |
| Aurobindo Pharma |
| Glenmark Pharmaceuticals Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| ScieGen Pharmaceuticals |
| Apotex Corporation |
| Camber Pharmaceuticals, Inc. |
| Jiangsu Hengrui Medicine |
| Others |
Supply & Pricing Matrix
Benzothiophene intermediate pricing indices cascade through raloxifene hydrochloride supply tiers, compressing margins for API converters in India while amplifying cost pass-through advantages for integrated manufacturers serving FDA and EMA-regulated markets. Hospital group purchasing organizations in the United States exploit this concentration to extract volume discounts from finished dosage form suppliers.
Pricing Analysis
After-sales service bundling separates originator-grade raloxifene from unbundled generic offerings, with Eli Lilly's Evista legacy commanding premium positioning through pharmacovigilance support and patient adherence programs. Three-tier pricing structure across premium, standard, and economy levels reflects FDA bioequivalence certification tiers, volume commitment scales, and geographic delivery logistics. Price differentiation hinges on ICH Q3A impurity profiling depth and REACH-compliant solvent documentation. Cost compression in standard-tier 60 mg tablets is intensifying because Teva and Aurobindo are competing for Medicare Advantage formulary slots. Research laboratories exhibit highest price sensitivity due to discretionary procurement budgets, while integrated delivery networks in Texas and Florida demonstrate lowest sensitivity under capitated payment models.
Supply Chain Analysis
Return flows of expired raloxifene inventory are negligible given pharmaceutical disposal regulations, though API batch rejections from Zhejiang and Hyderabad facilities create secondary material streams for reprocessing. Benzothiophene core synthesis concentrates in China and India, with finished tablet conversion clustering in the United States, Germany, and Japan. The supply chain draws from 4-hydroxybenzothiophene intermediates, acylation reagents, and specialized excipient blends. Single-source vulnerability persists for high-purity benzothiophene feedstock where environmental compliance shutdowns in Jiangsu province disrupt global API availability. Distribution runs through hospital group purchasing organizations in North America, pharmaceutical wholesalers in Europe, and institutional procurement consortia in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over benzothiophene intermediate supply determines margin sustainability against Chinese and Indian API exporters.
For Market Incumbents: Lock in formulary positioning through PMDA streamlined approval pathways in Japan and hospital system partnerships in Texas and Florida. Eli Lilly and Teva should deepen backward integration into benzothiophene core synthesis to offset API supply concentration risk from Zhejiang and Hyderabad. FDA bioequivalence testing cost barriers protect established players from emerging entrants, though continuous processing adoption demands capital reconfiguration of legacy batch facilities.
For New Entrants and Emerging Players: PMDA streamlined approval pathways in Japan open a window for generic osteoporosis therapy entrants seeking to bypass saturated United States and German markets. Target breast cancer risk reduction indication expansion where updated screening guidelines redirect prophylactic therapy selection. Compounding pharmacy channel development for powder and granule segments offers margin expansion beyond commoditized tablet markets with lower regulatory entry barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale API manufacturers with existing benzothiophene synthesis capabilities in Zhejiang or Hyderabad. Long-term viability centers on regulatory sophistication depth and continuous processing technology adoption rather than pure volume scale. Watch for ECHA REACH authorization enforcement intensity as the inflection indicator for European market access cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Benzothiophene Synthesis | Captive intermediate supply insulates margins from Zhejiang environmental compliance shutdowns. |
| PMDA Streamlined Approval Pathway | Accelerated generic entry in Japan aligns with national healthcare cost containment priorities. |
| Continuous Processing Platform Adoption | Flow chemistry reduces solvent waste and accelerates cycle times for FDA-regulated shipments. |
| Hospital Group Purchasing Organization Partnership | Formulary consolidation in Texas and Florida concentrates procurement authority for volume commitments. |
| Breast Cancer Indication Expansion | Updated screening guidelines in the United States redirect prophylactic therapy toward selective estrogen receptor modulators. |
Research Methodology
Multi-period observation of FDA ANDA filing volumes, EMA marketing authorization trends, and PMDA generic approval rates anchored the trend analysis, supplemented by interviews with regulatory affairs leads at API manufacturers, formulary directors at United States hospital systems, and procurement managers at German chemical clusters. Secondary validation drew from FDA Orange Book entries, EMA EPAR assessments, ClinicalTrials.gov raloxifene protocol registries, and customs trade data for benzothiophene intermediate flows. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure triangulation converged on segment-level estimates.
Segment-weighting across formulation type, therapy area, and distribution channel dimensions structured the analytical framework throughout the projection horizon. CAGR derivation combined historical prescription growth trajectories with demographic aging elasticities and regulatory substitution policy shifts. Dosage form bioequivalence study requirements, hospital formulary generic substitution rates, and research laboratory API procurement patterns served as industry-specific forecast inputs across the modeling period.
The model assumes a particular technology adoption path; alternative pathways for continuous flow chemistry would alter the outlook for API manufacturing cost structures and competitive positioning. Forecasts incorporate assumptions regarding EMA quality guideline enforcement consistency and PMDA approval pathway efficiency. Practitioners should monitor ECHA REACH authorization intensity, PMDA generic substitution policy adjustments, and Medicare Advantage formulary consolidation rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Multiple System Atrophy (MSA) Therapeutics Market
Pharmaceuticals
US External Analgesics Market
Pharmaceuticals
Global Lidocaine Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Nicotine Replacement Product Market
Pharmaceuticals
Fibroblast Growth Factor Receptor Inhibitor Market
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Europe Adenomyosis Drugs Market
Pharmaceuticals
Global Cholera Vaccines Market
Pharmaceuticals
Antiplatelet Drugs Market
Pharmaceuticals
Bipolar Disorder Drugs and Treatment Market
Pharmaceuticals
Propofol Market