
 Europe Pharmaceutical Warehousing Market | 2026-2036
Europe Pharmaceutical Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmaceutical Warehousing Market Insights
Direct-to-pharmacy distribution is rewriting last-mile economics across Europe. DB Schenker leverages its integrated European road network to sustain ambient and cold-chain coverage in 30-plus countries. Kuehne Nagel Management AG anchors temperature-controlled capacity at Amsterdam Schiphol and Frankfurt Rhine-Main airports. GEODIS SA competes through specialized pharma lanes linking French manufacturing clusters to Southern European markets.
Europe pharmaceutical warehousing encompasses the receipt, storage, and dispatch of medicinal products under validated temperature and humidity conditions, typically maintaining 15°C to 25°C for controlled room temperature goods and 2°C to 8°C for refrigerated biologics, with full batch traceability from manufacturer to dispenser. Refrigerated storage commands the tightest capacity constraints and strongest lease rate premiums as cell and gene therapies expand. Automated storage systems attract capital fastest among storage methods, though racked pallet positions still dominate physical footprint across legacy facilities serving hospital and pharmacy end users.
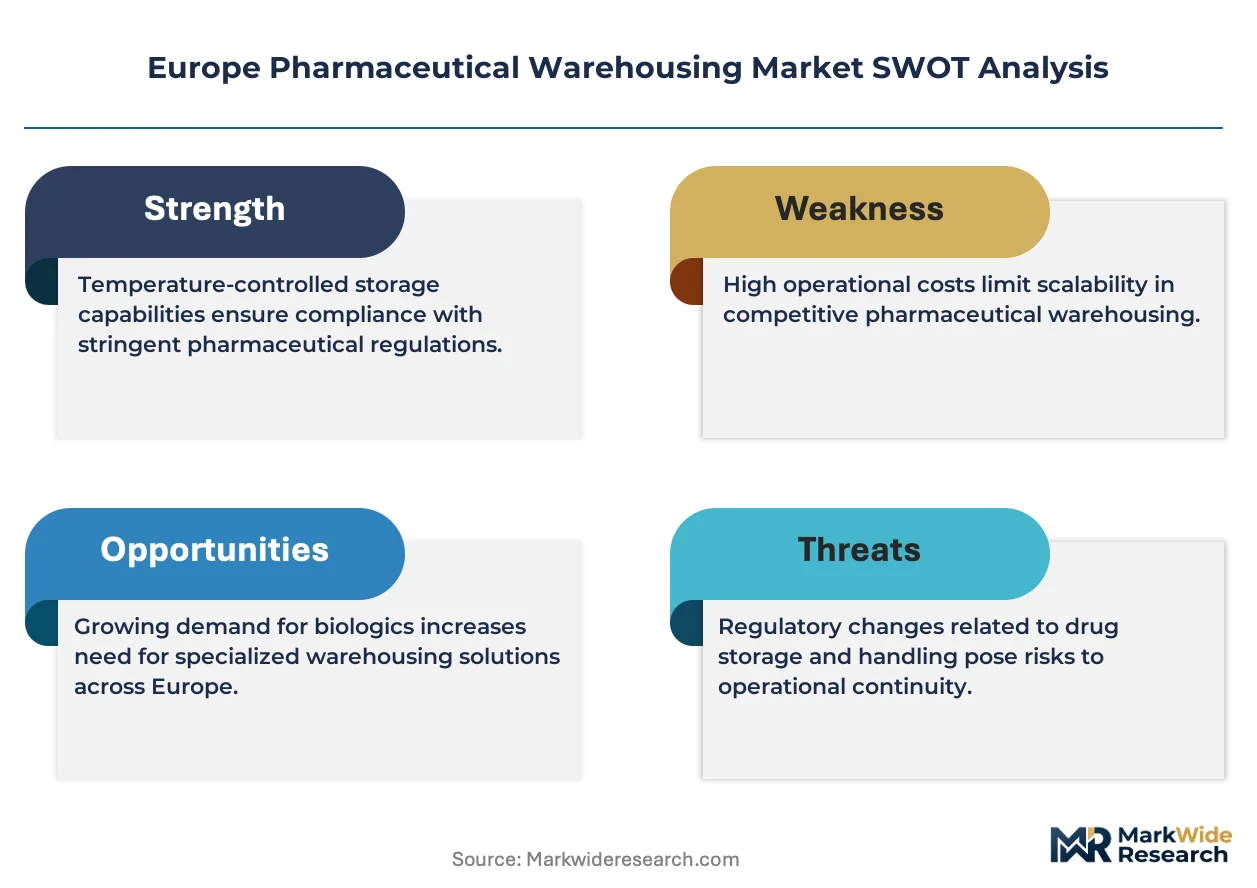
EMA guidelines and EU Good Distribution Practice standards mandate continuous temperature monitoring and documented deviation management, forcing warehouse operators to invest in validated thermal packaging and redundant cooling infrastructure. The EU F-Gas Regulation progressively restricts hydrofluorocarbon-based refrigeration, compelling retrofit programs or replacement with natural refrigerant systems. Stakeholders must weigh capital deployment between automation upgrades and regulatory-driven refrigeration overhauls as margin structures tighten.
Market Dynamics
EU Good Distribution Practice guidelines are compressing operational tolerance for temperature excursions, forcing warehouse operators to choose between redundant cooling infrastructure and automated monitoring systems as capital allocation priorities tighten.
Growth Catalysts
- EMA serialization mandates:The EU's Falsified Medicines Directive enforcement requires unit-level traceability, driving investment in validated warehouse management systems with integrated batch tracking capabilities.
- Cell and gene therapy commercialization:Cryogenic storage demand from advanced therapy medicinal products manufacturers is expanding specialized capacity requirements across German and French distribution hubs.
- Rotterdam-Frankfurt corridor concentration:Pharmaceutical cargo flows through the Netherlands and Rhine-Main region are consolidating, creating network economies for temperature-controlled cross-docking operations.
Market Restraints
- F-Gas refrigeration phase-down:The EU F-Gas Regulation's hydrofluorocarbon restrictions are accelerating equipment replacement cycles, compressing returns on existing cooling infrastructure investments.
- Specialized labor scarcity:Qualified personnel for validated thermal packaging and deviation management are concentrated in established pharma clusters, constraining facility expansion in peripheral markets.
- Real estate competition:Urban logistics demand from e-commerce and food delivery is bidding up cold-storage suitable land near Amsterdam Schiphol and Frankfurt Rhine-Main airport zones.
Strategic Opportunities
- Poland and Czech Republic expansion:Underpenetrated Central European markets present first-mover advantages for GDP-compliant facilities serving manufacturing relocations from Western Europe.
- Direct-to-pharmacy distribution:Bypassing wholesale intermediaries through dedicated last-mile cold-chain networks is compressing delivery times for hospital and retail pharmacy customers.
- CSRD sustainability reporting:The EU Corporate Sustainability Reporting Directive is creating competitive differentiation for warehouse operators with verified carbon footprint reduction and renewable energy integration.
Industry Challenges
- Deviation investigation capacity:Temperature excursion root-cause analysis requires specialized quality assurance personnel that outpace current training pipeline output.
- Legacy WMS integration:Automated storage and retrieval systems must interface with decades-old batch tracking databases without disrupting validated state.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmaceutical Warehousing Market |
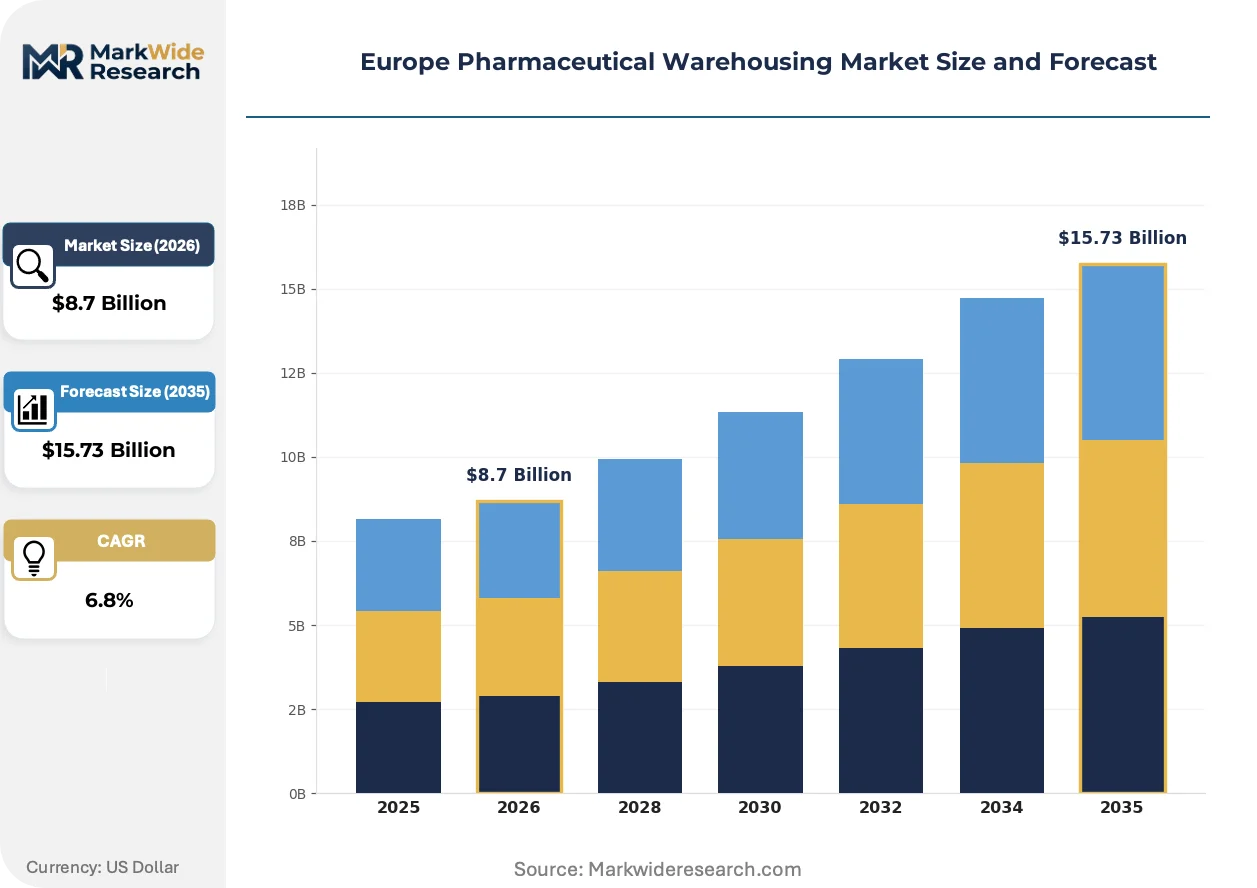
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medicines, Biologics, Vaccines, Medical Devices Temperature Control: Ambient, Refrigerated, Frozen, Controlled Room Temperature Storage Method: Racked, Palletized, Bulk, Automated Storage End User: Pharmacies, Hospitals, Distributors, Clinics |
| Companies Covered | KRC Logistics, DB Schenker, Bio Pharma Logistics, CEVA Logistics, Hellmann Worldwide Logistics SE and Co KG, Rhenus SE and Co. KG, United Parcel Service Inc., Kuehne Nagel Management AG, GEODIS SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmaceutical Warehousing Market Trends and Innovations
Digital twin technology is compressing commissioning timelines for new temperature-controlled facilities, while regulatory pressure on refrigerant chemistry and buyer consolidation are reshaping capital deployment priorities across the sector.
Digital twin platforms are virtualizing warehouse thermal mapping and equipment performance simulation before physical construction begins. German and Dutch operators are adopting these tools to reduce commissioning validation cycles for new cold-storage facilities. The technology is virtualizing risk mitigation in a sector where temperature qualification failures can delay facility activation by months.
The EU F-Gas Regulation is progressively restricting hydrofluorocarbon refrigerant availability, compelling warehouse operators to accelerate natural refrigerant system adoption. Ammonia and carbon dioxide-based cooling infrastructure requires redesigned safety protocols and modified facility layouts. French and Belgian facilities face the steepest retrofit urgency due to older installed bases of restricted refrigerant technologies.
Hospital procurement consolidation is compressing supplier lists and extending contract durations for pharmaceutical logistics providers. Integrated health systems in the Netherlands and Nordic countries are favoring warehouse operators with multi-temperature capabilities and dedicated quality agreement frameworks. This concentration is visible most acutely in tender processes for biologics distribution where single-source relationships are replacing fragmented multi-vendor arrangements.
Europe Pharmaceutical Warehousing Market Segmentation
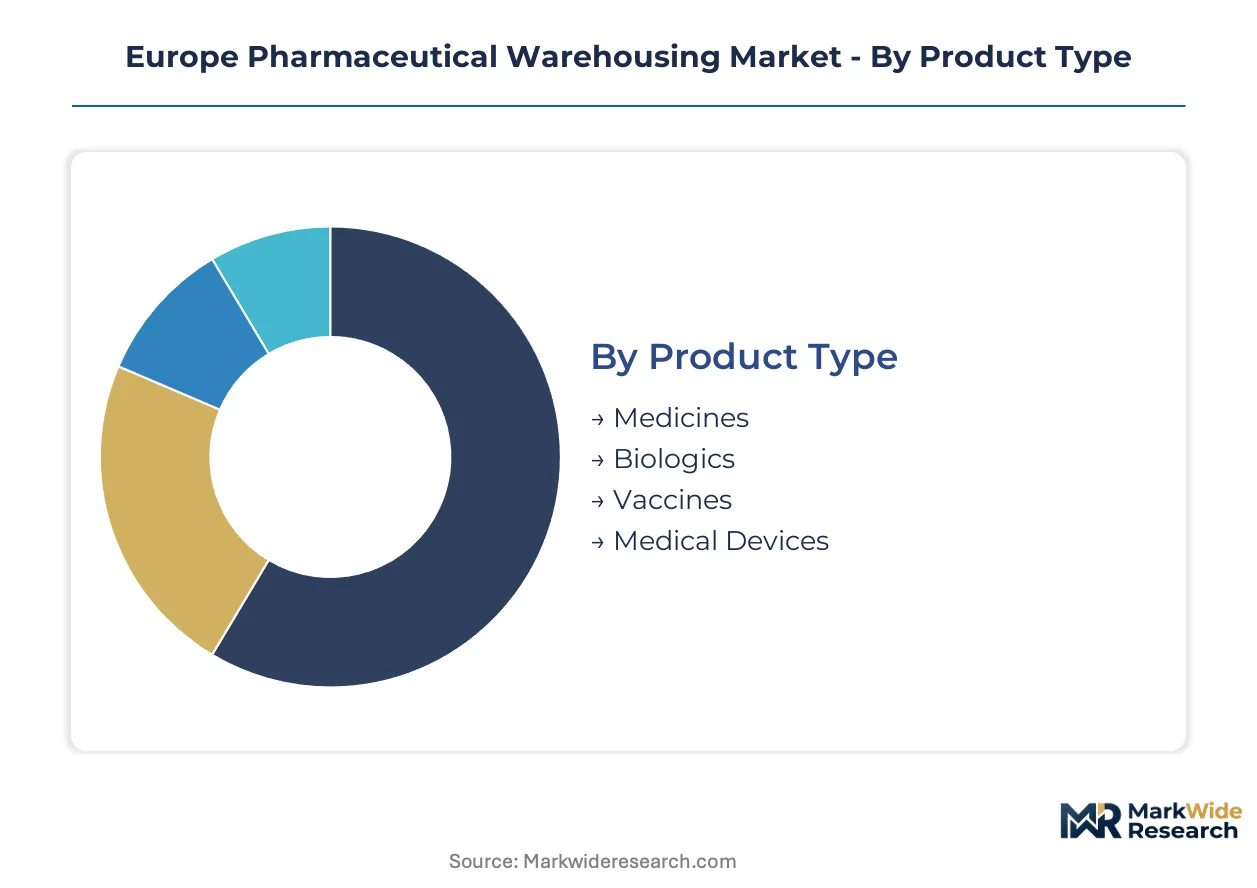
Product heterogeneity across temperature requirements and regulatory classifications drives distinct infrastructure investments. Segmentation reveals where capital concentrates versus where specialized capabilities command premium positioning.
Product Type:
Storage protocols diverge sharply across molecular complexity and patient administration routes.
- Medicines:Small-molecule tablets and capsules dominate physical throughput volumes, with ambient storage sufficient for most solid oral dosages. German and French hospital networks drive bulk replenishment cycles for chronic disease therapies.
- Biologics:Monoclonal antibodies and recombinant proteins require uninterrupted cold-chain integrity from manufacture through dispensation. EMA temperature excursion protocols mandate redundant cooling infrastructure for these high-value inventories.
- Vaccines:mRNA and viral-vector platforms need ultra-low frozen storage or specialized refrigerated distribution depending on formulation stability.
- Medical Devices:Sterile implants and diagnostic equipment demand humidity-controlled environments with validated packaging for contamination prevention.
The dominant share belongs to Medicines, while Biologics is closing the gap fastest.
Temperature Control:
Lease rate structures stratify according to thermal stringency and energy intensity.
- Ambient:Standard warehousing without active climate control suits stable solid-dose pharmaceuticals. Dutch distribution hubs near Rotterdam port leverage ambient capacity for high-velocity generic medicine throughput.
- Refrigerated:2°C to 8°C environments serve insulin, biologics, and certain vaccines. This tier attracts the steepest capacity premiums as cell therapy commercialization accelerates.
- Frozen:Sub-zero storage preserves mRNA vaccine stability and certain plasma-derived therapies. Cryogenic infrastructure requires specialized personnel training exceeding ambient facility labor pools.
- Controlled Room Temperature:15°C to 25°C corridors bridge ambient and refrigerated needs for temperature-stable biologics and certain medical devices.
Refrigerated commands the highest lease premiums, though Frozen capacity is expanding most quickly.
Storage Method:
Automation penetration varies with facility vintage and customer consolidation patterns.
- Racked:Selective pallet racking remains the default configuration across legacy hospital-serving warehouses in Belgium and Italy. Manual picking suits fragmented order profiles with low line-item counts.
- Palletized:Block stacking maximizes cube utilization for long-dated inventory with predictable rotation schedules. French pharmaceutical manufacturers favor this approach for bulk API staging.
- Bulk:Floor-loaded loose cartons accommodate promotional packaging and seasonal demand surges without racking capital commitment.
- Automated Storage:AS/RS systems with robotic retrieval minimize human contact for high-value biologics. Dutch operators at Schiphol logistics parks are deploying these systems to compress commissioning timelines and reduce deviation risk.
Racked positions dominate existing footprint, while Automated Storage is gaining share fastest.
End User:
Service level agreements diverge across customer scale and quality system maturity.
- Pharmacies:Community and hospital pharmacy networks require frequent small-lot replenishment with strict FIFO compliance. Direct-to-pharmacy distribution models are compressing wholesale intermediation in the Netherlands and Nordic markets.
- Hospitals:Integrated health systems negotiate multi-year contracts with dedicated quality agreements and batch-level traceability. German university hospitals drive demand for cryogenic capacity for clinical trial materials.
- Distributors:Wholesale intermediaries aggregate fragmented manufacturer supply for downstream pharmacy and clinic networks. GDP compliance certification determines supplier list eligibility under EU Falsified Medicines Directive enforcement.
- Clinics:Outpatient infusion centers and specialty care facilities need just-in-time delivery for patient-specific biologics with narrow administration windows.
Hospitals anchor revenue concentration, though Pharmacies are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam port complex and its direct rail links to the German industrial heartland underwrite the Netherlands' dominance in pharmaceutical distribution, channeling temperature-sensitive cargo from Atlantic shipping lanes into continental Europe.
Germany
Cell and gene therapy manufacturers in Munich and Heidelberg are expanding cryogenic storage requirements for advanced therapy medicinal products. The country's national pharmaceutical regulator enforces strict GDP compliance through regional inspection offices. The Frankfurt Rhine-Main corridor concentrates cold-chain infrastructure serving both domestic production and transshipment from Dutch ports.
Netherlands
Amsterdam Schiphol and Rotterdam port anchor the densest concentration of EU pharmaceutical warehousing capacity outside Germany. EMA guidelines on serialization and traceability drive investment in validated warehouse management systems across Dutch logistics parks. The Randstad region hosts specialized facilities for biologics cross-docking before distribution to Northwestern European markets.
France
Paris-based hospital networks and Lyon pharmaceutical manufacturing clusters sustain demand for multi-temperature storage. The EU F-Gas Regulation accelerates refrigeration retrofit programs in older facilities around Lille and Strasbourg. Île-de-France logistics zones are attracting automated storage investments to serve consolidated hospital procurement contracts.
Belgium
Brussels' position as de facto EU regulatory capital supports specialized warehousing for clinical trial materials and reference medicines. GDP certification requirements from the national pharmaceutical regulator shape facility investment decisions. The Antwerp port hinterland hosts temperature-controlled consolidation centers linking French and German production to UK markets.
Poland
Manufacturing relocations from Western Europe are stimulating GDP-compliant facility development around Warsaw and Kraków. EU structural funds support cold-chain infrastructure upgrades to meet EMA distribution standards. The country's central location is attracting regional distribution center investments from Western European logistics operators seeking lower-cost alternatives.
Europe Pharmaceutical Warehousing Market Competitive Landscape
On the supply side, the industry is consolidating around integrated logistics networks with dedicated pharmaceutical certifications. Tiered competition separates global freight forwarders with dedicated healthcare divisions from regional specialists focused on temperature-controlled compliance. Strategic archetypes include airport-centric cold-chain operators, port-linked distribution consolidators, and direct-to-pharmacy last-mile specialists. Dominant competitive moves involve M&A to acquire GDP-certified facilities and strategic partnerships with biopharma manufacturers for dedicated capacity.
Among integrated European networks, DB Schenker, Kuehne Nagel Management AG, and GEODIS SA exemplify distinct positioning archetypes. DB Schenker leverages its road network density across 30-plus countries to sustain ambient and cold-chain coverage at scale. Kuehne Nagel Management AG anchors temperature-controlled capacity at Amsterdam Schiphol and Frankfurt Rhine-Main, representing the airport-centric specialization vector. GEODIS SA occupies a position linking French manufacturing clusters to Southern European markets through dedicated pharma lanes.
| Leading Market Players |
|---|
| KRC Logistics |
| DB Schenker |
| Bio Pharma Logistics |
| CEVA Logistics |
| Hellmann Worldwide Logistics SE and Co KG |
| Rhenus SE and Co. KG |
| United Parcel Service Inc. |
| Kuehne Nagel Management AG |
| GEODIS SA |
| Others |
Pricing and Supply Chain Analysis
Rotterdam port concentration for Atlantic pharmaceutical imports anchors lease rate premiums for refrigerated capacity across the Netherlands and German Rhine-Main corridor. Margin pools concentrate with operators holding redundant cooling infrastructure and EMA-validated warehouse management systems.
Pricing Analysis
Volume-discount tiering separates dedicated capacity contracts from spot-market pallet positions. Pricing stratifies across GDP-certified premium facilities, standard temperature-controlled warehouses, and ambient generic storage tiers. Lease rate compression runs through ambient capacity as e-commerce logistics bids up cold-storage suitable land near Amsterdam Schiphol. Hospital procurement consolidation renders integrated health systems least price-sensitive; fragmented wholesale intermediaries face acute margin pressure.
Supply Chain Analysis
Upstream feedstock for temperature-controlled infrastructure draws from German refrigeration equipment manufacturers, Belgian thermal packaging specialists, and Dutch warehouse automation providers. Natural refrigerant systems hinge on ammonia and carbon dioxide component supply chains facing EU F-Gas Regulation acceleration. Single-source vulnerability concentrates in validated cold-chain packaging materials. Distribution runs through Rotterdam-Frankfurt corridor consolidation centers before last-mile pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell and gene therapy commercialization is reshaping competitive positioning as cryogenic storage demand outpaces qualified facility supply. EMA serialization mandates and EU GDP guideline enforcement create regulatory moats for compliant operators.
For Market Incumbents: Entrench market position through redundant cooling infrastructure deployment at Amsterdam Schiphol and Frankfurt Rhine-Main hubs. Acquire GDP-certified facilities in Poland and Czech Republic before manufacturing relocations saturate Central European capacity. Certification investment in automated storage and retrieval systems counters labor scarcity threats.
For New Entrants and Emerging Players: Underpenetrated Central European markets represent the most penetrable entry point for GDP-compliant cold-chain facilities. Direct-to-pharmacy distribution networks in Nordic countries offer white-space expansion with consolidated hospital procurement as anchor demand. Partner with biopharma manufacturers for dedicated cryogenic capacity rather than competing for spot-market pharmaceutical cargo.
For Investors and Strategic Acquirers: Capital is best deployed toward automated storage specialists with validated thermal infrastructure and established EMA quality agreements. Long-term viability centers on operators integrating renewable energy systems ahead of CSRD sustainability reporting mandates. Watch F-Gas Regulation retrofit timelines as inflection indicator for distressed asset opportunities in French and Belgian legacy facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Investment | EMA compliance validates facility eligibility for Falsified Medicines Directive enforcement. |
| Natural Refrigerant Retrofit | EU F-Gas Regulation phase-down accelerates equipment replacement cycles in older facilities. |
| Automated Storage Deployment | AS/RS systems reduce deviation risk and compress commissioning timelines at Schiphol logistics parks. |
| Direct-to-Pharmacy Network Buildout | Bypassing wholesale intermediaries captures margin from consolidated hospital procurement contracts. |
| Central European Facility Expansion | Poland and Czech Republic manufacturing relocations drive GDP-compliant capacity demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EMA regulatory filings, EU customs trade databases, and pharmaceutical logistics operator disclosures. Interviews with warehouse operations directors, quality assurance managers, cold-chain packaging engineers, and hospital procurement officers informed operational constraints and investment priorities. Bottom-up facility capacity counts triangulate against top-down pharmaceutical trade flow analysis.
Forecast inputs span temperature control tiers, storage method automation levels, end-user contract structures, and regional regulatory cluster variations across the projection horizon. CAGRs derive from facility investment pipelines, manufacturing relocation patterns, and therapy commercialization timelines. Modeled dimensions include product molecular complexity, patient administration routes, and distribution network consolidation trajectories.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments, energy cost volatility, or pharmaceutical trade policy would shift the trajectory. Forecasts reflect documented assumptions about EMA enforcement consistency and F-Gas Regulation implementation pace. Cross-checking against pharmaceutical import statistics and cold-storage construction permit data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Anticoccidial Drugs Market
Pharmaceuticals
Global Respiratory Drug Market
Pharmaceuticals
Esomeprazole Market
Pharmaceuticals
Global Nasal Drug Delivery Market
Pharmaceuticals
Dextromethorphan Market
Pharmaceuticals
Soft Capsules Drugs CMO Market
Pharmaceuticals
Global Interstitial Cystitis Drugs Market
Pharmaceuticals
Extended Oral Antibiotics Market
Pharmaceuticals
North America SGLT2 Inhibitors Market
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Global Bendamustine Injection Market
Pharmaceuticals
Global Anti-Infective Agents Market
Pharmaceuticals
Global Topical Analgesic Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market