
 Cyclosporine Drugs Market | 2026-2036
Cyclosporine Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Cyclosporine Drugs Market Outlook
USP-NF monograph compliance is bifurcating the competitive landscape between originator-grade and commoditized generic suppliers. Novartis AG leverages its transplant franchise heritage to sustain premium positioning in nephrology protocols. Sun Pharmaceutical Industries Ltd. anchors its presence through vertically integrated API-to-finished-dose manufacturing in regulated markets. Teva Pharmaceutical Industries Ltd. competes aggressively on cost while navigating complex abbreviated new drug application pathways.
Cyclosporine is a cyclic undecapeptide calcineurin inhibitor derived from Tolypocladium inflatum, formulated at standard concentrations of 25 mg, 50 mg, and 100 mg for oral administration, with primary purpose of preventing organ rejection and treating autoimmune pathologies. Capsules dominate value generation due to chronic maintenance dosing in transplant recipients, while ophthalmic formulations represent the fastest-expanding margin pool driven by dry eye syndrome protocols. Therapy area concentration in transplantation reflects mature reimbursement structures, though autoimmune disorder applications are gaining clinical traction in rheumatology and dermatology practice settings.
FDA bioequivalence standards and EMA immunosuppressant guidance documents enforce narrow therapeutic index protocols that limit substitutability and protect quality-tier suppliers. India's CDSCO and China's NMPA are converging toward ICH Q3D impurity specifications, raising compliance costs for export-oriented manufacturers. Stakeholders must monitor evolving pharmacovigilance requirements for generic immunosuppressants as regulators tighten post-market surveillance obligations.
Market Dynamics
Transplantation program expansion in emerging health systems is intensifying procurement competition between originator-grade and commoditized generic suppliers, with USP-NF monograph compliance emerging as the primary quality differentiator reshaping supplier viability.
Growth Catalysts
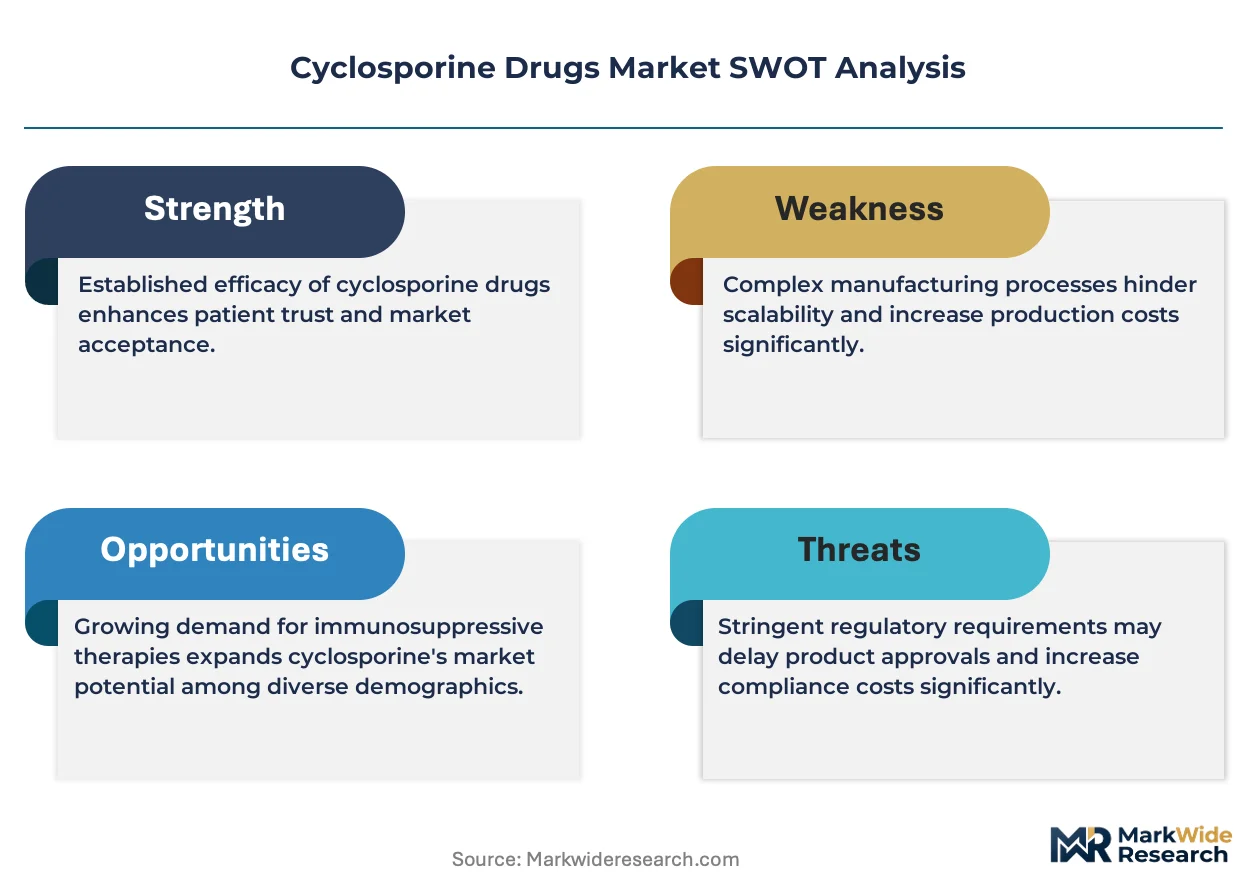
- EMA immunosuppressant guidance:Narrow therapeutic index protocols limit substitutability and protect quality-tier suppliers from price-only competition.
- Dry eye syndrome protocols:Ophthalmic formulations are capturing expanding margin pools as chronic ocular surface disease management protocols proliferate.
- India's hospital pharmacy networks:Concentrated demand from institutional procurement is consolidating volume toward vertically integrated domestic manufacturers.
Market Restraints
- Tolypocladium inflatum fermentation capacity:API production concentrates among limited fermentation specialists, creating supply vulnerability for non-integrated finished-dose manufacturers.
- FDA abbreviated new drug application complexity:Bioequivalence demonstration for calcineurin inhibitors demands extensive pharmacokinetic studies that extend generic approval timelines.
- Biologic immunosuppressant substitution:Monoclonal antibody induction regimens in high-risk transplantation are compressing cyclosporine's share in de novo immunosuppression protocols.
Strategic Opportunities
- China's NMPA ICH Q3D convergence:Rising compliance costs for export-oriented manufacturers create acquisition opportunities for quality-certified regional players.
- Rheumatology practice settings:Autoimmune disorder applications in psoriatic arthritis and lupus nephritis represent underpenetrated therapy area expansion.
- Direct-to-clinic distribution models:Bypassing wholesale intermediaries in transplant center networks captures margin and strengthens prescriber relationships.
Industry Challenges
- Pharmacovigilance system integration:Post-market surveillance obligations for generic immunosuppressants require substantial IT infrastructure investment that mid-tier manufacturers struggle to fund.
- Legacy calcineurin inhibitor switching protocols:Established transplant center formularies with tacrolimus dominance create institutional resistance to cyclosporine reintroduction despite comparable efficacy profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyclosporine Drugs Market |
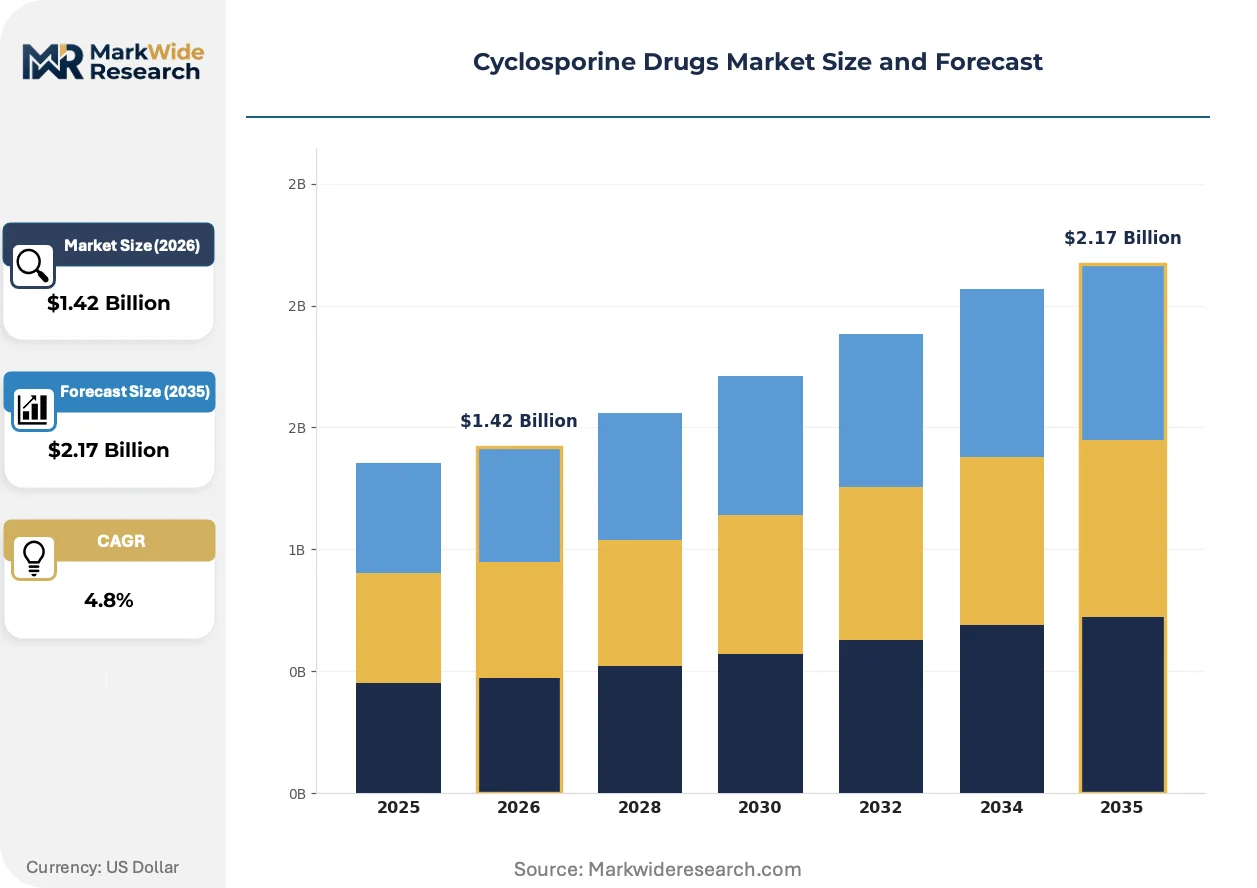
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Injections, Oral Solution, Eye Drops Therapy Area: Transplantation, Autoimmune Disorders, Ophthalmology, Dermatology End User: Hospitals, Clinics, Homecare, Specialty Pharmacies Delivery Mode: Intravenous, Oral, Topical, Subcutaneous |
| Companies Covered | Novartis AG, Sun Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd., AbbVie Inc., Santen Pharmaceutical Co., Ltd., Apotex Inc., Strides Pharma Science Limited, Sandoz International GmbH, Viatris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyclosporine Drugs Market Strategic Shifts
Formulation science advances and regulatory harmonization pressures are restructuring competitive advantage sources away from pure manufacturing scale toward specialized delivery technology and compliance infrastructure.
Nanolipid carrier ophthalmic emulsions is supplanting conventional oil-based eye drops in dry eye syndrome management. Retina specialists and cornea clinics are accelerating adoption of these formulations for chronic immunomodulation. The technology is compressing pricing power for conventional cyclosporine ophthalmic solutions while elevating reimbursement thresholds for differentiated delivery platforms.
ICH Q3D elemental impurity specifications are harmonizing quality standards across FDA, EMA, and NMPA jurisdictions. This regulatory convergence is elevating analytical chemistry and quality control infrastructure requirements for API manufacturers. Export-oriented suppliers in India and China are consolidating through acquisition to spread compliance costs across larger revenue bases.
Transplant center consolidation into regional health networks is centralizing formulary decision-making and contracting authority. Independent community nephrology practices are losing procurement autonomy as purchasing shifts to centralized pharmacy and therapeutics committees. This concentration is most visible in the United States and Germany, where hospital system mergers have reduced the number of independent transplant programs by substantial margins over the past decade.
Cyclosporine Drugs Market Segmentation
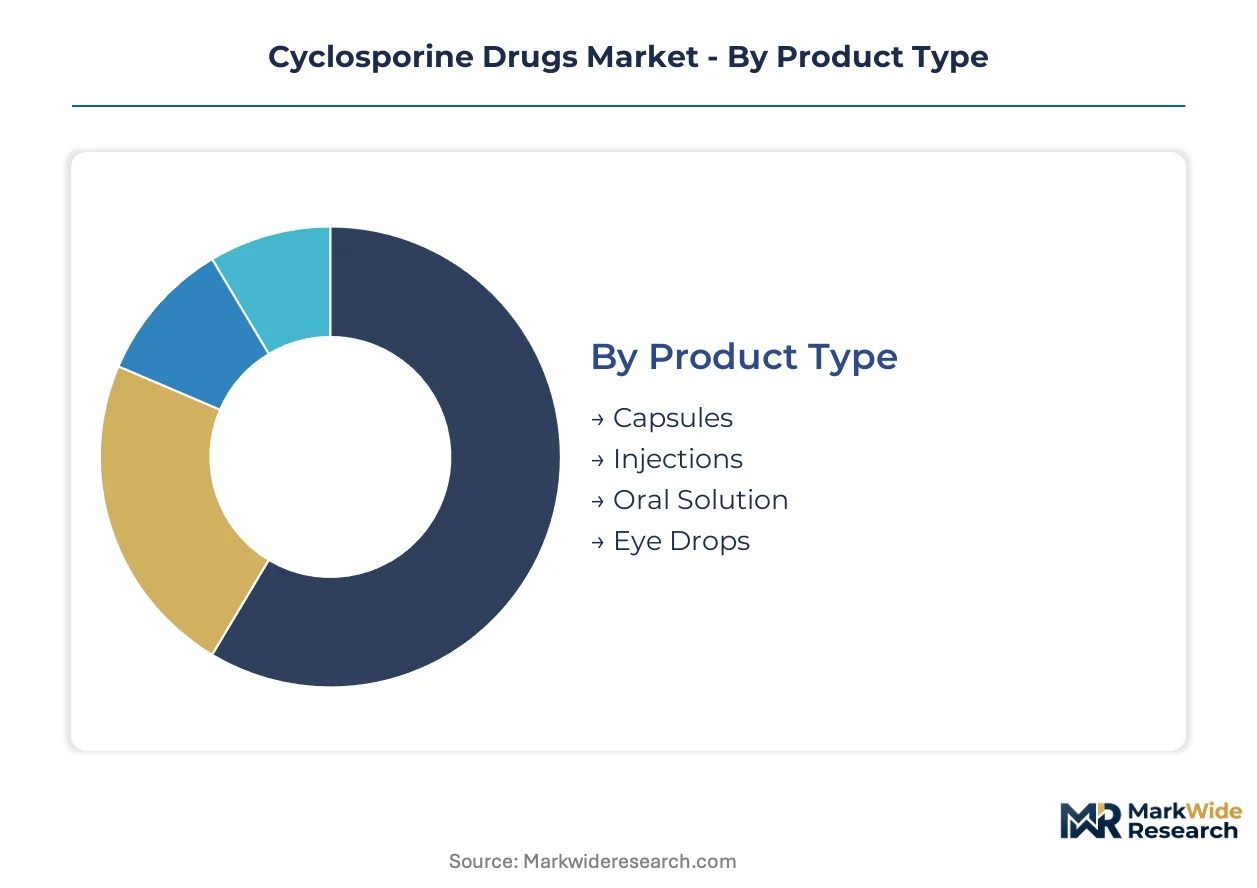
Cyclosporine's narrow therapeutic index demands precise segment targeting, as substitution risks vary sharply across formulations. Portfolio allocation decisions hinge on distinguishing chronic maintenance volumes from acute intervention opportunities.
Product Type:
Capsules and ophthalmic formulations face divergent substitution pressures, with oral maintenance dosing protected by therapeutic inertia while eye drops confront novel nanolipid carrier displacement.
- Capsules:Standard 25 mg, 50 mg, and 100 mg oral formulations for chronic immunosuppression. Demand concentrates in transplant center maintenance protocols where prescriber familiarity and patient stability resist switching. FDA bioequivalence requirements for narrow therapeutic index drugs protect incumbent suppliers from rapid generic erosion.
- Eye Drops:Oil-based ophthalmic solutions for dry eye syndrome management. Retina specialists and cornea clinics in India's hospital pharmacy networks are accelerating adoption, though nanolipid carrier emulsions are compressing pricing power for conventional formulations.
- Injections:Intravenous formulations for acute rejection episodes and perioperative immunosuppression. Hospital pharmacy networks favor pre-filled syringe presentations to reduce compounding errors.
- Oral Solution:Liquid formulations for pediatric patients and those with swallowing difficulties. CDSCO-regulated manufacturers in India dominate supply to institutional procurement channels.
Capsules anchor the volume base while eye drops gain share at the steepest rate.
Therapy Area:
Cost tier stratification separates mature transplantation reimbursement from emerging autoimmune disorder applications where prior authorization requirements create access friction.
- Transplantation:Kidney, liver, and heart allograft rejection prophylaxis with established Medicare and private payer coverage. Volume concentrates in United States and German transplant center networks where tacrolimus dominance creates institutional resistance to cyclosporine reintroduction.
- Autoimmune Disorders:Rheumatology and dermatology applications including psoriatic arthritis and lupus nephritis. Rheumatology practice settings in India's tier-1 cities represent underpenetrated expansion territory as CDSCO streamlines indication additions.
- Ophthalmology:Chronic ocular surface disease management with expanding dry eye syndrome protocols. Reimbursement thresholds for differentiated delivery platforms are elevating above conventional oil-based solutions.
- Dermatology:Psoriasis and atopic dermatitis applications where topical calcineurin inhibitors compete with corticosteroid regimens. Prescriber education requirements limit penetration outside academic medical centers.
Transplantation commands the revenue base while autoimmune disorders expand most quickly as indication creep accelerates.
End User:
Customer type concentration determines channel strategy, with institutional procurement consolidating toward vertically integrated domestic manufacturers while homecare demands specialized patient support infrastructure.
- Hospitals:Transplant center networks and nephrology units with centralized pharmacy and therapeutics committees. Hospital system mergers in the United States and Germany have reduced independent transplant programs substantially.
- Specialty Pharmacies:Distribution nodes for chronic oral immunosuppression with adherence monitoring capabilities. Direct-to-clinic distribution models are bypassing wholesale intermediaries to capture margin.
- Clinics:Independent community nephrology practices losing procurement autonomy to regional health network consolidation.
- Homecare:Self-administered maintenance dosing requiring cold chain integrity and patient education support. Compliance infrastructure investments favor larger manufacturers with dedicated nursing networks.
Hospitals dominate procurement volume while specialty pharmacies climb the fastest as distribution centralizes.
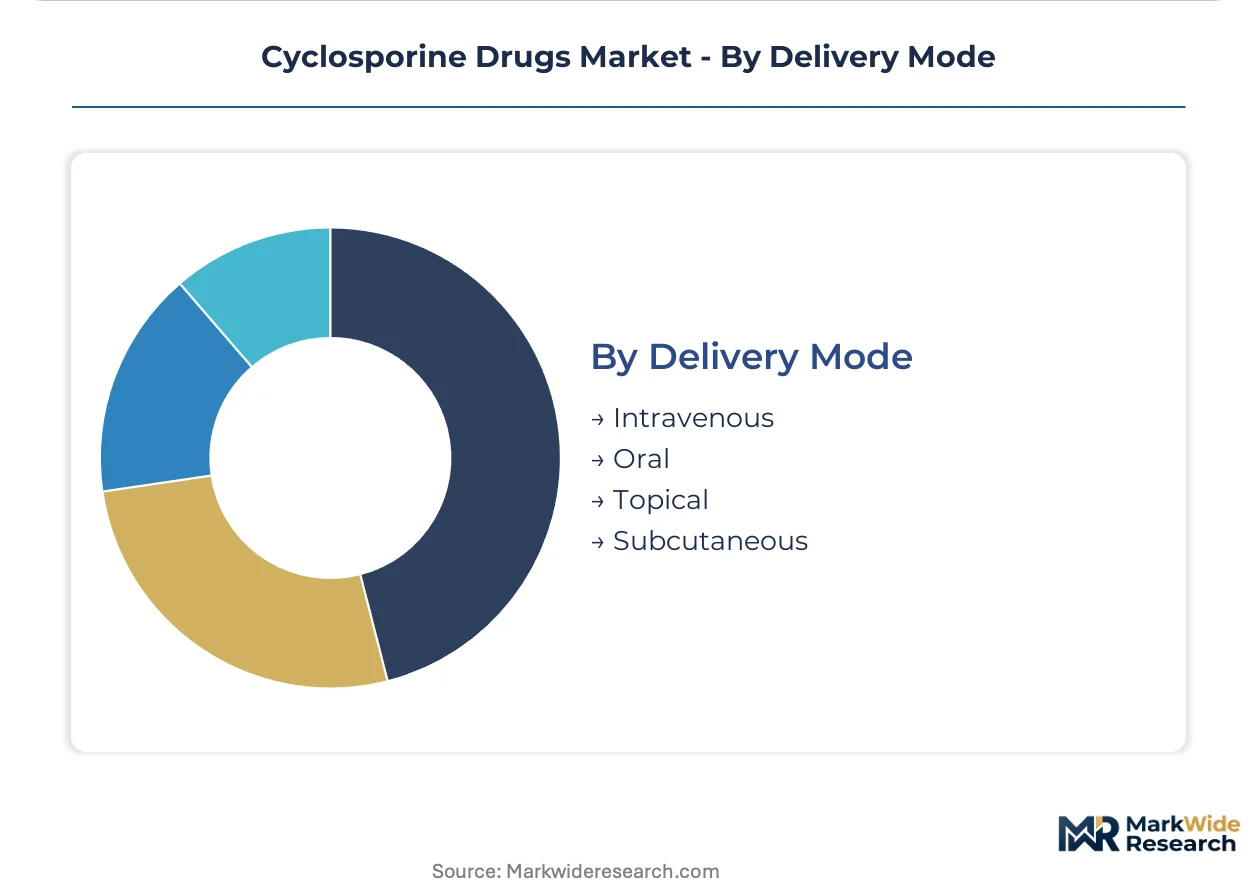
Delivery Mode:
Supply concentration among limited fermentation specialists creates vulnerability for finished-dose manufacturers dependent on external API sourcing.
- Oral:Chronic maintenance dosing with established pharmacokinetic profiles. Capsule and oral solution formulations depend on Tolypocladium inflatum fermentation capacity concentrated among API specialists.
- Intravenous:Perioperative and acute rejection management in controlled clinical settings. Compounding requirements limit site-of-care flexibility.
- Topical:Dermatology and ophthalmic surface applications with formulation-dependent bioavailability. Nanolipid carrier technology is displacing conventional oil-based vehicles.
- Subcutaneous:Limited current applications with potential for biosimilar immunosuppressant competition in development pipelines.
Oral delivery commands the volume base while topical routes show the steepest expansion trajectory as ophthalmic protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA immunosuppressant guidance and CDSCO regulatory convergence are accelerating procurement consolidation in transplant center networks across multiple jurisdictions. National reimbursement frameworks and fermentation capacity investments are reshaping competitive positioning in high-volume markets.
United States
Hospital system mergers have reduced independent transplant programs substantially, concentrating formulary authority within regional health networks. FDA bioequivalence requirements for narrow therapeutic index drugs protect incumbent suppliers from rapid generic substitution. The Medicare reimbursement structure anchors volume in nephrology maintenance protocols across the Southeast and Midwest corridor.
Germany
Transplant center consolidation into university hospital networks has centralized pharmacy and therapeutics committee authority. The country's national pharmaceutical regulator enforces stringent pharmacovigilance obligations for generic immunosuppressants that elevate compliance infrastructure requirements. Industrial concentration in Baden-Württemberg and Bavaria supports API-to-finished-dose manufacturing for regulated European export markets.
India
CDSCO streamlines indication additions for autoimmune disorder applications, expanding addressable patient populations beyond transplantation. The PLI scheme incentivizes domestic fermentation capacity expansion for Tolypocladium inflatum-derived APIs. Maharashtra and Gujarat host vertically integrated manufacturers supplying hospital pharmacy networks in tier-1 cities with institutional procurement concentration.
China
NMPA ICH Q3D convergence raises analytical chemistry requirements for elemental impurity specifications in API manufacturing. The national pharmaceutical regulator's tightening post-market surveillance obligations favor quality-certified regional players with dedicated quality control infrastructure. Yangtze River Delta pharmaceutical clusters are consolidating through acquisition to spread compliance costs across larger revenue bases.
Japan
PMDA guidance on calcineurin inhibitor switching protocols creates institutional friction against cyclosporine reintroduction in tacrolimus-dominated transplant centers. The country's national pharmaceutical regulator maintains narrow therapeutic index protocols that limit substitutability and protect quality-tier suppliers. Kanto region hospital networks concentrate procurement volume for chronic ocular surface disease management protocols.
Cyclosporine Drugs Market Competitive Environment
Player mix skews toward vertically integrated fermentation specialists and generic pharmaceutical conglomerates with transplant franchise heritage. Market structure exhibits tiered consolidation, with originator-grade suppliers commanding premium positioning in nephrology protocols while commoditized manufacturers compete on cost in emerging markets. Strategic archetypes include API-integrated finished-dose manufacturers, ophthalmic formulation specialists, and broad-line generic houses with immunosuppressant portfolios. Dominant competitive moves encompass backward integration into fermentation capacity and direct-to-clinic distribution model deployment.
Within the originator-grade tier, Novartis AG leverages its transplant franchise heritage to sustain premium positioning. Among India-based vertically integrated manufacturers, Sun Pharmaceutical Industries Ltd. anchors presence through API-to-finished-dose capabilities. Teva Pharmaceutical Industries Ltd. occupies a position exemplifying broad-line generic competition on cost while navigating complex abbreviated new drug application pathways.
| Leading Market Players |
|---|
| Novartis AG |
| Sun Pharmaceutical Industries Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| AbbVie Inc. |
| Santen Pharmaceutical Co., Ltd. |
| Apotex Inc. |
| Strides Pharma Science Limited |
| Sandoz International GmbH |
| Viatris Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between transplant center networks and vertically integrated manufacturers lock in both Tolypocladium inflatum fermentation capacity and price visibility across multi-year procurement cycles. These contracts anchor supply security for narrow therapeutic index immunosuppressants while insulating quality-tier suppliers from spot-market volatility in India's API export corridors.
Pricing Analysis
Certification level (FDA-grade versus CDSCO-registered) creates the primary spread between originator-grade and commoditized generic suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects USP-NF monograph compliance depth, with EMA immunosuppressant guidance enforcing narrow therapeutic index protocols that protect premium positioning. Cost compression in conventional oil-based ophthalmic solutions is intensifying because nanolipid carrier emulsions capture reimbursement premiums in dry eye syndrome protocols. Hospital pharmacy networks in India exhibit highest price sensitivity due to institutional procurement consolidation, while German transplant centers prioritize quality certification over unit cost.
Supply Chain Analysis
Port congestion on India-Europe pharmaceutical trade lanes elevates inbound logistics costs for finished-dose manufacturers dependent on API imports. Fermentation capacity concentrates in India, China, and Switzerland, with Tolypocladium inflatum-derived API production anchored in Maharashtra and Gujarat pharmaceutical clusters. Supply chain risk centers on single-source vulnerability for non-integrated manufacturers lacking captive fermentation assets. Distribution runs through hospital pharmacy networks and specialty pharmacy channels with direct-to-clinic models bypassing wholesale intermediaries in United States transplant center consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient adherence monitoring and cold chain logistics services expand faster than capsule and ophthalmic formulation hardware, creating recurring revenue layers that outperform product margins. This service-attach dynamic favors manufacturers with dedicated nursing networks and institutional pharmacy partnerships.
For Market Incumbents: Shield nephrology protocol positioning by deepening backward integration into Tolypocladium inflatum fermentation capacity in CDSCO-regulated zones. Certification investment in ICH Q3D elemental impurity testing infrastructure defends against NMPA-converging quality standards that threaten mid-tier suppliers. Channel control through direct-to-clinic distribution models captures margin from consolidating hospital pharmacy networks in the United States and Germany. For New Entrants and Emerging Players: Patient education service gaps in homecare maintenance dosing represent the most penetrable white-space target, as incumbents under-invest in compliance infrastructure outside tier-1 transplant centers. Rheumatology practice settings in India's tier-2 cities offer underpenetrated autoimmune disorder expansion with streamlined CDSCO indication pathways. Go-to-market angle: partner with regional health networks for formulary inclusion ahead of tacrolimus-dominated center consolidation. For Investors and Strategic Acquirers: Capital is best deployed toward quality-certified regional players with dedicated analytical chemistry infrastructure spread across larger revenue bases through acquisition consolidation. Long-term viability across the analysis window hinges on pharmacovigilance system integration capabilities that mid-tier manufacturers struggle to fund independently. Signal to watch: NMPA enforcement intensity on post-market surveillance obligations as inflection indicator for compliance-cost-driven consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive Tolypocladium inflatum API production insulates against supply vulnerability for non-integrated finished-dose manufacturers. |
| Direct-to-Clinic Distribution Deployment | Bypassing wholesale intermediaries in transplant center networks captures margin and strengthens prescriber relationships. |
| ICH Q3D Compliance Infrastructure Investment | Elevated analytical chemistry requirements harmonize quality standards across FDA, EMA, and NMPA jurisdictions. |
| Nanolipid Carrier Ophthalmic Formulation Development | Differentiated delivery platforms command reimbursement premiums above conventional oil-based dry eye solutions. |
| Pharmacovigilance System Integration | Post-market surveillance obligations for generic immunosuppressants require IT infrastructure that filters subscale competitors. |
Study Parameters
Desk research of FDA bioequivalence filings, EMA immunosuppressant guidance documents, and CDSCO regulatory circulars preceded structured interviews with transplant nephrologists, hospital pharmacy directors, formulary committee chairs, and API manufacturing executives. Secondary validation drew from USP-NF monograph updates, clinical trial registries, and institutional procurement databases. Bottom-up patient volume estimates and top-down revenue triangulation converged on segment-level figures.
Variance decomposition across therapy area, formulation type, and regional regulatory cluster shaped the analytical framework. Modeled dimensions encompassed transplantation versus autoimmune disorder application, capsule versus ophthalmic versus injectable delivery, and EMA-guided versus FDA-regulated versus NMPA-converging jurisdictions. CAGRs were derived from cohort-level patient flow analysis and reimbursement trajectory modeling, with inputs including tacrolimus-to-cyclosporine switching protocol prevalence and dry eye syndrome protocol adoption curves.
Forecasts assume regulatory continuity in FDA narrow therapeutic index protocols, EMA immunosuppressant guidance, and NMPA ICH Q3D convergence timelines; material policy shifts would require re-modeling. Specific risks that could revise projections include biologic immunosuppressant substitution acceleration in high-risk transplantation and unexpected fermentation capacity constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Meglitinide Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Proton Pump Inhibitors Market
Pharmaceuticals
Global Nausea Medicine Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
Oncology Adjuvants Market
Pharmaceuticals
Cannabinoid Drugs Market
Pharmaceuticals
Valsartan Market
Pharmaceuticals
Oral Vaccines Market
Pharmaceuticals
Systemic Lupus Erythematous SLE Drugs Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Mtor Inhibitors Market
Pharmaceuticals
France Diabetes Drugs Market