
 Aminophylline Market | 2026-2036
Aminophylline Market Size, Share, and Industry Trends Forecast 2026-2036
Aminophylline Market Outlook
Project finance for specialized respiratory API manufacturing is narrowing the competitive field to firms with capital access or asset-light partnerships. Pfizer Inc. leverages its integrated manufacturing footprint to control raw material costs for theophylline derivatives. Teva Pharmaceutical Industries Ltd. sustains broad generic portfolio breadth that spans multiple dosage forms and delivery modes. Hikma Pharmaceuticals PLC anchors its position through hospital contract penetration across North American and European markets.
Aminophylline is a compound of theophylline and ethylenediamine in a 2:1 ratio, formulated to enhance theophylline solubility for parenteral administration and acute bronchodilation in reversible airway obstruction. The injection segment dominates hospital emergency and intensive care settings where rapid onset is clinically required, while the tablet category serves maintenance therapy in outpatient COPD management. Among delivery modes, intravenous administration captures the highest per-unit pricing due to compounding complexity and sterility requirements, whereas oral formulations compete on volume scale in retail pharmacy channels.
The FDA enforces bioequivalence and current good manufacturing practice standards that determine which generic manufacturers gain market access, while the EMA's quality guidelines for theophylline salts shape formulation requirements across European markets. The EPA monitors ethylenediamine discharge from active pharmaceutical ingredient facilities, adding environmental compliance costs to production economics. Stakeholders must weigh manufacturing location decisions against evolving regulatory inspection intensity and the accelerating shift toward continuous process verification.
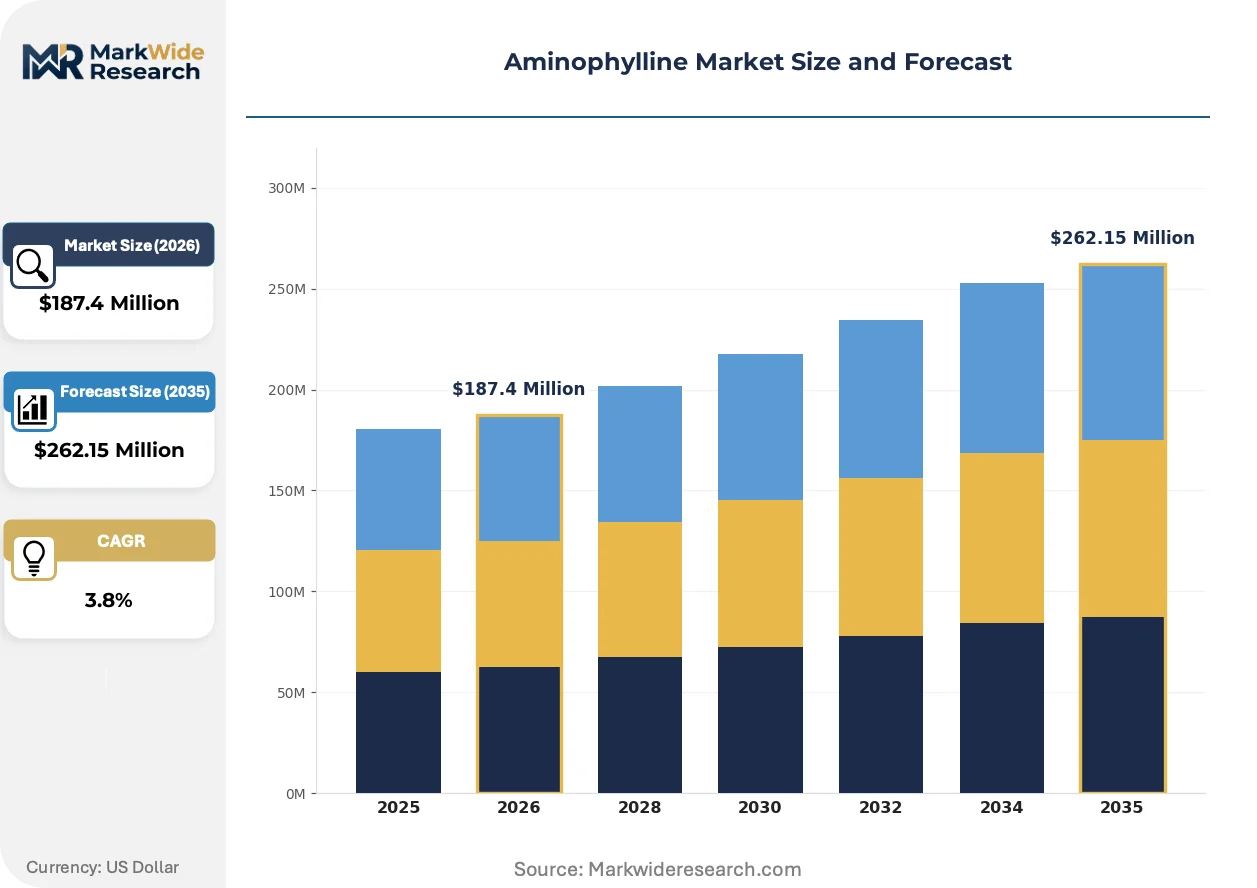
Market Dynamics
The aminophylline market is being reshaped by tightening bioequivalence enforcement for generic bronchodilators, which is compressing the supplier base to manufacturers capable of continuous process verification and sterile compounding at scale.
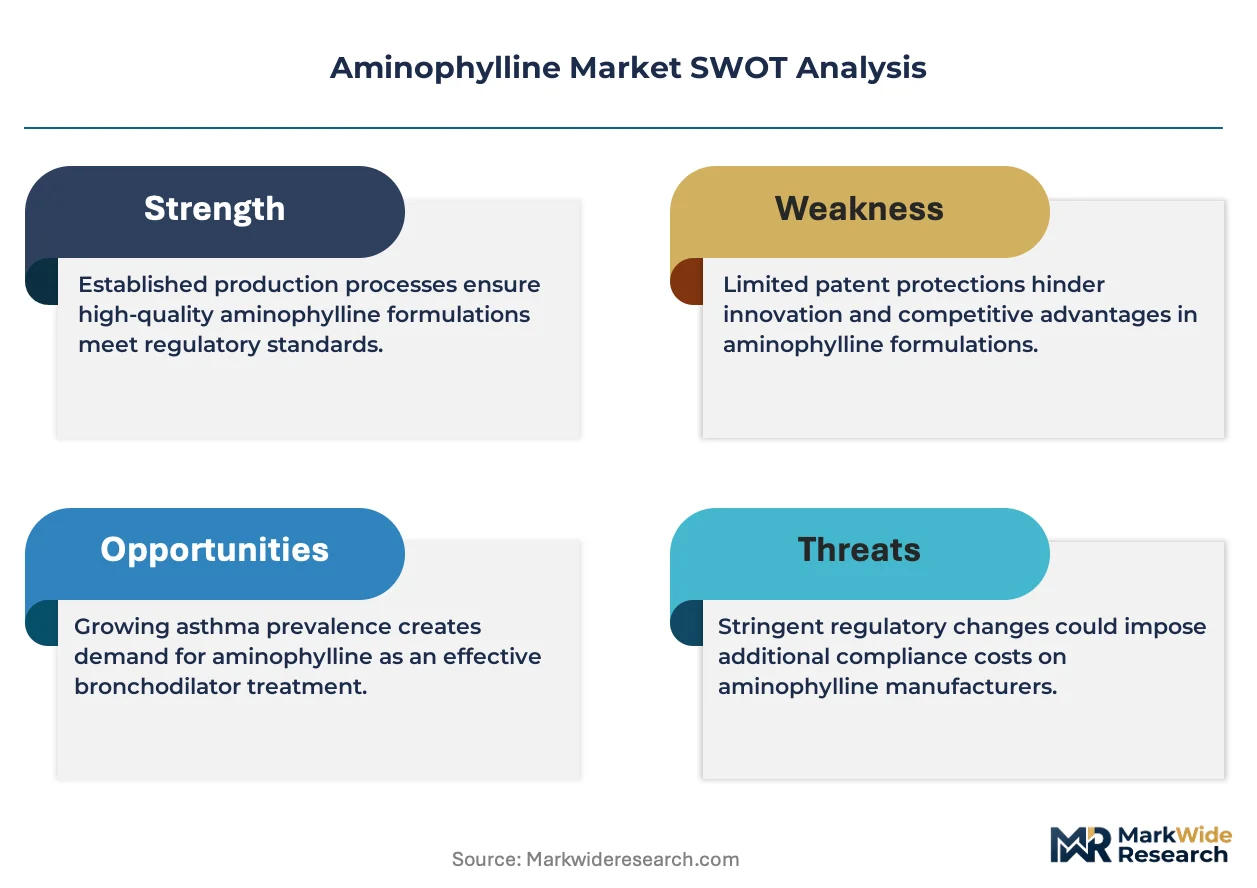
Growth Catalysts
- COPD Prevalence Trajectory:Rising chronic respiratory disease burden in aging populations is expanding hospital emergency department volumes requiring rapid-onset bronchodilation therapy.
- Medicare Reimbursement Stability:Sustained coverage for chronic respiratory maintenance therapy under Medicare Part B is anchoring outpatient prescription demand for oral formulations.
- Injectable Formulation Preference:Critical care protocols favoring intravenous aminophylline in acute airway obstruction are cementing hospital procurement commitments to parenteral supply.
Market Restraints
- Theophylline API Concentration:Active pharmaceutical ingredient production clusters in India and China, creating single-source dependency risks for Western formulators.
- Ethylenediamine Cost Volatility:This essential solubility-enhancing component faces petrochemical feedstock price swings that compress formulation margins unpredictably.
- Long-Acting Beta Agonist Substitution:Salmeterol and formoterol inhalers are displacing methylxanthine maintenance therapy in outpatient COPD management protocols.
Strategic Opportunities
- Continuous Manufacturing Adoption:FDA's quality-by-design framework is rewarding early adopters with abbreviated inspection cycles and expedited generic approvals.
- Home Infusion Channel Expansion:Post-acute care settings are creating demand for ambulatory pump-compatible aminophylline formulations outside traditional hospital boundaries.
- Pediatric Nebulization Formulations:Unmet need in childhood asthma exacerbations presents white space for age-appropriate dosing innovations.
Industry Challenges
- Sterile Compounding Workforce Scarcity:Aseptic processing technicians with parenteral API handling certification command premium wages and experience high turnover.
- Legacy Equipment Retrofit Costs:Batch-to-continuous process conversion demands capital deployment that mid-scale generic manufacturers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aminophylline Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injections, Capsules, Solutions Application: Respiratory Disorders, Asthma, COPD, Allergic Reactions End User: Hospitals, Clinics, Home Care, Pharmacies Delivery Mode: Oral, Intravenous, Inhalation, Sublingual |
| Companies Covered | Pfizer Inc., Teva Pharmaceutical Industries Ltd., Hikma Pharmaceuticals PLC, Sandoz AG, Amneal Pharmaceuticals LLC, Aurobindo Pharma, Cipla Ltd., Actiza Pharmaceutical, Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aminophylline Market Strategic Shifts
Process analytical technology is penetrating aminophylline manufacturing floors, replacing end-point testing with real-time quality verification that reduces batch failure rates and regulatory exposure.
Process analytical technology is digitizing quality control workflows across sterile injectable lines. Hospital purchasing departments are mandating electronic batch record access for vendor qualification. This transparency compression is disqualifying paper-dependent manufacturers from contract pharmacy networks.
EMA's revised guideline on theophylline salt bioequivalence is tightening dissolution profile requirements for generic approvals. European manufacturers are reformulating to narrower particle-size distributions. The tablet segment is absorbing the largest compliance burden as retesting protocols extend development timelines.
Hospital procurement departments are consolidating respiratory drug purchasing through integrated delivery networks. Group purchasing organizations are displacing individual pharmacy contracts with multi-year therapeutic-class agreements. The United States is exhibiting the most concentrated buyer power, with three national GPOs controlling the majority of acute-care aminophylline volume.
Aminophylline Market Segmentation
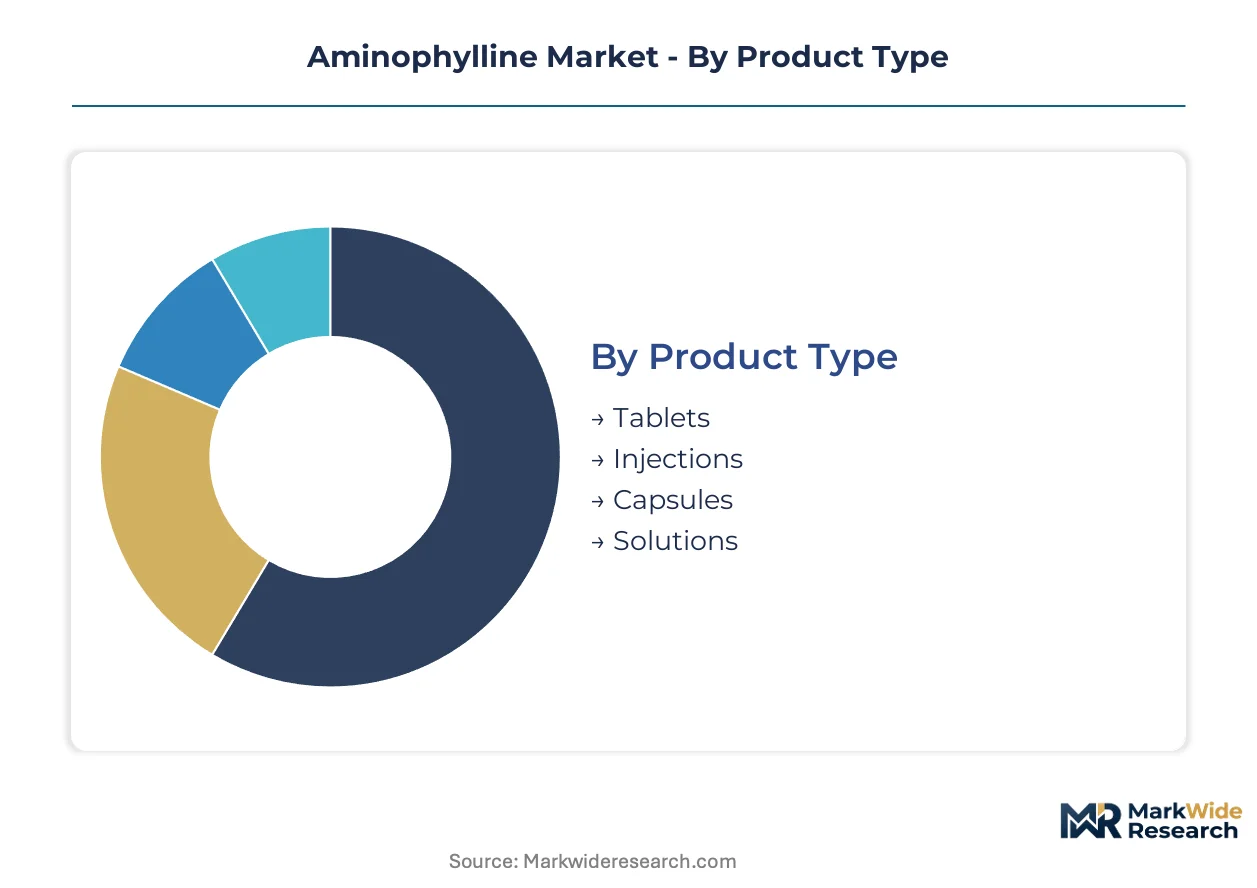
Segmentation in the aminophylline market reveals distinct procurement patterns across acute versus chronic care settings. Hospital buyers prioritize rapid-onset delivery modes, while retail channels optimize for outpatient compliance and cost containment.
Product Type:
Use-case spectrum spans emergency intervention through long-term maintenance, with formulation chemistry dictating clinical placement and reimbursement tier.
- Injections:Theophylline-ethylenediamine complex in sterile aqueous solution enables immediate bronchodilation in emergency departments and intensive care units. United States hospital systems anchor procurement volume through Medicare Part B reimbursement for acute respiratory failure protocols.
- Tablets:Compressed solid dosage forms deliver sustained theophylline release for outpatient COPD management. Retail pharmacy chains in the United States concentrate demand where Medicare Part D coverage stabilizes prescription refill patterns.
- Capsules:Gelatin-encased formulations offer dosing flexibility for titration protocols in specialty clinics.
- Solutions:Liquid preparations serve pediatric populations and patients with swallowing difficulties in home care environments.
Established volume favors injections; emerging adoption favors solutions.
Application:
Cost tier stratification separates acute rescue therapy from chronic maintenance, with reimbursement intensity varying across diagnostic codes.
- COPD:Chronic obstructive pulmonary disease represents the largest addressable population among methylxanthine-responsive conditions. United States Medicare spending on COPD maintenance therapy sustains tablet and capsule demand through Part D formularies.
- Asthma:Acute exacerbation protocols in emergency departments drive intravenous aminophylline utilization where beta-agonist resistance or contraindications exist. Pediatric asthma presents unmet formulation needs for weight-based dosing precision.
- Respiratory Disorders:Broader diagnostic category encompassing acute bronchospasm of varied etiology captures hospital admission volumes.
- Allergic Reactions:Anaphylaxis-associated bronchospasm represents niche utilization in emergency medicine settings.
Volume concentration rests with COPD; steepest expansion trajectory sits with asthma as pediatric protocols evolve.
End User:
Customer type determines packaging specifications, regulatory documentation requirements, and contract pricing structures.
- Hospitals:Acute care institutions procure sterile injectables through group purchasing organization contracts that mandate electronic batch record transparency. Three national GPOs in the United States control the majority of parenteral aminophylline volume.
- Home Care:Post-acute settings are generating demand for ambulatory pump-compatible formulations outside traditional facility boundaries. Medicare home health benefit expansions are shifting infusion therapy site-of-service.
- Clinics:Pulmonary specialty practices concentrate oral formulation prescribing for maintenance therapy titration.
- Pharmacies:Retail dispensing channels compete on generic substitution rates and 90-day supply compliance incentives.
Procurement scale favors hospitals; channel diversification favors home care.
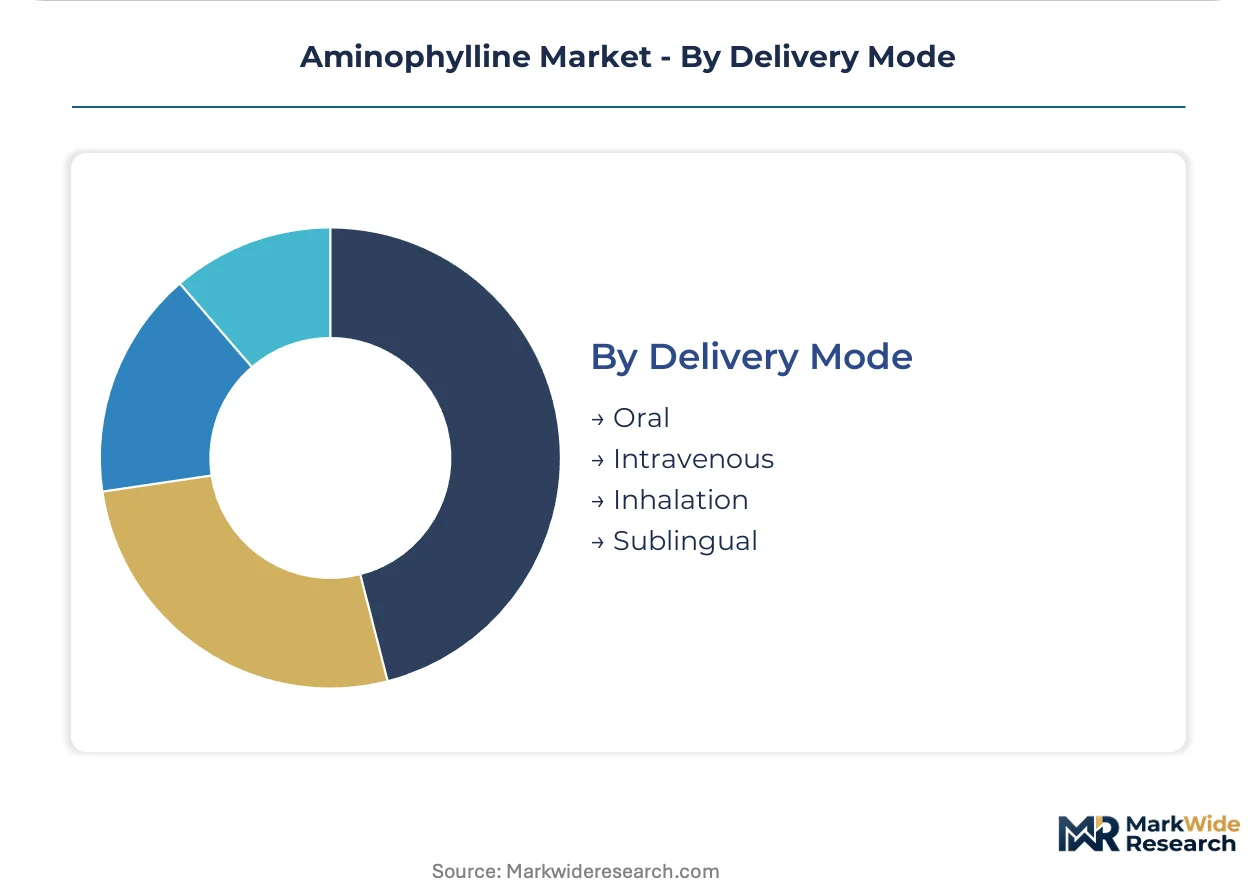
Delivery Mode:
Margin structure inverts across delivery modes, with sterile compounding complexity commanding premium pricing against commodity oral volumes.
- Intravenous:Direct vascular administration achieves rapid theophylline serum concentration in critical care. FDA bioequivalence requirements for generic parenteral theophylline salts restrict supplier qualification to manufacturers with validated aseptic processing capability.
- Oral:Gastrointestinal absorption governs maintenance therapy pharmacokinetics. EMA dissolution profile requirements for theophylline salts are narrowing acceptable particle-size distributions among European generic applicants.
- Inhalation:Pulmonary deposition targets local bronchodilation with reduced systemic exposure. Nebulization formulation development for pediatric populations remains underpenetrated.
- Sublingual:Buccal mucosa absorption offers rapid onset without vascular access requirements. Limited commercial availability constrains clinical adoption.
Revenue per unit favors intravenous; volume scale favors oral.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aminophylline trade flows reveal import dependency in Western markets against API export dominance from South Asian manufacturing clusters. The United States absorbs the largest finished-dosage import volumes while maintaining stringent FDA entry barriers. European markets balance domestic formulation capacity against active pharmaceutical ingredient sourcing from concentrated Asian suppliers.
United States
Medicare Part B reimbursement for acute respiratory failure protocols sustains hospital procurement of injectable formulations. FDA bioequivalence enforcement for generic parenteral theophylline salts restricts supplier qualification to manufacturers with validated aseptic processing. New Jersey and Pennsylvania host sterile compounding facilities serving integrated delivery networks.
Germany
EMA quality guidelines for theophylline salts shape dissolution profile requirements across European generic approvals. The country's federal drug regulator maintains inspection intensity for imported API batches. Frankfurt and Mannheim concentrate formulation science capabilities serving Central European distribution.
India
Domestic manufacturers supply theophylline API to Western formulators under contract manufacturing arrangements. CDSCO oversight of active pharmaceutical ingredient facilities aligns with FDA and EMA mutual recognition protocols. Hyderabad and Ahmedabad anchor chemical synthesis clusters for methylxanthine derivatives.
China
NMPA registration requirements for theophylline salts govern domestic market access and export certification. The country's dual carbon goals pressure ethylenediamine production economics through emissions compliance costs. Zhejiang and Jiangsu provinces concentrate API manufacturing with integrated petrochemical feedstock access.
United Kingdom
NHS procurement frameworks for respiratory therapies concentrate demand through national tender mechanisms. MHRA post-Brexit regulatory autonomy maintains alignment with EMA quality standards for theophylline formulations. London and Cambridge host clinical trial infrastructure supporting pediatric nebulization development.
Aminophylline Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in API and formulation chemistry. The aminophylline supplier base compresses toward manufacturers with simultaneous FDA approval, sterile processing validation, and hospital GPO contract access. Three archetypes dominate: integrated pharmaceutical conglomerates with captive API supply, mid-scale generic houses with therapeutic portfolio breadth, and regional injectable specialists with aseptic line concentration. Competitive moves center on backward integration into theophylline API production and multi-year hospital procurement contract capture.
Among integrated pharmaceutical conglomerates, Pfizer Inc. and Teva Pharmaceutical Industries Ltd. exemplify platform-scale positioning with manufacturing footprint control over raw material costs and dosage form diversity. Hikma Pharmaceuticals PLC occupies a position within the hospital contract penetration archetype, anchoring supply relationships across North American and European acute-care networks. These three entities represent the concentration of sterile compounding capability and regulatory qualification density that defines tier-one supply access.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Hikma Pharmaceuticals PLC |
| Sandoz AG |
| Amneal Pharmaceuticals LLC |
| Aurobindo Pharma |
| Cipla Ltd. |
| Actiza Pharmaceutical |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Hyderabad and Ahmedabad anchor theophylline API synthesis capacity that feeds Western formulation networks, with ethylenediamine cost volatility transmitting directly into parenteral pricing power. Contract manufacturers with validated aseptic lines command premium positioning against commodity tablet suppliers.
Pricing Analysis
Hospital procurement departments anchor contract-based long-term offtake structures that stabilize injectable aminophylline pricing against spot-market oral volatility. Three-tier pricing structure across FDA-validated sterile, standard generic, and economy non-sterile tiers separates buyers by certification burden and volume commitment. Pricing pressure stems from long-acting beta agonist substitution in outpatient COPD protocols, compressing maintenance therapy margins. Retail pharmacy chains exhibit highest price sensitivity through generic substitution mandates, while hospital GPOs trade volume scale for supply security.
Supply Chain Analysis
Contract manufacturing concentration rests with Indian and Chinese API houses serving Western formulators under FDA and EMA mutual recognition protocols. Theophylline feedstock and ethylenediamine solubilizer dependencies draw from petrochemical and methylxanthine extraction streams. Single-source vulnerability concentrates in South Asian theophylline API clusters exposed to environmental compliance disruptions. Distribution runs through hospital GPO networks in the United States and national tender mechanisms in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in the United States, where three national GPOs now control majority acute-care aminophylline procurement volume.
For Market Incumbents: Insulate sterile compounding margins through backward integration into theophylline API production, eliminating ethylenediamine cost pass-through exposure. Secure multi-year GPO contract renewals before FDA bioequivalence enforcement tightens supplier qualification further. Long-acting beta agonist substitution in outpatient protocols threatens maintenance therapy revenue streams. For New Entrants and Emerging Players: Pursue pediatric nebulization formulation white space where age-appropriate dosing protocols remain underpenetrated. Home infusion channel expansion offers the most penetrable entry vector as Medicare shifts site-of-service for post-acute respiratory therapy. Partner with ambulatory pump manufacturers for co-development of pump-compatible aminophylline solutions. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting mature respiratory portfolios to refocus on biologics. Mid-scale generic houses with therapeutic breadth but lacking sterile validation present consolidation opportunities over a 5-10 year window. Monitor FDA inspection intensity and warning letter issuance as inflection signals for supplier base compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Theophylline API | Captive supply of methylxanthine derivatives insulates margin from ethylenediamine petrochemical volatility. |
| Continuous Manufacturing Adoption | FDA quality-by-design framework rewards adopters with abbreviated inspection cycles and expedited approvals. |
| Home Infusion Formulation Development | Medicare home health benefit expansion shifts infusion therapy site-of-service outside hospital boundaries. |
| Pediatric Nebulization Pipeline Investment | Unmet need in childhood asthma exacerbations presents formulation innovation white space. |
| Hospital GPO Contract Consolidation | Three national GPOs control majority parenteral aminophylline volume in United States acute care. |
Study Parameters
Cross-validation between hospital procurement manager interviews and FDA bioequivalence filing data anchors the qualitative findings in documented regulatory outcomes. Primary fieldwork engaged sterile compounding technicians, formulary directors, regulatory affairs leads, and GPO contracts managers across North American and European markets. Secondary validation drew from FDA Orange Book entries, EMA quality guideline revisions, CMS Medicare Part B reimbursement schedules, and hospital procurement database extracts. Bottom-up demand modeling and top-down API trade flow analysis triangulate volume estimates.
Calibration against historical theophylline salt approval timelines and dissolution profile failure rates refines the projection framework across the analysis window. Segmentation dimensions include dosage form, delivery mode, application indication, end-user facility type, and regional regulatory cluster. CAGRs derive from patient volume epidemiology, reimbursement stability indices, and substitution elasticity modeling. Ethylenediamine feedstock price indices and FDA inspection frequency metrics inform industry-specific forecast sensitivity.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement policy, petrochemical pricing, or FDA enforcement intensity would shift the trajectory. Forecasts reflect assumptions around COPD prevalence stability and generic approval pathway continuity. Quarterly review of GPO contract award announcements, FDA warning letter issuance, and EMA guideline revision drafts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Cardiovascular Drugs Market
Pharmaceuticals
Medicinal Fungi Market
Pharmaceuticals
Prescription Stimulants Market
Pharmaceuticals
Global Hormonal Contraceptives Market
Pharmaceuticals
Acetylspiramycin Market
Pharmaceuticals
Global Travel Vaccines Market
Pharmaceuticals
Flumazenil Market
Pharmaceuticals
OTC Dry Eye Drops Market
Pharmaceuticals
North America Anticoccidial Drugs Market
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
Global Thyroid Cancer Drugs Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Antiplatelet Drugs Market