
 3D Printing Drug Market | 2026-2036
3D Printing Drug Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Drug Market Insights
The gap between premium patient-specific therapies and commodity solid-dose generics is restructuring competitive dynamics in additive pharmaceutical manufacturing. Aprecia Pharmaceuticals leverages its binder jetting platform to dominate the epilepsy and neurology specialty segment with FDA-approved printed formulations. Triastek sustains R&D intensity in China with its Melt Extrusion Deposition technology for complex geometric tablets. FabRx Ltd anchors European innovation through university-hospital partnerships that control clinical trial access for personalized polypill development.
3D printing drug production fabricates pharmaceutical dosage forms through layer-by-layer additive processes, typically achieving 50-500 micron resolution with programmable release kinetics for immediate, sustained, or pulsatile drug delivery. The technology serves industrial and commercial purposes by enabling geometric complexity impossible with conventional compression or molding, including internal lattice structures that modulate dissolution rates. Inkjet printing leads in clinical trial applications where micro-dose precision reduces API waste during early-phase testing. Fused Deposition Modeling competes in hospital and pharmacy settings for same-day custom medication production with thermoplastic polymer matrices. Patient-specific therapies command the fastest expansion as oncology and pediatric units demand weight-based dosing with polypill combinations.
FDA, EMA, and China's NMPA each maintain distinct quality frameworks that shape market access timelines and validation requirements for printed drug submissions. The FDA's emerging guidance on process analytical technology for continuous manufacturing directly impacts how 3D printing drug facilities validate layer-by-layer deposition as equivalent to batch release testing. Stakeholders must monitor which regulator first harmonizes pharmaceutical Current Good Manufacturing Practice with additive manufacturing-specific controls, as that jurisdiction will attract contract manufacturing investment and shape de facto global standards.
Market Dynamics
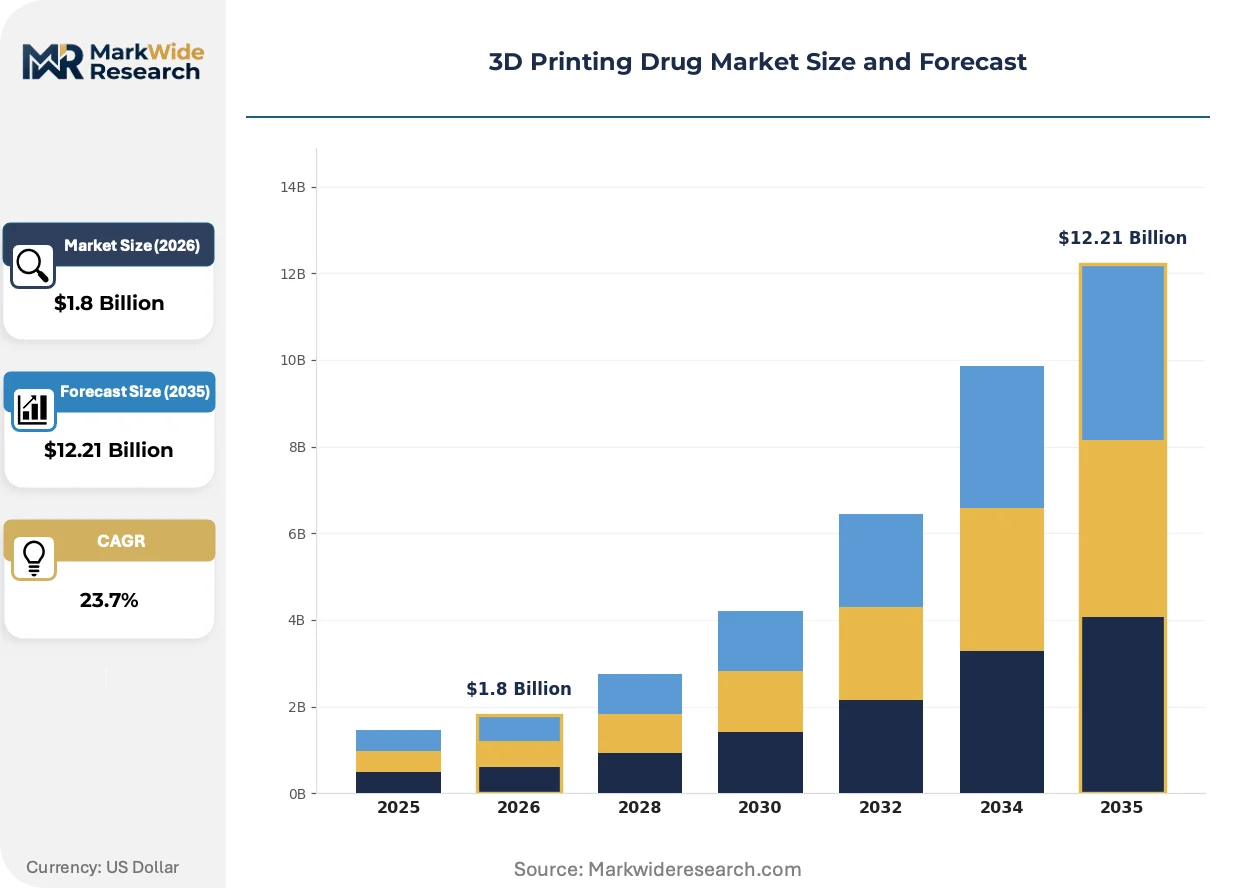
Patient-specific dosage fabrication is compressing the traditional pharmaceutical supply chain, collapsing the gap between centralized manufacturing and point-of-care dispensing as binder jetting and melt extrusion technologies mature for clinical deployment.
Growth Catalysts
- FDA Process Analytical Technology Guidance:The agency's framework for continuous manufacturing validation accelerates facility qualification timelines for layer-by-layer deposition systems in the United States.
- Oncology Unit Demand:Hospital cancer centers require weight-based dosing protocols that conventional batch production cannot economically fulfill, driving adoption of same-day tablet fabrication.
- Melt Extrusion Deposition:This thermal processing method enables complex geometric tablets with programmable release kinetics, expanding therapeutic applications beyond simple immediate-release formulations.
Market Restraints
- API Powder Supply Concentration:Specialty excipient and active pharmaceutical ingredient sourcing clusters in Germany and China, creating geographic vulnerability for Western contract manufacturers.
- EMA Batch Release Equivalence Requirements:European regulators demand extensive bioequivalence documentation for printed formulations versus traditional compressed tablets, extending approval timelines.
- Thermoplastic Polymer Cost Volatility:Medical-grade polycaprolactone and polyethylene oxide feedstock prices fluctuate with petrochemical markets, compressing margins for hospital-based production units.
Strategic Opportunities
- Pediatric Polypill Development:Combination therapies for children with multiple chronic conditions represent an underserved segment where geometric complexity delivers measurable adherence improvements.
- China's NMPA Innovation Pathway:The regulator's accelerated review track for breakthrough medical devices extends to novel manufacturing platforms, attracting foreign technology licensors.
- Hospital-Pharmacy Integration:Direct-to-patient dispensing from hospital-based additive manufacturing cells eliminates wholesale distribution layers for high-value specialty therapies.
Industry Challenges
- Formulation Scientist Talent Scarcity:The intersection of pharmaceutical chemistry and additive manufacturing engineering remains thinly staffed, constraining scale-up velocity for commercial facilities.
- CGMP-Additive Manufacturing Harmonization:Current Good Manufacturing Practice standards lack specific controls for layer-by-layer deposition validation, forcing sponsors to negotiate case-by-case with regulators.
- Intellectual Property Fragmentation:Patent thickets around print head designs, powder bed configurations, and release-kinetic algorithms complicate freedom-to-operate analyses for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Drug Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $12.21 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Tablets, Capsules, Drug Delivery Systems Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Inkjet Printing End User: Hospitals, Pharmacies, Research Institutions, Contract Manufacturing Organizations Application: Custom Medications, On-Demand Production, Clinical Trials, Patient-Specific Therapies |
| Companies Covered | Aprecia Pharmaceuticals, Triastek, FabRx Ltd, Merck KGaA, GlaxoSmithKline plc, Laxxon Medical, CurifyLabs, Multiply Labs, DOSER, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Drug Market Trends and Innovations
Digital formulation workflows are collapsing the traditional separation between drug development and manufacturing, enabling real-time adjustment of dissolution profiles based on individual patient pharmacokinetic data.
Binder jetting pharmaceutical platforms are decentralizing solid-dose production from centralized facilities to hospital pharmacies and specialized compounding centers. Clinical units in the United States and Germany are deploying these systems for same-day fabrication of epilepsy and neurology therapies. This geographic redistribution is compressing inventory carrying costs and enabling just-in-time production models that were structurally impossible under conventional compression manufacturing.
REACH regulatory updates in Europe are tightening scrutiny of polymer excipient safety profiles, forcing reformulation of thermoplastic matrices used in fused deposition modeling. Manufacturers must now submit comprehensive toxicity dossiers for novel binder systems before commercial deployment. Pediatric and geriatric dosage form developers face the steepest compliance burden, as these populations trigger enhanced safety thresholds under EMA guidance.
Hospital procurement committees are consolidating vendor relationships around integrated hardware-software-service bundles rather than discrete equipment purchases. This preference shift favors platform providers with validated formulation libraries and regulatory submission support over pure-play machinery suppliers. The concentration is most pronounced in North American academic medical centers, where capital committees prioritize total cost of ownership metrics over upfront equipment pricing.
3D Printing Drug Market Segmentation
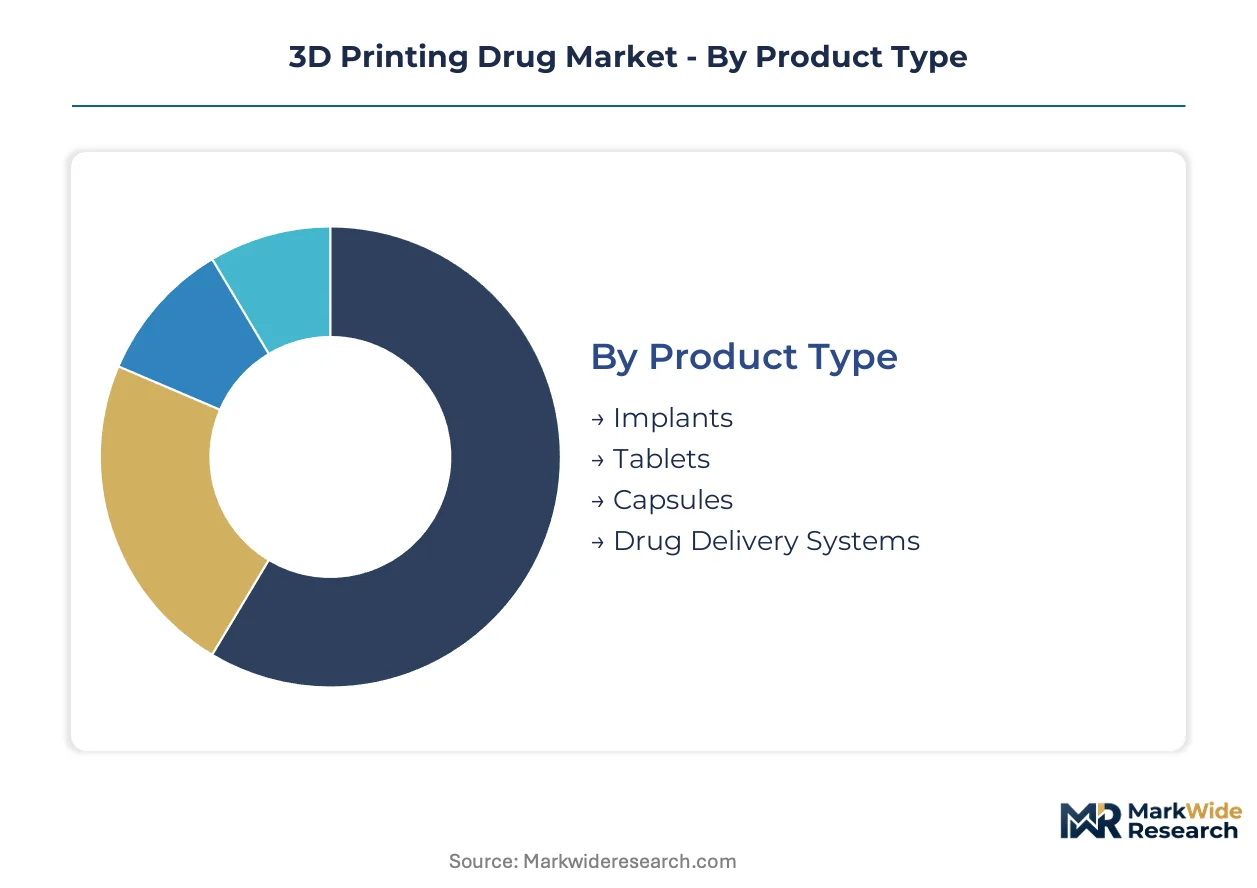
3D printing drug market segmentation reveals how fabrication complexity, regulatory pathways, and point-of-care deployment reshape competitive boundaries across product categories. Each dimension exposes distinct margin structures and capability requirements that determine vendor positioning.
Product Type:
The customization-to-standardization spectrum spans fully individualized implants at one extreme to mass-producible capsules at the other, with geometric complexity and regulatory burden determining production economics.
- Implants:Bioresorbable scaffolds and drug-eluding devices fabricated through selective laser sintering achieve patient-matched geometries for orthopedic and craniofacial applications. German university hospitals and Chinese orthopedic centers drive procurement, constrained by extended FDA and NMPA validation timelines for permanent implantable devices.
- Tablets:Layer-by-layer deposition enables internal lattice architectures that program dissolution kinetics for immediate, sustained, or pulsatile release. Hospital pharmacies in the United States and specialized compounding facilities in Germany concentrate demand for epilepsy and neurology therapies requiring same-day geometric customization.
- Capsules:Shell-based delivery systems leverage 3D printing for complex multi-compartment designs with sequential release profiles.
- Drug Delivery Systems:Transdermal patches, inhalation devices, and implantable pumps integrate printed drug reservoirs with mechanical components.
Most installed capacity flows through Tablets. Expansion is steepest in Implants.
Technology:
Cost tiering separates capital-intensive industrial platforms from deployable pharmacy-scale systems, with thermal processing methods commanding premium pricing against photopolymer alternatives.
- Fused Deposition Modeling:Thermoplastic extrusion systems operate at pharmacy-scale with medical-grade polycaprolactone and polyethylene oxide matrices, enabling same-day production for weight-based pediatric dosing. Hospital-based installations in the United States face margin pressure from petrochemical feedstock volatility.
- Inkjet Printing:Piezoelectric droplet deposition achieves micro-dose precision for early-phase clinical trials, slashing API waste during pharmacokinetic studies. Contract research organizations in Germany and China concentrate adoption where dose-escalation protocols demand rapid formulation iteration.
- Stereolithography:Photopolymer vat polymerization produces high-resolution structures for complex-release geometries, limited by resin biocompatibility requirements.
- Selective Laser Sintering:Powder-bed fusion fabricates metallic and polymeric implants with isotropic mechanical properties, requiring specialized facility infrastructure.
Most installed capacity flows through Fused Deposition Modeling. Inkjet Printing gains share fastest in clinical trial applications.
End User:
Customer type determines whether production occurs under centralized CGMP compliance or decentralized pharmacy compounding exemptions, with radically different validation and liability frameworks.
- Hospitals:Academic medical centers and cancer units deploy binder jetting and melt extrusion systems for point-of-care fabrication of weight-based oncology therapies and pediatric polypills. United States hospital procurement committees prioritize integrated hardware-software-service bundles with validated formulation libraries.
- Pharmacies:Specialized compounding pharmacies leverage regulatory exemptions for patient-specific medications, though REACH updates in Europe tighten polymer excipient safety documentation requirements.
- Research Institutions:University-hospital partnerships in Germany and China control clinical trial access for personalized polypill development, bridging formulation science and patient recruitment.
- Contract Manufacturing Organizations:Dedicated additive pharmaceutical facilities negotiate case-by-case CGMP validation with FDA, EMA, and NMPA as harmonized standards remain absent.
Most installed capacity flows through Hospitals. Research Institutions show the steepest expansion trajectory as university-hospital partnerships consolidate.
Application:
Maturity differentiation separates established clinical trial and on-demand production workflows from emerging patient-specific therapy protocols still navigating reimbursement and regulatory ambiguity.
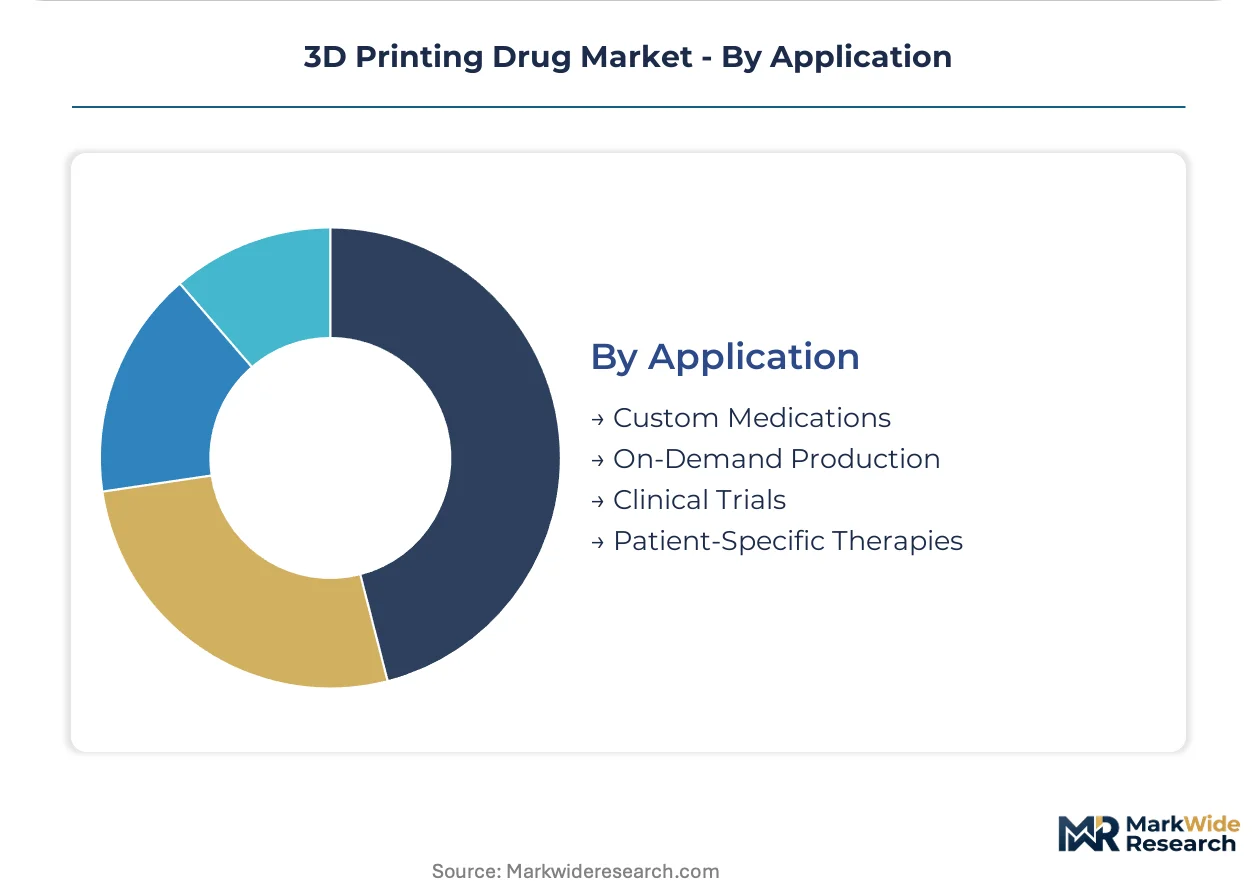
- Patient-Specific Therapies:Pharmacogenomic-informed dosing with polypill combinations for oncology and pediatric patients commands premium pricing, contingent on real-time dissolution profile adjustment based on individual pharmacokinetic data. United States cancer centers and German pediatric units concentrate early adoption.
- Clinical Trials:Micro-dose precision and rapid formulation iteration reduce API consumption and accelerate dose-escalation timelines for early-phase studies.
- Custom Medications:Weight-based dosing and allergen-free formulations address individual patient requirements outside standard commercial availability.
- On-Demand Production:Just-in-time fabrication eliminates inventory carrying costs for low-volume specialty therapies, compressing supply chain layers from centralized manufacturing to point-of-care dispensing.
Most installed capacity flows through Clinical Trials. Patient-Specific Therapies are climbing the fastest as oncology units demand geometric complexity for adherence improvement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation scientists and additive manufacturing engineers concentrate in pharmaceutical clusters across the United States, Germany, China, the United Kingdom, and Japan, anchoring regional capability development.
United States
Academic medical centers in Boston and the Research Triangle drive hospital-based point-of-care fabrication demand for weight-based oncology therapies. FDA process analytical technology guidance for continuous manufacturing accelerates facility qualification timelines for layer-by-layer deposition systems. The Philadelphia-Camden corridor hosts binder jetting specialists serving epilepsy and neurology specialty segments with FDA-approved printed formulations.
Germany
University-hospital partnerships in Munich and Heidelberg control clinical trial access for personalized polypill development, bridging formulation science and patient recruitment. EMA batch release equivalence requirements demand extensive bioequivalence documentation for printed formulations versus traditional compressed tablets. The Rhine-Main region concentrates specialty excipient sourcing clusters, creating geographic leverage for Western contract manufacturers.
China
NMPA's accelerated review track for breakthrough medical devices extends to novel manufacturing platforms, attracting foreign technology licensors to Shanghai and Suzhou. Melt extrusion deposition R&D intensity sustains complex geometric tablet development for programmable release kinetics. The Yangtze River Delta builds dedicated pharmaceutical additive manufacturing clusters with dual carbon goals influencing facility energy sourcing.
United Kingdom
London-Oxford-Cambridge corridor institutions anchor European innovation through university-hospital partnerships controlling pediatric polypill clinical trial access. MHRA alignment with EMA quality frameworks shapes validation requirements for printed drug submissions. Manchester and Birmingham specialized compounding facilities deploy pharmacy-scale thermoplastic extrusion systems for same-day custom medication production.
Japan
PMDA quality frameworks for novel manufacturing platforms create structured pathways for printed pharmaceutical commercialization in Tokyo-Osaka corridor facilities. METI industrial policy supports pharmaceutical additive manufacturing integration into existing precision machinery supply chains. Kansai region academic medical centers pilot patient-specific dosage fabrication for geriatric polypill adherence improvement.
3D Printing Drug Market Competitive Landscape
Top-tier vendors anchor platform provision with integrated hardware-software-service bundles, while mid-tier specialists concentrate on niche therapeutic applications or regional regulatory navigation. The competitive structure stratifies across three archetypes: pharmaceutical incumbents leveraging manufacturing scale, pure-play additive technology developers, and university spin-outs accessing clinical trial infrastructure. Dominant competitive moves include strategic partnerships between machinery suppliers and formulation houses, plus technology licensing agreements that transfer binder jetting and melt extrusion IP across geographic markets.
Among platform-focused developers, Aprecia Pharmaceuticals and Triastek exemplify divergent geographic and technological positioning. Aprecia Pharmaceuticals, a U.S.-based entity, occupies the binder jetting epilepsy-neurology specialty segment with FDA-validated commercial formulations. Triastek, a China-based developer, represents melt extrusion deposition capability for complex geometric tablets with programmable release profiles. FabRx Ltd, a UK-based limited company, anchors European positioning through university-hospital partnership structures that control clinical trial access pathways.
| Leading Market Players |
|---|
| Aprecia Pharmaceuticals |
| Triastek |
| FabRx Ltd |
| Merck KGaA |
| GlaxoSmithKline plc |
| Laxxon Medical |
| CurifyLabs |
| Multiply Labs |
| DOSER |
| Others |
Pricing and Supply Chain Analysis
Captive integration into specialty excipient sourcing anchors both supply security and pricing power for Western contract manufacturers facing petrochemical feedstock volatility. Hospital procurement committees in the United States and Germany increasingly demand bundled hardware-software-service packages that collapse discrete equipment margins into recurring service revenue streams.
Pricing Analysis
Bundled service contracts dominate hospital and pharmacy procurement, unbundled equipment sales concentrate in research institution pilot deployments. Pricing stratifies across FDA-validated commercial formulations, CE-marked clinical systems, and pharmacy-scale compounding units with excipient safety documentation tiers. Cost compression in thermoplastic polymer feedstocks intensifies because medical-grade polycaprolactone prices fluctuate with crude oil derivatives. Academic medical centers show least price sensitivity due to grant-funded capital budgets, while independent compounding pharmacies face acute margin pressure from polymer cost volatility.
Supply Chain Analysis
Certification gating through FDA process analytical technology validation, EMA batch release equivalence requirements, and NMPA innovation pathway documentation concentrates qualified supplier networks. Specialty API and excipient sourcing clusters in Germany and China, with thermoplastic polymer production anchored in petrochemical corridors of the United States and Belgium. Single-source vulnerability runs through REACH-regulated polymer safety dossier approvals for novel binder systems. Distribution feeds from centralized additive manufacturing facilities to hospital-based point-of-care cells, eliminating wholesale pharmaceutical distribution layers for patient-specific therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on pharmaceutical-grade polymer cost-down curves and the shift from equipment sales toward high-margin formulation licensing revenue. Hospital procurement consolidation favors platform providers with validated therapeutic libraries over pure-play machinery vendors.
For Market Incumbents: Extend regulatory submission support capabilities to capture hospital-pharmacy integration demand, while deepening captive supply of medical-grade polycaprolactone to defend against polymer price volatility. Binder jetting platform holders should consolidate formulation scientist talent through university-hospital partnership structures before melt extrusion competitors scale comparable clinical trial access. For New Entrants and Emerging Players: Launch via pharmacy-scale fused deposition modeling systems targeting pediatric polypill compounding exemptions in European specialized pharmacies, where REACH compliance burdens deter incumbent expansion. White-space concentration in weight-based oncology dosing protocols at mid-tier cancer centers offers fastest payback for melt extrusion deposition platforms with programmable release kinetics. For Investors and Strategic Acquirers: Roll-up economics work for university spin-outs with locked clinical trial infrastructure because hospital procurement committees prioritize validated formulation libraries over de novo regulatory pathways. Five-to-ten year viability hinges on which regulator first harmonizes CGMP with additive manufacturing-specific controls. Watch FDA-EMA-NMPA alignment timelines as the inflection signal for contract manufacturing investment flows.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Submission Support Expansion | FDA process analytical technology guidance accelerates facility qualification for binder jetting platforms. |
| University-Hospital Partnership Formation | Heidelberg and Munich institutions control pediatric polypill clinical trial recruitment pipelines. |
| Specialty Excipient Backward Integration | Rhine-Main sourcing clusters reduce geographic vulnerability for Western contract manufacturers. |
| Pharmacy-Scale System Deployment | Manchester and Birmingham compounding facilities bypass centralized CGMP compliance requirements. |
| Formulation Scientist Talent Acquisition | Scarce pharmaceutical chemistry-additive manufacturing intersection constrains commercial scale-up velocity. |
Research Methodology
Multiple input streams — primary interviews with formulation scientists, regulatory affairs leads, hospital procurement managers, and payer access specialists; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases; plus customs data on pharmaceutical-grade polymer trade flows — were reconciled through bottom-up installation base modeling and top-down market sizing triangulation.
Data-stream reconciliation across technology adoption curves, therapeutic application penetration rates, and regional regulatory cluster maturity shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include dosage form complexity, end-user compliance framework, fabrication technology thermal processing method, and regional regulator harmonization status. CAGRs derived from technology diffusion S-curves applied to hospital capital expenditure cycles and pharmacy compounding volume trends, with API waste reduction metrics and patient adherence improvement data informing premium pricing assumptions for patient-specific therapies.
Several conditions sit outside the modeled scope, including hypothetical NMPA policy reversals on breakthrough device pathways, EMA REACH regulatory updates affecting novel polymer excipient classifications, and FDA guidance revisions on continuous manufacturing validation standards. Forecasts reflect assumptions about polymer feedstock price stability and hospital capital budget continuity. A model refresh is warranted upon material change in regulator harmonization timelines or petrochemical derivative cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Veterinary Insulin Drugs Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Middle East and Africa Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Gemcitabine HCL Market
Pharmaceuticals
Global Antiemetic Drugs Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
Global Interstitial Cystitis Drugs Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Capecitabine Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Sinus Therapeutic Drugs Market
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
Live Attenuated Vaccines Market
Pharmaceuticals
Topical Acne Medication Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market