
 Pregnancy Point of Care Testing Market | 2026-2036
Pregnancy Point of Care Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Pregnancy Point of Care Testing Market Analytics
Capital-intensity divergence between integrated diagnostic manufacturers and kit assemblers is reorganizing competitive tiers in pregnancy point of care testing. Abbott Laboratories leverages its lateral flow manufacturing infrastructure across multiple diagnostic categories to sustain cost advantages in high-volume urine test production. Swiss Precision Diagnostics GmbH anchors its position through proprietary antibody sourcing relationships that limit supplier switching for European and North American pharmacy chains.
Pregnancy point of care testing encompasses rapid diagnostic devices that detect human chorionic gonadotropin hormone in urine or blood specimens at sensitivity thresholds typically ranging from 20 to 25 mIU/mL, delivering qualitative or semi-quantitative results within three to five minutes without laboratory infrastructure. These devices serve clinical settings requiring immediate gestational status confirmation to guide medication decisions, imaging protocols, and care pathway assignments. Urine test kits dominate volume flows through retail and clinical channels due to non-invasive collection and minimal operator training requirements, while digital test devices command premium positioning through Bluetooth-connected result logging and cycle-tracking integration that appeals to health system remote monitoring programs. Lateral flow assays retain manufacturing scale advantages from decades of process optimization, though microfluidics platforms are gaining traction in hospital emergency departments where multiplexed hCG quantification supports ectopic pregnancy risk stratification.
The FDA's 510(k) clearance framework for over-the-counter diagnostics and the Clinical Laboratory Improvement Amendments govern product performance claims and waived-test categorization that determines whether devices qualify for use outside certified laboratories. The European Union's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for self-testing pregnancy devices, creating compliance cost barriers for smaller manufacturers seeking CE marking. Stakeholders must monitor evolving classification boundaries between wellness apps and regulated diagnostic hardware as smartphone-integrated testing platforms blur traditional regulatory jurisdictions.
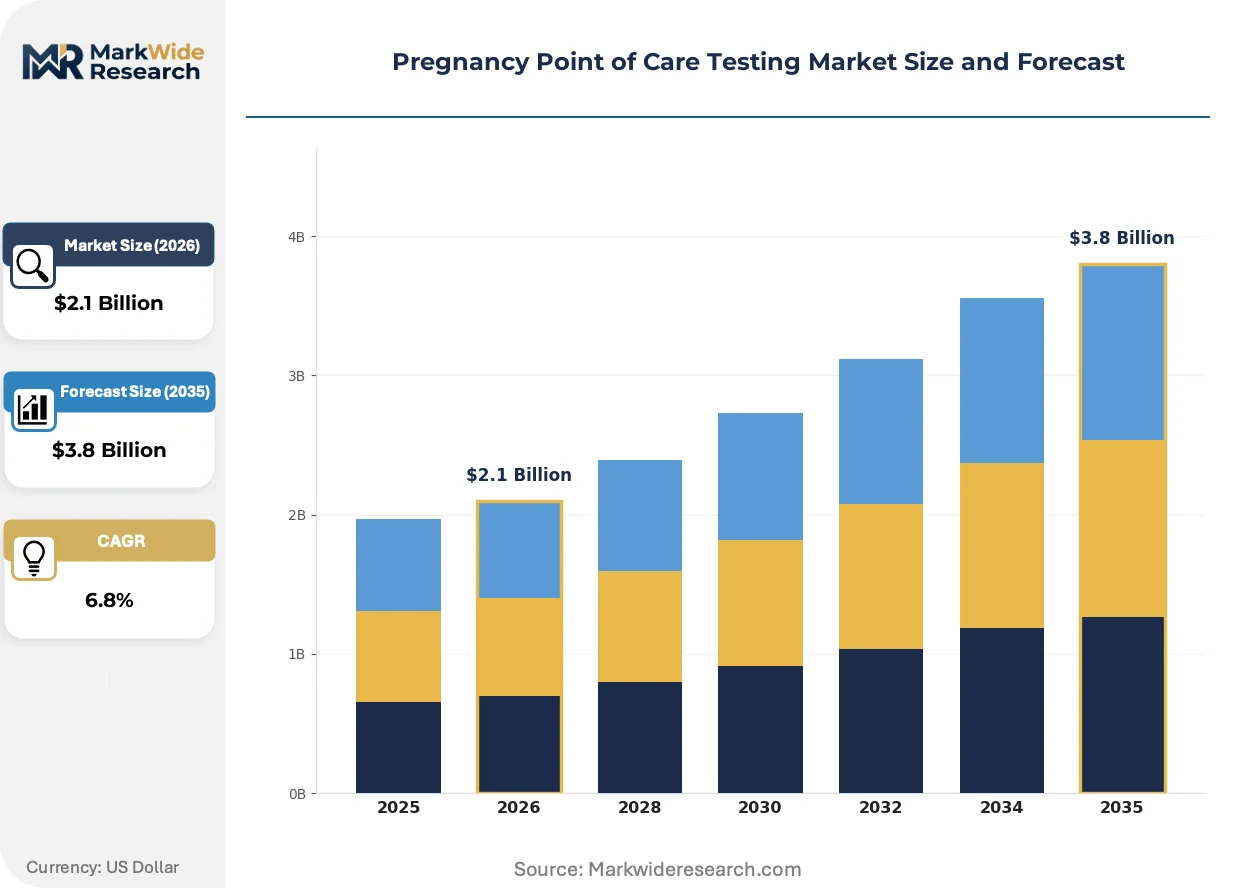
Market Dynamics
Retail pharmacy chains are consolidating procurement power and embedding pregnancy verification into broader reproductive health service workflows, compressing margins for standalone test manufacturers while rewarding suppliers with integrated digital health platforms.
Growth Catalysts
- CLIA-waived test expansion:The FDA's streamlined 510(k) clearance for over-the-counter diagnostics accelerates time-to-market for lateral flow manufacturers targeting urgent care networks.
- Telehealth integration:Remote patient monitoring programs in United States health systems are incorporating Bluetooth-connected result logging into chronic care pathways.
- Antibody sourcing partnerships:Proprietary bioreagent supply relationships with European diagnostic material suppliers limit competitor switching costs for established kit assemblers.
Market Restraints
- IVDR compliance burden:The European Union's In Vitro Diagnostic Regulation imposes clinical evidence requirements that create cost barriers for smaller manufacturers seeking CE marking.
- Raw material concentration:Nitrocellulose membrane supply concentrates among Asian chemical processors, exposing production schedules to regional logistics disruptions.
- Smartphone app substitution:Unregulated cycle-tracking applications capture consumer attention before clinical confirmation, delaying formal testing adoption.
Strategic Opportunities
- Microfluidics convergence:Hospital emergency departments in the United States are adopting multiplexed hCG quantification platforms for ectopic pregnancy risk stratification.
- Private-label pharmacy expansion:CVS Health and Walgreens Boots Alliance are expanding captive-brand testing portfolios, opening supplier slots for contract manufacturers with lateral flow expertise.
- Indian retail pharmacy modernization:Organized pharmacy chains in Mumbai and Bangalore are introducing point-of-care diagnostic corners with immediate confirmation services.
Industry Challenges
- Regulatory boundary ambiguity:Smartphone-integrated testing platforms blur classification between wellness apps and FDA-regulated diagnostic hardware, creating pre-market consultation delays.
- Multiplex assay development timelines:Quantitative hCG-progesterone combination tests require extended clinical validation studies that strain R&D budgets for mid-tier manufacturers.
- Legacy LIS integration:Digital test devices face interoperability friction with hospital laboratory information systems that lack standardized Bluetooth result ingestion protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pregnancy Point of Care Testing Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urine Test Kits, Blood Test Kits, Digital Test Devices, Others Application: Home Testing, Hospital Testing, Clinic Testing, Emergency Care Technology: Lateral Flow Assays, Enzyme-linked Immunosorbent Assays, Microfluidics, Others End User: Hospitals, Clinics, Pharmacies, At-home Users |
| Companies Covered | Abbott Laboratories, Quidel Corporation, EKF Diagnostics Holdings plc, Swiss Precision Diagnostics GmbH, Prestige Brands Holdings, BioMérieux SA, Piramal Enterprises, Church & Dwight, BIOSYNEX SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pregnancy Point of Care Testing Market Evolving Landscape
Device connectivity and regulatory recalibration are converging to redefine how pregnancy confirmation interfaces with broader reproductive health data ecosystems.
Microfluidics-based quantitative hCG platforms are displacing traditional lateral flow assays in United States hospital emergency departments where rapid risk stratification for ectopic pregnancy guides imaging decisions. These cartridge-based systems deliver numerical results within eight minutes, enabling triage protocols that previously required laboratory send-outs. The technology is displacing qualitative urine tests from high-acuity clinical workflows and compressing the addressable market for basic kit manufacturers.
The FDA's ongoing refinement of over-the-counter diagnostic clearance pathways is compressing pre-market review timelines for lateral flow manufacturers with established predicate devices. This regulatory momentum rewards companies with existing 510(k) portfolios while raising entry barriers for novel platform technologies lacking comparison studies. Digital test devices with smartphone integration face heightened scrutiny as the agency clarifies software-as-medical-device boundaries.
Pharmacy-based health service bundling is reshaping how consumers access pregnancy confirmation, with minute-clinic networks capturing volume that previously flowed to obstetric practices. United States retail chains are training pharmacists to interpret results and provide immediate counseling, converting a product transaction into a service encounter. This channel evolution concentrates procurement power among three national pharmacy banners and marginalizes independent drugstore distributors.
Pregnancy Point of Care Testing Market Segmentation
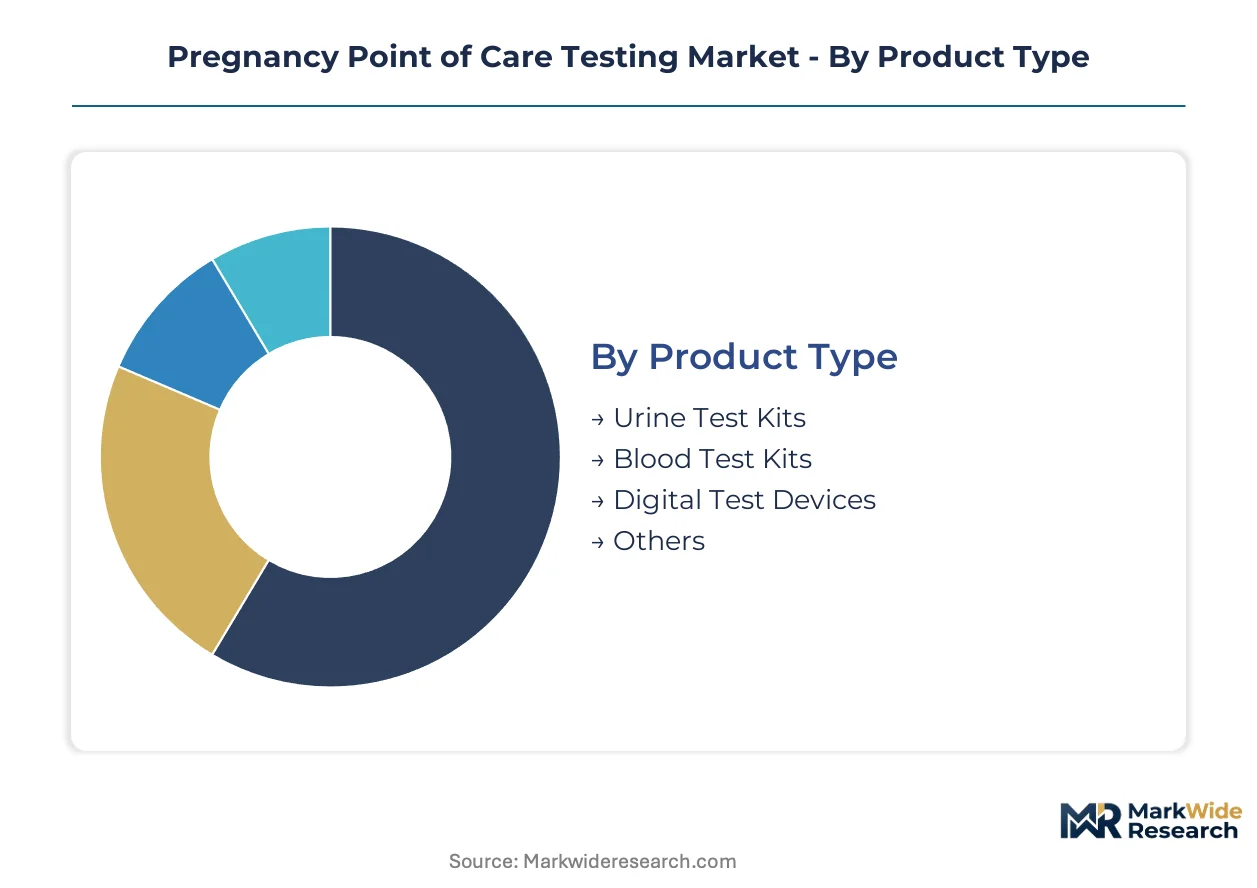
Pregnancy point of care testing segments diverge sharply by clinical setting requirements and supply chain complexity. Manufacturers must calibrate sensitivity specifications, connectivity features, and regulatory pathways differently across each category to capture volume in fragmented procurement environments.
Product Type:
Urine test kits dominate domestic pharmacy and retail channels across the United States, Germany, and Japan, while blood test kits and digital devices concentrate in export-led hospital supply contracts.
- Urine Test Kits:Lateral flow cassettes and dipsticks detect hCG at 20-25 mIU/mL sensitivity using monoclonal antibody conjugates on nitrocellulose membranes. Demand concentrates in United States retail pharmacy chains where CVS Health and Walgreens Boots Alliance bundle confirmation services with reproductive health counseling.
- Digital Test Devices:Bluetooth-enabled readers with LCD displays and smartphone connectivity capture cycle data for health system remote monitoring programs. Export-led sales drive revenue through European hospital group purchasing organizations seeking LIS-integrated result logging.
- Blood Test Kits:Capillary collection devices with plasma separation membranes serve clinic workflows requiring quantitative hCG thresholds.
- Others:Saliva-based and multiplexed formats occupy niche wellness channel positions.
Urine test kits hold the largest share; momentum sits with digital test devices.
Application:
Cost tier stratification separates premium hospital testing from economy home testing segments, with emergency care commanding the highest per-test pricing.
- Home Testing:Over-the-counter retail formats emphasize privacy, simplicity, and immediate result interpretation without clinical supervision. Volume concentrates in United States mass merchandisers and Japanese drugstore chains where consumers prioritize convenience over quantitative precision.
- Emergency Care:Rapid triage protocols in United States hospital emergency departments demand quantitative hCG with progesterone multiplexing for ectopic pregnancy risk stratification. Reimbursement rates support premium cartridge pricing for microfluidics platforms.
- Hospital Testing:Laboratory-send-out alternatives in obstetrics wards require waived-test certification and operator training documentation.
- Clinic Testing:Minute-clinic networks and urgent care centers balance speed with medico-legal result documentation.
Home testing generates the highest unit volumes; emergency care delivers the steepest expansion trajectory.
Technology:
Manufacturing maturity and R&D intensity divide segments, with lateral flow assays leveraging decades of process optimization against microfluidics platforms requiring fresh clinical validation investments.
- Lateral Flow Assays:Nitrocellulose membrane strips with colloidal gold or fluorescent labels dominate production scale economics. Supply concentrates in Asian membrane processing centers serving contract manufacturers across India, China, and Southeast Asia.
- Microfluidics:Cartridge-based systems with integrated reagent storage and automated fluidic control enable multiplexed quantification in eight-minute workflows. Adoption concentrates in United States academic medical centers and German hospital networks with established point-of-care coordination infrastructure.
- Enzyme-linked Immunosorbent Assays:Laboratory-grade specificity supports reference standard applications in fertility clinics.
- Others:Electrochemical biosensors and smartphone-integrated optics remain pre-commercial.
Lateral flow assays anchor current revenue; microfluidics is climbing the fastest.
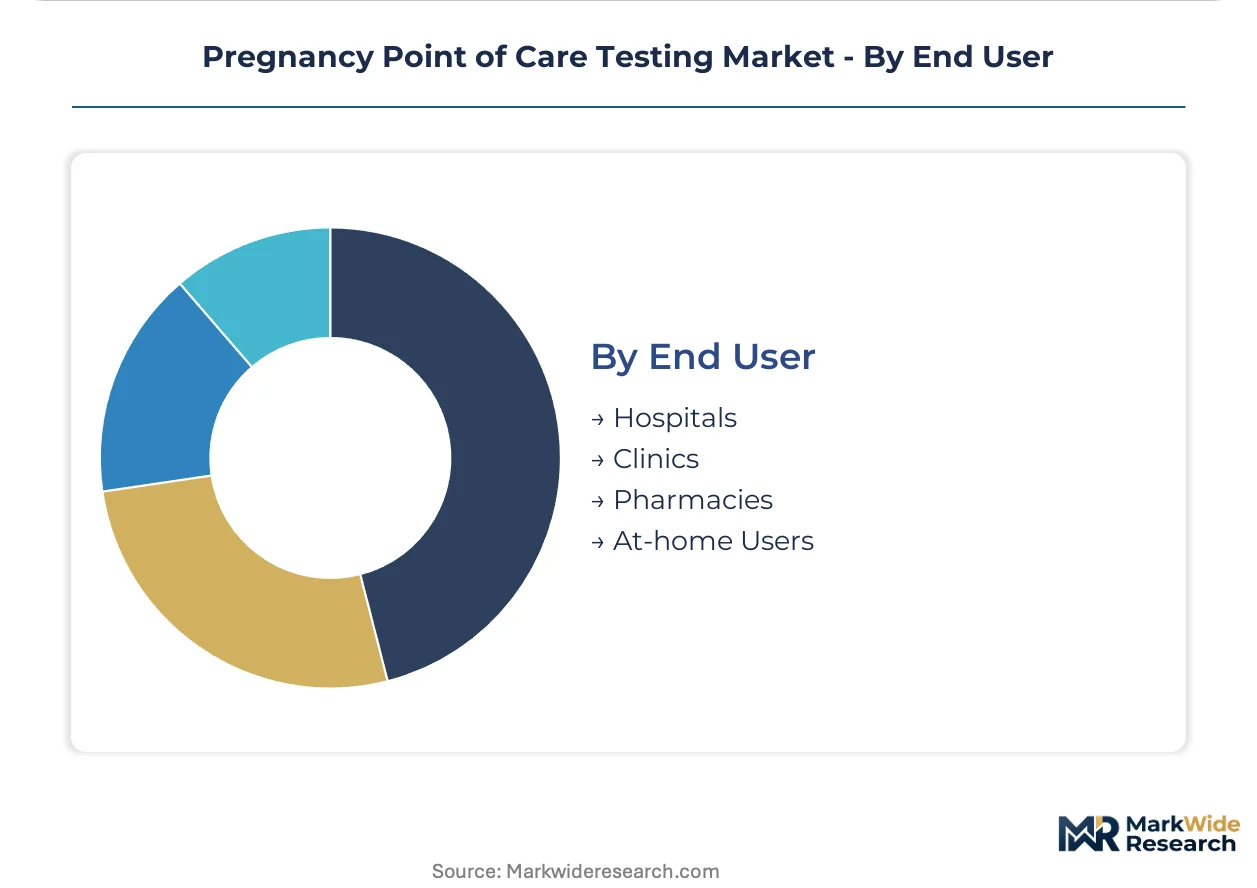
End User:
Customer procurement sophistication separates segments, with hospitals demanding integrated data systems and at-home users driving volume through retail impulse purchasing.
- Pharmacies:United States national chains consolidate procurement through private-label programs and exclusive supplier agreements. Swiss Precision Diagnostics GmbH and Abbott Laboratories compete for shelf space through differentiated antibody sourcing and digital platform bundling.
- Hospitals:Integrated delivery networks in the United States and National Health Service trusts in England specify CLIA-waived status, LIS interoperability, and supply chain redundancy in group purchasing contracts.
- Clinics:Federally qualified health centers and urgent care networks prioritize waived-test simplicity with medico-legal documentation.
- At-home Users:Direct-to-consumer e-commerce channels and retail pharmacy self-selection drive volume with minimal clinical oversight.
Pharmacies capture the highest transaction frequency; hospitals command the strongest pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States hospital networks while European pharmacy chains extract procurement concessions through consolidated purchasing. German and French regulators impose stricter clinical evidence burdens than FDA pathways, compressing margins for manufacturers without established predicate devices. Japanese distribution channels favor domestic partnerships over direct market entry.
United States
Urgent care networks and retail pharmacy chains embed pregnancy verification into reproductive health workflows, driving demand for CLIA-waived devices with digital connectivity. FDA 510(k) clearance pathways reward established lateral flow manufacturers with predicate device portfolios. Texas and Florida health systems lead adoption of microfluidics platforms for emergency department risk stratification.
Germany
Hospital group purchasing organizations specify In Vitro Diagnostic Regulation compliance and LIS interoperability in supply contracts. EMA-aligned clinical evidence requirements extend validation timelines for novel platform technologies. The Baden-Württemberg medical technology cluster hosts contract manufacturers serving European pharmacy private-label programs.
Japan
PMDA marketing authorization prioritizes domestic clinical trial data, favoring partnerships with local distributors over direct foreign entry. METI standards for connected health devices shape Bluetooth-enabled test specifications. Tokyo and Osaka pharmacy chains consolidate shelf space around established antibody sourcing relationships.
India
Organized pharmacy modernization in Mumbai and Bangalore introduces point-of-care diagnostic corners with immediate confirmation services. CDSCO import licensing requirements for diagnostic kits create compliance hurdles for unregistered foreign manufacturers. Gujarat contract manufacturers leverage lateral flow expertise to supply private-label programs for domestic retail chains.
United Kingdom
NHS trusts negotiate centralized procurement for point-of-care diagnostics, compressing margins through volume-based contracting. MHRA post-Brexit regulatory divergence from EU IVDR creates dual compliance obligations for manufacturers. The Oxford-Cambridge life sciences corridor attracts microfluidics platform developers seeking clinical validation partnerships.
Pregnancy Point of Care Testing Market Competitive Landscape
Concentration sits with integrated diagnostic manufacturers leveraging cross-category manufacturing infrastructure against specialized kit assemblers dependent on external bioreagent supply. The vendor base separates into three tiers: multinational conglomerates with waived-test portfolios, regional contract manufacturers serving pharmacy private-label programs, and emerging platform developers targeting quantitative hCG multiplexing. M&A activity concentrates on digital connectivity capabilities and antibody sourcing relationships. Strategic partnerships between lateral flow specialists and European diagnostic material suppliers limit competitor switching.
Within the integrated manufacturer tier, Abbott Laboratories and Swiss Precision Diagnostics GmbH exemplify divergent competitive positioning. Abbott leverages lateral flow manufacturing scale across multiple diagnostic categories to sustain cost advantages in high-volume urine test production. Swiss Precision Diagnostics anchors European and North American pharmacy chain relationships through proprietary antibody sourcing arrangements. Quidel Corporation occupies a position between these archetypes with focused point-of-care infectious disease and reproductive health expertise. These three companies represent the competitive spectrum from diversified conglomerate to specialized regional supplier.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Quidel Corporation |
| EKF Diagnostics Holdings plc |
| Swiss Precision Diagnostics GmbH |
| Prestige Brands Holdings |
| BioMérieux SA |
| Piramal Enterprises |
| Church & Dwight |
| BIOSYNEX SA |
| Others |
Value Network & Pricing Analysis
Lateral flow manufacturing scale across multiple diagnostic categories sustains cost advantages for high-volume producers while compressing price floors for standalone kit assemblers lacking cross-category capacity utilization. Nitrocellulose membrane processing concentrates among Asian chemical suppliers, tethering production economics to regional logistics reliability and procurement consolidation by United States pharmacy chains.
Pricing Analysis
The customization-premium spread separates configured-to-order microfluidics platforms from standard lateral flow cassettes, with three-tier pricing structure across premium, standard, and economy levels driven by certification grade and volume scale. Pricing pressure stems from private-label pharmacy expansion compressing branded margins, while at-home users exhibit highest price sensitivity and emergency care networks demonstrate lowest sensitivity due to reimbursement coverage.
Supply Chain Analysis
China and India anchor nitrocellulose membrane processing and antibody conjugate production, with South Korea contributing specialized reagent refinement for digital device components. Raw material dependencies center on nitrocellulose membranes, monoclonal antibody supplies, and colloidal gold labels, exposing manufacturers to single-source vulnerability in membrane substrates. Distribution runs through contract manufacturers serving pharmacy private-label programs and direct hospital supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pregnancy point of care testing represents an early-cycle expansion story as telehealth integration and pharmacy-based health service bundling accelerate adoption beyond traditional clinical settings.
For Market Incumbents: Shield proprietary antibody sourcing relationships through exclusive bioreagent supply contracts that limit competitor switching. Deepen backward integration into nitrocellulose membrane production to mitigate single-source exposure from Asian chemical processors. Secure CLIA-waived certification expansions ahead of FDA pathway refinements to maintain predicate device advantages against novel platform entrants.
For New Entrants and Emerging Players: Lead with microfluidics-based quantitative hCG platforms targeting United States academic medical centers where multiplexed risk stratification commands premium positioning. Capture white-space in Indian organized pharmacy modernization across Mumbai and Bangalore diagnostic corners. Pursue contract manufacturing partnerships with European retail chains seeking lateral flow expertise for private-label expansion.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated diagnostic manufacturers with cross-category lateral flow infrastructure over specialized kit assemblers dependent on external bioreagent supply. Long-term viability hinges on digital connectivity capabilities and LIS interoperability development. Monitor FDA software-as-medical-device boundary clarifications as inflection indicator for smartphone-integrated platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Antibody Sourcing Partnership | Proprietary bioreagent relationships with European diagnostic material suppliers limit competitor switching costs. |
| Microfluidics Platform Development | Multiplexed hCG quantification enables emergency department risk stratification protocols in United States hospitals. |
| Private-Label Manufacturing Contract | CVS Health and Walgreens Boots Alliance captive-brand expansion opens supplier slots for lateral flow specialists. |
| Digital Connectivity Integration | Bluetooth-enabled result logging supports health system remote monitoring program requirements. |
| Regulatory Pathway Investment | FDA 510(k) clearance streamlining rewards established predicate device portfolios with accelerated time-to-market. |
Research Methodology
Desk research of FDA 510(k) filings, EMA marketing authorization databases, and hospital procurement contract records preceded structured interviews with point-of-care diagnostics executives, pharmacy chain category managers, and hospital laboratory directors. Secondary validation drew from GPO contract databases, CLIA-waived test registries, and customs trade data for nitrocellulose membrane imports. Bottom-up unit volume estimates and top-down market sizing triangulated across manufacturer disclosures and channel inventory patterns.
Variance decomposition across product type, application setting, technology platform, and end-user procurement sophistication shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro healthcare expenditure trends and point-of-care diagnostic adoption curves. Forecast inputs incorporated telehealth integration velocity, pharmacy clinic expansion trajectories, and microfluidics platform clinical validation timelines.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU IVDR implementation; material policy shifts in software-as-medical-device classification or CE marking requirements would require re-modeling. Specific risks include smartphone app substitution accelerating, nitrocellulose supply disruption, and IVDR compliance cost barriers reshaping competitive tiers. Recalibration cycles align with material shifts in telehealth reimbursement policy and pharmacy-based diagnostic service expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Chromatin Immunoprecipitation Testing Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
Europe Point-Of-Care-Testing (POCT) Market
Testing Services
Global Sleep Testing Services Market
Testing Services
Global Legionella Testing Market
Testing Services
Skin Perfusion Pressure Testing Devices Market
Testing Services
Antimicrobial Susceptibility Testing Market
Testing Services
Thrombophilia Testing Market
Testing Services
Cell Line Authentication and Characterization Tests Market
Testing Services
Vaginal Panel Testing Market
Testing Services
Friability Tester Market
Testing Services
Mycological Testing Market
Testing Services
Rapid Hepatitis Testing Market
Testing Services
Global GMP Testing Service Market
Testing Services
Asia-Pacific Viral Clearance Market
Testing Services
Hemotransmissive Infections Testing Market