
 Propofol Market | 2026-2036
Propofol Market Size, Share, and Industry Trends Forecast 2026-2036
Propofol Market Outlook
A wide capital-intensity gap between integrated manufacturers and API-dependent competitors is bifurcating competitive dynamics in propofol supply. Fresenius Kabi leverages captive emulsion manufacturing and sterile fill-finish capacity to control cost structures across European and North American hospital networks. Baxter International anchors its position through vertically integrated lipid supply chains and dedicated aseptic production lines for intravenous anesthesia.
Propofol is an intravenous sedative-hypnotic agent formulated as an oil-in-water emulsion containing soybean oil, egg lecithin, and glycerol, administered for induction and maintenance of general anesthesia or procedural sedation in monitored care settings. Injectable emulsion formulations dominate hospital procurement due to established compatibility with infusion pump protocols and lower per-dose variability than vial presentations. Ambulatory surgical centers represent the fastest-growing end-user channel as outpatient procedural volumes shift away from inpatient settings, while critical care sedation applications sustain steady demand through long-acting infusion regimens in intensive care units.
FDA Current Good Manufacturing Practice enforcement and EMA's updated guidelines on parenteral lipid emulsion stability are tightening batch-release protocols and shelf-life validation requirements for propofol manufacturers. The EPA and OSHA frameworks governing sterile pharmaceutical manufacturing also constrain site expansion timelines, particularly for facilities handling flammable lipid solvents. Stakeholders must monitor evolving pharmacovigilance requirements for propofol-related infusion syndrome reporting, as regulatory bodies on both sides of the Atlantic tighten post-market surveillance obligations for long-duration sedation protocols.
Market Dynamics
Hospital procurement consolidation and FDA enforcement of liposomal injectable standards are compressing supplier margins while favoring manufacturers with captive sterile fill-finish infrastructure.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient procedural volume migration from inpatient settings accelerates propofol consumption in freestanding surgical facilities across the United States.
- EMA parenteral lipid emulsion stability guidelines:Updated batch-release protocols extend validation requirements, locking in compliant manufacturers with established shelf-life documentation.
- Critical care sedation protocols:Long-acting infusion regimens in intensive care units sustain steady demand for emulsion formulations compatible with extended-duration pump administration.
Market Restraints
- Soybean oil input volatility:Lipid feedstock price fluctuations constrain margin predictability for emulsion-dependent manufacturers without backward integration into agricultural supply.
- Flammable solvent handling constraints:EPA and OSHA frameworks governing sterile pharmaceutical manufacturing extend site expansion timelines for facilities processing lipid solvents.
- Propofol-related infusion syndrome surveillance:Tightened pharmacovigilance reporting obligations for long-duration sedation create compliance overhead and liability exposure.
Strategic Opportunities
- Prefilled syringe presentation expansion:Ready-to-administer formats reduce per-dose variability and compatibility testing burden in high-throughput surgical settings.
- Centralized hospital network purchasing:Consolidated procurement systems in United States health systems create volume aggregation points for qualified suppliers with dedicated aseptic lines.
- ISO 13485 certification alignment:Medical device quality management integration enables cross-selling into procedural sedation device bundles.
Industry Challenges
- Sterile manufacturing workforce scarcity:Aseptic processing technician certification pipelines lag facility expansion requirements, constraining output scaling.
- Legacy vial-to-emulsion format transition:Hospital pharmacy inventory systems require reconfiguration to accommodate oil-in-water emulsion storage and handling protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propofol Market |
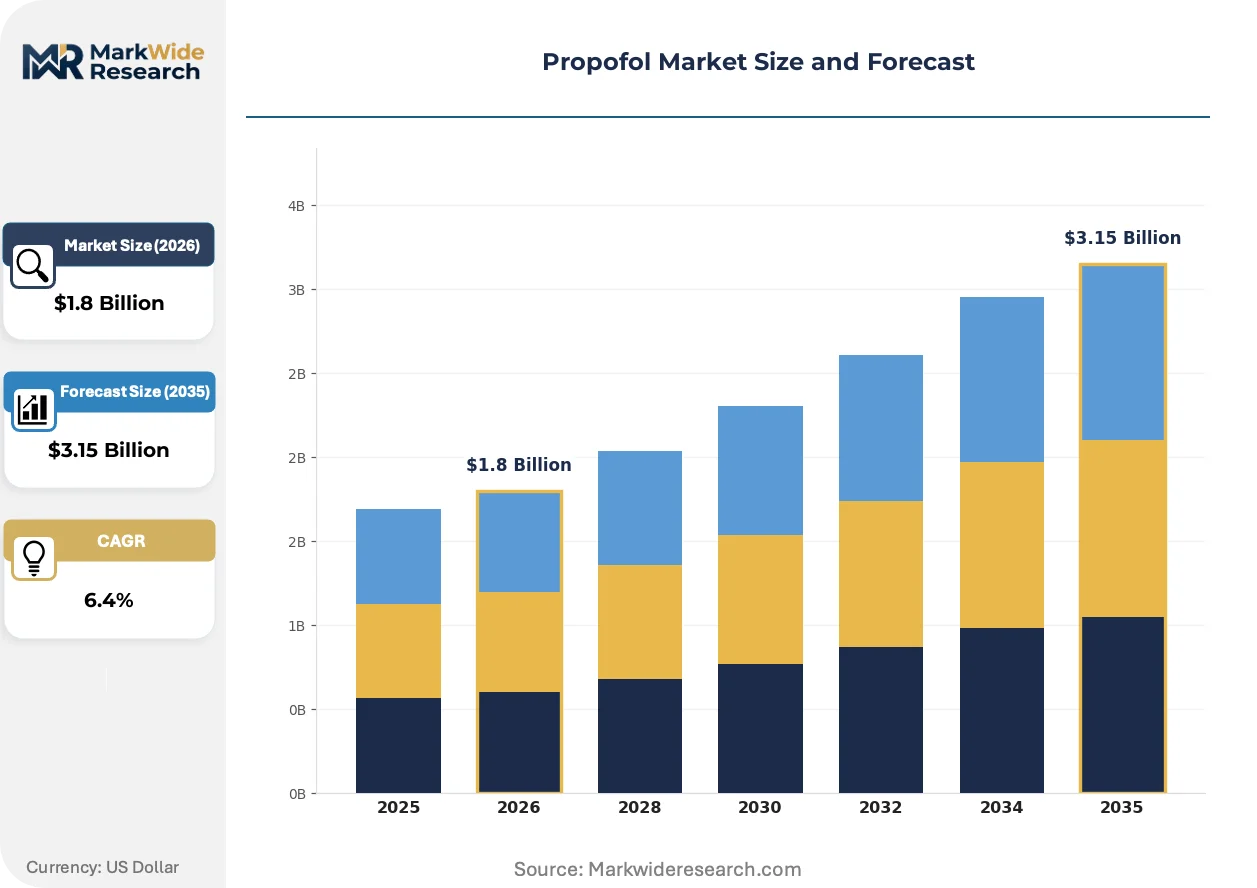
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Intravenous, Emulsion, Solution End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Dental Practices Delivery Mode: Syringe, Infusion Pump, Vial, Pre-filled Cartridge Therapy Area: General Anesthesia, Sedation, Pain Management, Critical Care |
| Companies Covered | Fresenius Kabi, Baxter International, B. Braun Melsungen, Pfizer, Hikma Pharmaceuticals, AbbVie, Dr. Reddy's Laboratories, Sagent Pharmaceuticals, Jiangsu Nhwa Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propofol Market Strategic Shifts
Formulation stability improvements and administration technology convergence are reshaping competitive differentiation in intravenous anesthesia supply. Three developments warrant particular attention.
Lipid nanoemulsion stabilization technologies are displacing conventional macroemulsion formats in high-acuity settings. Academic medical centers in Germany and Japan are piloting these presentations for reduced injection pain and improved pharmacokinetic predictability. The structural consequence is compression of shelf-life advantage held by incumbent macroemulsion suppliers.
FDA Current Good Manufacturing Practice enforcement for liposomal injectables is tightening documentation requirements for lipid excipient traceability. Manufacturers must now demonstrate supply chain visibility back to egg lecithin and glycerol raw material sources. Hospital procurement teams in the United States are responding by qualifying suppliers with vertically integrated lipid supply chains.
Surgeon-anesthesiologist preference for pump-integrated sedation workflows is fragmenting purchasing authority within health systems. Ambulatory surgical centers are bypassing centralized pharmacy committees to contract directly with emulsion manufacturers for procedural sedation kits. This pattern is most visible in United States metropolitan markets with high concentrations of freestanding endoscopy and ophthalmology facilities.
Propofol Market Segmentation
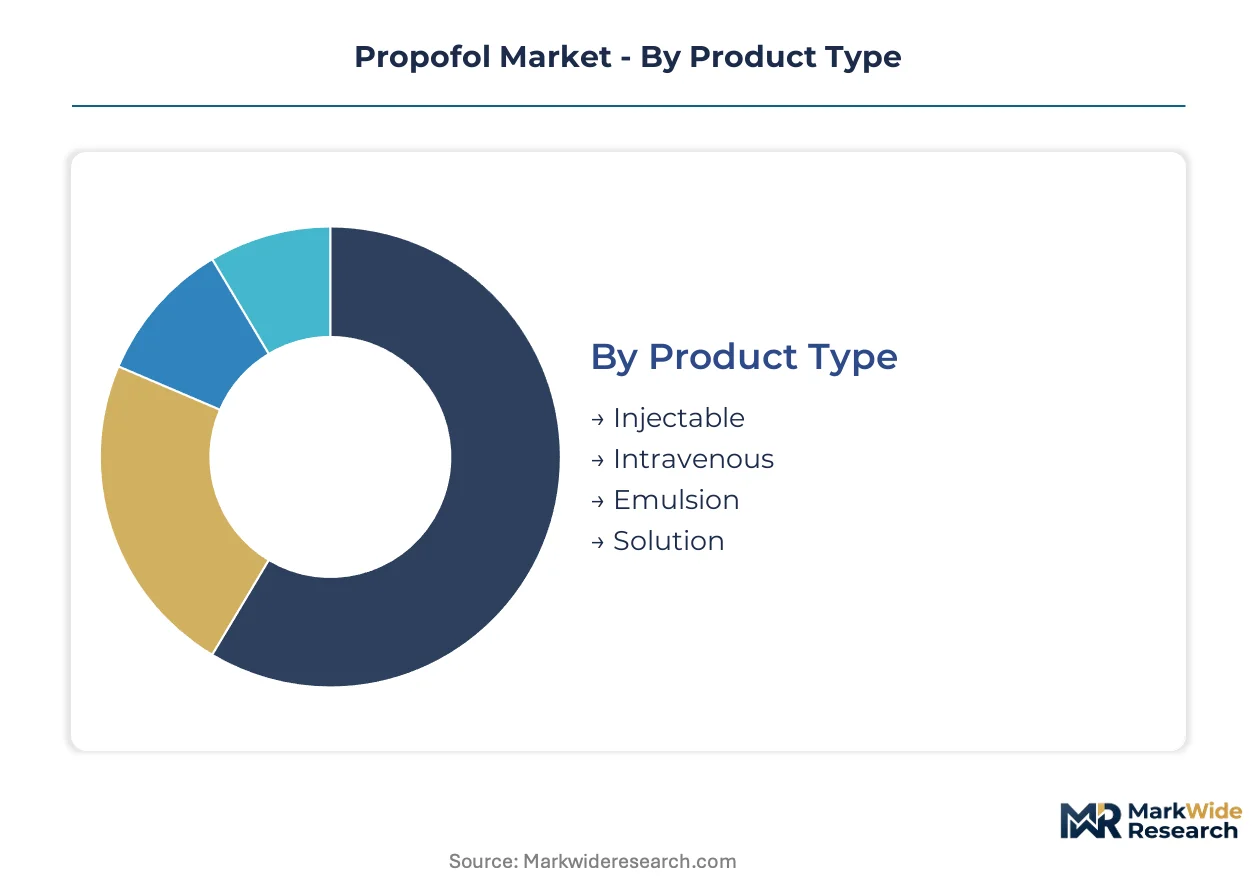
Propofol segmentation reflects divergent channel economics across acute care versus ambulatory settings. Formulation stability requirements and pump compatibility standards fragment procurement patterns by delivery mode and end-user infrastructure.
Product Type:
Emulsion formulations flow through hospital centralized pharmacy systems, while solution formats reach outpatient channels directly.
- Injectable:Sterile aqueous presentations for intravenous bolus administration dominate emergency department and rapid-sequence induction protocols. Demand concentrates in United States trauma centers where compatibility with high-pressure injection systems is mandatory.
- Intravenous:Systemic delivery formulations with established pharmacokinetic profiles anchor maintenance dosing in prolonged surgical procedures. German and Japanese academic medical centers are piloting these presentations for reduced injection pain and improved predictability.
- Emulsion:Oil-in-water formulations containing soybean oil, egg lecithin, and glycerol serve induction and maintenance of general anesthesia.
- Solution:Alternative presentations for specific procedural sedation applications.
By volume, Emulsion leads. By growth pace, Intravenous is climbing the fastest.
End User:
Cost tier stratification separates capital-intensive hospital networks from lean ambulatory operators.
- Hospitals:Integrated health systems with captive pharmacy committees and dedicated anesthesia departments drive bulk procurement of multi-dose vials. United States hospital consolidation creates volume aggregation points for qualified suppliers with dedicated aseptic lines.
- Ambulatory Surgical Centers:Freestanding facilities with streamlined formularies favor prefilled presentations and direct manufacturer contracting. These centers are expanding propofol utilization for outpatient procedures across United States metropolitan markets with high concentrations of endoscopy and ophthalmology facilities.
- Outpatient Clinics:Limited-procedure settings with intermittent sedation requirements.
- Dental Practices:Smaller-scale operators with basic sedation infrastructure.
By volume, Hospitals dominate. By expansion trajectory, Ambulatory Surgical Centers are gaining share fastest.
Delivery Mode:
Volume concentration tracks pump infrastructure deployment across facility types.
- Infusion Pump:Programmable delivery systems with dose-rate control enable extended-duration sedation in intensive care units. Critical care protocols in United States health systems sustain steady demand for emulsion formulations compatible with long-acting infusion regimens.
- Syringe:Manual bolus administration devices serve rapid induction and short-procedure settings. Ambulatory surgical centers in high-throughput United States markets favor these formats for reduced per-dose variability.
- Vial:Multi-dose glass containers with rubber septum closures for pharmacy-compounded administration.
- Pre-filled Cartridge:Ready-to-administer single-unit presentations for point-of-care deployment.
By volume, Infusion Pump leads. By growth pace, Syringe is ahead.
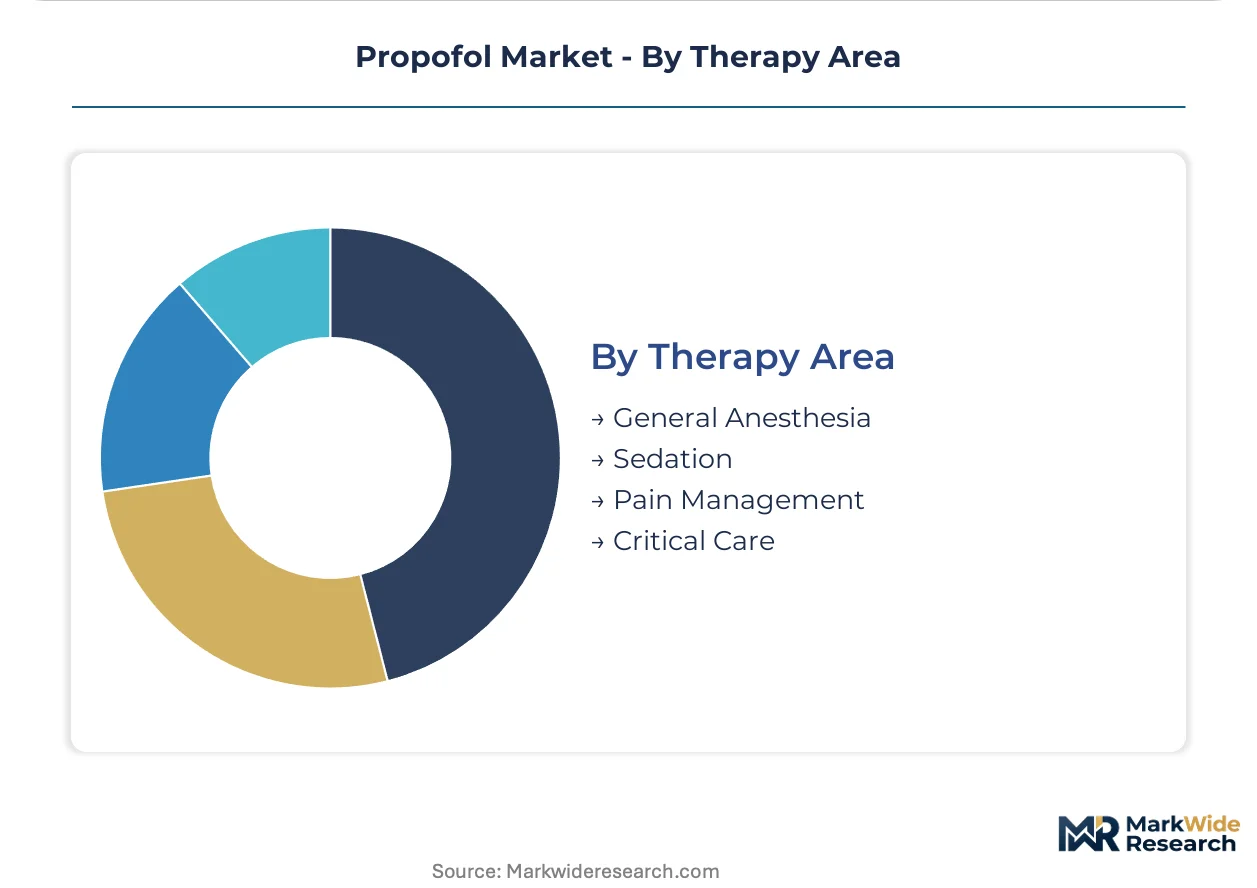
Therapy Area:
Application maturity separates established anesthesia protocols from emerging sedation indications.
- General Anesthesia:Induction and maintenance protocols for surgical procedures represent the foundational use case. Hospital networks in the United States anchor procurement volume through centralized purchasing of anesthesia supplies.
- Sedation:Procedural sedation for monitored anesthesia care expands fastest as outpatient volumes migrate from inpatient settings. Ambulatory surgical centers across United States metropolitan areas drive this channel's steepest expansion trajectory.
- Pain Management:Adjunctive applications in multimodal analgesia protocols.
- Critical Care:Long-duration infusion regimens in intensive care units with specialized monitoring requirements.
By volume, General Anesthesia leads. By growth pace, Sedation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from European emulsion manufacturers balance against import dependence for lipid feedstocks in Asian compounding facilities. The United States maintains net import exposure for finished propofol presentations despite domestic sterile fill-finish capacity. Regulatory divergence between FDA batch-release protocols and EMA stability guidelines fragments cross-border procurement standardization.
United States
Hospital consolidation in Texas and Florida drives centralized anesthesia supply contracts toward multi-year volume agreements. FDA Current Good Manufacturing Practice enforcement for liposomal injectables tightens documentation requirements for egg lecithin traceability. The Cleveland Clinic and Mayo Clinic networks in Ohio and Minnesota anchor qualification programs for suppliers with dedicated aseptic lines.
Germany
Academic medical centers in Berlin and Munich pilot lipid nanoemulsion stabilization technologies for reduced injection pain protocols. EMA updated guidelines on parenteral lipid emulsion stability extend batch-release validation timelines for manufacturers. The Rhine-Ruhr pharmaceutical cluster around Düsseldorf and Cologne concentrates sterile emulsion compounding capacity serving Central European hospital networks.
China
Domestic surgical volume expansion in Shanghai and Guangzhou accelerates propofol consumption for general anesthesia induction. NMPA registration requirements for oil-in-water emulsion formulations tighten stability documentation for soybean oil excipient sourcing. The Yangtze River Delta region around Jiangsu province anchors captive manufacturing for hospital network procurement consolidation.
Japan
Critical care sedation protocols in Tokyo and Osaka academic hospitals sustain demand for long-acting infusion regimens. PMDA pharmacovigilance requirements for propofol-related infusion syndrome reporting create compliance overhead for extended-duration applications. The Kansai region around Osaka concentrates sterile fill-finish infrastructure serving domestic intensive care unit networks.
India
Outpatient procedural migration in Maharashtra and Karnataka expands ambulatory surgical center utilization of propofol sedation. CDSCO manufacturing license requirements for parenteral emulsions align with WHO prequalification standards for export-oriented production. The Hyderabad-Visakhapatnam pharmaceutical corridor anchors API-to-finished-dose integration for lipid-based injectable supply.
Propofol Market Competitive Environment
Concentration sits with integrated manufacturers possessing captive emulsion technology and sterile fill-finish infrastructure. The supplier base separates into three archetypes: diversified hospital supply conglomerates with vertical lipid control, mid-scale generic injectable specialists, and regional API-dependent compounders. Competitive moves center on backward integration into agricultural lipid sourcing and strategic partnerships with ambulatory surgical center networks for direct contracting.
Among European-based diversified suppliers, Fresenius Kabi and B. Braun Melsungen occupy positions exemplifying captive manufacturing archetypes with established hospital network relationships. Baxter International represents North American vertical integration into lipid supply chains. Pfizer and Hikma Pharmaceuticals sit within the generic injectable specialist tier, while Dr. Reddy's Laboratories and Jiangsu Nhwa Pharmaceutical anchor regional production archetypes serving price-sensitive procurement channels.
| Leading Market Players |
|---|
| Fresenius Kabi |
| Baxter International |
| B. Braun Melsungen |
| Pfizer |
| Hikma Pharmaceuticals |
| AbbVie |
| Dr. Reddy's Laboratories |
| Sagent Pharmaceuticals |
| Jiangsu Nhwa Pharmaceutical |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lipid feedstock inventory buffers separate integrated manufacturers from API-dependent competitors, concentrating pricing power with suppliers possessing captive emulsion technology and sterile fill-finish infrastructure. Hospital procurement consolidation in the United States amplifies volume leverage, compressing margins for compounders without backward integration into agricultural supply chains.
Pricing Analysis
The customization-premium spread between configured-to-order prefilled syringes and standard multi-dose vials runs wide in this market. Contract-based long-term offtake agreements dominate hospital network procurement, with price differentiation driven by FDA Current Good Manufacturing Practice certification tier and volume scale. Pricing pressure stems from soybean oil input volatility, with ambulatory surgical centers exhibiting highest price sensitivity due to lean operating models while integrated health systems anchor least sensitive demand through captive pharmacy committees.
Supply Chain Analysis
Just-in-time inventory strategies prevail among European and North American hospital networks, while Asian compounding facilities maintain strategic stockpiles of lipid excipients to buffer agricultural price swings. Supply concentrates in Germany, the United States, and China for finished emulsion manufacturing, with raw material dependencies on Argentine soybean oil, Ukrainian egg lecithin, and Malaysian glycerol. Single-source vulnerability in egg lecithin traceability documentation creates compliance risk under tightened FDA batch-release protocols. Distribution runs through GPO-affiliated wholesalers to hospital networks, with direct manufacturer contracting penetrating ambulatory channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic processing technician certification gaps constrain output scaling across sterile manufacturing facilities, creating durable scarcity premiums for qualified suppliers. This capability bottleneck shapes competitive positioning and investment attractiveness.
For Market Incumbents: Consolidate sterile fill-finish capacity through targeted facility acquisitions in the United States Sun Belt, where hospital network expansion concentrates demand. Lock in multi-year volume agreements with consolidating health systems before mid-scale generic injectable specialists achieve EMA stability guideline compliance. Prioritize backward integration into agricultural lipid sourcing to neutralize soybean oil price volatility threatening margin predictability. For New Entrants and Emerging Players: Lead with prefilled syringe presentations targeting ambulatory surgical centers in United States metropolitan markets with high concentrations of freestanding endoscopy facilities. This segment offers lowest qualification barriers and fastest procurement cycle times. Pursue ISO 13485 certification alignment to enable cross-selling into procedural sedation device bundles, bypassing centralized pharmacy committee gatekeeping. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because sterile manufacturing workforce scarcity and regulatory compliance overhead favor scaled incumbents with established shelf-life documentation. Target acquisition profiles emphasize API-to-finished-dose integrators with captive emulsion technology. The signal to watch is FDA enforcement action intensity against lipid excipient traceability violations, which would accelerate supplier qualification attrition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Lipid Supply | Captive sourcing of soybean oil and egg lecithin neutralizes input price volatility under EPA solvent handling constraints. |
| Prefilled Syringe Presentation Expansion | Ready-to-administer formats reduce per-dose variability for ambulatory surgical centers in high-throughput United States markets. |
| EMA Stability Guideline Compliance Investment | Extended batch-release validation timelines lock in qualified manufacturers serving Central European hospital networks. |
| Direct Manufacturer Contracting with ASC Networks | Bypassing centralized pharmacy committees captures procedural sedation kit volumes in metropolitan endoscopy corridors. |
| Aseptic Processing Workforce Development Pipeline | Certification programs address technician scarcity constraining sterile fill-finish capacity expansion timelines. |
Study Parameters
Initial hypotheses were tested against primary input from anesthesia department heads, hospital pharmacy directors, GPO contracts managers, and sterile manufacturing quality leads, and refined through secondary validation against FDA Current Good Manufacturing Practice enforcement records, EMA parenteral lipid emulsion stability guidelines, hospital procurement databases, and customs trade data for lipid excipient flows. Bottom-up demand modeling across end-user segments triangulated with top-down supply capacity assessments.
Variance decomposition across the projection horizon isolates volume drivers by formulation type, delivery mode, end-user infrastructure, and regional regulatory cluster. CAGRs derive from segment-level demand elasticity modeling and supply capacity expansion schedules, incorporating propofol-related infusion syndrome surveillance burden as a demand modifier for extended-duration critical care applications.
Forecasts assume regulatory continuity in FDA Current Good Manufacturing Practice enforcement and EMA stability documentation requirements; material policy shifts would require re-modeling. Revision becomes warranted when hospital consolidation velocity or aseptic processing workforce availability crosses thresholds that alter supply-demand balance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
Global Narcolepsy Drugs Market
Pharmaceuticals
Mexico Diabetes Drugs Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Compounding Chemotherapy Market
Pharmaceuticals
Sustained Release Drugs Market
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
Global Dengue Vaccine Market
Pharmaceuticals
Oral Contraceptive Pills Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market
Pharmaceuticals
Global Chick Embryo Cell Rabies Vaccine Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Saline Laxative Market