
 Global Body Temperature Monitoring Market | 2026-2036
Global Body Temperature Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Body Temperature Monitoring Market Foresight
Aftermarket service revenue for calibration and sensor replacement is narrowing as manufacturers shift toward subscription-based remote monitoring platforms. Philips sustains technology leadership through integrated hospital ecosystems that bundle hardware with cloud analytics. Omron Corporation dominates home-use digital thermometers through pharmacy channel control across Asia-Pacific markets. Baxter International leverages its clinical infusion device footprint to cross-sell continuous temperature monitoring in intensive care settings.
Body temperature monitoring encompasses devices that measure core or surface thermal status using thermistor, infrared, or thermocouple sensing elements with accuracy thresholds typically within ±0.1°C for clinical applications. These systems serve fever detection, perioperative surveillance, and physiological stress tracking across acute care and ambulatory environments. Digital thermometers and infrared thermometers anchor hospital procurement volumes where infection control protocols mandate single-use or dedicated patient devices. Smart wearables represent the fastest-expanding margin pool as biosensor miniaturization enables multi-parameter streaming through cloud-based platforms. Wireless temperature sensors occupy a maturing niche in neonatal intensive care where skin-adhesive patches replace intermittent axillary measurements.
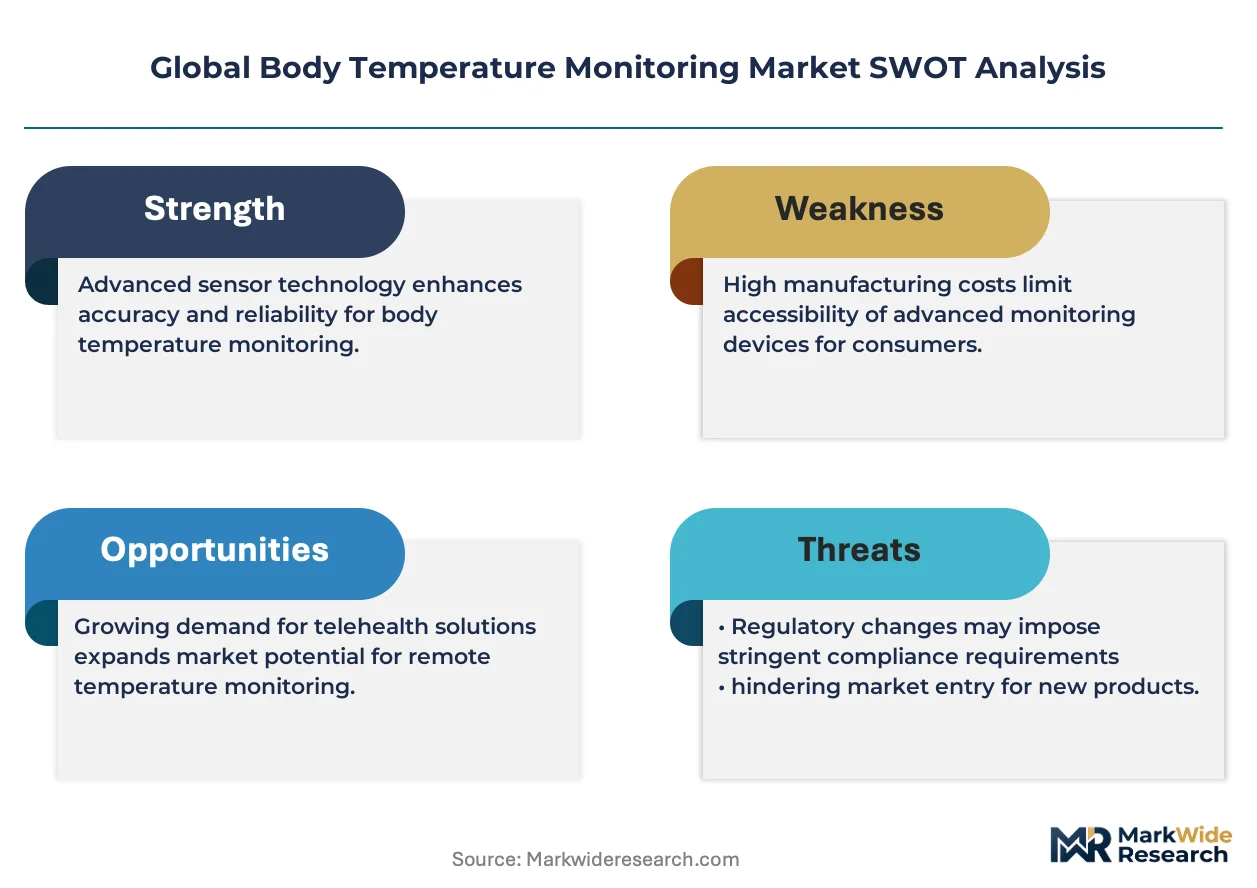
The FDA enforces 510(k) premarket notification for clinical-grade non-invasive thermometers while the EU Medical Device Regulation imposes post-market surveillance obligations that extend manufacturer liability across the product lifecycle. Japan's PMDA maintains distinct thermal sensor accuracy standards that create compliance friction for imported wearable devices. Stakeholders must weigh regulatory divergence against platform standardization as cloud-based deployment models blur traditional geographic certification boundaries.
Market Dynamics
Hospital procurement of wireless temperature sensors is expanding as healthcare systems prioritize continuous patient surveillance over intermittent spot-checking, compressing the installed base of traditional digital thermometers while elevating platform-based recurring revenue models.
Growth Catalysts
- EU Medical Device Regulation:Post-market surveillance obligations are extending manufacturer liability across the product lifecycle, favoring established players with robust quality systems and accelerating consolidation among smaller device makers.
- Neonatal intensive care:Skin-adhesive wireless patches are replacing intermittent axillary measurements in NICU environments, creating dedicated demand for continuous monitoring infrastructure.
- Biosensor miniaturization:Multi-parameter streaming through cloud-based platforms is enabling fever detection, perioperative surveillance, and physiological stress tracking from single wearable devices.
Market Restraints
- Thermistor supply concentration:Precision thermistor manufacturing clusters in East Asian component hubs, exposing device makers to single-source risk for clinical-grade sensing elements.
- FDA 510(k) pathway friction:Evolving guidance on clinical-grade wearable devices is extending premarket notification timelines and increasing documentation burdens for novel form factors.
- Reusable infrared alternatives:Non-contact tympanic and temporal artery thermometers remain entrenched in ambulatory settings, limiting penetration of disposable patch-based systems.
Strategic Opportunities
- Germany's chronic disease management protocols:Aging population demographics and home-based care expansion are creating demand for remote patient monitoring platforms with integrated temperature streaming.
- AI-enhanced predictive analytics:Machine learning algorithms applied to continuous thermal data streams are enabling early sepsis detection and postoperative complication forecasting in acute care settings.
- Pharmacy channel control:Direct-to-consumer distribution through retail health networks is opening patient-paid segments outside traditional hospital procurement cycles.
Industry Challenges
- Cloud infrastructure integration:Legacy hospital IT systems require substantial middleware development to ingest real-time biometric streams from heterogeneous wearable device fleets.
- Cross-border certification divergence:Japan's PMDA maintains distinct thermal sensor accuracy standards that create compliance friction for wearable devices seeking multi-territory approval.
- Calibration workforce scarcity:Field service engineers with combined competencies in biomedical device maintenance and cloud platform troubleshooting remain under-supplied relative to installed base growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Body Temperature Monitoring Market |
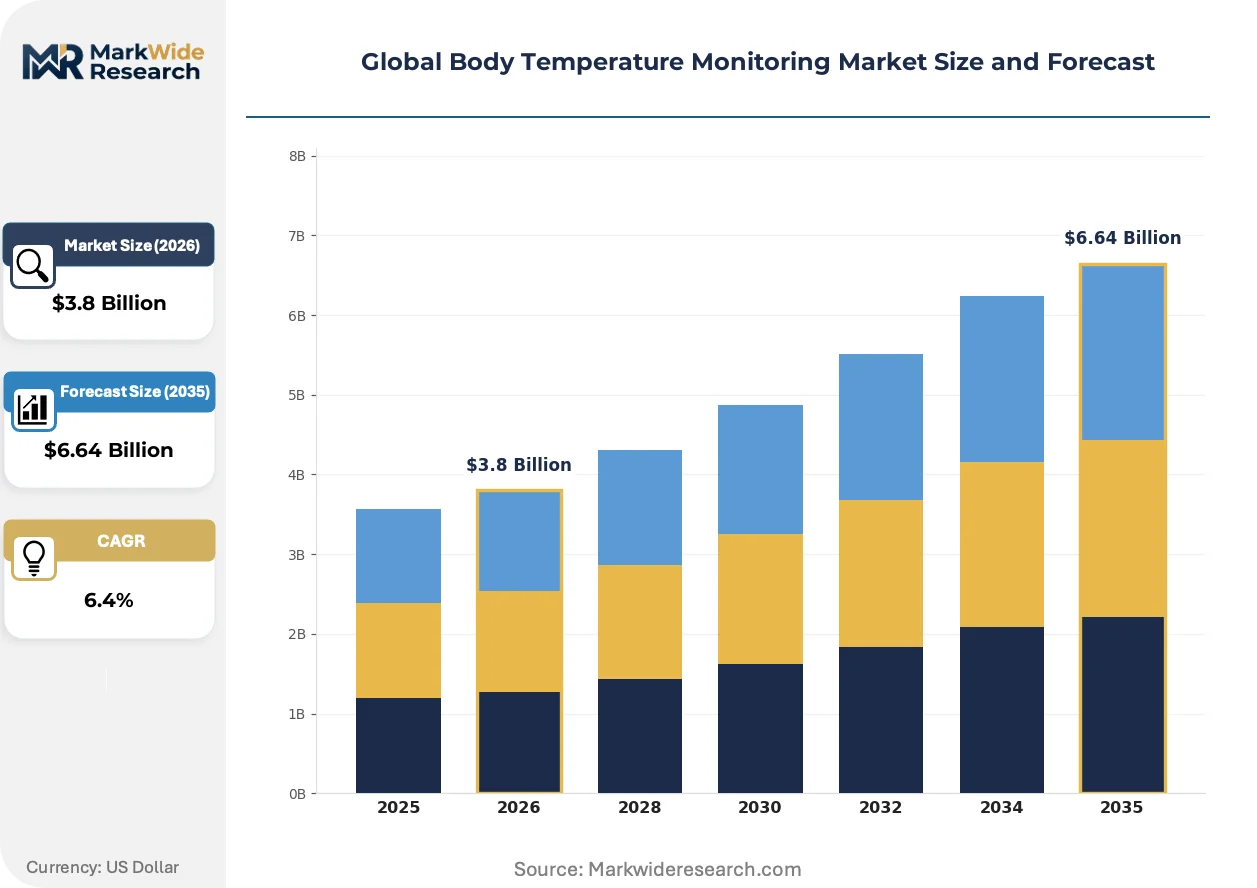
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Thermometers, Infrared Thermometers, Smart Wearables, Wireless Temperature Sensors, Mercury Thermometers Application: Clinical Diagnosis, Remote Patient Monitoring, Sports Performance, Neonatal Care, Occupational Health End User: Hospitals, Ambulatory Care Centers, Nursing Homes, Sports Clinics, Research Laboratories Deployment: On-Premise, Cloud-Based Platforms, Mobile Applications, Embedded Systems, Standalone Devices |
| Companies Covered | Omron Corporation, Microlife Corporation, Philips, Baxter International, Cardinal Health, 3M Company, Terumo Corporation, American Diagnostic Corporation, A&D Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Body Temperature Monitoring Market Shifts & Advancements
Digital thermometer hardware is commoditizing while value capture migrates toward software-enabled surveillance platforms, reshaping competitive positioning around data interoperability rather than sensor precision alone.
Thermopile array sensors are virtualizing the traditional thermometer by enabling continuous spatial temperature mapping without patient contact. Hospital systems in the United States are piloting ceiling-mounted installations for ward-wide fever screening. This architecture is virtualizing device ownership models, shifting capital expenditure toward subscription-based monitoring services.
Japan's PMDA thermal sensor accuracy standards are diverging from FDA and EU MDR benchmarks, creating a three-regime compliance environment for wearable device manufacturers. Companies seeking multi-territory approval must maintain parallel technical documentation streams. Smart wearables with multi-parameter capability face the greatest certification burden, slowing rollout timelines for integrated biosensor platforms.
Aftermarket service revenue for calibration and sensor replacement is narrowing as manufacturers shift toward subscription-based remote monitoring platforms. Hospital procurement teams in Germany and Japan are bundling hardware acquisition with multi-year cloud analytics commitments. This transition is most visible in intensive care settings, where continuous temperature surveillance is displacing scheduled spot-checking protocols entirely.
Global Body Temperature Monitoring Market Segmentation
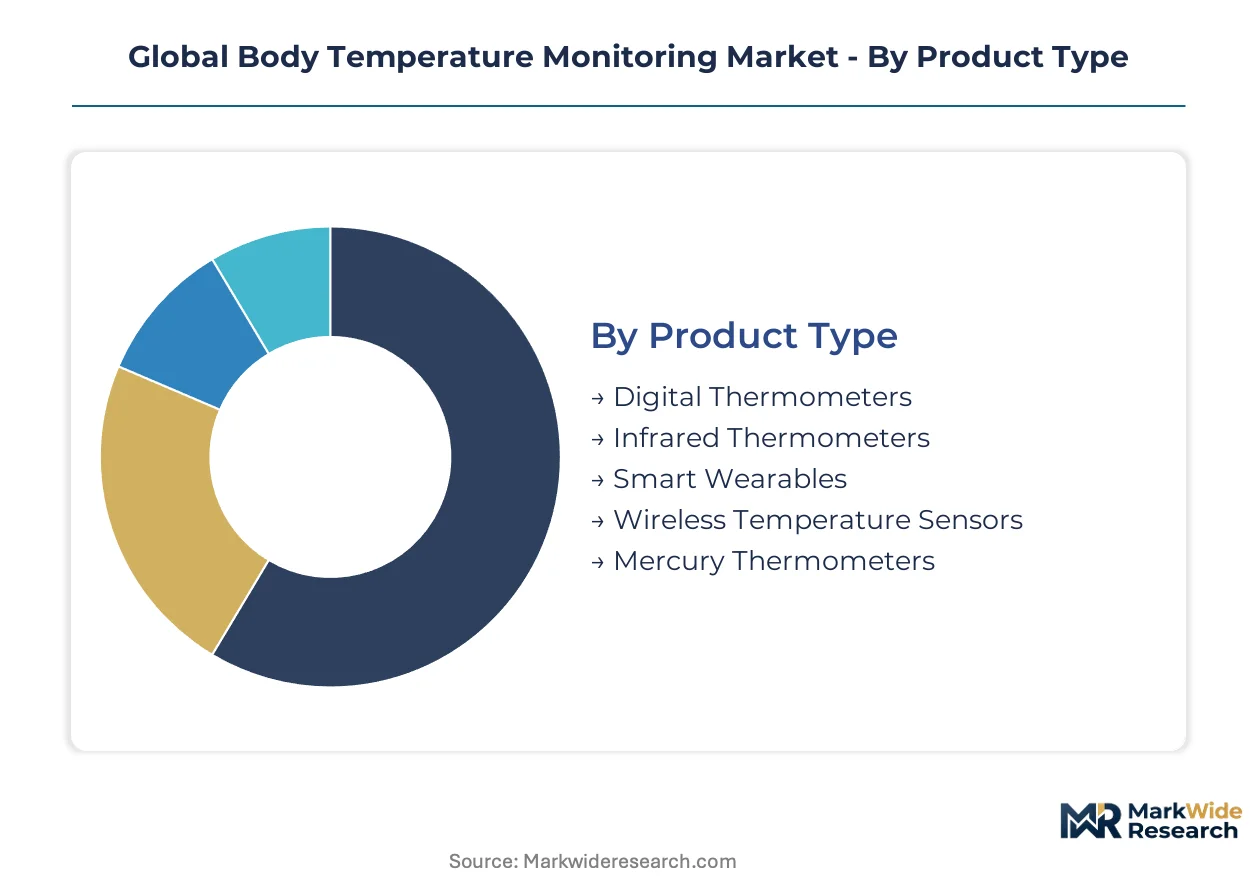
Body temperature monitoring segments diverge sharply by clinical validation requirements and connectivity architecture. Product categories span disposable hardware to subscription-anchored platforms, while deployment models determine whether data remains siloed in hospital IT or streams to cloud analytics vendors.
Product Type:
Use-case spectrum spans intermittent spot-checking in ambulatory settings to continuous streaming in intensive care environments.
- Digital Thermometers:Thermistor-based handheld devices with ±0.1°C accuracy for oral, rectal, or axillary measurement. Hospital procurement in the United States and Germany favors single-use probe covers for infection control, compressing per-unit margins while sustaining volume concentration in acute care.
- Smart Wearables:Skin-adhesive patches and wrist-worn biosensors enabling multi-parameter streaming through Bluetooth Low Energy. Demand concentrates in neonatal intensive care units and postoperative wards where continuous surveillance replaces scheduled nursing rounds.
- Infrared Thermometers:Non-contact tympanic and temporal artery devices using thermopile sensors for rapid screening. Pharmacy channel control across Japan and South Korea sustains consumer segment viability.
- Wireless Temperature Sensors:Disposable adhesive patches with embedded RFID or NFC transmission for automated charting. NICU adoption in Germany and Japan is displacing traditional axillary protocols.
- Mercury Thermometers:Glass-column devices with declining clinical utilization due to EPA disposal regulations and EU RoHS restrictions. Remaining demand clusters in resource-constrained settings with limited digital infrastructure.
Established volume favors digital thermometers; emerging adoption favors smart wearables.
Application:
Margin concentration tracks reimbursement eligibility and data integration depth.
- Clinical Diagnosis:Fever detection in emergency departments and primary care settings requiring FDA 510(k) or EU MDR certification. Hospital procurement cycles in the United States prioritize devices with EHR interoperability.
- Remote Patient Monitoring:Home-based temperature streaming for chronic disease management and post-discharge surveillance. Germany's statutory health insurance reimbursement for telemonitoring is accelerating platform deployment.
- Sports Performance:Core temperature monitoring for heat illness prevention in endurance athletics and military training. Demand clusters in Australia and the United States with established occupational safety protocols.
- Neonatal Care:Continuous skin temperature surveillance in NICU environments with alarm thresholds for hypothermia detection. Japan's PMDA maintains distinct accuracy standards that fragment device certification.
- Occupational Health:Pre-shift fever screening in manufacturing and food processing facilities. Post-pandemic protocols in South Korea and Singapore sustain infrared thermometer demand.
Reimbursement eligibility favors clinical diagnosis; steepest expansion trajectory favors remote patient monitoring.
End User:
Procurement authority determines pricing structure and service bundling requirements.
- Hospitals:Integrated delivery networks with centralized purchasing negotiating multi-year platform contracts. Cloud analytics bundling is displacing standalone hardware acquisition in the United States and Germany.
- Nursing Homes:Long-term care facilities prioritizing wireless sensors for fall-risk reduction alongside temperature surveillance. Staffing shortages in Japan are accelerating automated monitoring adoption.
- Ambulatory Care Centers:Urgent care and outpatient clinics requiring rapid-turnaround devices with minimal calibration overhead. Infrared thermometers dominate due to throughput requirements.
- Sports Clinics:Specialized facilities serving professional athletes and military populations. Premium pricing tolerance supports advanced ingestible core temperature capsules.
- Research Laboratories:Precision thermometry for physiological studies requiring calibrated traceability to national standards. NIST-traceable certification commands 3-4x hardware premiums in the United States.
Contract scale favors hospitals; unmet need concentration favors nursing homes.
Deployment:
Data sovereignty requirements and legacy IT compatibility shape architecture selection.
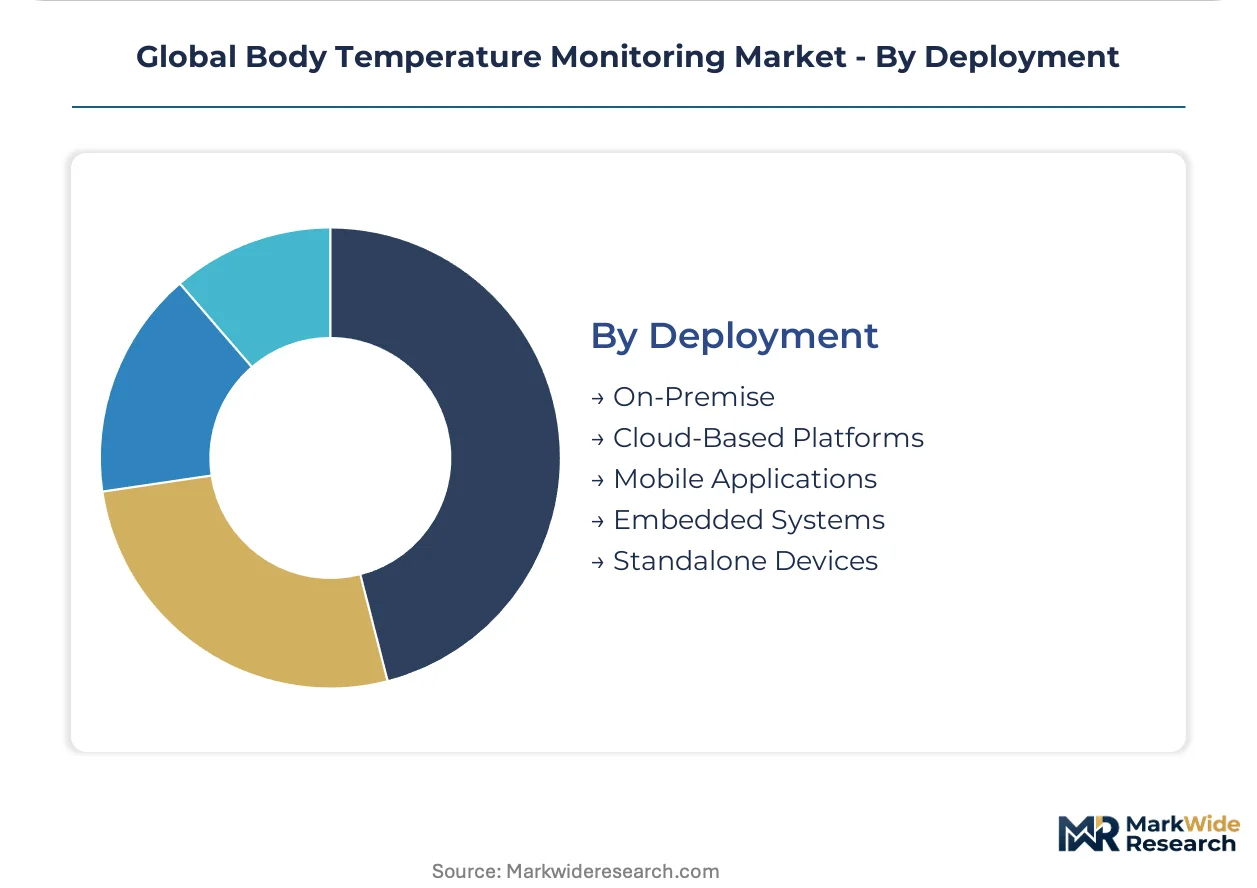
- Cloud-Based Platforms:Real-time biometric streaming to vendor-managed infrastructure with predictive analytics overlays. EU GDPR compliance and Japan's APPI create cross-border data governance friction.
- On-Premise:Hospital-controlled servers maintaining patient data within institutional firewalls. German healthcare providers prioritize this architecture for statutory data localization requirements.
- Mobile Applications:Consumer-facing interfaces for home-use devices with limited clinical validation. Direct-to-consumer distribution in the United States bypasses traditional procurement cycles.
- Embedded Systems:Firmware-integrated processing in standalone devices without external connectivity. Critical for FDA-regulated clinical thermometers requiring deterministic performance.
- Standalone Devices:Battery-operated units with onboard memory and no network dependency. Field medicine and disaster response applications in geographically dispersed settings.
Regulatory compliance favors on-premise; functionality expansion favors cloud-based platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision thermistor manufacturing concentrates in East Asian component hubs, exposing device makers to single-source risk for clinical-grade sensing elements. Hospital procurement patterns diverge sharply across regulatory jurisdictions, with reimbursement eligibility and data localization requirements fragmenting deployment models.
United States
Integrated delivery networks negotiate multi-year platform contracts bundling hardware with cloud analytics. FDA 510(k) premarket notification governs clinical-grade non-invasive thermometers, with evolving guidance extending timelines for wearable form factors. Greater Boston and the Research Triangle host concentrated medical device innovation clusters where AI-enhanced predictive analytics firms partner with hospital systems for sepsis detection algorithms.
Germany
Statutory health insurance reimbursement for telemonitoring accelerates remote patient monitoring platform deployment. EU Medical Device Regulation imposes post-market surveillance obligations extending manufacturer liability across product lifecycles, favoring established players with robust quality systems. Baden-Württemberg's precision engineering corridor supplies thermistor calibration equipment to device manufacturers across the continent.
Japan
Aging demographics and chronic disease management protocols drive device utilization in home-based care expansion. PMDA maintains distinct thermal sensor accuracy standards creating compliance friction for imported wearable devices seeking multi-territory approval. Osaka-based electronics manufacturers dominate thermopile sensor production for infrared thermometer modules.
China
Domestic hospital procurement prioritizes cost-optimized digital thermometers for infection control protocols in acute care expansion. NMPA medical device registration requirements diverge from FDA and EU MDR benchmarks, necessitating parallel technical documentation streams. Shenzhen's biosensor manufacturing ecosystem supplies wireless temperature patch components to global device assemblers.
South Korea
Post-pandemic occupational health protocols sustain infrared thermometer demand for pre-shift fever screening in manufacturing facilities. MFDS maintains harmonized standards with FDA benchmarks, reducing certification burden for export-oriented device makers. Seoul Capital Area hosts concentrated R&D activity in flexible electronics for skin-adhesive monitoring patches.
Global Body Temperature Monitoring Market Competitive Landscape
Hospital-system integrators and consumer-health specialists split the market along clinical validation and channel control vectors. Three tiers emerge: premium platform vendors bundling hardware with cloud analytics, mid-tier device manufacturers competing on procurement contract scale, and commodity hardware suppliers serving pharmacy retail networks. Consolidation accelerates through strategic partnerships between sensor technology firms and hospital IT infrastructure providers, while geographic licensing agreements resolve cross-border certification fragmentation.
Within the integrated platform tier, Philips and Baxter International exemplify archetypes leveraging existing hospital relationships to cross-sell continuous monitoring capabilities. Omron Corporation anchors the consumer channel control archetype through pharmacy network dominance across Asia-Pacific markets. These three entities represent distinct strategic positions: clinical ecosystem integration, acute care device bundling, and retail distribution scale.
| Leading Market Players |
|---|
| Omron Corporation |
| Microlife Corporation |
| Philips |
| Baxter International |
| Cardinal Health |
| 3M Company |
| Terumo Corporation |
| American Diagnostic Corporation |
| A&D Company Limited |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's freight volatility cascades through thermistor component economics, amplifying price spreads between clinical-grade precision sensors and commodity alternatives while hospital procurement teams in Germany and Japan negotiate cloud-analytics bundling to offset hardware margin compression.
Pricing Analysis
Aftermarket calibration contracts anchor lifetime value capture as manufacturers abandon per-unit transactional models for subscription-based remote monitoring platforms. Pricing stratifies across FDA 510(k)-certified premium tiers, EU MDR-compliant mid-market bundles, and economy digital thermometers serving pharmacy retail networks. Cost compression in disposable probe covers intensifies because infection control mandates drive single-use volumes without proportional margin expansion. Ambulatory care centers exhibit acute price sensitivity, while intensive care units absorb premium positioning for continuous wireless surveillance infrastructure.
Supply Chain Analysis
Export control restrictions on precision thermistor manufacturing equipment constrain capacity expansion outside established East Asian component hubs, tethering device makers to concentrated supply sources. Manufacturing clusters in Japan, South Korea, and coastal China dominate clinical-grade sensing element production, drawing from specialized ceramic substrate feedstocks and thin-film deposition equipment. Single-source vulnerability pervades neonatal-grade adhesive patch assemblies where biocompatible substrate qualification timelines extend certification cycles. Distribution runs through hospital group purchasing organizations in the United States and statutory health insurance procurement frameworks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated delivery network consolidation across the United States and Germany has shifted procurement leverage toward centralized purchasing committees, compressing vendor margins while elevating platform-scale contract requirements.
For Market Incumbents: Harden cloud infrastructure interoperability to defend against emerging AI-native surveillance platforms threatening Philips and Baxter International's ecosystem lock-in. Deepen backward integration into thermistor calibration equipment production within Baden-Württemberg's precision engineering corridor. Prioritize PMDA parallel certification investment to preempt Japanese market access barriers for multi-parameter wearable rollouts.
For New Entrants and Emerging Players: Pursue nursing home wireless sensor deployment as the most penetrable segment, where staffing shortages in Japan and Germany accelerate automated monitoring adoption without incumbent platform entrenchment. Target direct-to-consumer pharmacy channel partnerships in South Korea and Singapore, leveraging post-pandemic occupational health protocol persistence. Lead with mobile application-enabled home-use devices bypassing traditional hospital procurement cycles entirely.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial electronics parents with dormant medical-grade thermopile sensor divisions capable of rapid FDA 510(k) pathway navigation. Long-term viability hinges on subscription revenue recurrence rather than hardware shipment volumes. Watch for MFDS harmonization announcements with FDA benchmarks as inflection indicators reducing export certification friction for acquisition targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Cloud analytics bundling with integrated delivery networks secures multi-year recurring revenue streams. |
| CE Marking Pathway | EU MDR post-market surveillance compliance accelerates consolidation among smaller device manufacturers. |
| Software Companion Development | AI-enhanced sepsis detection algorithms differentiate platform offerings in acute care settings. |
| Reimbursement Strategy | Germany's statutory telemonitoring coverage expansion enables patient-paid segment bypass. |
| Backward Integration | In-house thermistor calibration equipment production mitigates East Asian supply concentration risk. |
Research Methodology
A spread of perspectives from hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs directors converged on the working assumptions underpinning demand projections. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up device shipment modeling triangulated against top-down healthcare expenditure allocation analysis.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling spanning product type, application setting, end-user procurement authority, and deployment architecture. CAGRs derived from historical adoption curve analysis and reimbursement policy trajectory assessment. Forecast inputs incorporated PMDA certification timeline friction and cloud infrastructure penetration rates in German statutory health insurance networks.
Sensitivities concentrate around FDA guidance evolution on wearable form factors and thermistor supply chain disruption scenarios. Forecasts reflect documented assumptions regarding continuous surveillance protocol displacement of spot-checking in intensive care. Material shifts in EU MDR post-market surveillance enforcement intensity or Japan's thermal sensor accuracy standard harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
United Kingdom Patient Monitoring Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
Urine Output Monitoring Systems Market
Patient Monitoring
Transcutaneous Monitors Market
Patient Monitoring
Digital Patient Monitoring Devices Market
Patient Monitoring
Heart Monitoring Devices Market
Patient Monitoring
Compartment Syndrome Monitoring Devices Market
Patient Monitoring
Europe Biomedical Sensors Market
Patient Monitoring
Multi-Channel Remote ECG Monitors Market
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
Digital Patient Monitoring Systems Market
Patient Monitoring
Remote Patient Monitoring Software Market
Patient Monitoring
Europe Cardiac Holter Monitor Market
Patient Monitoring
Wearable ECG Monitors Market
Patient Monitoring
Global Patient Positioning System Market