
 Ovulation Test Kit Market | 2026-2036
Ovulation Test Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Ovulation Test Kit Market Outlook
Pharmacy shelf space allocation is reconfiguring as retailers prioritize high-margin digital ovulation products over legacy strip formats. Clearblue leverages its brand strength to command premium positioning in European pharmacy chains. Wondfo competes aggressively on manufacturing scale, supplying private-label hormone detection strips to multiple retail banners. Easy@Home anchors its position through direct-to-consumer online retail, bypassing traditional wholesale markups entirely.
An ovulation test kit is a diagnostic device that detects luteinizing hormone or estrogen metabolites in urine or saliva to predict fertile windows, typically achieving sensitivity thresholds of 20-40 mIU/mL for clinical reliability. These kits serve both individual consumers tracking conception timing and fertility clinics optimizing treatment cycles. Digital kits now lead value generation through Bluetooth-enabled app synchronization and cycle-history algorithms that command premium pricing. Strip tests sustain volume dominance in emerging markets where cost sensitivity drives purchasing decisions. App-based kits represent the fastest-growing segment as smartphone penetration integrates fertility tracking into broader digital health ecosystems.
The FDA regulates ovulation test kits as Class II medical devices requiring 510(k) premarket notification, while the EU Medical Device Regulation imposes stricter clinical evidence standards for digital fertility platforms seeking CE marking. China's NMPA enforces GB standard compliance for domestic hormone detection product manufacturing, creating divergent certification burdens for multinational suppliers. Stakeholders must monitor evolving software-as-medical-device classifications that could reclassify app-connected fertility tools under enhanced regulatory scrutiny.
Market Dynamics
The transition from visual strip interpretation to algorithm-driven fertility prediction is compressing price premiums and redistributing margin pools across the value chain.
Growth Catalysts
- Smartphone penetration in fertility tracking:Bluetooth-enabled kits synchronize cycle data with health apps, creating recurring engagement platforms that extend customer lifetime value beyond the initial purchase.
- FDA 510(k) pathway efficiency:Streamlined premarket notification for Class II diagnostic devices accelerates time-to-market for algorithm-enhanced ovulation predictors relative to pharmaceutical fertility interventions.
- Reimbursement expansion for fertility diagnostics:Employer-sponsored fertility benefits and HSA eligibility for diagnostic kits in the United States broaden addressable consumer segments beyond out-of-pocket purchasers.
Market Restraints
- Monoclonal antibody supply concentration:Sensitivity-optimized LH detection reagents depend on biologics manufacturing clusters in China and South Korea, creating input vulnerability for strip-based producers.
- EU MDR clinical evidence burden:Digital fertility platforms seeking CE marking face expanded requirements for algorithm validation and post-market surveillance, extending certification timelines.
- Salivary ferning microscopy substitution:Low-cost optical fertility tracking methods compete at the economy tier, particularly in price-sensitive emerging markets where smartphone camera access is universal.
Strategic Opportunities
- Underpenetrated rural India:ASHA worker networks and Jan Aushadhi pharmacy expansion create last-mile distribution infrastructure for affordable hormone detection strips.
- Polycystic ovary syndrome monitoring:Irregular cycle algorithms address an underserved application beyond standard fertile window prediction, opening clinical partnerships with endocrinology practices.
- Software-as-medical-device reclassification clarity:FDA guidance on app-connected diagnostic tools creates regulatory certainty that enables investment in AI-enhanced cycle prediction engines.
Industry Challenges
- Biostatistician talent scarcity:Algorithm development for cycle prediction requires specialized expertise in reproductive endocrinology data modeling, with limited talent pools concentrated in Boston and Basel clusters.
- Legacy ERP integration friction:Fertility clinic customers demand seamless data export into electronic health record systems, requiring costly interoperability certification for digital kit manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ovulation Test Kit Market |
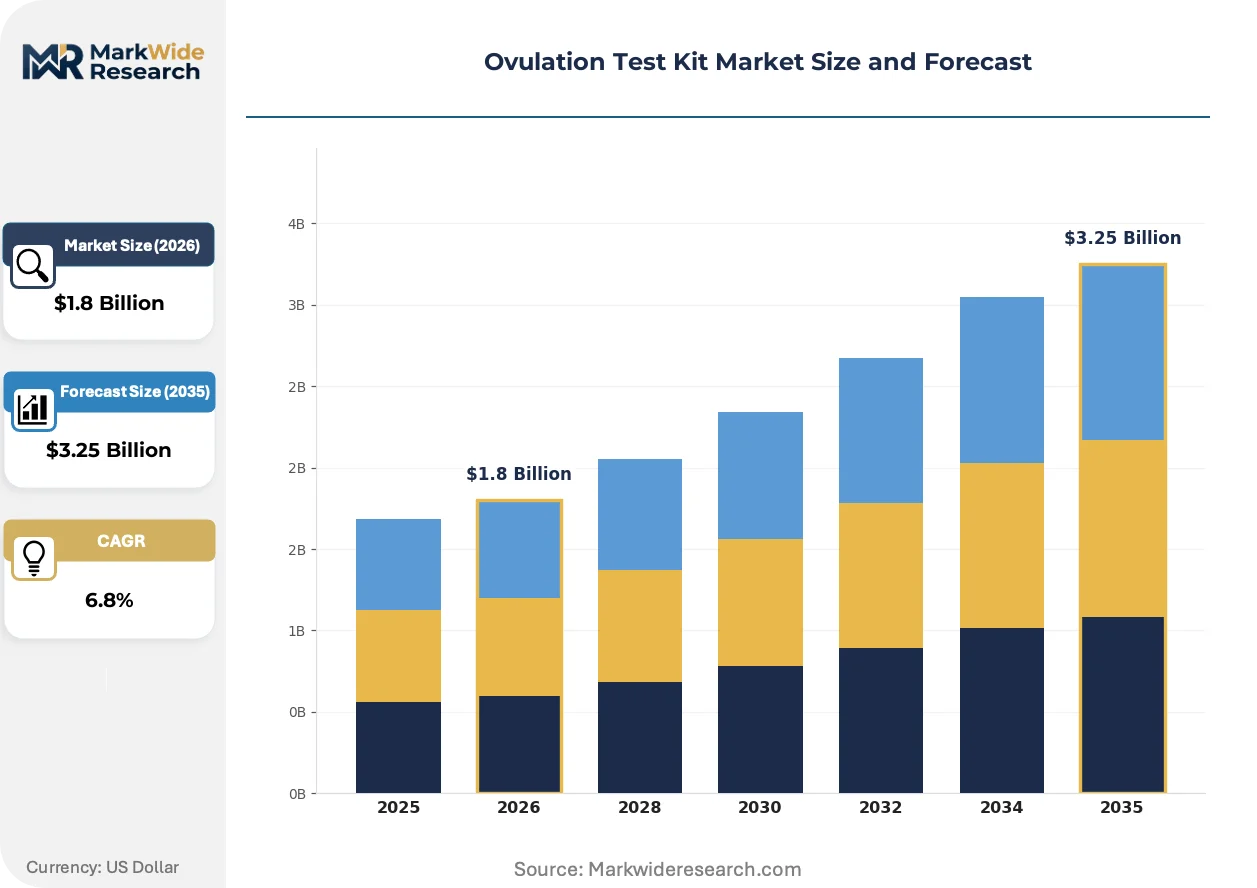
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Kits, App-Based Kits, Strip Tests, Midstream Tests Distribution Channel: Pharmacies, Online Retail, Supermarkets, Direct Sales Customer Type: Individuals, Couples, Fertility Clinics, Healthcare Providers Technology: Hormone Detection, Urine-Based, Saliva-Based, Colorimetric |
| Companies Covered | Easy@Home, Pregmate, Clearblue, Fairhaven Health, Swiss Precision Diagnostics GmbH, First Response, Proov, Piramal Pharma Ltd, Wondfo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ovulation Test Kit Market Strategic Shifts
Connected diagnostic hardware is transforming ovulation testing from a discrete purchase into a subscription-compatible data service, with implications for pricing architecture and customer retention mechanics.
Continuous hormone monitoring patches using electrochemical biosensors are rendering obsolete the single-point urine test model that has dominated fertility tracking for three decades. Early adopters in concierge fertility medicine and Silicon Valley employer wellness programs are piloting these wearable alternatives. The technology is compressing the addressable market for conventional strip manufacturers while opening premium service tiers that integrate real-time data with telemedicine consultations.
The EU Medical Device Regulation's software classification criteria are forcing digital fertility platforms to maintain clinical evidence portfolios that match pharmaceutical-grade standards. Manufacturers must now document algorithm performance across diverse demographic cohorts before CE marking approval. Platforms targeting the German and French markets are responding by establishing in-country clinical investigation sites and post-market surveillance systems.
Direct-to-consumer subscription models are displacing pharmacy-centric purchasing for repeat-cycle users, with automated replenishment timed to individual cycle lengths. This channel shift concentrates customer data with platform operators rather than retail intermediaries, enabling personalized cross-selling of prenatal supplements and fertility services. The United States exhibits the most pronounced migration, though UK and Australian markets are following comparable trajectories.
Ovulation Test Kit Market Segmentation
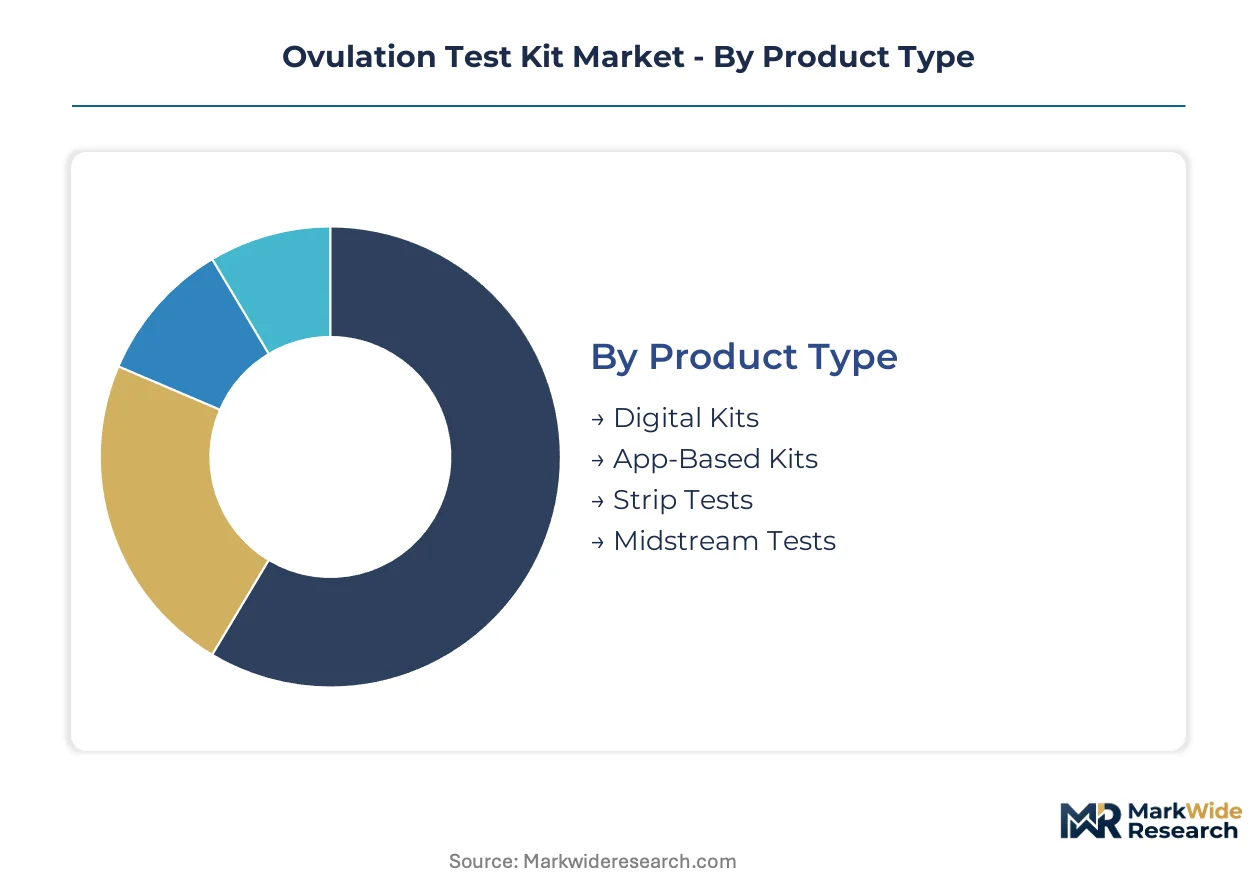
Ovulation test kit segmentation reveals divergent purchase cycles across product formats and customer types. Digital platforms extract recurring revenue through subscription replenishment while strip formats depend on pharmacy foot traffic velocity.
Product Type:
Strip tests turn over fastest through mass retail impulse purchasing. Digital kits lock in multi-cycle commitment through app synchronization. App-based platforms accelerate fastest as smartphone fertility tracking normalizes. Midstream formats hold intermediate velocity through pharmacy channel placement.
- Digital Kits:Bluetooth-enabled hardware pairs with cycle-tracking algorithms to store historical fertility data and predict ovulation windows. Demand concentrates in employer-sponsored fertility benefit programs across the United States where HSA reimbursement eligibility reduces effective purchase price. FDA 510(k) premarket notification requirements shape product development timelines for algorithm-enhanced features.
- App-Based Kits:Smartphone-connected platforms synchronize hormone detection results with cloud-based cycle analytics and telemedicine integration. Expansion concentrates in Germany and France where EU MDR software classification drives clinical evidence investment for CE marking. German fertility platforms now maintain post-market surveillance systems matching pharmaceutical-grade standards.
- Strip Tests:Visual interpretation strips using monoclonal antibody LH detection reagents dominate volume in emerging markets.
- Midstream Tests:Integrated cassette formats with built-in control lines serve pharmacy-centric purchasing in European markets.
Strip tests dominate installed base. App-based kits are where expansion concentrates.
Distribution Channel:
Online retail commands the widest margin spread between premium digital kits and economy strip bundles. Pharmacy channels sustain highest absolute volume through prescription-adjacent placement. Direct sales compress distributor markups for fertility clinic procurement. Supermarket placement drives impulse conversion for midstream formats.
- Pharmacies:Physical retail locations with trained staff consultation support premium product positioning and reimbursement documentation. Shelf space reallocation in UK and German chains favors high-margin digital formats over legacy strips.
- Online Retail:Direct-to-consumer platforms enable subscription replenishment timed to individual cycle lengths. United States consumers migrate fastest to automated delivery models that concentrate customer data with platform operators.
- Supermarkets:Mass retail placement captures economy-tier purchasing with minimal staff intervention.
- Direct Sales:Fertility clinic procurement contracts bypass retail markups for high-volume hormone detection strip purchasing.
Pharmacies dominate installed base. Online retail is where expansion concentrates.
Customer Type:
Fertility clinics generate the most predictable recurring demand through standardized treatment protocols. Individual purchasers exhibit highest price elasticity and channel-switching behavior. Couples represent intermediate commitment with shared app access driving digital adoption. Healthcare providers outside fertility specialization show sporadic diagnostic purchasing patterns.
- Fertility Clinics:Specialized reproductive medicine practices require LH detection sensitivity thresholds of 20-40 mIU/mL for treatment cycle optimization. Clinic procurement in Boston and Basel clusters demands seamless EHR interoperability certification from digital kit manufacturers.
- Individuals:Single-user purchasers tracking conception timing drive volume in emerging markets where cost sensitivity shapes strip format dominance. ASHA worker networks in rural India extend last-mile access to affordable hormone detection.
- Couples:Shared fertility tracking accounts synchronize partner access to cycle predictions and appointment scheduling.
- Healthcare Providers:General practice and gynecology clinics purchase diagnostic kits for patient education and preliminary fertility assessment.
Individuals dominate installed base. Fertility clinics are where expansion concentrates.
Technology:
Hormone detection platforms concentrate manufacturing scale in Chinese biologics clusters. Urine-based methods retain volume leadership through established supply chains. Saliva-based alternatives compete at economy tier where smartphone camera access enables optical ferning interpretation. Colorimetric strips sustain lowest production cost position.
- Hormone Detection:Monoclonal antibody-based LH and estrogen metabolite quantification achieves clinical reliability thresholds required for fertility treatment protocols. Manufacturing concentration in China and South Korea creates input vulnerability for strip-based producers dependent on biologics supply chains.
- Urine-Based:Single-point urine sampling with lateral flow immunoassay technology dominates established product formats. China's NMPA enforces GB standard compliance for domestic manufacturing of urine hormone detection products.
- Saliva-Based:Optical microscopy of salivary ferning patterns substitutes for chemical detection in price-sensitive markets.
- Colorimetric:Visual dye reaction strips represent the lowest technology tier with minimal electronic component requirements.
Urine-based technology dominates installed base. Hormone detection platforms are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer-sponsored fertility benefits in the United States and Germany's reimbursement expansion for reproductive diagnostics are accelerating kit adoption beyond out-of-pocket purchasing. China's NMPA enforcement of GB standards for domestic hormone detection manufacturing is reshaping supply chain geography. India's Jan Aushadhi pharmacy network is extending last-mile access to affordable diagnostic strips.
United States
Employer-sponsored fertility benefits and HSA eligibility for diagnostic kits broaden consumer segments beyond cash purchasers. The FDA's 510(k) premarket notification pathway for Class II devices accelerates algorithm-enhanced product launches relative to pharmaceutical alternatives. Boston's reproductive medicine cluster demands seamless EHR interoperability from digital kit suppliers.
Germany
EU MDR software classification drives clinical evidence investment for CE marking of digital fertility platforms. The country's statutory health insurance system is expanding reimbursement coverage for fertility diagnostics. Berlin and Munich host post-market surveillance systems matching pharmaceutical-grade standards for algorithm-validated products.
China
Domestic manufacturers scale production of hormone detection technologies as NMPA enforces GB standard compliance. Dual carbon goals pressure biologics manufacturing clusters toward cleaner production methods. Shenzhen and Guangzhou concentrate private-label strip supply to international retail banners.
India
ASHA worker networks and Jan Aushadhi pharmacy expansion create last-mile distribution for affordable hormone detection strips. The country's national pharmaceutical regulator maintains quality standards for imported and domestic diagnostic products. Maharashtra and Gujarat host contract manufacturing facilities serving regional demand.
United Kingdom
Pharmacy shelf space reallocation favors high-margin digital formats over legacy strips in Boots and Lloyds chains. MHRA post-Brexit regulatory autonomy is diverging from EU MDR timelines for software-as-medical-device classifications. London's fertility clinic concentration drives demand for Bluetooth-enabled cycle tracking platforms.
Ovulation Test Kit Market Competitive Environment
On the supply side, the industry is bifurcated between premium digital platform operators and high-volume strip manufacturers serving price-sensitive segments. Three archetypes dominate: brand-owned algorithm developers, contract manufacturers supplying private-label retail banners, and direct-to-consumer subscription platforms. Competitive moves concentrate on strategic partnerships with fertility clinic networks and geographic expansion through regulatory pathway optimization.
Within the premium digital tier, Clearblue and Swiss Precision Diagnostics GmbH exemplify brand strength commanding pharmacy chain positioning. Wondfo occupies a position as a scale-driven contract manufacturer supplying multiple retail banners from Chinese production bases. Easy@Home anchors the direct-to-consumer archetype through online retail bypassing wholesale markups entirely.
| Leading Market Players |
|---|
| Easy@Home |
| Pregmate |
| Clearblue |
| Fairhaven Health |
| Swiss Precision Diagnostics GmbH |
| First Response |
| Proov |
| Piramal Pharma Ltd |
| Wondfo |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in South Korean monoclonal antibody production is pushing strip manufacturers toward Chinese biologics clusters, compressing input costs for economy-tier producers while digital kit makers absorb premium pricing for Bluetooth module supply security.
Pricing Analysis
Volume-discount tiering separates subscription-replenishment digital platforms from per-unit strip transactions. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) certification grade and algorithm sophistication. Cost compression in strip formats is intensifying because Wondfo's manufacturing scale anchors private-label supply contracts. Fertility clinics show lowest price sensitivity due to reimbursement pass-through, while individual purchasers in emerging markets drive economy-tier volume.
Supply Chain Analysis
Contract-manufacturing concentration rests with Shenzhen and Guangzhou biologics clusters for antibody reagents, plus South Korean foundries for sensor components. Raw material dependencies center on monoclonal antibodies, lateral flow membranes, and lithium coin cells for Bluetooth hardware. Single-source vulnerability in Chinese biologics supply creates exposure to NMPA enforcement actions. Distribution runs through pharmacy wholesale networks in Europe and direct-to-consumer platforms in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in employer-sponsored fertility benefits is accelerating kit adoption beyond traditional out-of-pocket purchasing, creating runway for algorithm-enhanced platform growth.
For Market Incumbents: Harden algorithm differentiation through reproductive endocrinology data partnerships in Boston and Basel clusters. Deepen backward integration into monoclonal antibody supply through captive biologics manufacturing in Guangzhou. Defend against salivary ferning microscopy substitution by embedding telemedicine consultation bundles into premium digital subscriptions.
For New Entrants and Emerging Players: Rural India through ASHA worker networks represents the most penetrable entry point for affordable hormone detection strips. Polycystic ovary syndrome monitoring algorithms for endocrinology practices open clinical white-space beyond standard fertile window prediction. Go-to-market through Jan Aushadhi pharmacy partnerships bypasses established wholesale markups.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across app-connected diagnostic platforms requiring EU MDR clinical evidence portfolios. Long-term viability favors acquirers of algorithm-validated fertility tracking engines with post-market surveillance infrastructure. Watch FDA software-as-medical-device guidance clarity as the signal for AI-enhanced cycle prediction investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Bluetooth-Enabled Hardware Launch | Locks in multi-cycle customer commitment through app synchronization and HSA reimbursement eligibility. |
| EU MDR CE Marking Pathway | Opens German and French statutory insurance reimbursement for algorithm-validated fertility platforms. |
| Fertility Clinic Partnership | Secures predictable recurring demand through EHR interoperability certification in Boston reproductive medicine clusters. |
| Direct-to-Consumer Subscription | Concentrates customer data with platform operators for prenatal supplement cross-selling in United States markets. |
| Backward Integration into Biologics | Reduces monoclonal antibody supply vulnerability from South Korean and Chinese manufacturing concentration. |
Study Parameters
A spread of perspectives from reproductive endocrinologists, fertility clinic procurement managers, digital health platform engineers, and pharmacy category buyers converged on the working assumptions. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and NMPA GB standard compliance registries. Bottom-up demand modeling and top-down market sizing triangulated volume estimates across the analysis window.
Demand-supply-balance framing anchored the analytical approach across product type, distribution channel, customer segment, and technology platform dimensions. CAGRs derived from segment-level growth trajectory synthesis with smartphone fertility tracking penetration curves and reimbursement expansion timelines as key inputs. Algorithm development cost curves and biologics manufacturing capacity utilization shaped supply-side constraints.
Practitioners should monitor FDA software-as-medical-device reclassification signals and EU MDR post-market surveillance enforcement for early revision triggers. Cross-checking against employer fertility benefit adoption rates reported by benefits consultants is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Nicotine Testing Market
Testing Services
Global C-Reactive Protein Testing Market
Testing Services
Asia-Pacific Viral Clearance Market
Testing Services
Global Metabolic Testing Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
Blood Borne Testing Market
Testing Services
Friability Tester Market
Testing Services
Global Homocysteine Testing Market
Testing Services
Global Urinalysis Test Market
Testing Services
Dengue Testing Market
Testing Services
Global Enteric Disease Testing Market
Testing Services
Rapid Hepatitis Testing Market
Testing Services
Rapid Test Cards Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Medical Device Analytical Testing Outsourcing Market
Testing Services
Infusion Toxicology Services Market