
 Microparticle Injectables Market | 2026-2036
Microparticle Injectables Market Size, Share, and Industry Trends Forecast 2026-2036
Microparticle Injectables Market Foresight
Modular kit configurations is decoupling drug-device combinations from traditional bundled procurement, letting buyers select microparticle formulations and delivery systems independently. Pfizer leverages its sterile manufacturing footprint across multiple geographies to sustain supply security for complex parenteral products. Johnson & Johnson anchors its position through vertically integrated biologics capabilities that span active pharmaceutical ingredient synthesis through finished injectable production. Teva Pharmaceutical Industries Ltd competes on cost-optimized biosimilar microparticle platforms that target high-volume therapy categories.
Microparticle injectables comprise biodegradable polymer matrices, typically poly(lactic-co-glycolic acid) or polycaprolactone, engineered to encapsulate active pharmaceutical ingredients and release them over controlled durations ranging from days to months. These systems enable sustained therapeutic plasma levels, reduce dosing frequency, and improve patient compliance in chronic disease management. The oncology therapy area leads value generation due to high-margin cytotoxic and immunotherapy payloads requiring targeted depot release. Subcutaneous delivery mode exhibits the fastest structural expansion as self-administration trends shift administration sites from clinical settings to home healthcare environments. Hospitals remain the dominant end user channel, though home healthcare captures disproportionate growth momentum driven by reimbursement incentives for reduced clinical visits.
FDA current good manufacturing practice requirements and EMA's Annex 1 sterile product guidelines dictate validation protocols for aseptic microparticle processing, directly shaping capital deployment timelines for manufacturing expansion. ISO 13485 quality management standards and USP general chapters on particulate matter constrain formulation design space and compel analytical method investments. WHO prequalification pathways for combination products further complicate market access for manufacturers targeting procurement programs in lower-income settings. Stakeholders must monitor evolving regulatory convergence between pharmaceutical and medical device frameworks as combination product classifications proliferate.
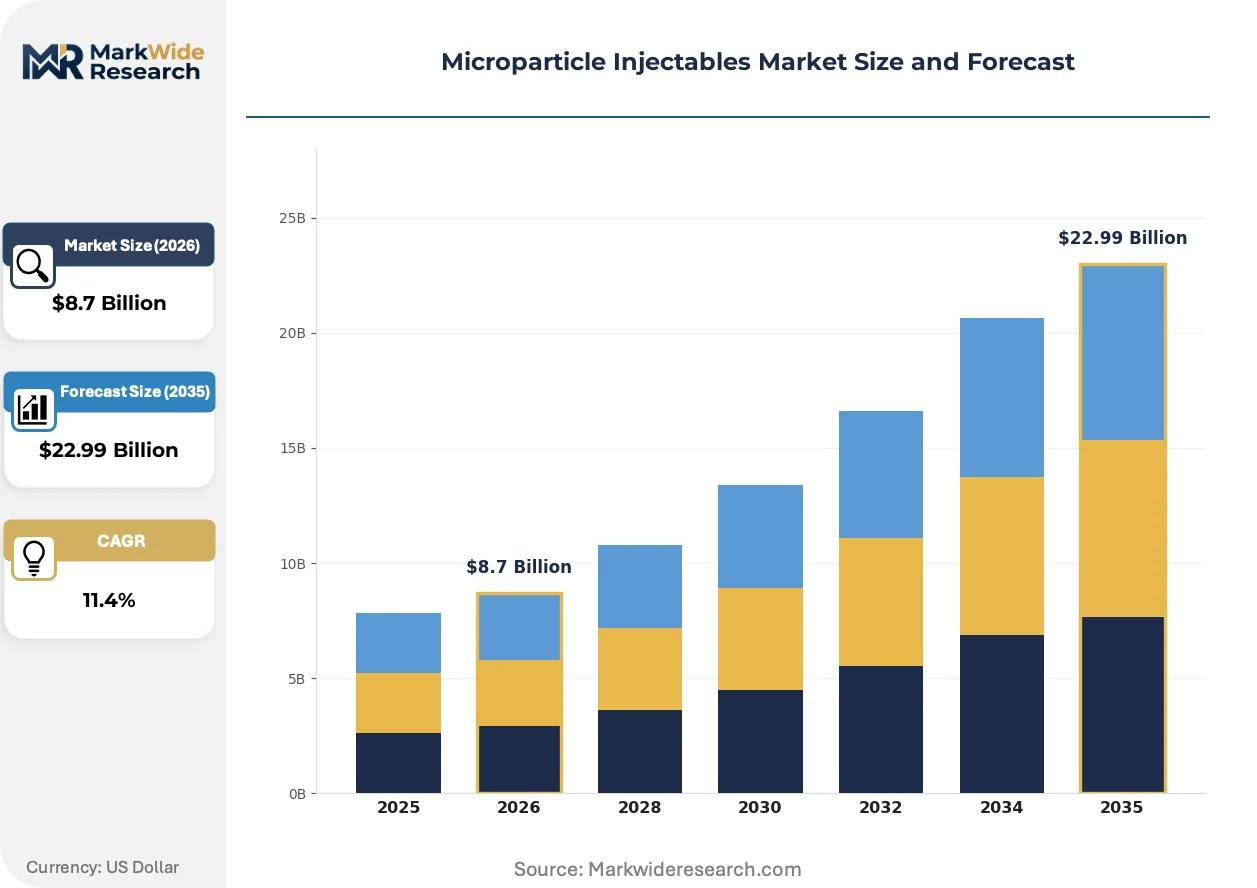
Market Dynamics
Modular drug-device procurement is decoupling formulation selection from delivery system bundling, forcing manufacturers to compete on microparticle engineering performance rather than captive device ecosystems.
Growth Catalysts
- EMA Process Analytical Technology:The framework accelerates validated manufacturing investments by enabling real-time quality verification, reducing batch release timelines for sterile microparticle production.
- Subcutaneous self-administration:Home healthcare environments are absorbing administration volume previously confined to infusion centers, expanding addressable patient populations for depot formulations.
- PLGA polymer matrices:Tunable degradation kinetics enable customized release profiles spanning days to months, matching therapeutic windows for chronic disease management.
Market Restraints
- Lactide-glycolide monomer supply:Petrochemical feedstock volatility transmits directly to PLGA raw material costs, compressing margin structures for generic depot formulations.
- Aseptic fill-finish infrastructure:Sterile manufacturing capacity concentrates in the United States, Germany, and Japan, creating geographic supply vulnerability for emerging market access.
- FDA combination product classification:Overlapping pharmaceutical and device jurisdiction extends regulatory review timelines, delaying market entry for novel microparticle-device pairings.
Strategic Opportunities
- Brazil oncology access:ANVISA streamlined review pathways for complex parenterals create first-mover advantage for depot chemotherapy formulations in Latin America's largest therapeutic market.
- WHO prequalification:Procurement program eligibility for combination products opens institutional volume in lower-income settings currently served by conventional injectables.
- Continuous manufacturing:Microfluidic polymer precipitation converges with process analytical technology to enable real-time release, collapsing batch cycle times from weeks to hours.
Industry Challenges
- Sterile process engineering talent:Aseptic microparticle processing requires cross-trained personnel fluent in both polymer science and current good manufacturing practice, with acute scarcity outside established manufacturing clusters.
- ISO 13485 quality system integration:Dual pharmaceutical and medical device certification demands parallel documentation streams, extending quality management system implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microparticle Injectables Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Hormones, Antibodies, Enzymes Delivery Mode: Intramuscular, Subcutaneous, Intravenous, Intra-articular Therapy Area: Oncology, Immunology, Rheumatology, Endocrinology End User: Hospitals, Clinics, Research Laboratories, Home Healthcare |
| Companies Covered | Teva Pharmaceutical Industries Ltd, Pfizer Inc, Johnson & Johnson, Amgen, Sanofi, Lubrizol Life Science, Baxter International Inc, Evonik, Oakwood Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microparticle Injectables Market Shifts & Advancements
Biodegradable polymer engineering and regulatory convergence are compressing development timelines while expanding administration settings beyond traditional clinical infrastructure.
Microfluidic polymer precipitation is overtaking conventional batch emulsion methods for microparticle fabrication. Biopharmaceutical process development groups are adopting continuous flow platforms at pilot scale. The technology is overtaking legacy solvent extraction approaches by enabling tighter particle size distribution control and reducing organic solvent residuals.
EMA Annex 1 sterile product guidelines mandate barrier technology and isolator-based processing for aseptic manufacturing. European manufacturers are retrofitting cleanroom infrastructure to comply with 2022 revision requirements. Oncology depot formulations face the steepest compliance investment burden due to cytotoxic handling protocols and environmental containment specifications.
Self-administration training programs are displacing clinical-staff-dependent injection models for subcutaneous depot therapies. Home healthcare agencies and specialty pharmacies are capturing patient education and adherence monitoring functions previously performed in hospital infusion centers. The United States exhibits the most pronounced channel migration, driven by reimbursement differentials favoring reduced site-of-care costs.
Microparticle Injectables Market Segmentation
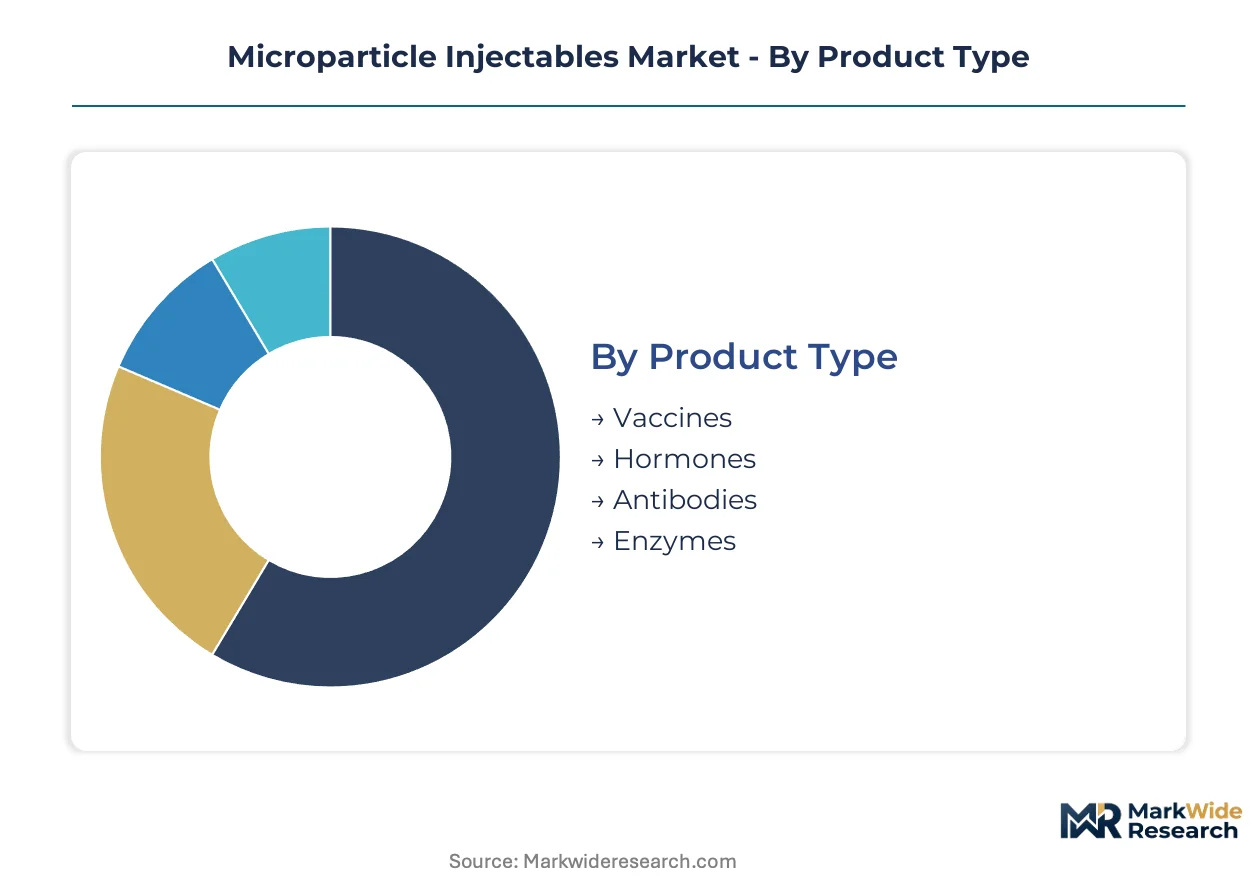
Microparticle injectables demand fragments across formulation chemistry, administration anatomy, therapeutic indication, and care setting. Each segmentation axis carries distinct regulatory, reimbursement, and supply chain implications that reshape competitive priorities.
Product Type:
Standalone depot formulations operate independently of device ecosystems, while embedded microparticle systems integrate with prefilled syringes or auto-injectors.
- Vaccines:PLGA-encapsulated antigens enable single-dose priming with extended immune stimulation, reducing cold-chain burden for national immunization programs in India and Brazil. Demand clusters around pediatric prophylaxis and emerging infectious disease preparedness, with WHO prequalification serving as the critical procurement gate.
- Hormones:Polycaprolactone matrices sustain testosterone or estrogen release over months, anchoring compliance in gender-affirming care and hypogonadism management. Subcutaneous depot placement in home healthcare settings is displacing intramuscular clinic administration across Germany and Japan.
- Antibodies:Monoclonal payloads in biodegradable scaffolds target oncology maintenance therapy with reduced infusion frequency.
- Enzymes:Encapsulated replacement therapies address lysosomal storage disorders with controlled enzymatic release kinetics.
Volume placements concentrate in Vaccines; the faster expansion belongs to Hormones.
Delivery Mode:
Cost tiering separates invasive hospital-based administration from self-administered subcutaneous alternatives, with reimbursement differentials widening the gap.
- Intramuscular:Deep depot placement in deltoid or gluteal muscle suits large-volume suspensions and slow-release vaccines requiring professional administration. United States hospital systems absorb the bulk of placement volume for oncology supportive care and long-acting antipsychotics.
- Subcutaneous:Abdominal or thigh self-injection of small-volume microparticle suspensions collapses site-of-care costs and expands patient eligibility. Home healthcare agencies in the United States and specialty pharmacies in Germany are capturing training and adherence monitoring functions.
- Intravenous:Systemic distribution of nanoparticle-scale formulations targets acute oncology indications.
- Intra-articular:Direct joint cavity deposition of corticosteroid-loaded microparticles addresses localized rheumatoid inflammation.
Intramuscular placements dominate current volume; Subcutaneous modes are climbing the fastest as self-administration infrastructure matures.
Therapy Area:
Application maturity varies from established endocrine maintenance to experimental immuno-oncology combinations, with regulatory burden scaling with therapeutic novelty.
- Oncology:Cytotoxic and immunotherapy payloads in PLGA matrices enable localized tumor depot or systemic sustained release, commanding premium pricing due to high-value biologic cargo and sterile handling complexity. EMA Annex 1 compliance investments concentrate here due to cytotoxic containment requirements.
- Immunology:Tolerogenic microparticles delivering autoantigen peptides are advancing through clinical pipelines for multiple sclerosis and type 1 diabetes, with PMDA in Japan accelerating review for breakthrough-designated candidates.
- Rheumatology:Corticosteroid and biologic depots extend joint injection intervals in osteoarthritis and inflammatory arthropathies.
- Endocrinology:Long-acting GLP-1 and insulin analog formulations in polymer matrices address diabetes and obesity with reduced injection burden.
Oncology anchors revenue concentration; Immunology applications are gaining share fastest on pipeline momentum.
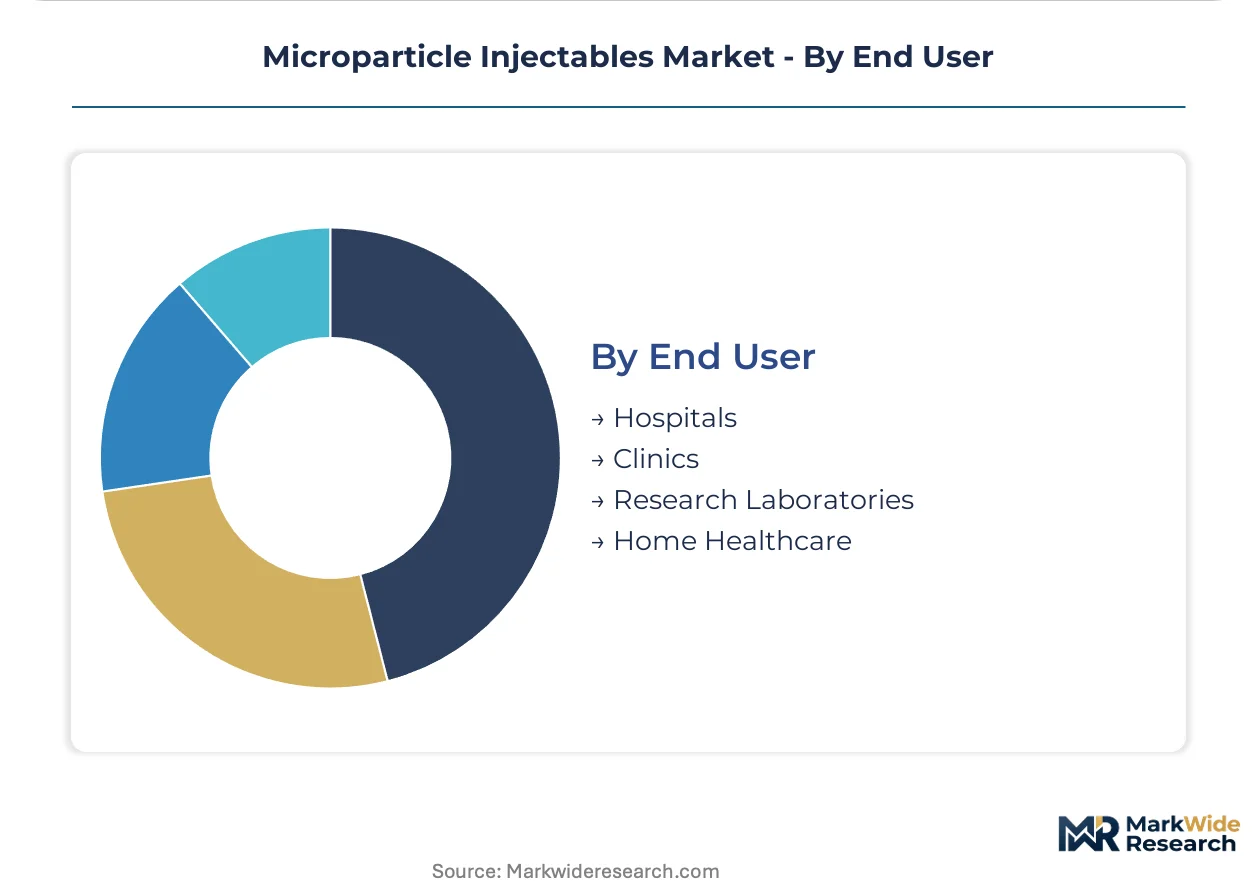
End User:
Customer type determines sterility assurance level, batch size economics, and reimbursement pathway complexity.
- Hospitals:Infusion centers and oncology units handle complex parenteral compounding, cytotoxic handling, and adverse event monitoring for high-risk depot therapies. Sterile fill-finish infrastructure clusters in tertiary systems across the United States, Germany, and Japan.
- Home Healthcare:Nursing services and specialty pharmacies manage patient training, cold-chain logistics, and adherence tracking for self-administered subcutaneous depot products. United States reimbursement incentives for reduced site-of-care costs are accelerating channel migration.
- Clinics:Ambulatory settings handle routine intramuscular depot administration for contraception and hormone replacement.
- Research Laboratories:Academic and contract research organizations pilot novel polymer formulations and release kinetics in preclinical and early-phase studies.
Hospitals retain the dominant placement volume; Home Healthcare exhibits the steepest expansion trajectory on self-administration adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized sterile fill-finish infrastructure clusters concentrate in designated pharmaceutical manufacturing zones across multiple continents. Tax incentives for biopharma production in Singapore's Tuas Biomedical Park and Ireland's Shannon Free Zone accelerate capital deployment for aseptic microparticle processing.
United States
Oncology depot formulations and long-acting antipsychotics absorb the majority of domestic microparticle volume. FDA current good manufacturing practice requirements for combination products extend regulatory review timelines. The Greater Boston and San Francisco Bay Area clusters host contract development and manufacturing organizations scaling microfluidic polymer precipitation platforms.
Germany
Hormone replacement and immunology applications sustain demand for polycaprolactone-based depot systems. EMA Annex 1 sterile product guidelines mandate barrier technology retrofits for existing cleanroom infrastructure. The Rhine-Main and Upper Bavaria regions concentrate fill-finish capacity serving European Union distribution networks.
Japan
PMDA breakthrough-designated tolerogenic microparticles for autoimmune indications advance through priority review pathways. The national regulator accelerates timelines for depot formulations addressing multiple sclerosis and type 1 diabetes. The Kanto region around Tokyo anchors sterile manufacturing for domestic biopharmaceutical supply security.
Brazil
ANVISA streamlined review pathways for complex parenterals create procurement access for depot chemotherapy formulations. The national pharmaceutical regulator reduces administrative burden for oncology microparticle registrations. São Paulo state's pharmaceutical manufacturing corridor attracts first-mover investments for Latin American market entry.
India
WHO prequalification pathways for combination products open institutional procurement volume for PLGA-encapsulated vaccines. CDSCO manufacturing licensing requirements align with international standards for export-oriented production. The Hyderabad-Pune pharmaceutical belt scales sterile injectable capacity for emerging market supply.
Microparticle Injectables Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and delivery system integration. The market structure tilts toward consolidation at the top tier, with mid-scale players occupying niche therapeutic segments. Three archetypes dominate: vertically integrated biopharmaceutical majors, contract development and manufacturing organizations, and polymer science specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves as manufacturers secure aseptic processing capabilities.
Among diversified biopharmaceutical majors, Pfizer Inc and Johnson & Johnson occupy positions spanning active pharmaceutical ingredient synthesis through finished injectable production. Teva Pharmaceutical Industries Ltd exemplifies the generic-focused archetype competing on cost-optimized platform technologies. These three entities represent contrasting strategic postures: multinational scale with sterile manufacturing footprints, vertically integrated biologics capabilities, and biosimilar volume positioning respectively.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd |
| Pfizer Inc |
| Johnson & Johnson |
| Amgen |
| Sanofi |
| Lubrizol Life Science |
| Baxter International Inc |
| Evonik |
| Oakwood Labs |
| Others |
Supply & Pricing Matrix
Captive sterile fill-finish infrastructure in the United States, Germany, and Japan anchors both supply security and pricing power for microparticle injectables, with manufacturers who own aseptic processing assets commanding premium positioning against contract-dependent competitors facing capacity queues.
Pricing Analysis
Lead-time-driven pricing separates urgent clinical trial supply from scheduled commercial batches, with manufacturers extracting premiums for accelerated sterile processing slots while spot inventory of standard PLGA formulations trades at compressed margins. Three-tier pricing structure across GMP-certified premium, ISO-standard mid-tier, and prequalified economy levels tracks certification burden and regulatory file completeness. Pricing pressure stems from lactide-glycolide monomer cost volatility transmitting through polymer raw material inputs. Hospital procurement committees exhibit acute price sensitivity for oncology supportive care depots, while emerging market tenders for vaccine formulations prioritize unit cost minimization above technical performance.
Supply Chain Analysis
PLGA polymer feedstock rests on petrochemical-derived lactide and glycolide monomer production concentrated in China, Germany, and the United States, with specialty polymer synthesis capacity clustering around Evonik's German sites and select North American chemical processors. Critical dependencies include high-purity solvents for microparticle precipitation, medical-grade polymer resins, and isolator-based aseptic filling equipment. Single-source vulnerability concentrates in barrier technology components for EMA Annex 1 compliance retrofits. Distribution runs through cold-chain logistics networks terminating at hospital pharmacies, specialty distributors, and direct-to-site delivery for clinical trials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microparticle injectables market functions as a cost-of-compliance arena where FDA current good manufacturing practice requirements for combination products erect capital barriers that protect incumbent positions and compress returns for underinvested challengers.
For Market Incumbents: Deploy barrier technology retrofits as the anchor move, converting EMA Annex 1 compliance investments into customer lock-in through preferred supplier status at European oncology centers. Capture additional volume by acquiring distressed CDMO assets in the Rhine-Main cluster. Counter the threat of microfluidic continuous manufacturing entrants by filing process patents around real-time release analytics.
For New Entrants and Emerging Players: Microfluidic polymer precipitation platforms offer a technology-first wedge into the market, enabling 90% reduction in batch cycle times against legacy emulsion methods. Target Brazil's depot chemotherapy segment where ANVISA streamlined review pathways reduce time-to-revenue for first movers. Pursue WHO prequalification for combination products as the go-to-market angle, unlocking institutional procurement volume in India and lower-income settings.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified biopharmaceutical majors seeking sterile manufacturing capacity. Long-term viability hinges on sustained R&D productivity in tolerogenic microparticles for autoimmune indications. Watch PMDA breakthrough designation grants in Japan as the signal indicating pipeline maturation and valuation inflection for platform technology acquisitions.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Annex 1 Compliance Retrofit | Isolator-based processing investments satisfy 2022 revision requirements for European oncology depot manufacturing. |
| Microfluidic Platform Scale-Up | Continuous polymer precipitation collapses batch release timelines from weeks to hours for sterile microparticles. |
| WHO Prequalification Pathway | Combination product eligibility opens procurement volume for PLGA-encapsulated vaccines in emerging markets. |
| Subcutaneous Self-Administration Training | Patient education programs shift site-of-care costs from hospitals to home healthcare agencies. |
| ANVISA Registration Acceleration | Streamlined review pathways for complex parenterals reduce regulatory burden in Latin America's largest therapeutic market. |
Research Methodology
Independent corroboration across regulatory filing databases, sterile manufacturing facility inspections, and procurement contract disclosures underwrites the qualitative findings in this analysis. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and CDMO operations directors combined with secondary validation against FDA 483 observations, EMA GMP inspection reports, ClinicalTrials.gov entries, and WHO prequalification listings. Bottom-up capacity modeling and top-down therapeutic demand estimation triangulate volume estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including polymer chemistry, administration route, therapy area, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to base-year estimates, with cross-checks against announced manufacturing capacity expansions and disclosed clinical pipeline milestones for depot formulations.
Several conditions sit outside the modeled scope, including preclinical-stage tolerogenic microparticles without disclosed trial initiation dates and hypothetical regulatory convergence scenarios between pharmaceutical and medical device frameworks. Forecasts reflect documented assumptions about sterile manufacturing capacity utilization and reimbursement stability for subcutaneous administration. A small set of named triggers warrants ongoing watch: PMDA breakthrough designation decisions, ANVISA regulatory guidance revisions, and PLGA raw material supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Global Psoriasis Drugs Market
Pharmaceuticals
Gemcitabine HCL Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Monkeypox Vaccine and Treatment Market
Pharmaceuticals
PAP and Paracetamol Market
Pharmaceuticals
Capecitabine Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
BCL-2 (B-Cell Lymphoma 2) Inhibitors Market
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Intravitreal (IVT) Injectables Market
Pharmaceuticals
Global Antacids Market