
 Global Pharmaceuticals Market | 2026-2036
Global Pharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceuticals Market Outlook
A widening capital-intensity divergence between large-cap innovators and mid-tier generics manufacturers is rotating strategic investment toward biological manufacturing platforms. Pfizer leverages its global manufacturing footprint to sustain supply chain resilience across multiple therapy areas. Roche dominates oncology biologics through proprietary diagnostic-companion testing integration. Eli Lilly specializes in metabolic disease innovation, anchoring its pipeline around peptide-based therapeutics.
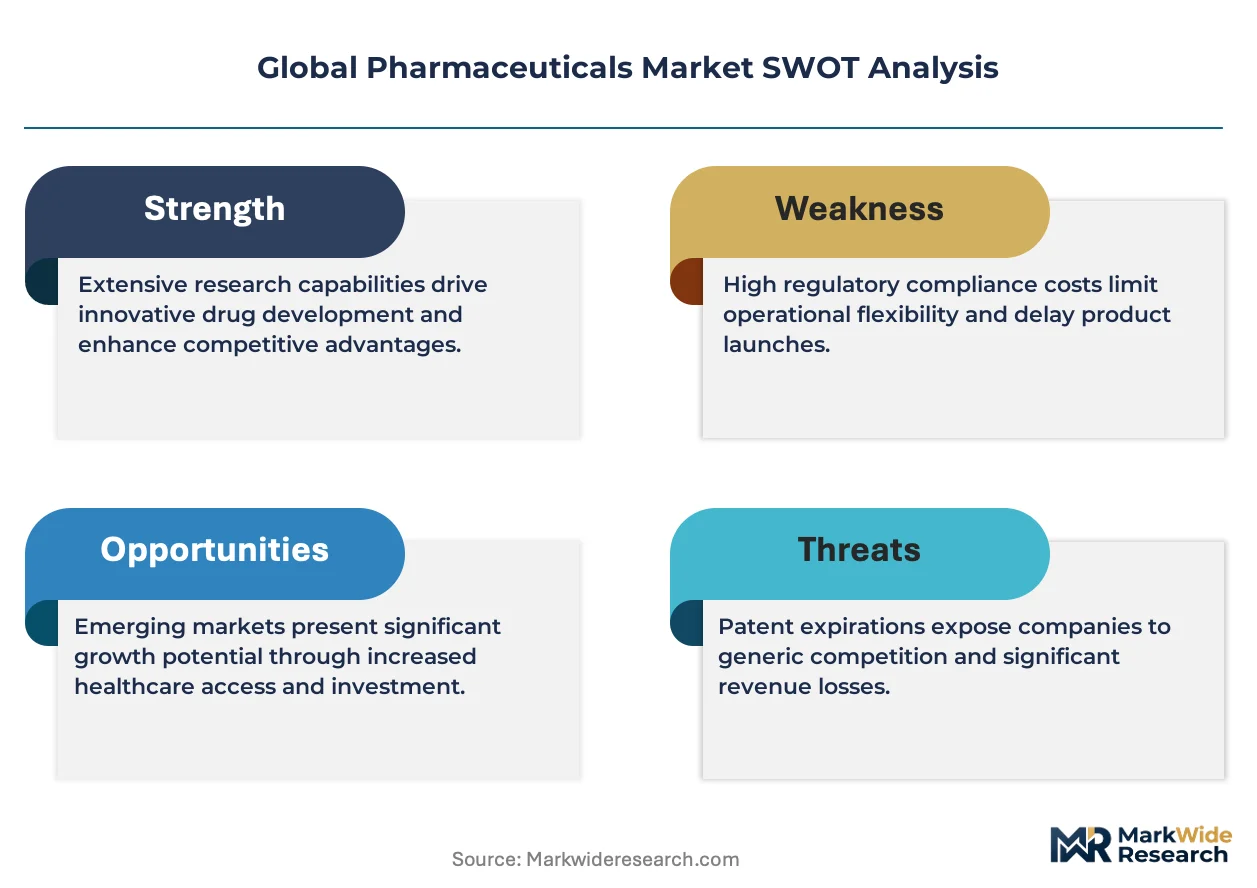
Global pharmaceuticals encompass chemically synthesized small molecules, recombinant proteins, monoclonal antibodies, nucleic acid therapies, and live attenuated or mRNA-based vaccines, formulated for oral, parenteral, topical, or pulmonary delivery to prevent, diagnose, or treat disease. Primary commercial purpose centers on improving patient survival and quality-adjusted life years while managing healthcare system cost burdens. Prescription drugs and biologics command the dominant value share as patent-protected specialty therapies capture concentrated margin pools, while vaccines represent the fastest-expanding category driven by mRNA platform proliferation and pandemic preparedness mandates. Oncology and immunology therapy areas attract disproportionate R&D allocation as developers target unmet needs in checkpoint inhibition and autoimmune modulation.
The FDA, EMA, and China's NMPA collectively govern market access through divergent approval standards, post-market surveillance requirements, and manufacturing inspection protocols that directly shape product launch sequencing and geographic revenue timing. REACH and the EU MDR impose additional substance safety and device-drug combination obligations on European market entrants. Stakeholders must monitor evolving biosimilar interchangeability designations and real-world evidence acceptance criteria as these regulatory instruments determine competitive substitution thresholds and pricing power durability.
Market Dynamics
Biologics manufacturing scale-up is compressing competitive timelines as hospital systems and contract manufacturers race to secure mammalian cell culture capacity before regulatory submission windows open.
Growth Catalysts
- EMA Adaptive Pathways:Conditional marketing authorizations in Europe accelerate oncology and rare disease launches, compressing revenue realization timelines by 12-18 months for qualifying therapies.
- Peptide synthesis automation:Continuous manufacturing platforms for GLP-1 receptor agonists are expanding Eli Lilly's and Novo Nordisk's metabolic disease supply capacity.
- China NMPA reform:Priority review channels for innovative drugs are pulling multinational sponsors toward simultaneous US-China filing strategies.
Market Restraints
- Active pharmaceutical ingredient concentration:Over 60% of small-molecule API supply originates from Chinese and Indian contract manufacturers, creating single-source vulnerability for antibiotics and oncology generics.
- Cold chain infrastructure gaps:mRNA vaccines and cell therapies require sustained -70°C logistics that remain unavailable across Sub-Saharan Africa and parts of Southeast Asia.
- REACH substance registration:European chemical safety documentation requirements impose 18-24 month pre-market delays for novel excipients and delivery vehicle components.
Strategic Opportunities
- Biosimilar interchangeability:FDA designation pathways for automatic pharmacy substitution create margin capture potential in adalimumab and trastuzumab reference product markets.
- Real-world evidence integration:EMA's acceptance of patient registry data for label expansion is enabling post-approval indication broadening without dedicated Phase III trials.
- Digital therapeutics bundling:Prescription software for diabetes and psychiatric management is creating reimbursement codes that pair with traditional pharmaceutical offerings.
Industry Challenges
- Bioprocess engineering talent scarcity:Cell culture specialists and downstream purification experts command 40-60% salary premiums over traditional chemical engineering roles, constraining manufacturing expansion.
- Multi-product facility validation:FDA's stance on viral clearance and cross-contamination prevention forces 9-14 month facility downtime between product changeovers in shared biologics suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceuticals Market |
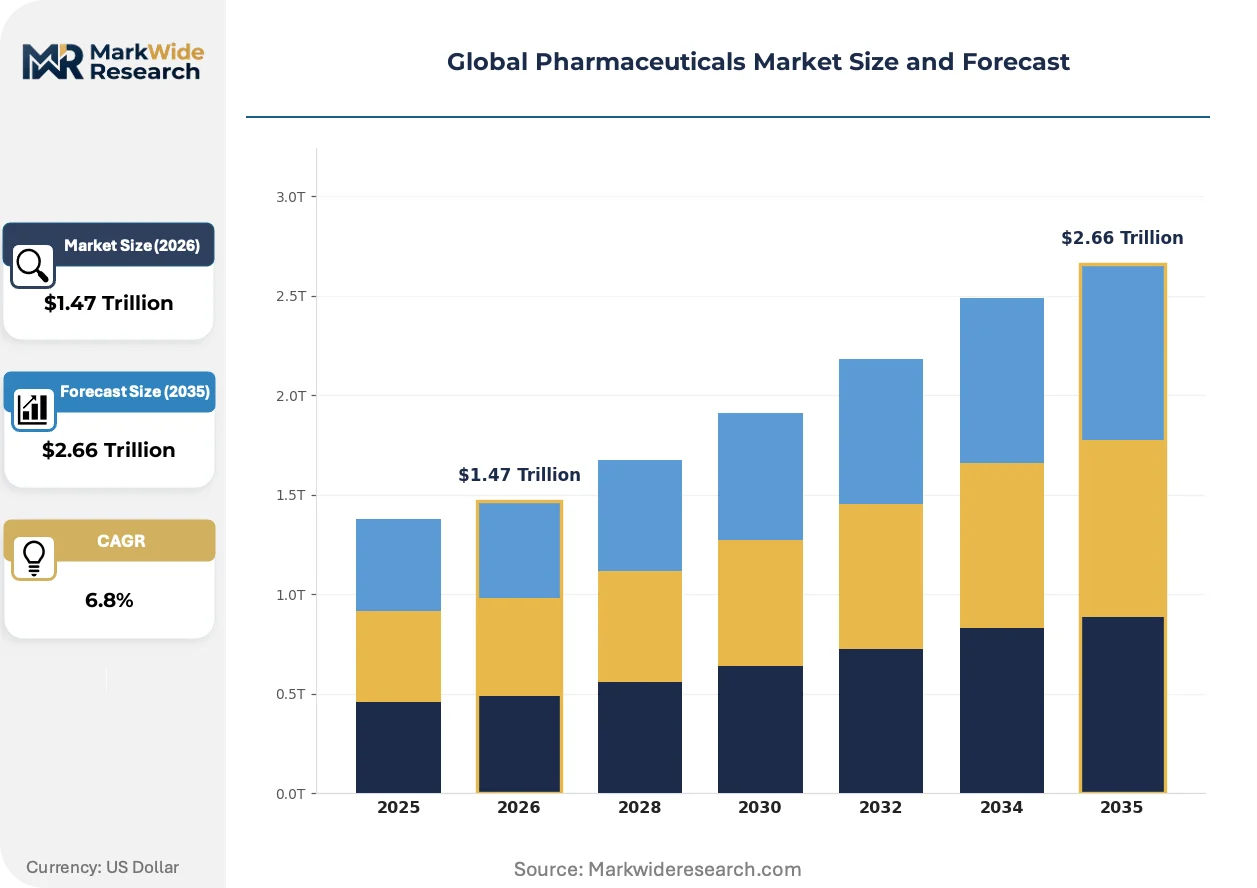
| Market Size in 2026 | $1.47 Trillion |
| Market Size in 2035 | $2.66 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, OTC Medications, Biologics, Vaccines Therapy Area: Oncology, Cardiology, Neurology, Immunology End User: Hospitals, Clinics, Retail Pharmacies, Research Laboratories Form: Tablets, Injections, Creams, Inhalers |
| Companies Covered | Merck & Co., Johnson & Johnson, AbbVie, AstraZeneca, Eli Lilly, Pfizer, Roche, Novartis, Sinopharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceuticals Market Strategic Shifts
mRNA platform standardization is collapsing vaccine development timelines while nucleic acid delivery technologies expand into protein replacement and gene editing applications previously reserved for viral vectors.
Continuous bioprocessing is supplanting traditional fed-batch fermentation in monoclonal antibody production. Contract manufacturers in Germany and Switzerland are installing perfusion-based systems that compress cell culture duration from 14 days to 10 days while improving titers. This shift is enabling geographic production redistribution as smaller-footprint facilities achieve comparable output to legacy stainless-steel plants.
REACH substance restrictions are forcing reformulation of topical and inhalation products containing per- and polyfluoroalkyl substances. European formulators are substituting fluorinated propellants and surfactants with bio-based alternatives, triggering 24-36 month stability revalidation cycles. Dermatology and respiratory portfolios face the steepest compliance cost absorption.
Hospital procurement consortia in the United States are consolidating purchasing power through 340B program expansion and group purchasing organization mergers. Academic medical centers now negotiate three-year sole-source agreements for oncology biologics, displacing traditional wholesaler relationships. This concentration is most pronounced in the Northeast and Great Lakes regions where health system consolidation has advanced furthest.
Global Pharmaceuticals Market Segmentation
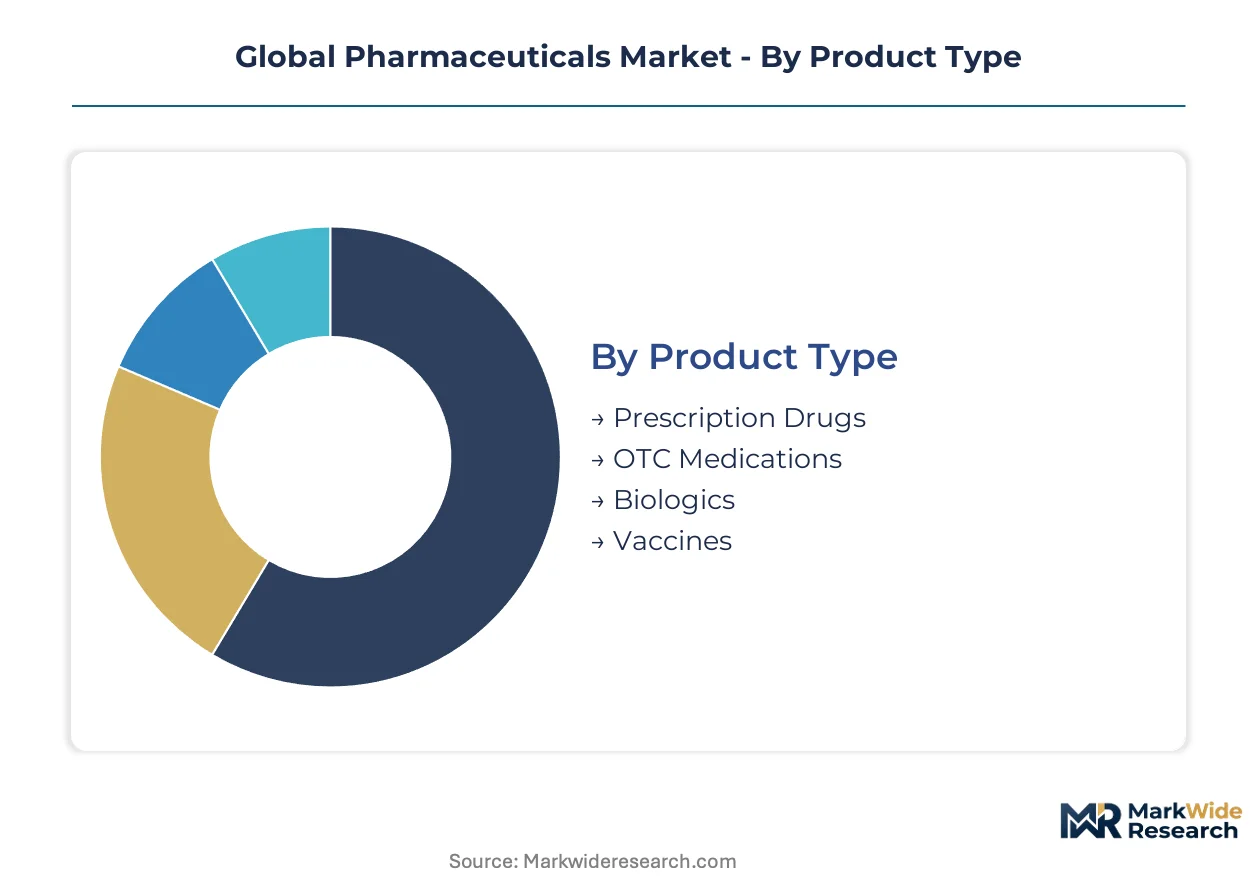
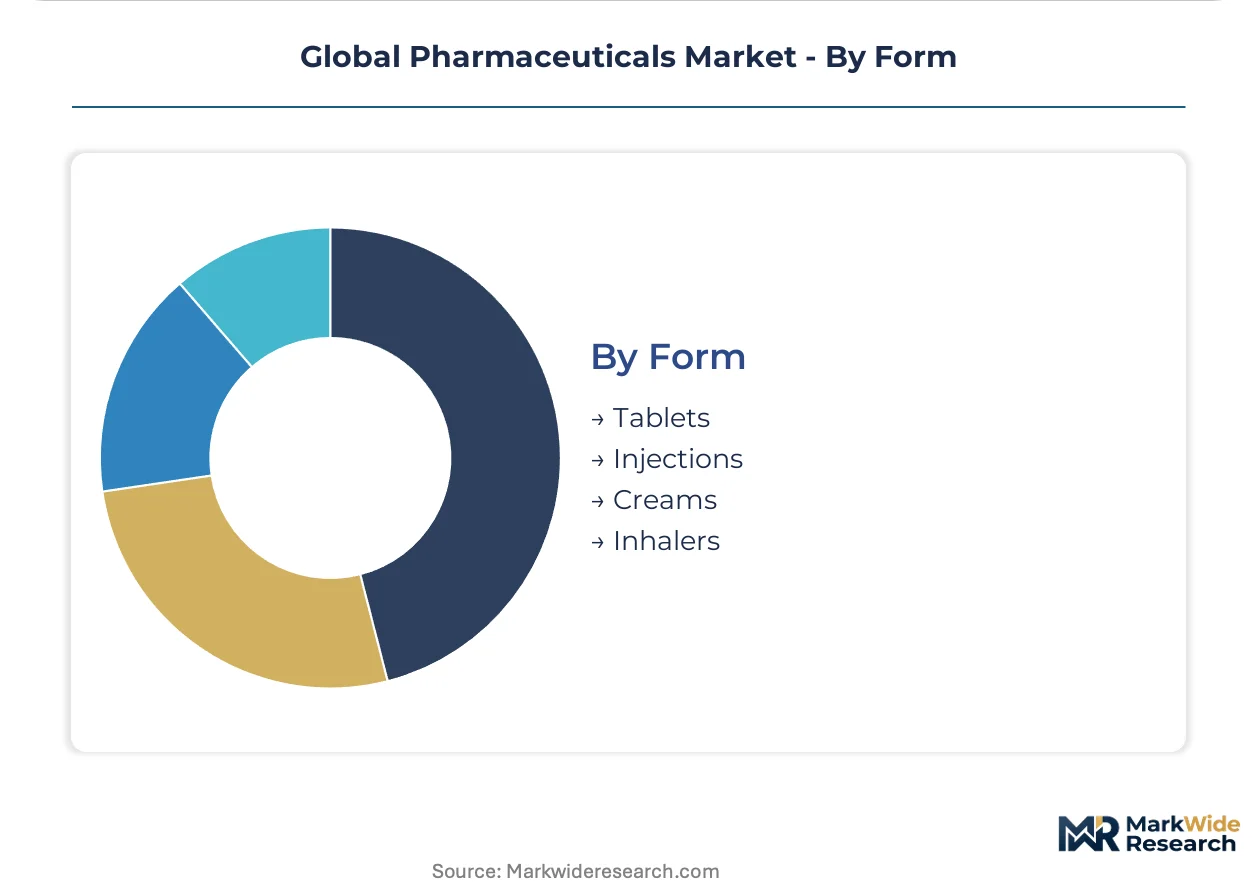
Segmentation in pharmaceuticals determines regulatory pathway complexity, manufacturing infrastructure requirements, and commercial access models. Each dimension—product type, therapy area, end user, and formulation—carries distinct margin profiles and compliance burdens that shape strategic resource allocation.
Product Type:
FDA, EMA, and NMPA each impose divergent approval timelines and post-market surveillance obligations across product categories, creating launch sequencing advantages for sponsors with multi-regulatory expertise.
- Prescription Drugs:Chemically synthesized small molecules requiring bioequivalence documentation for generic substitution. Hospital systems in the United States and Germany concentrate procurement for oncology and cardiovascular indications, driving three-year sole-source contracting trends.
- Biologics:Recombinant proteins and monoclonal antibodies manufactured in mammalian cell culture facilities. Roche's diagnostic-companion testing integration in oncology and Eli Lilly's peptide automation for metabolic disease anchor demand concentration in specialty infusion centers.
- OTC Medications:Self-administered formulations with abbreviated safety documentation. Retail pharmacy chains in China and India drive volume through direct-to-consumer channels.
- Vaccines:mRNA and live attenuated platforms requiring cold chain distribution. Pandemic preparedness mandates and platform standardization are compressing development timelines.
Prescription drugs handle the majority of throughput; biologics are the fastest mover on share.
Therapy Area:
Cost tier stratification separates premium biologic therapies from commoditized small-molecule treatments, with reimbursement codes determining patient access and prescriber behavior.
- Oncology:Checkpoint inhibitors and targeted kinase therapies commanding concentrated R&D allocation. Academic medical centers in the United States negotiate bundled payments for CAR-T and antibody-drug conjugates.
- Cardiology:Statins, anticoagulants, and heart failure biologics with established generic substitution pathways. Hospital consortia in Germany prioritize value-based procurement for post-acute management.
- Neurology:Disease-modifying therapies for Alzheimer's and multiple sclerosis facing payer scrutiny. China's NMPA priority review channels accelerate access for novel mechanisms.
- Immunology:Autoimmune modulation through cytokine inhibition and B-cell targeting. Biosimilar interchangeability designations for adalimumab and trastuzumab are reshaping pharmacy substitution patterns.
Oncology commands the steepest pricing premium; immunology is climbing the fastest as biosimilar penetration accelerates volume.
End User:
Customer type determines distribution complexity, with institutional procurement consolidating purchasing power while retail channels fragment demand across geographic markets.
- Hospitals:Inpatient and infusion center administration of biologics and parenteral formulations. 340B program expansion in the United States and group purchasing organization mergers concentrate negotiating leverage in the Northeast and Great Lakes regions.
- Clinics:Outpatient specialty care for chronic disease management. Physician-owned infusion centers in Switzerland and Germany capture margin through direct biologic sourcing.
- Retail Pharmacies:Dispensing of oral solids and self-injectable therapies. Chain consolidation in China and India enables volume-driven generic substitution.
- Research Laboratories:Investigational product supply for clinical trials. Contract manufacturers in Germany and Switzerland install perfusion-based systems to serve sponsor demand.
Hospitals absorb the largest value share; research laboratories are expanding most quickly as decentralized trial models proliferate.
Form:
Supply concentration in manufacturing infrastructure creates geographic production advantages, with continuous bioprocessing and formulation expertise clustering in specific regulatory jurisdictions.
- Injections:Parenteral biologics and vaccines requiring aseptic fill-finish capacity. Cold chain infrastructure gaps in Sub-Saharan Africa and Southeast Asia constrain mRNA vaccine access.
- Tablets:Oral solid dosage forms with established high-speed compression and coating operations. Indian and Chinese contract manufacturers supply over 60% of small-molecule API for antibiotic and oncology generics.
- Creams:Topical dermatology formulations facing REACH substance restrictions on per- and polyfluoroalkyl substances. European reformulation triggers 24-36 month stability revalidation cycles.
- Inhalers:Pulmonary delivery devices with fluorinated propellant phase-out obligations. Bio-based surfactant substitution under EU F-Gas Regulation drives portfolio restructuring.
Injections dominate biologic value capture; inhalers face the steepest regulatory-driven reformulation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States sustains 40-60% premiums over German reimbursement levels, while Chinese volume expansion absorbs cost efficiencies that manufacturers cannot capture in saturated Western markets. This asymmetry drives divergent launch sequencing and geographic revenue timing across the analysis window.
United States
Academic medical centers in the Northeast and Great Lakes regions negotiate three-year sole-source agreements for oncology biologics, displacing traditional wholesaler relationships. The FDA's accelerated approval pathway compresses revenue realization timelines by 12-18 months for qualifying therapies. Boston and San Francisco anchor cell therapy manufacturing clusters where perfusion-based systems achieve comparable output to legacy stainless-steel plants.
Germany
Hospital consortia prioritize value-based procurement for post-acute cardiovascular management, driving generic substitution in statins and anticoagulants. REACH substance registration imposes 18-24 month pre-market delays for novel excipients and delivery vehicle components. The Rhine-Ruhr and Bavarian industrial corridors concentrate continuous bioprocessing expertise as contract manufacturers install mammalian cell culture capacity.
China
Priority review channels for innovative drugs pull multinational sponsors toward simultaneous US-China filing strategies, accelerating neurology and oncology access. The NMPA's reform agenda compresses regulatory review timelines for novel mechanisms. Shanghai and Suzhou biotech parks attract foreign direct investment as domestic peptide synthesis automation expands metabolic disease supply capacity.
Switzerland
Physician-owned infusion centers capture margin through direct biologic sourcing for autoimmune and metabolic indications. Swissmedic maintains stringent post-market surveillance requirements that extend label expansion timelines. Basel and Zurich host diagnostic-companion testing integration hubs where oncology biologics anchor specialty infusion center demand.
India
Retail pharmacy chains drive volume through direct-to-consumer channels for OTC medications and self-administered therapies. The CDSCO's abbreviated approval pathways for certain biologics attract contract manufacturing investment. Hyderabad and Mumbai concentrate API production for antibiotics and oncology generics, though over 60% of small-molecule supply originates from concentrated contract manufacturer networks.
Global Pharmaceuticals Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with large-cap innovators commanding biological manufacturing platforms while mid-tier generics manufacturers absorb commodity pricing pressure. The market structure consolidates around three strategic tiers: integrated biopharmaceutical conglomerates with diagnostic-companion testing capabilities, peptide automation specialists in metabolic disease, and volume-driven API suppliers concentrated in Asian manufacturing hubs. Dominant competitive moves include strategic partnerships for mRNA platform licensing and backward integration into mammalian cell culture capacity.
Among the integrated biopharmaceutical tier, Merck & Co., Johnson & Johnson, and Roche occupy positions defined by oncology and immunology therapeutic concentration. These entities exemplify archetypes spanning diagnostic-companion testing integration, global manufacturing footprint leverage, and specialty infusion center channel control. Their positioning reflects divergent strategic bets on biologics manufacturing scale-up versus small-molecule portfolio optimization.
| Leading Market Players |
|---|
| Merck & Co. |
| Johnson & Johnson |
| AbbVie |
| AstraZeneca |
| Eli Lilly |
| Pfizer |
| Roche |
| Novartis |
| Sinopharm |
| Others |
Value Chain & Pricing Dynamics
Ninety-to-120-day API inventory cycles in antibiotic and oncology generics manufacturing tether pricing power to geographic supply concentration, compressing margins where Indian and Chinese contract manufacturers dominate while preserving premiums for biologics with captive mammalian cell culture capacity.
Pricing Analysis
Configured-to-order peptide synthesis commands 25-40% premiums over standard catalog offerings, with Eli Lilly and Novo Nordisk capturing margin through GLP-1 automation scale. Three-tier pricing structure across patent-protected specialty, authorized generic, and commodity substitution levels stratifies the market, with hospital procurement consortia in the United States extracting volume discounts that narrow the spread. Cost compression in small-molecule generics intensifies as 340B program expansion concentrates buyer leverage, while biologics maintain pricing durability through biosimilar interchangeability barriers and companion diagnostic bundling.
Supply Chain Analysis
Just-in-time API procurement preferences clash with strategic stockpiling mandates for pandemic preparedness, creating inventory tension across mRNA vaccine and cell therapy networks. Active pharmaceutical ingredient supply draws from India, China, and concentrated European fermentation hubs, with over 60% of small-molecule inputs originating from Subcontinent contract manufacturers. Single-source vulnerability in antibiotic and oncology generic APIs amplifies disruption risk from regulatory inspection delays or export restrictions. Distribution runs through hospital consortia and group purchasing organizations in developed markets, while retail pharmacy chains fragment downstream access in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell culture specialist scarcity and downstream purification bottlenecks constrain manufacturing expansion, rewarding stakeholders who secure bioprocess engineering talent and mammalian facility capacity ahead of regulatory submission windows.
For Market Incumbents: Consolidate biologics manufacturing scale through perfusion-based system installation in Germany and Switzerland, while locking three-year sole-source agreements with academic medical centers in the Northeast and Great Lakes regions. Biosimilar interchangeability designations for adalimumab and trastuzumab threaten reference product margins, demanding backward integration into API supply or diagnostic-companion testing bundling to defend pricing power. For New Entrants and Emerging Players: Anchor in neurology and rare disease indications where China's NMPA priority review channels accelerate regulatory timelines and payer scrutiny remains less entrenched than in oncology. Digital therapeutics bundling for diabetes and psychiatric management creates reimbursement codes that pair with traditional pharmaceutical offerings, offering a go-to-market angle distinct from molecule-centric competition. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap conglomerates divesting small-molecule portfolios under biosimilar and generic pricing pressure, particularly cardiology and respiratory assets facing REACH-driven reformulation costs. Mid-tier manufacturers with mammalian cell culture capacity and EMA adaptive pathway expertise represent acquisition archetypes with durable competitive positioning. Watch FDA accelerated approval withdrawal rates and EMA conditional marketing authorization conversion failures as inflection indicators for regulatory risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Perfusion-based bioprocessing in German and Swiss facilities compresses cell culture duration from 14 days to 10 days. |
| Regulatory Approval Pathway | EMA adaptive licensing frameworks compress oncology and rare disease revenue realization timelines by 12-18 months. |
| Clinical Trial Advancement | Real-world evidence integration enables post-approval indication broadening without dedicated Phase III trials. |
| Pipeline Diversification | mRNA platform standardization collapses vaccine development timelines while expanding into protein replacement applications. |
| Strategic Partnership | Diagnostic-companion testing integration in Basel and Zurich anchors oncology biologics demand in specialty infusion centers. |
Study Parameters
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Primary fieldwork across the United States, Germany, China, and Switzerland validated secondary findings on manufacturing capacity expansion and procurement consolidation trends. Bottom-up patient-flow modeling and top-down revenue reconciliation triangulated market sizing across the analysis window.
Variance decomposition separates volume drivers from price-mix effects across treatment line, dosage form, administration route, and regional regulatory cluster dimensions. CAGRs derive from segment-level growth rate aggregation weighted by base-year revenue contribution. Forecast inputs incorporate biosimilar interchangeability designation timelines, NMPA reform implementation pace, and hospital system merger activity in the Northeast and Great Lakes regions.
Decision-makers should treat outputs as directional under assumptions of continued EMA adaptive pathway utilization and stable US-Germany-China regulatory convergence; material deviation would warrant model refresh. Revision becomes warranted when FDA accelerated approval withdrawal rates or NMPA priority review channel backlogs cross thresholds that alter commercial launch sequencing assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
API Contract Manufacturing Market
Pharmaceuticals
Apalutamide API Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Asia Pacific Multiple Sclerosis Drugs Market
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
Global Hormonal Contraceptives Market
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Hypertensive Emergency Medications Market
Pharmaceuticals
Sulfonylureas Market
Pharmaceuticals
Pharmaceuticals Preservative Market
Pharmaceuticals
Italy Opioids Market
Pharmaceuticals
Neurological Disorder Drugs Market
Pharmaceuticals
Cough and Cold Preparations Market
Pharmaceuticals
Advanced Therapy Medicinal Products CDMO Market
Pharmaceuticals
Granulocyte Macrophage Colony Stimulating Factor Market