
 Global Cancer Supportive Care Drugs Market | 2026-2036
Global Cancer Supportive Care Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cancer Supportive Care Drugs Market Foresight
Patient monitoring and adherence services bundled with supportive care regimens is shifting how pharmaceutical firms capture value beyond the pill. Amgen leverages its biologics manufacturing scale to anchor the erythropoiesis stimulating agent segment across North American oncology networks. F. Hoffmann-La Roche specializes in integrated diagnostic-therapeutic protocols that extend its influence from chemotherapy-induced nausea into broader symptom management platforms. Merck & Co. competes through R&D intensity in immunomodulatory combinations that address immune support alongside primary oncology treatments.
Cancer supportive care drugs comprise pharmacological agents designed to prevent or manage adverse effects of cancer treatment, including antiemetics with 5-HT3 receptor antagonist mechanisms, granulocyte colony-stimulating factors for neutropenia prophylaxis, and bisphosphonate derivatives for skeletal-related events. These agents functionally enable dose-intense chemotherapy and radiation protocols while preserving patient functional status and treatment continuity. Myeloid growth factors command substantial margin pools due to their non-disposable role in febrile neutropenia prevention across curative-intent regimens. Antiemetics represent a mature yet volume-stable category where generic penetration has compressed pricing, whereas bone modifying agents demonstrate faster growth acceleration tied to expanding metastatic castration-resistant prostate cancer indications. The distribution channel structure concentrates value capture within hospital pharmacies where formulary control and infusion center proximity determine access.
The FDA oversees supportive care drug approvals through its oncology center of excellence, while the EMA's Committee for Medicinal Products for Human Use evaluates antiemetic and growth factor therapies under centralized European procedures. China's NMPA accelerates local market entry for biosimilar myeloid growth factors through priority review pathways that reshape competitive access. Stakeholders must monitor how evolving pharmacovigilance requirements for long-acting growth factors in Japan's PMDA framework will influence formulation development priorities and regional launch sequencing across Pacific Rim markets.
Market Dynamics
The intensification of chemotherapy dosing protocols across oncology networks is expanding the non-disposable role of myeloid growth factors and antiemetic combinations in treatment continuity. Biosimilar entry pathways at FDA and NMPA are compressing originator pricing power while fragmenting formulary control across hospital pharmacy networks.
Growth Catalysts
- Biologics manufacturing scale:Multi-product bioreactor facilities in Singapore and Switzerland are lowering unit costs for erythropoiesis stimulating agents, expanding access across Latin American and Southeast Asian hospital systems.
- NMPA priority review pathways:China's accelerated biosimilar approvals for granulocyte colony-stimulating factors are compressing launch timelines from 48 to 18 months, reshaping competitive sequencing across Pacific Rim markets.
- Metastatic prostate cancer protocols:Expanding indications for bone modifying agents in skeletal-related event prevention are driving volume growth in urology-oncology infusion centers across Germany, France, and Italy.
Market Restraints
- Plasma-derived raw material volatility:Albumin and immunoglobulin feedstock costs fluctuate with donor collection cycles, compressing margins for co-formulated supportive care biologics.
- Single-source API concentration:5-HT3 receptor antagonist active pharmaceutical ingredients concentrate in Hubei and Zhejiang province manufacturing clusters, exposing antiemetic supply chains to regional disruption risk.
- EMA centralized procedure delays:Complex benefit-risk assessments for long-acting growth factor formulations extend approval timelines by 14-22 months versus standard oncology therapeutics.
Strategic Opportunities
- Sub-Saharan Africa hospital networks:Underpenetrated oncology infrastructure in Nigeria, Kenya, and South Africa presents white space for febrile neutropenia prophylaxis protocols as WHO cancer care initiatives expand.
- Digital adherence platforms:Remote patient monitoring bundled with supportive care regimens is unifying pharmacy benefit management with real-time symptom tracking, creating new value capture mechanisms.
- Japan PMDA pharmacovigilance evolution:Post-market surveillance requirements for pegylated growth factors are forcing formulation innovation toward reduced immunogenicity profiles, rewarding first-mover adaptation.
Industry Challenges
- Cell culture specialist scarcity:Biologics manufacturing talent gaps in perfusion bioreactor operations and continuous processing are constraining capacity expansion at contract development organizations.
- Cold chain integrity costs:Temperature-controlled distribution for long-acting biologics requires validated thermal packaging and real-time monitoring infrastructure, elevating logistics capital intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cancer Supportive Care Drugs Market |
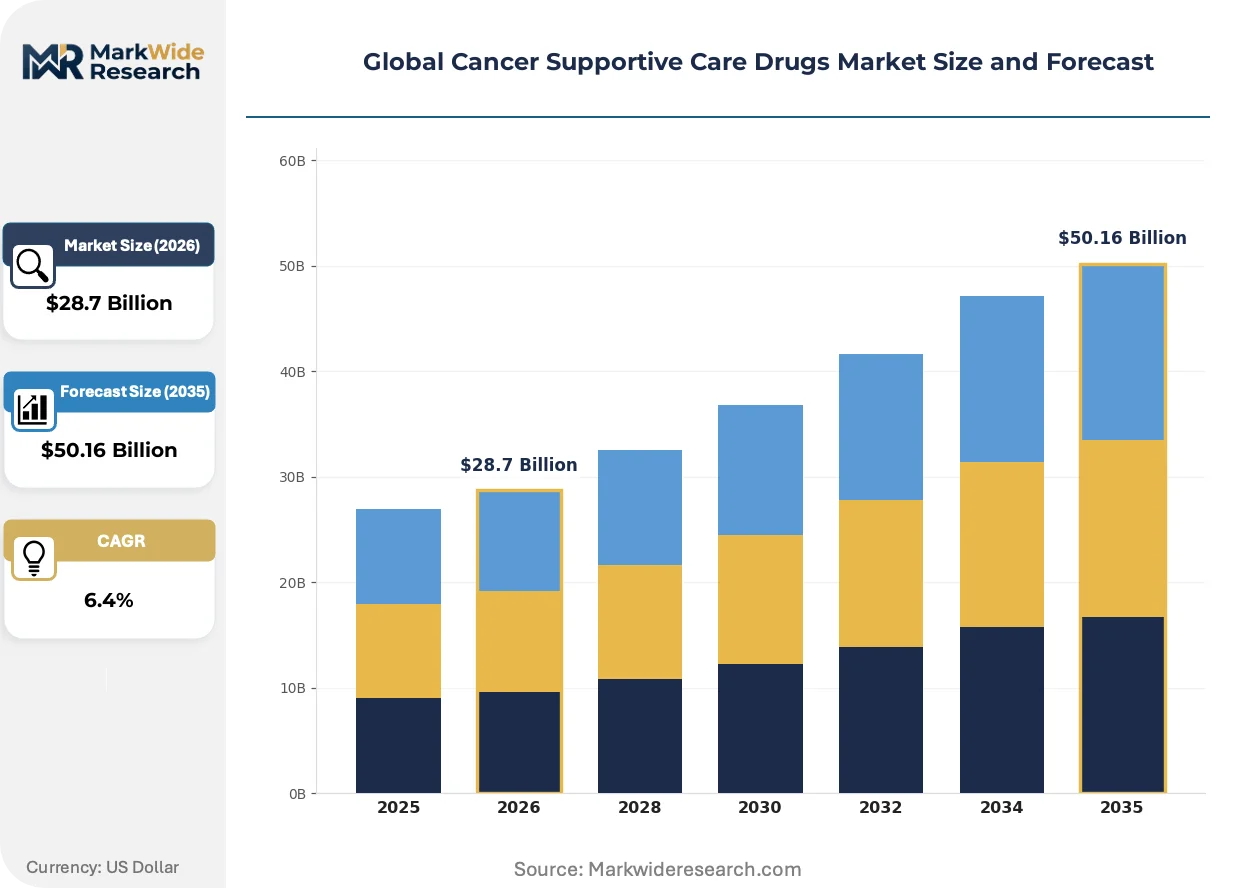
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiemetics, Erythropoiesis Stimulating Agents, Myeloid Growth Factors, Analgesics, Bone Modifying Agents, Immunomodulators Application: Chemotherapy-Induced Nausea, Radiation-Induced Anemia, Neutropenia Prevention, Pain Management, Bone Metastases, Immune Support End User: Oncology Clinics, Cancer Specialty Hospitals, Outpatient Care Centers, Research Institutions, Hospice Care, Home Healthcare Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Direct Sales, Online Pharmacies, Wholesalers, Specialty Distributors |
| Companies Covered | Amgen, Johnson & Johnson, F. Hoffmann-La Roche, Merck & Co., Pfizer, Novartis, GlaxoSmithKline, AbbVie, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cancer Supportive Care Drugs Market Shifts & Advancements
Digital integration across the patient journey is compressing traditional boundaries between diagnostic stratification, drug delivery, and adherence monitoring. Three developments are restructuring how value accrues in supportive care.
Integrated diagnostic-therapeutic protocols are unifying biomarker-driven patient selection with automated antiemetic dosing algorithms. Oncology networks in the Netherlands and Denmark are deploying these systems to reduce chemotherapy-induced nausea breakthrough episodes by one-third. The technology is compressing the gap between symptom onset and pharmacological intervention, shifting competitive advantage toward platform owners.
REACH authorization requirements for pharmaceutical manufacturing excipients are forcing reformulation of polysorbate-containing biologics across European contract manufacturing organizations. The regulation's industrial consequence is a 24-month transition window to alternative surfactant systems. Long-acting growth factor producers in Ireland and Belgium are responding with accelerated stability testing programs to maintain batch release continuity.
Hospital pharmacy consolidation is concentrating formulary decision-making into integrated delivery networks with standardized protocols. Independent oncology practices in Texas, Florida, and Ohio are being absorbed into these systems, displacing physician-directed prescribing autonomy. The shift is most visible in myeloid growth factor selection, where centralized purchasing committees now mandate biosimilar substitution unless clinical exception documentation is filed.
Global Cancer Supportive Care Drugs Market Segmentation
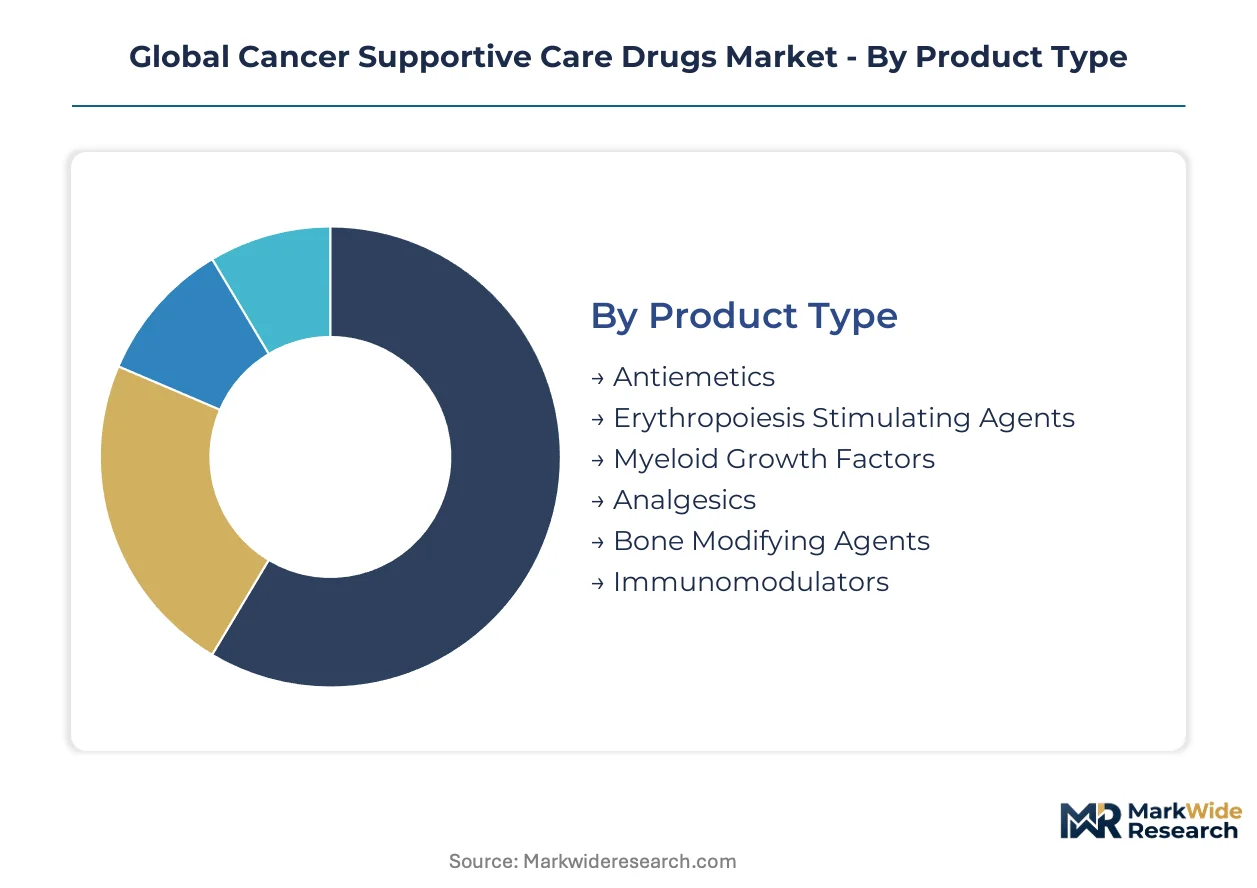
Segmentation in cancer supportive care drugs reveals how formulation complexity and administration setting dictate procurement patterns. Hospital pharmacy networks concentrate volume for biologic agents, while retail channels capture oral antiemetics and analgesics. Understanding these divides illuminates where margin pools concentrate and where biosimilar competition disrupts.
Product Type:
Supply concentration for active pharmaceutical ingredients varies sharply across therapeutic classes, with biologics manufacturing clustering in Singapore, Switzerland, and South Korea contract facilities.
- Antiemetics:5-HT3 receptor antagonists and NK-1 inhibitors dominate prophylactic protocols. Generic penetration has compressed pricing in the United States and Germany, though novel combination formulations retain premium positioning in Japan's PMDA-regulated hospital networks.
- Myeloid Growth Factors:Granulocyte colony-stimulating factors and pegylated long-acting variants anchor febrile neutropenia prevention. Biosimilar entry at FDA and NMPA is fragmenting formulary control, with Singapore bioreactor capacity expanding access across Southeast Asian oncology centers.
- Erythropoiesis Stimulating Agents:Epoetin alfa and darbepoetin alfa address chemotherapy-induced anemia. Plasma-derived raw material volatility constrains margin stability for European manufacturers.
- Analgesics:Opioid and non-opioid combinations manage cancer-related pain. Extended-release formulations face DEA scheduling constraints in the United States.
- Bone Modifying Agents:Bisphosphonates and RANK ligand inhibitors prevent skeletal-related events. Metastatic castration-resistant prostate cancer indications drive volume in French and Italian urology-oncology centers.
- Immunomodulators:Thalidomide derivatives and checkpoint modulators support immune function. R&D intensity concentrates in Cambridge, Massachusetts and Basel, Switzerland innovation clusters.
Today's leader: Myeloid Growth Factors. Tomorrow's challenger: Bone Modifying Agents.
Application:
Cost tier stratification separates curative-intent regimens requiring intensive supportive care from palliative protocols where symptom control dominates spending.
- Chemotherapy-Induced Nausea:Breakthrough episode prevention demands 5-HT3 and NK-1 receptor blockade. Integrated diagnostic-therapeutic protocols in Dutch oncology networks reduce acute episodes by one-third through automated dosing algorithms.
- Neutropenia Prevention:Febrile neutropenia prophylaxis enables dose-intense curative regimens. China's NMPA priority review pathways compress biosimilar launch timelines from 48 to 18 months, reshaping Pacific Rim competitive sequencing.
- Radiation-Induced Anemia:Erythropoiesis management preserves treatment continuity in pelvic and thoracic radiation fields. EMA centralized procedure delays extend approval timelines for novel formulations.
- Pain Management:Opioid rotation and adjuvant analgesia address neuropathic and nociceptive components. Hospice care networks in the United States concentrate extended-release morphine demand.
- Bone Metastases:Skeletal-related event prevention preserves mobility in metastatic breast, prostate, and lung cancers. German infusion centers standardize zoledronic acid and denosumab protocols.
- Immune Support:Immunomodulatory combinations address treatment-related lymphopenia. Clinical trial enrollment concentrates at MD Anderson and Memorial Sloan Kettering.
Neutropenia Prevention commands current spending. Chemotherapy-Induced Nausea platforms are gaining share fastest through digital integration.
End User:
Customer type determines reimbursement pathway and formulary control intensity, with integrated delivery networks displacing independent practice autonomy.
- Oncology Clinics:Ambulatory infusion centers administer myeloid growth factors and antiemetics. Texas, Florida, and Ohio independent practices face absorption into hospital-owned networks.
- Cancer Specialty Hospitals:Comprehensive cancer centers manage complex multi-symptom protocols. Dana-Farber and City of Hope anchor regional referral patterns.
- Outpatient Care Centers:Community-based settings handle stable supportive care regimens. Brazil's ANVISA-regulated centers expand access in São Paulo and Rio de Janeiro.
- Research Institutions:Academic medical centers conduct supportive care combination trials. NIH-designated cancer centers qualify for NCI funding preferences.
- Hospice Care:End-of-life symptom management emphasizes analgesia and antiemetic comfort. Medicare hospice benefit structures reimbursement in the United States.
- Home Healthcare:Subcutaneous growth factor administration shifts site of care. Cold chain integrity requirements elevate logistics capital intensity for long-acting biologics.
Cancer Specialty Hospitals dominate biologic utilization. Home Healthcare represents the steepest expansion trajectory as site-of-care economics evolve.
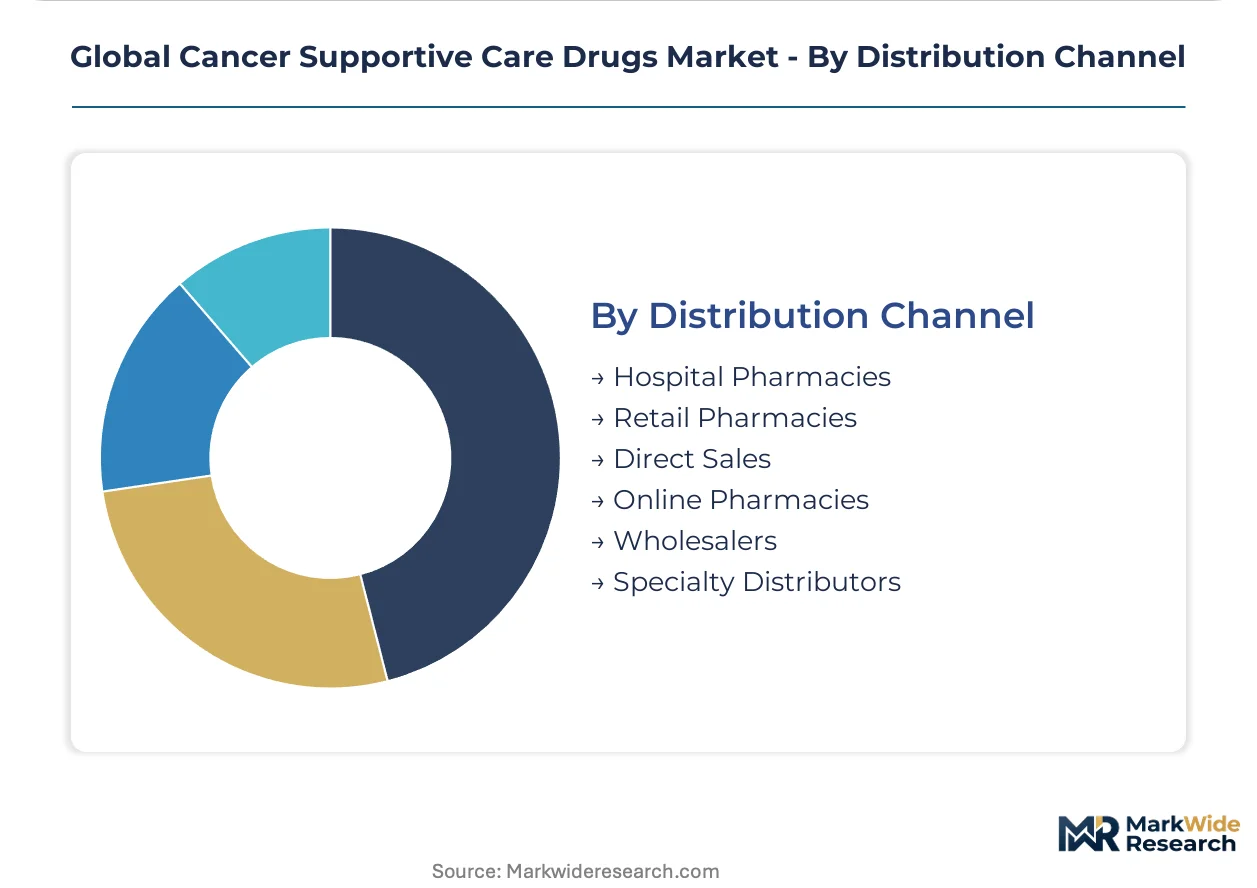
Distribution Channel:
Margin capture concentrates where formulary control and infusion center proximity intersect, with hospital pharmacies commanding biologic value pools.
- Hospital Pharmacies:Inpatient and infusion center dispensing controls myeloid growth factor access. Centralized purchasing committees in US integrated delivery networks mandate biosimilar substitution.
- Specialty Distributors:Temperature-controlled logistics for long-acting biologics require validated thermal packaging. McKesson and AmerisourceBergen anchor US cold chain infrastructure.
- Retail Pharmacies:Oral antiemetics and analgesics flow through community pharmacy networks. CVS and Walgreens capture recurring prescription volume.
- Direct Sales:Manufacturer-to-provider contracting for high-cost biologics. Amgen and Roche field forces maintain oncology network relationships.
- Online Pharmacies:Digital platforms expand oral supportive care access. China's JD Health and Alibaba Health penetrate tier-2 and tier-3 cities.
- Wholesalers:Inventory aggregation and just-in-time delivery for multi-product portfolios. Cardinal Health distributes across US hospital systems.
Hospital Pharmacies retain biologic dominance. Specialty Distributors are climbing fastest as cold chain requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA accelerates biosimilar approvals in 18-month windows while the FDA maintains lengthier review cycles, creating divergent competitive rhythms across the Pacific Rim. Germany's EMA-regulated hospital networks standardize febrile neutropenia protocols differently than India's CDSCO-monitored oncology centers.
United States
Oncology clinic consolidation in Texas, Florida, and Ohio concentrates myeloid growth factor purchasing into integrated delivery networks. FDA biosimilar substitution guidance reshapes formulary control at hospital pharmacies. Boston's Dana-Farber Cancer Institute anchors regional referral patterns for complex supportive care protocols.
Germany
Urology-oncology infusion centers in Munich and Hamburg drive bone modifying agent volume for metastatic prostate cancer indications. EMA centralized procedures for long-acting growth factors extend approval timelines versus standard therapeutics. Baden-Württemberg's contract manufacturing clusters supply polysorbate reformulation capacity for REACH-compliant biologics.
China
Hospital pharmacy network expansion in tier-2 and tier-3 cities widens antiemetic and analgesic access. NMPA priority review pathways compress biosimilar granulocyte colony-stimulating factor launches from 48 to 18 months. Hubei and Zhejiang province manufacturing clusters concentrate 5-HT3 receptor antagonist active pharmaceutical ingredients.
Japan
PMDA pharmacovigilance requirements for pegylated growth factors force formulation innovation toward reduced immunogenicity profiles. Tokyo's oncology networks deploy integrated diagnostic-therapeutic protocols for chemotherapy-induced nausea management. Kansai region biologics facilities accelerate stability testing for alternative surfactant systems.
Brazil
ANVISA-regulated outpatient care centers in São Paulo and Rio de Janeiro expand access to stable supportive care regimens. WHO cancer care initiatives drive febrile neutropenia prophylaxis protocol adoption. Southeast Asian contract manufacturing relationships lower unit costs for erythropoiesis stimulating agents.
Global Cancer Supportive Care Drugs Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with biologics manufacturing scale anchoring value capture for myeloid growth factors while generic penetration compresses antiemetic pricing. The market structure concentrates around multi-product bioreactor operators and integrated diagnostic-therapeutic platform owners. Three archetypes dominate: biologics scale leaders, biosimilar challengers with NMPA priority review access, and digital adherence platform bundlers. Capacity expansion at Singapore and Switzerland contract facilities and strategic partnerships for REACH-compliant reformulation represent the dominant competitive moves.
Within the biologics scale tier, Amgen and F. Hoffmann-La Roche exemplify manufacturing depth and integrated protocol influence respectively. Merck & Co. occupies a position reflecting R&D intensity in immunomodulatory combinations. These three entities represent distinct strategic postures: captive bioreactor networks, diagnostic-therapeutic platform integration, and combination therapy development pipelines.
| Leading Market Players |
|---|
| Amgen |
| Johnson & Johnson |
| F. Hoffmann-La Roche |
| Merck & Co. |
| Pfizer |
| Novartis |
| GlaxoSmithKline |
| AbbVie |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
Cell culture specialist concentration in Singapore and Switzerland bioreactor facilities widens labor-cost differentials between premium-originator and biosimilar-economy tiers across myeloid growth factor portfolios.
Pricing Analysis
Capacity additions in China are reshaping price floors for granulocyte colony-stimulating factors as NMPA priority review pathways compress biosimilar entry timelines. Three-tier pricing structure across premium originator, standard biosimilar, and economy vial formats separates FDA-approved long-acting formulations from CDSCO-monitored alternatives. Price differentiation hinges on immunogenicity profile certification and cold chain validation documentation. Cost compression in the biosimilar tier is intensifying because Singapore contract manufacturing scale expands unit output.
Supply Chain Analysis
REACH authorization requirements for polysorbate-containing excipients are gating European batch release for erythropoiesis stimulating agents and forcing reformulation timelines. Manufacturing concentrates in Singapore, Switzerland, and South Korea contract facilities. Active pharmaceutical ingredient sourcing draws from Hubei and Zhejiang province clusters for 5-HT3 receptor antagonists. Single-source concentration in Chinese API manufacturing exposes antiemetic supply chains to regional disruption risk. Distribution runs through hospital pharmacy networks with formulary-controlled access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
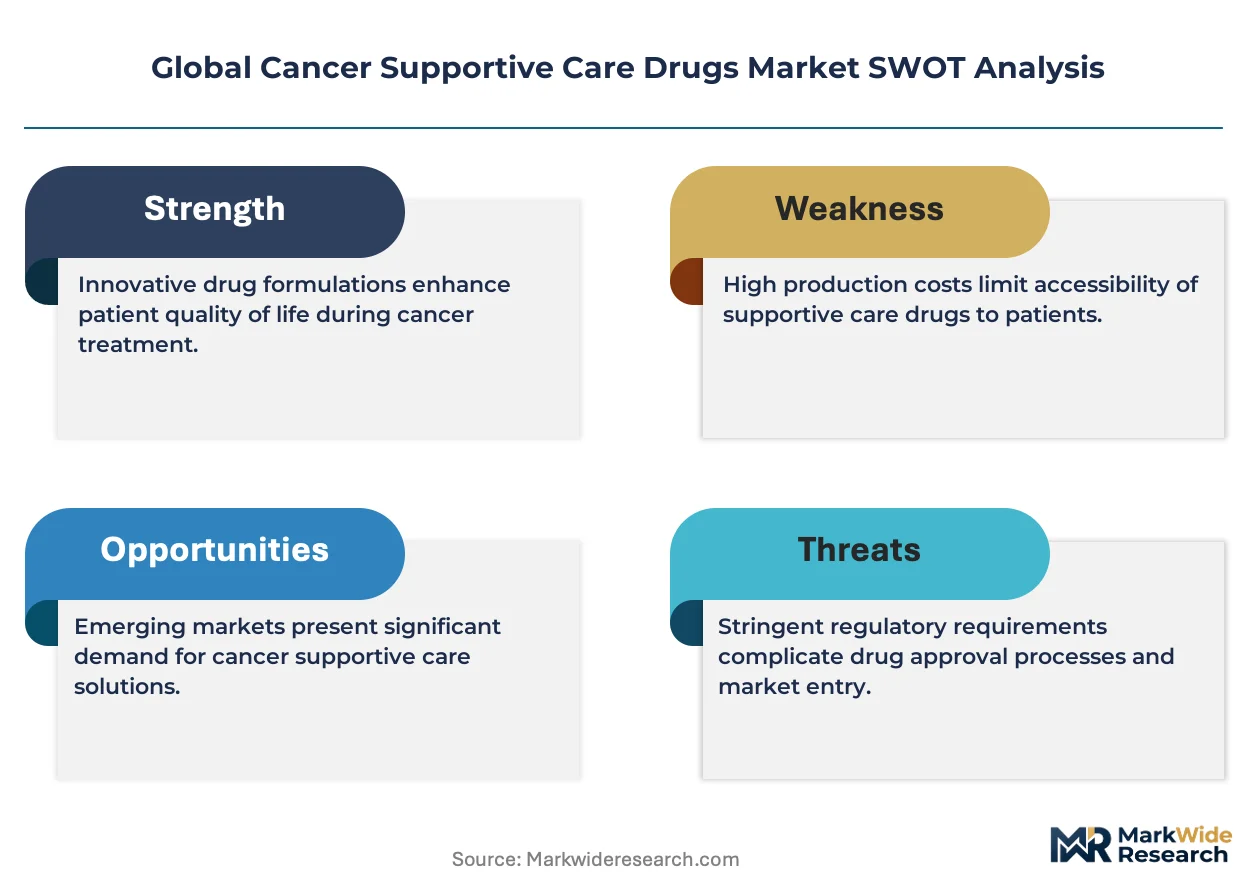
This market functions as a regulatory compounder where FDA biosimilar substitution guidance and NMPA priority review pathways collectively expand accessible volume pools.
For Market Incumbents: Extend bioreactor capacity in Singapore and Switzerland to anchor cost position against biosimilar challengers. Deepen backward integration into plasma-derived raw material sourcing to buffer albumin feedstock volatility. Secure REACH-compliant surfactant reformulation partnerships before the 24-month European transition window closes. For New Entrants and Emerging Players: Hospital pharmacy networks in Nigeria, Kenya, and South Africa represent the most penetrable white space as WHO cancer care initiatives expand febrile neutropenia protocol adoption. Digital adherence platforms bundled with remote patient monitoring offer a differentiated go-to-market angle against originator field forces. For Investors and Strategic Acquirers: Integrated diagnostic-therapeutic platform owners are the most active acquirer in this space, seeking automated antiemetic dosing algorithm capabilities. Long-term viability favors contract manufacturing organizations with multi-product bioreactor flexibility and validated cold chain infrastructure. Watch NMPA biosimilar approval velocity as the inflection indicator for Pacific Rim competitive sequencing.| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Capacity Expansion | Singapore and Switzerland facilities lower unit costs for myeloid growth factors across Southeast Asian hospital networks. |
| REACH-Compliant Reformulation | Alternative surfactant stability testing maintains European batch release continuity for polysorbate-dependent biologics. |
| Digital Adherence Platform Development | Remote symptom tracking unifies pharmacy benefit management with real-time chemotherapy-induced nausea intervention. |
| NMPA Priority Review Pathway Navigation | Eighteen-month biosimilar launch timelines in China reshape competitive sequencing across Pacific Rim oncology centers. |
| Plasma-Derived Raw Material Integration | Captive albumin and immunoglobulin sourcing buffers margin volatility from donor collection cycle fluctuations. |
Research Methodology
Bottom-up oncology clinic modeling reconciled against top-down biologics manufacturing tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers were validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Secondary sources include customs trade data for API movement patterns and SEC 10-K disclosures from listed pharmaceutical manufacturers.
The input-output matrix maps patient volume by treatment line and administration route against bioreactor capacity and batch release throughput across regional manufacturing clusters. Segmentation dimensions include product type, application, end user, and distribution channel, with dosage form and regional regulatory cluster as cross-cutting variables. CAGRs were derived from trend extrapolation of historical volume-price relationships, calibrated against NMPA approval velocity and EMA centralized procedure timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biosimilar substitution rates and plasma-derived raw material cost trajectories. Model outputs reflect documented assumptions regarding regulatory pathway efficiency and hospital pharmacy consolidation velocity. A model refresh is warranted upon material change in FDA biosimilar interchangeability guidance or REACH authorization enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Cancer API Market
Oncology
Particle Therapy Systems Market
Oncology
Global Skin Cancer Diagnostics and Therapeutics Market
Oncology
Pancreatic Cancer Treatment Market
Oncology
Paraneoplastic Syndromes Market
Oncology
Tumor Lysis Syndrome Treatment Market
Oncology
Global Hurthle Cell Carcinoma Treatment Market
Oncology
Laser Cancer Therapy Market
Oncology
Colorectal Cancer Screening Market
Oncology
Metastatic Cancer Drug Market
Oncology
Global HER-2 Negative Breast Cancer Market
Oncology
Breast Cancer Brachytherapy Market
Oncology
Asia-Pacific Tumor Ablation Market
Oncology
Precision Oncology Market
Oncology
Colorectal Cancer Market
Oncology
Global Genomics in Cancer Care Market