
 Warts Therapeutics Market | 2026-2036
Warts Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Warts Therapeutics Market Outlook
Buyer concentration across dermatology clinics is realigning as independent practices consolidate into multi-site networks and retail health clinics expand cosmetic and medical dermatology services. Verrica Pharmaceuticals leverages its specialty focus on viral skin diseases to sustain clinical trial momentum. GlaxoSmithKline plc anchors consumer-accessible topical segments through established over-the-counter distribution. Merck & Co. Inc. competes in the prescription immunotherapy space with differentiated biologic approaches.
Warts therapeutics encompass pharmaceutical and procedural interventions designed to eliminate benign epidermal growths caused by human papillomavirus infection, primarily functioning through cryodestruction, immunostimulation, or chemical keratolysis at concentrations typically ranging from 17% salicylic acid in consumer formulations to 85% trichloroacetic acid in clinical settings. Topical treatments command the largest revenue share due to repeat-purchase patterns and home-use accessibility, while cryotherapy retains margin strength in professional settings where reimbursement supports per-procedure pricing. Intralesional delivery modes represent the fastest-expanding structural category as clinicians seek alternatives resistant to topical therapy failures.
The FDA oversees prescription topical and intralesional formulations through its Center for Drug Evaluation and Research, while the EPA regulates cryogenic gases used in dermatologic applications, collectively shaping formulation standards and clinical trial endpoints. Dermatology clinics must navigate payer prior-authorization requirements that increasingly favor documented treatment resistance before approving advanced immunotherapy. Stakeholders should monitor how biosimilar competition and point-of-care diagnostic integration reshape prescribing economics and patient routing between homecare and clinical settings.
Market Dynamics
The FDA's evolving guidance on topical immunomodulators is compressing clinical trial timelines while expanding the addressable patient population for prescription-grade therapies, forcing developers to recalibrate efficacy endpoints toward durable clearance rather than lesion reduction alone.
Growth Catalysts
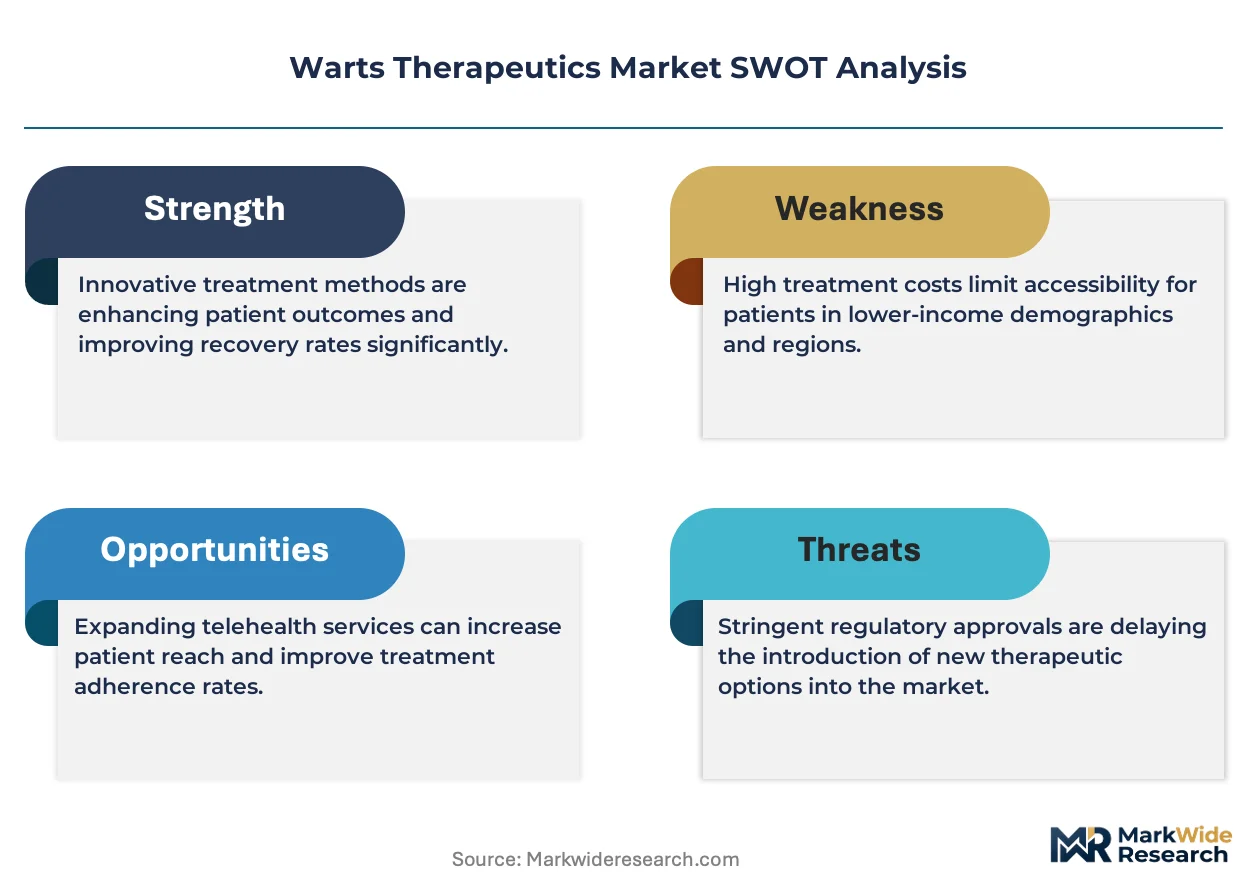
- Expanded payer coverage:United States commercial insurers are broadening prior-authorization pathways for office-based cryotherapy and intralesional immunotherapy, routing refractory cases toward reimbursed clinical procedures.
- REACH compliance harmonization:The European Chemicals Agency's streamlined substance evaluation for keratolytic agents is accelerating formulation approvals across EU member states.
- HPV typing integration:Point-of-care diagnostic platforms are identifying high-risk viral strains in dermatology clinics, enabling targeted therapeutic selection and repeat-visit revenue capture.
Market Restraints
- Salicylic acid supply concentration:Bulk pharmaceutical-grade supply chains for the primary over-the-counter active ingredient concentrate in Chinese chemical manufacturing clusters, exposing formulators to input volatility.
- Cryogen regulatory friction:The EPA's Clean Air Act restrictions on fluorinated propellants used in portable cryosurgical devices are constraining device portability and home-use expansion.
- Topical failure rates:Documented resistance to first-line salicylic acid and imiquimod regimens in plantar wart subtypes limits patient adherence and truncates repeat-purchase lifecycles.
Strategic Opportunities
- Retail health clinic penetration:CVS MinuteClinic and Walmart Health are adding medical dermatology services, creating new channel access for procedural therapies previously confined to independent practices.
- Telehealth prescription routing:Asynchronous dermatology platforms are capturing initial consultations and directing appropriate cases toward mail-order topical fulfillment or in-person procedural referrals.
- MDR device classification clarity:The EU Medical Device Regulation's clarified risk-classification for cryosurgical instruments is reducing notified body review timelines for novel delivery systems.
Industry Challenges
- Intralesional injection training:Dermatology residency programs offer limited hands-on exposure to bleomycin and Candida antigen administration, creating a skills gap as these modalities expand.
- Legacy EHR integration:Practice management systems in consolidated clinic networks require custom API development to capture structured wart-specific outcome data for payer reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warts Therapeutics Market |
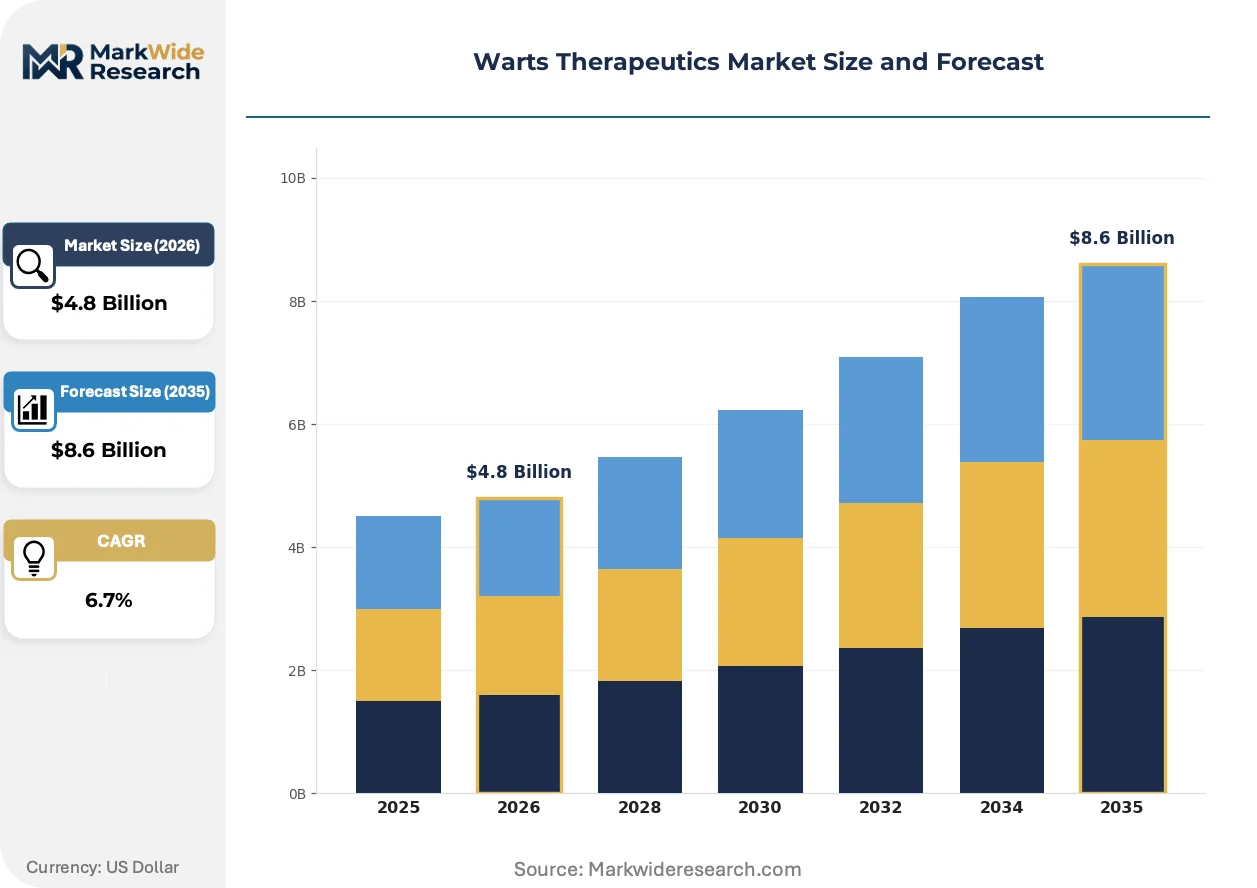
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryotherapy, Laser Therapy, Topical Treatments, Surgical Removal End User: Hospitals, Dermatology Clinics, Homecare Settings, Pharmacies Application: Plantar Warts, Common Warts, Genital Warts, Flat Warts Delivery Mode: Topical, Intralesional, Systemic, Combination Therapy |
| Companies Covered | Verrica Pharmaceuticals Inc., Bausch Health Companies Inc., GlaxoSmithKline plc, Merck & Co. Inc., Teva Pharmaceutical Industries Ltd., Pfizer Inc., Cipla Ltd., Novan Inc., Nielsen BioSciences Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warts Therapeutics Market Strategic Shifts
Automation of diagnostic-treatment coupling and the unbundling of care delivery from traditional site-of-service constraints are restructuring how patients access and pay for wart elimination across ambulatory settings.
Artificial intelligence-powered dermoscopy is automating the differential diagnosis of verrucous lesions against mimickers such as seborrheic keratoses and amelanotic melanoma. Dermatology clinics in the United States are deploying these algorithms at triage to reduce unnecessary biopsies and accelerate appropriate therapeutic routing. The technology is automating clinical decision support, compressing the time from presentation to definitive treatment initiation while reducing liability exposure from missed malignancies.
The EU F-Gas Regulation is phasing down hydrofluorocarbon propellants used in handheld cryosurgical devices, compelling manufacturers to reformulate around nitrogen or carbon dioxide delivery systems. Device makers are redesigning canister geometries and valve mechanisms to maintain therapeutic temperatures with alternative cryogens. The regulation most acutely affects portable consumer-directed devices, where form factor constraints conflict with thermal performance requirements under new substance restrictions.
Patients are self-triaging through direct-to-consumer telehealth platforms before presenting to physical clinics, altering the severity mix of in-person encounters toward refractory or atypical cases. Dermatology practices are responding by unbundling initial consultation from procedural reimbursement, capturing value through diagnostic clarity rather than throughput volume. This behavioral shift concentrates most visibly in suburban United States markets where digital health literacy and insurance cost-sharing incentives align.
Warts Therapeutics Market Segmentation
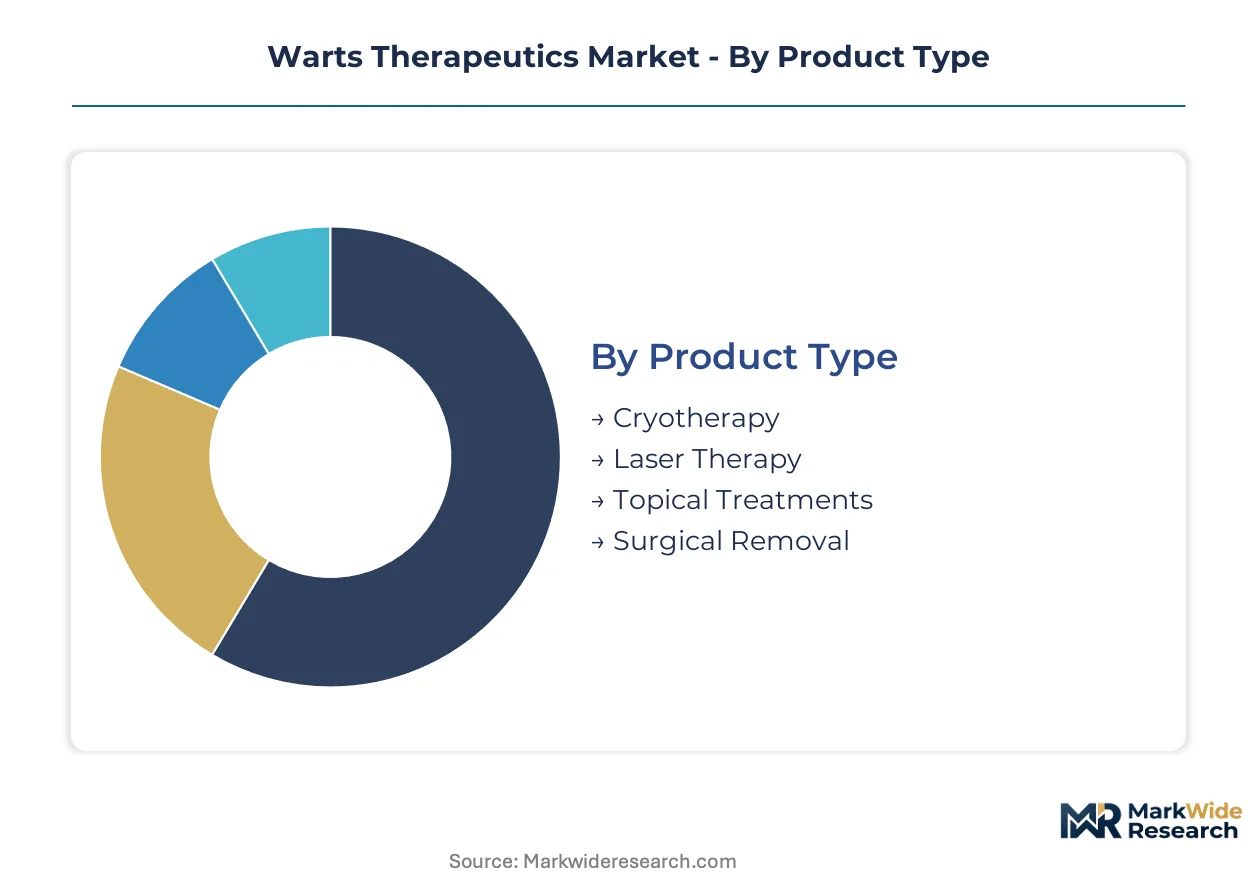
Treatment modality selection in the warts therapeutics market hinges on lesion location, viral strain classification, and reimbursement economics. Segmentation reveals how capital requirements and clinical workflows partition demand across ambulatory settings.
Product Type:
Cryotherapy and laser systems demand the highest upfront capital outlays, while topical formulations require minimal fixed investment but carry recurring formulation costs.
- Cryotherapy:Liquid nitrogen delivery systems and portable cryosurgical devices operate at temperatures below -196°C to induce targeted cell necrosis. United States dermatology clinics are expanding in-house cryotherapy suites as commercial payers broaden prior-authorization pathways for office-based procedures.
- Laser Therapy:Pulsed-dye and carbon dioxide laser platforms deliver precise thermal destruction with reduced scarring risk. Hospital outpatient departments in Germany and France are prioritizing laser acquisitions under EU Medical Device Regulation clarity, though equipment costs limit penetration in independent practices.
- Topical Treatments:Salicylic acid, imiquimod, and podophyllotoxin formulations dominate consumer-accessible segments with minimal capital barriers.
- Surgical Removal:Curettage and excision procedures require standard surgical instrumentation with low technology differentiation.
Topical treatments absorb the bulk of installed capacity; laser therapy is expanding most quickly among capital-intensive modalities.
End User:
Site-of-service economics and regulatory oversight intensity vary sharply across patient access points, reshaping where procedural versus pharmaceutical interventions concentrate.
- Dermatology Clinics:Multi-site networks in Texas, Florida, and California are consolidating independent practices to capture economies of scale in cryotherapy and intralesional administration. These clinics route refractory cases toward reimbursed procedures while managing formulary access for topical failures.
- Hospitals:Academic medical centers maintain laser therapy and surgical capabilities for complex or immunocompromised patient populations. REACH compliance harmonization across EU member states is accelerating centralized procurement of keratolytic agents for hospital pharmacies.
- Homecare Settings:Direct-to-consumer telehealth platforms are capturing initial consultations and routing appropriate cases toward mail-order topical fulfillment.
- Pharmacies:Retail health clinics at CVS MinuteClinic and Walmart Health locations are adding medical dermatology services, creating new channel access for procedural therapies.
Dermatology clinics command the highest procedure volumes; retail health clinic penetration is climbing the fastest.
Application:
Lesion anatomical location determines treatment resistance profiles, recurrence risk, and payer willingness to cover advanced immunotherapy.
- Plantar Warts:Deep epidermal invasion and pressure-induced hyperkeratosis produce documented resistance to first-line salicylic acid and imiquimod regimens. HPV typing integration at United States point-of-care platforms is identifying refractory viral strains, enabling targeted therapeutic selection.
- Genital Warts:Anogenital lesions carry distinct psychosocial and oncogenic risk profiles, driving demand for prescription-grade immunomodulators with durable clearance endpoints.
- Common Warts:Hand and finger lesions represent the most accessible home-treatment segment with established over-the-counter pathways.
- Flat Warts:Facial and extremity distribution in younger populations favors gentle topical approaches over destructive modalities.
Plantar warts generate the most refractory-case referrals; genital warts are gaining share fastest on immunotherapy expansion.
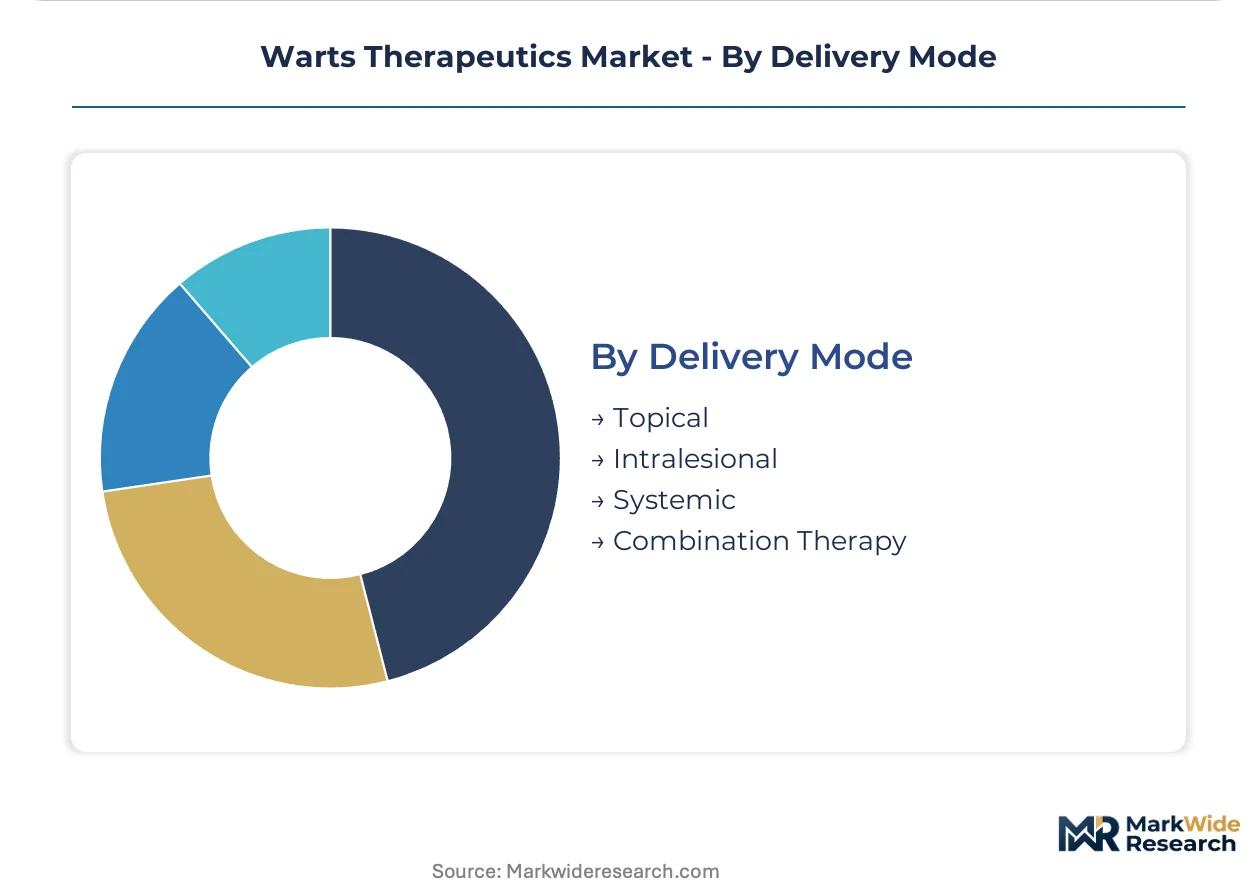
Delivery Mode:
Administration route selection balances patient convenience, clinician skill requirements, and pharmacokinetic targeting of infected epidermis.
- Intralesional:Bleomycin and Candida antigen injections deliver concentrated immunostimulation directly to lesion sites. Dermatology residency programs in the United States offer limited hands-on exposure, creating a skills gap as these modalities expand.
- Topical:Repeat-purchase patterns and home-use accessibility sustain the largest volume footprint across consumer and prescription channels.
- Systemic:Oral immunomodulators and retinoids address extensive or recalcitrant disease in immunocompromised populations.
- Combination Therapy:Sequential or concurrent topical-procedural protocols are emerging as standard of care for treatment-resistant presentations.
Topical delivery maintains the widest installed base; intralesional administration is expanding most quickly on clinical trial momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States commercial payers now route the majority of refractory wart cases toward reimbursed office-based procedures, concentrating demand in dermatology clinic networks across suburban and metropolitan markets. This demand-side concentration reshapes how product developers prioritize regulatory pathways and reimbursement strategy.
United States
Texas, Florida, and California host the fastest-consolidating dermatology clinic networks, capturing economies of scale in cryotherapy and intralesional administration. The FDA's Center for Drug Evaluation and Research oversees prescription topical and intralesional formulations, compressing clinical trial timelines for immunomodulator developers. Greater Houston and Dallas-Fort Worth metro areas concentrate multi-site practice acquisitions that centralize procurement of keratolytic agents.
Germany
Hospital outpatient departments in Bavaria and North Rhine-Westphalia prioritize laser therapy acquisitions under clarified EU Medical Device Regulation risk-classification standards. REACH compliance harmonization across EU member states accelerates centralized procurement of salicylic acid and trichloroacetic acid formulations for hospital pharmacies. The Munich-Stuttgart corridor concentrates medical device distribution networks serving ambulatory surgical centers.
United Kingdom
NHS England's expanding prior-authorization pathways for dermatology procedures route refractory cases toward secondary care settings, altering site-of-service economics. The Medicines and Healthcare products Regulatory Agency aligns with EMA guidance on topical immunomodulator efficacy endpoints. London and Greater Manchester concentrate telehealth platform development that captures initial consultations and directs patients toward mail-order topical fulfillment.
India
Maharashtra and Karnataka states see expanding retail pharmacy chains adding basic dermatology consultation services, creating new channel access for over-the-counter wart treatments. The Central Drugs Standard Control Organization regulates prescription-grade imiquimod and podophyllotoxin formulations under streamlined approval pathways. Mumbai and Bengaluru industrial clusters concentrate contract manufacturing of pharmaceutical-grade salicylic acid for export markets.
Japan
Kanto region dermatology clinics integrate point-of-care HPV typing platforms to identify refractory viral strains and enable targeted therapeutic selection. The Pharmaceuticals and Medical Devices Agency maintains distinct efficacy standards for durable clearance endpoints in immunotherapy approvals. The Tokyo-Osaka corridor concentrates medical device importers redesigning cryosurgical systems around nitrogen delivery to comply with EU F-Gas Regulation export standards.
Warts Therapeutics Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue intralesional immunotherapy and point-of-care diagnostic coupling. The market structure stratifies across three tiers: multinational pharmaceutical conglomerates with consumer-accessible over-the-counter distribution, specialty dermatology-focused developers with concentrated clinical trial pipelines, and contract manufacturers supplying bulk pharmaceutical-grade actives. Dominant competitive moves include multi-site dermatology clinic network acquisitions and technology licensing agreements for cryosurgical device redesign.
Within the specialty-focused tier, Verrica Pharmaceuticals Inc. and Novan Inc. occupy positions emphasizing viral skin disease concentration. GlaxoSmithKline plc and Merck & Co. Inc. exemplify the multinational pharmaceutical archetype with established prescription immunotherapy and consumer topical segments. Among these, Verrica Pharmaceuticals Inc. represents the clinical-trial-driven developer model, while GlaxoSmithKline plc anchors consumer-accessible distribution networks.
| Leading Market Players |
|---|
| Verrica Pharmaceuticals Inc. |
| Bausch Health Companies Inc. |
| GlaxoSmithKline plc |
| Merck & Co. Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Cipla Ltd. |
| Novan Inc. |
| Nielsen BioSciences Inc. |
| Others |
Value Chain & Pricing Dynamics
Bulk pharmaceutical-grade salicylic acid from Chinese chemical manufacturing clusters feeds a three-tier pricing structure across premium, standard, and economy levels, with concentration in upstream active ingredient supply creating asymmetric margin capture between formulators and raw material suppliers.
Pricing Analysis
Volume-driven over-the-counter topical formulations compete on shelf price and repeat-purchase frequency, while cryotherapy and intralesional immunotherapy command per-procedure premiums supported by United States commercial payer reimbursement. Price differentiation hinges on FDA regulatory tier for prescription-grade therapies and brand heritage in consumer segments. Cost compression in standard-tier salicylic acid formulations is intensifying because of input volatility from concentrated Chinese supply. Retail pharmacy chains exhibit highest price sensitivity; academic medical centers demonstrate lowest sensitivity due to bundled procurement and formulary control.
Supply Chain Analysis
CE marking and FDA 510(k) clearance requirements gate entry for cryosurgical device manufacturers, creating qualification barriers that protect incumbent positions. Active pharmaceutical ingredient production concentrates in China and India; device assembly clusters in Germany and the United States. Formulation draws from salicylic acid, trichloroacetic acid, and imiquimod bulk supplies. Single-source vulnerability in fluorinated propellant feedstocks for portable cryogenic devices poses structural risk under EPA Clean Air Act restrictions. Distribution runs through consolidated dermatology clinic networks, retail health clinic chains, and direct-to-consumer telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial intelligence-powered dermoscopy is displacing visual diagnosis for verrucous lesions, compressing the window for legacy triage methods and rewarding early movers in diagnostic-treatment coupling.
For Market Incumbents: Hedge against biosimilar competition in immunomodulator segments by deepening captive supply of pharmaceutical-grade actives through backward integration into Indian and Chinese API sourcing relationships. Defensive patent clustering around intralesional delivery mechanisms preserves margin in the fastest-expanding structural category.
For New Entrants and Emerging Players: EU Medical Device Regulation clarity on cryosurgical instrument risk-classification opens a window for novel nitrogen-based delivery systems redesigned around F-Gas compliance. White-space concentration sits with portable consumer-directed devices and telehealth-integrated prescription routing. A direct-to-consumer platform partnership with established asynchronous dermatology providers offers the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: FDA prior-authorization pathway expansion for office-based cryotherapy is the leading indicator that procedural reimbursement economics will sustain clinic network consolidation. Long-term viability favors specialty dermatology developers with concentrated viral skin disease pipelines over diversified pharmaceutical conglomerates. Monitor HPV typing platform adoption rates in Texas and Florida dermatology networks as the inflection signal for targeted therapeutic selection demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Verrica Pharmaceuticals' phase programs for viral skin diseases validate intralesional immunotherapy endpoints. |
| Regulatory Approval Pathway | FDA Center for Drug Evaluation and Research guidance compression accelerates immunomodulator development timelines. |
| Backward Integration | Formulators securing pharmaceutical-grade salicylic acid supply from Maharashtra and Karnataka clusters reduce input volatility. |
| Reimbursement Strategy | United States commercial payer prior-authorization documentation for cryotherapy sustains per-procedure pricing power. |
| Platform Integration | Telehealth-dermatology coupling with mail-order topical fulfillment captures patient routing before clinic presentation. |
Study Parameters
Multi-period observation of FDA submission timelines, payer prior-authorization pathway expansions, and dermatology clinic network consolidation patterns anchored the trend analysis, supplemented by interviews with drug development executives, formulary directors at United States commercial insurers, dermatology residency program directors, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, ClinicalTrials.gov protocol registrations, CMS Medicare procedure volume data, and EMA marketing authorization submissions. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated against cryotherapy procedure claims data.
Input-output matrix framing connected active ingredient supply volumes through formulation tiers to end-user channel demand across the projection horizon. Segmentation dimensions encompassed treatment modality, delivery mode, lesion anatomical location, and site-of-service economics. CAGRs were derived from patient volume projections and pricing trajectory assumptions. Forecast inputs included HPV typing platform adoption curves and REACH compliance harmonization timelines for keratolytic agent approvals.
The model assumes a particular technology adoption path for artificial intelligence-powered dermoscopy; alternative pathways for teledermatology triage automation would alter the outlook for in-person procedural volume concentration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Oral Vaccines Market
Pharmaceuticals
Meperidine Drugs Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Angiogenesis Inhibitors and Stimulators Market
Pharmaceuticals
Global Doxorubicin Market
Pharmaceuticals
Oral Antiviral Market
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
Antiviral Immunoglobulin Market
Pharmaceuticals
Psychedelic Drugs Market
Pharmaceuticals
Sweden Pharmaceutical Market
Pharmaceuticals
Liver Cancer Drug Market
Pharmaceuticals
Vaginitis Therapeutics Market
Pharmaceuticals
Compound Acetaminophen Market
Pharmaceuticals
Global Atherosclerosis Drugs Market