
 Candidiasis Drug Market | 2026-2036
Candidiasis Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Candidiasis Drug Market Insights
Subscription-based access programs for novel antifungal therapies is rebalancing how hospitals procure candidiasis treatments, shifting from episodic purchasing to bundled care contracts. Pfizer Inc. leverages its hospital formulary relationships to sustain volume commitments across acute care networks. Astellas Pharma Inc. anchors its position through deep specialization in invasive fungal infection portfolios. SCYNEXIS, Inc. differentiates via targeted development of next-generation azole derivatives with resistance-resistant mechanisms.
Candidiasis drugs comprise pharmaceutical agents designed to inhibit fungal cell wall synthesis, disrupt ergosterol biosynthesis, or interfere with fungal DNA replication, with azoles targeting lanosterol demethylase and echinocandins blocking beta-glucan synthase activity. These agents serve the primary clinical purpose of treating mucosal, invasive, and systemic Candida infections in immunocompromised and critically ill populations. Oral formulations retain the largest patient volume base due to outpatient convenience, while intravenous echinocandins command premium positioning in intensive care settings where candidemia requires rapid intervention. Immunocompromised patient categories generate the most intensive therapy requirements, driving sustained demand for hospital-administered polyenes and echinocandins.
FDA antifungal guidance, EMA orphan drug incentives, and WHO essential medicines list inclusion collectively shape development priorities and market access pathways for candidiasis therapeutics. The FDA's resistance surveillance mandates compel sponsors to incorporate antifungal stewardship data into new drug applications, while EMA incentives accelerate pediatric formulation development. Stakeholders must monitor evolving breakpoints from CLSI and EUCAST standards that redefine clinical efficacy thresholds and directly impact formulary positioning decisions.
Market Dynamics
Antifungal resistance surveillance mandates from the FDA are restructuring clinical trial protocols and forcing sponsors to embed stewardship data into development pipelines, compressing timelines for new molecular entities.
Growth Catalysts
- Hospital formulary consolidation:Acute care networks in the United States are standardizing antifungal protocols through centralized procurement, creating volume commitments for approved agents.
- EMA orphan drug incentives:Pediatric formulation development for invasive candidiasis receives accelerated regulatory review and market exclusivity protections.
- Immunocompromised patient expansion:Oncology and transplant centers are expanding bed capacity, intensifying demand for intravenous echinocandins in critical care settings.
Market Restraints
- Active pharmaceutical ingredient concentration:Azole precursor synthesis depends on concentrated Chinese and Indian intermediate suppliers, exposing formulators to supply disruption risk.
- Polyene nephrotoxicity profile:Amphotericin B's renal safety limitations restrict prolonged therapy in ICU populations with comorbid organ dysfunction.
- CLSI breakpoint revisions:Evolving susceptibility thresholds force sponsors to redesign non-inferiority margins mid-trial, extending validation timelines.
Strategic Opportunities
- Bundled care contracting:Subscription-based access programs for novel azole derivatives enable hospitals to shift from episodic purchasing to per-patient episode pricing.
- Next-generation resistance mechanisms:Lanosterol demethylase inhibitors with modified binding affinity profiles address emerging Candida auris isolates.
- WHO essential medicines list inclusion:Echinocandin class agents receive procurement prioritization in low- and middle-income health systems.
Industry Challenges
- Antifungal stewardship integration:Hospital pharmacy committees require real-time resistance surveillance dashboards, demanding IT infrastructure investments from formulary vendors.
- Specialized infectious disease expertise scarcity:Fellowship-trained candidemia management specialists concentrate in tertiary academic centers, limiting protocol standardization in community hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Candidiasis Drug Market |
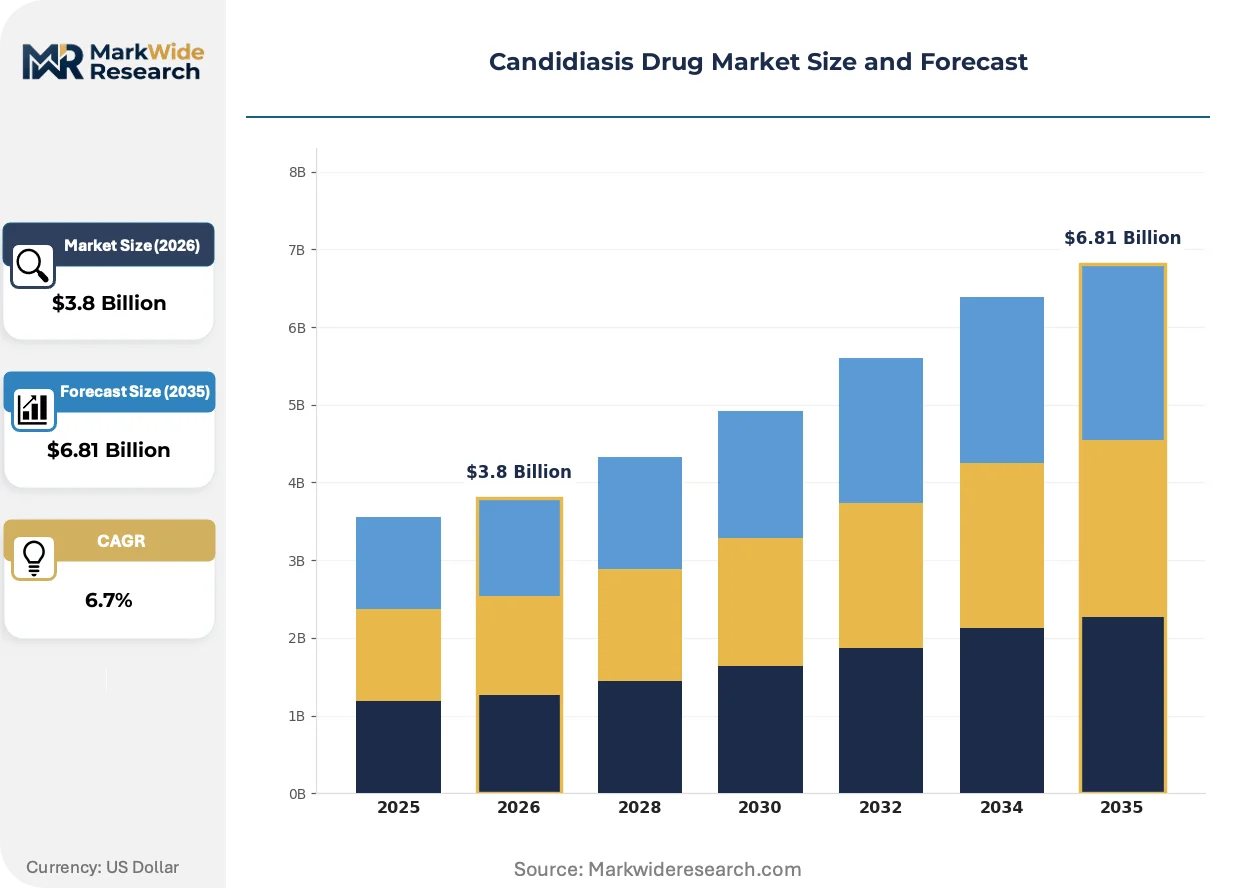
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Antifungal Agents, Azoles, Echinocandins, Polyenes Route of Administration: Oral, Intravenous, Topical, Vaginal Patient Type: Immunocompromised, Pediatric, Geriatric, Hospitalized Patients Treatment Setting: Outpatient, Inpatient, Home Healthcare, Long-term Care |
| Companies Covered | Pfizer Inc., Astellas Pharma Inc., SCYNEXIS, Inc., Basilea Pharmaceuticals, Viatris Inc., Mycovia Pharmaceuticals, Inc., Merck & Co., Inc., Novartis AG, GSK plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Candidiasis Drug Market Trends and Innovations
Resistance-resistant molecular architectures and stewardship-embedded trial designs are displacing legacy development approaches, while procurement models pivot toward outcomes-linked contracting.
Next-generation azole derivatives with modified sterol binding profiles are converging with rapid susceptibility testing platforms, enabling precision dosing in ICU settings. Hospital infectious disease departments in the United States are piloting these combinations to compress time-to-appropriate-therapy intervals. This convergence is collapsing the traditional empiric-to-targeted therapy transition window from 72 hours to under 24 hours.
REACH regulatory frameworks in Europe are mandating environmental fate assessments for antifungal manufacturing effluents, compelling API producers to install advanced wastewater treatment systems. Active pharmaceutical ingredient suppliers in Germany and Switzerland are retrofitting fermentation facilities to meet biodegradability thresholds. Echinocandin manufacturers face the steepest compliance costs due to lipopeptide structural complexity in waste streams.
Hospital procurement committees are unbundling antifungal acquisition from bundled infection management service contracts, separating drug cost from clinical pathway consulting. Acute care networks in the United States are negotiating direct manufacturer relationships that bypass traditional wholesale distribution. This disintermediation concentrates volume with formulary-incumbent suppliers while marginalizing secondary distributors.
Candidiasis Drug Market Segmentation
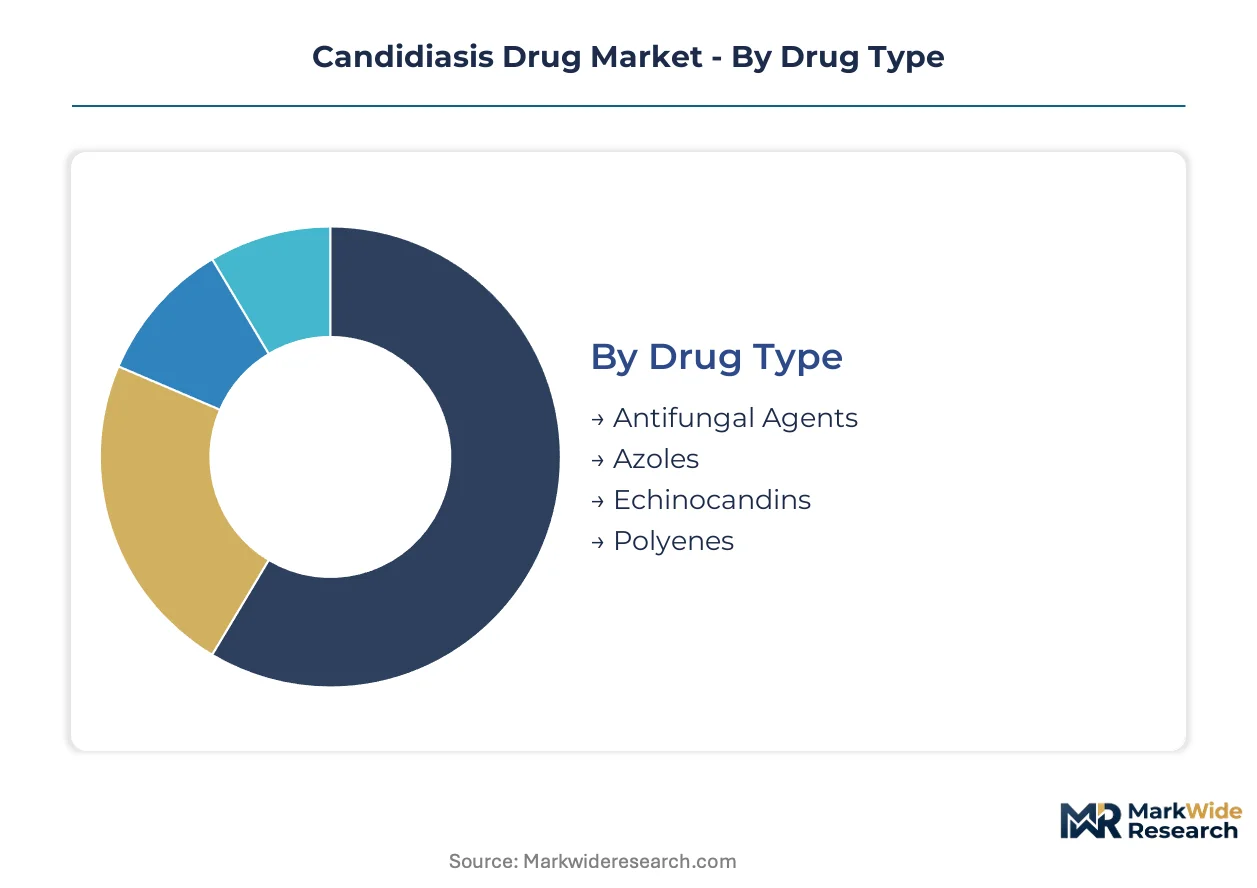
Segmentation in the candidiasis drug market reveals how formulation choices, patient risk profiles, and care settings determine procurement patterns and pricing power. Manufacturers align development pipelines with specific route-of-administration and patient-type combinations to secure formulary placement.
Drug Type:
Azoles and echinocandins operate as standalone first-line therapies, while polyenes and combination antifungal agents embed within broader critical care protocols where resistance surveillance drives selection.
- Azoles:Lanosterol demethylase inhibitors disrupt ergosterol biosynthesis through oral and intravenous formulations. Demand concentrates in outpatient oncology clinics across the United States where fluconazole prophylaxis protocols reduce breakthrough infections in chemotherapy patients.
- Echinocandins:Beta-glucan synthase blockers deliver fungicidal activity against Candida biofilms with superior safety profiles versus amphotericin B. Intensive care units in tertiary hospitals drive premium positioning where candidemia requires rapid intravenous intervention in hemodynamically unstable patients.
- Polyenes:Amphotericin B formulations retain niche positioning for azole-resistant Candida auris isolates despite nephrotoxicity constraints.
- Antifungal Agents:Combination and adjunctive therapies address polymicrobial infections in surgical intensive care populations.
Volume placements concentrate in azoles; the faster expansion belongs to echinocandins.
Route of Administration:
Oral and topical routes command cost-sensitive outpatient markets, while intravenous formulations capture margin-intensive inpatient episodes where bioavailability failures demand parenteral escalation.
- Intravenous:Parenteral echinocandins and liposomal amphotericin B achieve therapeutic concentrations in critically ill patients with compromised gastrointestinal absorption. Hospital pharmacy committees in the United States standardize IV-to-oral step-down protocols to reduce length-of-stay costs.
- Oral:Fluconazole and itraconazole capsules enable outpatient management of mucosal candidiasis with high patient compliance. Retail pharmacy networks drive volume through 90-day maintenance prescriptions for recurrent vulvovaginal cases.
- Topical:Creams and ointments address localized cutaneous infections in dermatology and primary care settings.
- Vaginal:Suppositories and creams target recurrent vulvovaginal candidiasis with over-the-counter availability in major pharmacy chains.
Oral formulations dominate prescription counts; intravenous routes capture the steepest revenue per patient.
Patient Type:
Immunocompromised and hospitalized categories generate intensive therapy requirements with prolonged duration, while pediatric and geriatric segments demand formulation adaptations for safety and compliance.
- Immunocompromised:Oncology, transplant, and HIV-positive populations require suppressive or empiric antifungal coverage due to neutropenia and cellular immune defects. Stem cell transplant centers in the United States mandate echinocandin prophylaxis for graft-versus-host disease patients on high-dose corticosteroids.
- Hospitalized Patients:Critically ill individuals with central lines, total parenteral nutrition, or broad-spectrum antibiotic exposure face elevated candidemia risk. Surgical intensive care units drive protocol-driven empiric therapy initiation before culture confirmation.
- Pediatric:Neonatal intensive care units require weight-based dosing adjustments and limited formulation availability creates supply vulnerabilities.
- Geriatric:Polypharmacy interactions and renal function decline necessitate dose modifications in long-term care facilities.
Hospitalized patients anchor volume commitments; immunocompromised populations are climbing the fastest in per-patient spending.
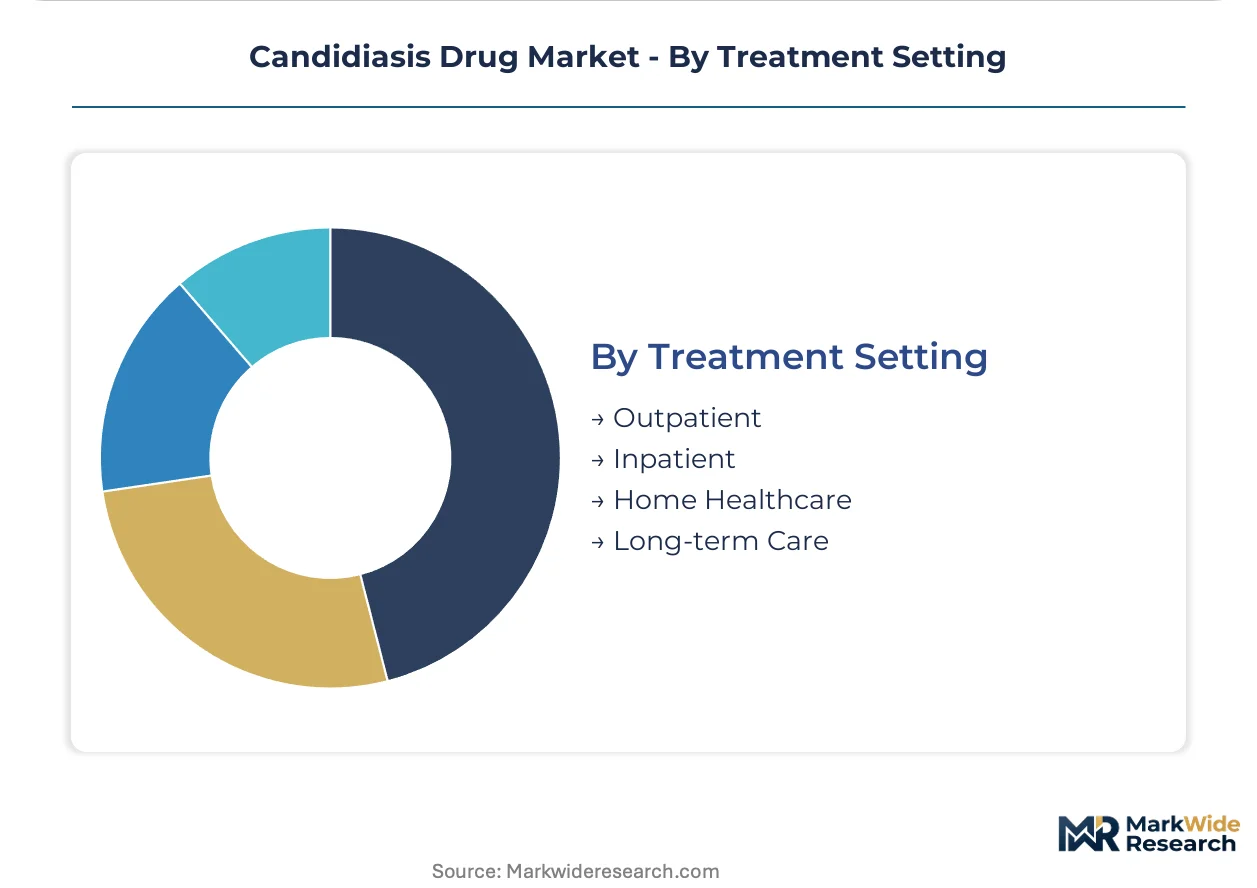
Treatment Setting:
Outpatient and home healthcare settings optimize convenience and cost, while inpatient and long-term care environments prioritize rapid therapeutic response and resistance containment.
- Inpatient:Acute care hospitals administer intravenous echinocandins and polyenes under infectious disease consultation for candidemia and invasive candidiasis. Formulary standardization across hospital networks in the United States creates volume concentration with approved agents.
- Outpatient:Primary care and infectious disease clinics prescribe oral azoles for mucosal and uncomplicated infections with retail pharmacy fulfillment. Telemedicine expansion post-pandemic has shifted initial diagnostic encounters to virtual platforms with e-prescribing.
- Home Healthcare:Outpatient parenteral antimicrobial therapy programs enable IV echinocandin administration in residential settings for stable patients.
- Long-term Care:Skilled nursing facilities manage oropharyngeal candidiasis in elderly residents with topical and oral formulations.
Inpatient settings retain the highest revenue per episode; home healthcare is gaining share fastest as payers push site-of-care migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors the highest concentration of infectious disease research institutions developing candidiasis therapeutics. The metropolitan corridor houses specialized transplant centers and oncology units that generate intensive antifungal demand. This geographic clustering shapes procurement patterns across North American hospital networks.
United States
FDA antifungal resistance surveillance mandates compel sponsors to embed stewardship data into new drug applications, compressing development timelines for novel molecular entities. The agency's evolving guidance on clinical trial requirements reshapes how manufacturers approach candidemia studies. Philadelphia's University City corridor hosts contract research organizations specializing in invasive fungal infection protocols.
Germany
REACH regulatory frameworks mandate environmental fate assessments for antifungal manufacturing effluents, compelling API producers to install advanced wastewater treatment systems. EMA orphan drug incentives accelerate pediatric formulation development for invasive candidiasis. Frankfurt's pharmaceutical manufacturing belt concentrates lipopeptide fermentation facilities facing steep biodegradability compliance costs.
Japan
PMDA accelerated review pathways for antifungal agents address Candida auris emergence in tertiary care settings. METI industrial policy supports domestic fermentation capacity for echinocandin precursors. Osaka's pharmaceutical corridor maintains specialized sterile manufacturing for intravenous antifungal formulations serving Asia-Pacific markets.
India
CDSCO streamlined approval processes for WHO prequalified antifungal generics expand access in low- and middle-income health systems. The country's national pharmaceutical regulator aligns with international susceptibility standards from CLSI and EUCAST. Hyderabad's Genome Valley clusters active pharmaceutical ingredient synthesis for azole intermediates supplying global formulators.
Switzerland
Swissmedic maintains stringent quality benchmarks for antifungal manufacturing that exceed baseline EMA requirements, creating premium positioning for domestically produced agents. Basel's pharmaceutical corridor concentrates headquarters operations for companies with specialized infectious disease portfolios. The region's contract manufacturing organizations serve as critical suppliers for European hospital formulary networks.
Candidiasis Drug Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the candidiasis drug market, with integrated pharmaceutical conglomerates maintaining captive fermentation capacity while biotechnology specialists outsource manufacturing to contract partners. The structure concentrates around three tiers: research-intensive developers of novel mechanisms, established formulators with hospital formulary relationships, and generic manufacturers supplying cost-sensitive outpatient markets. Competitive positioning depends on securing volume commitments through acute care network procurement contracts and navigating evolving regulatory requirements for resistance surveillance data.
Within the research-intensive tier, SCYNEXIS, Inc. and Mycovia Pharmaceuticals, Inc. exemplify asset-light developers focused on next-generation molecular architectures. Pfizer Inc. anchors the established formulator segment with deep hospital network penetration. These three companies occupy distinct strategic positions: the specialists concentrate on resistance-resistant mechanisms, while the integrated incumbent leverages existing formulary relationships to sustain volume across acute care networks. Geographic distribution spans American, Swiss, and Japanese headquarters, reflecting the global dispersion of antifungal development expertise.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Astellas Pharma Inc. |
| SCYNEXIS, Inc. |
| Basilea Pharmaceuticals |
| Viatris Inc. |
| Mycovia Pharmaceuticals, Inc. |
| Merck & Co., Inc. |
| Novartis AG |
| GSK plc |
| Others |
Pricing and Supply Chain Analysis
Captive fermentation capacity at Pfizer Inc. and Astellas Pharma Inc. anchors both supply security and premium pricing power for intravenous echinocandins, while asset-light developers like SCYNEXIS, Inc. outsource manufacturing and compete on value-based contracting rather than volume scale.
Pricing Analysis
Cost-down pressure on oral azole generics accelerates because Indian and Chinese API suppliers compete on fermentation yield efficiency, while intravenous echinocandins maintain premium positioning through hospital formulary exclusivity and resistance-resistant clinical profiles. Three-tier pricing structure across premium, standard, and economy levels separates originator liposomal amphotericin B from branded echinocandins and commodity fluconazole. Price differentiation hinges on FDA resistance surveillance data requirements and formulary tier placement. Community hospitals exhibit highest price sensitivity due to constrained pharmacy budgets; academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Azole precursor synthesis rests on concentrated intermediate suppliers in China and India, with lipopeptide fermentation for echinocandins anchored in Germany, Switzerland, and Japan. Active pharmaceutical ingredient production draws from specialized fermentation facilities, purified intermediate streams, and sterile fill-finish capacity. Single-source vulnerability concentrates in Chinese suppliers of tetrazole and imidazole building blocks. Distribution runs through hospital procurement committees negotiating direct manufacturer relationships that bypass wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive fermentation capacity and downstream formulary control is becoming the decisive competitive lever as resistance surveillance requirements compress development timelines and API supply concentration creates vulnerability.
For Market Incumbents: Deepen hospital formulary relationships through bundled stewardship service contracts that embed real-time resistance surveillance dashboards. Expand captive lipopeptide fermentation capacity in Switzerland or Germany to reduce dependency on Asian intermediate suppliers. Lock in volume commitments across acute care networks before next-generation azole derivatives reach Phase III endpoints. For New Entrants and Emerging Players: Community hospital infectious disease departments represent the most penetrable buyer archetype given scarcity of fellowship-trained candidemia specialists and limited formulary standardization. Target outpatient oncology clinics for oral prophylaxis formulations with 90-day maintenance prescribing protocols. Pursue EMA orphan drug designation to accelerate pediatric formulation development and secure market exclusivity protections. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated pharmaceutical conglomerates seeking resistance-resistant molecular architectures to refresh hospital portfolios. Long-term viability favors developers with Phase II-ready next-generation azoles and established API supply agreements. Watch for FDA breakpoint revisions that redefine non-inferiority margins and trigger portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Stewardship-Embedded Trial Design | FDA resistance surveillance mandates now require antifungal stewardship data in new drug applications. |
| Pediatric Formulation Development | EMA orphan drug incentives accelerate review timelines and extend market exclusivity for neonatal indications. |
| API Supply Security Investment | REACH compliance costs and Chinese supplier concentration drive backward integration into European fermentation capacity. |
| Hospital Procurement Direct Contracting | Acute care networks bypass wholesale distribution to negotiate volume commitments with formulary-incumbent manufacturers. |
| Resistance-Resistant Mechanism R&D | Modified lanosterol demethylase inhibitors address emerging Candida auris isolates with reduced azole susceptibility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with infectious disease specialists, hospital formulary directors, pharmaceutical regulatory affairs leads, and API procurement managers at contract manufacturers. FDA antifungal guidance documents, EMA orphan drug designation records, ClinicalTrials.gov entries, and WHO essential medicines list submissions provided secondary validation. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure analysis were triangulated against hospital procurement database extracts.
Reconciliation of prescription volume streams, ASP trends, and formulary placement data informed the analytical framework across the projection horizon. Segmentation dimensions included drug class mechanism, route of administration, patient risk category, treatment setting, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to hospital admission volumes and immunocompromised population projections. Resistance surveillance breakpoint revisions and EMA pediatric incentive utilization rates served as industry-specific forecast inputs.
Revisions become necessary when FDA guidance shifts on antifungal resistance surveillance requirements, when CLSI or EUCAST breakpoints are redefined, or when API supply disruptions alter manufacturing cost structures. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Exocrine Pancreatic Insufficiency (EPI) Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Indapamide Market
Pharmaceuticals
Short-Acting Insulin Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Antibodies Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market
Pharmaceuticals
North America Anticoccidial Drugs Market
Pharmaceuticals
Global Human Vaccines Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Artificial Intelligence in Drug Screening Market
Pharmaceuticals
Fibroblast Activation Protein Inhibitors Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Asia-Pacific Vaccines Market