
 Bladder Cancer Treatment Drugs Market | 2026-2036
Bladder Cancer Treatment Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Bladder Cancer Treatment Drugs Market Outlook
Oncology nursing specialization is rotating toward immuno-oncology administration and biomarker-guided patient monitoring, tightening labor availability for conventional chemotherapy units. Bristol-Myers Squibb Company leverages its PD-1 inhibitor manufacturing scale to sustain supply across major treatment centers. Merck & Co. Inc. anchors its position through deep clinical trial investment in neoadjuvant settings. F. Hoffmann-La Roche Ltd differentiates via companion diagnostic integration with its therapeutic portfolio.
Bladder cancer treatment drugs comprise pharmaceutical agents designed to eliminate or control malignant urothelial cells, spanning cytotoxic chemotherapeutics, immune checkpoint inhibitors, antibody-drug conjugates, and targeted small molecules formulated for intravesical, oral, or parenteral delivery. These agents function by inducing apoptosis, blocking immune evasion pathways, or inhibiting oncogenic signaling to prevent recurrence, progression, or metastasis in patients across the disease spectrum. Immunotherapy now leads clinical preference for non-muscle invasive disease, while intravenous targeted therapy captures margin concentration in metastatic lines where standard-of-care failure rates drive protocol escalation. Patient type segmentation reveals the fastest growth trajectory in recurrent cases, where repeated BCG failure creates urgent demand for alternative intravesical and systemic options.
The FDA's breakthrough therapy designation and the EMA's PRIME scheme compress development timelines, compelling sponsors to generate biomarker-defined efficacy data earlier in regulatory engagement. NMPA reform of oncology drug review procedures in China is expanding market access for imported checkpoint inhibitors, while Japan's PMDA Sakigake designation accelerates domestic availability of novel mechanisms. Stakeholders must monitor how evolving PD-L1 expression thresholds in labeling claims reshape prescriber selection criteria and payer prior authorization requirements across jurisdictions.
Market Dynamics
The FDA's accelerated approval pathway for breakthrough therapies is compressing clinical trial timelines and forcing sponsors to front-load biomarker-defined efficacy data, fundamentally restructuring how developers allocate R&D capital across the bladder cancer pipeline.
Growth Catalysts
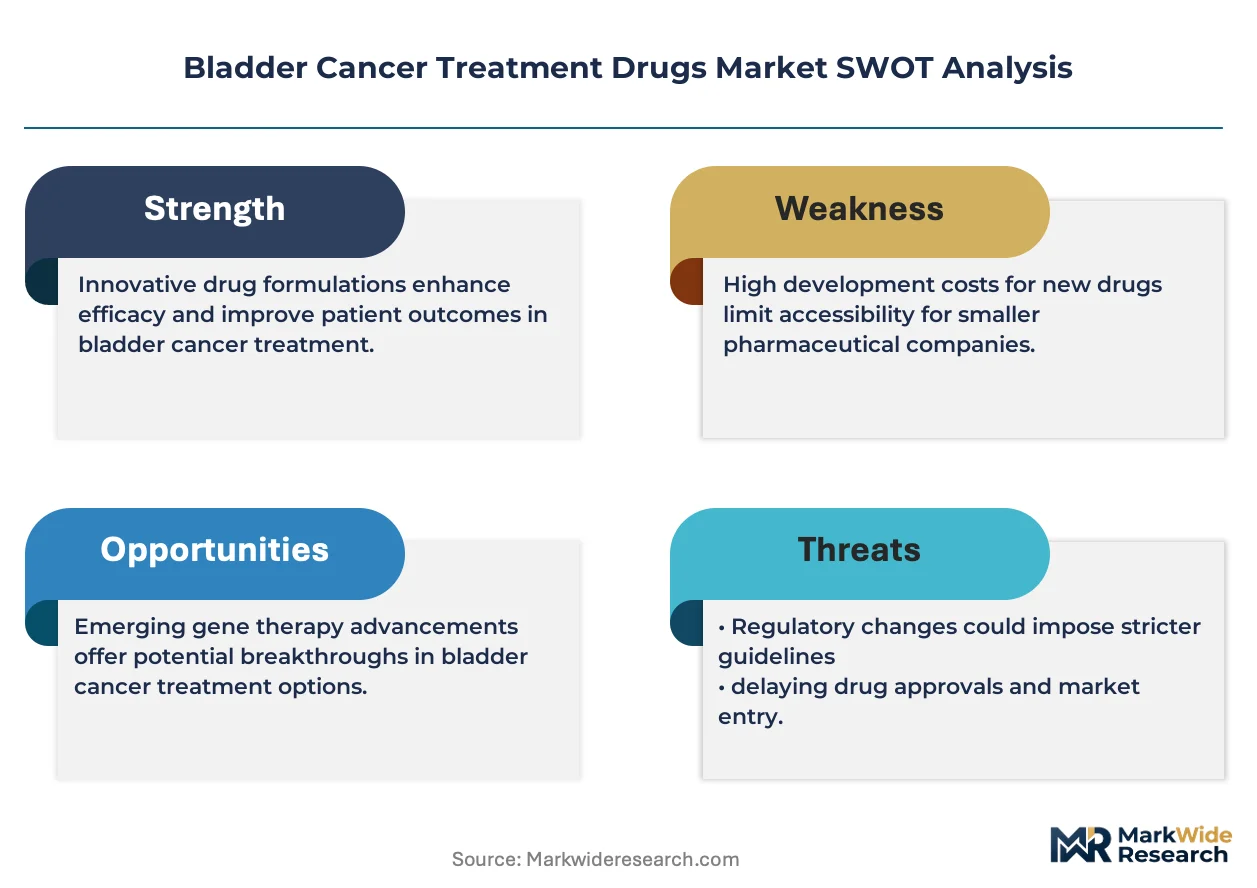
- Breakthrough Therapy Designation:The FDA's expedited review pathway reduces regulatory friction for novel checkpoint inhibitors, enabling faster patient access to first-in-class mechanisms.
- BCG Shortage Protocol Escalation:Persistent supply disruptions of bacillus Calmette-Guérin are driving tertiary hospitals toward intravesical immunotherapy alternatives, expanding addressable volume for novel agents.
- Companion Diagnostic Integration:PD-L1 expression testing is becoming standard-of-care in oncology clinics, creating pull-through demand for biomarker-matched therapeutic portfolios.
Market Restraints
- Platinum-Based Chemotherapy Input Costs:Cisplatin and carboplatin supply chains remain vulnerable to active pharmaceutical ingredient concentration in India and China, creating price volatility for standard-of-care regimens.
- Reimbursement Compression:Medicare's increasingly restrictive prior authorization requirements for intravenous immunotherapy are extending treatment initiation timelines and dampening prescriber enthusiasm.
- Technical Limitation in Non-Muscle Invasive Disease:Current systemic agents demonstrate limited tissue penetration for superficial tumors, constraining efficacy in the largest patient segment by incidence.
Strategic Opportunities
- Neoadjuvant Setting Expansion:Muscle-invasive disease protocols are shifting toward pre-surgical systemic therapy, opening new treatment windows before radical cystectomy.
- Antibody-Drug Conjugate Convergence:Nectin-4 targeted payloads combined with immune checkpoint blockade are creating combination therapy white space distinct from monotherapy positioning.
- Japan's PMDA Sakigake Designation:Accelerated domestic approval timelines for novel mechanisms enable first-mover advantage in a high-price, concentrated-payer market.
Industry Challenges
- Immuno-Oncology Nursing Scarcity:Specialized training for biomarker-guided patient monitoring and immune-related adverse event management is outpacing labor pool expansion, creating bottlenecks at infusion centers.
- Legacy EHR Integration Friction:Real-world evidence capture for accelerated approval confirmatory trials requires interoperability with hospital data systems that lack standardized oncology module architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bladder Cancer Treatment Drugs Market |
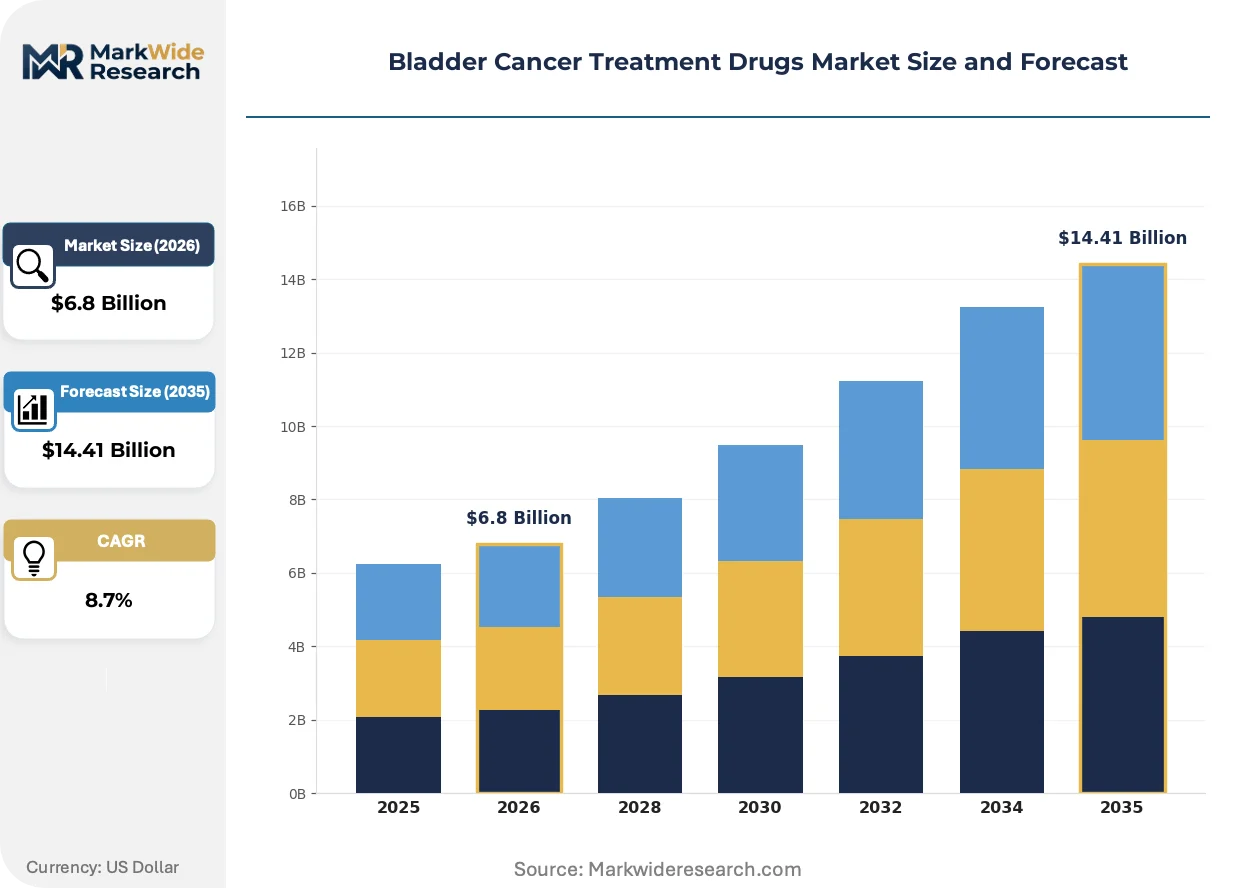
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Chemotherapy, Immunotherapy, Targeted Therapy, Hormonal Therapy Administration Route: Intravesical, Oral, Intravenous, Subcutaneous Patient Type: Recurrent, Non-Muscle Invasive, Muscle-Invasive, Metastatic Development Stage: Clinical Trials, Market Approval, Preclinical, Research |
| Companies Covered | Bristol-Myers Squibb Company, Merck & Co. Inc., F. Hoffmann-La Roche Ltd, AstraZeneca PLC, Johnson & Johnson, Pfizer Inc., GlaxoSmithKline PLC, Novartis AG, CG Oncology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bladder Cancer Treatment Drugs Market Strategic Shifts
Novel antibody-drug conjugate payloads are fragmenting established treatment hierarchies across disease stages, while regulatory pressure on biomarker-driven development is compressing traditional trial design assumptions.
FGFR inhibitor therapy is fragmenting the metastatic second-line landscape as academic medical centers adopt comprehensive genomic profiling for all progressing patients. Urology practices with embedded molecular tumor boards are identifying actionable alterations at twice the rate of community settings. This molecular stratification is fragmenting what was previously a homogeneous chemotherapy-refractory population into discrete targetable subgroups.
The EMA's PRIME scheme is compressing development timelines for sponsors willing to generate European-specific efficacy data earlier in regulatory engagement. Developers now face pressure to include EU sites in pivotal trials rather than relying on FDA approval as a regulatory bridge. This shift is most pronounced for checkpoint inhibitor combinations where EMA labeling claims increasingly diverge from FDA-approved indications.
Specialized oncology pharmacies are displacing traditional hospital outpatient departments as the preferred distribution channel for oral targeted agents. Third-party logistics providers with cold-chain capabilities are capturing volume from institutional pharmacies ill-equipped for temperature-sensitive biologics. This channel migration is most visible in the United States, where Medicare's 340B program creates financial incentives for hospital-affiliated specialty pharmacies.
Bladder Cancer Treatment Drugs Market Segmentation
Segmentation in bladder cancer therapeutics reveals how regulatory pathways and clinical trial designs allocate R&D capital across distinct mechanistic categories. Treatment hierarchies fragment along biomarker-defined eligibility criteria, reshaping prescriber selection and payer reimbursement logic.
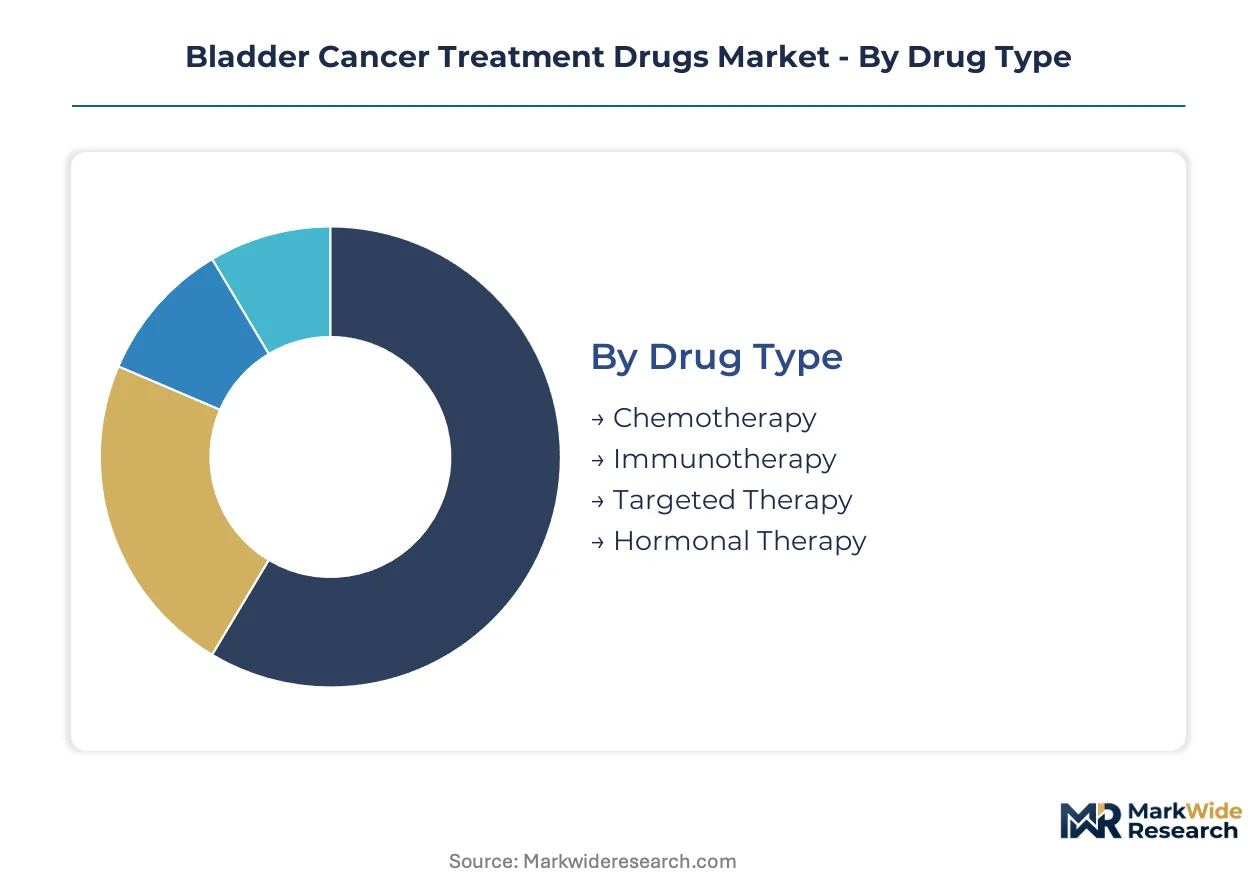
Drug Type:
FDA breakthrough therapy designation and EMA PRIME scheme eligibility diverge sharply across mechanistic classes, compressing development timelines for immunomodulatory agents while maintaining conventional review cycles for cytotoxic platforms.
- Chemotherapy:Platinum-based regimens (cisplatin, carboplatin, gemcitabine) retain standard-of-care status in neoadjuvant and first-line metastatic settings. Demand concentrates in community oncology practices where biomarker testing penetration lags academic centers, constrained by Medicare reimbursement compression for intravenous administration.
- Immunotherapy:PD-1 and PD-L1 checkpoint inhibitors dominate non-muscle invasive disease after BCG failure, with intravesical delivery formats expanding. Adoption accelerates in tertiary hospitals with embedded molecular tumor boards, driven by NCI-funded protocol expansion and prior authorization pathway standardization.
- Targeted Therapy:FGFR inhibitors and antibody-drug conjugates address genomic subsets in metastatic progression. Clinical uptake tracks companion diagnostic availability.
- Hormonal Therapy:Limited application in urothelial carcinoma; investigational use in specific histological variants. Research-stage pipeline concentration.
Established volume favors chemotherapy; emerging adoption favors immunotherapy.
Administration Route:
Cost tier stratification separates hospital-based infusion services from ambulatory oral dispensing, with cold-chain logistics capabilities determining channel access for biologics.
- Intravesical:Direct bladder instillation of BCG and investigational immunotherapies preserves urologist control in non-muscle invasive disease. Demand localizes in high-volume cystoscopy centers with dedicated pharmacy compounding facilities, constrained by BCG supply volatility and sterile preparation requirements.
- Intravenous:Systemic checkpoint inhibitors and cytotoxic regimens require infusion center infrastructure. Concentration in Medicare-certified hospital outpatient departments with immuno-oncology nursing specialization.
- Oral:FGFR inhibitors and small-molecule targeted agents shift fulfillment toward specialty pharmacies with 340B program participation.
- Subcutaneous:Emerging delivery format for checkpoint inhibitors; penetration limited by formulation stability and injection volume constraints.
Institutional revenue concentrates in intravenous; patient convenience and pharmacy margin expansion favor oral.
Patient Type:
Disease stage at presentation determines addressable therapeutic intensity, with progression events creating multiple treatment episodes per patient lifetime.
- Recurrent:Repeated BCG failure creates urgent demand for alternative intravesical and systemic options. Volume concentrates in academic medical centers with protocol access to investigational agents, climbing the fastest as salvage therapy development prioritizes this population.
- Metastatic:Second-line and later therapy sequences require biomarker-directed selection. Demand fragments across comprehensive genomic profiling capabilities.
- Non-Muscle Invasive:Largest incident population by volume; constrained by limited systemic agent tissue penetration for superficial tumors.
- Muscle-Invasive:Neoadjuvant protocol expansion opens pre-surgical treatment windows before radical cystectomy.
Incident volume favors non-muscle invasive; revenue intensity and protocol innovation favor recurrent.
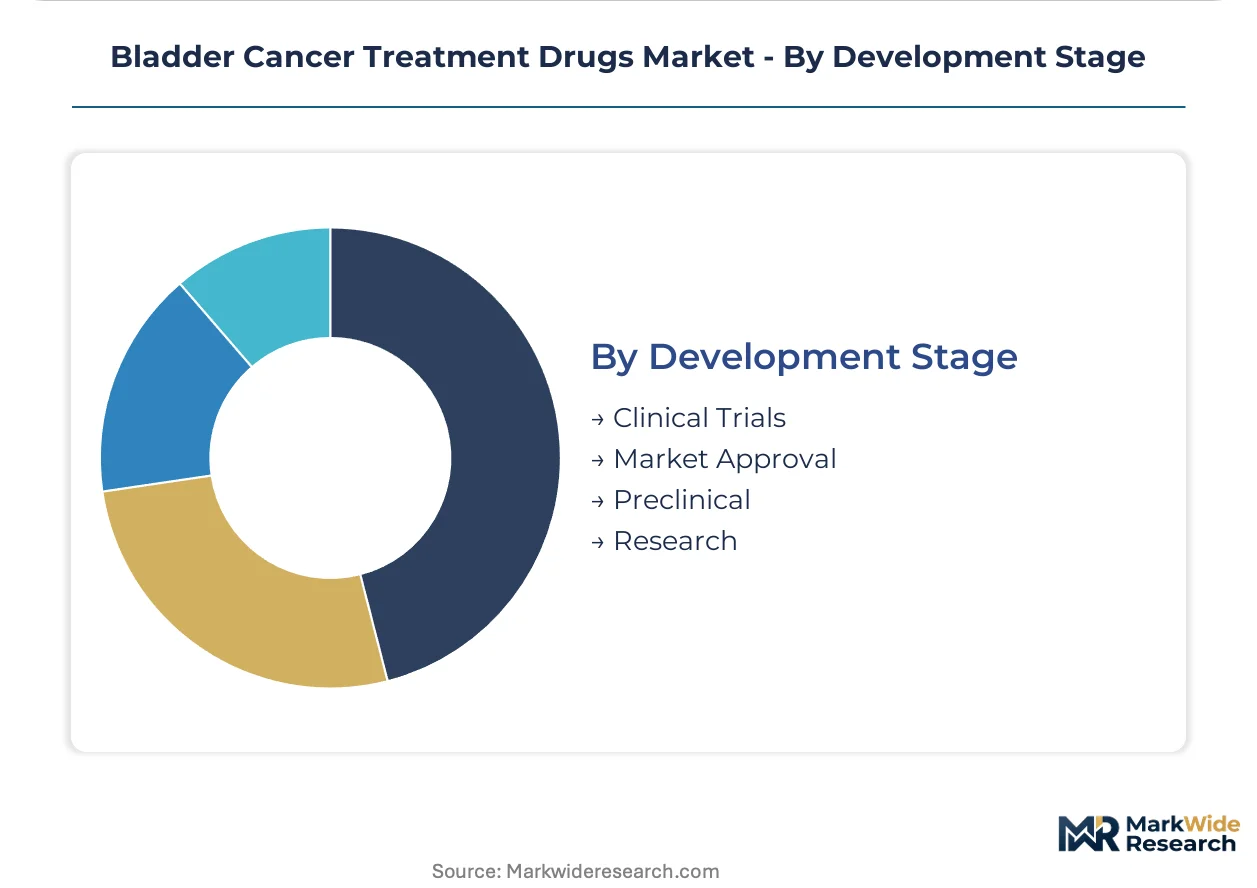
Development Stage:
Regulatory capital allocation tilts toward late-stage assets with biomarker-defined efficacy datasets, compressing preclinical and early-phase funding availability.
- Market Approval:Commercialized agents with established reimbursement codes capture prescriber familiarity and formulary placement. Concentration in checkpoint inhibitor and antibody-drug conjugate portfolios with companion diagnostic alignment.
- Clinical Trials:Phase II and III studies for neoadjuvant indications and combination regimens absorb investigator site capacity. Enrollment competition intensifies across NCI-funded networks and academic medical centers.
- Preclinical:Novel payload mechanisms and intravesical delivery technologies face funding constraints without human efficacy signals.
- Research:Early target validation and biomarker discovery programs; limited pharmaceutical industry engagement without translational partnership structures.
Revenue realization favors market approval; pipeline optionality and regulatory priority review favor clinical trials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough therapy designation and Medicare reimbursement policies anchor United States demand, while EMA PRIME scheme access and Japan's PMDA Sakigake designation create parallel regulatory pathways across developed markets.
United States
Medicare reimbursement policies sustain treatment access across NCI-funded research networks. The FDA's accelerated approval pathway compresses clinical trial timelines for novel checkpoint inhibitors. Tertiary hospitals in Boston, Houston, and New York anchor immuno-oncology protocol expansion.
Germany
Comprehensive genomic profiling adoption in academic medical centers drives biomarker-directed therapy selection. EMA PRIME scheme eligibility accelerates European market entry for sponsors with EU-specific efficacy data. The Rhine-Ruhr and Munich clusters concentrate urology practice consolidation.
Japan
PMDA Sakigake designation enables domestic availability of novel mechanisms ahead of standard review cycles. Aging demographics expand the incident patient pool for muscle-invasive disease protocols. The Kanto region around Tokyo anchors pharmaceutical distribution infrastructure.
China
NMPA reform of oncology drug review procedures expands market access for imported checkpoint inhibitors. Domestic pharmaceutical investment concentrates in Shanghai and Beijing biotech corridors. Tier-one hospitals accelerate companion diagnostic integration.
United Kingdom
NICE technology appraisals reshape NHS formulary placement for antibody-drug conjugates. Genomic England's tumor profiling networks fragment treatment hierarchies in metastatic settings. The Greater Manchester and London cancer centers drive neoadjuvant protocol adoption.
Bladder Cancer Treatment Drugs Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the bladder cancer treatment drugs market. Large-cap pharmaceutical conglomerates with PD-1 inhibitor manufacturing scale anchor supply security for infusion centers. Mid-tier biotech specialists concentrate on novel payload mechanisms and intravesical delivery formats. The dominant competitive moves center on companion diagnostic integration and neoadjuvant indication expansion through clinical trial investment.
Within the large-cap tier, Bristol-Myers Squibb Company, Merck & Co. Inc., and F. Hoffmann-La Roche Ltd represent the archetype of checkpoint inhibitor scale and regulatory sophistication. These entities occupy positions defined by manufacturing capacity and biomarker-guided portfolio alignment rather than therapeutic mechanism novelty alone.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Merck & Co. Inc. |
| F. Hoffmann-La Roche Ltd |
| AstraZeneca PLC |
| Johnson & Johnson |
| Pfizer Inc. |
| GlaxoSmithKline PLC |
| Novartis AG |
| CG Oncology Inc. |
| Others |
Value Chain & Pricing Dynamics
FDA breakthrough therapy designation gates both supply qualification and price differentiation for novel bladder cancer agents, compressing development timelines for sponsors who front-load biomarker-defined efficacy data while simultaneously enabling premium positioning against standard-of-care regimens. This regulatory threshold simultaneously constrains which manufacturers can enter the market and determines the pricing latitude available to those who clear it.
Pricing Analysis
Geographic price spreads widen between the United States and European markets, with Medicare reimbursement policies sustaining higher price floors for intravenous immunotherapy in American tertiary hospitals compared to NHS formulary negotiations in the United Kingdom. Three-tier pricing structure across premium checkpoint inhibitors, standard platinum-based chemotherapy, and economy BCG alternatives reflects companion diagnostic alignment and manufacturing scale. Pricing pressure stems from Medicare's increasingly restrictive prior authorization requirements, extending treatment initiation timelines. Community oncology practices exhibit highest price sensitivity due to biomarker testing cost absorption, while academic medical centers with NCI-funded protocol access demonstrate lowest sensitivity.
Supply Chain Analysis
Inbound logistics costs for temperature-sensitive biologics fluctuate with container availability on Asia-Pacific trade lanes serving active pharmaceutical ingredient manufacturers in India and China. Cisplatin and carboplatin supply chains concentrate in Indian and Chinese API facilities, while finished dose formulation for checkpoint inhibitors centers on Massachusetts and Puerto Rico manufacturing networks. Raw material dependencies span platinum salts, monoclonal antibody cell lines, and sterile diluents. Single-source vulnerability pervades BCG production, where limited global manufacturing sites create recurrent shortage conditions. Distribution runs through specialty pharmacy channels with cold-chain capabilities, displacing traditional hospital outpatient departments for oral targeted agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment, where FDA breakthrough therapy designation and companion diagnostic integration create switching costs that lock prescribers into established therapeutic portfolios.
For Market Incumbents: Compound manufacturing scale advantages in PD-1 inhibitor production by securing long-term cell line supply agreements with contract development organizations. Deepen biomarker-guided portfolio alignment through companion diagnostic co-development with molecular testing laboratories, defending against emerging antibody-drug conjugate specialists threatening to fragment metastatic treatment hierarchies. Prioritize neoadjuvant indication expansion through investigator-initiated trial networks before radical cystectomy protocols standardize. For New Entrants and Emerging Players: Anchor in the recurrent non-muscle invasive disease segment, where repeated BCG failure creates urgent demand for alternative intravesical immunotherapies and prescriber willingness to adopt novel mechanisms exceeds metastatic settings. Target urology practices with embedded molecular tumor boards in the American Midwest and German Rhine-Ruhr clusters, where genomic profiling adoption outpaces community oncology. Pursue conditional approval pathways leveraging single-arm Phase II efficacy data in biomarker-defined populations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across antibody-drug conjugate manufacturing, where payload-linker chemistry expertise and sterile bioconjugation capacity command scarcity premiums. Favor acquisition targets with proprietary intravesical delivery technologies or nectin-4 targeted payloads positioned for combination therapy development. Monitor EMA PRIME scheme enrollment rates as an inflection indicator for European market access velocity and pricing power realization.| Strategic Initiative | Industry Significance |
|---|---|
| Neoadjuvant Clinical Trial Expansion | Muscle-invasive disease protocols shift toward pre-surgical systemic therapy before radical cystectomy. |
| Companion Diagnostic Co-Development | PD-L1 expression testing standardization creates pull-through demand for biomarker-matched portfolios. |
| Specialty Pharmacy Channel Partnership | Medicare's 340B program incentives drive hospital-affiliated pharmacy capture of oral targeted agent dispensing. |
| Antibody-Drug Conjugate Manufacturing Scale-Up | Nectin-4 targeted payload production requires sterile bioconjugation capacity concentrated in Puerto Rico facilities. |
| Japan PMDA Sakigake Designation Pursuit | Accelerated domestic approval timelines enable first-mover positioning in concentrated-payer markets. |
Study Parameters
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and Medicare reimbursement databases. Bottom-up patient flow modeling across treatment lines and administration routes triangulated with top-down pharmaceutical revenue segmentation to ensure consistency.
Outputs were validated against external benchmarks including NCI-funded protocol enrollment data and comprehensive genomic profiling adoption rates reported by molecular diagnostic laboratories. The analytical framework segmented volume and value across drug type, administration route, patient disease stage, and regional regulatory cluster throughout the projection horizon. CAGRs were derived from treatment episode frequency, protocol escalation patterns, and biomarker eligibility expansion assumptions.
Underlying assumptions cover continued BCG shortage conditions, Medicare reimbursement stability, and companion diagnostic penetration rates, with deviation risk concentrated in FDA labeling claim modifications for PD-L1 expression thresholds and EMA-FDA indication divergence for checkpoint inhibitor combinations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Testosterone Nasal Gels Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
Global Treatment-Resistant Depression Market
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
Cholinesterase Inhibitors Market
Pharmaceuticals
US Pharmaceutical CMO Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Global Monoclonal Antibody Therapeutics Market
Pharmaceuticals
Zoledronic Acid Market
Pharmaceuticals
Antidiuretic Drugs Market
Pharmaceuticals
Plasma-Derived Drugs Market
Pharmaceuticals
Capecitabine Market
Pharmaceuticals
Latin America Generic Injectables Market
Pharmaceuticals
Diuretic Drugs Market