
 Autosomal Dominant Polycystic Kidney Disease Treatment Market | 2026-2036
Autosomal Dominant Polycystic Kidney Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Autosomal Dominant Polycystic Kidney Disease Treatment Market Outlook
The ADPKD treatment landscape is restructuring around a sharp divergence between premium genetic therapies and commodity symptomatic medications. Vertex Pharmaceuticals leverages its cystic fibrosis cash flows to fund high-risk gene-editing programs for polycystic kidney disease. Otsuka Pharmaceutical anchors the volume tier through its established tolvaptan franchise and nephrology hospital relationships. Galapagos NV competes via differentiated small-molecule discovery platforms targeting novel disease pathways.
Autosomal dominant polycystic kidney disease treatment encompasses pharmaceutical, surgical, and emerging genetic interventions designed to slow cyst proliferation, manage hypertension, and delay end-stage renal failure in patients with PKD1 or PKD2 mutations. The therapeutic arsenal spans vasopressin receptor antagonists, somatostatin analogues, and investigational RNA-targeted modalities that modulate cyst epithelial cell proliferation. Medications currently command the largest revenue pool given tolvaptan's established reimbursement, while genetic therapies represent the fastest-expanding segment as CRISPR-based approaches advance through clinical validation. Dialysis and transplantation retain structural importance as downstream revenue anchors tied to disease progression timelines and transplant center economics.
The FDA orphan drug program and EMA's similar designation framework shape competitive entry economics by granting market exclusivity and tax incentives for developers targeting ADPKD's relatively small patient population. Reata Pharmaceuticals navigates this regulatory architecture through oxidative stress modulation programs, while Janssen Pharmaceuticals positions its nephrology portfolio against evolving FDA renal endpoints guidance. Stakeholders must monitor how CMS reimbursement for genetic therapies intersects with Medicare's kidney care transformation models to determine whether premium pricing for disease-modifying treatments achieves sustainable access.
Market Dynamics
The ADPKD treatment market restructures around a decisive split between established volume-based pharmaceutical franchises and emerging premium genetic interventions, with reimbursement architecture determining which pathway achieves sustainable commercial traction.
Growth Catalysts
- FDA Orphan Drug Designation:The FDA's expedited review pathway grants seven-year market exclusivity and tax credits for ADPKD developers, compressing clinical-to-commercial timelines for disease-modifying therapies.
- Hospital Nephrology Expansion:Academic medical centers in the United States are building dedicated polycystic kidney disease centers, creating concentrated demand nodes for specialized therapeutics and transplant coordination.
- CRISPR Platform Maturation:Gene-editing technologies targeting PKD1 and PKD2 mutations advance through preclinical validation, attracting venture funding toward curative rather than palliative endpoints.
Market Restraints
- Tolvaptan Generic Entry:Patent expiry for the sole approved disease-modifying therapy exposes Otsuka Pharmaceutical to commodity pricing pressure, compressing revenue pools for vasopressin receptor antagonists.
- Specialized Cystic Kidney Centers:Treatment concentration in tertiary academic hospitals limits patient access in rural and community settings, constraining addressable population growth.
- End-Stage Renal Failure Timeline Variability:Unpredictable disease progression complicates clinical trial endpoint design, extending validation periods and inflating development costs for novel mechanisms.
Strategic Opportunities
- RNA-Targeted Modality Convergence:Antisense oligonucleotides and siRNA platforms targeting cyst epithelial proliferation create white space between small-molecule and gene-editing approaches.
- CMS Kidney Care Transformation:Medicare's value-based care models for renal disease create reimbursement pathways for therapies demonstrating delayed dialysis initiation.
- Underserved European Cohorts:EMA centralized approval processes enable rapid access expansion into Germany, France, and Italy where specialized nephrology infrastructure remains less concentrated than in the United States.
Industry Challenges
- Biomarker Validation Deficits:Lack of surrogate endpoints accepted by FDA renal guidance forces reliance on hard outcomes like glomerular filtration rate decline, extending trial duration.
- Gene Therapy Manufacturing Scale-Up:Viral vector production capacity constraints and cold-chain logistics complexity limit rollout velocity for CRISPR-based interventions.
- Reimbursement Evidence Generation:Payers demand real-world data on dialysis deferral rates, requiring post-market infrastructure that stretches commercial resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autosomal Dominant Polycystic Kidney Disease Treatment Market |
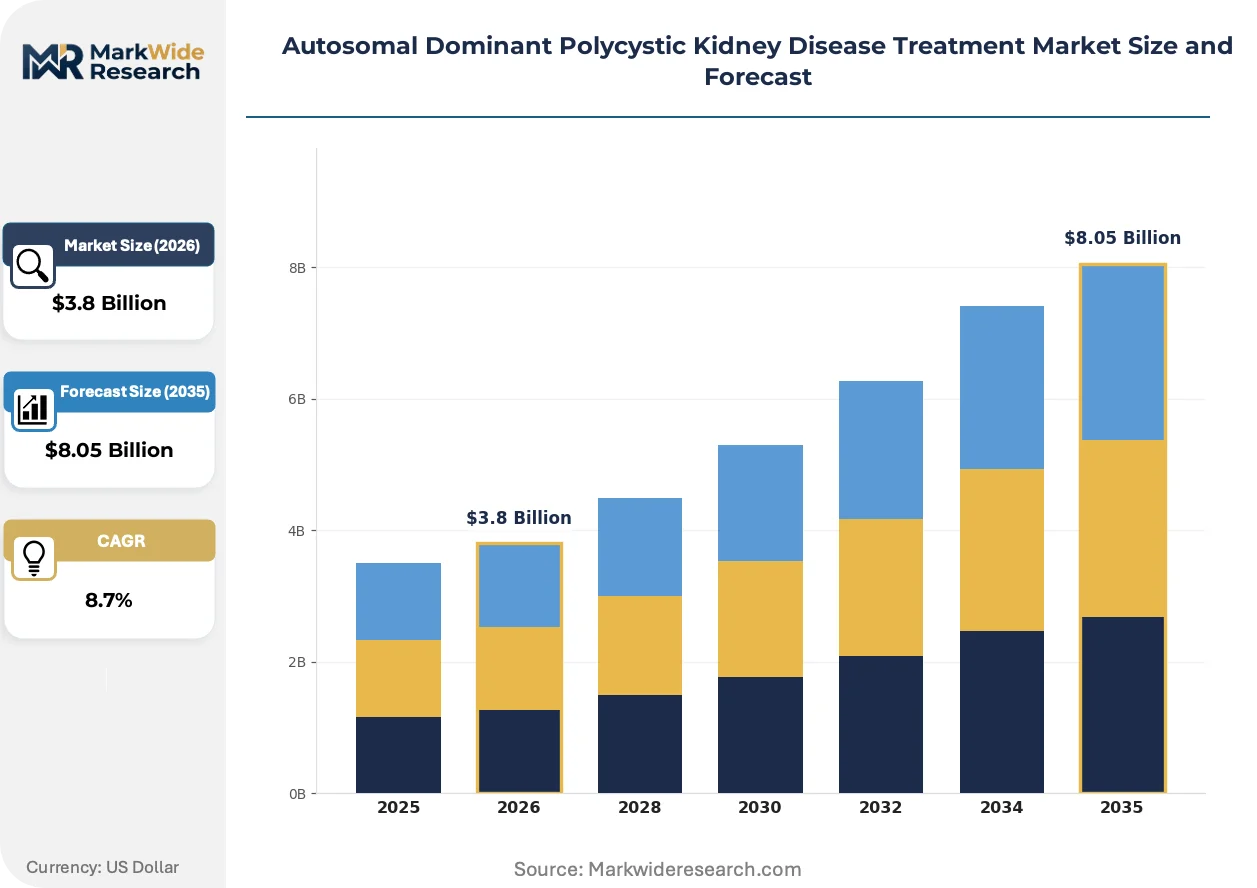
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Dialysis, Transplantation, Genetic Therapies Delivery Mode: Oral, Intravenous, Subcutaneous, Intravenous Push End User: Hospitals, Clinics, Home Care, Research Institutions Therapy Area: Kidney Disorders, Genetic Diseases, Chronic Illness, Nephrology |
| Companies Covered | Regulus Therapeutics Inc., Merck & Co. Inc., Otsuka Pharmaceutical Co., Ltd., Vertex Pharmaceuticals, Janssen Pharmaceuticals, Reata Pharmaceuticals, Galapagos NV, Xortx Therapeutics, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autosomal Dominant Polycystic Kidney Disease Treatment Market Strategic Shifts
Gene-editing platforms and RNA-targeted mechanisms are displacing incremental small-molecule improvements as the locus of competitive investment, while regulatory frameworks adapt to evaluate one-time curative interventions against chronic management paradigms.
CRISPR-Cas9 systems targeting PKD1 mutations are absorbing preclinical investment from large pharmaceutical sponsors seeking disease-modifying rather than symptomatic endpoints. Vertex Pharmaceuticals channels cystic fibrosis cash flows toward polycystic kidney disease programs, accelerating IND-enabling studies. The technology is absorbing development resources previously allocated to me-too vasopressin antagonists, compressing the small-molecule pipeline.
EMA's PRIME designation and FDA's Breakthrough Therapy pathways converge to accelerate review timelines for genetic interventions targeting orphan renal indications. These frameworks compress regulatory phases but impose stringent manufacturing quality requirements on viral vector suppliers. European developers prioritize centralized EMA procedures over national competent authority routes to capture unified market access.
Hospital procurement committees now bundle disease-modifying therapies with transplant center referrals, conditioning formulary placement on demonstrated end-stage renal failure delay. Academic medical centers in Boston, Baltimore, and San Francisco lead this integration, displacing community nephrology prescribing autonomy. The shift concentrates volume in integrated delivery networks with captive dialysis and surgical capabilities.
Autosomal Dominant Polycystic Kidney Disease Treatment Market Segmentation
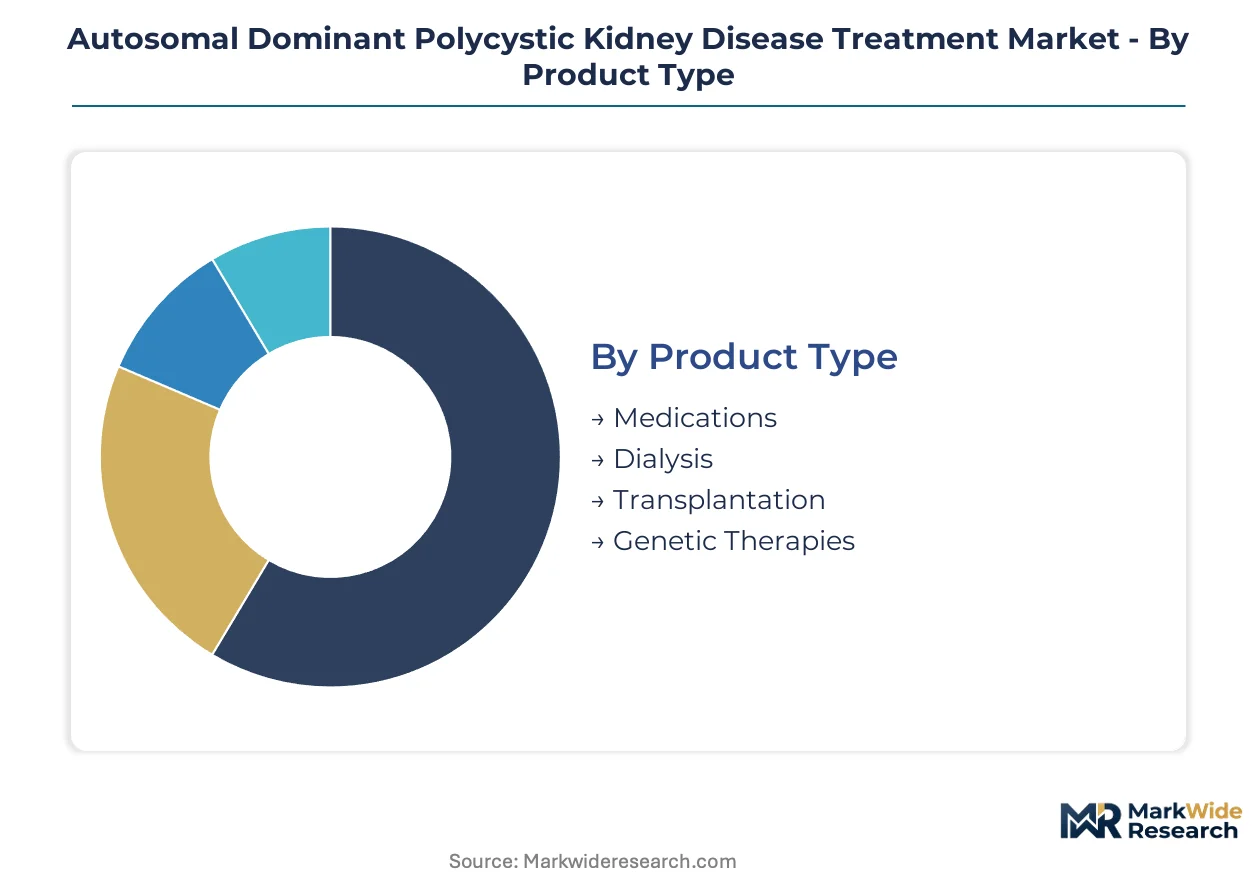
ADPKD treatment segmentation reveals how therapeutic modalities, delivery mechanisms, and care settings interact to shape patient access and reimbursement economics. Understanding these intersections enables stakeholders to identify where value concentrates versus where expansion potential sits.
Product Type:
Integration depth varies sharply across product categories, with chronic management tools functioning as standalone prescriptions while curative modalities require embedded coordination with transplant and dialysis infrastructure.
- Medications:Small-molecule vasopressin receptor antagonists and somatostatin analogues constitute the established revenue base through chronic outpatient prescribing. Demand concentrates in tertiary nephrology centers where Otsuka Pharmaceutical's tolvaptan franchise maintains formulary dominance, though patent expiry pressures are compressing margins.
- Genetic Therapies:CRISPR-based and RNA-targeted modalities targeting PKD1/PKD2 mutations require sophisticated cold-chain logistics and specialized administration infrastructure. Vertex Pharmaceuticals channels cystic fibrosis cash flows toward these programs, attracting venture funding toward one-time curative endpoints rather than chronic management.
- Dialysis:Hemodialysis and peritoneal dialysis serve as downstream revenue anchors tied to disease progression timelines, with academic medical centers bundling these services with transplant referrals.
- Transplantation:Surgical intervention and immunosuppressive regimens represent the terminal treatment stage, with procedure volumes concentrated in United States transplant centers possessing dedicated polycystic kidney disease expertise.
Volume placements concentrate in Medications; the faster expansion belongs to Genetic Therapies.
Delivery Mode:
Route selection directly determines which care settings capture patient encounters and how reimbursement pathways structure provider economics.
- Oral:Tolvaptan tablets dominate outpatient prescribing due to established home administration protocols and pharmacy benefit coverage. United States nephrology clinics generate the highest prescription volumes where Medicare Part D structures patient cost-sharing.
- Intravenous:Hospital-based infusion of investigational genetic therapies requires specialized nursing protocols and adverse event monitoring capabilities. Academic medical centers in Boston and Baltimore lead adoption as CRISPR platforms advance through clinical validation.
- Subcutaneous:Self-administered injections for somatostatin analogues bridge hospital and home settings, with training programs determining patient eligibility.
- Intravenous Push:Rapid bolus administration for acute interventions remains limited to emergency nephrology departments and intensive care units managing cyst hemorrhage or infection complications.
Oral formulations generate the highest prescription counts; intravenous delivery commands the steepest expansion trajectory as genetic therapies progress toward regulatory submission.
End User:
Site-of-care migration patterns reveal how integrated delivery networks are consolidating ADPKD patient management away from fragmented community settings.
- Hospitals:Academic medical centers with dedicated polycystic kidney disease programs capture complex cases requiring multidisciplinary coordination between nephrology, urology, and transplant services. Johns Hopkins and Mayo Clinic anchor United States referral patterns through bundled care contracts.
- Clinics:Community nephrology practices manage stable patients on established medication regimens, though prescribing autonomy is diminishing as hospital procurement committees centralize formulary decisions.
- Home Care:Peritoneal dialysis and oral medication administration shift treatment burden to patients and caregivers, with remote monitoring technologies expanding eligibility criteria.
- Research Institutions:Clinical trial sites at NIH-funded centers and university hospitals access investigational genetic therapies, generating real-world evidence for payer negotiations.
Hospital encounters dominate acute intervention volumes; home care settings are gaining share fastest as remote monitoring and self-administered modalities mature.
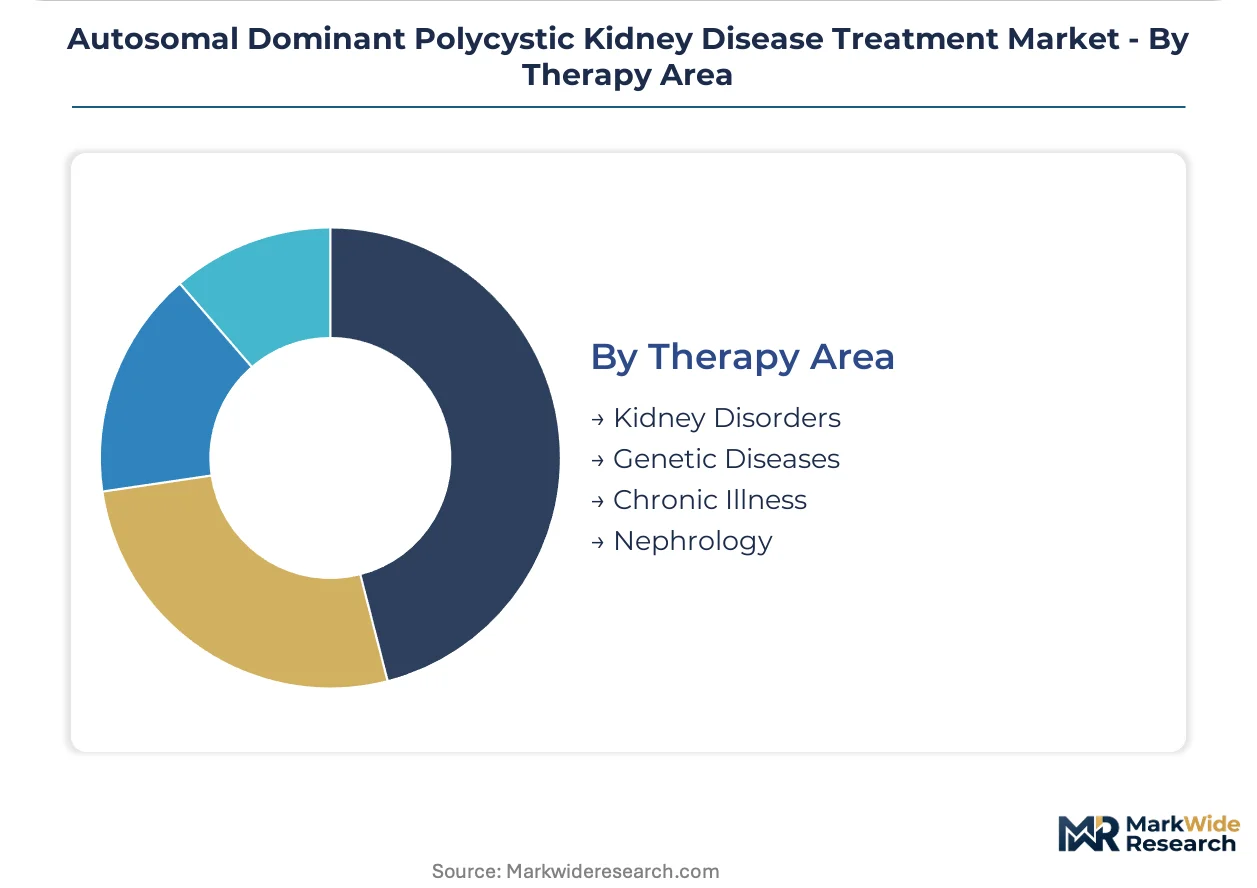
Therapy Area:
Clinical framing determines regulatory pathway selection and how FDA and EMA categorize novel mechanisms for review prioritization.
- Kidney Disorders:Renal-focused indications align with established nephrology endpoints and dialysis deferral metrics that CMS kidney care transformation models reward. United States payers prioritize therapies demonstrating glomerular filtration rate preservation.
- Genetic Diseases:Orphan drug designation pathways accelerate review timelines for PKD1 and PKD2 mutation-targeting interventions, with FDA granting seven-year market exclusivity and tax credits.
- Chronic Illness:Long-term management paradigms structure reimbursement around maintenance prescribing rather than curative outcomes, favoring tolvaptan-like chronic therapies.
- Nephrology:Specialty-specific coding and billing infrastructure determines provider reimbursement rates, with academic centers capturing higher facility fees for complex cases.
Kidney Disorders framing captures the highest commercial investment; Genetic Diseases designation is climbing the fastest as developers pursue orphan drug incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors specialized nephrology concentration through Massachusetts General Hospital's polycystic kidney disease program. Academic medical centers across four countries drive differential access to genetic therapies and transplant coordination.
United States
Johns Hopkins in Baltimore and Mayo Clinic in Rochester generate the highest patient volumes for specialized cystic kidney management. FDA orphan drug designation accelerates clinical trial enrollment through tax credits and seven-year exclusivity provisions. The San Francisco Bay Area biotech corridor hosts CRISPR platform developers advancing preclinical PKD1 targeting programs.
Germany
EMA centralized procedures enable rapid national reimbursement decisions following pan-European approval. Heidelberg and Berlin academic hospitals coordinate multicenter genetic therapy trials through the German Society of Nephrology network. Bavaria's medical technology cluster supplies dialysis equipment to university transplant centers.
Switzerland
Swissmedic's expedited review pathway attracts developers seeking concurrent European and global regulatory submissions. Basel anchors pharmaceutical R&D concentration with established nephrology trial infrastructure. Zurich University Hospital bundles genetic counseling with transplant evaluation pathways.
United Kingdom
NHS England's specialized commissioning framework concentrates ADPKD care in London, Manchester, and Birmingham renal units. The MHRA's reliance on EMA assessments streamlines market entry following European approval. Cambridge biomedical campus hosts RNA-targeted modality developers partnering with academic nephrology departments.
Japan
PMDA's Sakigake designation system accelerates review for genetic therapies addressing unmet renal needs. Tokyo and Osaka university hospitals maintain longitudinal PKD patient registries supporting real-world evidence generation. The Kansai region's pharmaceutical manufacturing base supplies active pharmaceutical ingredients for vasopressin antagonist production.
Autosomal Dominant Polycystic Kidney Disease Treatment Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the ADPKD treatment spectrum. Large pharmaceutical incumbents with established nephrology franchises defend volume positions through hospital formulary relationships. Biotechnology specialists pursue premium pricing through genetic intervention platforms. Three archetypes dominate: integrated pharmaceutical conglomerates with dialysis-to-transplant service lines, gene-editing platform companies channeling cash flows from adjacent rare disease markets, and regional generic manufacturers preparing for tolvaptan patent expiry. Competitive moves concentrate on strategic partnerships for viral vector manufacturing capacity and portfolio diversification into RNA-targeted modalities.
Within the gene-editing platform tier, Vertex Pharmaceuticals exemplifies the archetype of rare disease specialists cross-leveraging technical capabilities. Otsuka Pharmaceutical occupies a position representing established pharmaceutical incumbents with chronic therapy franchises. Galapagos NV sits within the European biotechnology specialist segment targeting novel disease pathways through differentiated discovery platforms.
| Leading Market Players |
|---|
| Regulus Therapeutics Inc. |
| Merck & Co. Inc. |
| Otsuka Pharmaceutical Co., Ltd. |
| Vertex Pharmaceuticals |
| Janssen Pharmaceuticals |
| Reata Pharmaceuticals |
| Galapagos NV |
| Xortx Therapeutics |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Viral vector manufacturing costs cascade through genetic therapy pricing tiers, with academic medical centers absorbing premium markups for CRISPR-based interventions while community nephrology clinics face reimbursement compression for oral small-molecule prescriptions. This cost flow concentrates pricing power in integrated delivery networks possessing captive dialysis and transplant capabilities.
Pricing Analysis
Dialysis deferral outcomes anchor value-based pricing for disease-modifying therapies, with CMS kidney care transformation models rewarding demonstrated glomerular filtration rate preservation through bundled reimbursement rates. Price differentiation separates gene-editing interventions requiring specialized administration infrastructure from commodity vasopressin antagonists facing generic entry pressure. Pricing pressure stems from tolvaptan patent expiry exposing chronic therapy franchises to margin compression. Hospital procurement committees demonstrate lowest price sensitivity given bundled care contract structures, while community nephrology practices face tightening pharmacy benefit constraints.
Supply Chain Analysis
Dual-sourcing requirements for viral vector production mandate multi-supplier qualification across CDMO networks in the United States, Switzerland, and Belgium to mitigate single-source vulnerability for genetic therapy candidates. Active pharmaceutical ingredients for small-molecule vasopressin antagonists draw from chemical manufacturing bases in India and China, with finished dosage form production concentrated in European facilities. Supply chain risk centers on cold-chain logistics complexity for CRISPR platform distribution. Distribution runs through hospital-based specialty pharmacies and academic medical center procurement committees rather than retail pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as tolvaptan generic entry forces chronic therapy specialists toward merger or exit, concentrating volume in integrated delivery networks with genetic therapy administration capabilities.
For Market Incumbents: Lock in formulary dominance at academic medical centers through bundled transplant referral agreements before gene-editing platforms achieve regulatory validation. Defend against CRISPR-based displacement by securing exclusive viral vector manufacturing partnerships with CDMOs possessing FDA-approved facilities. Vertical integration into dialysis service lines preserves patient capture across disease progression timelines. For New Entrants and Emerging Players: Capture white space in RNA-targeted modalities occupying the therapeutic gap between small-molecule chronic management and one-time curative gene editing. European markets present the most penetrable geography given EMA centralized approval pathways and less concentrated specialized nephrology infrastructure. Pursue hospital system partnership models embedding genetic counseling with transplant evaluation pathways. For Investors and Strategic Acquirers: FDA Breakthrough Therapy designation for PKD1-targeting CRISPR programs is the leading indicator that premium pricing for curative endpoints will achieve sustainable reimbursement. Long-term viability favors platform companies with demonstrated rare disease commercialization capabilities and existing nephrology stakeholder relationships. Watch for CMS reimbursement determinations on genetic therapy coding as the signal for market access trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | PKD1-targeting CRISPR programs at Vertex accelerate IND-enabling studies through cystic fibrosis cash flow redeployment. |
| Regulatory Approval Pathway | FDA orphan drug designation compresses review timelines while granting seven-year market exclusivity for disease-modifying therapies. |
| Manufacturing Scale-Up | Viral vector production capacity constraints limit rollout velocity for genetic therapies requiring specialized cold-chain infrastructure. |
| Licensing Agreement | RNA-targeted modality partnerships with academic nephrology departments generate real-world evidence for payer negotiations. |
| Pipeline Diversification | Antisense oligonucleotide platforms targeting cyst epithelial proliferation create white space between small-molecule and gene-editing approaches. |
Study Parameters
FDA filings, ClinicalTrials.gov, and EMA assessment reports formed the secondary backbone, cross-referenced against primary interviews with nephrology department heads, formulary directors at academic medical centers, payer access specialists, and genetic therapy program executives. Bottom-up prescription volume modeling and top-down reimbursement pathway analysis were triangulated against hospital procurement database trends and CMS kidney care transformation model specifications.
Bottom-up patient flow analysis across treatment lines, administration routes, and regional regulatory clusters was reconciled with top-down pharmaceutical revenue segmentation across the projection horizon. CAGRs were derived from modeled adoption curves for genetic therapies against established small-molecule decline trajectories. Forecast inputs incorporated dialysis deferral endpoint validation timelines and transplant center capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA renal endpoint guidance revisions and CMS genetic therapy reimbursement determinations. Deviation in viral vector manufacturing scale-up timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Paget Disease Treatment Market
Specialty Medicine
Marfan Syndrome Treatment Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market
Specialty Medicine
Cystic Fibrosis Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Global Alopecia Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Treatment Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
Psychedelic Medicine Market
Specialty Medicine
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Liver Fibrosis Treatment Market