
 Global Intravenous Solutions Market | 2026-2036
Global Intravenous Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intravenous Solutions Market Foresight
Closed-system transfer devices and aseptic blow-fill-seal technology is reconfiguring manufacturing workflows for large-volume parenterals, reducing contamination risk while enabling continuous production. Baxter International leverages its integrated plasma fractionation and IV solution portfolio to sustain supply chain control across North American hospital networks. Fresenius Kabi anchors European market presence through captive manufacturing of electrolyte-specific formulations for critical care settings. B. Braun Melsungen differentiates via specialization in needle-free connector systems and closed drug transfer devices that interface with standard IV administration sets.
Intravenous solutions are sterile, pyrogen-free aqueous preparations containing electrolytes, nutrients, or medications intended for direct infusion into the venous circulation, typically manufactured through aseptic compounding or terminal sterilization at pH ranges between 3.5 and 6.5 to ensure vascular compatibility. These formulations serve as essential vehicles for fluid resuscitation, electrolyte correction, parenteral nutrition, and drug delivery in acute and chronic care environments. Crystalloid solutions occupy the dominant volume position due to standardized clinical protocols for sepsis and surgical resuscitation, while lipid emulsions command premium positioning as indispensable components of total parenteral nutrition regimens for patients with non-functional gastrointestinal tracts. Flexible bag packaging is displacing glass containers across hospital formularies, driven by reduced breakage rates and compatibility with automated compounding workflows.
The FDA enforces current Good Manufacturing Practice regulations for sterile pharmaceutical products, including particulate matter limits and container closure integrity standards that directly shape IV solution formulation and packaging decisions. The EMA's Annex 1 revision on sterile medicinal products mandates barrier isolation technology and enhanced environmental monitoring, elevating capital requirements for European production facilities. Japan's PMDA maintains distinct pharmacopeial standards for electrolyte concentration tolerances that influence regional product registration strategies. Stakeholders must monitor evolving regulatory divergence between polymer packaging migration timelines and glass-container retention requirements in emerging markets.
Market Dynamics
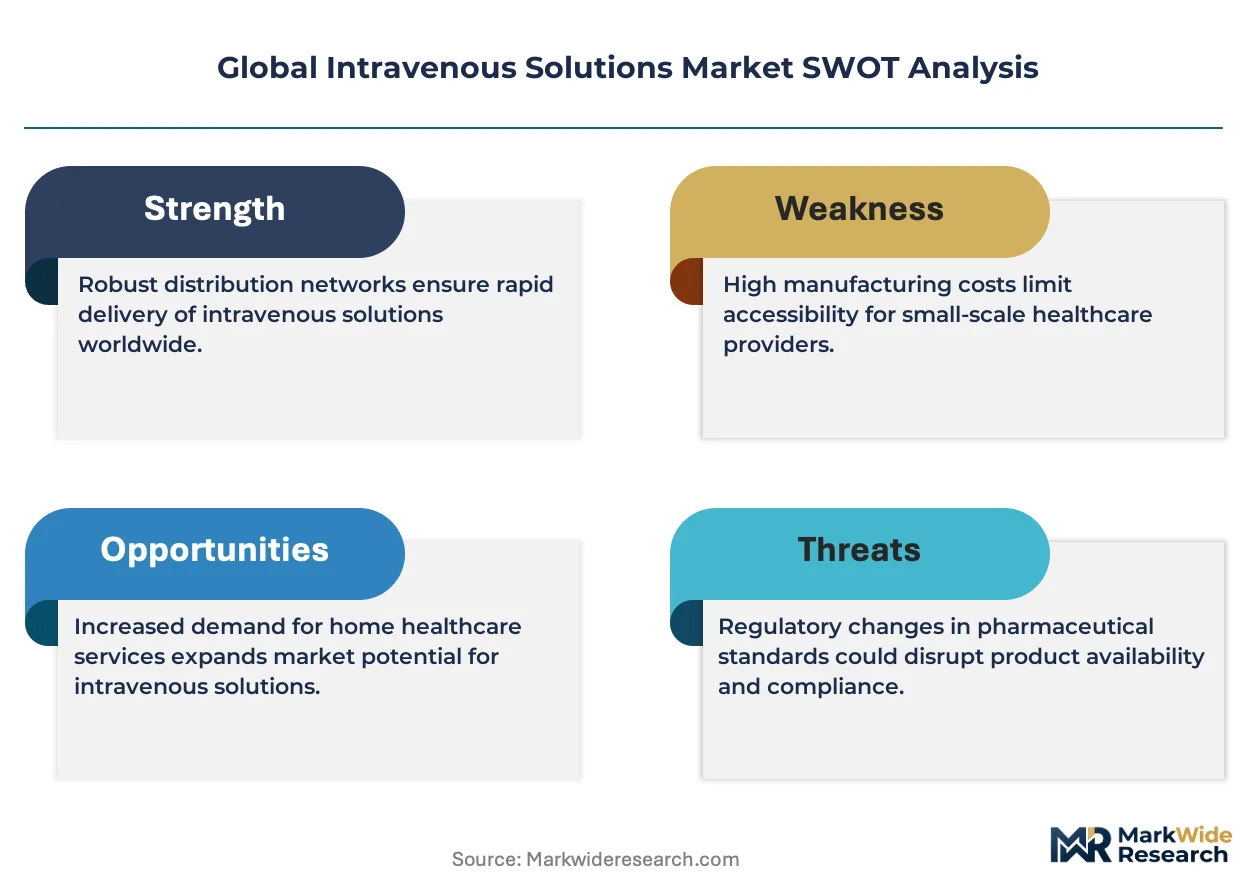
Polymer-based flexible packaging migration is compressing glass container demand while forcing capital reallocation across sterile manufacturing facilities worldwide. FDA guidance on glass particulate contamination and EMA Annex 1 barrier isolation mandates are synchronizing to reshape production infrastructure requirements.
Growth Catalysts
- Surgical volume expansion:Tertiary hospitals in the United States are standardizing balanced crystalloid protocols for sepsis resuscitation, pulling multi-liter bag volumes into centralized procurement frameworks.
- Regulatory packaging migration:The FDA's updated glass particulate guidance is accelerating polymer bag adoption by hospital formularies seeking reduced breakage liability and automated compounding compatibility.
- Aging demographics:Japan's elderly population sustains inpatient infusion therapy volumes for chronic disease management, anchoring demand for electrolyte-specific formulations in acute care settings.
Market Restraints
- Polymer resin cost volatility:Medical-grade polypropylene and multilayer film input costs fluctuate with petrochemical feedstock markets, compressing margin stability for flexible packaging converters.
- European supply concentration:EMA Annex 1 barrier isolation mandates have consolidated sterile production among capital-intensive facilities in Germany and Switzerland, elevating geographic supply risk.
- Glass retention in emerging markets:Cost-sensitive hospital systems in Brazil and India maintain glass container formularies due to lower unit economics, fragmenting packaging standardization timelines.
Strategic Opportunities
- Home infusion expansion:Ambulatory infusion centers in the United States are adopting portable pump-compatible bag formats, opening channel diversification beyond inpatient settings.
- Closed-system integration:Blow-fill-seal technology convergence with needle-free connector systems is enabling continuous aseptic production lines that reduce human intervention points.
- Indian manufacturing scale-up:CDSCO regulatory harmonization with ICH standards is positioning domestic producers to capture regional export demand for standard crystalloid formulations.
Industry Challenges
- Aseptic engineering talent scarcity:Barrier isolation technology deployment requires specialized cleanroom validation expertise that outpaces technical training pipeline output in European manufacturing hubs.
- Legacy equipment integration:Terminal sterilization facilities face retrofit complexity when interfacing automated compounding workflows with existing glass-container filling lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intravenous Solutions Market |
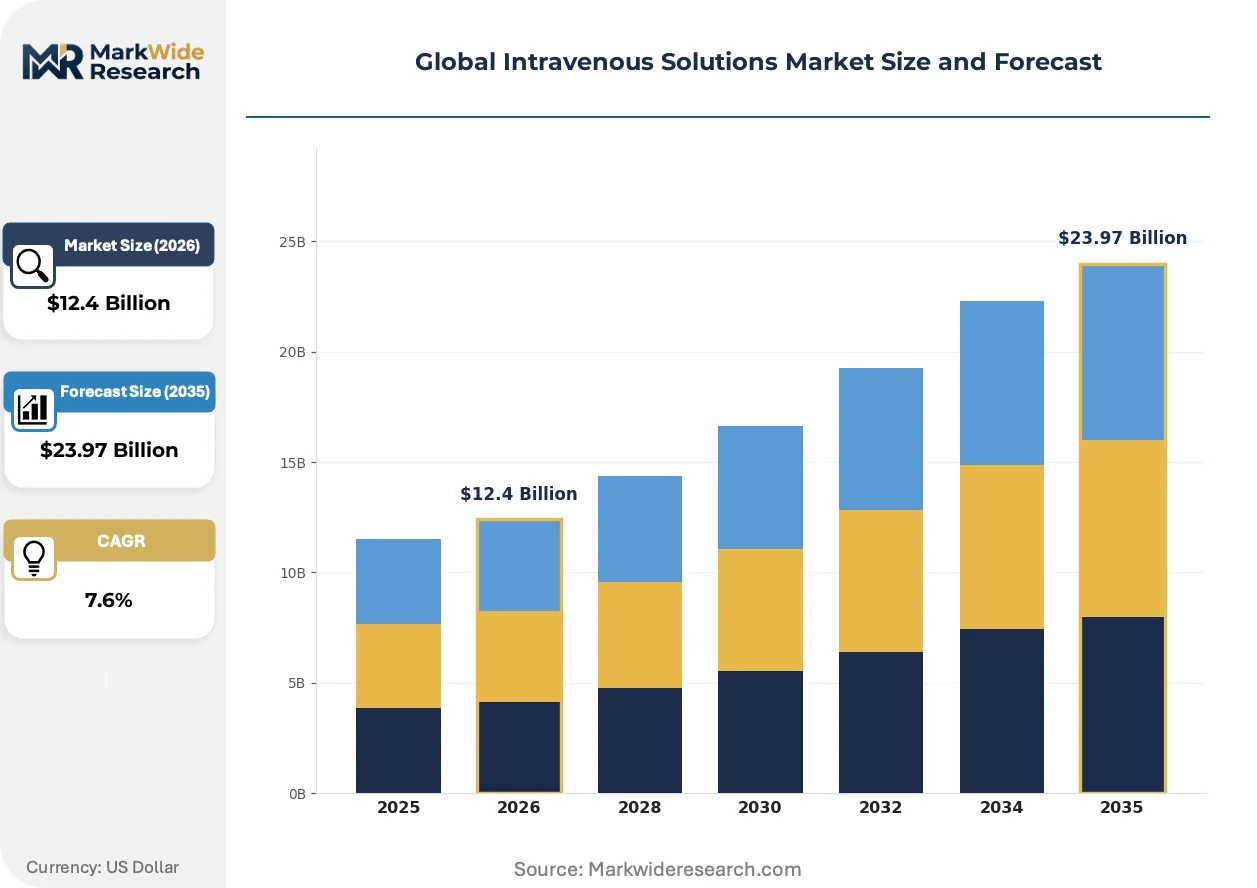
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $23.97 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalloids, Colloids, Blood Components, Lipid Emulsions Application: Fluid Replacement, Electrolyte Balance, Nutrition Support, Drug Delivery End User: Hospitals, Ambulatory Care Centers, Home Healthcare, Specialty Clinics Packaging Type: Flexible Bags, Glass Bottles, Plastic Bottles, Pre-filled Syringes |
| Companies Covered | Baxter International, Fresenius Kabi, B. Braun Melsungen, Otsuka Pharmaceutical, Kelun Industry Group, ICU Medical, JW Life Science, Grifols, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intravenous Solutions Market Shifts & Advancements
Manufacturing workflows are converging around continuous processing architectures that compress batch cycle times while elevating contamination control standards. Technology vendors and pharmaceutical manufacturers are co-developing integrated systems that merge formulation, filling, and closure into unified sterile environments.
Multilayer coextruded film technology is hybridizing polymer barrier properties with mechanical flexibility to replace glass in large-volume parenteral applications. Tertiary hospital networks in Germany and the United States are piloting these formats for total parenteral nutrition compounding. The structural consequence is compressing glass supplier bargaining power while elevating film converter partnerships to strategic supplier status.
EMA Annex 1 revision on sterile medicinal products is mandating isolator technology and enhanced environmental monitoring across European production facilities. This regulatory pressure is forcing capital redeployment toward barrier systems and real-time particle detection infrastructure. Critical care electrolyte formulations manufactured in Switzerland and Germany face the steepest compliance cost escalation, driving regional production consolidation.
Hospital procurement patterns are compressing supplier rosters through centralized GPO contracting that bundles IV solutions with infusion pump and administration set categories. Academic medical centers in the United States are leading this consolidation, displacing fragmented multi-vendor purchasing. The shift is most visible in surgical service lines where standardized resuscitation protocols enable single-source crystalloid commitments.
Global Intravenous Solutions Market Segmentation
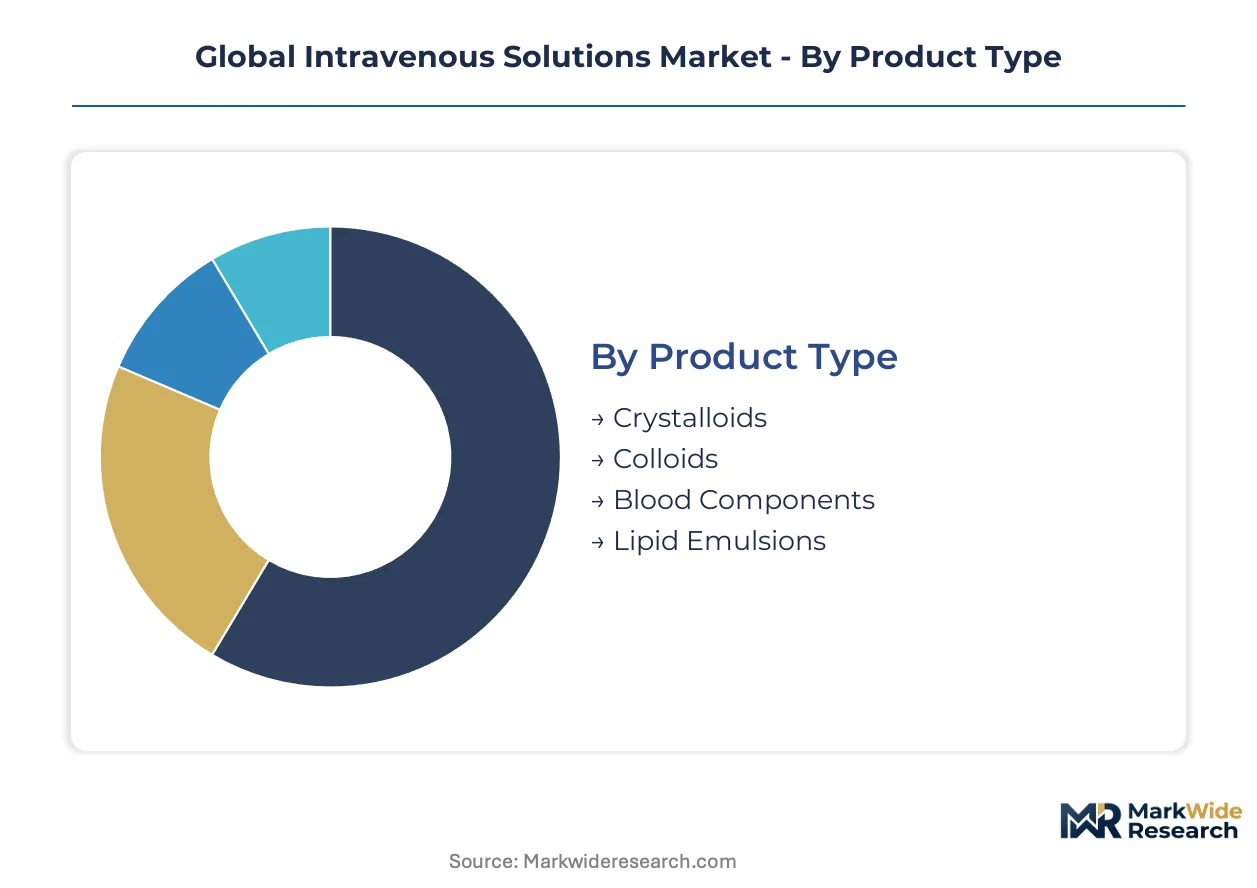
IV solution purchasing patterns fragment across clinical use cases, packaging preferences, and care settings. Procurement managers navigate trade-offs between standardized crystalloid volumes and specialized nutrition formulations. Understanding these segment boundaries reveals where margin concentration diverges from volume concentration.
Product Type:
Mature crystalloid formulations anchor hospital formularies while emerging lipid emulsion technologies capture premium positioning in specialized nutrition.
- Crystalloids:Electrolyte-based aqueous solutions with sodium chloride, lactated Ringer's, or balanced formulations dominate surgical resuscitation and sepsis protocols. United States tertiary hospitals standardize multi-liter bag procurement for these applications, pulling volumes into centralized GPO frameworks.
- Colloids:Albumin and synthetic plasma expanders maintain critical care positioning for hypovolemic shock despite cost premiums over crystalloid alternatives. German and Swiss academic medical centers retain these formulations for specific hemodynamic stabilization protocols.
- Blood Components:Plasma-derived and recombinant clotting factor solutions serve transfusion-dependent patient populations.
- Lipid Emulsions:Essential fatty acid delivery systems for total parenteral nutrition command formulation complexity premiums in patients with non-functional gastrointestinal tracts.
Crystalloids retain volume leadership; lipid emulsions hold the steepest expansion curve.
Application:
Application demand clusters around acute intervention needs versus chronic maintenance requirements, with reimbursement pathways determining commercial prioritization.
- Fluid Replacement:Volume resuscitation for hemorrhage, burns, and surgical blood loss consumes the largest absolute bag volumes across inpatient settings. Japanese emergency departments and operating rooms sustain particularly intensive utilization patterns for crystalloid replacement protocols.
- Electrolyte Balance:Corrective infusions for hyponatremia, hyperkalemia, and acid-base disorders require precise concentration tolerances. PMDA pharmacopeial standards in Japan create distinct formulation specifications that influence regional manufacturing strategies.
- Nutrition Support:Parenteral feeding solutions bypass compromised gastrointestinal function in critical care populations.
- Drug Delivery:IV solutions serve as vehicles for antibiotic, chemotherapy, and biologic agent administration.
Fluid replacement commands absolute volume; nutrition support delivers the highest per-liter margin realization.
End User:
Customer type segmentation reflects the migration of infusion therapy from centralized hospital campuses toward distributed care environments.
- Hospitals:Inpatient surgical, medical, and intensive care units generate the dominant share of multi-liter bag consumption through standardized resuscitation protocols. United States academic medical centers lead centralized procurement consolidation that bundles solutions with pump and administration set categories.
- Ambulatory Care Centers:Same-day surgical and infusion facilities require portable pump-compatible formats that enable treatment completion without overnight admission. These settings in Germany and the United States are piloting flexible bag systems for chemotherapy and antibiotic delivery.
- Home Healthcare:Patient-directed infusion therapy demands simplified administration interfaces and cold-chain distribution capabilities.
- Specialty Clinics:Dialysis and oncology centers maintain dedicated solution requirements for procedure-specific protocols.
Hospitals retain procurement concentration; ambulatory care centers are gaining share fastest as site-of-service shifts accelerate.
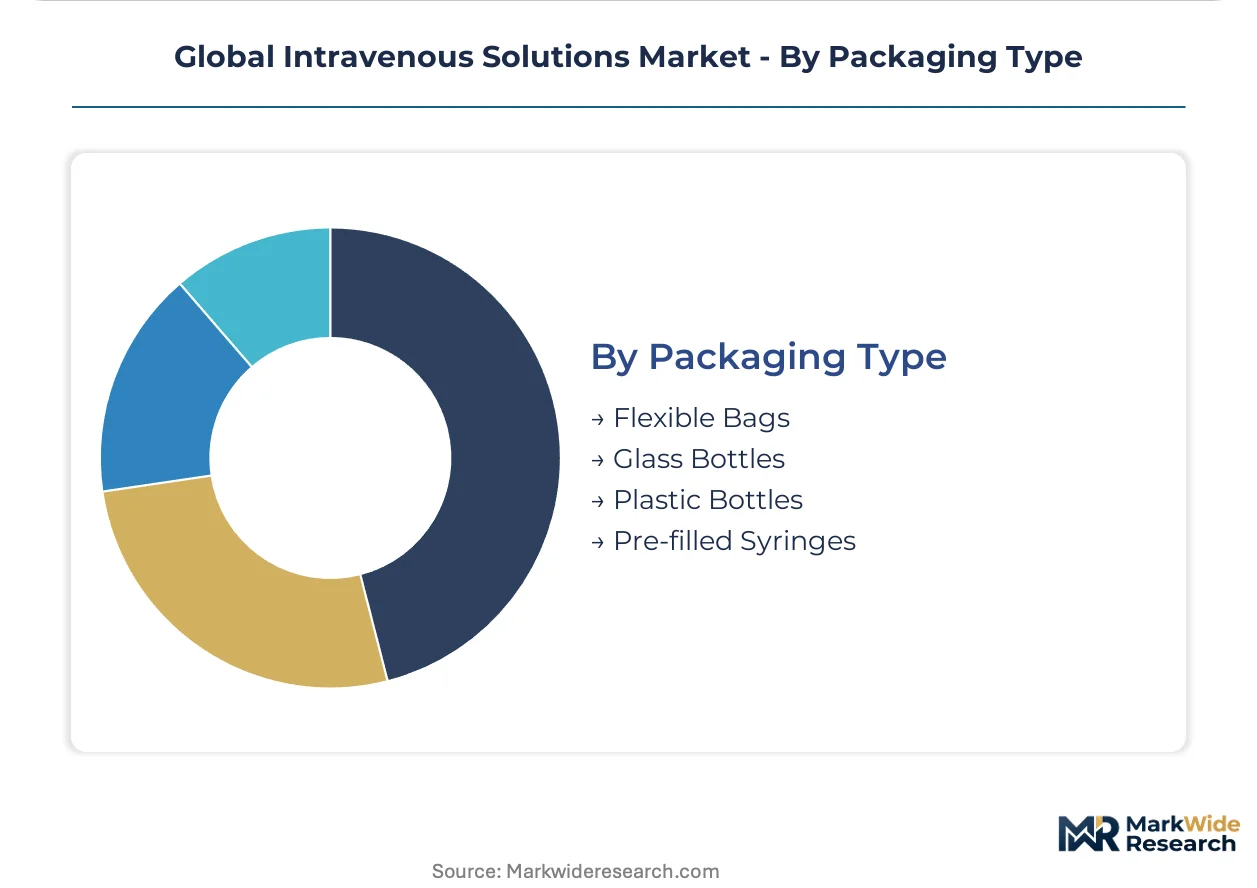
Packaging Type:
Material selection divides between polymer migration in developed markets and glass retention in cost-sensitive procurement environments.
- Flexible Bags:Multilayer coextruded film containers reduce breakage rates and enable automated compounding workflow integration. FDA guidance on glass particulate contamination accelerates hospital formulary adoption in the United States, displacing traditional glass containers in large-volume parenteral applications.
- Glass Bottles:Borosilicate containers persist in emerging market hospital systems where unit economics favor lower material costs over automation compatibility. Brazilian and Indian procurement patterns retain glass formularies despite global polymer transition trends.
- Plastic Bottles:Semi-rigid polymer containers occupy intermediate positioning for specific medication compatibility requirements.
- Pre-filled Syringes:Unit-dose presentation formats support emergency medication preparation and anesthesia workflows.
Flexible bags dominate new capital deployment; glass bottles maintain residual volume in emerging market procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export sterile large-volume parenterals to hospital networks across Central and Eastern Europe, while Swiss producers supply specialized electrolyte formulations to Middle Eastern acute care facilities.
United States
Tertiary hospitals in Texas and Florida sustain multi-liter crystalloid procurement through standardized sepsis resuscitation protocols. FDA guidance on glass particulate contamination accelerates polymer bag migration across hospital formularies. The Boston-Cambridge corridor hosts contract manufacturing organizations developing blow-fill-seal capacity for ambulatory infusion formats.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia maintain demand for albumin-based colloids in hemodynamic stabilization protocols. EMA Annex 1 mandates on barrier isolation technology elevate capital requirements for sterile production facilities. The Frankfurt-Rhine-Main cluster concentrates advanced multilayer film converter operations serving European flexible packaging demand.
Switzerland
Critical care units in Geneva and Zurich anchor consumption of precision electrolyte formulations for acid-base disorder correction. Swissmedic enforcement of sterile manufacturing standards aligns with EMA Annex 1 environmental monitoring requirements. The Basel pharmaceutical corridor integrates plasma fractionation with IV solution production for supply chain control.
Japan
Emergency departments in Tokyo and Osaka sustain intensive crystalloid utilization patterns for fluid replacement protocols. PMDA pharmacopeial standards for electrolyte concentration tolerances create distinct regional formulation specifications. The Kansai manufacturing belt concentrates production of elderly-specific hydration solutions for chronic disease management.
India
Cost-sensitive hospital systems in Maharashtra and Gujarat retain glass container formularies for standard saline and dextrose solutions. CDSCO regulatory harmonization with ICH standards positions domestic producers for regional export capture. The Hyderabad-Visakhapatnam corridor scales aseptic manufacturing capacity for standard crystalloid formulations.
Global Intravenous Solutions Market Competitive Landscape
On the supply side, the industry is consolidating around integrated plasma fractionators and specialized sterile manufacturers with captive polymer film supply. Three archetypes dominate: diversified healthcare conglomerates with hospital supply chain control, mid-scale regional specialists in electrolyte formulations, and technology-focused device-solution integrators. Competitive intensity centers on backward integration into polymer resin compounding and strategic partnerships with automated compounding equipment vendors.
Within the diversified healthcare tier, Baxter International and Fresenius Kabi exemplify supply chain integration across North American and European hospital networks. B. Braun Melsungen occupies a position among device-specialized manufacturers emphasizing closed-system transfer technology. These three entities represent distinct strategic postures: plasma-derived vertical control, European critical care formulation depth, and administration set compatibility engineering.
| Leading Market Players |
|---|
| Baxter International |
| Fresenius Kabi |
| B. Braun Melsungen |
| Otsuka Pharmaceutical |
| Kelun Industry Group |
| ICU Medical |
| JW Life Science |
| Grifols |
| Pfizer |
| Others |
Supply & Pricing Matrix
Single-source dependency on medical-grade polypropylene resin suppliers in South Korea and Germany determines both the spread between premium flexible bag formulations and economy glass alternatives and the geographic shape of sterile manufacturing investment. FDA guidance on glass particulate contamination and EMA Annex 1 barrier isolation mandates are synchronizing to compress pricing power at the packaging conversion tier while elevating capital barriers at the formulation level.
Pricing Analysis
Current-generation multilayer coextruded film technology commands formulation complexity premiums over prior-generation single-layer polymer containers and next-generation bio-based barrier films still in pilot validation. Three-tier pricing structure across premium isolator-produced specialty electrolytes, standard blow-fill-seal crystalloids, and economy glass-bottle saline separates procurement tiers by contamination control certification and automation compatibility. Pricing pressure stems from resin cost volatility tethered to petrochemical feedstock markets, with hospital GPOs in the United States extracting volume concessions that squeeze converter margins. Ambulatory care centers demonstrate highest price sensitivity due to reimbursement compression, while Swiss and German academic medical centers retain lowest sensitivity for critical care formulations.
Supply Chain Analysis
Tariff exposure between United States and China on medical-grade polymer resin inputs dominates supply chain risk assessment for North American flexible packaging converters. Sterile large-volume parenteral production concentrates in Germany, Switzerland, and the United States, with multilayer film supply anchored in the Frankfurt-Rhine-Main cluster and specialized electrolyte compounding centered on Basel and Bavaria. Raw material dependencies rest on medical-grade polypropylene, ethylene vinyl alcohol barrier resins, and electrolyte-grade sodium chloride sourced from captive salt deposits. Distribution runs through hospital GPO consolidated procurement frameworks in the United States and direct tender contracts with national health systems in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across packaging technology generations and regulatory compliance tiers creates niche opportunities for specialists capable of bridging polymer migration timelines in emerging markets. Home infusion channel expansion and Indian manufacturing scale-up represent the most penetrable white-space corridors.
For Market Incumbents: Insulate formulation margin pools by deepening captive polymer resin compounding partnerships and accelerating barrier isolator deployment ahead of EMA Annex 1 enforcement waves. Baxter International and Fresenius Kabi should consolidate automated compounding equipment vendor relationships to lock hospital GPO bundling power against emerging device-solution integrators. Swiss and German production assets require environmental monitoring infrastructure upgrades to defend European market access. For New Entrants and Emerging Players: Indian domestic producers scaling aseptic manufacturing for standard crystalloid export capture represent the most penetrable geographic entry vector. CDSCO regulatory harmonization with ICH standards enables regional supply to Middle Eastern and Southeast Asian hospital systems still sourcing from European incumbents at freight-inflated landed costs. Target go-to-market angle: contract manufacturing partnerships with established Indian producers seeking formulation technology transfer rather than greenfield capital deployment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-scale specialists with captive polymer film supply and validated isolator infrastructure over diversified healthcare conglomerates facing legacy glass-container retrofit burdens. Acquisition target archetype: European electrolyte formulation specialists with EMA Annex 1 compliance already operational and distribution relationships into Middle Eastern acute care facilities. Signal to watch: CDSCO accelerated approval pathways for Indian producers achieving PIC/S membership status as inflection indicator for regional supply rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Isolator Technology Deployment | EMA Annex 1 mandates elevate capital requirements for sterile production facilities in Germany and Switzerland. |
| Polymer Film Converter Partnership | Multilayer coextrusion expertise becomes strategic supplier status as glass displacement accelerates in United States hospital formularies. |
| Indian Manufacturing Scale-Up | CDSCO harmonization with ICH standards positions domestic producers for regional export capture in standard crystalloids. |
| Home Infusion Format Development | Ambulatory care centers in Germany and the United States pilot portable pump-compatible bag systems for chemotherapy delivery. |
| Closed-System Transfer Integration | Blow-fill-seal convergence with needle-free connectors reduces human intervention points in continuous aseptic production. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, GPO contracts directors, sterile manufacturing engineers, regulatory affairs specialists at polymer film converters, and critical care pharmacists at academic medical centers. Secondary validation drew from FDA guidance documents, EMA Annex 1 revision texts, PMDA pharmacopeial standards, CDSCO regulatory circulars, hospital formulary databases, and SEC filings of listed healthcare conglomerates. Bottom-up crystalloid volume modeling by hospital bed capacity and surgical procedure codes was triangulated against top-down polymer resin consumption data from medical-grade polypropylene suppliers.
Calibration against historical volume trajectories in United States tertiary hospitals and Japanese emergency departments anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type crystalloid-colloid-lipid emulsion stratification, packaging technology generation, end-user channel hospital-ambulatory-home, and regional regulatory cluster FDA-EMA-PMDA-CDSCO. CAGRs were derived from elasticity-adjusted procedure volume forecasts and packaging migration curve assumptions. Industry-specific inputs incorporated sepsis protocol standardization rates and automated compounding equipment installation pipelines.
Practitioners should monitor polymer resin cost volatility, EMA Annex 1 enforcement variance across European member states, and CDSCO inspection capacity expansion for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Osteoarthritis Drugs Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Listeria Monocytogenes Treatment Market
Pharmaceuticals
Latin America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Advanced Therapy Medicinal Products CDMO Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Global Alpha-Blocker Market
Pharmaceuticals
Europe Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market
Pharmaceuticals
Compound Potassium Hydrogen Phosphate Injection Market
Pharmaceuticals
Global Pharmaceutical Warehousing Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market
Pharmaceuticals
Tuberculosis Vaccine Treatment Market