
 Filgrastim Market | 2026-2036
Filgrastim Market Size, Share, and Industry Trends Forecast 2026-2036
Filgrastim Market Analysis
Hospital group purchasing organization consolidation is repositioning filgrastim procurement toward centralized tendering and multi-year supply contracts. Amgen Inc. leverages its originator brand heritage and decades of clinical data to sustain premium positioning in institutional accounts. Teva Pharmaceutical Industries Ltd. anchors its competitive stance through deep biosimilar manufacturing scale across multiple production sites. Sandoz Group AG differentiates via early-mover biosimilar approvals and established European hospital channel relationships.
Filgrastim is a recombinant human granulocyte colony-stimulating factor (G-CSF) produced in Escherichia coli through recombinant DNA technology, formulated at specific protein concentrations for parenteral administration to stimulate neutrophil production and reduce infection risk in chemotherapy-induced neutropenia. The prefilled syringe segment leads volume due to reduced pharmacy preparation burden and lower medication error rates, while the biosimilar product type captures the fastest expansion as regulatory parity and payer pressure erode originator dominance. Oncology dominates therapy area demand reflecting high chemotherapy utilization rates, though transplantation represents a concentrated margin pool due to stringent cold-chain and timing requirements.
The FDA biosimilar interchangeability designation and EMA biosimilar comparability protocols jointly determine market access tiers and reimbursement positioning across the United States and European Union. WHO prequalification pathways shape access dynamics in lower-income markets where procurement agencies rely on international reference standards. Stakeholders must monitor evolving interchangeability state-level legislation and payer step-therapy mandates that will determine substitution velocity and brand retention strategies.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while accelerating long-term supply contract adoption, fundamentally restructuring how filgrastim manufacturers compete for institutional access.
Growth Catalysts
- FDA Interchangeability Pathway:The designation framework enables automatic substitution at pharmacies without prescriber intervention, accelerating biosimilar penetration in US outpatient settings.
- EMA Biosimilar Comparability Protocols:Streamlined approval pathways reduce time-to-market for European manufacturers, expanding patient access across EU member states.
- Oncology Chemotherapy Utilization:Rising treatment volumes in febrile neutropenia prophylaxis drive consistent demand for G-CSF support across academic medical centers.
Market Restraints
- Biologics Manufacturing Concentration:Fermentation capacity for E. coli-derived proteins concentrates among a limited supplier base in Germany and Switzerland, creating supply vulnerability.
- Cold-Chain Infrastructure Requirements:Temperature-controlled distribution from manufacturing through administration imposes capital intensity that limits market entry for emerging manufacturers.
- Originator Data Exclusivity:Amgen's decades of published clinical outcomes create switching hesitancy among conservative prescribers despite biosimilar analytical parity.
Strategic Opportunities
- Indian Subcontinent Access Expansion:WHO prequalification pathways enable tender participation by domestic manufacturers serving procurement agencies in Bangladesh and Pakistan.
- Home Administration Models:Prefilled syringe formulations support patient self-injection protocols, opening ambulatory and home health channels previously served only by infusion centers.
- Transplantation Protocol Standardization:Harmonized G-CSF mobilization regimens for peripheral blood stem cell collection create specification opportunities in specialized cellular therapy centers.
Industry Challenges
- Biosimilar Immunogenicity Surveillance:Post-market pharmacovigilance systems must detect rare antibody responses across distributed patient populations with limited long-term follow-up infrastructure.
- Multi-Site Manufacturing Coordination:Consistent glycosylation profiles and potency assays across geographically dispersed production facilities demand sophisticated quality system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filgrastim Market |
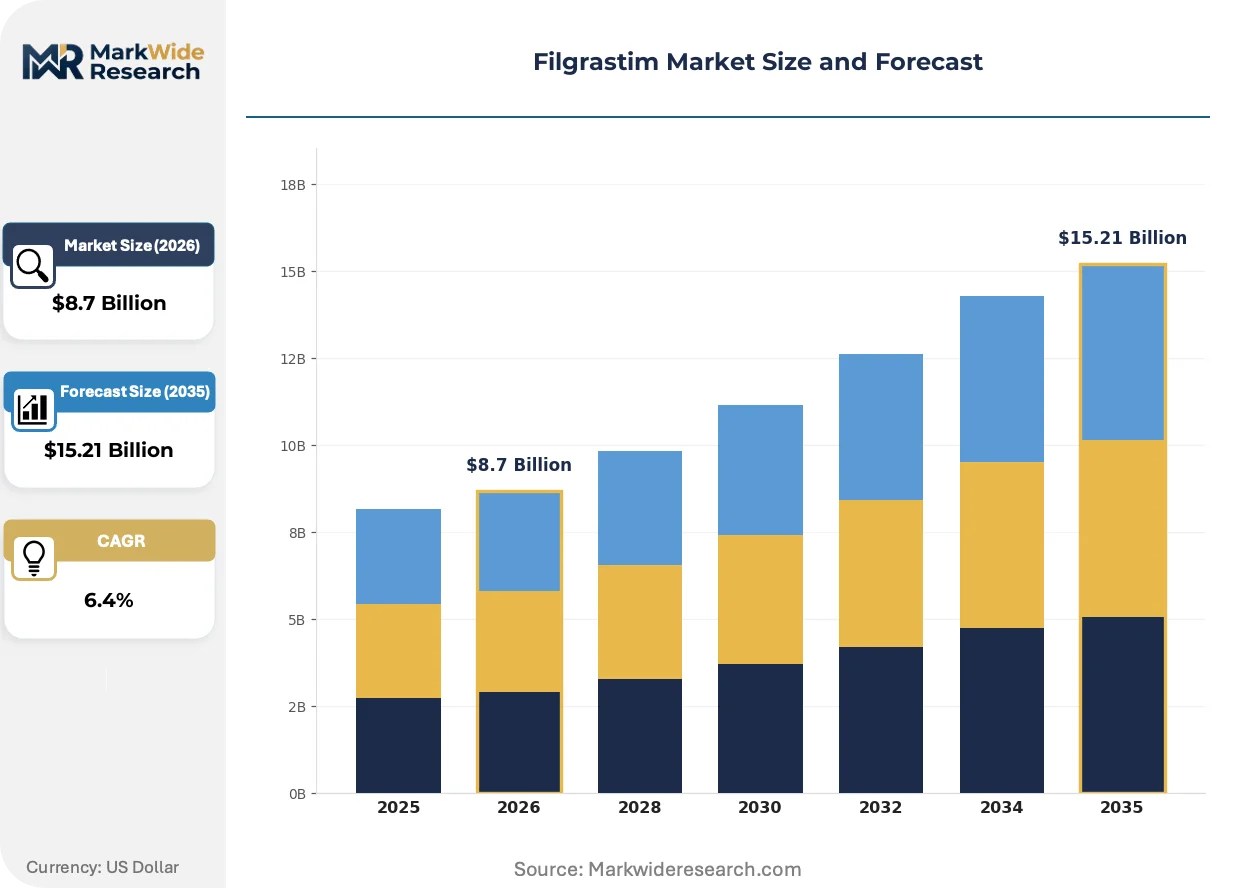
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Vial, Prefilled Syringe, Biosimilar Therapy Area: Oncology, Hematology, Transplantation, Autoimmune Disorders End User: Hospitals, Outpatient Clinics, Homecare, Research Laboratories Distribution Channel: Direct Sales, Wholesalers, Pharmacies, Online Platforms |
| Companies Covered | Amgen Inc., Teva Pharmaceutical Industries Ltd., Sandoz Group AG, Pfizer Inc., Mylan, Dr. Reddy's Laboratories, Boehringer Ingelheim, Roche, Biocon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filgrastim Market Emerging Trajectories
Filgrastim delivery and commercial models are undergoing systematic transformation as biological manufacturing advances intersect with regulatory harmonization and institutional purchasing evolution.
Long-acting pegfilgrastim formulations are modularizing treatment protocols by reducing injection frequency from daily to single per-cycle administration. Community oncology practices are adopting these extended-duration products to minimize patient visit burden and pharmacy preparation workload. This shift is compressing demand for short-acting filgrastim in adjuvant chemotherapy settings while preserving originator premium positioning in complex salvage regimens.
EMA's refined biosimilar guidance on immunogenicity assessment is accelerating European approval timelines for G-CSF follow-on products. The framework reduces residual uncertainty around switching studies, enabling manufacturers to reference established analytical comparability packages. Hospital procurement bodies in France and Italy are leveraging this regulatory clarity to expand tender eligibility and drive competitive pricing in centralized purchasing.
Consolidated hospital buying groups are unbundling traditional bundled contracts that tied filgrastim to broader oncology supportive care portfolios. Independent pharmacy benefit managers are constructing therapeutic class-specific formularies with explicit biosimilar preference tiers. This disintermediation is most advanced in the United States, where group purchasing organization consolidation has concentrated negotiating leverage among three dominant entities serving over sixty percent of acute care beds.
Filgrastim Market Segmentation
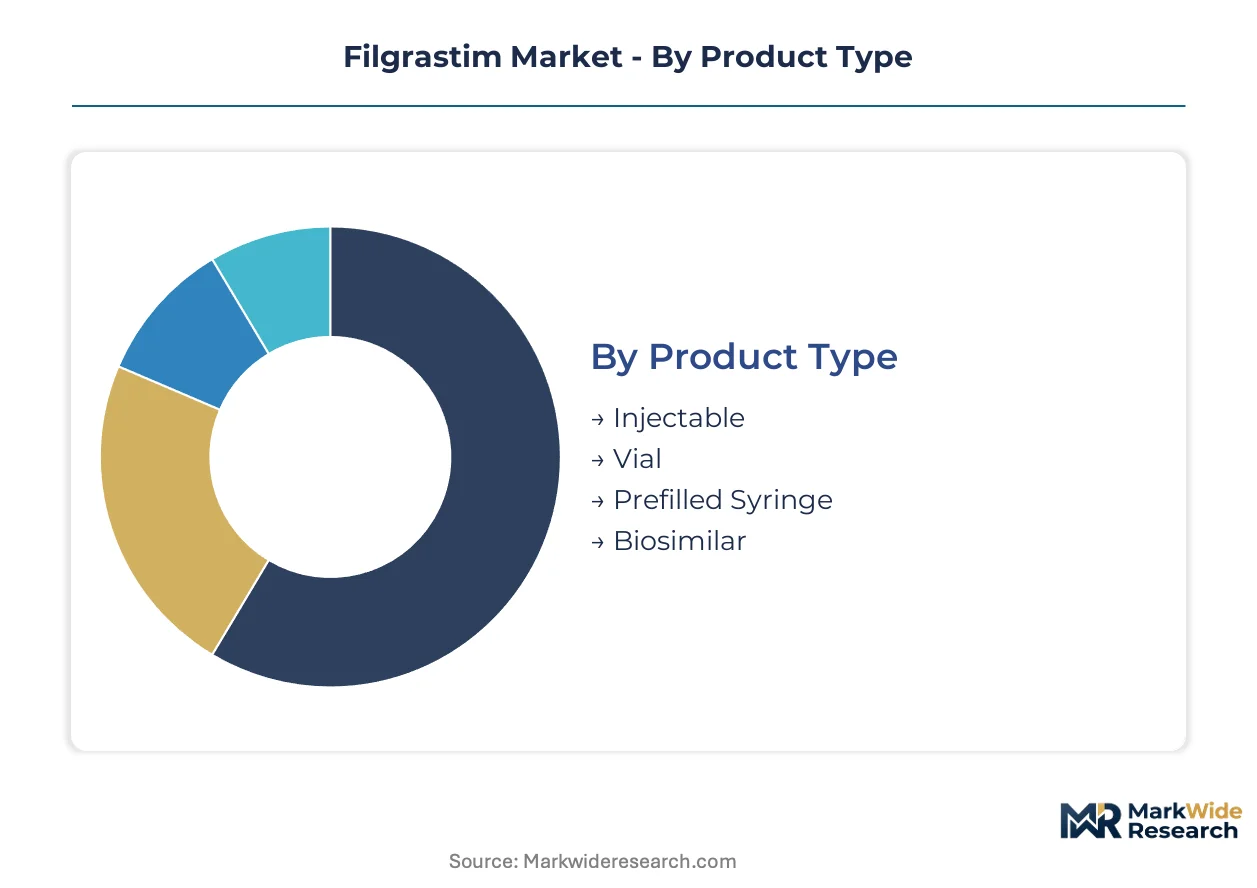
Filgrastim market segmentation reflects manufacturing complexity, clinical protocol requirements, and procurement channel evolution. Supply concentration across fermentation capacity and cold-chain infrastructure shapes competitive positioning within each category.
Product Type:
Fermentation capacity for E. coli-derived G-CSF concentrates among specialized biologics manufacturers in Germany and Switzerland, creating tiered supply security profiles across dosage forms.
- Prefilled Syringe:Ready-to-use presentation eliminates pharmacy reconstitution steps and reduces dosing errors. Hospital oncology units in the United States favor this format for febrile neutropenia prophylaxis protocols due to workflow efficiency gains. Cold-chain requirements from manufacturing through administration limit supplier qualification to established players with validated distribution networks.
- Biosimilar:Analytically comparable follow-on products manufactured through recombinant DNA technology in E. coli expression systems. European hospital procurement bodies leverage EMA comparability protocols to expand tender eligibility and compress pricing. FDA interchangeability designations accelerate automatic substitution at US outpatient pharmacies.
- Injectable:Lyophilized or liquid formulations requiring healthcare professional administration. Academic medical centers maintain this format for complex salvage chemotherapy regimens.
- Vial:Multi-dose presentations suited to high-volume institutional settings with dedicated pharmacy compounding capabilities.
Prefilled syringe formats absorb the bulk of installed capacity; biosimilar production lines are expanding most quickly.
Therapy Area:
Clinical protocol standardization varies sharply across indication complexity, with transplantation and cellular therapy imposing the most stringent product specifications.
- Oncology:Febrile neutropenia prophylaxis in myelosuppressive chemotherapy represents the foundational use case. High treatment volumes across academic and community settings sustain consistent demand. US protocols remain the most deeply penetrated globally, driving specification requirements that cascade to other markets.
- Transplantation:Peripheral blood stem cell mobilization for autologous and allogeneic procedures demands precise timing and validated cold-chain integrity. Specialized cellular therapy centers command premium positioning due to narrow supplier qualification criteria and limited manufacturing slots.
- Hematology:Congenital neutropenia and cyclic neutropenia management requires chronic administration protocols.
- Autoimmune Disorders:Off-label and emerging applications in neutrophil-mediated inflammatory conditions.
Oncology commands the dominant share of volume throughput; transplantation offers the steepest margin expansion trajectory.
End User:
Site-of-care migration from inpatient to ambulatory settings is reshaping packaging requirements and reimbursement pathways.
- Hospitals:Consolidated purchasing through group purchasing organizations concentrates negotiating leverage. Multi-year supply agreements with originator and biosimilar manufacturers are displacing spot procurement.
- Outpatient Clinics:Community oncology practices adopt prefilled syringe formats to minimize pharmacy preparation burden.
- Homecare:Self-administration protocols supported by patient education programs and remote monitoring infrastructure.
- Research Laboratories:Investigational protocols and cell therapy process development applications.
Hospitals retain the largest procurement volumes; homecare channels are gaining share fastest.
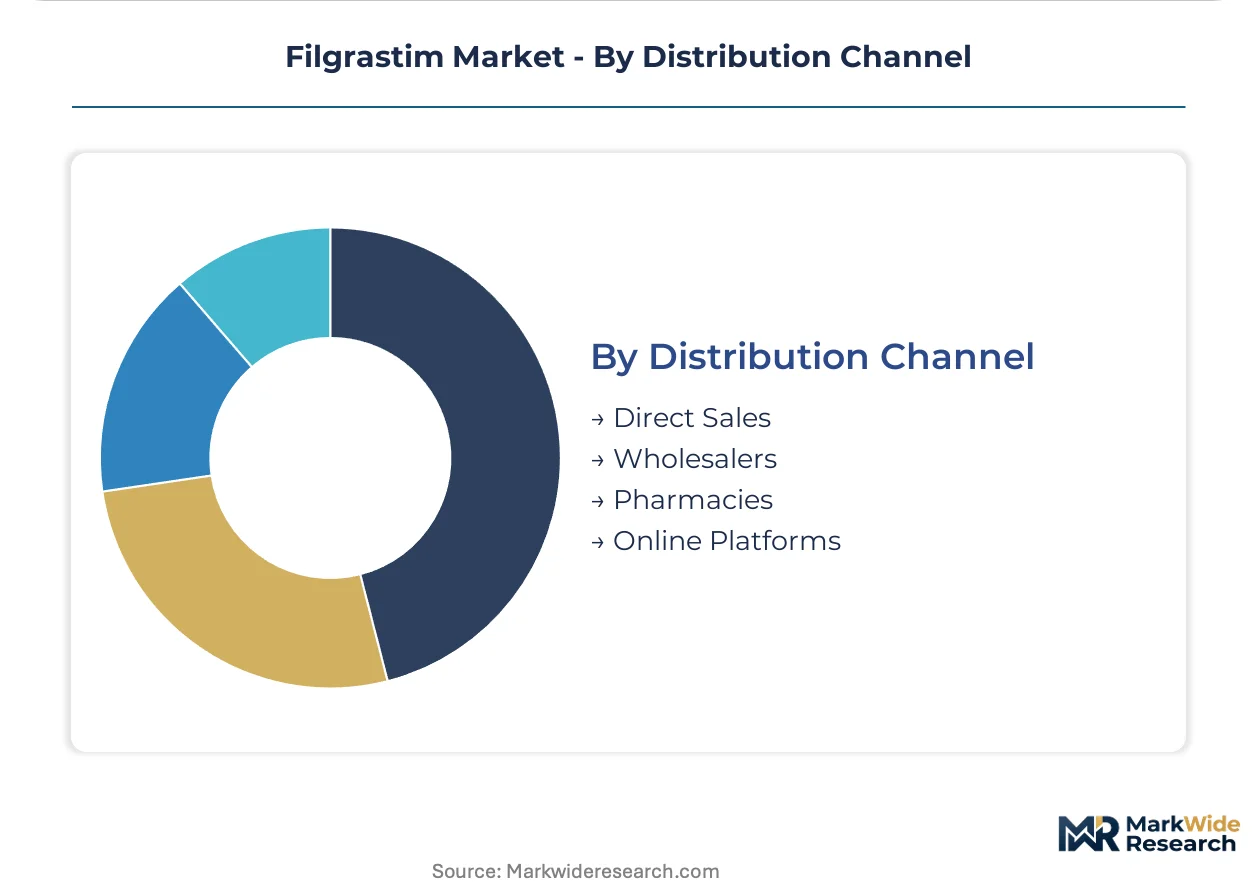
Distribution Channel:
Cold-chain integrity requirements and traceability mandates favor distributors with validated temperature monitoring systems.
- Direct Sales:Manufacturer-to-institution relationships for large hospital systems and integrated delivery networks. Long-term supply agreements with explicit volume commitments and price protection clauses.
- Wholesalers:Specialized biologics distributors with temperature-controlled warehousing and same-day replenishment capabilities.
- Pharmacies:Retail and specialty pharmacy channels for outpatient prescription fulfillment.
- Online Platforms:Emerging direct-to-patient models in markets with established cold-chain last-mile infrastructure.
Direct sales channels handle the majority of institutional volume; online platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation and febrile neutropenia prophylaxis protocol penetration concentrate demand most acutely in the United States, with regulatory frameworks in Germany, India, and Japan shaping supply-side manufacturing and access dynamics across distinct market tiers.
United States
Febrile neutropenia prophylaxis protocols in academic medical centers and community oncology practices drive substantial G-CSF consumption volumes. FDA interchangeability designations for biosimilars enable automatic pharmacy substitution without prescriber intervention, accelerating outpatient penetration. The Boston-Cambridge biotech corridor and Research Triangle Park in North Carolina host specialized biologics manufacturing and clinical trial infrastructure supporting product development.
Germany
EMA biosimilar comparability protocols streamline approval timelines for domestic manufacturers serving European hospital procurement bodies. The country's national pharmaceutical regulator enforces stringent GMP standards for E. coli-derived protein fermentation facilities. The Rhine-Main region around Frankfurt and the Munich metropolitan area concentrate biologics production capacity and specialized cold-chain distribution networks.
India
WHO prequalification pathways enable domestic manufacturers to participate in procurement tenders serving Bangladesh, Pakistan, and African markets. CDSCO oversees biosimilar approval frameworks that reference established analytical comparability packages. Hyderabad and Bangalore host fermentation capacity and formulation facilities supplying cost-competitive filgrastim presentations to public health programs.
Japan
PMDA maintains rigorous immunogenicity assessment requirements that shape post-market surveillance obligations for G-CSF products. The Tokyo-Osaka corridor concentrates hospital procurement decision-making for myelosuppressive chemotherapy support. Kansai-based manufacturers leverage established E. coli expression platforms to serve domestic oncology and transplantation protocols.
Switzerland
Swissmedic oversees specialized approval pathways for biologics manufactured in Basel-Zurich biopharma clusters. The country's concentrated fermentation infrastructure supplies active pharmaceutical ingredients to formulation facilities across Europe. Geneva and Basel host headquarters operations for manufacturers negotiating multi-year supply agreements with consolidated hospital buying groups.
Filgrastim Market Vendor Landscape
United States-based originator manufacturers anchor the premium-tier segment; European and Indian specialists hold positions across biosimilar manufacturing and emerging market access. Market structure reflects consolidation around three strategic archetypes: originator incumbents with decades of clinical data, multi-site biosimilar manufacturers with E. coli fermentation scale, and regional specialists leveraging WHO prequalification for tender participation. Dominant competitive moves include long-term supply contract negotiation with consolidated hospital purchasing entities and backward integration into specialized cold-chain distribution infrastructure.
Within the originator tier, Amgen Inc. occupies a position defined by brand heritage and published clinical outcomes. Among multi-national pharmaceutical conglomerates, Pfizer Inc. and Roche exemplify diversified portfolios spanning originator and biosimilar G-CSF presentations. Teva Pharmaceutical Industries Ltd. and Dr. Reddy's Laboratories represent manufacturing-scale specialists with fermentation capacity distributed across multiple production sites. Sandoz Group AG anchors early-mover biosimilar positioning through established European hospital channel relationships. Biocon occupies a distinct archetype as an Indian manufacturer leveraging WHO prequalification pathways for emerging market procurement participation.
| Leading Market Players |
|---|
| Amgen Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sandoz Group AG |
| Pfizer Inc. |
| Mylan |
| Dr. Reddy's Laboratories |
| Boehringer Ingelheim |
| Roche |
| Biocon |
| Others |
Supply Flow & Price Mechanics
Fermentation-grade nutrient media and E. coli cell bank maintenance costs cascade through three distinct pricing tiers before reaching institutional buyers, with German and Swiss manufacturing clusters commanding premium positioning against Indian cost-optimized alternatives.
Pricing Analysis
Volume throughput concentrates in standard-tier biosimilar presentations while margin expansion concentrates in originator-maintained premium channels for transplantation protocols. Three-tier pricing structure across premium, standard, and economy levels separates Amgen's Neupogen heritage positioning from Sandoz's early-mover biosimilar tier and Biocon's WHO-prequalified economy access tier. Price compression runs through the standard tier as FDA interchangeability designations accelerate automatic substitution. Community oncology practices exhibit highest price sensitivity due to reimbursement pressure, while academic medical centers in transplantation maintain lowest sensitivity due to protocol rigidity.
Supply Chain Analysis
EMA GMP certification and FDA establishment inspection reports gate supplier qualification before contract participation, creating structural barriers for emerging manufacturers. Fermentation capacity concentrates in Germany, Switzerland, and India, with active pharmaceutical ingredient output feeding formulation facilities across Europe and North America. Raw material dependencies center on pharmaceutical-grade yeast extract, trace mineral supplements, and single-use bioreactor components. Single-source vulnerability concentrates in specialized cold-chain distribution lanes serving cellular therapy centers. Distribution runs through direct manufacturer-to-institution relationships for hospital systems, supplemented by specialized biologics wholesalers for ambulatory channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
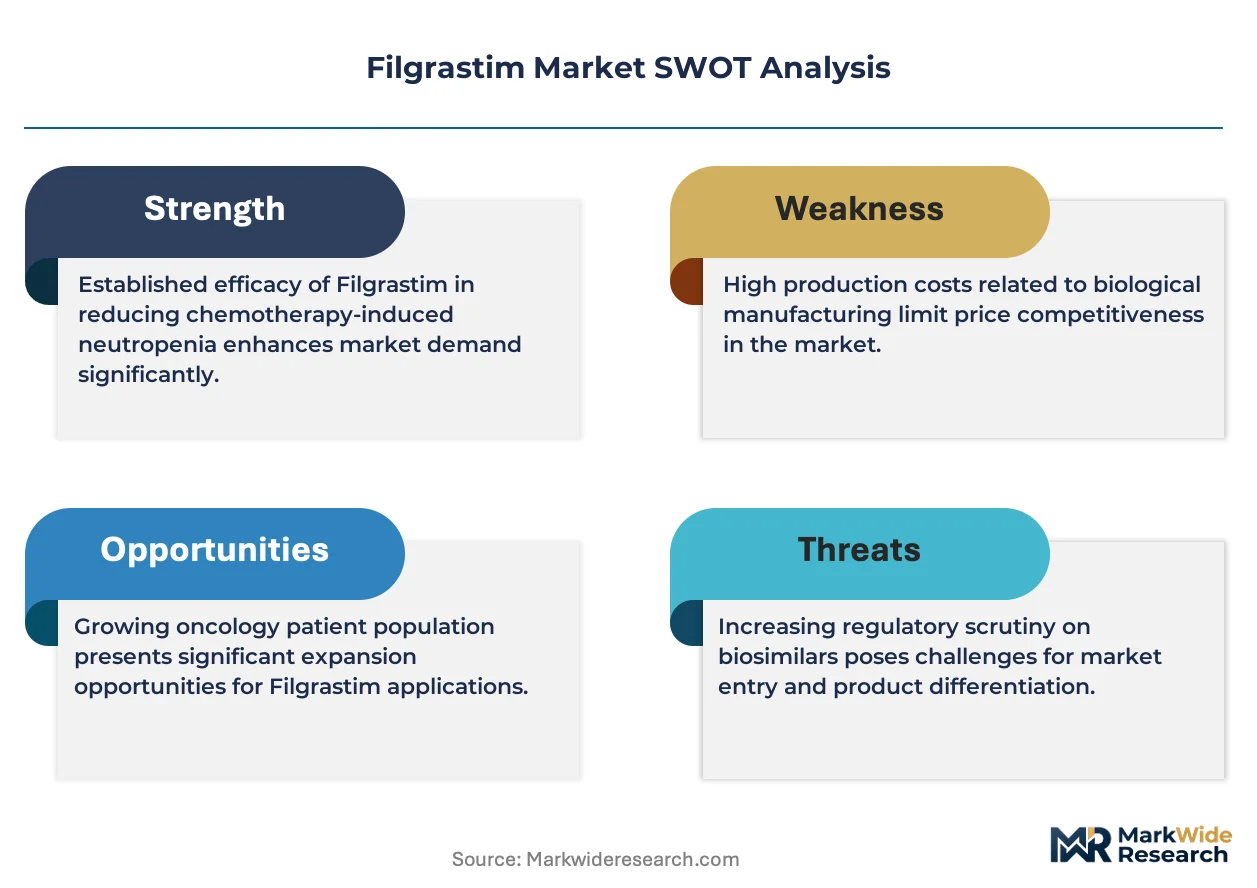
The filgrastim market sits in a technology-transition phase as long-acting pegfilgrastim formulations displace daily-injection protocols across adjuvant chemotherapy settings, compressing short-acting demand while preserving complex-regimen premium positioning.
For Market Incumbents: Acquire captive fermentation capacity in the Rhine-Main corridor to secure E. coli expression platform continuity against biosimilar manufacturing scale expansion by Teva and Dr. Reddy's. Defend transplantation protocol share through backward integration into validated cold-chain distribution infrastructure serving cellular therapy centers. Counter FDA interchangeability acceleration by deepening clinical outcome publication in salvage chemotherapy settings where switching hesitancy persists. For New Entrants and Emerging Players: Capture WHO prequalification pathway participation for tender eligibility in Bangladesh, Pakistan, and African procurement markets where originator presence remains thin. Prioritize Hyderabad and Bangalore manufacturing bases to leverage existing CDSCO inspection infrastructure and cost-competitive fermentation economics. Enter through prefilled syringe format specialization targeting community oncology workflow efficiency demands rather than competing head-to-head in lyophilized vial institutional contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap biosimilar manufacturers with EMA-approved G-CSF portfolios and underutilized Indian fermentation assets during periods of originator price aggression. Long-term viability hinges on positioning for pegfilgrastim formulation transition rather than short-acting filgrastim share capture alone. Monitor FDA interchangeability designation velocity as the critical inflection signal for substitution-driven margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Interchangeability Designation Pursuit | Automatic pharmacy substitution authority accelerates biosimilar outpatient penetration against originator retention strategies. |
| Backward Integration into Cold-Chain Distribution | In-house temperature-controlled logistics secures transplantation protocol qualification and margin protection. |
| EMA Biosimilar Comparability Package Investment | Streamlined European approval timelines expand hospital tender eligibility across France, Italy, and Germany. |
| Long-Acting Pegfilgrastim Formulation Development | Single per-cycle administration captures adjuvant chemotherapy volume migrating from daily injection burden. |
| WHO Prequalification Pathway Engagement | International reference standard compliance unlocks procurement agency participation in lower-income markets. |
Methodological Framework
FDA Orange Book listings, EMA EPAR documentation, and ClinicalTrials.gov protocol records formed the secondary backbone, cross-referenced against primary interviews with hospital formulary directors, GPO contracts managers, biosimilar regulatory affairs leads, and cold-chain logistics specialists. Bottom-up volume estimates by dosage form and therapy area triangulated against top-down market sizing from customs trade data and manufacturer revenue disclosures.
Historical trendline analysis of G-CSF utilization rates by chemotherapy protocol intensity informed projection modeling across the analysis window. Segmentation dimensions included product type, therapy area, end-user site of care, and regional regulatory cluster. CAGRs derived from weighted average of protocol penetration trajectories, biosimilar substitution elasticity parameters, and manufacturing capacity expansion schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA interchangeability designation velocity and pegfilgrastim formulation adoption curves. Forecasts reflect documented assumptions around hospital procurement consolidation trajectories and EMA regulatory guidance stability. A model refresh is warranted upon material change in CMS reimbursement policy for biosimilar G-CSF products.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Pharmaceutical Warehousing Market
Pharmaceuticals
Methylphenidate Hydrochloride Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
OTC Topical Drugs Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
Compound Acetaminophen Market
Pharmaceuticals
Meningococcal Vaccines Market
Pharmaceuticals
Performance Enhancing Drugs Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
Alopecia Drugs Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Nicotine Replacement Product Market