
 South Africa Diabetes Drugs Market | 2026-2036
South Africa Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Diabetes Drugs Market Analytics
Biologic drug manufacturing is rewriting the competitive landscape for diabetes therapy in South Africa. Novo Nordisk A/S leverages its recombinant insulin production infrastructure to dominate the high-potency analog segment. Sanofi anchors its position through established distribution partnerships with private hospital groups across the country. Eli Lilly differentiates via concentrated R&D investment in next-generation GLP-1 receptor agonist formulations tailored for emerging-market pricing constraints.
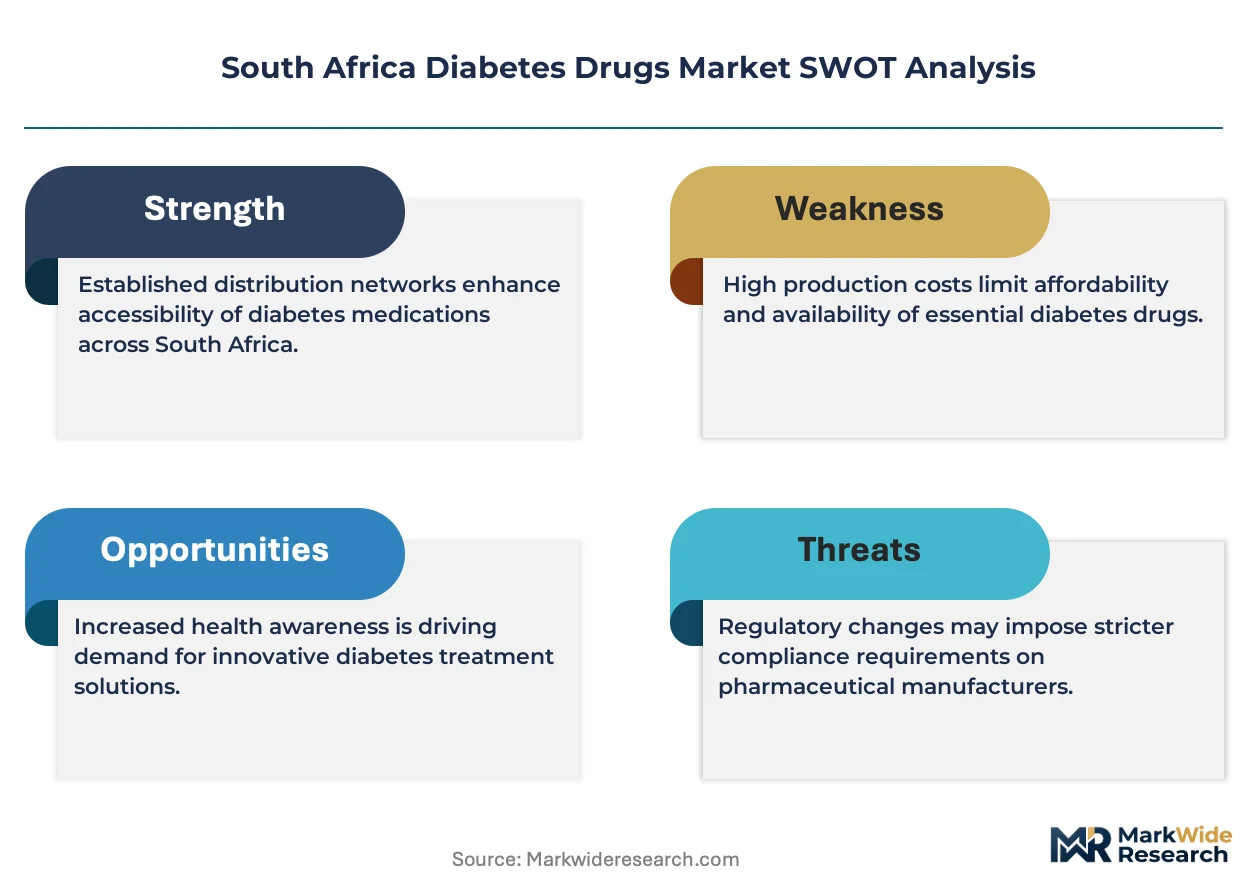
Diabetes drugs encompass synthetic and biologically derived pharmaceutical agents formulated to regulate blood glucose levels through insulin replacement, secretion stimulation, or renal glucose excretion inhibition; these compounds typically require cold-chain distribution at 2-8°C and sterile manufacturing under GMP conditions to preserve peptide integrity and therapeutic efficacy. Insulin retains the largest revenue share due to entrenched prescribing habits in public sector facilities, while SGLT2 inhibitors represent the fastest-expanding drug class as nephrologists and cardiologists increasingly co-prescribe them for renal protection beyond glycemic control. The homecare delivery channel is gaining structural importance as South Africa's chronic disease management programs shift toward decentralized patient monitoring models.
The South African Health Products Regulatory Authority (SAHPRA) governs market authorization and GMP compliance for all diabetes pharmaceuticals, while the Department of Health's Essential Medicines List determines public sector reimbursement and tender eligibility. The National Health Insurance framework will reshape procurement centralization and pricing transparency for manufacturers seeking access to government contracts. Stakeholders must monitor SAHPRA's evolving biosimilar approval pathways and the NHI's formulary design to anticipate volume shifts between originator and generic insulin products.
Market Dynamics
The National Health Insurance framework is compressing procurement timelines and forcing manufacturers to restructure tender strategies around centralized volume commitments rather than fragmented private hospital contracts.
Growth Catalysts
- Essential Medicines List revision:SAHPRA's updated prioritization of non-communicable disease management is unlocking public sector tender volumes for GLP-1 agonists and insulin analogues previously restricted to private channels.
- Gauteng-KwaZulu-Natal hospital network expansion:Provincial health departments in these two provinces are consolidating diabetes care into specialized chronic disease units, creating concentrated demand nodes for cold-chain biologics.
- Biosimilar pathway maturation:SAHPRA's evolving abbreviated approval routes for insulin biosimilars are shortening time-to-market for domestic manufacturers, expanding the supplier base beyond originator multinationals.
Market Restraints
- Import dependency for active pharmaceutical ingredients:Over 90 percent of insulin API supply originates from European and Indian contract manufacturers, exposing the market to rupee-euro volatility and shipping disruptions through the Cape of Good Hope route.
- Cold-chain infrastructure gaps:Rural provinces lack verified 2-8°C storage capacity at clinic level, forcing manufacturers to absorb write-off costs for temperature excursions or restrict distribution to urban nodes.
- Prescriber conservatism in public facilities:Entrenched clinical protocols at tertiary hospitals prioritize human insulin over analogues despite glycemic superiority, limiting uptake of premium formulations even where tenders are won.
Strategic Opportunities
- Eastern Cape and Limpopo penetration:These under-served provinces operate minimal private diabetes clinic infrastructure, creating first-mover advantage for manufacturers establishing direct-to-clinic distribution partnerships ahead of NHI rollout.
- Renal-cardiology co-prescribing convergence:Nephrologists and cardiologists are adopting SGLT2 inhibitors for albuminuria reduction independent of endocrinology referrals, opening new prescriber segments beyond traditional diabetes specialists.
- Homecare monitoring integration:Remote glucose telemetry platforms linked to provincial electronic health records are enabling outcome-based reimbursement pilots that reward sustained HbA1c control rather than product volume.
Industry Challenges
- Biologic manufacturing technician scarcity:GMP-compliant aseptic filling and peptide purification expertise concentrates in Cape Town and Johannesburg, constraining capacity expansion at emerging domestic facilities.
- SAHPRA inspection backlog:Pre-approval GMP site audits for new manufacturing lines currently queue 18-24 months, delaying product launches and freezing capital in incomplete facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Diabetes Drugs Market |
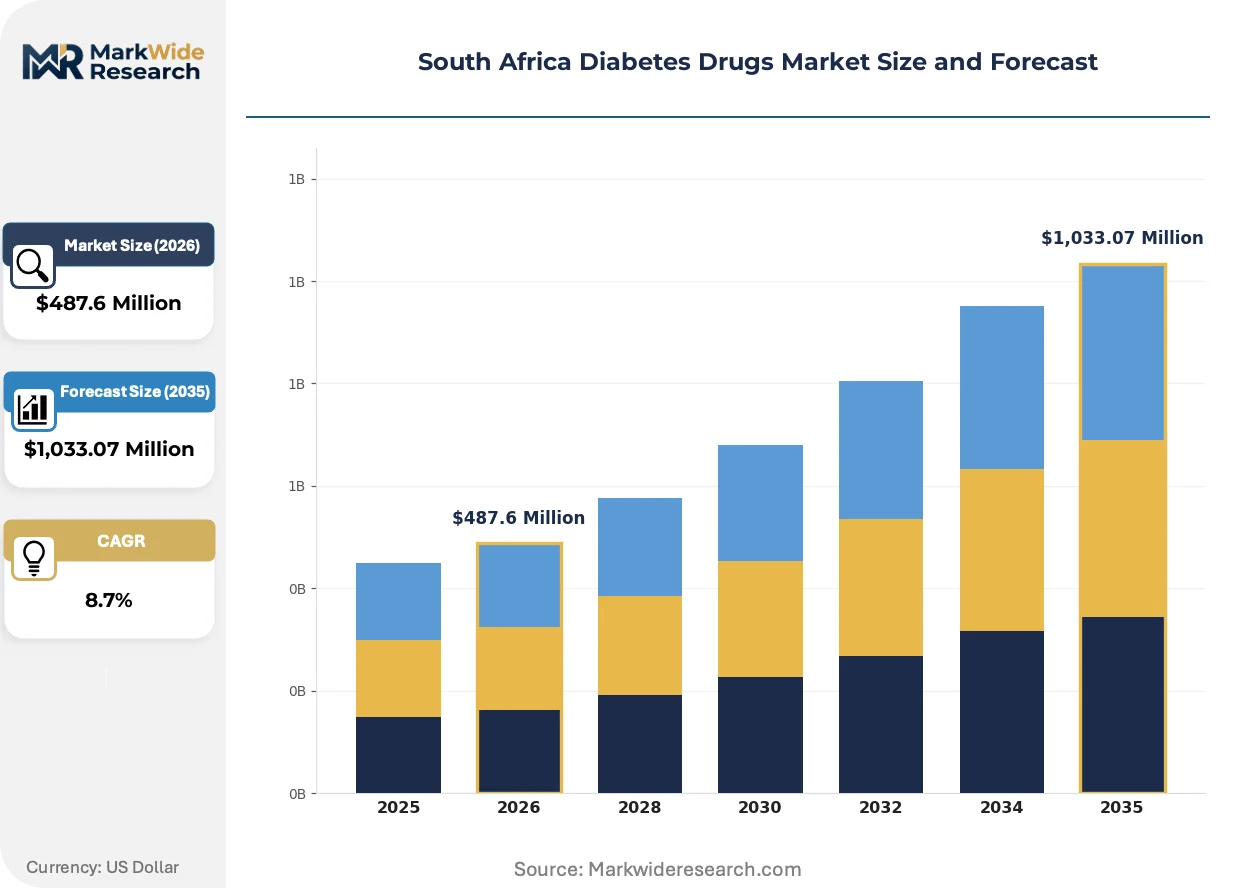
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Insulin, GLP-1 Agonists, DPP-4 Inhibitors, SGLT2 Inhibitors Delivery Method: Injectable, Oral, Continuous Glucose Monitoring, Patch End User: Hospitals, Clinics, Homecare, Pharmacies Age Group: Children, Adolescents, Adults, Seniors |
| Companies Covered | Novo Nordisk A/S, Sanofi, Eli Lilly, Merck & Co., AstraZeneca, Boehringer Ingelheim, Biovac, GlaxoSmithKline, Takeda, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Diabetes Drugs Market Evolving Landscape
Digital integration is collapsing the traditional separation between pharmaceutical supply and patient monitoring, while regulatory pressure on cold-chain integrity is accelerating packaging innovation.
Continuous glucose monitoring systems paired with algorithm-driven insulin dosing is virtualizing the patient-pharmacist relationship. Private diabetes clinics in Johannesburg and Durban are deploying these closed-loop configurations fastest, compressing the role of traditional retail pharmacy in chronic disease management and shifting margin capture toward device-pharma bundled contracts.
SAHPRA's impending adoption of ICH Q5E comparability guidelines for biologics is tightening stability testing requirements for insulin biosimilars. Domestic manufacturers must now demonstrate molecular similarity across three production lots rather than single-batch validation, extending development timelines but raising barrier heights against low-quality entrants.
Hospital procurement committees are unbundling device and drug purchasing decisions that historically ran through single tender awards. This separation allows endocrinology units to select continuous monitoring hardware independently of pharmacy-directed insulin contracts, fragmenting vendor lock-in and forcing manufacturers to defend position across two distinct buying centers simultaneously.
South Africa Diabetes Drugs Market Segmentation
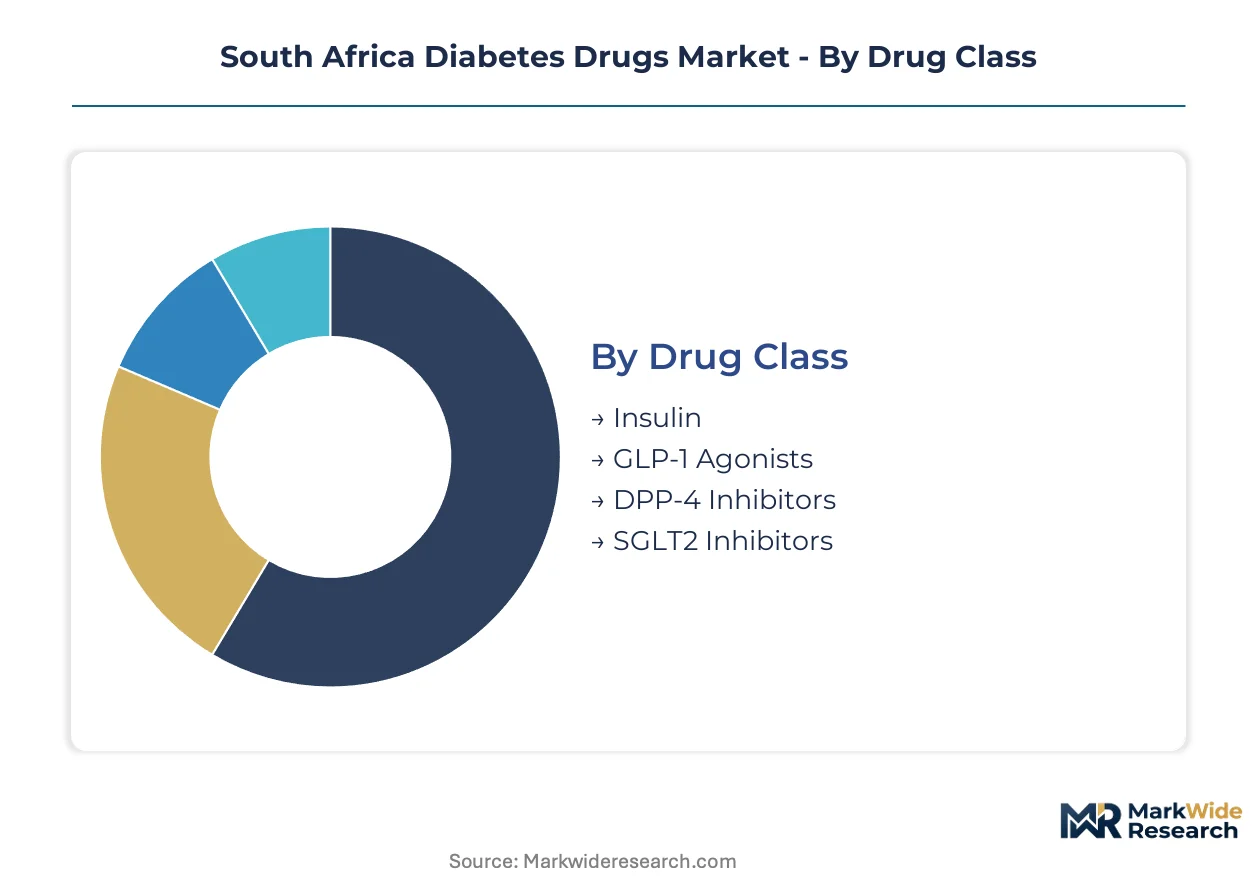
Segmentation in South Africa's diabetes drugs market reveals how therapeutic choices, distribution infrastructure, and patient demographics intersect to determine commercial viability. Understanding these divides exposes where procurement power concentrates and which access channels are structurally underdeveloped.
Drug Class:
Mature biologic therapies anchor volume while emerging oral agents disrupt prescribing patterns across Gauteng and KwaZulu-Natal hospital networks.
- Insulin:Recombinant human insulin and analogues require sterile aseptic manufacturing and 2-8°C cold-chain preservation throughout distribution. Public sector tenders in Gauteng and KwaZulu-Natal prioritize this category due to entrenched clinical protocols at tertiary hospitals, though prescriber conservatism limits analogue uptake despite glycemic superiority.
- GLP-1 Agonists:Peptide-based injectables stimulate glucose-dependent insulin secretion with demonstrated cardiovascular benefit. Department of Health Essential Medicines List revisions are unlocking public sector procurement volumes previously restricted to private diabetes clinics in Johannesburg and Durban.
- DPP-4 Inhibitors:Oral gliptins extend endogenous incretin half-life through enzyme inhibition.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 blockers reduce renal glucose reabsorption; nephrologists and cardiologists are adopting these for albuminuria reduction independent of endocrinology referrals.
Insulin handles the majority of throughput; SGLT2 inhibitors are gaining share fastest as renal-cardiology co-prescribing expands.
Delivery Method:
Cost tier stratification separates capital-intensive device-dependent therapies from commodity oral formulations accessible through retail pharmacy networks.
- Injectable:Subcutaneous delivery of insulin and GLP-1 agonists via vial-syringe or pen systems dominates hospital procurement. Cold-chain infrastructure gaps in rural Eastern Cape and Limpopo force manufacturers to restrict distribution to urban nodes or absorb temperature excursion write-offs.
- Oral:Small-molecule tablets and capsules for metformin, DPP-4 inhibitors, and SGLT2 inhibitors require ambient storage only. Pharmacies in peri-urban townships handle significant volume due to lower storage barriers and patient self-administration convenience.
- Continuous Glucose Monitoring:Sensor-augmented pump systems with algorithm-driven insulin dosing.
- Patch:Transdermal or microneedle array delivery systems for basal insulin or GLP-1.
Injectable formats capture the highest absolute spend; continuous glucose monitoring is climbing fastest as private clinics deploy closed-loop configurations.
End User:
Customer type determines tender structure, with centralized hospital procurement diverging sharply from fragmented retail pharmacy reimbursement.
- Hospitals:Tertiary and district facilities in Gauteng and KwaZulu-Natal operate centralized pharmacy committees that bundle device and drug purchasing through single tender awards. National Health Insurance framework compression is forcing manufacturers to restructure strategies around volume commitments rather than fragmented contracts.
- Clinics:Primary healthcare facilities and specialized chronic disease units. Eastern Cape and Limpopo provinces operate minimal private diabetes clinic infrastructure, creating first-mover advantage for manufacturers establishing direct-to-clinic partnerships.
- Homecare:Patient-managed therapy with remote monitoring integration.
- Pharmacies:Retail dispensaries and community health centers.
Hospitals command the dominant procurement volume; homecare is expanding most quickly under decentralized chronic disease management programs.
Age Group:
Volume concentrates in mature patient populations while pediatric and adolescent segments face structural access barriers.
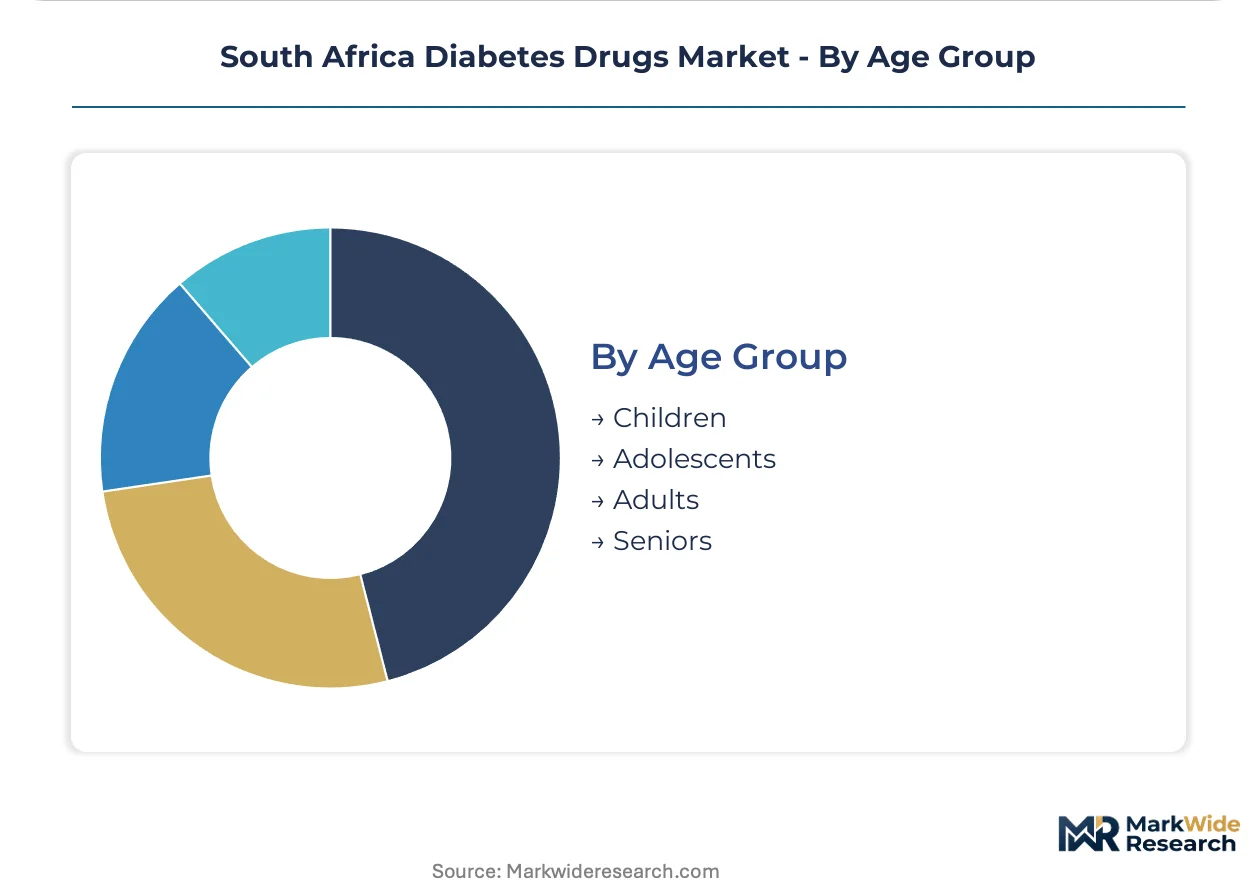
- Adults:Patients aged 18-64 represent the core prescribing base for insulin and oral agents. Workplace-based health screening in Johannesburg and Cape Town corporate clusters drives early diagnosis and sustained therapy adherence.
- Seniors:Patients over 65 with comorbid cardiovascular and renal conditions. Polypharmacy complexity in this segment favors SGLT2 inhibitors and GLP-1 agonists with demonstrated organ protection beyond glycemic control.
- Children:Pediatric type 1 diabetes patients requiring intensive insulin regimens.
- Adolescents:Transition-age patients with rising type 2 incidence.
Adults generate the majority of prescription volume; seniors are expanding fastest as population aging accelerates and cardiorenal protective prescribing spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian pharmaceutical exporters supply active pharmaceutical ingredients to South African formulation facilities, while European biologics manufacturers ship finished insulin products through Durban and Cape Town ports.
Gauteng
The Johannesburg-Pretoria corridor houses the densest concentration of private diabetes clinics and tertiary hospital networks. SAHPRA's Pretoria headquarters accelerates regulatory processing for manufacturers targeting public sector tenders. The Charlotte Maxeke Johannesburg Academic Hospital anchors specialist endocrinology referrals that drive analogue insulin prescribing.
KwaZulu-Natal
Durban's port infrastructure handles the majority of temperature-controlled biologic imports entering South Africa. The provincial health department's chronic disease unit consolidation creates concentrated procurement nodes for cold-chain dependent therapies. King Edward VIII Hospital operates the largest public sector diabetes clinic in the province.
Western Cape
Cape Town's biotech manufacturing cluster concentrates GMP-compliant aseptic filling capacity for domestic insulin production. The University of Cape Town's clinical trial infrastructure attracts multinational sponsors testing biosimilar formulations. Groote Schuur Hospital maintains entrenched protocols favoring human insulin over premium analogues.
Eastern Cape
Minimal private clinic infrastructure and unreliable cold-chain storage at rural facilities restrict biologic distribution to urban nodes. The provincial health department's direct-to-clinic partnership pilots offer first-mover advantage for manufacturers establishing decentralized supply models. Nelson Mandela Academic Hospital in Mthatha serves as the sole tertiary referral center for complex diabetes cases.
Limpopo
Workplace health screening programs at platinum and chrome mining operations drive early diabetes diagnosis in the Bushveld Igneous Complex. Provincial clinics lack verified 2-8°C storage, forcing manufacturers to absorb temperature excursion costs or exclude rural areas. Polokwane's hospital network represents the only concentrated demand node for insulin procurement.
South Africa Diabetes Drugs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement layers. The market structure tilts toward consolidated originator multinationals in biologics, with emerging domestic manufacturers gaining traction in oral small-molecule segments. Three archetypes dominate: European-Nordic insulin specialists with recombinant production heritage, diversified French-German pharmaceutical conglomerates leveraging hospital distribution partnerships, and emerging-market biosimilar challengers exploiting abbreviated SAHPRA pathways. Competitive intensity centers on tender restructuring around NHI volume commitments and cold-chain reliability guarantees for rural distribution.
Among the European-Nordic insulin specialists, Novo Nordisk A/S anchors the high-potency analogue segment through established recombinant manufacturing infrastructure. Sanofi occupies a position exemplifying diversified pharmaceutical conglomerates with embedded hospital group relationships. Eli Lilly sits within the innovation-focused archetype, concentrating development resources on next-generation GLP-1 formulations calibrated for emerging-market pricing constraints. These three entities collectively represent the dominant competitive tension shaping procurement negotiations with South Africa's consolidating public health purchasers.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Sanofi |
| Eli Lilly |
| Merck & Co. |
| AstraZeneca |
| Boehringer Ingelheim |
| Biovac |
| GlaxoSmithKline |
| Takeda |
| Others |
Value Network & Pricing Analysis
Single-source dependency on European and Indian active pharmaceutical ingredient suppliers compresses pricing spreads between originator insulin analogues and biosimilar alternatives while forcing manufacturers to absorb rupee-euro volatility through inventory hedging or tender margin sacrifice. This import concentration simultaneously shapes supply chain decisions around buffer stock sizing and distribution network redundancy.
Pricing Analysis
The technology-generation pricing gap between recombinant human insulin, first-generation analogues, and next-generation GLP-1 formulations structures procurement negotiations across Gauteng and KwaZulu-Natal hospital networks. Pricing stratifies across premium analogue, standard human insulin, and economy biosimilar tiers, with differentiation driven by SAHPRA certification status and cold-chain reliability guarantees. Cost compression in the standard tier intensifies as domestic manufacturers exploit abbreviated biosimilar pathways, while public sector buyers exhibit highest price sensitivity due to Essential Medicines List budget caps. Private diabetes clinics retain lowest sensitivity, prioritizing glycemic outcomes over unit cost.
Supply Chain Analysis
Extended payment terms from provincial health departments force API suppliers to shoulder 90-180 day receivables cycles, concentrating working capital strain on domestic formulation facilities. Active pharmaceutical ingredient supply draws from Denmark, Germany, and India, with recombinant peptide fermentation feedstocks and sterile filling components anchoring cost structures. Single-source vulnerability persists for high-potency analogue cell lines, where patent-protected master cell banks restrict supplier diversification. Distribution runs through Durban's temperature-controlled port infrastructure, with last-mile cold-chain gaps in Eastern Cape and Limpopo forcing urban-centric deployment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where SAHPRA regulatory entrenchment and cold-chain infrastructure switching costs protect incumbent positions against price-based disruption.
For Market Incumbents: Harden tender defense by securing exclusive distribution partnerships with Gauteng and KwaZulu-Natal chronic disease unit consolidations ahead of NHI formulary finalization. Deepen backward integration into peptide purification capacity at Cape Town manufacturing clusters to offset API import dependency and create cost asymmetry against biosimilar challengers. For New Entrants and Emerging Players: Pursue direct-to-clinic distribution partnerships in Eastern Cape and Limpopo provinces where minimal private infrastructure creates first-mover whitespace before NHI rollout centralizes procurement. Target the SGLT2 inhibitor segment for nephrology-cardiology co-prescribing, leveraging ambient storage requirements to bypass cold-chain barriers that constrain biologic competitors. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors acquisition of domestic manufacturers with SAHPRA-approved biosimilar filings and established provincial tender relationships. Long-term viability hinges on National Health Insurance formulary inclusion, with the signal to watch being SAHPRA's publication of ICH Q5E comparability guideline implementation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | Secures 2-8°C distribution integrity through Eastern Cape and Limpopo rural clinic networks. |
| Biosimilar Regulatory Approval Pathway | Accelerates SAHPRA market authorization via abbreviated ICH Q5E comparability demonstrations. |
| Hospital System Partnership | Locks in volume commitments with Charlotte Maxeke Johannesburg Academic Hospital endocrinology units. |
| Manufacturing Scale-Up | Expands Cape Town GMP aseptic filling capacity to reduce import dependency for insulin formulations. |
| Reimbursement Strategy | Aligns SGLT2 inhibitor positioning with National Health Insurance renal protection coverage criteria. |
Research Methodology
Cross-validation between hospital procurement managers and SAHPRA regulatory affairs specialists anchors the qualitative findings on tender restructuring dynamics. Primary interviews with formulary directors, cold-chain logistics operators, and domestic biosimilar manufacturers combined with secondary validation through SAHPRA registration databases, Essential Medicines List revision documents, and provincial health department tender awards. Bottom-up patient volume modeling and top-down pharmaceutical expenditure reconciliation triangulate market sizing.
Calibration against historical insulin analogue adoption curves and GLP-1 expansion patterns in comparable emerging markets refines projection parameters across the analysis window. Segmentation dimensions span drug class, delivery method, end-user facility type, and provincial regulatory cluster. CAGRs derive from multivariate regression across epidemiological prevalence trends, reimbursement policy scenarios, and prescriber behavior transition rates, with specific weighting for NHI implementation phasing assumptions.
Sensitivities concentrate around National Health Insurance rollout timing, SAHPRA inspection backlog resolution, and API import tariff fluctuations. Forecasts reflect documented assumptions regarding prescriber protocol evolution and cold-chain infrastructure investment trajectories. Macroeconomic currency volatility, regulatory pathway modification, or technological disruption in glucose monitoring integration would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Urban Pharma Micro-Depot and Delivery Network Market
Pharmaceuticals
Global Orphan Drugs Market
Pharmaceuticals
RNA-Targeted Small Molecules Market
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Neurological Disorder Drugs Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
Multiple System Atrophy (MSA) Therapeutics Market
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
South Korea Human Papillomavirus Vaccine Market
Pharmaceuticals
Minocycline Hydrochloride Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Global Bacterial Vaccines Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Nasal Drug Delivery Market
Pharmaceuticals
Europe Adenomyosis Drugs Market
Pharmaceuticals
Leuprolide Acetate Market