
 Lidar in Construction Market | 2026-2036
Lidar in Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Lidar in Construction Market Analysis
Modular sensor-to-software bundling is realigning procurement patterns across heavy construction. Trimble Inc. leverages integrated field-to-office workflows that reduce data handoff friction for earthwork contractors. RIEGL Laser Measurement Systems GmbH anchors its position through high-pulse-rate terrestrial scanners purpose-built for structural deformation monitoring. FARO Technologies, Inc. competes on portable form factors that enable single-operator deployment on congested urban job sites.
Lidar in construction denotes active remote-sensing systems that emit pulsed laser light to generate dense three-dimensional point clouds with millimeter-scale accuracy, typically operating at near-infrared wavelengths between 905 and 1550 nanometers. These systems primarily serve volumetric measurement, as-built documentation, and geometric quality control across building and civil engineering projects. Mobile Lidar now leads equipment revenue as fleet operators outfit roadwork and rail contractors with vehicle-mounted arrays for corridor mapping at highway speeds. Ground-Based Lidar retains the deepest margin pools in heritage conservation and forensic structural analysis, where scan-to-BIM deliverables command premium service fees. Cloud-Based delivery models are displacing on-premises installations among mid-tier engineering firms seeking to avoid capital-intensive point-cloud processing infrastructure.
The Federal Aviation Administration governs aerial Lidar deployment altitudes and flight corridor clearances over populated areas, directly constraining service-provider operating economics and insurance requirements. OSHA site-safety protocols increasingly reference pre-construction topographic baselines as documented evidence for trench and excavation hazard planning, embedding Lidar-derived surveys into liability frameworks. Stakeholders must now decide whether to build captive point-cloud analytics competencies or accept vendor lock-in through subscription-based processing platforms that bundle proprietary classification algorithms.
Market Dynamics
Digital twin mandates embedded in German and Japanese building codes are forcing accelerated instrument replacement cycles among civil infrastructure contractors, compressing traditional five-year procurement horizons into eighteen-month refresh windows.
Growth Catalysts
- Building code digitization:Germany's digital twin requirements and Japan's smart infrastructure standards now mandate as-built documentation in native point-cloud formats, eliminating legacy survey methods.
- Federal infrastructure spending:United States appropriations flow directly into state-level surveying modernization programs, prioritizing corridor mapping for highway and rail rehabilitation.
- Mobile Lidar arrays:Vehicle-mounted systems operating at highway speeds enable continuous data capture without traffic closure penalties, reshaping roadwork contractor economics.
Market Restraints
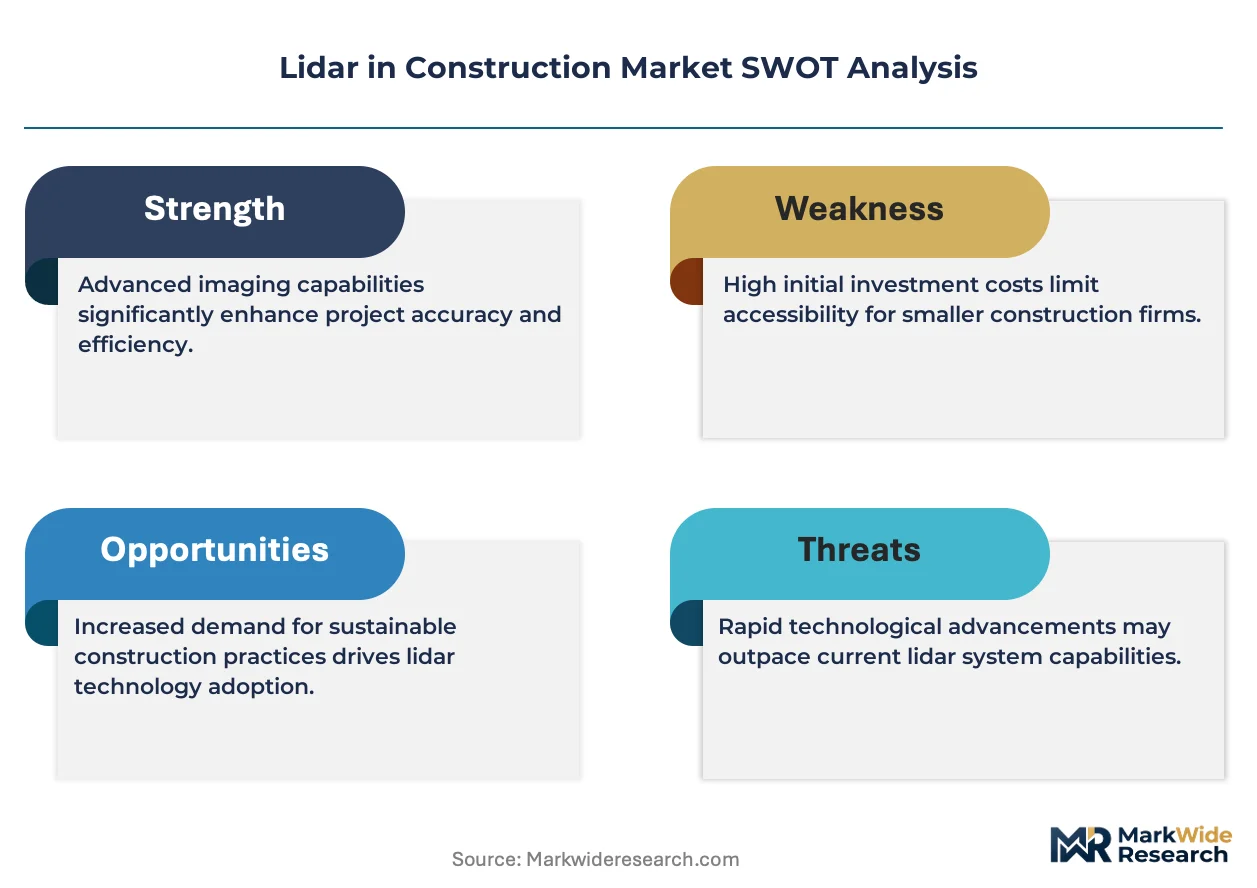
- Detector component concentration:Avalanche photodiode and SPAD array manufacturing concentrates in East Asian foundries, exposing equipment makers to single-source supply risk.
- 1550-nanometer laser cost structure:Eye-safe wavelength sources require indium gallium arsenide substrates that trade at four to six times the cost of 905-nanometer alternatives.
- FAA operational constraints:Federal Aviation Administration altitude restrictions and flight corridor clearances over populated areas constrain aerial service-provider operating economics and insurance requirements.
Strategic Opportunities
- Cloud-based processing platforms:Mid-tier engineering firms seek to avoid capital-intensive point-cloud infrastructure, creating subscription revenue pools for analytics vendors.
- Heritage conservation applications:Scan-to-BIM deliverables for forensic structural analysis command premium service fees with limited price sensitivity.
- OSHA liability embedding:Site-safety protocols increasingly reference pre-construction topographic baselines as documented evidence for trench and excavation hazard planning.
Industry Challenges
- Point-cloud analytics talent scarcity:Geomatics engineers with native classification algorithm development skills command compensation premiums that strain mid-tier firm margins.
- Vendor lock-in risk:Subscription-based processing platforms bundle proprietary classification algorithms, forcing buyers to choose between captive competency investment and platform dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lidar in Construction Market |
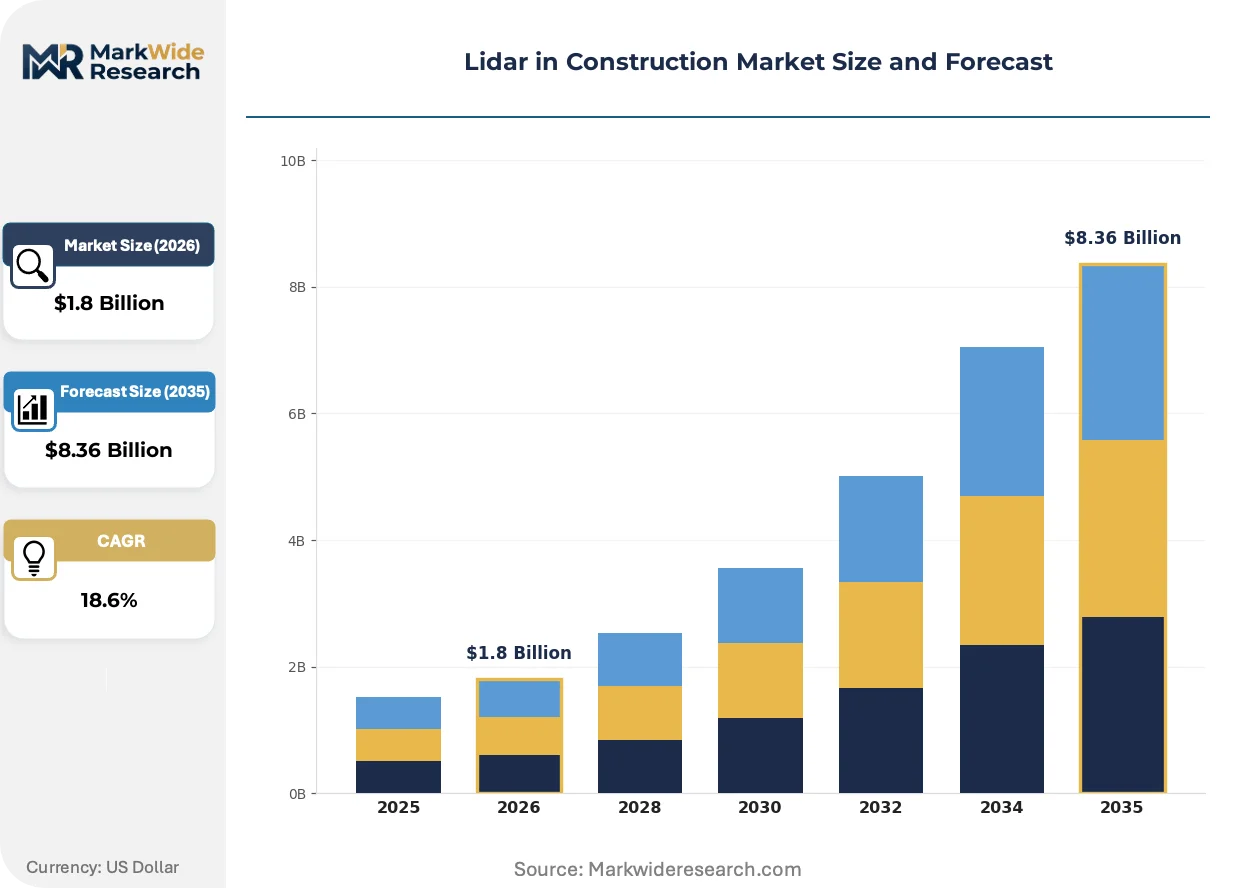
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Lidar, Aerial Lidar, Ground-Based Lidar, Static Lidar Application: Site Surveying, 3D Mapping, Asset Management, Progress Monitoring Delivery Model: Cloud-Based, On-Premises, Hybrid, Software-as-a-Service End User: Contractors, Engineers, Architects, Project Managers |
| Companies Covered | FARO Technologies, Inc., Trimble Inc., Hexagon AB, Teledyne Technologies, RIEGL Laser Measurement Systems GmbH, Sick AG, Leica Geosystems, Topcon Positioning Systems, Inc., GeoSLAM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lidar in Construction Market Emerging Trajectories
Sensor-to-software bundling is collapsing traditional procurement boundaries between hardware vendors and analytics providers, with workflow integration rather than raw specifications now determining competitive outcomes.
Photonic integration is overtaking discrete component architectures in next-generation solid-state Lidar. Silicon photonics platforms combine laser sources, beam steering, and detection arrays on single substrates. Automotive-tier suppliers now drive volume scaling that construction equipment makers leverage for cost reduction. This convergence is overtaking mechanical scanning systems in price-sensitive mobile mapping deployments.
OSHA site-safety protocols now embed Lidar-derived topographic baselines into liability frameworks for trench and excavation hazard planning. Pre-construction surveys serve as documented evidence in accident litigation, elevating survey accuracy from operational convenience to legal necessity. Earthwork contractors in the United States face the steepest compliance ramp as state-level adoption spreads.
Equipment-as-a-service contracting is displacing capital purchase models among mid-tier engineering firms. Monthly per-project fees replace six-figure hardware outlays, transferring obsolescence risk to vendors. This restructuring is most visible in congested urban markets where single-operator portable systems enable rapid deployment without crew scaling penalties.
Lidar in Construction Market Segmentation
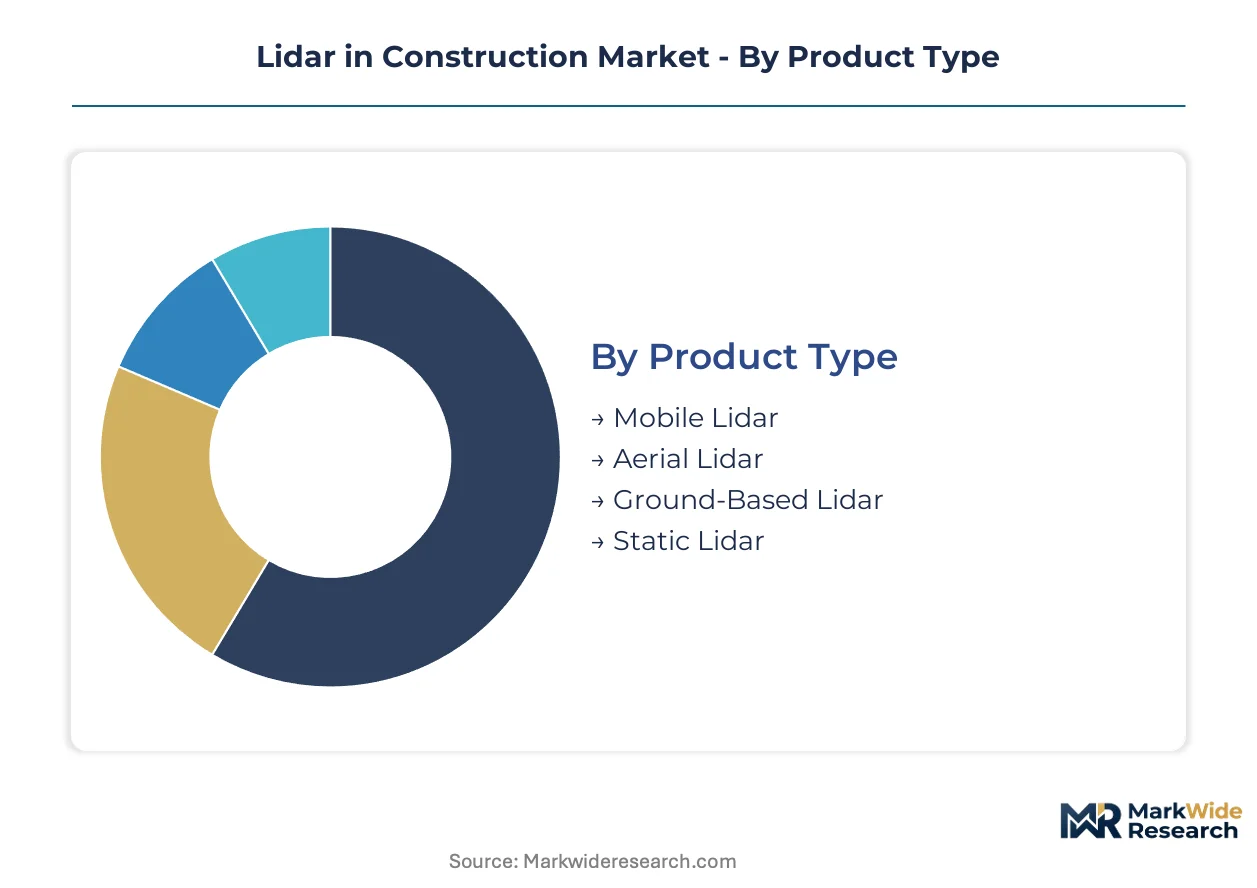
Construction Lidar procurement splits sharply between high-volume mobile deployments and premium-margin specialized systems. Understanding these fault lines reveals where vendor bundling strategies capture value and where buyer power concentrates.
Product Type:
Mobile Lidar dominates unit shipments while Ground-Based systems command the steepest price premiums per deployment.
- Mobile Lidar:Vehicle-mounted arrays integrate solid-state photonic chips for continuous corridor capture at highway speeds. Fleet operators serving United States federal highway rehabilitation contracts drive replacement cycles as traffic closure penalties reshape contractor economics.
- Ground-Based Lidar:Tripod-mounted terrestrial scanners achieve millimeter-scale precision for structural deformation monitoring. Heritage conservation mandates in Germany and Japan sustain premium pricing for scan-to-BIM deliverables with limited price sensitivity.
- Aerial Lidar:Manned and unmanned aircraft payloads governed by FAA altitude restrictions over populated areas.
- Static Lidar:Fixed-position installations for controlled-environment metrology and quality assurance.
Today's leader: Mobile Lidar. Tomorrow's challenger: Ground-Based Lidar.
Application:
Site Surveying anchors current revenue while Progress Monitoring applications expand most quickly through subscription-based delivery models.
- Site Surveying:Pre-construction topographic baselines now serve as documented evidence under OSHA trench and excavation hazard protocols. Earthwork contractors in the United States face compliance ramps as state-level adoption spreads.
- Progress Monitoring:Temporal point-cloud differencing tracks earthwork volumes and structural advancement against schedule. Mid-tier engineering firms favor cloud-based processing to avoid capital-intensive infrastructure investments.
- 3D Mapping:Corridor and facility documentation for as-built verification and digital twin population.
- Asset Management:Lifecycle condition assessment for infrastructure owners and facility operators.
Site Surveying captures the deepest regulatory embedding. Progress Monitoring offers the steepest expansion trajectory.
Delivery Model:
Cloud-Based platforms are displacing capital purchases among price-sensitive mid-tier buyers while Hybrid architectures serve security-conscious infrastructure owners.
- Cloud-Based:Subscription processing eliminates on-premises point-cloud infrastructure. Engineering firms in congested urban markets favor per-project fees over six-figure hardware outlays.
- Software-as-a-Service:Bundled analytics platforms with proprietary classification algorithms create vendor lock-in risks. Buyers must choose between captive competency investment and platform dependency.
- On-Premises:Local data sovereignty for classified infrastructure and defense-adjacent projects.
- Hybrid:Edge preprocessing with cloud analytics for bandwidth-constrained deployments.
Cloud-Based delivery is gaining share fastest. Hybrid models retain the highest retention among infrastructure owners.
End User:
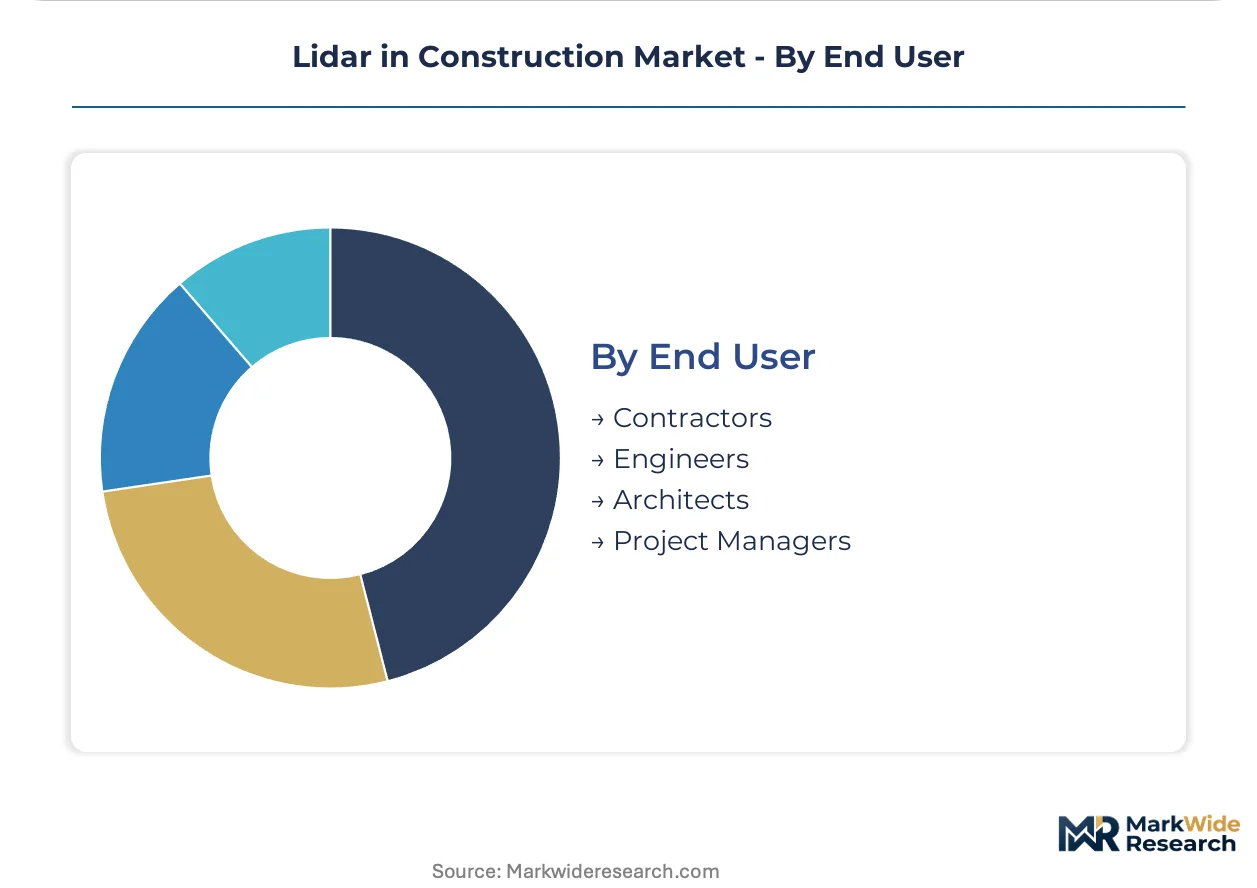
Contractors drive equipment procurement volume while Engineers control specification standards that determine vendor selection.
- Contractors:Civil infrastructure and earthwork specialists face compressed eighteen-month instrument refresh cycles under German and Japanese digital twin mandates. Mobile Lidar arrays reduce crew scaling penalties on congested urban job sites.
- Engineers:Geomatics specialists with native classification algorithm development skills command compensation premiums. Talent scarcity strains mid-tier firm margins and pushes outsourcing to subscription platforms.
- Architects:Heritage and forensic applications requiring portable single-operator deployment.
- Project Managers:Progress verification and schedule compliance through temporal point-cloud comparison.
Contractors represent the fastest-expanding buyer segment. Engineers control the technical specifications that determine competitive outcomes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lidar-enabled construction surveying originated in Central European precision engineering traditions before scaling through North American federal infrastructure programs. Geographic demand patterns now reflect regulatory embedding depth rather than raw construction volume.
United States
Federal highway rehabilitation appropriations channel directly into state-level surveying modernization programs. FAA altitude restrictions and flight corridor clearances constrain aerial service-provider operating economics over populated areas. Texas and California corridor mapping contractors deploy vehicle-mounted mobile arrays to avoid traffic closure penalties.
Germany
Digital twin mandates embedded in national building codes compress traditional five-year instrument procurement horizons into eighteen-month refresh cycles. KBA and federal construction standards enforce as-built documentation in native point-cloud formats. Bavarian civil infrastructure contractors lead replacement velocity among European buyers.
Japan
Smart infrastructure standards from METI mandate point-cloud-native documentation for public works projects. JIS certification requirements for surveying instrumentation sustain premium pricing for precision equipment. Tokyo-Osaka corridor rail contractors drive mobile Lidar fleet outfitting for continuous capture.
China
Dual carbon goals and MIIT smart city directives accelerate digital twin adoption across provincial infrastructure bureaus. GB standards for construction surveying increasingly reference three-dimensional point-cloud deliverables. Yangtze River Delta megacity clusters concentrate equipment procurement for rail and highway digitization.
United Arab Emirates
NEOM and giga-project construction timelines demand millimeter-scale as-built verification for foreign contractor compliance. MOHAP-adjacent safety protocols reference pre-construction topographic baselines for excavation hazard planning. Dubai-based engineering consultancies specify portable single-operator systems for congested urban deployment.
Lidar in Construction Market Vendor Landscape
Premium-margin players sit above commodity-margin players across workflow integration depth and pulse-rate specification tiers. Market structure tilts toward consolidated instrument manufacturing with fragmented analytics service layers. Three archetypes dominate: integrated field-to-office workflow bundlers, high-specification terrestrial scanner specialists, and portable form-factor enablers. Dominant competitive moves include sensor-to-software bundling and photonic integration partnerships with automotive-tier suppliers.
Within the premium terrestrial scanner tier, RIEGL Laser Measurement Systems GmbH and FARO Technologies, Inc. exemplify divergent specialization vectors. RIEGL anchors high-pulse-rate structural monitoring applications through its GmbH structure. FARO occupies a position emphasizing portable deployment economics for congested urban environments. Trimble Inc. represents the integrated workflow archetype, leveraging field-to-office bundling to reduce data handoff friction. Hexagon AB and Teledyne Technologies sit within diversified measurement technology conglomerates where construction Lidar represents one vertical among several industrial applications.
| Leading Market Players |
|---|
| FARO Technologies, Inc. |
| Trimble Inc. |
| Hexagon AB |
| Teledyne Technologies |
| RIEGL Laser Measurement Systems GmbH |
| Sick AG |
| Leica Geosystems |
| Topcon Positioning Systems, Inc. |
| GeoSLAM |
| Others |
Supply Flow & Price Mechanics
Silicon photonics integration is collapsing discrete component cost structures while simultaneously redistributing manufacturing concentration toward automotive-tier foundries in Taiwan and South Korea. This dual transformation compresses scanner bill-of-materials by eliminating mechanical steering assemblies, yet concentrates detector and laser source supply among a handful of East Asian substrate suppliers.
Pricing Analysis
Equipment-as-a-service contracting now dominates mid-tier procurement, replacing six-figure capital outlays with monthly per-project fees that transfer obsolescence risk to vendors. Price differentiation rests on pulse-rate specification tiers and bundled analytics depth, with heritage conservation applications showing limited price sensitivity against highway-speed mobile arrays facing acute cost compression. Pricing pressure stems from automotive photonics volume scaling that construction equipment makers leverage for cost reduction. Earthwork contractors exhibit the steepest price sensitivity, while forensic structural analysis commands premium positioning.
Supply Chain Analysis
Freight costs for precision terrestrial scanners from Austria and Germany to United States federal contractors add 8-12% to landed equipment costs, compressing vendor margins on cross-Atlantic deliveries. Component manufacturing concentrates in Taiwan, South Korea, and Japan, where avalanche photodiode and SPAD array fabrication draws from indium gallium arsenide substrate supplies. Single-source vulnerability in 1550-nanometer laser sources exposes equipment makers to foundry allocation decisions. Distribution runs through authorized dealer networks serving state-level surveying modernization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where German and Japanese digital twin mandates are forcing specification upgrades toward millimeter-precision terrestrial systems. Premium-margin players capture value through workflow integration rather than raw hardware specifications.
For Market Incumbents: To counter photonic integration cost compression from automotive-tier suppliers, deepen captive point-cloud analytics competencies to reduce subscription-platform dependency. Anchor positioning through high-pulse-rate structural monitoring specifications that resist commoditization. Prioritize certification investment for FAA operational clearances that constrain aerial service-provider competition. For New Entrants and Emerging Players: Solid-state beam steering without mechanical assemblies offers entry into price-sensitive mobile mapping deployments where incumbent mechanical systems face displacement. White-space concentrates in cloud-based processing platforms for mid-tier engineering firms seeking to avoid capital-intensive infrastructure. Target heritage conservation scan-to-BIM deliverables in Germany and Japan where premium pricing endures. Lead with per-project SaaS contracting to bypass incumbent dealer networks. For Investors and Strategic Acquirers: Valuations sit cheapest among equipment-as-a-service platform operators with recurring revenue visibility and embedded analytics workflows. Long-term viability favors vendors controlling proprietary classification algorithms that create switching costs. Acquisition targets should demonstrate FAA operational certifications or KBA compliance pathways. Watch for inflection when OSHA site-safety protocol adoption spreads beyond Texas and California to additional state jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integration Partnership | Automotive-tier silicon photonics sourcing reduces scanner bill-of-materials for mobile arrays. |
| Cloud-Based Analytics Platform Launch | Subscription processing captures mid-tier engineering firms avoiding capital infrastructure. |
| FAA Operational Certification Investment | Altitude clearance approvals constrain aerial service-provider competition over populated areas. |
| Heritage Conservation Service Expansion | Scan-to-BIM deliverables in Germany and Japan command premium fees with limited price sensitivity. |
| Equipment-as-a-Service Contracting Rollout | Monthly per-project fees displace capital purchases among price-sensitive earthwork contractors. |
Methodological Framework
Multiple input streams — primary interviews with geomatics engineers, equipment procurement leads at civil infrastructure contractors, and FAA-certified aerial survey operators — were reconciled against secondary validation from SEC filings of listed measurement technology vendors, German KBA building code documentation, and METI smart infrastructure standards. Bottom-up equipment shipment estimates triangulated against top-down federal infrastructure appropriation flows.
Historical replacement cycle patterns cross-referenced against panel input from Bavarian civil infrastructure contractors and Tokyo-Osaka rail operators informed the analytical framework. Segmentation dimensions modeled include product type, application, delivery model, and end-user archetype across the projection horizon. CAGRs derived from instrument refresh velocity under digital twin mandates and photonics cost curve trajectories. Industry-specific inputs incorporated OSHA protocol adoption timelines and FAA flight corridor restriction evolution.
The model holds under sustained federal infrastructure spending and continued German-Japanese regulatory embedding; deviation in automotive photonics allocation or East Asian foundry disruption would shift equipment availability and pricing trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Mobile Lidar Scanner Market
Sensors
Yield Monitoring Systems Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Asset Tags Market
Sensors
Global Energy Harvesting System for Wireless Sensor Network Market
Sensors
Underground Utility Mapping Market
Sensors
Active Noise and Vibration Control (ANVC) Systems Market
Sensors
Europe Lidar Market
Sensors
Handheld GPS Units Market
Sensors
Bluetooth Photo Capture Device Market
Sensors
Indoor Air Quality Monitor Market
Sensors
Cloud Camera Market
Sensors
Global Position Tracking System Market
Sensors
Vibration Monitoring Market
Sensors
NB-IoT Smart Gas Meter Market
Sensors
Mobile Mapping Systems Market