
 Cloud Camera Market | 2026-2036
Cloud Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Camera Market Outlook
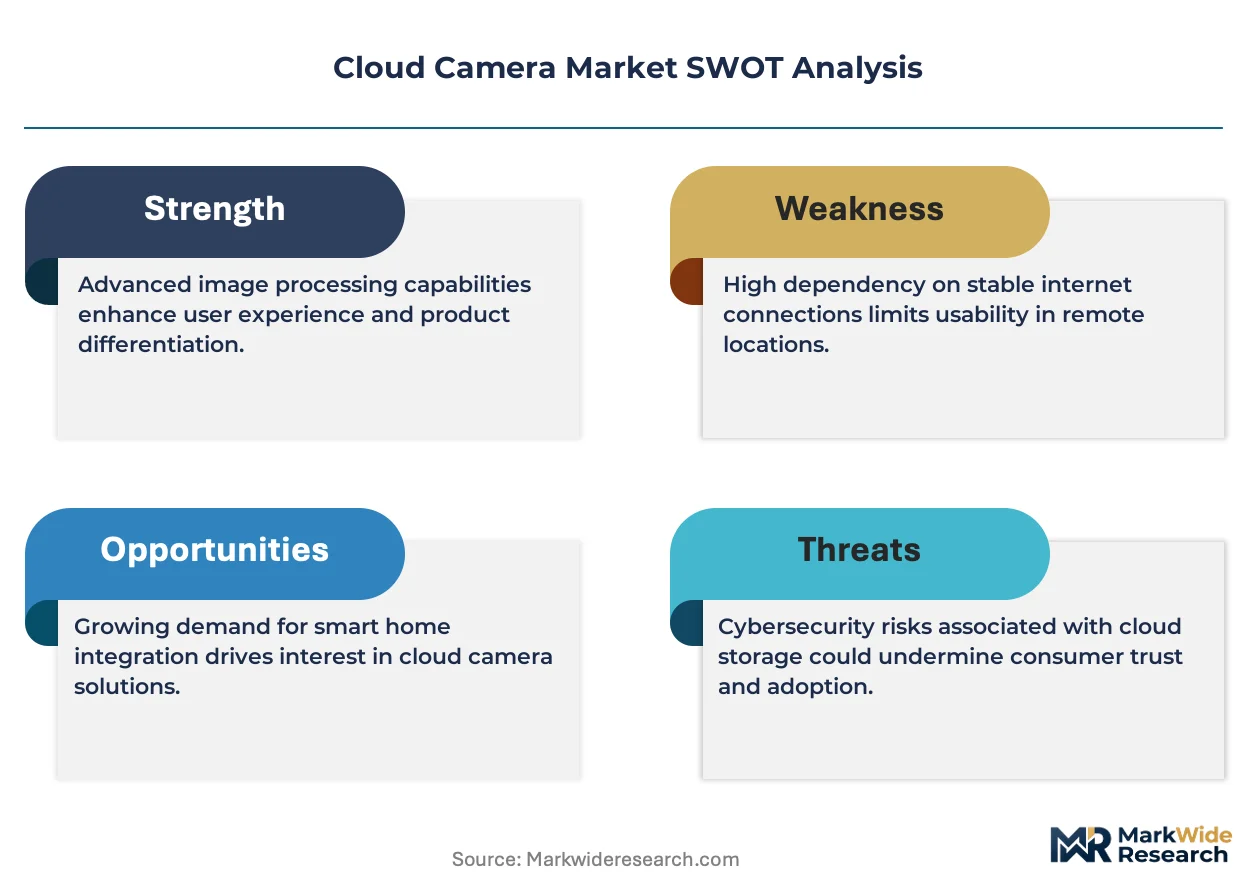
GDPR's biometric data provisions is hardening compliance costs for cloud camera vendors serving European enterprise clients. Hikvision leverages its vertically integrated sensor manufacturing to sustain price competitiveness in the IP camera tier. Axis Communications specializes in open-platform software architectures that differentiate its offerings for system integrators.
Cloud cameras are network-connected imaging devices that stream, store, and analyze video data through remote server infrastructure rather than local digital video recorders, typically operating at resolutions from 1080p to 4K with H.265 compression and edge-based motion detection algorithms. Their primary commercial purpose is to enable centralized security monitoring, operational analytics, and real-time alerting without on-site storage hardware. Indoor cameras occupy the highest volume tier in residential channels, while PTZ cameras capture expanding margin pools in commercial installations requiring active remote steering. Government end users represent the most structurally concentrated procurement segment, with municipal and federal contracts often bundling cloud storage subscriptions into multi-year service agreements.
The EU AI Act and GDPR jointly constrain facial recognition deployments in public spaces, redirecting vendor R&D toward anonymized behavioral analytics and edge-based processing that minimizes personal data transmission. In the United States, FCC equipment authorization requirements and state-level biometric privacy laws in Illinois and Texas fragment compliance obligations across jurisdictions. Stakeholders must monitor whether emerging national AI governance frameworks will classify cloud camera analytics as high-risk applications, potentially triggering third-party conformity assessments and reshaping competitive positioning among vendors with differential certification readiness.
Market Dynamics
Edge AI processing architectures are displacing centralized cloud analytics as GDPR and the EU AI Act impose strict limits on biometric data transmission, forcing vendors to relocate inference workloads to camera hardware.
Growth Catalysts
- Smart city infrastructure mandates:Southeast Asian municipal governments are bundling cloud-connected surveillance into urban digitization contracts, creating sustained procurement pipelines for PTZ and thermal camera systems.
- EU AI Act compliance redesign:Vendors are retooling software stacks to support anonymized behavioral analytics, opening new revenue streams in retail footfall measurement and workplace safety monitoring.
- Logistics hub centralization:India's warehousing and cold-chain operators are consolidating multi-site monitoring onto unified cloud platforms, driving demand for 4K cameras with H.265 compression.
Market Restraints
- Image sensor supply concentration:CMOS sensor fabrication concentrates in East Asian foundries, exposing camera OEMs to geopolitical trade friction and capacity allocation disruptions.
- Biometric privacy law fragmentation:Illinois BIPA and Texas biometric statutes impose conflicting consent and retention requirements, complicating multi-state deployment strategies for US enterprise clients.
- On-premise DVR substitution:Hybrid edge-recorder systems retain cost advantages for small commercial sites with limited IT infrastructure, slowing pure-cloud adoption in the long-tail segment.
Strategic Opportunities
- India commercial security underpenetration:Organized retail and last-mile logistics networks remain under-monitored relative to global benchmarks, creating expansion room for subscription-based cloud monitoring services.
- 5G-enabled mobile surveillance:Convergence of cellular low-latency connectivity and battery-efficient edge processors is unlocking temporary deployment scenarios for construction and event security.
- EU CSRD reporting alignment:Corporate sustainability disclosure requirements are incentivizing cloud camera deployments for ESG-compliant facility monitoring and supply chain transparency documentation.
Industry Challenges
- Edge-AI firmware integration complexity:Camera vendors face prolonged validation cycles when embedding third-party inference engines, delaying product launches and stretching R&D budgets.
- Multi-jurisdiction certification timelines:FCC equipment authorization, CE marking, and BIS safety approvals operate on non-harmonized schedules, complicating synchronized global rollouts.
- Legacy analog infrastructure interoperability:Enterprises with installed coaxial cabling resist full rip-and-replace upgrades, forcing vendors to support hybrid signal-conversion architectures that dilute margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Camera Market |
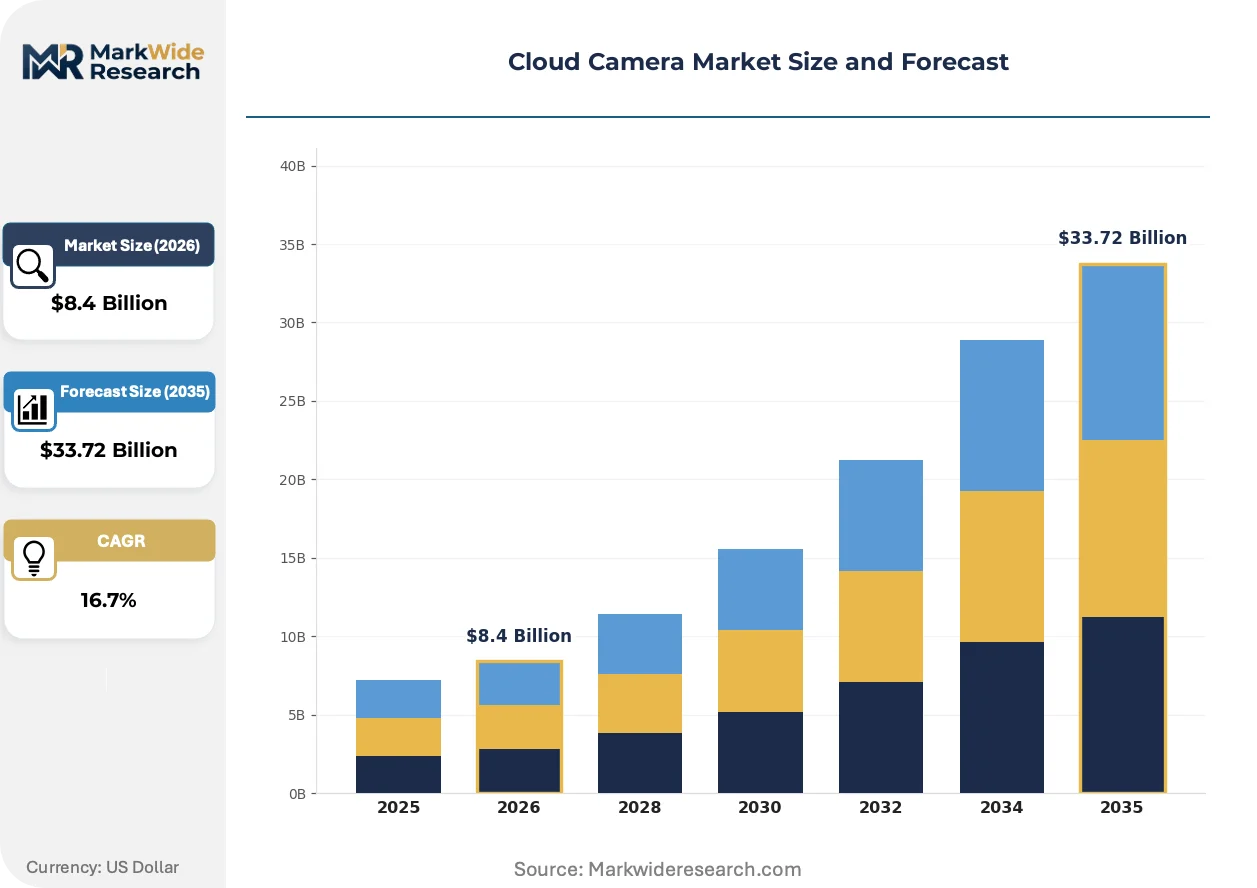
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $33.72 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Cameras, Outdoor Cameras, PTZ Cameras, Action Cameras Technology: IP Cameras, Wi-Fi Cameras, PoE Cameras, 4G Cameras End User: Residential, Commercial, Industrial, Government Installation Type: Ceiling Mount, Wall Mount, Desktop, Integrated |
| Companies Covered | Amazon, Hikvision, Arlo Technologies, Google, Dahua Technology, Axis Communications, Honeywell International, Nest Labs, ADT Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Camera Market Strategic Shifts
On-device inference chips are redistributing computational workloads away from centralized servers, while regulatory pressure on biometric surveillance accelerates anonymization-first design philosophies.
Edge-based neural processing units are expanding into mainstream IP camera designs, enabling real-time object classification and anomaly detection without transmitting raw video streams. Logistics operators and smart city integrators are adopting these systems fastest, prioritizing bandwidth efficiency over legacy cloud-only architectures. This silicon migration is expanding into premium residential and mid-market commercial tiers, compressing the addressable market for pure-cloud analytics providers.
The EU AI Act's biometric surveillance restrictions are forcing architectural pivots toward privacy-preserving computer vision. Vendors now design cameras that process facial data into non-reversible feature vectors at the edge, transmitting only anonymized behavioral metadata. European public-sector procurement contracts increasingly mandate such designs, while vendors serving US federal and state agencies face pressure to demonstrate comparable data-minimization capabilities.
Subscription-based monitoring services are displacing capital-intensive hardware purchases in the small-business segment. Security integrators and telecom carriers now bundle cloud storage, AI analytics, and maintenance into monthly per-camera fees. This preference shift is most visible in India's tier-2 retail chains and Southeast Asian hospitality operators, where IT capital constraints favor operational expenditure models over upfront equipment investment.
Cloud Camera Market Segmentation
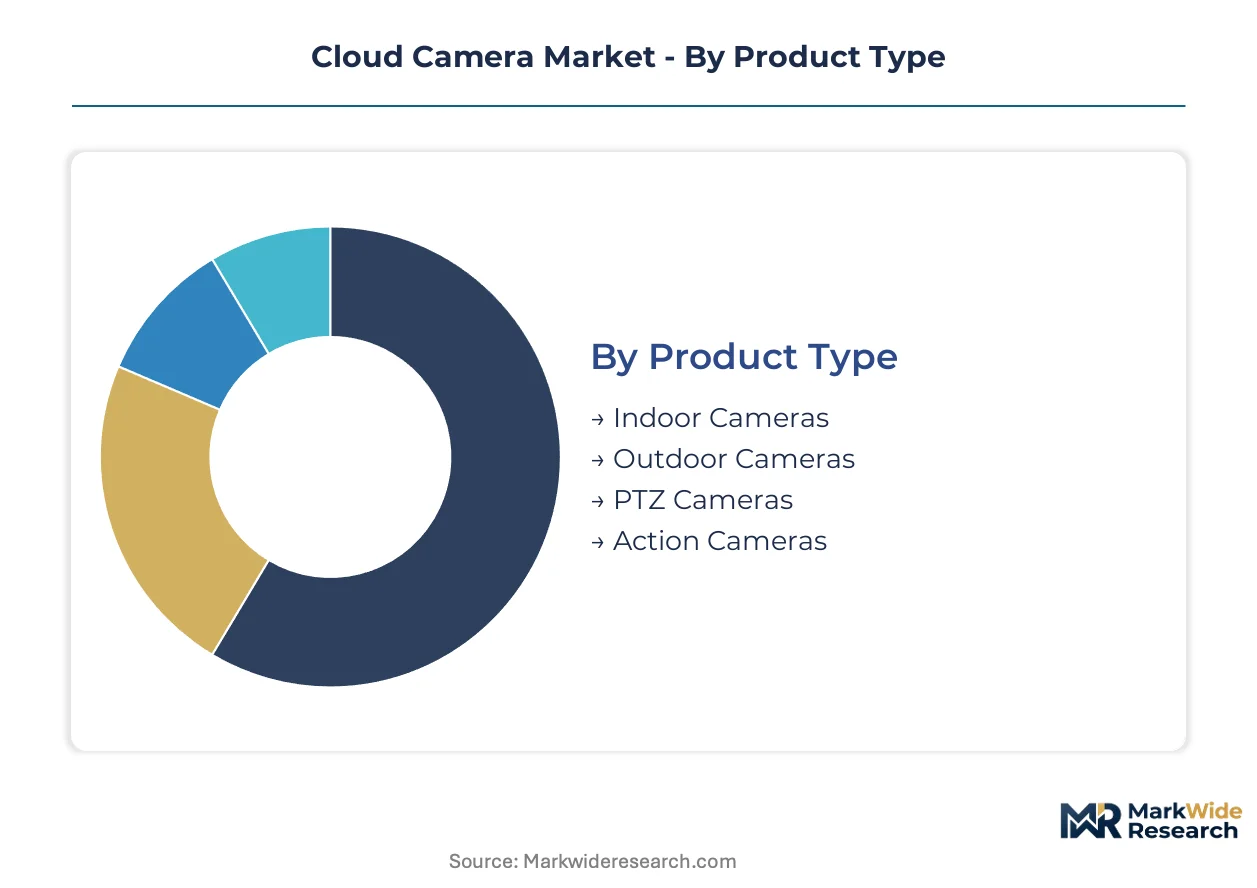
Cloud camera segmentation reveals how hardware specifications, connectivity protocols, and deployment contexts reshape procurement priorities across security ecosystems. Distinct technical architectures serve divergent bandwidth constraints, power availability, and regulatory exposure.
Product Type:
Resolution tiers and environmental sealing ratings differentiate hardware portfolios across residential and enterprise channels.
- Indoor Cameras:Fixed-lens designs with 1080p to 4K sensors and H.265 compression dominate residential subscriptions and retail loss-prevention deployments. India's tier-2 retail chains favor these for centralized monitoring over upfront DVR investment.
- Outdoor Cameras:Weather-sealed enclosures with IP66+ ratings and infrared night-vision arrays serve perimeter security for logistics hubs and municipal smart city contracts across Southeast Asia.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms with optical zoom lenses capture premium margins in commercial installations requiring active remote steering.
- Action Cameras:Ruggedized, battery-powered units with wide-angle lenses address temporary construction and event security scenarios where permanent infrastructure is impractical.
Indoor cameras lead on scale; PTZ cameras lead on momentum.
Technology:
Connectivity protocols determine installation complexity, bandwidth consumption, and edge-processing feasibility.
- IP Cameras:Ethernet-based devices with dedicated network infrastructure support high-bitrate 4K streaming and centralized VMS integration in enterprise security operations.
- Wi-Fi Cameras:Wireless 802.11ac/ax connectivity reduces cabling costs for residential and small-commercial retrofits, though signal interference limits density in concrete structures.
- PoE Cameras:Power-over-Ethernet single-cable deployment simplifies installation for commercial integrators managing multi-site rollouts with unified switch infrastructure.
- 4G Cameras:Cellular-connected units with embedded SIM slots unlock remote and mobile surveillance for construction sites and temporary event security where fixed broadband is unavailable.
IP cameras anchor enterprise procurement; 4G cameras are climbing the fastest on 5G infrastructure expansion.
End User:
Budget cycles, compliance obligations, and integration complexity fragment demand patterns across customer categories.
- Residential:Subscription-priced indoor cameras with smartphone app control drive volume through telecom and security service bundles, particularly in India's emerging middle-class housing developments.
- Commercial:Retail chains, hospitality operators, and office complexes prioritize cloud storage and AI analytics subscriptions over capital-intensive on-premise systems.
- Industrial:Manufacturing and warehousing facilities demand ruggedized outdoor and PTZ cameras with edge-based safety compliance monitoring and thermal anomaly detection.
- Government:Municipal and federal agencies bundle multi-year cloud storage subscriptions into procurement contracts, with EU AI Act biometric restrictions forcing edge-processing redesigns.
Residential leads on unit volume; government leads on contract value concentration.
Installation Type:
Mounting configurations reflect site constraints, aesthetic requirements, and legacy infrastructure compatibility.
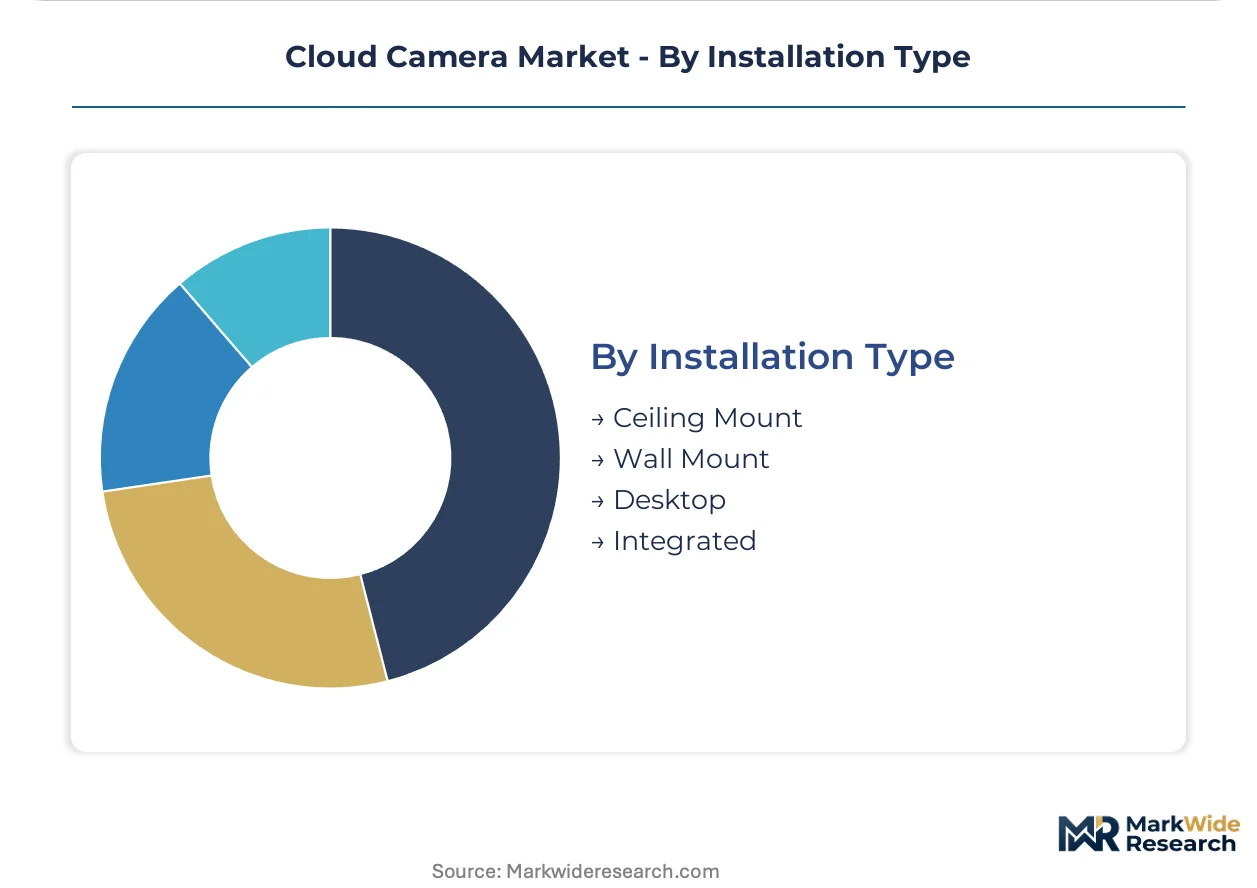
- Ceiling Mount:Recessed dome and turret designs provide 360-degree coverage with discreet positioning for retail, hospitality, and corporate lobby deployments.
- Wall Mount:Bullet-style housings with adjustable brackets optimize perimeter sightlines for outdoor industrial and logistics facility applications.
- Desktop:Freestanding units with integrated stands serve home offices and small commercial spaces lacking permanent mounting infrastructure.
- Integrated:Embedded camera modules within lighting fixtures, access control panels, or IoT sensors enable unified building management system architectures.
Ceiling mount dominates commercial fit-outs; integrated installations are gaining share fastest on smart building convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud camera manufacturing originated in East Asian electronics clusters before spreading to North American software integrators and European compliance-focused designers. Today's procurement patterns reflect this geographic lineage, with distinct regulatory and infrastructure conditions shaping regional deployment strategies.
United States
Enterprise security budgets concentrate in Illinois and Texas, where state biometric privacy statutes impose strict consent protocols for facial recognition deployments. FCC equipment authorization requirements govern all radio-frequency camera models entering commercial channels. The Dallas-Fort Worth logistics corridor drives demand for PTZ cameras with edge-based processing in warehousing applications.
Germany
Industrial facility operators in Baden-Württemberg prioritize PoE camera installations with integrated safety compliance monitoring for manufacturing floors. The EU AI Act's biometric surveillance restrictions force vendors to redesign edge-processing architectures before public-sector procurement eligibility. Munich's smart city infrastructure contracts increasingly mandate anonymized behavioral analytics over raw video transmission.
China
Domestic CMOS sensor foundries supply cost-competitive imaging components to camera OEMs serving Southeast Asian export markets. MIIT cybersecurity standards and GB certification requirements structure equipment authorization timelines for networked surveillance products. Shenzhen's electronics manufacturing ecosystem anchors global supply chains for Wi-Fi and 4G-connected camera modules.
India
Tier-2 retail chains in Maharashtra and Karnataka favor subscription-priced indoor cameras over capital-intensive DVR systems for centralized multi-site monitoring. BIS safety approvals and TRAI data localization guidelines shape vendor compliance obligations for cloud-connected deployments. The Delhi-NCR logistics hub drives procurement of 4K cameras with H.265 compression for cold-chain warehousing operations.
Singapore
Government smart city mandates accelerate procurement of thermal and PTZ camera systems for urban digitization contracts. The country's data protection authority enforces strict cross-border transfer limitations on biometric video analytics. Marina Bay's integrated building management projects demonstrate converged camera-IoT architectures for regional reference.
Cloud Camera Market Competitive Environment
The competitive structure tilts toward vertically integrated hardware specialists with captive sensor supply and open-platform software vendors serving system integrators. Market concentration splits between East Asian component-scale manufacturers and Western subscription-service bundlers. Three archetypes dominate: sensor-integrated hardware OEMs, cloud-software platform operators, and security-service integrators. Primary competitive moves include edge-AI firmware partnerships and multi-jurisdiction certification pre-positioning.
Among Chinese hardware fabricators, Hikvision and Dahua Technology exemplify the sensor-integrated archetype with upstream control over CMOS manufacturing. Axis Communications anchors the open-platform specialist tier, occupying a position that emphasizes software interoperability for European system integrators navigating GDPR and EU AI Act compliance redesigns. These three companies represent distinct strategic postures without implying specific market share or revenue figures.
| Leading Market Players |
|---|
| Amazon |
| Hikvision |
| Arlo Technologies |
| Dahua Technology |
| Axis Communications |
| Honeywell International |
| Nest Labs |
| ADT Inc. |
| Others |
Value Chain & Pricing Dynamics
Edge-AI certification tiers split the market into premium inference-enabled units and commodity streaming devices, with FCC authorization and CE marking requirements driving cost differentials that compound through CMOS sensor procurement and firmware validation cycles. This bifurcation concentrates margin capture among vendors with captive silicon supply while forcing price compression on generic IP camera assemblers dependent on merchant sensor markets.
Pricing Analysis
Bundled subscription services versus unbundled hardware transactions define the dominant pricing split, with monthly per-camera fees for cloud storage and AI analytics commanding three-year contract values that exceed upfront equipment costs. Price differentiation rests on edge-processing capability and regulatory certification tier, with GDPR-compliant edge-AI units capturing premium positioning against basic cloud-streaming alternatives. Pricing pressure stems from CMOS sensor oversupply in Chinese foundries and aggressive bundling by telecom carriers entering security monitoring. Small commercial sites in India's tier-2 cities exhibit highest price sensitivity, while government procurement in Singapore and Germany shows lowest sensitivity due to compliance mandates.
Supply Chain Analysis
Certification gating through FCC, CE marking, and BIS approvals structures supplier eligibility and extends lead times for non-integrated vendors lacking pre-certified module platforms. Manufacturing concentrates in China, Taiwan, and South Korea, with Shenzhen anchoring Wi-Fi and 4G module assembly and Hsinchu supplying advanced CMOS sensors. Raw material dependencies include silicon wafers, optical glass lenses, and rare-earth magnet components for PTZ motors. Single-source vulnerability in East Asian foundry capacity exposes OEMs to geopolitical trade friction and allocation disruptions. Distribution runs through security integrators, telecom carriers, and direct enterprise sales channels with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cloud camera market functions as a regulatory compounder where EU AI Act biometric restrictions and GDPR data localization mandates continuously reshape procurement specifications and vendor qualification requirements.
For Market Incumbents: Cement firmware differentiation through edge-AI inference partnerships that preempt compliance redesign cycles forced by emerging biometric surveillance restrictions. Deepen backward integration into CMOS sensor supply to defend margin position against merchant component price volatility. Prioritize multi-jurisdiction certification pre-positioning to capture municipal smart city contracts in Southeast Asia before qualification windows close. For New Entrants and Emerging Players: Capture India's tier-2 retail and last-mile logistics segments where subscription-priced indoor cameras face limited incumbent penetration relative to global benchmarks. Exploit 5G-enabled mobile surveillance white space in temporary construction and event security scenarios lacking fixed broadband infrastructure. Lead with telecom carrier partnership channels that bundle cloud monitoring into connectivity service packages. For Investors and Strategic Acquirers: Consolidation pressure builds where edge-AI firmware complexity stretches R&D budgets and certification timelines fragment global rollout synchronization. Long-term viability favors vendors with vertically integrated sensor supply and open-platform software architectures serving system integrator channels. Watch for EU AI Act high-risk application classification decisions as the inflection signal triggering third-party conformity assessment requirements and reshaping competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Firmware Partnership | Accelerates GDPR-compliant product qualification for European public-sector procurement contracts. |
| CMOS Sensor Backward Integration | Reduces exposure to East Asian foundry allocation disruptions and sustains price competitiveness. |
| Multi-Jurisdiction Certification Pre-Positioning | Enables synchronized global rollouts before FCC, CE marking, and BIS approval schedules diverge. |
| Telecom Carrier Channel Partnership | Unlocks subscription revenue streams in India's capital-constrained tier-2 retail segment. |
| 5G-Enabled Mobile Surveillance Development | Captures temporary deployment scenarios in construction and event security lacking fixed infrastructure. |
Study Parameters
Direct dialogue with security integrators, cloud platform engineers, municipal procurement officers, and regulatory compliance leads grounded the qualitative foundation, combined with secondary validation across FCC equipment authorization databases, EU AI Act implementation guidance, BIS safety approval registries, and TRAI data localization guidelines. Bottom-up and top-down triangulation reconciled vendor shipment disclosures with end-user deployment tracking.
Bottom-up unit economics and top-down macro segmentation anchored the analytical framework across the projection horizon. The model disaggregated demand by resolution tier, connectivity protocol, end-user category, and regional regulatory cluster. CAGRs derived from historical trajectory analysis and scenario-weighted adoption curves incorporated edge-AI silicon cost decline assumptions and 5G infrastructure deployment pacing.
Regulatory reclassification, foundry capacity shocks, and biometric privacy law fragmentation are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in EU AI Act enforcement interpretation or CMOS sensor supply concentration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Asset Tags Market
Sensors
Global Real-Time Locating Systems (RTLS) Market
Sensors
Transportation Sensors Market
Sensors
Remote Sensing Technology Market
Sensors
Body Area Network Market
Sensors
RFID Smart Cabinet Market
Sensors
IO-Link Technology Market
Sensors
Smart Barcode Readers Market
Sensors
Alcohol Sensor Market
Sensors
Lidar in Mapping Market
Sensors
Digital Olfaction Products Market
Sensors
Europe Remote Sensing Technology Market
Sensors
Global Equipment Monitoring Market
Sensors
Global Load Monitoring System (LMS) Market
Sensors
Safety Motion Control System Market
Sensors
Vibration Monitoring Market