
 Smart Mat Market | 2026-2036
Smart Mat Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Mat Market Analytics
Direct-to-consumer e-commerce channels is reconfiguring how smart mat manufacturers reach end users, bypassing traditional retail markups and accelerating purchase cycles. Amazon.com, Inc. leverages its logistics infrastructure to dominate online distribution of connected home fitness products. Samsung Electronics anchors its position through vertical integration of flexible display and sensor technologies into proprietary mat designs. Robert Bosch GmbH competes on industrial safety applications, extending its automotive sensor expertise into pressure-sensitive floor systems for manufacturing environments.
A smart mat is an instrumented floor covering incorporating pressure sensors, flexible printed circuit substrates, and wireless communication modules to detect presence, measure force distribution, or transmit biometric data to connected systems. These devices typically operate at pressure sensitivities between 0.1 and 10 N/cm² and communicate via Bluetooth Low Energy or Wi-Fi protocols to enable real-time monitoring. Fitness Mats lead product type revenue due to premium pricing of connected exercise platforms, while Monitoring Mats represent the fastest-expanding category as hospitals deploy fall-detection infrastructure for aging populations. IOT-enabled technology captures the dominant margin pool through recurring software subscription attach rates, whereas Pressure Sensors technology sustains higher unit economics in industrial safety applications where certification requirements limit supplier competition.
The EU AI Act and CE marking requirements under the EU Green Deal are reshaping product compliance costs for connected wellness devices distributed in Europe, forcing redesigns of data processing architectures. The FDA in the United States classifies certain patient-monitoring smart mats as Class II medical devices, triggering 510(k) clearance pathways that extend development timelines but create regulatory moats for approved suppliers. Stakeholders must monitor evolving cybersecurity certification mandates from ETSI and ISO as healthcare and industrial buyers increasingly require third-party validated data protection before procurement.
Market Dynamics
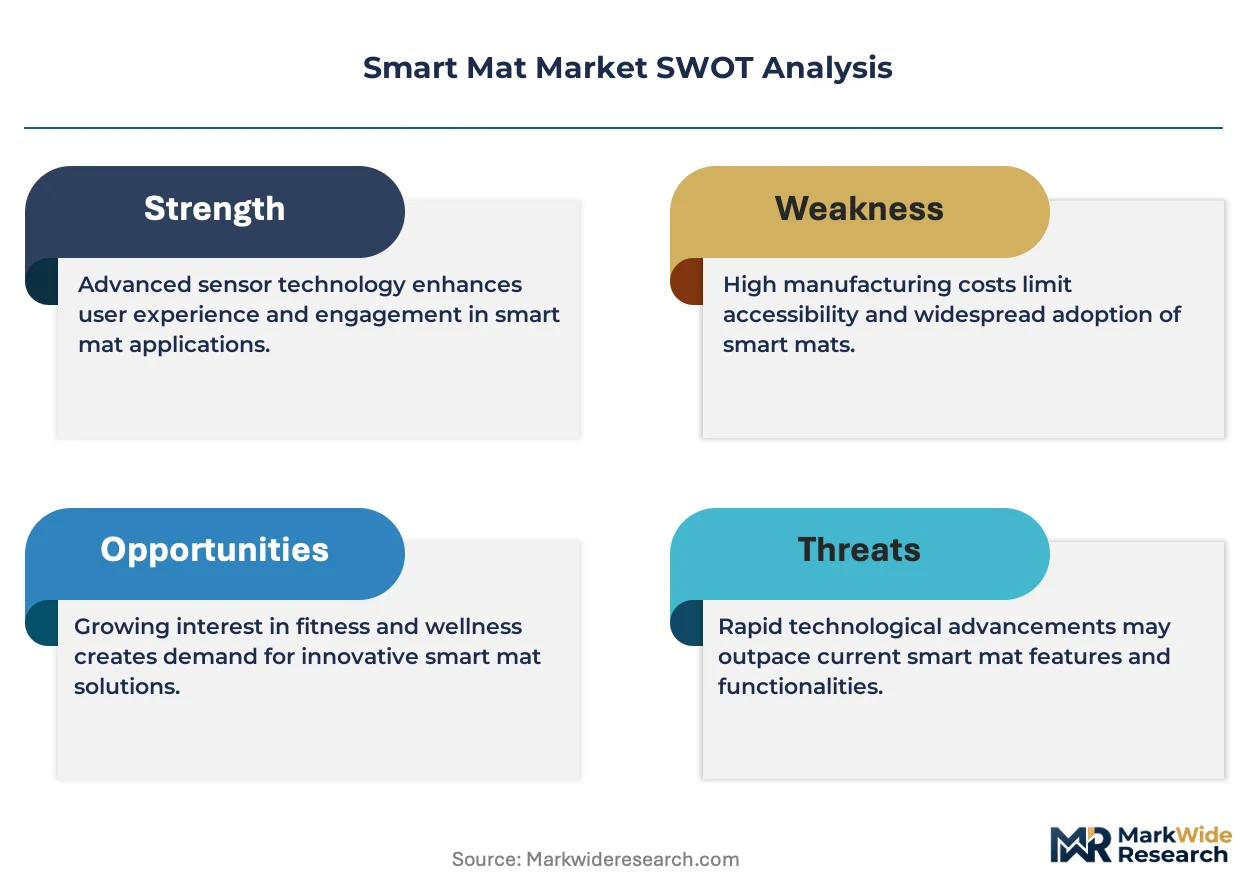
The EU AI Act's risk-classification framework for biometric data processing is forcing redesigns of connected wellness devices, while Japan's hospital procurement of pressure-sensing floor systems for elderly fall detection creates concentrated demand pull in precision healthcare infrastructure.
Growth Catalysts
- CE marking under EU Green Deal:Sustainability mandates for electronics are accelerating material substitutions toward recyclable substrates in mat manufacturing, opening compliance-driven product refresh cycles.
- Industrial safety automation:Germany's automotive and machinery sectors are deploying pressure-sensitive floor systems to reduce workplace injury liability, anchoring demand for certified industrial-grade sensors.
- Bluetooth Low Energy maturation:Power-efficient wireless protocols are enabling battery-free or energy-harvesting mat designs, reducing total cost of ownership in large-area healthcare deployments.
Market Restraints
- Flexible printed circuit substrate concentration:East Asian suppliers dominate high-durability FPC manufacturing, creating vulnerability to trade-route disruptions and input cost volatility.
- FDA 510(k) pathway friction:Class II medical device classification for patient-monitoring mats extends development timelines, compressing returns for venture-backed entrants.
- Pressure sensor calibration drift:Long-term accuracy degradation in capacitive sensing elements limits warranty terms and raises service cost burdens for institutional buyers.
Strategic Opportunities
- ETSI cybersecurity certification:Third-party validated data protection protocols are becoming a procurement gate in European healthcare, creating differentiation for early certifiers.
- Home-based rehabilitation:Post-acute care shifting to residential settings is opening demand for consumer-grade monitoring mats with clinical-grade accuracy.
- Industrial IoT convergence:Integration of smart mats with digital twin platforms for factory floor simulation represents an unpenetrated application layer.
Industry Challenges
- Embedded systems firmware talent scarcity:Shortage of engineers skilled in real-time pressure-mapping algorithms is constraining product development velocity.
- Legacy hospital IT integration:Proprietary electronic health record architectures resist seamless data ingestion from connected mat devices, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Mat Market |
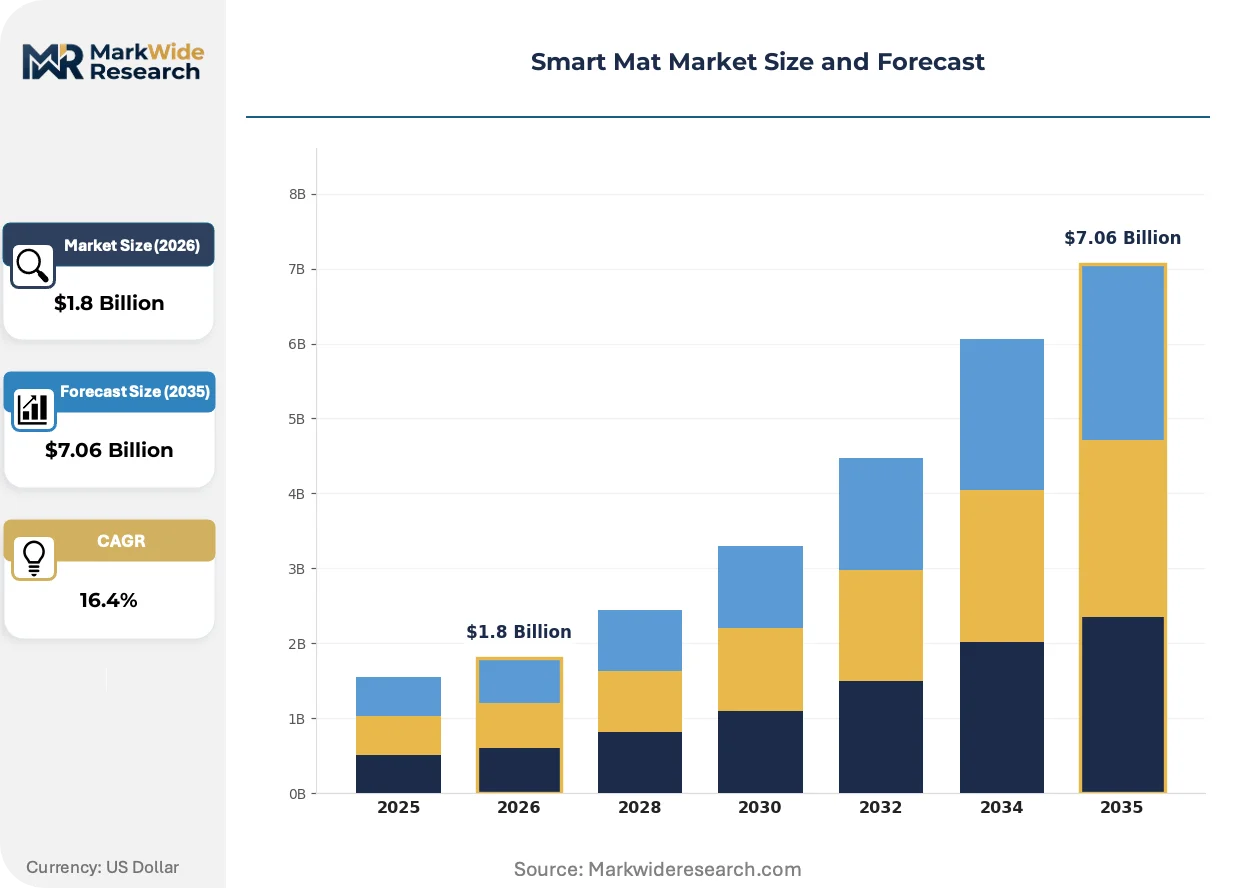
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Mats, Safety Mats, Monitoring Mats, Heating Mats Technology: IOT-enabled, Pressure Sensors, Flexible Electronics, Wireless Charging End User: Households, Gyms, Hospitals, Sports Facilities Application: Exercise Tracking, Fall Detection, Temperature Control, Weight Measurement |
| Companies Covered | Samsung Electronics, LG Electronics, Amazon.com, Inc., Apple Inc., Honeywell International Inc., Schneider Electric, Johnson Controls Inc., Robert Bosch GmbH, ABB Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Mat Market Evolving Landscape
Sensor fusion architectures and edge-computing capabilities are compressing latency in biometric detection, while regulatory pressure on data sovereignty is reshaping where processing occurs within smart mat networks.
Capacitive pressure sensing arrays with spatial resolution below 5 mm are migrating from laboratory prototyping into commercial fitness and physical therapy mats. Boutique studios and sports medicine clinics in North America are adopting these high-definition platforms for movement analytics. This precision tier is compressing the addressable market for legacy force-plate systems priced at multiples of integrated mat solutions.
The EU AI Act's prohibition on real-time biometric identification in public spaces is reshaping data-processing architectures for wellness devices distributed in Europe. Manufacturers are relocating inference engines to on-mat edge processors to avoid cloud transmission of raw pressure imagery. Hospital procurement committees in Germany and France are now requiring documented AI Act conformity assessments before contract award.
Direct institutional procurement bypassing medical device distributors is consolidating buyer power among large health systems and industrial facility operators. Group purchasing organizations in the United States are unbundling smart mats from broader fall-prevention bundles, enabling price discovery at the SKU level. This disintermediation is most visible in Japan's hospital network consolidations, where centralized procurement offices negotiate sensor-lifetime service agreements directly with manufacturers.
Smart Mat Market Segmentation
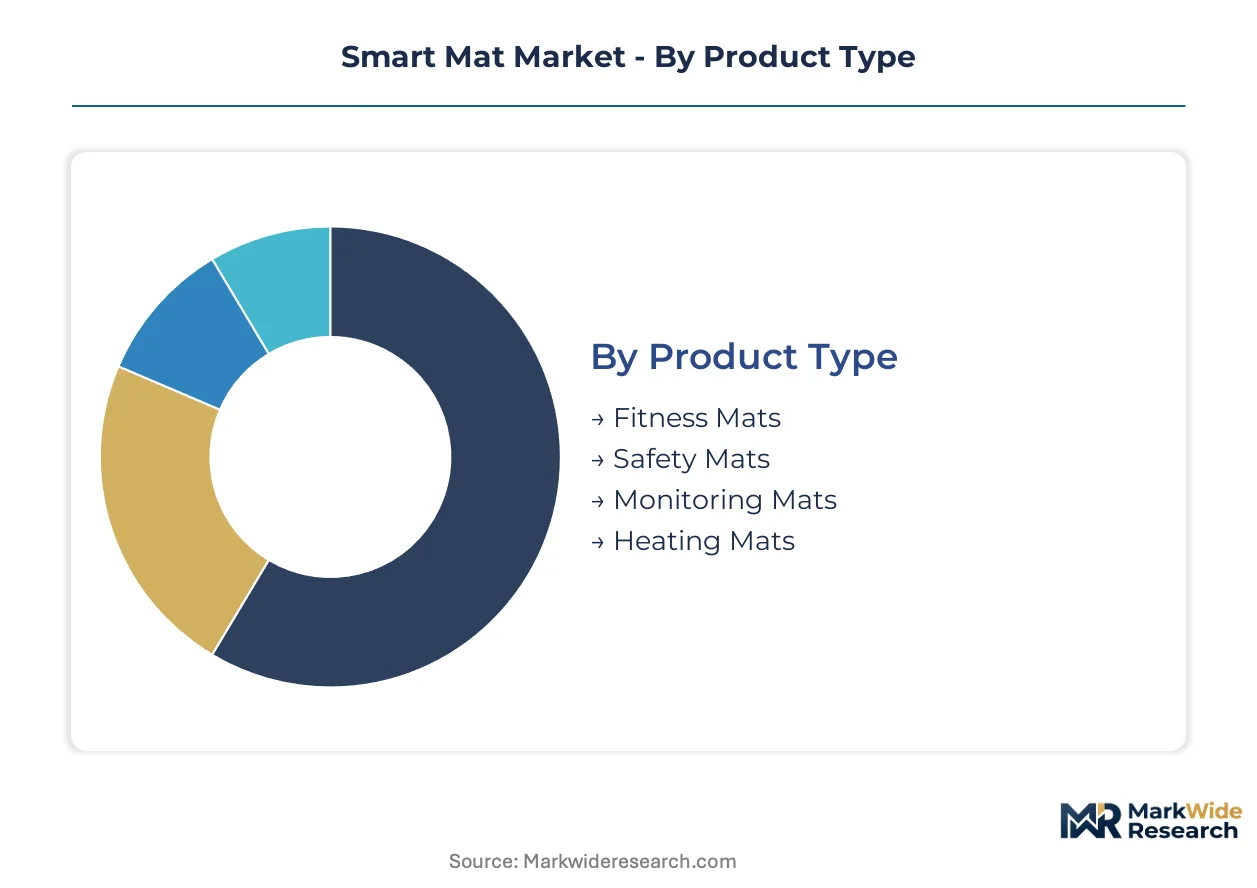
Smart mat segmentation reveals divergent margin structures across wellness, industrial safety, and clinical monitoring applications. Manufacturers configure sensor density, connectivity protocols, and certification tiers to match the price sensitivity and performance requirements of distinct buyer constituencies.
Product Type:
Mature categories dominate revenue capture while emerging formats reshape competitive positioning through novel use cases.
- Fitness Mats:Instrumented exercise platforms integrate capacitive pressure arrays with Bluetooth Low Energy modules to transmit force distribution data to companion applications. Boutique studios in Germany and North American sports medicine clinics drive premium pricing for high-definition movement analytics platforms.
- Monitoring Mats:Fall-detection floor systems deploy piezoelectric or capacitive sensors beneath surface materials to identify gait anomalies and trigger alerts. Japanese hospitals are expanding procurement of these systems for elderly patient wards, creating concentrated demand pull in precision healthcare infrastructure.
- Safety Mats:Industrial-grade pressure-sensitive floor coverings certified to machinery safety standards protect workers in automated manufacturing environments. Germany's automotive sector anchors deployment volume.
- Heating Mats:Thermostatically controlled floor warming systems with basic occupancy sensing target residential bathroom and kitchen renovations.
Fitness Mats handle the majority of throughput; Monitoring Mats is the fastest mover on share.
Technology:
Cost tier separation between subscription-enabled platforms and hardware-only systems determines vendor profitability and customer lifetime value.
- IOT-enabled:Cloud-connected architectures with embedded firmware for real-time data transmission and software subscription attach rates. Recurring revenue models concentrate in consumer fitness and clinical monitoring segments where data analytics justify ongoing fees.
- Pressure Sensors:Discrete capacitive or piezoelectric sensing elements calibrated for force measurement accuracy. Industrial safety applications in Germany's machinery sector sustain higher unit economics where CE marking and functional safety certification limit supplier competition.
- Flexible Electronics:Printed circuit substrates and conductive traces manufactured on polymer films for conformal surface integration. East Asian suppliers dominate high-durability FPC manufacturing.
- Wireless Charging:Inductive power transfer coils embedded within mat structures to eliminate battery replacement cycles in healthcare deployments.
IOT-enabled technology commands the dominant margin pool; Wireless Charging is expanding most quickly as hospitals prioritize maintenance reduction.
End User:
Customer type stratification separates price-sensitive residential purchasers from institutional buyers with compliance mandates and service contract requirements.
- Hospitals:Acute care and long-term care facilities requiring FDA Class II medical device clearance or equivalent regulatory validation for patient monitoring applications. Procurement committees in France and Germany now require documented EU AI Act conformity assessments.
- Gyms:Commercial fitness operators and boutique studio chains sourcing connected exercise platforms for member retention and differentiated class offerings.
- Sports Facilities:Professional training centers and rehabilitation clinics demanding clinical-grade accuracy for athlete performance optimization.
- Households:Direct-to-consumer purchasers through e-commerce channels seeking home fitness or wellness monitoring solutions.
Hospitals concentrate the highest average selling prices; Households represents the steepest expansion trajectory through online distribution.
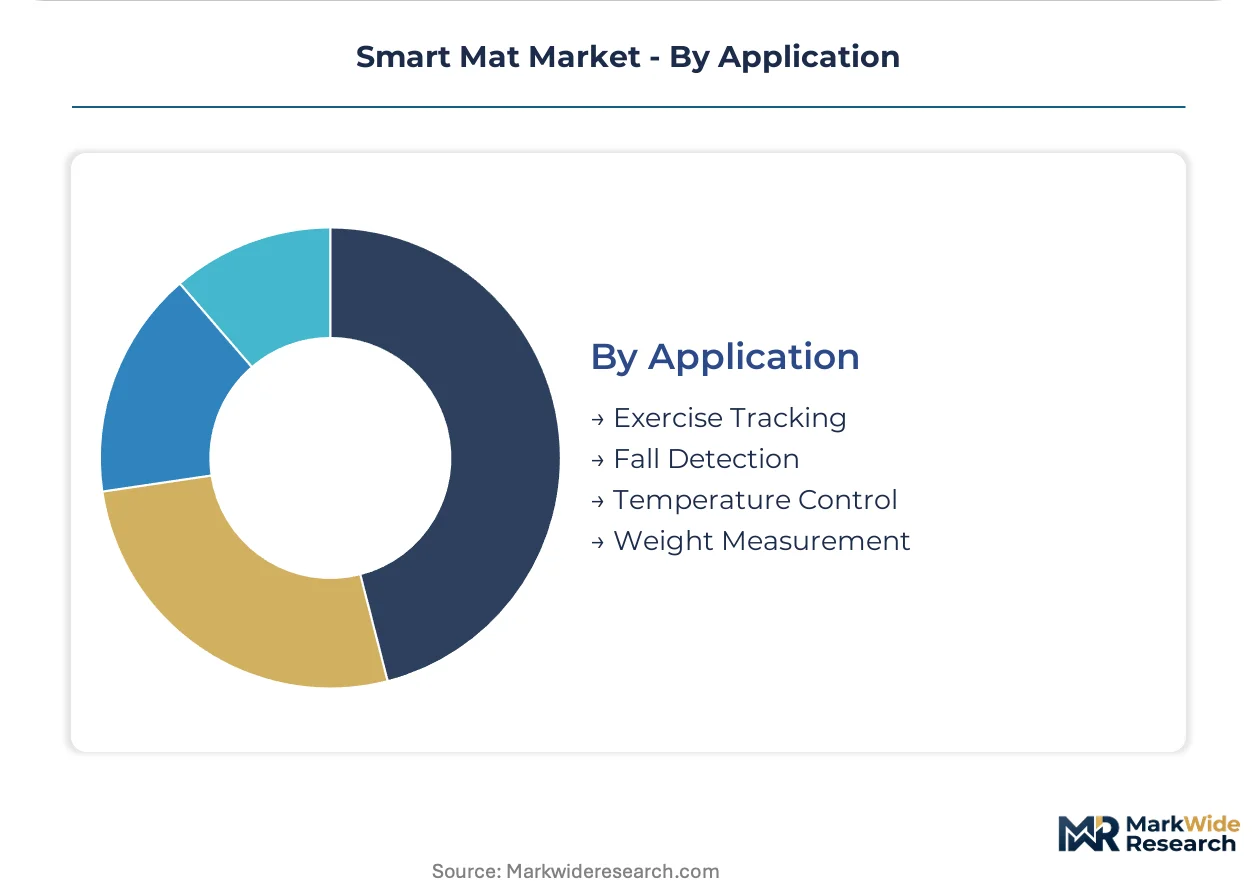
Application:
Volume distribution across use cases reflects the relative maturity of biometric sensing applications versus emerging temperature management functions.
- Exercise Tracking:Movement analytics, repetition counting, and force distribution visualization for strength training and yoga applications. Sports medicine clinics in North America drive adoption of high spatial resolution platforms.
- Fall Detection:Real-time gait analysis and anomaly detection for elderly care and post-surgical rehabilitation settings. Japan's aging population demographics accelerate hospital procurement.
- Weight Measurement:Integrated load cells or pressure mapping for body mass indexing and longitudinal health tracking.
- Temperature Control:Thermostatic floor warming with occupancy-based energy management for residential and commercial building automation.
Exercise Tracking handles the majority of throughput; Fall Detection is gaining share fastest as healthcare systems prioritize preventive care infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) pathways in the United States and CE marking requirements under the EU Green Deal are anchoring compliance frameworks that reshape procurement patterns across concentrated demand centers. National regulators in Japan and Germany are accelerating hospital and industrial safety deployments through targeted procurement mandates.
United States
Hospital systems in the United States are expanding fall-detection infrastructure for elderly patient wards, with acute care facilities driving concentrated demand for FDA-cleared monitoring platforms. The FDA classifies certain patient-monitoring smart mats as Class II medical devices, triggering 510(k) clearance pathways that extend development timelines. Group purchasing organizations in the Midwest and Southeast are unbundling smart mats from broader fall-prevention bundles, enabling direct price discovery at the SKU level.
Germany
Automotive and machinery sectors in Germany are deploying pressure-sensitive floor systems to reduce workplace injury liability, anchoring industrial safety mat demand. CE marking under the EU Green Deal is accelerating material substitutions toward recyclable substrates, opening compliance-driven product refresh cycles. The industrial corridor spanning Bavaria and Baden-Württemberg hosts concentrated deployments of certified machinery safety systems.
Japan
Hospital networks in Japan are expanding procurement of pressure-sensing floor systems for elderly fall detection, creating concentrated demand pull in precision healthcare infrastructure. METI procurement guidelines favor domestic sensor manufacturers for critical healthcare infrastructure. The Kanto region around Tokyo and the Kansai cluster centered on Osaka are consolidating centralized procurement offices that negotiate sensor-lifetime service agreements directly with manufacturers.
France
Hospital procurement committees in France are requiring documented EU AI Act conformity assessments before contract award for connected wellness devices. The CNIL is tightening data sovereignty requirements that push inference engines toward on-mat edge processors. The Île-de-France region around Paris concentrates health system headquarters where procurement standardization decisions are centralized.
United Kingdom
Sports medicine clinics in the United Kingdom are adopting high-definition movement analytics platforms, compressing the addressable market for legacy force-plate systems. The Medicines and Healthcare products Regulatory Agency is aligning post-Brexit device clearance pathways with EU MDR standards. London and the Southeast corridor host boutique fitness studio chains sourcing connected exercise platforms for member retention.
Smart Mat Market Competitive Landscape
Consumer electronics conglomerates and industrial automation specialists split the market into divergent margin pools with incompatible capability requirements. The vendor base concentrates around three strategic archetypes: diversified technology holding companies with captive sensor supply, pure-play industrial safety equipment manufacturers with certification moats, and e-commerce platforms leveraging logistics infrastructure for distribution control. Competitive moves center on backward integration into flexible printed circuit substrate supply and geographic expansion through direct institutional procurement channels that bypass medical device distributors.
Within the diversified technology tier, Samsung Electronics and LG Electronics exemplify conglomerate players that anchor positions through in-house production of flexible display and sensor technologies. Amazon.com, Inc. occupies a distinct archetype as an e-commerce platform operator that leverages logistics infrastructure to dominate online distribution of connected home fitness products. Robert Bosch GmbH represents the industrial automation specialist segment, extending automotive sensor expertise into pressure-sensitive floor systems for manufacturing environments where CE marking and functional safety certification limit supplier competition.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Amazon.com, Inc. |
| Apple Inc. |
| Honeywell International Inc. |
| Schneider Electric |
| Johnson Controls Inc. |
| Robert Bosch GmbH |
| ABB Ltd |
| Others |
Value Network & Pricing Analysis
Single-source dependency on East Asian flexible printed circuit substrate suppliers determines both the premium spread for certified industrial-grade mats and the geographic clustering of contract manufacturing capacity. FDA 510(k) clearance requirements and EU AI Act compliance costs compress margins at the standard tier while insulating premium-priced clinical segments from price competition.
Pricing Analysis
The customization-premium spread separates configured-to-order industrial safety systems from standard fitness mat SKUs. Pricing stratifies across premium clinical-grade, standard commercial-grade, and economy consumer-grade tiers based on FDA/CE certification level and sensor density. Cost compression in the consumer tier intensifies as direct-to-consumer e-commerce channels disintermediate traditional retail markups. Hospital procurement committees exhibit the lowest price sensitivity due to liability-driven specification requirements, while household buyers through Amazon.com, Inc. platforms demonstrate the highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwanese and South Korean EMS providers holding dedicated capacity for roll-to-roll flexible electronics processing. Raw material dependencies center on polyimide films, silver nanowire conductive inks, and Bluetooth Low Energy module chipsets. Single-source vulnerability in high-durability FPC manufacturing exposes the supply chain to trade-route disruptions and input cost volatility. Distribution runs through direct institutional procurement channels for hospital and industrial buyers, with e-commerce platforms capturing consumer segment fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart mat penetration remains in early-cycle expansion as aging demographics across Japan, Germany, and the United States accelerate hospital procurement of fall-detection infrastructure. Post-acute care shifting to residential settings creates a secondary demand wave for clinical-grade accuracy in consumer-accessible formats.
For Market Incumbents: Harden certification moats by accelerating FDA 510(k) submissions for next-generation monitoring platforms before venture-backed entrants exhaust capital reserves. Deepen backward integration into flexible printed circuit substrate supply through strategic partnerships with East Asian roll-to-roll manufacturers, reducing exposure to single-source concentration risk. Anchor hospital system relationships through sensor-lifetime service agreements that preempt disintermediation by group purchasing organizations. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point for industrial safety mat deployment, as manufacturing relocation from China creates greenfield facility demand without entrenched supplier relationships. Home-based rehabilitation monitoring for post-surgical patients offers a white-space consumer application with reimbursement tailwinds. A direct-to-clinic go-to-market angle bypasses medical device distributor markups and accelerates price discovery with sports medicine practitioners. For Investors and Strategic Acquirers: The EU AI Act's prohibition on real-time biometric cloud processing reshapes the acquisition landscape by elevating edge-computing firmware capabilities above hardware scale. Long-term viability across the analysis window favors targets with validated ETSI cybersecurity certification and hospital procurement committee relationships. The signal to watch is METI procurement guideline revisions in Japan, which would signal domestic manufacturer preference shifts affecting regional competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| ETSI Cybersecurity Certification | Third-party validated data protection protocols unlock European hospital procurement gates. |
| Backward Integration into FPC Supply | Captive polyimide substrate production insulates margin from East Asian supplier concentration. |
| Edge Processor Relocation | On-mat inference engines satisfy EU AI Act data sovereignty mandates without cloud architecture redesign. |
| Direct Institutional Procurement Channels | Bypassing medical device distributors captures price discovery benefits from hospital system consolidation. |
| Sensor-Lifetime Service Agreements | Recurring revenue models attach to Japanese hospital network centralized procurement offices. |
Research Methodology
A standing panel of biomedical engineers, hospital purchasing committee chairs, industrial safety officers, and GPO contracts managers provided ongoing calibration of sensor performance requirements and procurement decision criteria. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation, and METI procurement guideline releases. Bottom-up triangulation of unit shipment estimates with top-down healthcare infrastructure spending allocations anchored volume projections.
Scenario-bracketing around regulatory approval timelines and hospital capital expenditure cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user category, and application use case, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derived from logistic diffusion curves fitted to historical medical device adoption patterns, with inputs from Bluetooth SIG membership growth and industrial safety automation capex surveys.
Practitioners should monitor FDA guidance document revisions for patient-monitoring device classification and EU AI Act implementing acts for biometric processing scope definitions as early signals requiring forecast reassessment. Cross-checking against hospital procurement database trend lines from Definitive Healthcare or equivalent regional sources is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Eye Tracking Market
Sensors
Barcode Scanner Market
Sensors
Europe RFID Market
Sensors
Asia-Pacific Remote Sensing Technology Market
Sensors
Drain Camera Market
Sensors
Mobile Lidar Scanner Market
Sensors
Location-Based Ambient Intelligence Market
Sensors
Sensor Landscape in Robotics and ADAS Vehicle Market
Sensors
Asset Tracking Market
Sensors
Handheld RFID Readers Market
Sensors
Vision Positioning System Market
Sensors
Facial Tracking Solution Market
Sensors
Global Remote Tank Monitoring System Market
Sensors
Heat Stress Meter Market
Sensors
Europe Lidar Market
Sensors
Digital Olfaction Products Market