
 Wireless Occupancy Sensors Market | 2026-2036
Wireless Occupancy Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Occupancy Sensors Market Analytics
Sensor-to-gateway bundling is restructuring procurement patterns across the wireless occupancy sensors industry. Schneider Electric leverages its EcoStruxure platform to anchor integrated building automation packages in European commercial projects. Honeywell International Inc competes through vertical integration into its own sensor silicon and cloud analytics stack. Legrand specializes in modular wall-switch units that contractors can retrofit without rewiring, sustaining strong positions in renovation-heavy markets.
Wireless occupancy sensors are self-contained detection devices that transmit occupancy state data via radio frequency protocols, typically operating at detection ranges of 15–30 feet with milliwatt-level power consumption to enable multi-year battery life. Their primary purpose is to trigger automated responses in lighting, climate, and security systems based on human presence or absence. Passive infrared units dominate unit shipments due to lowest installed cost, yet dual technology sensors that combine PIR and ultrasonic elements command the richest margin pools in high-security and healthcare applications. Bluetooth Low Energy connectivity is displacing Zigbee in residential and small commercial deployments where smartphone-native commissioning reduces installation labor.
The EPA Energy Star program and the EU Green Deal both mandate measurable reductions in building energy intensity, directly expanding addressable demand for occupancy-driven automation. NEMA standards in the United States and CE marking requirements in Europe dictate electromagnetic compatibility and safety thresholds that shape product design and market access timelines. Stakeholders must monitor whether Thread protocol certification achieves critical mass in multi-vendor building ecosystems before committing to connectivity roadmaps.
Market Dynamics
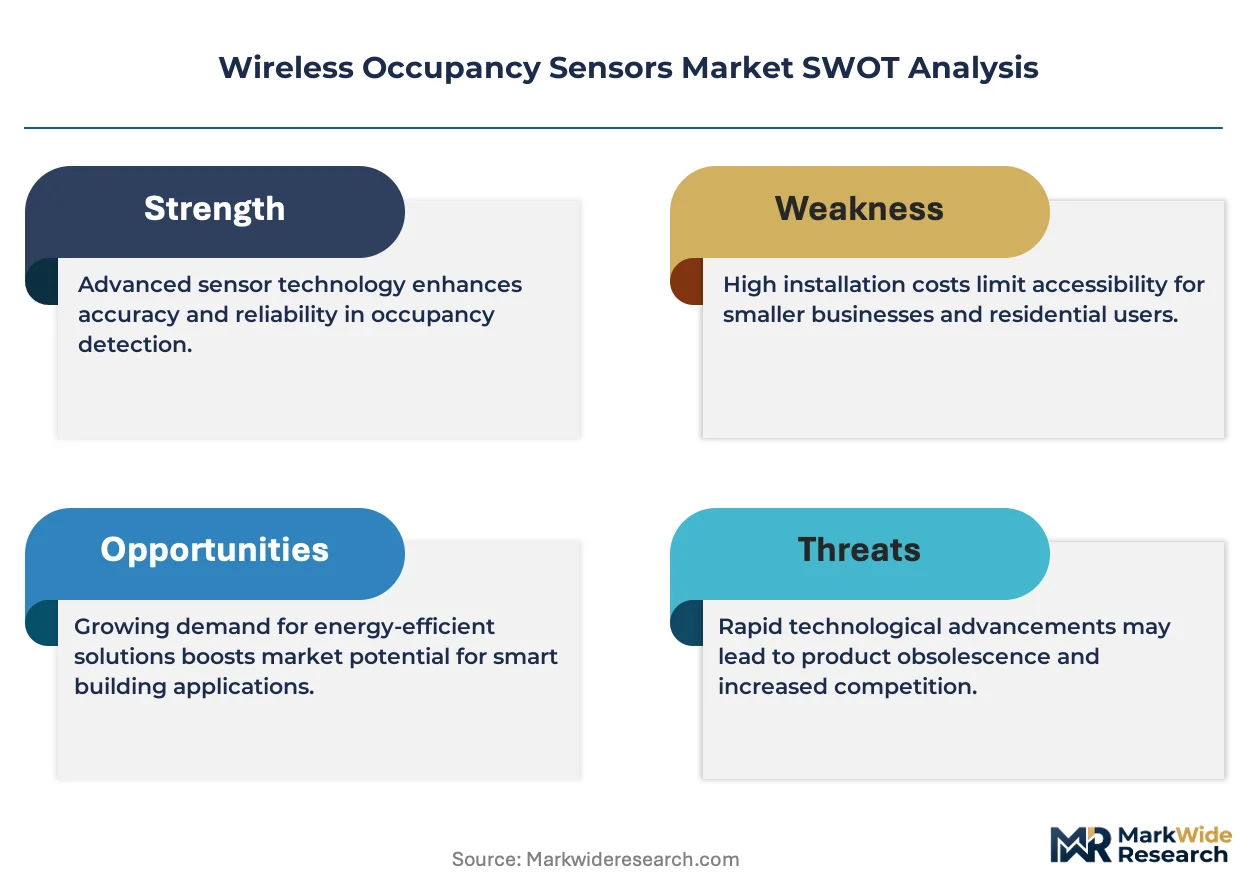
Sensor-to-gateway bundling is restructuring procurement patterns across the wireless occupancy sensors industry, forcing standalone hardware vendors to integrate software stacks or surrender margin to platform providers.
Growth Catalysts
- EPA Energy Star mandates:Building operators in the United States deploy occupancy-driven automation to meet federal energy intensity reduction requirements, expanding retrofit demand.
- Healthcare facilities:Dual-technology sensors combining passive infrared and ultrasonic detection command premium positioning in patient monitoring and infection control applications.
- Germany's building code revisions:Automated lighting controls are now compulsory in public structures, accelerating wireless sensor deployment across municipal retrofit projects.
Market Restraints
- Battery chemistry volatility:Lithium manganese dioxide cell prices fluctuate with raw material availability, squeezing margin on multi-year battery-life product lines.
- Gateway vendor concentration:North American cloud infrastructure providers dominate data aggregation layers, creating single-point-of-failure risk for sensor OEMs.
- PIR range limitations:Passive infrared units suffer detection gaps in irregular room geometries, restricting addressable square footage per device.
Strategic Opportunities
- India's smart city programs:Municipal lighting automation tenders create first-mover advantage for vendors establishing local certification with BIS.
- Thread protocol convergence:Certification harmonization with Matter standards enables single-hardware SKUs across residential and commercial channels.
- Predictive maintenance bundling:Sensor data streams feed HVAC predictive analytics, opening recurring revenue models for installation contractors.
Industry Challenges
- RF commissioning expertise:Shortage of technicians trained in Bluetooth Low Energy mesh configuration delays project timelines and elevates callback rates.
- CE marking timeline compression:Electromagnetic compatibility testing queues at notified bodies extend product launch windows by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Occupancy Sensors Market |
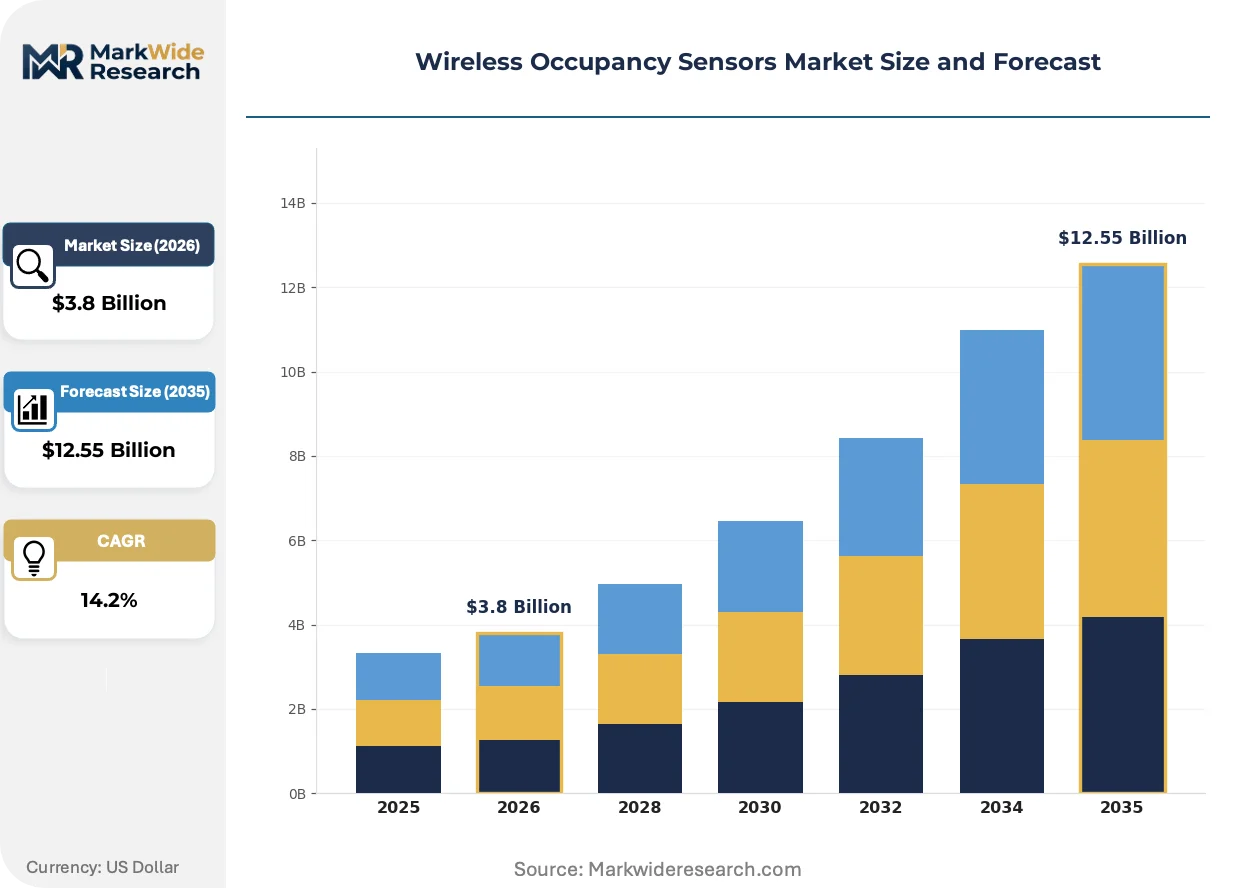
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Infrared, Ultrasonic, Dual Technology, Microwave Application: Commercial Buildings, Residential Spaces, Industrial Facilities, Educational Institutions Connectivity: Wi-Fi, Zigbee, Bluetooth Low Energy, Thread End User: Facility Managers, Homeowners, Contractors, Architects |
| Companies Covered | Honeywell International Inc, Schneider Electric, Johnson Controls, Legrand, Acuity Brands, Eaton Corporation, Lutron Electronics, Signify, Leviton Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Occupancy Sensors Market Evolving Landscape
Connectivity protocol migration and regulatory energy mandates are compressing hardware replacement cycles while elevating software analytics as the primary value capture mechanism.
Bluetooth Low Energy mesh is overtaking Zigbee in small commercial and residential deployments. Property managers favor smartphone-native commissioning tools that eliminate dedicated installer hardware. This protocol shift is overtaking traditional proprietary radio stacks and compressing installation labor costs by half in sub-ten-thousand-square-foot buildings.
EU Green Deal building renovation requirements are mandating measurable energy intensity reductions across member state public structures. France and Italy have transposed these directives into national construction codes with 2027 compliance deadlines. Commercial retrofit contractors now specify wireless occupancy sensors as standard inclusion in lighting upgrade packages to satisfy ANSM and local prefecture inspection protocols.
Facility managers now demand outcome-based energy performance contracts rather than equipment procurement. Energy service companies absorb upfront hardware costs and recover investment through guaranteed HVAC savings shares. This model concentrates buyer power among large ESCOs in Germany and Japan, squeezing standalone sensor vendors into white-label supply roles.
Wireless Occupancy Sensors Market Segmentation
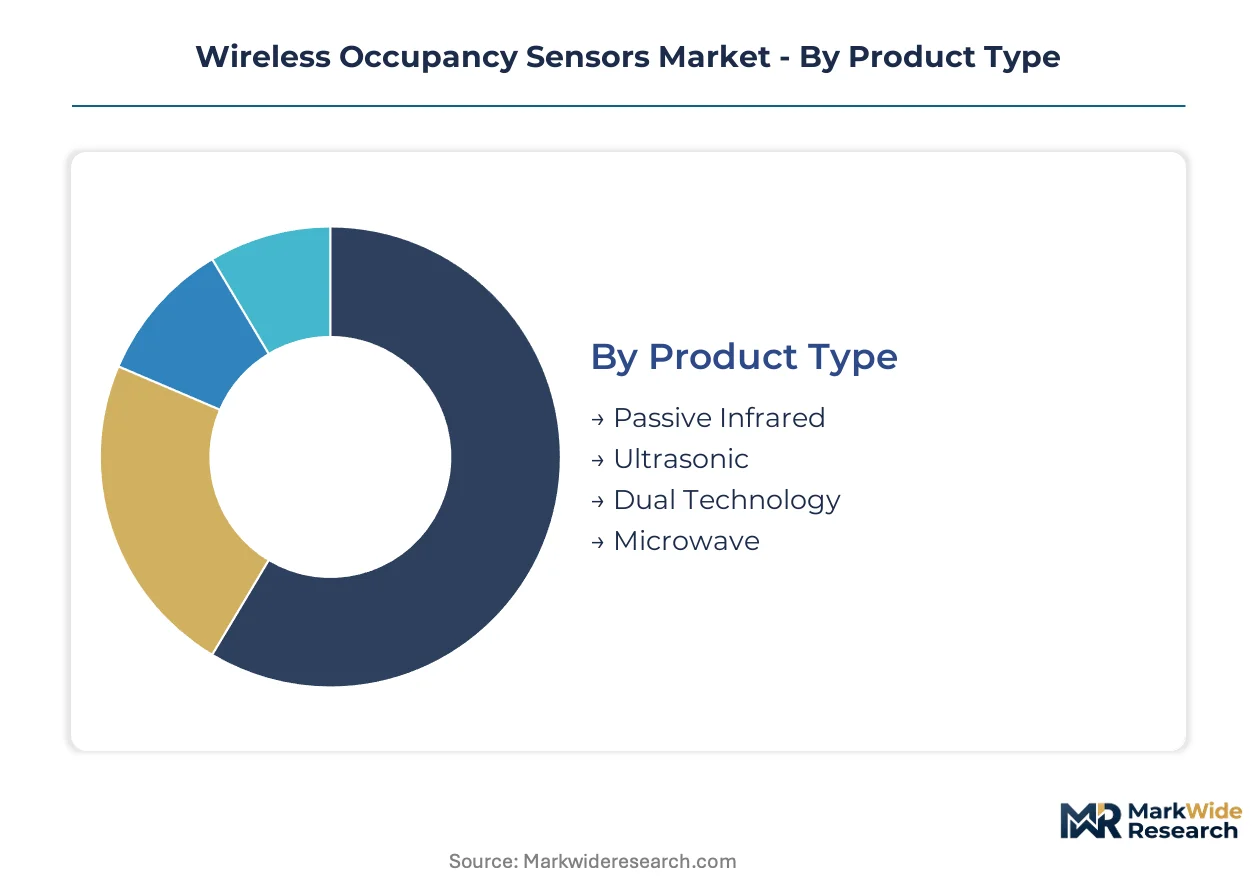
Segmentation in the wireless occupancy sensors market reveals divergent technology preferences across price tiers and use cases. Procurement patterns vary sharply between cost-driven retrofits and performance-critical new construction.
Product Type:
Passive infrared sensors dominate unit volume while dual technology variants capture the richest margins in specialized applications.
- Passive Infrared:These sensors detect body heat through pyroelectric elements, operating without active emission to preserve battery life. Demand concentrates in German and Japanese municipal retrofit projects where building codes mandate automated lighting controls but budgets constrain hardware selection.
- Dual Technology:Combining PIR and ultrasonic detection eliminates false triggers in irregular geometries. Healthcare facilities in the United States deploy these units for patient monitoring and infection control applications where detection reliability justifies premium positioning.
- Ultrasonic:Active emission sensors excel in partitioned office environments where line-of-sight PIR coverage fails.
- Microwave:Doppler-based detection penetrates physical barriers, serving outdoor and high-bay industrial applications.
Today's leader: Passive Infrared. Tomorrow's challenger: Dual Technology.
Application:
Commercial buildings absorb the majority of sensor shipments, though residential channels are expanding fastest as smart home adoption accelerates.
- Commercial Buildings:Office towers, retail centers, and hospitality properties deploy ceiling-mounted and wall-switch units to satisfy EPA Energy Star mandates. South Korean developers specify wireless sensors in new construction to meet green building certification requirements.
- Residential Spaces:Single-family homes and multifamily apartments favor battery-powered retrofit units with smartphone commissioning. Bluetooth Low Energy connectivity reduces installation labor, expanding addressable demand among homeowners without electrical expertise.
- Industrial Facilities:Manufacturing plants and warehouses prioritize ruggedized housings with extended detection ranges for high-ceiling environments.
- Educational Institutions:K-12 schools and university campuses balance first-cost constraints against maintenance accessibility in aging infrastructure.
Commercial Buildings anchor current procurement volumes. Residential Spaces are climbing the fastest as Matter protocol certification simplifies cross-platform integration.
Connectivity:
Protocol selection determines installation economics and ecosystem compatibility across deployment scales.
- Bluetooth Low Energy:Native smartphone support eliminates dedicated commissioning hardware, compressing labor costs by half in sub-ten-thousand-square-foot buildings. Small commercial property managers in the United States favor this protocol for tenant improvement projects.
- Wi-Fi:Direct cloud connectivity bypasses gateway infrastructure, appealing to residential homeowners and single-location commercial operators.
- Zigbee:Mesh networking reliability sustains position in large-scale commercial deployments despite more complex configuration requirements.
- Thread:IP-native architecture promises interoperability across vendor ecosystems, pending certification harmonization with Matter standards.
Bluetooth Low Energy holds current volume leadership. Thread represents the steepest expansion trajectory if multi-vendor certification achieves critical mass.
End User:
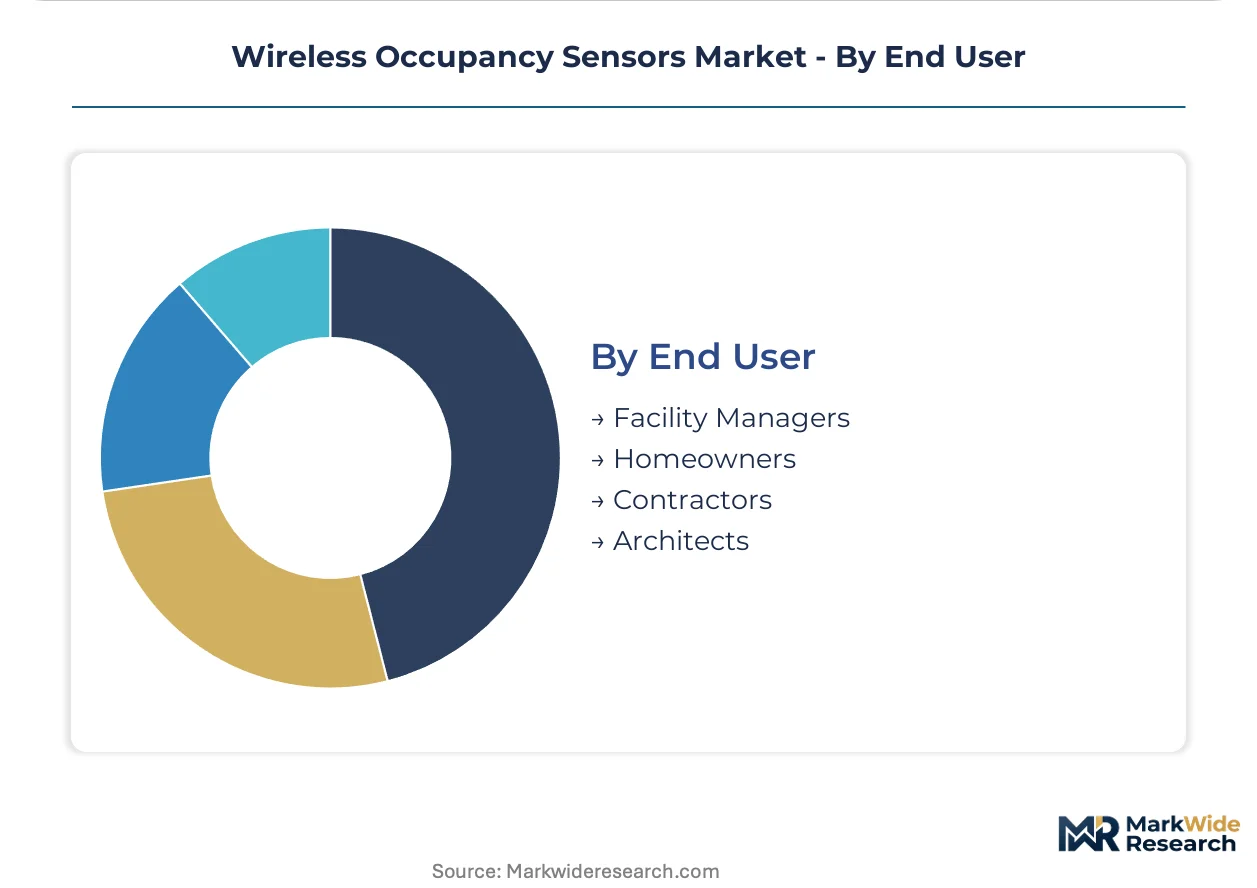
Procurement authority varies by project type, with contractors controlling retrofit decisions and architects influencing new construction specifications.
- Contractors:Electrical and lighting retrofit specialists prioritize modular wall-switch units requiring no rewiring. Legrand's contractor-focused distribution sustains strong positions in renovation-heavy markets.
- Facility Managers:Building operators demand outcome-based energy performance contracts rather than equipment procurement, concentrating buyer power among large energy service companies in Germany and Japan.
- Homeowners:Do-it-yourself installation preferences drive demand for battery-powered, app-commissioned devices.
- Architects:Design-phase specification authority shapes connectivity and aesthetic requirements for new construction.
Contractors command retrofit channel decisions. Facility Managers are gaining procurement authority fastest as energy performance contracting expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wireless occupancy sensor technology achieved commercial scale in the United States during the 1990s energy efficiency movement, with European and Asian markets adopting localized variants through the 2000s as building automation standards hardened.
United States
Commercial building operators deploy ceiling-mounted and wall-switch units to satisfy EPA Energy Star mandates for energy intensity reduction. The EPA administers certification protocols that directly shape procurement specifications for federal and municipal retrofit projects. Installation contractors in Chicago and New York metropolitan corridors concentrate on lighting upgrade packages that bundle sensors with LED retrofits.
Germany
Municipal retrofit projects drive demand for passive infrared units where building codes mandate automated lighting controls in public structures. The country's national construction code transposes EU Green Deal directives into binding energy efficiency requirements with 2027 compliance deadlines. Energy service companies in the Ruhr industrial region and Bavaria dominate outcome-based performance contracting, concentrating buyer power among large ESCOs.
Japan
Healthcare facilities and aging commercial infrastructure create demand for dual-technology sensors with premium positioning in patient monitoring applications. METI oversees building energy standards that accelerate wireless sensor deployment in municipal and hospital renovation programs. Tokyo and Osaka metropolitan clusters host concentrated procurement activity among facility management consortia.
South Korea
Green building certification requirements in new construction specifications drive developer adoption of integrated sensor-to-gateway systems. The national energy efficiency framework mandates measurable consumption reductions in public and commercial structures. Seoul and Incheon development corridors exhibit dense deployment of ceiling-mounted units in high-rise office and retail towers.
India
Municipal lighting automation tenders under smart city programs create first-mover opportunities for vendors establishing BIS certification. The Bureau of Indian Standards regulates electromagnetic compatibility and safety thresholds that shape product launch timelines. Mumbai and Delhi-NCR infrastructure projects concentrate early procurement activity among state-level urban development authorities.
Wireless Occupancy Sensors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with full-stack platform providers commanding richer pricing than standalone hardware vendors. The vendor base organizes into three tiers: multinational building automation conglomerates with captive sensor silicon, specialized electrical component manufacturers with contractor-centric distribution, and emerging connectivity-focused entrants. Strategic archetypes include platform-anchored integrators, modular retrofit specialists, and protocol-native challengers. Dominant competitive moves encompass backward integration into semiconductor supply and outcome-based energy performance contracting that absorbs upfront hardware costs.
Within the platform-anchored tier, Schneider Electric and Honeywell International Inc exemplify multinational conglomerates with integrated building automation stacks. Legrand occupies a position among modular retrofit specialists with contractor-focused distribution networks. These three companies represent distinct strategic archetypes: EcoStruxure-platform integration, in-house silicon and cloud analytics control, and rewiring-free wall-switch modularity respectively.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Schneider Electric |
| Johnson Controls |
| Legrand |
| Acuity Brands |
| Eaton Corporation |
| Lutron Electronics |
| Signify |
| Leviton Manufacturing |
| Others |
Value Network & Pricing Analysis
Backward integration into captive sensor silicon production anchors supply position and pricing power for multinational building automation conglomerates competing against modular hardware vendors. Honeywell International Inc and Schneider Electric leverage in-house semiconductor supply to defend margin pools against commodity pressure from white-label sensor assemblers in East Asian manufacturing hubs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates dual-technology healthcare sensors from passive infrared retrofit units and unbranded gateway-compatible hardware. Price differentiation hinges on FCC Part 15 certification tier and after-sales predictive maintenance bundling. Cost compression in the economy tier is intensifying because lithium manganese dioxide cell volatility squeezes multi-year battery-life product lines. Municipal contractors in Germany exhibit highest price sensitivity; hospital facility managers in Japan demonstrate lowest sensitivity due to infection control liability exposure.
Supply Chain Analysis
Technician shortages in Shenzhen and Dongguan manufacturing clusters constrain final assembly throughput for Bluetooth Low Energy mesh modules destined for North American retrofit channels. Component sourcing draws from Taiwanese foundries for pyroelectric elements, South Korean battery cell producers, and Malaysian PCB substrate suppliers. Single-source vulnerability concentrates in cloud gateway infrastructure where North American hyperscalers dominate data aggregation layers. Distribution runs through electrical wholesale networks serving contractor-centric procurement in renovation-heavy metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between India's BIS certification timeline and the EU's compressed CE marking queues creates first-mover cost advantages for vendors establishing local electromagnetic compliance ahead of 2027 building code deadlines.
For Market Incumbents: Deploy outcome-based energy performance contracting to absorb upfront hardware costs and lock out standalone sensor vendors from large German and Japanese ESCO relationships. Deepen backward integration into battery management IC design to offset lithium chemistry volatility threatening multi-year product warranties. Counter Thread protocol fragmentation risk by accelerating Matter certification harmonization across residential and commercial SKUs. For New Entrants and Emerging Players: Direct-to-contractor digital channels bypass established electrical wholesale gatekeepers and compress customer acquisition costs in India's smart city lighting automation tenders. White-space concentration sits in battery-powered Bluetooth Low Energy wall-switch units for US residential DIY installation where smartphone-native commissioning eliminates electrician dependency. Target municipal retrofit specifications in South Korea's green building certification pipeline through localized gateway integration partnerships. For Investors and Strategic Acquirers: Roll-up economics work for connectivity-focused sensor specialists because platform-anchored integrators face antitrust scrutiny on large-scale acquisitions that would concentrate building automation stacks. Five-to-ten year viability favors vendors with dual-technology IP portfolios serving healthcare monitoring applications where detection reliability commands sustainable premium positioning. Monitor Thread protocol certification harmonization with Matter standards as inflection indicator for multi-vendor ecosystem consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Schneider Electric's EcoStruxure anchors integrated building automation packages in European commercial projects. |
| Backward Integration | In-house sensor silicon production insulates Honeywell from commodity margin pressure in gateway hardware. |
| Certification Investment | BIS local certification in India unlocks municipal smart city lighting automation tender participation. |
| Channel Control | Legrand's contractor-focused distribution sustains retrofit market share without rewiring labor costs. |
| Product Launch | Bluetooth Low Energy mesh modules with smartphone commissioning halve installation labor in sub-ten-thousand-square-foot buildings. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with building automation system integrators, electrical contracting procurement leads, facility management consortia, and energy service company contract officers with secondary validation. Regulatory filings from EPA Energy Star certification databases, EU Green Deal directive transpositions, and BIS electromagnetic compatibility standards anchored policy impact assessment. SEC 10-K disclosures from listed building automation conglomerates, customs records for sensor component trade flows, and municipal tender documentation from German, Japanese, and Indian urban development authorities supplied demand-side triangulation against bottom-up shipment estimates.
Segment-weighting approaches distributed total addressable value across passive infrared, dual-technology, ultrasonic, and microwave product types, then cross-cut by Bluetooth Low Energy, Wi-Fi, Zigbee, and Thread connectivity protocols. Commercial building, residential, industrial, and educational application channels were modeled separately with distinct replacement cycle assumptions. CAGRs were derived from installed base penetration curves and regulatory mandate compliance deadlines across the projection horizon. Forecast inputs incorporated battery chemistry cost trajectories, RF commissioning technician availability by metropolitan cluster, and gateway vendor concentration risk in cloud infrastructure layers.
The model assumes a particular technology adoption path; alternative pathways for Thread protocol convergence with Matter standards would alter the outlook for multi-vendor interoperability and hardware SKU consolidation. Forecasts reflect assumptions regarding EPA mandate enforcement continuity, EU Green Deal transposition timelines, and lithium raw material supply stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Safety Motion Control System Market
Sensors
IO-Link Technology Market
Sensors
Global Equipment Monitoring Market
Sensors
Cloud Camera Market
Sensors
Global Remote Tank Monitoring System Market
Sensors
Indoor Air Quality Monitor Market
Sensors
Lidar in Mapping Market
Sensors
IO Link Market
Sensors
Asia-Pacific Remote Sensing Technology Market
Sensors
Digital Direction Finder Market
Sensors
Vision Positioning System Market
Sensors
Mobile Lidar Scanner Market
Sensors
Eye Tracking Solutions Market
Sensors
Global Weather Monitoring Solutions and Services Market
Sensors
Automatic Number Plate Recognition (ANPR) Market
Sensors
Asia Pacific Container Monitoring Market