
 Refrigeration Monitoring Market | 2026-2036
Refrigeration Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigeration Monitoring Market Analysis
Aftermarket service revenue is fragmenting across hardware vendors and independent software platforms as monitoring ecosystems decouple from original equipment. Emerson Electric leverages its compressor installed base to extend into predictive diagnostics, while Danfoss sustains European channel control through proprietary sensor-to-cloud protocols. Samsara competes on fleet-scale deployments, anchoring North American transportation monitoring with cellular-connected loggers.
Refrigeration monitoring encompasses sensor networks, data acquisition systems, and analytics platforms that track thermal conditions in controlled environments, typically operating within ±0.5°C accuracy for pharmaceutical applications and ±2°C for food service. The primary purpose is ensuring product integrity, regulatory compliance, and energy optimization across temperature-sensitive supply chains. Cloud-based solutions capture expanding margin pools as subscription models displace capital-intensive standalone installations. Wireless sensors lead volume growth in retrofit applications where wired infrastructure proves cost-prohibitive. IoT devices concentrate R&D investment as edge computing enables real-time intervention before excursions breach thresholds.
FDA 21 CFR Part 11 and EU MDR documentation requirements shape product design by mandating audit trails, electronic signatures, and tamper-evident data logging for pharmaceutical cold chains. EPA SNAP regulations and F-Gas restrictions in Europe drive refrigerant leak detection integration into monitoring platforms. Stakeholders must weigh interoperability standards against proprietary ecosystem lock-in as procurement teams consolidate vendor relationships across facility and fleet footprints.
Market Dynamics
Cloud-native platforms are decoupling monitoring hardware from analytics software, fragmenting vendor ecosystems and forcing compressor OEMs to defend installed bases through predictive service contracts rather than equipment sales alone.
Growth Catalysts
- EU MDR temperature documentation mandates:Pharmaceutical distributors in Germany and the Netherlands must deploy continuous data loggers with tamper-evident audit trails, accelerating retrofit sensor deployments across cold storage facilities.
- Wireless LoRaWAN sensor networks:Food service operators in France and Spain bypass wired infrastructure costs by installing battery-powered probes that transmit through existing cellular gateways, cutting installation timelines from weeks to days.
- F-Gas leak detection integration:Supermarket chains across Italy and Poland face mandatory refrigerant monitoring under EU F-Gas Regulation phasedown schedules, bundling environmental compliance with thermal integrity tracking.
Market Restraints
- Semiconductor component concentration:MEMS temperature sensor fabrication concentrates in Taiwanese foundries, exposing European system integrators to lead time volatility and minimum order quantity pressures.
- Proprietary cloud protocol lock-in:Danfoss and Emerson maintain incompatible data architectures, forcing multi-site operators into single-vendor relationships or expensive middleware development.
- Lithium battery supply constraints:Wireless logger manufacturers compete with electric vehicle and consumer electronics sectors for cylindrical cell supply, compressing margins on disposable sensor units.
Strategic Opportunities
- Indian cold chain infrastructure gaps:FSSAI's 2022 food safety modernization rules lack enforcement bandwidth outside Mumbai and Delhi, creating first-mover advantage for compliant monitoring-as-a-service platforms in tier-two cities.
- mRNA vaccine distribution protocols:Ultra-low temperature requirements for Pfizer and Moderna formulations are extending sensor specifications below -70°C, opening premium hardware segments beyond traditional pharmaceutical ranges.
- Edge AI inference at the sensor node:On-device anomaly detection reduces cloud transmission costs and enables millisecond intervention triggers, differentiating offerings for biologics manufacturers with excursion-sensitive payloads.
Industry Challenges
- Calibration technician scarcity:Pharmaceutical-grade sensor validation requires ISO 17025-traceable procedures that few field service organizations outside Germany and Switzerland can execute at scale.
- Legacy SCADA integration friction:Cold storage facilities running 1990s-era building management systems face protocol translation complexity when overlaying IoT monitoring layers, extending deployment timelines.
- Multi-jurisdiction data residency:EU GDPR, China's PIPL, and India's DPDP Act impose conflicting cloud storage location requirements on global pharmaceutical distributors operating unified fleet monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigeration Monitoring Market |
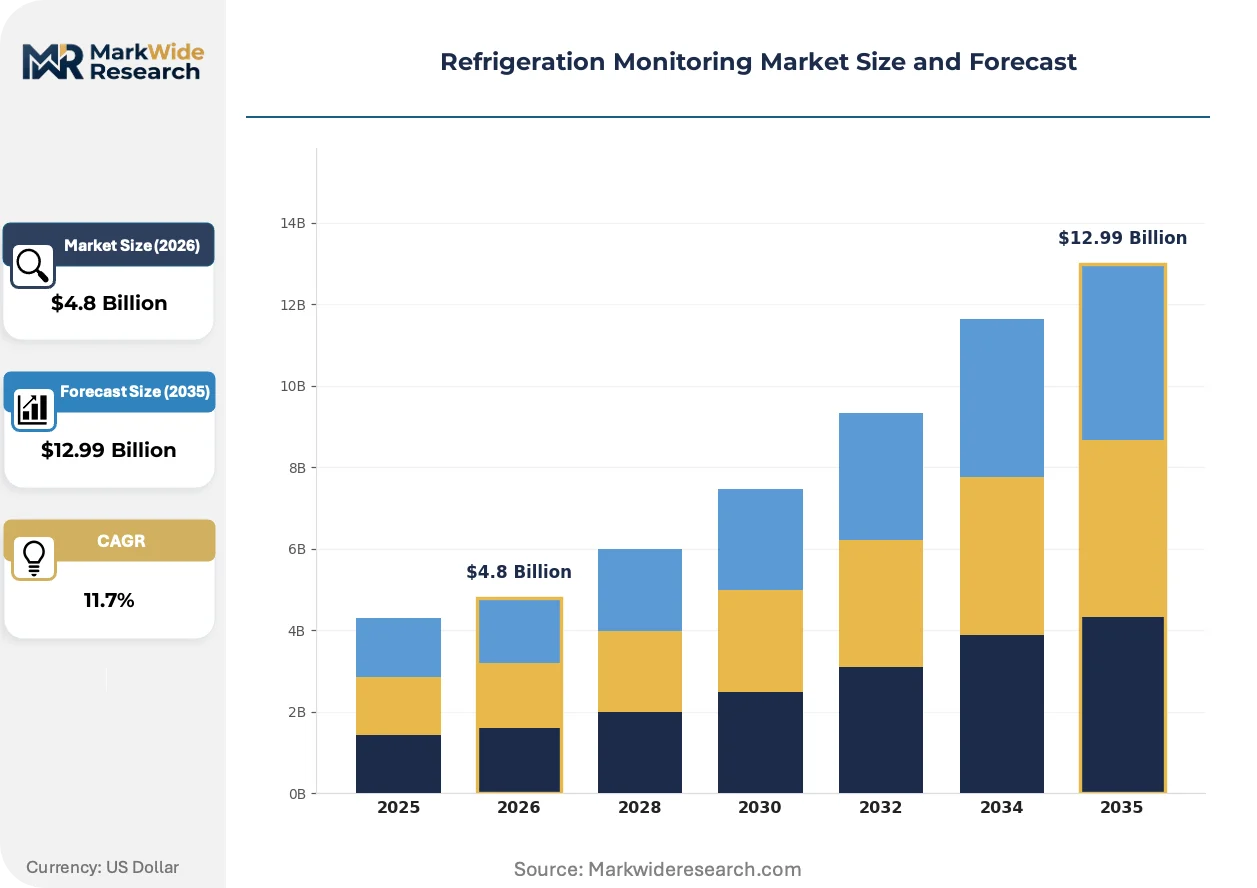
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Standalone Systems, Cloud-Based Solutions, Wireless Sensors, IoT Devices End User: Food & Beverage, Healthcare, Pharmaceuticals, Logistics Application: Cold Storage, Transportation, Monitoring Systems, Supply Chain Technology: Temperature Sensors, Humidity Sensors, Data Loggers, Alarm Systems |
| Companies Covered | Emerson Electric, Danfoss, Sensaphone, Monnit, Zebra Technologies, Texas Instruments, ORBCOMM, Samsara, Vaisala, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigeration Monitoring Market Emerging Trajectories
Digital twin architectures are compressing the feedback loop between field sensor data and predictive maintenance algorithms, repositioning monitoring from compliance documentation to operational optimization.
Self-calibrating platinum resistance thermometers with embedded reference junctions are rendering obsolete manual annual recalibration cycles that required facility shutdowns. Biologics manufacturers in Denmark and Belgium are adopting these probes for continuous process verification. The technology is rendering obsolete third-party metrology service contracts that previously consumed fifteen to twenty percent of annual monitoring budgets.
EPA SNAP approval restrictions on high-GWP refrigerants are accelerating leak detection sensor deployment in US supermarket chains. The regulations force integration of pressure transducers and infrared sensors into standard monitoring dashboards. California's CARB mandates are most aggressive, requiring real-time leak alerts that trigger automatic service dispatch before threshold breaches.
Consolidated procurement by pharmaceutical third-party logistics providers is unbundling hardware and software purchasing decisions. DHL Supply Chain and Kuehne+Nagel now source sensors through separate RFP processes from analytics platforms, pressuring bundled vendors to demonstrate API interoperability. This pattern is most pronounced in the Netherlands, where distribution hub concentration enables standardized fleet-wide specifications across multiple carrier relationships.
Refrigeration Monitoring Market Segmentation
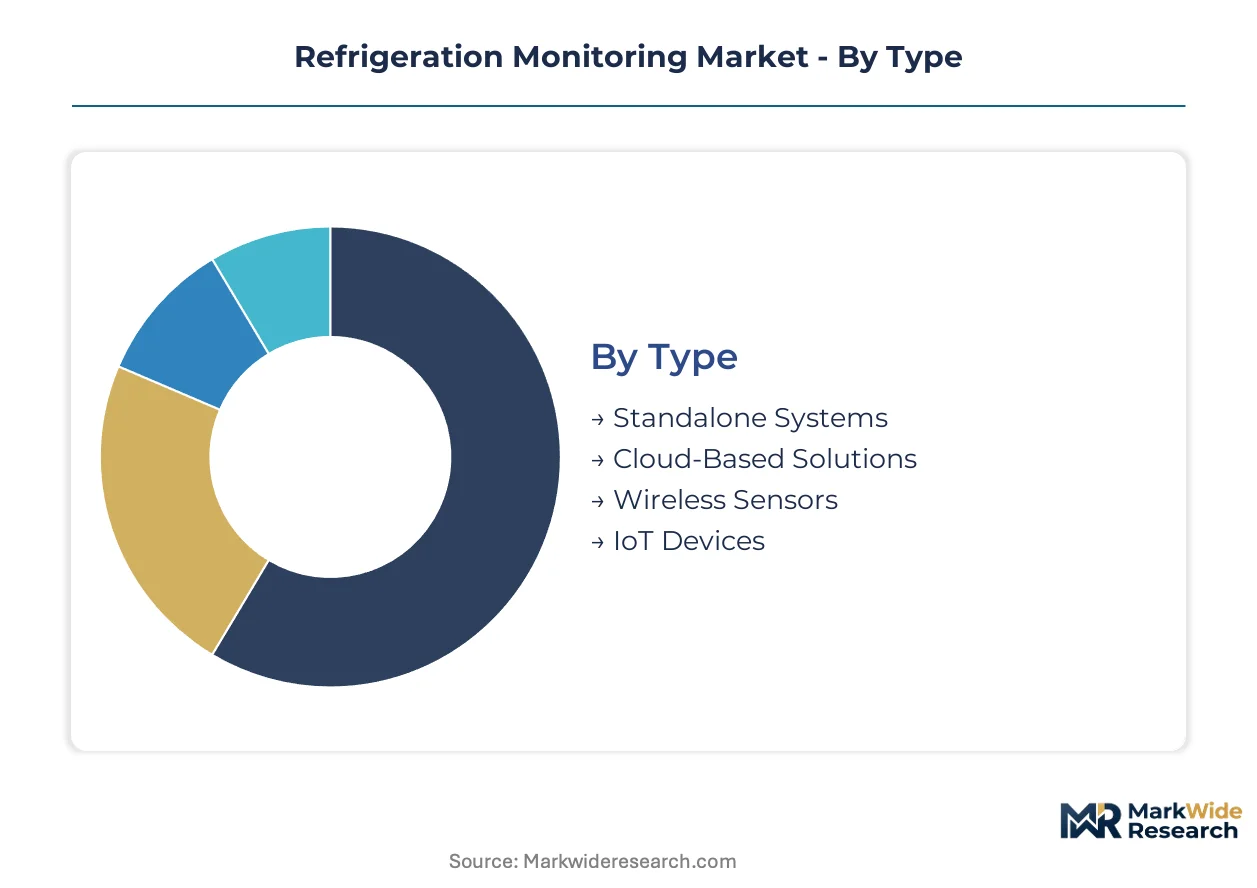
Refrigeration monitoring vendors monetize through divergent service intensity models across hardware and software layers. Segment boundaries determine whether procurement teams consolidate vendors or unbundle components through separate RFP processes.
Type:
After-sales service intensity varies dramatically by system architecture, with cloud platforms generating recurring revenue streams while standalone hardware depends on episodic replacement cycles.
- Cloud-Based Solutions:Subscription architectures centralize data aggregation across distributed sensor fleets, enabling predictive analytics without on-premise infrastructure. Pharmaceutical distributors in Germany and the Netherlands favor these platforms for EU MDR compliance documentation that requires tamper-evident audit trails and electronic signature workflows.
- IoT Devices:Edge-enabled sensors process anomaly detection locally before cloud transmission, reducing latency for excursion-sensitive biologics shipments. Battery supply constraints from competing electric vehicle demand are compressing margins on disposable logger units.
- Standalone Systems:Capital-intensive installations persist in legacy cold storage facilities with 1990s-era SCADA infrastructure that resists protocol translation.
- Wireless Sensors:Battery-powered LoRaWAN probes bypass wired installation costs, cutting deployment timelines from weeks to days for food service retrofits.
By volume, Wireless Sensors lead. By growth pace, Cloud-Based Solutions are climbing the fastest.
End User:
Customer procurement sophistication separates price-sensitive food service operators from pharmaceutical buyers who mandate ISO 17025-traceable calibration protocols.
- Pharmaceuticals:Ultra-low temperature requirements for mRNA vaccine distribution extend sensor specifications below -70°C, opening premium hardware segments beyond traditional ranges. FDA 21 CFR Part 11 and EU MDR documentation mandates force continuous data logger deployment with audit trail capabilities.
- Healthcare:Hospital pharmacy cold chains require integration with existing building management systems, creating protocol translation friction during IoT overlay deployments. Biologics manufacturers in Denmark and Belgium adopt self-calibrating platinum resistance thermometers to eliminate annual recalibration shutdowns.
- Food & Beverage:FSSAI modernization rules in India create first-mover opportunities for monitoring-as-a-service platforms in tier-two cities outside Mumbai and Delhi.
- Logistics:Third-party logistics providers now unbundle hardware and software sourcing, pressuring bundled vendors to demonstrate API interoperability across carrier relationships.
Pharmaceuticals command the highest price points. Food & Beverage is expanding most quickly in emerging markets.
Application:
Deployment environment determines sensor durability specifications and connectivity architecture choices across facility versus mobile use cases.
- Cold Storage:Fixed installations in distribution hubs concentrate around Frankfurt and Munich, where pharmaceutical-grade sensor validation requires scarce ISO 17025-traceable field service capacity.
- Transportation:Cellular-connected loggers anchor North American fleet monitoring, with real-time alerts triggering automatic service dispatch before threshold breaches under California CARB mandates.
- Supply Chain:Multi-jurisdiction data residency requirements from EU GDPR, China's PIPL, and India's DPDP Act impose conflicting cloud storage location constraints on unified fleet monitoring.
- Monitoring Systems:Digital twin architectures compress feedback loops between field data and predictive maintenance algorithms, repositioning systems from compliance documentation to operational optimization.
Cold Storage dominates installed base. Transportation is gaining share fastest through fleet-scale cellular deployments.
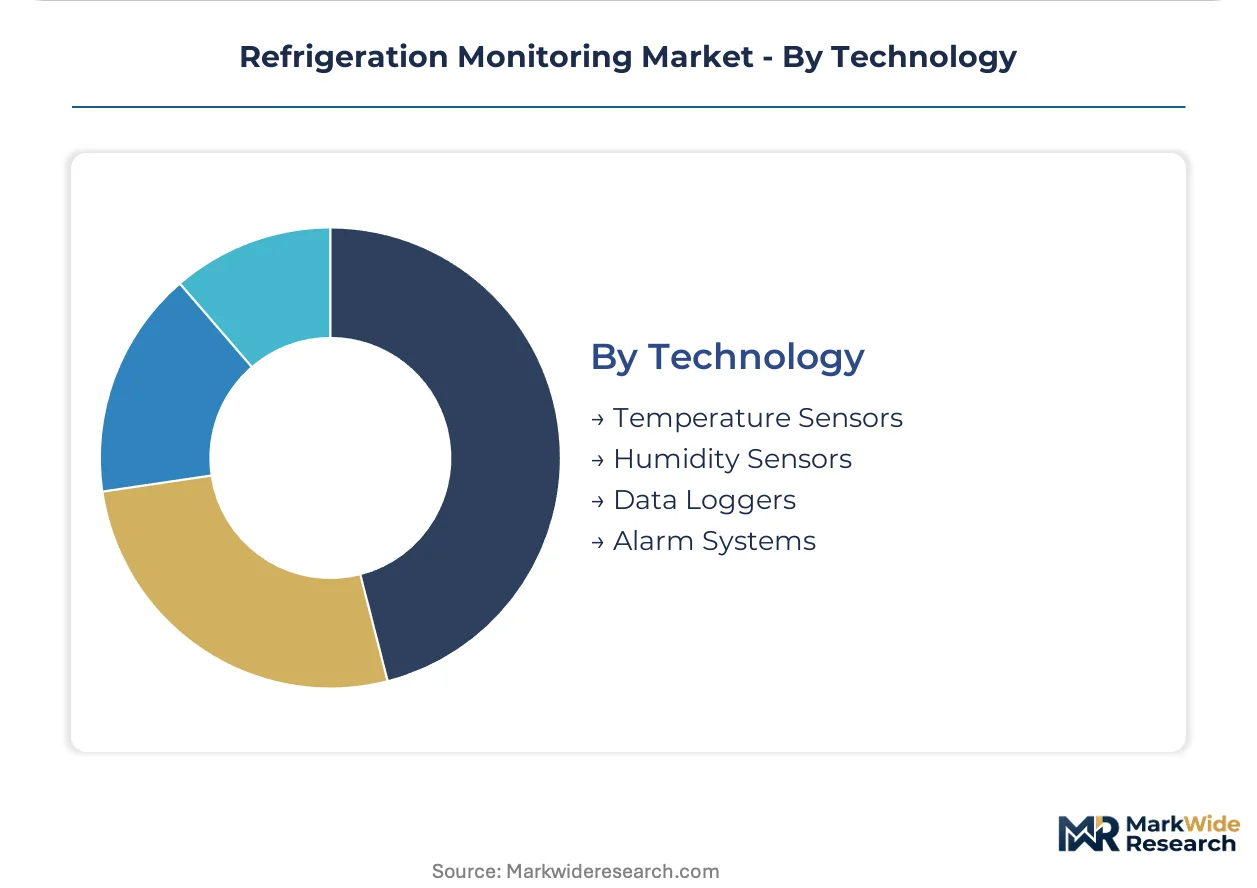
Technology:
Component supply concentration in Taiwanese MEMS foundries exposes European integrators to lead time volatility across sensor categories.
- Temperature Sensors:MEMS fabrication concentration creates minimum order quantity pressures for European system integrators. Self-calibrating platinum resistance thermometers with embedded reference junctions are displacing third-party metrology service contracts that previously consumed fifteen to twenty percent of annual monitoring budgets.
- Data Loggers:Continuous recording devices with tamper-evident functionality satisfy pharmaceutical cold chain compliance. Lithium battery supply competition from consumer electronics and electric vehicle sectors constrains disposable unit margins.
- Humidity Sensors:Secondary environmental parameter tracking integrates into standard monitoring dashboards for comprehensive payload protection.
- Alarm Systems:Real-time alert infrastructure triggers automatic service dispatch under EPA SNAP and EU F-Gas leak detection mandates.
Temperature Sensors lead by unit volume. Data Loggers show the steepest expansion trajectory through regulatory documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical buyers in Germany tolerate premium pricing for calibration-traceable systems, while food service operators in Southern Europe prioritize low-cost wireless retrofits. This elasticity split shapes vendor go-to-market strategies across regional clusters.
Germany
Pharmaceutical distribution hubs around Frankfurt and Munich drive demand for EU MDR-compliant continuous data loggers with tamper-evident audit trails. The country's national pharmaceutical regulator enforces strict temperature documentation requirements for cold chain distribution. Baden-Württemberg hosts compressor OEMs extending into predictive diagnostics through installed base leverage.
United States
EPA SNAP refrigerant regulations and California CARB mandates accelerate leak detection sensor deployment in supermarket chains. FDA 21 CFR Part 11 shapes pharmaceutical cold chain product design through electronic signature and audit trail requirements. Cold storage concentration in the Midwest and California triggers fleet-scale cellular logger deployments for transportation monitoring.
Netherlands
Third-party logistics consolidation around Rotterdam and Amsterdam unbundles hardware and software procurement decisions. EU MDR temperature documentation mandates force pharmaceutical distributors toward subscription-based cloud platforms. Distribution hub concentration enables standardized fleet-wide specifications across multiple carrier relationships.
India
FSSAI food safety modernization rules create first-mover opportunities for monitoring-as-a-service platforms in tier-two cities beyond Mumbai and Delhi. The country's food safety regulator lacks enforcement bandwidth outside major metros, opening compliance gaps for early entrants. Cold chain infrastructure underinvestment in Gujarat and Karnataka drives retrofit wireless sensor demand.
France
Food service operators deploy LoRaWAN sensor networks to bypass wired infrastructure costs in restaurant and retail retrofits. EU F-Gas Regulation phasedown schedules mandate refrigerant leak detection integration into thermal monitoring platforms. The Île-de-France region anchors pharmaceutical logistics demand alongside growing food service automation.
Refrigeration Monitoring Market Vendor Landscape
Capability concentration sits with compressor OEMs possessing installed base data; scale advantage sits with fleet-scale cellular platform operators. The vendor ecosystem fragments across hardware specialists, cloud-native software platforms, and integrated system providers. Two strategic archetypes dominate: predictive service contractors leveraging equipment footprints, and interoperability-focused platforms unbundling hardware from analytics. Competitive moves center on API ecosystem expansion and predictive maintenance contract penetration.
Within the integrated systems tier, Emerson Electric and Danfoss occupy positions anchored by compressor manufacturing heritage and proprietary sensor-to-cloud protocols. Samsara exemplifies the fleet-scale cellular platform archetype, competing on transportation monitoring deployments across North American logistics networks. These three represent contrasting strategic vectors—equipment-installed-base extension versus cloud-native scale aggregation—shaping procurement team vendor consolidation decisions.
| Leading Market Players |
|---|
| Emerson Electric |
| Danfoss |
| Sensaphone |
| Monnit |
| Zebra Technologies |
| Texas Instruments |
| ORBCOMM |
| Samsara |
| Vaisala |
| Others |
Supply Flow & Price Mechanics
Taiwanese MEMS foundry clusters in Hsinchu and Tainan anchor global temperature sensor fabrication, translating wafer capacity tightness directly into pricing leverage for European system integrators facing minimum order quantity floors. Pharmaceutical buyers absorbing premium pricing for ISO 17025-traceable calibration protocols subsidize margin compression in food service wireless logger segments where lithium battery costs compete with electric vehicle procurement.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical cold chain procurement, with EU MDR-compliant data logger subscriptions locking distributors into multi-year SaaS tiers that bundle hardware refresh cycles. Price differentiation hinges on calibration certification grade—ISO 17025-traceable units command three-tier separation from standard CE-marked probes—and geographic delivery cost premiums for field service deployment. Cost compression in disposable wireless logger tiers is intensifying because cylindrical lithium cell supply competition from consumer electronics erodes unit economics. Food service operators in Southern Europe exhibit highest price sensitivity, while German pharmaceutical distributors tolerate premium positioning for audit-trail compliance.
Supply Chain Analysis
Upstream feedstock concentration in Taiwanese MEMS fabrication, South Korean battery cell production, and Chinese PCB assembly exposes monitoring hardware vendors to cross-border logistics chokepoints. Raw material dependencies center on platinum resistance wire for precision thermometry, lithium cobalt oxide cathodes for wireless power, and epoxy encapsulants for probe durability. Single-source vulnerability concentrates in 8-inch wafer foundry capacity for temperature sensor die production. Distribution runs through compressor OEM captive channels and independent IoT platform marketplaces in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of ISO 17025-traceable calibration technicians outside Germany and Switzerland constrains market expansion, privileging vendors who internalize metrology capabilities or automate validation workflows.
For Market Incumbents: Entrench predictive service contract penetration across pharmaceutical installed bases before cloud-native platforms decouple analytics from hardware. Compressor OEMs must defend channel control through proprietary sensor-to-cloud protocols that resist API standardization pressures from unbundling procurement teams. Capacity addition in Baden-Württemberg calibration centers addresses technician scarcity threatening service margin expansion. For New Entrants and Emerging Players: Pursue tier-two Indian cities where FSSAI enforcement gaps create monitoring-as-a-service white space outside Mumbai and Delhi. Edge AI inference at the sensor node offers the most penetrable technology wedge against incumbent cloud-dependent architectures. Direct-to-fleet sales models bypass compressor OEM channel capture in North American transportation monitoring. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because pharmaceutical cold chain documentation mandates harden irreversibly across FDA and EU jurisdictions. Acquisition targets should concentrate on software platforms with demonstrated API interoperability across hardware agnostic deployments. The signal to watch is consolidation velocity among third-party logistics providers unbundling procurement decisions.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Unbundled procurement by DHL Supply Chain and Kuehne+Nagel forces demonstrated interoperability across carrier relationships. |
| Edge AI Sensor Development | On-device anomaly detection reduces cloud transmission costs for biologics manufacturers with excursion-sensitive payloads. |
| Calibration Automation Investment | Self-calibrating platinum resistance thermometers displace third-party metrology contracts consuming fifteen to twenty percent of monitoring budgets. |
| Refrigerant Leak Detection Integration | EPA SNAP and EU F-Gas Regulation mandates bundle environmental compliance with thermal integrity tracking in supermarket chains. |
| Ultra-Low Temperature Hardware Extension | mRNA vaccine distribution protocols below -70°C open premium segments beyond traditional pharmaceutical sensor ranges. |
Methodological Framework
A spread of perspectives from cold storage facility engineers, pharmaceutical quality assurance directors, fleet operations managers at third-party logistics providers, and compressor OEM service heads converged on the working assumptions underlying segment sizing. Primary fieldwork combined structured interviews with secondary validation through FDA 21 CFR Part 11 guidance documents, EU MDR technical documentation requirements, EPA SNAP regulatory filings, and FSSAI food safety modernization circulars. Bottom-up sensor shipment estimates triangulated against top-down cold chain infrastructure investment flows.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with modeled segmentation spanning deployment architecture, end-user compliance tier, application environment, and sensor technology category. CAGRs derived from fitted adoption curves calibrated to regulatory mandate effective dates and infrastructure investment cycles. Forecast inputs incorporated lithium battery supply constraints from competing electric vehicle demand and MEMS foundry capacity utilization rates.
Sensitivities concentrate around enforcement bandwidth variance in emerging market regulators, lithium cell commodity price volatility, and protocol standardization timing affecting vendor lock-in dynamics. Cross-checking against cold chain infrastructure investment disclosures from major pharmaceutical distributors is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
IO Link Market
Sensors
Ultrasonic Technologies Market
Sensors
Industrial Automation Sensors Market
Sensors
Europe Lidar Market
Sensors
Residential Water Leak Detection System Market
Sensors
RFID Smart Cabinet Market
Sensors
Facial Tracking Solution Market
Sensors
Smart Barcode Readers Market
Sensors
Traffic Sensor Market
Sensors
Asset Tracking Market
Sensors
Vibration Monitoring Market
Sensors
Eye Tracking Solutions Market
Sensors
Global RFID Market
Sensors
Automated Weather Observation System Market
Sensors
Body Area Network Market
Sensors
Location-Based Ambient Intelligence Market