
 Underground Utility Mapping Market | 2026-2036
Underground Utility Mapping Market Size, Share, and Industry Trends Forecast 2026-2036
Underground Utility Mapping Market Intelligence
Aftermarket service revenue from utility data licensing and subscription-based mapping updates is tilting toward recurring-margin models. Hexagon AB leverages its sensor-to-software portfolio to capture lifecycle contracts across municipal clients. Radiodetection Ltd anchors electromagnetic locator sales through dense distributor networks in North American construction channels. GSSI Geophysical Survey Systems, Inc. specializes in ground-penetrating radar hardware for geotechnical firms requiring penetration depths below four meters.
Underground utility mapping encompasses geophysical detection, spatial data integration, and three-dimensional visualization of buried infrastructure including pipelines, cables, and transit tunnels. Electromagnetic induction and ground-penetrating radar systems typically operate at frequencies between 10 MHz and 2.6 GHz, resolving metallic and non-metallic targets to depths exceeding ten meters in favorable soil conditions. GPR technology commands the largest installed base among detection modalities, though laser scanning segments are expanding fastest as mobile LiDAR platforms integrate with subsurface datasets. Consulting services carry elevated margins where engineering firms bundle risk assessment with regulatory compliance documentation.
The Federal Communications Commission's broadband equity programs mandate call-before-you-dig coordination, while OSHA excavation standards enforce pre-construction utility verification. The EPA's stormwater and combined sewer overflow consent decrees drive municipal investment in accurate sewer lateral location. Stakeholders must weigh capital deployment between electromagnetic hardware refresh cycles and cloud-native data platforms that federate legacy CAD records with real-time mobile capture.
Market Dynamics
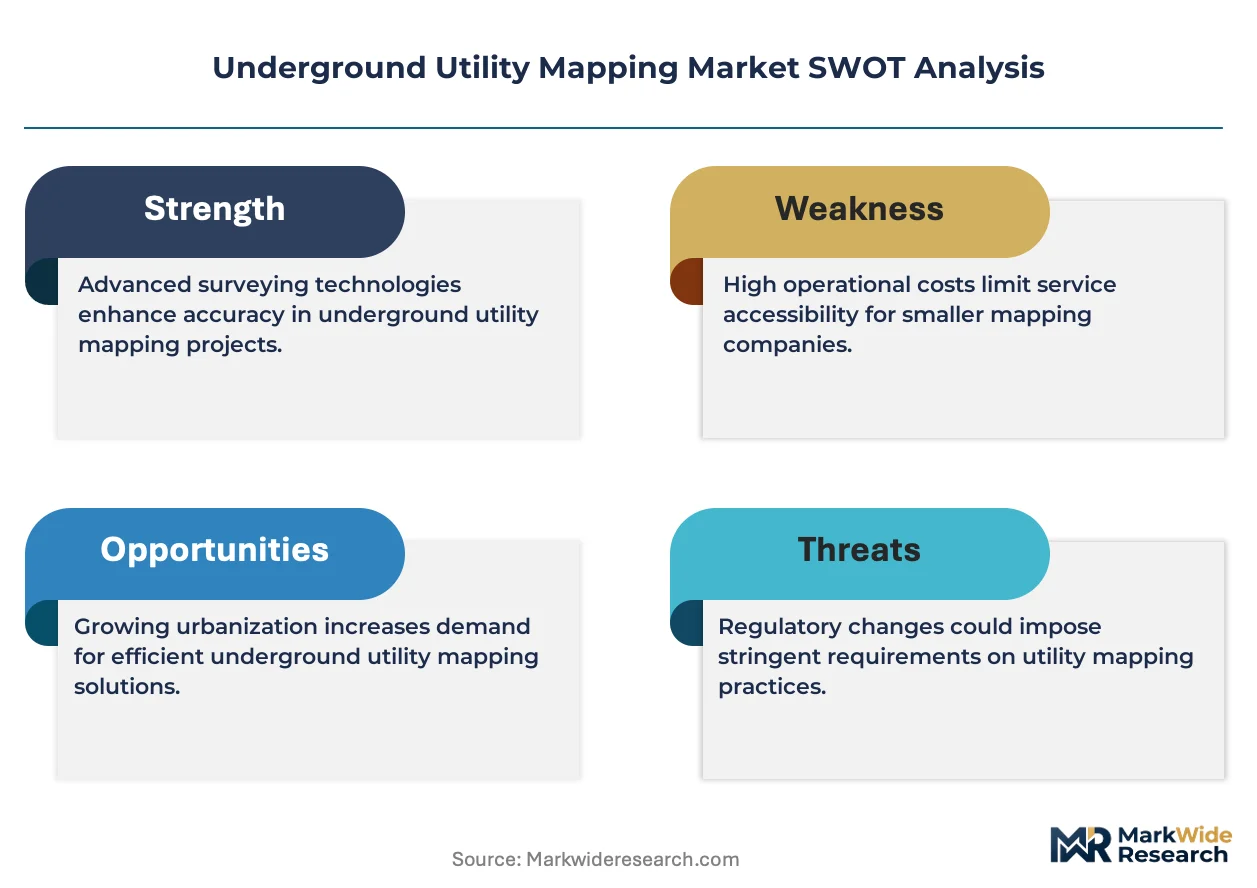
The underground utility mapping sector faces intensifying pressure from overlapping excavation demands as fiber-optic broadband deployment collides with century-old water infrastructure replacement cycles, forcing asset owners to consolidate fragmented subsurface records into unified geospatial platforms.
Growth Catalysts
- FCC Broadband Equity Mandates:Call-before-you-dig coordination requirements under federal broadband programs are accelerating municipal investment in verified utility location databases across the United States.
- Electromagnetic-GPR Sensor Fusion:Combined detection modalities are resolving metallic and non-metallic targets in single passes, reducing field verification time for geotechnical contractors.
- Stormwater Consent Decrees:EPA enforcement actions on combined sewer overflows are compelling cities to map sewer laterals with centimeter-grade accuracy.
Market Restraints
- High-Purity Germanium Detector Costs:Supply constraints in semiconductor-grade germanium for gamma-ray spectroscopy are inflating hardware procurement budgets for nuclear utility mapping.
- Clay-Rich Soil Signal Attenuation:High-conductivity substrates in the Gulf Coast region degrade GPR penetration depth below two meters, limiting single-modality deployments.
- OSHA Excavation Standard Variability:State-level interpretation differences in pre-construction verification rules create compliance fragmentation for national contractors.
Strategic Opportunities
- Subscription Data Licensing:Cloud-native platforms offering real-time map updates are capturing recurring revenue from municipal public works departments.
- Mobile LiDAR-GPR Integration:Vehicle-mounted platforms combining above-ground laser scanning with subsurface radar are opening highway corridor mapping contracts.
- India Smart Cities Mission:Urban infrastructure digitization programs are creating first-mover advantages for integrated detection-service providers in metropolitan water authority tenders.
Industry Challenges
- Geophysicist Talent Scarcity:Interpretation of multi-frequency GPR returns requires specialized training that outpaces university program output.
- Legacy CAD Record Migration:Paper-based utility as-builts from the 1970s-1980s resist automated vectorization, forcing manual digitization at utility-scale cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underground Utility Mapping Market |
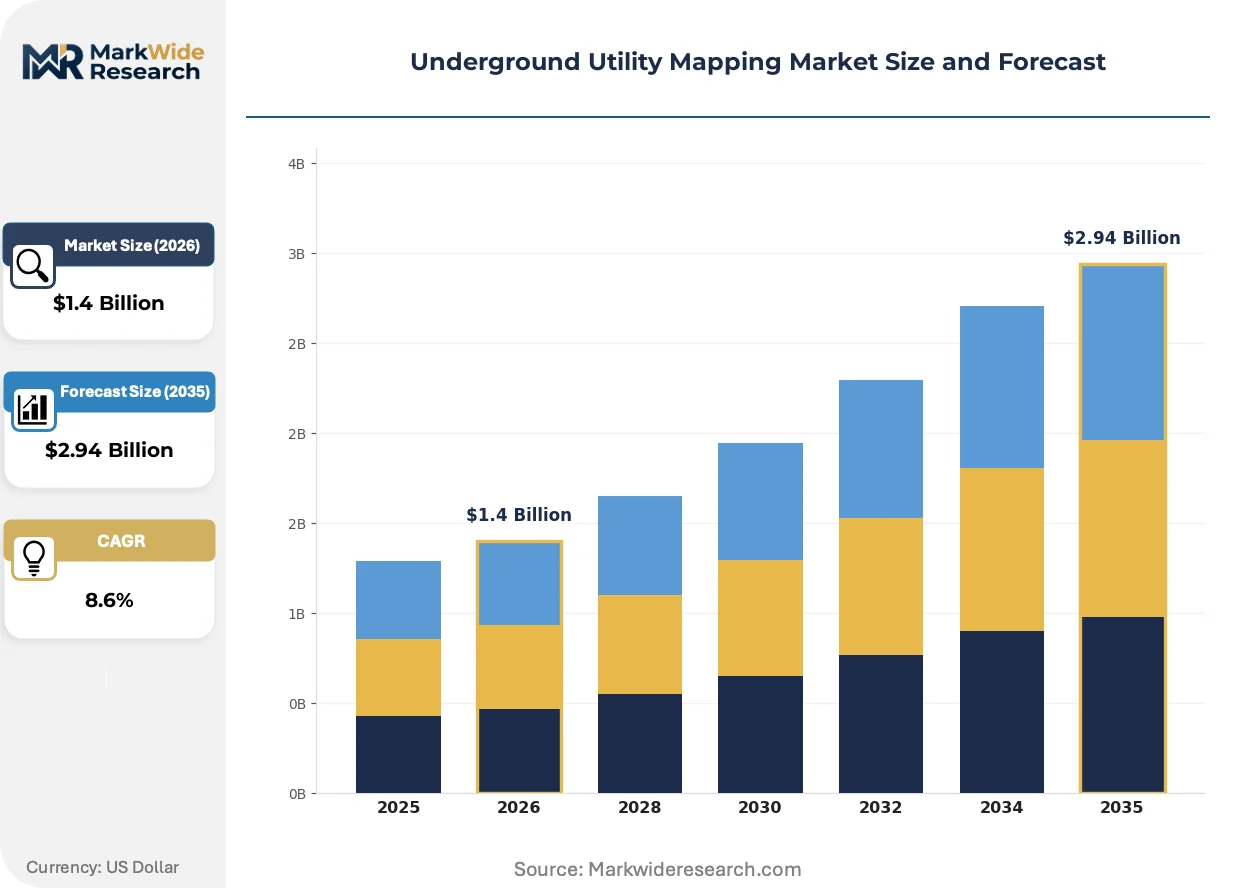
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mapping, Surveying, Consulting, Maintenance Technology: GPR, Electromagnetic, GPS, Laser Scanning End User: Construction Firms, Utility Companies, Government Bodies, Engineering Firms Application: Civil Engineering, Environmental Assessment, Infrastructure Management, Asset Location |
| Companies Covered | Hexagon AB, Leica Geosystems AG, GSSI Geophysical Survey Systems, Inc., Vivax-Metrotech Corp., Radiodetection Ltd, Sensors & Software Inc., Guideline Geo, IDS GeoRadar, US Radar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underground Utility Mapping Market Strategic Shifts & Innovations
Detection hardware and data platforms are converging around real-time fusion workflows that collapse the traditional gap between field capture and engineering deliverables. Three developments are compressing project timelines and reshaping competitive positioning.
Multi-channel ground-penetrating radar arrays are hybridizing electromagnetic and acoustic sensing in single hardware units, enabling simultaneous detection of metallic conduits and non-metallic plastic pipes. Municipal engineering firms in Texas and California are deploying these units for water main replacement pre-location. The technology is hybridizing service delivery models by collapsing separate electromagnetic and GPR contractor roles into unified field teams.
Europe's CSRD sustainability disclosure rules are mandating infrastructure asset condition reporting that requires verified subsurface utility inventories for embodied carbon calculations. Construction firms bidding on EU-funded projects must now submit georeferenced utility maps as compliance documentation. German and French civil engineering contractors are responding by embedding certified utility locators directly into project environmental teams.
Utility data procurement is consolidating around platform subscriptions that displace per-project survey contracts. Municipal asset managers in Australia and Canada are shifting from commissioning one-off locating services to annual licensing agreements with cloud-hosted map repositories. This behavioral shift is most visible among water utilities managing over ten thousand kilometers of buried pipe, where real-time update capabilities outweigh static survey accuracy.
Underground Utility Mapping Market Segmentation
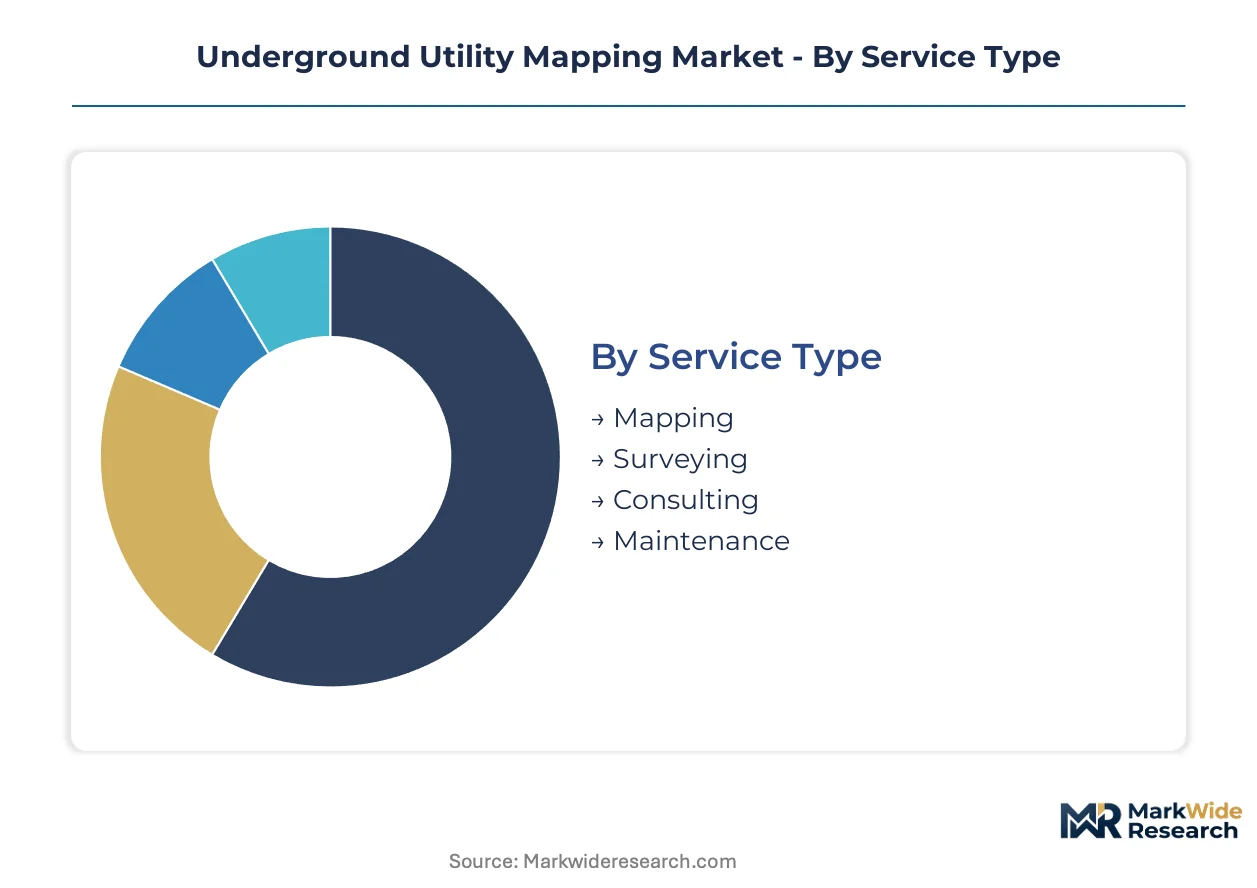
Underground utility mapping vendors structure offerings around distinct service delivery models, detection technologies, buyer archetypes, and use-case verticals. Each segmentation axis reveals divergent margin profiles and contract renewal patterns that shape go-to-market design.
Service Type:
Mature inspection workflows coexist with emerging predictive maintenance subscriptions across the service portfolio.
- Mapping:Georeferenced utility inventories compiled from field verification and legacy record fusion. Water utilities in Texas and California commission these datasets for main replacement programs under EPA consent decrees.
- Surveying:Centimeter-grade topographic and subsurface capture for engineering-grade deliverables. Demand concentrates with civil contractors bidding on federally funded broadband trenching projects requiring pre-construction verification.
- Consulting:Risk assessment and regulatory compliance documentation bundled with detection services.
- Maintenance:Subscription-based map refresh cycles and anomaly monitoring.
Mapping retains volume leadership; Maintenance holds the steepest expansion curve.
Technology:
Cost tiers separate established electromagnetic hardware from premium sensor fusion platforms.
- GPR:Ground-penetrating radar systems operating between 10 MHz and 2.6 GHz resolve metallic and non-metallic targets to depths exceeding ten meters in favorable soil conditions. Municipal agencies deploy GPR for sewer lateral location in sandy substrates across the southeastern United States.
- Electromagnetic:Induction-based locators detect conductive utilities through dense distributor networks serving North American construction channels. Clay-rich Gulf Coast soils degrade penetration, forcing multimodal deployments.
- GPS:Satellite positioning integration for real-time georeferencing of field captures.
- Laser Scanning:Mobile LiDAR platforms integrating above-ground point clouds with subsurface datasets.
GPR dominates installed base; Laser Scanning climbs the fastest as highway corridor mapping contracts expand.
End User:
Customer type determines contract structure, with public procurement cycles differing sharply from private sector urgency.
- Construction Firms:Project-based utility verification for excavation safety compliance. OSHA pre-construction mandates drive recurring spend among national contractors operating across multiple state jurisdictions.
- Utility Companies:Asset owners managing buried infrastructure lifecycle data. Electric and water utilities commission annual map licensing rather than one-off surveys.
- Government Bodies:Municipal public works departments and federal broadband program administrators.
- Engineering Firms:Geotechnical and civil engineering practices bundling detection with design services.
Utility Companies anchor recurring revenue; Construction Firms generate the highest transaction velocity.
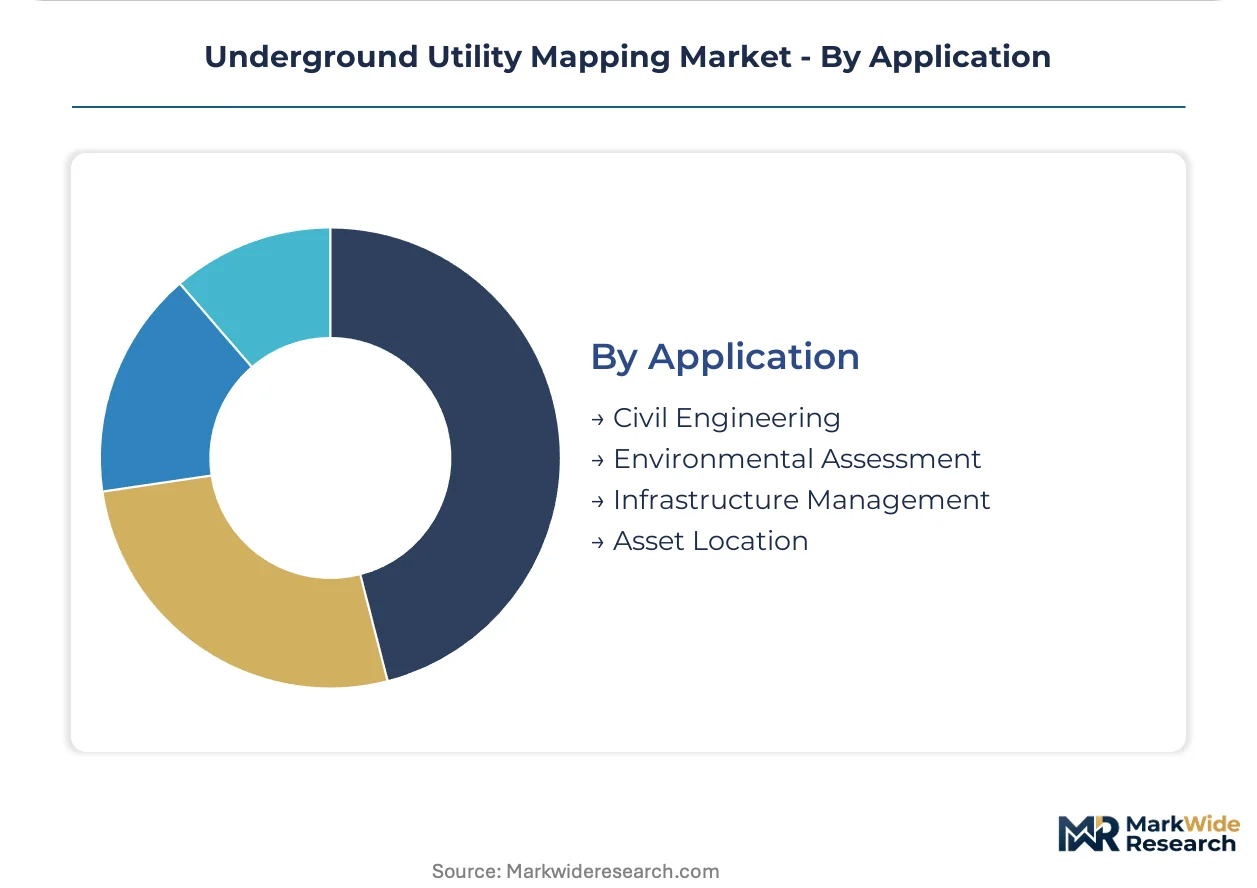
Application:
Volume concentrates in infrastructure replacement cycles, while environmental compliance opens premium pricing.
- Civil Engineering:Pre-construction utility location for transportation, building, and broadband projects. State departments of transportation in Florida and Ohio mandate verified subsurface inventories for federal-aid highway contracts.
- Environmental Assessment:Contaminated site characterization requiring precise utility location before soil sampling. EPA enforcement actions on combined sewer overflows compel centimeter-grade sewer lateral mapping.
- Infrastructure Management:Asset condition monitoring and replacement prioritization.
- Asset Location:Emergency response and damage prevention for existing facility networks.
Civil Engineering commands the largest project scale; Environmental Assessment carries the highest margin per square kilometer surveyed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with the United States emphasizing broadband-trenching verification while European markets prioritize sustainability-linked asset disclosure and Asian markets focus on smart-city digitization mandates.
United States
FCC broadband equity programs and century-old water main replacement cycles generate overlapping excavation demand. OSHA pre-construction verification standards enforce utility location compliance across state transportation departments. Texas and California municipal agencies deploy combined electromagnetic-GPR arrays for sewer lateral mapping under EPA consent decrees.
Germany
CSRD sustainability disclosure rules mandate verified subsurface inventories for infrastructure embodied carbon calculations. The national civil engineering regulator requires georeferenced utility documentation for federally funded construction bids. Engineering contractors in Bavaria and North Rhine-Westphalia embed certified locators within environmental compliance teams.
United Kingdom
Highway England corridor mapping contracts drive mobile LiDAR-GPR platform adoption for pre-construction verification. The national call-before-you-dig coordination framework mandates standardized utility record submission. Greater London water utilities commission subscription-based map licensing for real-time lateral location updates.
India
Smart Cities Mission urban digitization programs create tender opportunities for integrated detection-service providers. The Central Public Works Department mandates subsurface verification for metro rail and water authority projects. Maharashtra and Karnataka metropolitan water authorities issue multi-year mapping contracts for buried asset inventory consolidation.
Australia
Water utilities managing extensive buried pipe networks shift from per-project surveys to annual platform subscriptions. State-level public works departments in New South Wales and Victoria require real-time map update capabilities for emergency response coordination. Consulting firms bundle risk assessment with cloud-hosted utility repositories for municipal clients.
Underground Utility Mapping Market Key Industry Players
Capability concentration sits with sensor-software integrated specialists; scale advantage sits with distributor-networked hardware vendors. The vendor base organizes around three strategic archetypes: electromagnetic equipment manufacturers, ground-penetrating radar specialists, and full-stack platform providers bundling field capture with data licensing. Dominant competitive moves include technology licensing partnerships between hardware OEMs and cloud platform developers, plus backward integration into proprietary sensor arrays.
Among Swedish-based technology conglomerates, Hexagon AB exemplifies the full-stack archetype through sensor-to-software portfolio breadth. Radiodetection Ltd occupies a position within electromagnetic locator supply through dense North American distribution channels. GSSI Geophysical Survey Systems, Inc. anchors the GPR specialist tier with hardware configurations targeting geotechnical penetration requirements below four meters.
| Leading Market Players |
|---|
| Hexagon AB |
| Leica Geosystems AG |
| GSSI Geophysical Survey Systems, Inc. |
| Vivax-Metrotech Corp. |
| Radiodetection Ltd |
| Sensors & Software Inc. |
| Guideline Geo |
| IDS GeoRadar |
| US Radar Inc. |
| Others |
Cost & Logistics Intelligence
High-purity germanium detector manufacturing concentrates in specialized semiconductor foundries across Germany and Japan, concentrating margin capture in the gamma-ray spectroscopy hardware tier while downstream platform providers extract recurring revenue from municipal software subscriptions. This upstream concentration forces electromagnetic equipment vendors to absorb component cost volatility or pass through price adjustments to construction contractor buyers.
Pricing Analysis
Project-based contracting dominates utility verification services, though subscription licensing for cloud-hosted map repositories is displacing one-off survey commissions among water utilities managing extensive pipe networks. Price differentiation rests on certification grade for electromagnetic locators and penetration depth specifications for GPR arrays. Cost compression in entry-level electromagnetic hardware intensifies as Asian manufacturers expand distribution through North American construction channels. Municipal public works departments exhibit lowest price sensitivity due to EPA consent decree compliance mandates, while independent geotechnical contractors face acute margin pressure from bid-competitive highway corridor projects.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for ground-penetrating radar OEMs sourcing printed circuit assemblies and antenna substrates. Manufacturing concentration spans the United States for precision electromagnetic sensors, Sweden for integrated sensor-software platforms, and China for cost-optimized GPR components. Raw material dependencies include high-purity germanium for nuclear utility detection, lithium niobate for acoustic sensing arrays, and specialized ferrites for electromagnetic induction coils. Distribution runs through dense North American construction equipment dealer networks for hardware, while platform subscriptions deploy direct-to-municipal SaaS sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Underground utility mapping presents a service-attach opportunity where annual map licensing and real-time update subscriptions expand faster than hardware replacement cycles, particularly among water utilities consolidating fragmented legacy records.
For Market Incumbents: Harden platform stickiness by embedding certified utility locators within municipal engineering departments through multi-year lifecycle contracts that bundle hardware refresh with cloud data hosting. Deepen backward integration into proprietary multi-channel GPR arrays to differentiate from commodity electromagnetic locator competition. Prioritize EPA consent decree compliance documentation as a defensive moat against regional engineering firms bundling detection with design services. For New Entrants and Emerging Players: Build out mobile LiDAR-GPR integration capabilities targeting highway corridor mapping contracts where state transportation departments mandate verified subsurface inventories for federal-aid projects. Penetrate the India Smart Cities Mission tender pipeline by partnering with metropolitan water authorities in Maharashtra and Karnataka for buried asset inventory digitization. Lead with subscription-based pricing that displaces per-project survey relationships among Australian and Canadian municipal utilities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electromagnetic equipment manufacturers lacking cloud platform capabilities and facing hardware margin compression from Asian competitors. Five-to-ten-year viability favors full-stack providers with sensor-to-software integration and recurring revenue depth. Monitor municipal procurement shifts from one-off surveys to annual platform licensing as the inflection signal for valuation multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Combines electromagnetic and GPR modalities into single-pass field capture, collapsing contractor roles and accelerating project timelines for Texas municipal water authorities. |
| Cloud-Native Data Licensing Expansion | Captures recurring revenue from Australian and Canadian utilities shifting from per-project surveys to annual subscription agreements with real-time map update capabilities. |
| Certified Locator Workforce Embedding | Positions detection specialists within German and French civil engineering environmental teams responding to CSRD sustainability disclosure mandates for infrastructure asset condition reporting. |
| Highway Corridor Mapping Partnership | Secures vehicle-mounted LiDAR-GPR contracts with Highway England and state departments of transportation in Florida and Ohio for pre-construction verification compliance. |
| Legacy CAD Record Migration Services | Addresses manual digitization bottlenecks for 1970s-1980s paper utility as-builts through specialized vectorization workflows targeting EPA stormwater consent decree deadlines. |
Research Approach
Desk research of municipal procurement databases, FCC broadband program filings, EPA consent decree documentation, and equipment distributor financial disclosures preceded structured interviews with municipal public works directors, geotechnical engineering firm principals, electromagnetic equipment procurement managers, and cloud platform product leads. Primary field capture validated secondary estimates of sensor deployment rates and subscription contract terms. Bottom-up triangulation across utility-scale project pipelines and top-down reconciliation against national infrastructure spending forecasts anchored market sizing.
Assumptions held fixed include sustained FCC broadband equity program funding levels, continued EPA enforcement intensity on combined sewer overflows, and stable semiconductor-grade germanium supply availability. Variables stress-tested across the projection horizon encompass state-level OSHA excavation standard interpretation divergence, Gulf Coast soil conductivity degradation effects on GPR penetration depth, and municipal fiscal capacity for preventive infrastructure digitization versus reactive damage response. Segmentation dimensions modeled include service delivery model, detection technology modality, end-user archetype, and application vertical with regional regulatory cluster overlays.
Stress conditions across broadband deployment pace, municipal bond financing costs, and geophysicist labor market tightness were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology adoption curves and procurement behavioral shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Gesture Recognition in Retail Market
Sensors
Global Radio Frequency Identification (RFID) Smart Cabinet Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Yield Monitoring Systems Market
Sensors
Eye Tracking Market
Sensors
Safety Motion Control System Market
Sensors
Sensor Landscape in Robotics and ADAS Vehicle Market
Sensors
Barcode Scanner Market
Sensors
Smart Mat Market
Sensors
Connected Smart Thermostats Market
Sensors
Location-Based Ambient Intelligence Market
Sensors
Consumer 3D Sensing Products Market
Sensors
Traffic Sensor Market
Sensors
Smart Barcode Readers Market
Sensors
Personal Navigation Devices Market
Sensors
In-Counter Barcode Scanners Market