
 Global Digital Thermostats Market | 2026-2036
Global Digital Thermostats Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Thermostats Market Analysis
The capital-intensity divergence between in-house semiconductor fabrication and outsourced controller assembly is bifurcating competitive tiers. Honeywell International leverages captive sensor production to sustain margin structures across premium installations. Google Nest competes through cloud-native architecture that anchors recurring software revenue streams. Ecobee specializes in utility-partnership channels, positioning its devices within demand-response programs operated by regional power authorities.
Digital thermostats are electronic climate-control devices incorporating microprocessor-based temperature sensing, relay switching, and communication protocols to regulate heating, ventilation, and air conditioning systems. These devices typically operate within 24V AC control circuits and employ thermistors or resistance temperature detectors with accuracy thresholds of ±0.5°C for commercial-grade units. Smart thermostat configurations with Wi-Fi connectivity and machine-learning algorithms now dominate residential retrofit pipelines, while programmable thermostat segments retain stable replacement demand across legacy commercial building stock. Energy management feature sets command premium positioning as utility rate structures introduce time-of-use pricing across multiple state jurisdictions.
FCC certification requirements govern wireless transmission protocols in the United States, while CE marking and the EU F-Gas Regulation establish efficiency benchmarks for European product entry. China's GB standards and NMPA-equivalent quality frameworks shape import compliance for connected home devices. Stakeholders must monitor how fragmented cybersecurity mandates across national regulators reshape firmware update obligations and cloud data residency requirements.
Market Dynamics
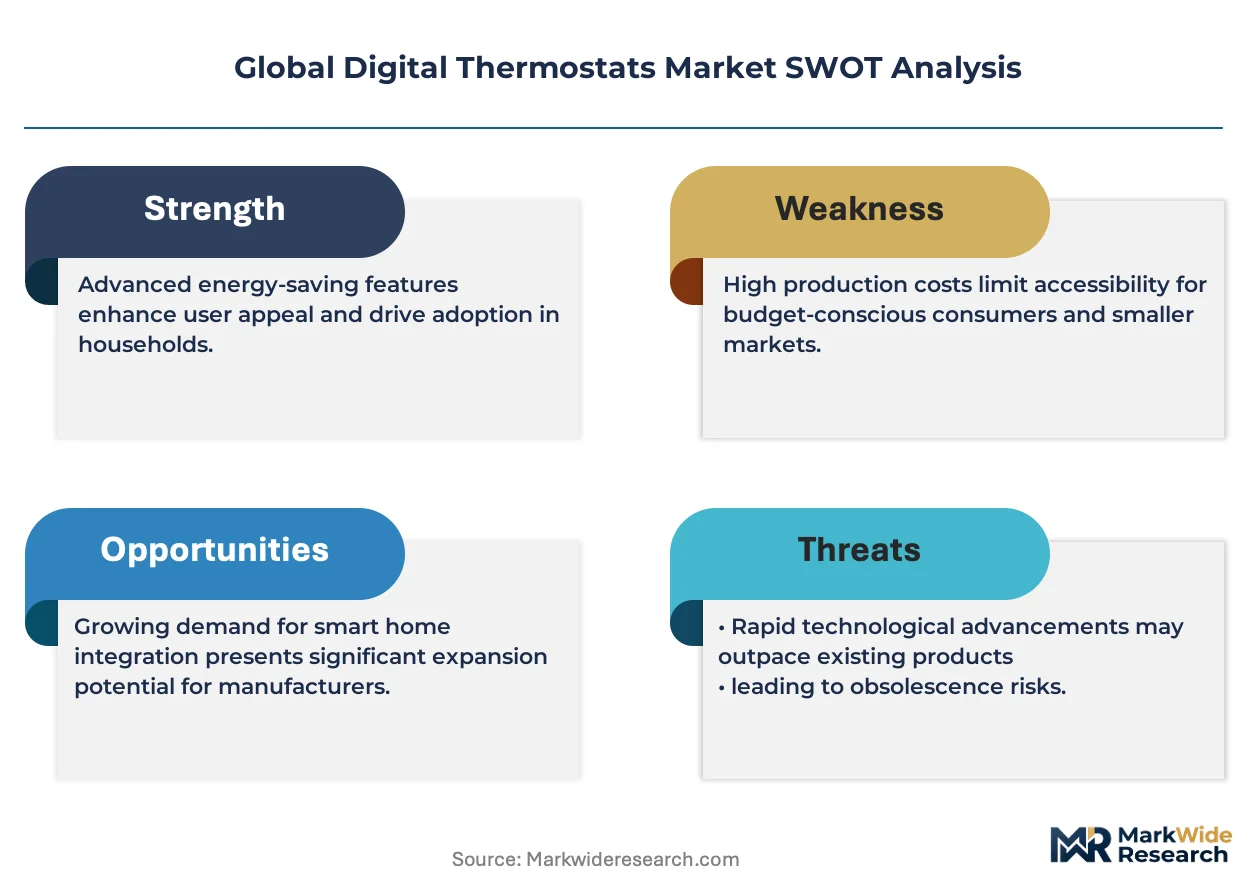
The EU F-Gas Regulation and EPA refrigerant mandates are compressing replacement cycles while bifurcating competitive tiers between captive semiconductor producers and outsourced controller assemblers.
Growth Catalysts
- Utility rate restructuring:Time-of-use pricing across multiple US state jurisdictions accelerates demand-response thermostat installations in residential retrofits.
- EU F-Gas Regulation:Efficiency threshold tightening forces HVAC system upgrades, pulling connected climate controls into commercial building automation pipelines.
- Machine-learning algorithms:Wi-Fi-enabled devices with predictive temperature adjustment are displacing programmable thermostats in Germany's residential replacement market.
Market Restraints
- Semiconductor supply concentration:Thermistor and microprocessor sourcing bottlenecks in East Asian foundries constrain controller production scaling.
- 24V AC legacy infrastructure:Pervasive existing control circuits in US commercial building stock slow smart thermostat penetration requiring C-wire installation.
- Cybersecurity compliance fragmentation:Divergent national firmware update mandates and cloud data residency rules inflate certification costs for multi-market launches.
Strategic Opportunities
- Demand-response program integration:Utility-partnership channels with regional power authorities in Texas and California open direct procurement pathways bypassing retail.
- GB standards alignment:China's connected home device quality frameworks create entry points for certified products in smart grid investment zones.
- Sensor fusion convergence:Combined occupancy detection, humidity sensing, and air quality monitoring enable premium positioning in wellness-focused residential construction.
Industry Challenges
- Embedded systems firmware expertise:Shortage of engineers proficient in real-time operating systems for thermostat controllers delays product development cycles.
- Multi-protocol certification timelines:Simultaneous FCC, CE marking, and GB standards testing extends time-to-market by 8-14 months for connected devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Thermostats Market |
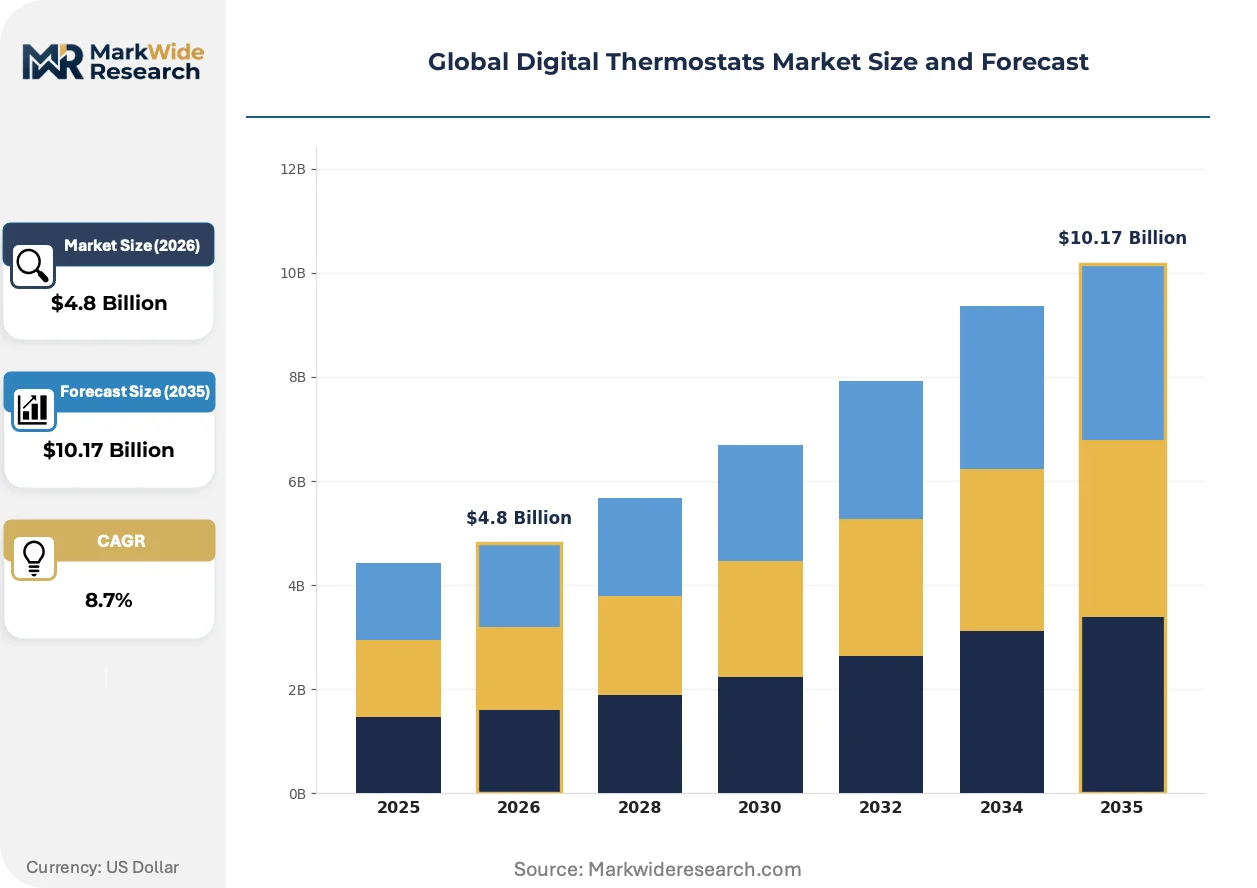
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Thermostat, Programmable Thermostat, Non-Programmable Thermostat, Wi-Fi Thermostat End User: Residential, Commercial, Industrial, HVAC Contractors Feature: Energy Management, Remote Access, Learning Capability, Compatibility Installation: Wall-Mounted, Free-Standing, Integrated System, Retro-Fit |
| Companies Covered | Honeywell International, Google Nest, Emerson Electric, Ecobee, Johnson Controls, Schneider Electric, Siemens, Carrier Global Corporation, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Thermostats Market Emerging Trajectories
Machine-learning inference at the edge is redistributing computational load away from cloud dependencies while reshaping how temperature control systems interact with broader building automation networks.
Edge AI chipsets with dedicated neural processing units are fragmenting the traditional cloud-native architecture model. Residential buyers in Germany and the United States are specifying on-device learning to reduce latency and eliminate subscription dependencies. This hardware shift is fragmenting vendor competitive positions between semiconductor-integrated players and software-centric platform operators.
EPA refrigerant phase-down schedules under the AIM Act are mandating lower-global-warming-potential alternatives in new HVAC installations. Equipment OEMs must redesign control system compatibility for refrigerant-specific operating pressures and compressor profiles. Commercial-grade thermostat segments face the steepest recertification burden as building codes in California and New York adopt the new standards earliest.
Homeowners are consolidating climate control purchasing decisions with broader smart home ecosystem selections rather than standalone device evaluations. Retail channels in the United States report bundling preference shifts toward platforms with unified app control across lighting, security, and HVAC. This behavior compresses brand switching flexibility and privileges vertically integrated platform providers in consumer consideration sets.
Global Digital Thermostats Market Segmentation
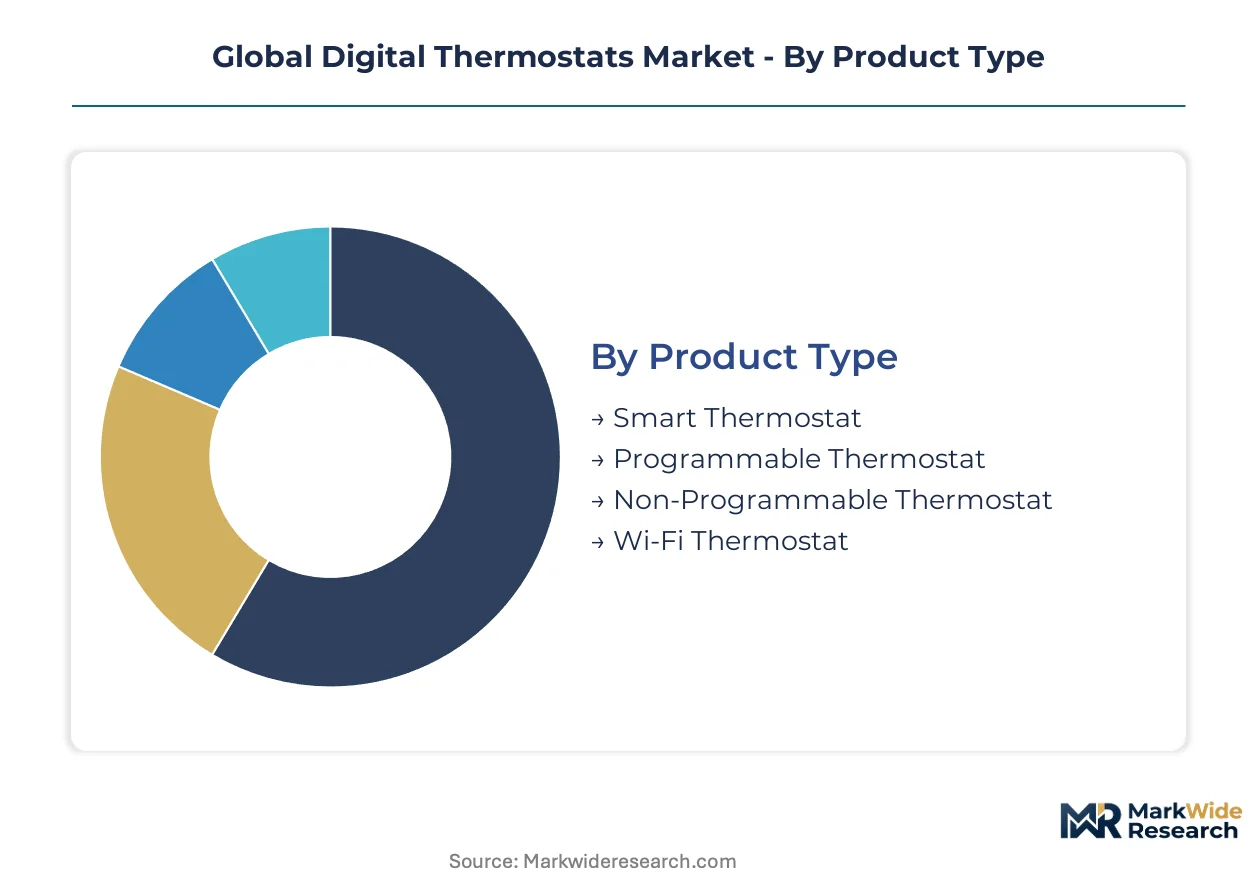
Product differentiation in digital thermostats maps directly to margin capture, with connectivity tiers and installation complexity creating distinct competitive battlegrounds. Segmentation reveals where semiconductor integration and software subscription models concentrate profitability.
Product Type:
Premium margin pools concentrate in connected devices with recurring revenue architectures, while legacy programmable segments compete on replacement cycle efficiency.
- Smart Thermostat:Microprocessor-based units with machine-learning algorithms and multi-sensor fusion dominate residential retrofit demand in Germany and the United States. Edge AI chipsets with dedicated neural processing units are fragmenting vendor positions between semiconductor-integrated players and software-centric operators.
- Wi-Fi Thermostat:Cloud-native architectures enabling remote access and utility demand-response integration command the steepest price premiums in Texas and California procurement channels. FCC certification requirements govern wireless transmission protocols, compressing time-to-market for multi-protocol launches.
- Programmable Thermostat:Retains stable replacement demand across legacy US commercial building stock with 24V AC control circuit compatibility.
- Non-Programmable Thermostat:Basic electromechanical replacements in price-sensitive construction segments with minimal feature differentiation.
The dominant share belongs to Smart Thermostat, while Wi-Fi Thermostat is closing the gap fastest.
End User:
Application-specific requirements reshape feature bundling and channel strategy across customer types.
- Residential:Homeowners consolidate climate control decisions with broader smart home ecosystem selections, privileging platforms with unified app control across lighting, security, and HVAC in US retail channels.
- Commercial:Building automation mandates under EU F-Gas Regulation and EPA refrigerant phase-downs force HVAC system upgrades, pulling connected climate controls into retrofit pipelines in California and New York.
- HVAC Contractors:Installation complexity and C-wire requirements in legacy 24V AC infrastructure create service revenue attachment opportunities.
- Industrial:Process control integration with building management systems demands ±0.5°C accuracy thresholds and hardened communication protocols.
Residential captures the volume base, though Commercial is expanding most quickly as efficiency regulations tighten.
Feature:
Functionality tiers separate subscription-dependent platforms from standalone hardware sales.
- Energy Management:Time-of-use pricing optimization across multiple US state jurisdictions commands premium positioning as utility rate structures reshape consumption economics.
- Learning Capability:Predictive temperature adjustment algorithms displace programmable schedules in Germany's residential replacement market, with on-device inference reducing cloud latency.
- Remote Access:Mobile application control has become table stakes, with cybersecurity compliance fragmentation across national firmware mandates inflating certification costs.
- Compatibility:Multi-protocol support for diverse HVAC equipment and refrigerant-specific compressor profiles faces steepest recertification burden under AIM Act phase-down schedules.
Energy Management holds the margin advantage, while Learning Capability is gaining share fastest as edge AI hardware costs decline.
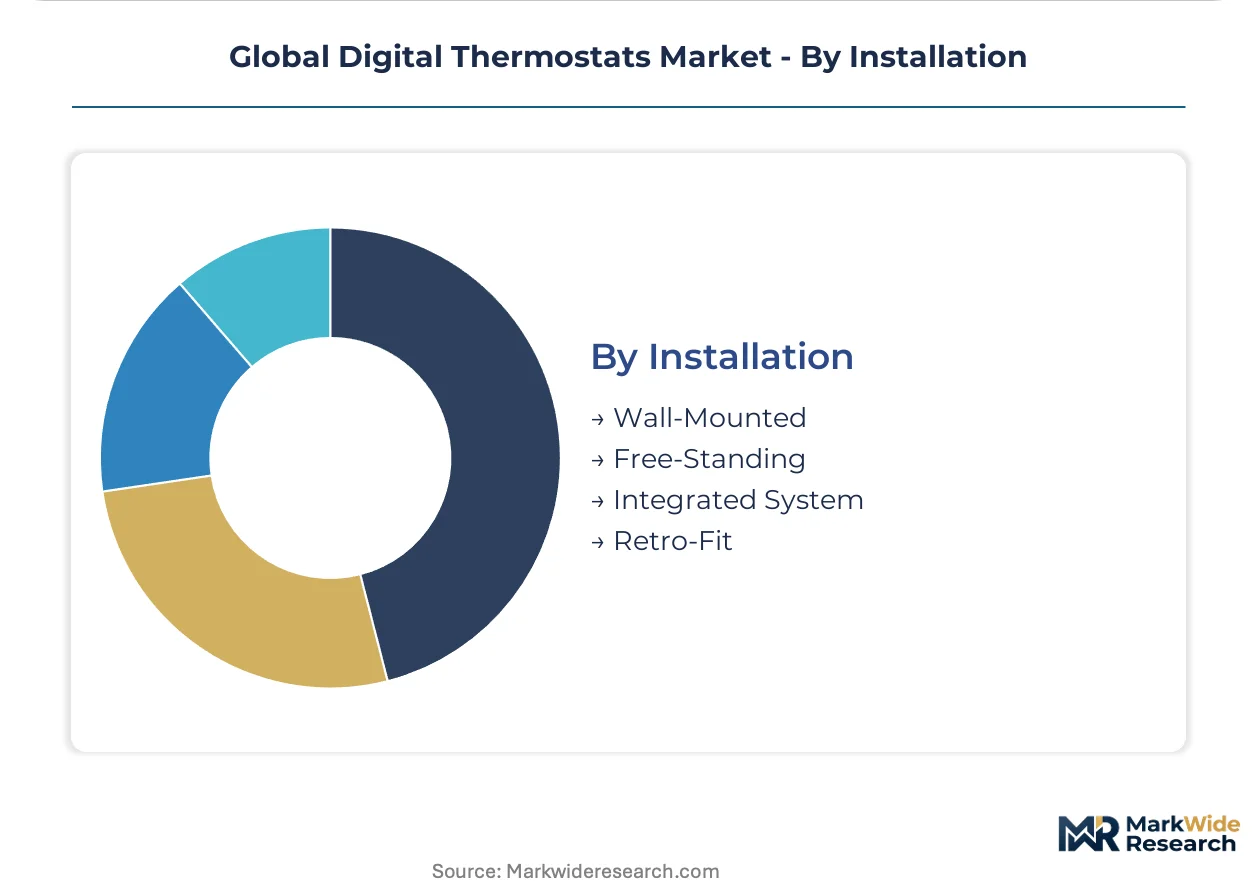
Installation:
Deployment method determines channel economics and customer acquisition cost structures.
- Retro-Fit:C-wire installation requirements in legacy US commercial building stock slow penetration but create contractor attachment revenue in residential replacement cycles.
- Wall-Mounted:Standard form factor for new construction and residential upgrades with 24V AC control circuit compatibility.
- Integrated System:Embedded controllers within OEM HVAC equipment face redesign pressure from refrigerant-specific operating pressure requirements under EPA mandates.
- Free-Standing:Portable units for supplemental zone control in renovation and light commercial applications with minimal installation infrastructure.
Retro-Fit dominates current volume, though Integrated System is climbing the fastest as new construction aligns with smart grid investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German and Japanese buyers absorb premium pricing for edge AI-enabled units, while Indian and Brazilian markets gravitate toward basic programmable models. United States demand splits between utility-subsidized smart thermostats in coastal states and cost-conscious replacement cycles in the interior.
United States
Time-of-use electricity pricing in California and Texas accelerates demand-response thermostat procurement. EPA refrigerant mandates under the AIM Act force HVAC system replacements in commercial buildings. Austin and Dallas utility districts operate direct-install programs bypassing retail channels entirely.
Germany
Residential buyers specify on-device machine learning to eliminate cloud subscription dependencies. EU F-Gas Regulation tightens efficiency thresholds for commercial building automation retrofits. Munich and Stuttgart industrial clusters concentrate HVAC OEM redesign activity for refrigerant compatibility.
China
Smart grid investments in tier-one cities pull connected climate controls into new construction pipelines. GB standards and MIIT quality frameworks shape import compliance for connected home devices. Yangtze River Delta manufacturing zones scale thermistor and microprocessor controller production.
Japan
Residential consumers prioritize humidity sensing and air quality integration in wellness-focused construction. METI efficiency standards and JIS certification requirements govern product entry. Kanto region building automation integrators specify ±0.5°C accuracy thresholds for commercial installations.
India
Price-sensitive residential construction favors non-programmable electromechanical replacements over connected devices. BIS certification and state-level energy conservation building codes create fragmented compliance landscapes. Maharashtra and Gujarat urban development authorities pilot smart grid zones with subsidized thermostat distribution.
Global Digital Thermostats Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in digital thermostats. Semiconductor-captive manufacturers control premium margin pools through in-house sensor production, while software-centric platforms compete on recurring revenue architectures. Three archetypes dominate: diversified industrial conglomerates with building automation portfolios, cloud-native consumer electronics specialists, and utility-channel specialists with demand-response integration. Consolidation pressure operates through OEM-HVAC equipment alignment and refrigerant-mandated system redesign partnerships.
Within the diversified industrial tier, Honeywell International and Emerson Electric exemplify scale-driven positions anchored by captive manufacturing capabilities. Google Nest occupies a distinct cloud-native archetype, while Ecobee represents the utility-partnership specialist model. These three companies illustrate how competitive positioning fragments between hardware-integrated and software-subscription revenue architectures.
| Leading Market Players |
|---|
| Honeywell International |
| Google Nest |
| Emerson Electric |
| Ecobee |
| Johnson Controls |
| Schneider Electric |
| Siemens |
| Carrier Global Corporation |
| ABB |
| Others |
Supply Flow & Price Mechanics
Capacity utilization rates at East Asian foundries directly determine component cost floors for thermostat controllers, concentrating margin pressure on outsourced assemblers while semiconductor-integrated players capture pricing power through captive sensor production. This scale asymmetry stratifies the vendor base between premium hardware-integrated tiers and cost-competitive software-centric platforms.
Pricing Analysis
After-sales service revenue from C-wire installation support and extended warranty contracts drives lifetime value capture for HVAC contractor channels. Three-tier pricing structure across premium, standard, and economy levels separates edge AI-enabled units with neural processing units from Wi-Fi-connected mid-tier devices and basic programmable replacements. Cost compression in the non-programmable segment is intensifying because of price-sensitive construction demand in emerging economies. Residential retrofit buyers in Germany and the United States exhibit the lowest price sensitivity, while Indian and Brazilian construction markets gravitate toward economy-tier electromechanical units.
Supply Chain Analysis
Just-in-time inventory strategies dominate thermostat assembly operations, though strategic stockpiling of thermistors and microprocessors has intensified following East Asian foundry bottlenecks. Controller production draws from Taiwan, South Korea, and China for semiconductor inputs, with Mexico and Vietnam scaling final assembly capacity. Microprocessor wafers, thermistor ceramics, and relay switches constitute critical input dependencies. Single-source vulnerability in neural processing unit fabrication poses structural risk for edge AI product lines. Distribution runs through HVAC wholesale distributors, retail home improvement chains, and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as edge AI hardware costs decline and machine-learning capability diffuses beyond cloud-native platforms, creating niche openings for specialized sensor-fusion players and regional utility-channel specialists.
For Market Incumbents: Fortify margin structures through backward integration into thermistor and microprocessor controller production, mirroring Honeywell International's captive sensor manufacturing model. Deepen channel control by embedding devices within OEM HVAC equipment partnerships as EPA refrigerant mandates force system redesigns. Certification investment in multi-protocol compliance (FCC, CE marking, GB standards) creates defensive moats against faster-moving software-centric entrants. For New Entrants and Emerging Players: Lead with demand-response program integration as the most penetrable pathway, targeting Texas and California utility districts operating direct-install procurement channels that bypass established retail shelf competition. Sensor fusion convergence combining occupancy detection, humidity sensing, and air quality monitoring offers white-space positioning in wellness-focused residential construction segments. Go-to-market execution should prioritize HVAC contractor training programs to overcome C-wire installation complexity barriers in legacy 24V AC infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semiconductor-integrated specialists with utility-channel scale over pure software-platform operators facing subscription fatigue headwinds. Long-term viability across the projection horizon rests on refrigerant-mandated HVAC system replacement cycles pulling connected controls into commercial retrofits. Acquisition target archetype: mid-cap specialists with GB standards certification and established presence in Yangtze River Delta manufacturing zones. Signal to watch: EPA AIM Act enforcement intensity in California and New York as leading indicator for commercial-grade thermostat recertification volume.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Chipset Integration | On-device neural processing reduces cloud latency and eliminates subscription dependencies for residential buyers. |
| Utility Partnership Expansion | Direct procurement pathways in Texas and California utility districts bypass retail channel saturation. |
| Multi-Protocol Certification Investment | Simultaneous FCC, CE marking, and GB standards compliance compresses time-to-market for connected devices. |
| Sensor Fusion Capability Buildout | Combined occupancy, humidity, and air quality sensing enables premium positioning in wellness construction. |
| OEM HVAC Equipment Alignment | Refrigerant-specific compressor profile compatibility under EPA mandates pulls controls into system redesigns. |
Methodological Framework
Initial hypotheses were tested against primary input from HVAC contractor operations managers, building automation integrators, utility demand-response program directors, semiconductor procurement leads, and regulatory affairs specialists at equipment OEMs, and refined through secondary validation against SEC filings, EPA regulatory dockets, EU F-Gas Regulation implementation reports, and connected home device certification databases. Bottom-up unit shipment estimates triangulated with top-down market value reconstructions.
Variance decomposition across product type, connectivity tier, end-user application, installation method, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling. Forecast inputs incorporated utility rate restructuring timelines, refrigerant phase-down schedules, and smart grid investment flows.
The analysis sits within stated boundaries; outcomes outside continued regulatory enforcement of efficiency mandates, stable East Asian semiconductor supply, and sustained utility subsidy programs would require recalibration. Forecasts reflect documented assumptions regarding technology cost curves and adoption elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Data Center Power Management Market
Energy Management Systems
Global Thermal Management Technologies Market
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
Asia-Pacific Energy Management System Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Portable Air Cooler Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Advanced Server Energy Monitoring Tools Market
Energy Management Systems
Europe Advanced Distribution Management System Market
Energy Management Systems
Africa Digital Showers Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Grid Operations Management Software Market
Energy Management Systems
Smart Climate Control Market
Energy Management Systems
Airflow Management Market