
 Mobile Lidar Scanner Market | 2026-2036
Mobile Lidar Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Lidar Scanner Market Foresight
German sensor manufacturers is rebalancing output toward solid-state architectures as automotive qualification timelines compress. Trimble Inc. leverages its construction software ecosystem to bundle hardware subscriptions, while Velodyne LiDAR, Inc. anchors its position through captive supply agreements with autonomous vehicle developers. FARO Technologies, Inc. competes on metrology-grade accuracy in factory automation inspection workflows.
A mobile lidar scanner integrates laser rangefinding, inertial measurement units, and GNSS positioning into a vehicle-mountable or backpack-portable system capable of capturing three-dimensional point clouds at frequencies exceeding one million measurements per second. The device serves primary commercial purpose in geospatial documentation, enabling rapid as-built surveying without traffic disruption or site closure. Mobile scanners and handheld scanners now command the fastest expansion trajectories as civil engineering firms phase out tripod-based static deployments; aerial scanners retain premium margin pools in corridor mapping for electric transmission lines and pipeline routes. The technology dimension shows LiDAR maintaining structural dominance while photogrammetry gains ground in heritage documentation where color fidelity outweighs geometric precision.
The EPA enforces emissions thresholds for survey fleet vehicles, indirectly accelerating electrified mobile platform adoption across US infrastructure programs. REACH compliance in Europe restricts hazardous substances in laser diode assemblies, elevating documentation burdens for component suppliers. ISO 19130 governs sensor model encoding for georeferenced imagery, shaping interoperability requirements that buyers specify in procurement tenders. Stakeholders must monitor evolving certification harmonization between FAA unmanned aircraft rules and national surveying licensure boards as drone-integrated mobile scanning crosses regulatory boundaries.
Market Dynamics
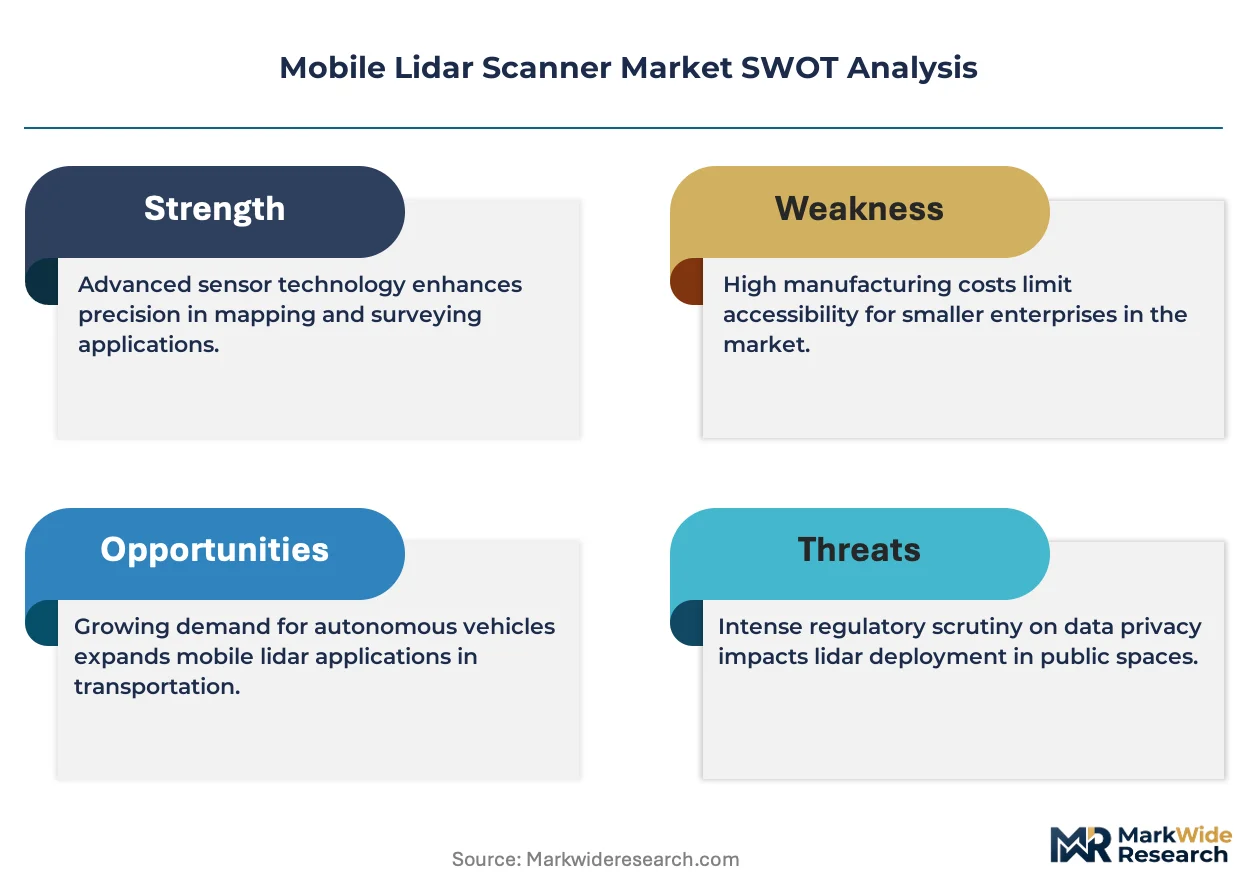
The mobile lidar scanner market is undergoing structural compression as solid-state architectures displace mechanical spinning units, driven by automotive qualification timelines and the EU Green Deal's electrification mandates for survey fleets.
Growth Catalysts
- EU Green Deal:National emissions frameworks across Germany, France, and Italy pressure survey contractors to replace diesel-based static rigs with battery-electric mobile platforms, creating replacement demand.
- Smart city infrastructure:China's Yangtze River Delta requires continuous mobile mapping coverage for digital twin construction, concentrating procurement in municipal engineering consortia.
- Solid-state LiDAR maturation:MEMS and OPA architectures reduce unit costs and vibration sensitivity, enabling backpack-portable deployments in underground mining operations across Australia and Chile.
Market Restraints
- Input cost volatility:Indium phosphide and gallium arsenide substrate prices for laser diodes fluctuate with semiconductor foundry capacity constraints in Taiwan and South Korea.
- Supply concentration risk:High-precision inertial measurement units rely on a limited supplier base concentrated in Bavaria and Massachusetts, creating single-source vulnerabilities.
- REACH compliance friction:ECHA restrictions on hazardous substances in laser diode assemblies elevate documentation burdens and extend qualification timelines for European component suppliers.
Strategic Opportunities
- Heritage documentation:Photogrammetry-LiDAR fusion systems capture color-accurate point clouds for UNESCO site preservation, opening procurement channels among European conservation authorities.
- Drone-integrated mobile scanning:FAA unmanned aircraft rules harmonization with state surveying licensure boards creates regulatory clarity for aerial corridor mapping of electric transmission lines.
- Battery-electric platform retrofit:EPA emissions thresholds for survey fleet vehicles accelerate demand for electrified mobile platforms across US Department of Transportation infrastructure programs.
Industry Challenges
- Geodetic surveyor shortage:Specialized expertise in GNSS-IMU integration and point cloud georeferencing remains scarce, constraining deployment scale for civil engineering firms.
- ISO 19130 certification timelines:Sensor model encoding standardization for georeferenced imagery requires extensive third-party validation, delaying tender eligibility for new market entrants.
- Legacy CAD integration complexity:Point cloud processing workflows demand middleware development to interface with existing Autodesk and Bentley Systems environments, extending implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Lidar Scanner Market |
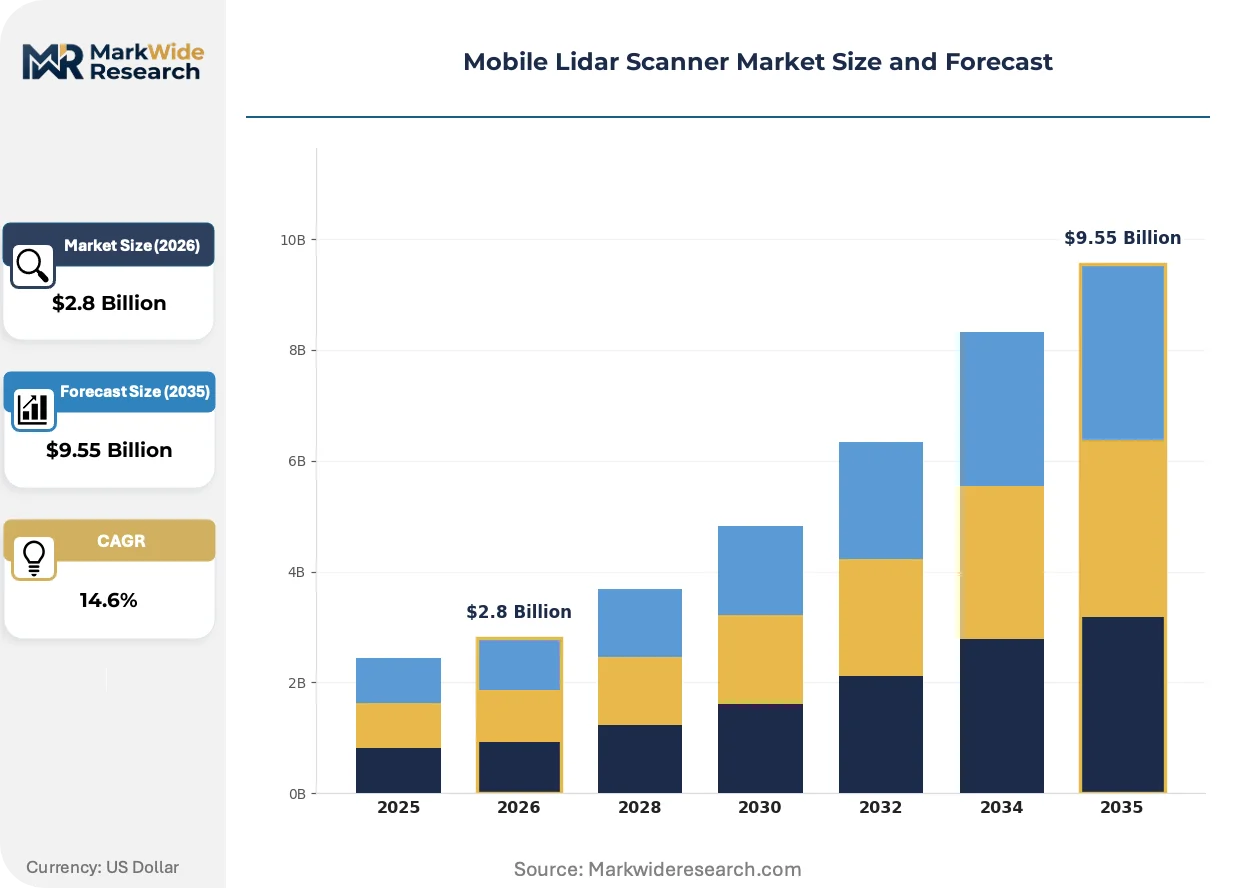
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Scanners, Mobile Scanners, Aerial Scanners, Handheld Scanners Technology: LiDAR, Photogrammetry, Radar, Acoustic Application: Surveying, Mapping, Archaeology, Mining End User: Construction, Transportation, Environmental, Utilities |
| Companies Covered | Hexagon AB, Trimble Inc., Velodyne LiDAR, Inc., Leica Geosystems AG, FARO Technologies, Inc., Sick AG, Teledyne Optech, Ibeo Automotive Systems GmbH, Topcon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Lidar Scanner Market Shifts & Advancements
Technology convergence and regulatory harmonization are compressing product lifecycles while expanding addressable use cases beyond traditional surveying into autonomous navigation and digital twin construction.
Solid-state LiDAR architectures are expanding into mobile mapping applications as automotive qualification timelines compress cost curves and performance thresholds. Civil engineering firms in Germany and Japan adopt MEMS-based units for as-built surveying at frequencies exceeding mechanical alternatives. The shift enables backpack-portable systems that capture million-point-per-second clouds without vehicle mounting, collapsing deployment logistics for underground infrastructure inspection.
REACH compliance and RoHS substance restrictions in Europe elevate documentation requirements for laser diode component suppliers. Manufacturers must trace indium, gallium, and rare earth content through multi-tier supply chains to maintain market access. German sensor producers respond by rebalancing output toward architectures with reduced hazardous material content, prioritizing EU Green Deal alignment over legacy mechanical designs.
Subscription-based hardware bundling displaces capital purchase models among mid-sized surveying contractors. Trimble's construction software ecosystem anchors this shift, embedding mobile scanner access into annual SaaS commitments. The pattern concentrates most visibly in North American infrastructure programs where municipal budget cycles favor operational expenditure classification over equipment capitalization.
Mobile Lidar Scanner Market Segmentation
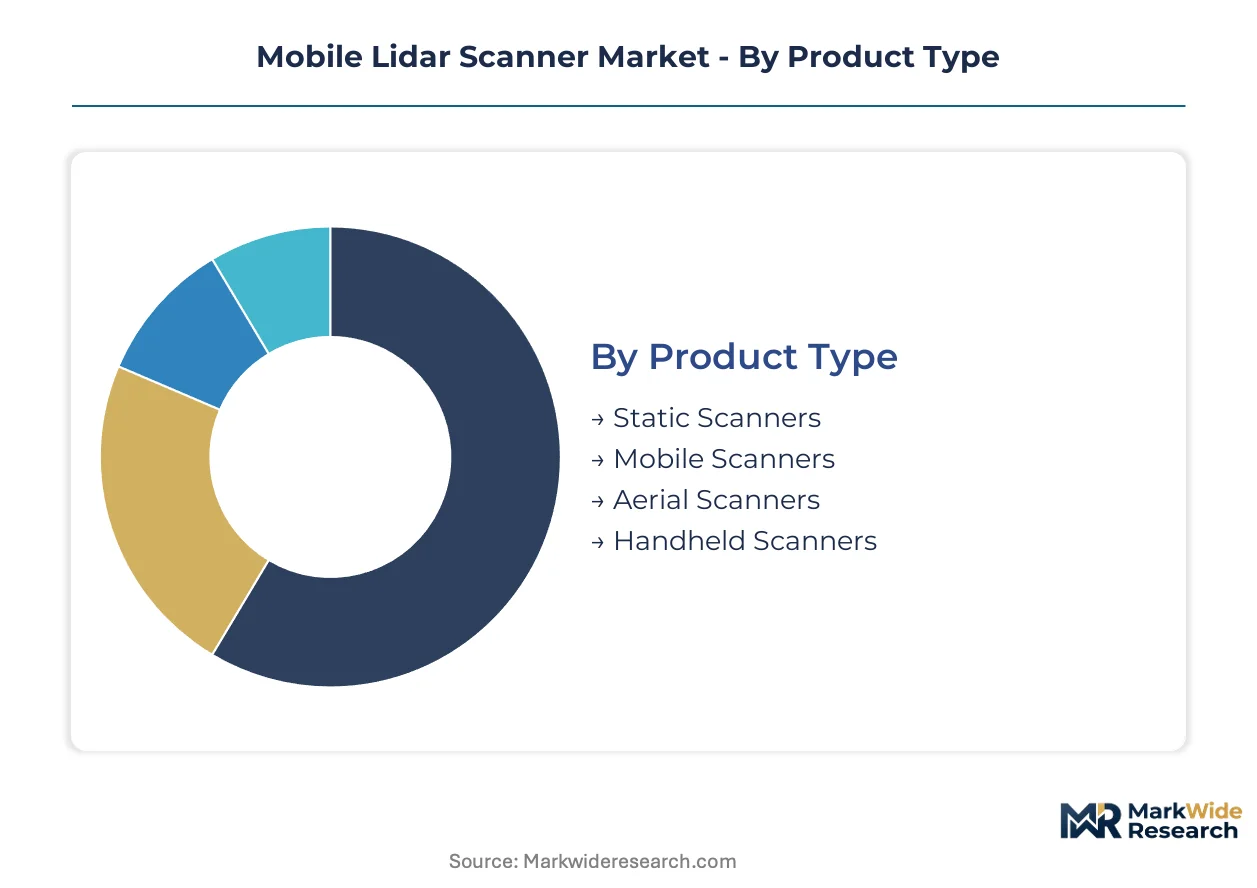
Segmentation in mobile lidar scanners reveals how procurement priorities diverge across civil engineering workflows, with upgrade cycles accelerating as solid-state architectures displace mechanical units. Contractors now specify scanner categories against project duration, site access constraints, and point cloud density requirements rather than defaulting to legacy static deployments.
Product Type:
Replacement cycles vary sharply by mounting configuration, with vehicle-integrated systems refreshing faster than tripod-based units due to vibration wear and automotive technology spillover.
- Static Scanners:Tripod-mounted units with sub-millimeter accuracy dominate metrology-grade factory inspection and heritage documentation. Demand concentrates in German automotive manufacturing and Japanese precision engineering facilities where ISO 19130 certification governs tender eligibility.
- Mobile Scanners:Vehicle-mounted or backpack-portable systems integrating laser rangefinding, IMU, and GNSS capture million-point-per-second clouds for as-built surveying without traffic disruption. Procurement clusters in China's Yangtze River Delta smart city programs and Australian mining corridors where continuous coverage requirements override precision thresholds.
- Aerial Scanners:Drone-integrated units command premium positioning for electric transmission line and pipeline corridor mapping where terrain access limits ground deployment.
- Handheld Scanners:Compact units penetrate underground mining operations across Chile and confined-space industrial inspection where vehicle mounting proves impractical.
Mobile scanners sit at the top of the volume ranking, with handheld scanners climbing the fastest as MEMS cost curves enable backpack-portable architectures.
Technology:
Cost tier stratification separates qualified automotive-grade components from industrial surveying alternatives, with photogrammetry gaining ground where color fidelity outweighs geometric precision.
- LiDAR:Pulsed and continuous-wave laser systems maintain structural dominance through direct distance measurement and weather-independent operation. Solid-state MEMS and OPA architectures displace mechanical spinning units as German and Japanese automotive qualification timelines compress unit costs for civil engineering adoption.
- Photogrammetry:Image-based reconstruction captures RGB-textured meshes for UNESCO heritage site documentation where visual authenticity supersedes millimeter accuracy. European conservation authorities drive procurement as REACH compliance elevates laser diode documentation burdens.
- Radar:Microwave-based systems penetrate dust and precipitation for mining operations in Australia's Pilbara region where optical sensors suffer occlusion.
- Acoustic:Sonar-based underwater mapping serves dam inspection and hydrographic survey niches with limited addressable market scale.
LiDAR commands the dominant revenue tier, while photogrammetry gains share fastest in conservation authority procurement channels.
Application:
Application selection tracks project lifecycle phase, with front-end surveying commanding different specifications than operational monitoring or archival documentation.
- Surveying:Cadastral and engineering survey workflows specify mobile platforms for highway as-built documentation and municipal infrastructure programs. EPA emissions thresholds for US Department of Transportation fleets accelerate battery-electric platform adoption.
- Mapping:Continuous mobile mapping for digital twin construction concentrates procurement in China's Yangtze River Delta municipal engineering consortia.
- Archaeology:Non-invasive subsurface detection combines ground-penetrating radar with photogrammetry for European excavation permits.
- Mining:Fleet deployments across Australian and Chilean open-pit operations prioritize dust-resistant solid-state units with minimal calibration drift.
Surveying generates the highest equipment throughput, with mining applications expanding most quickly as fleet standardization replaces rental models.
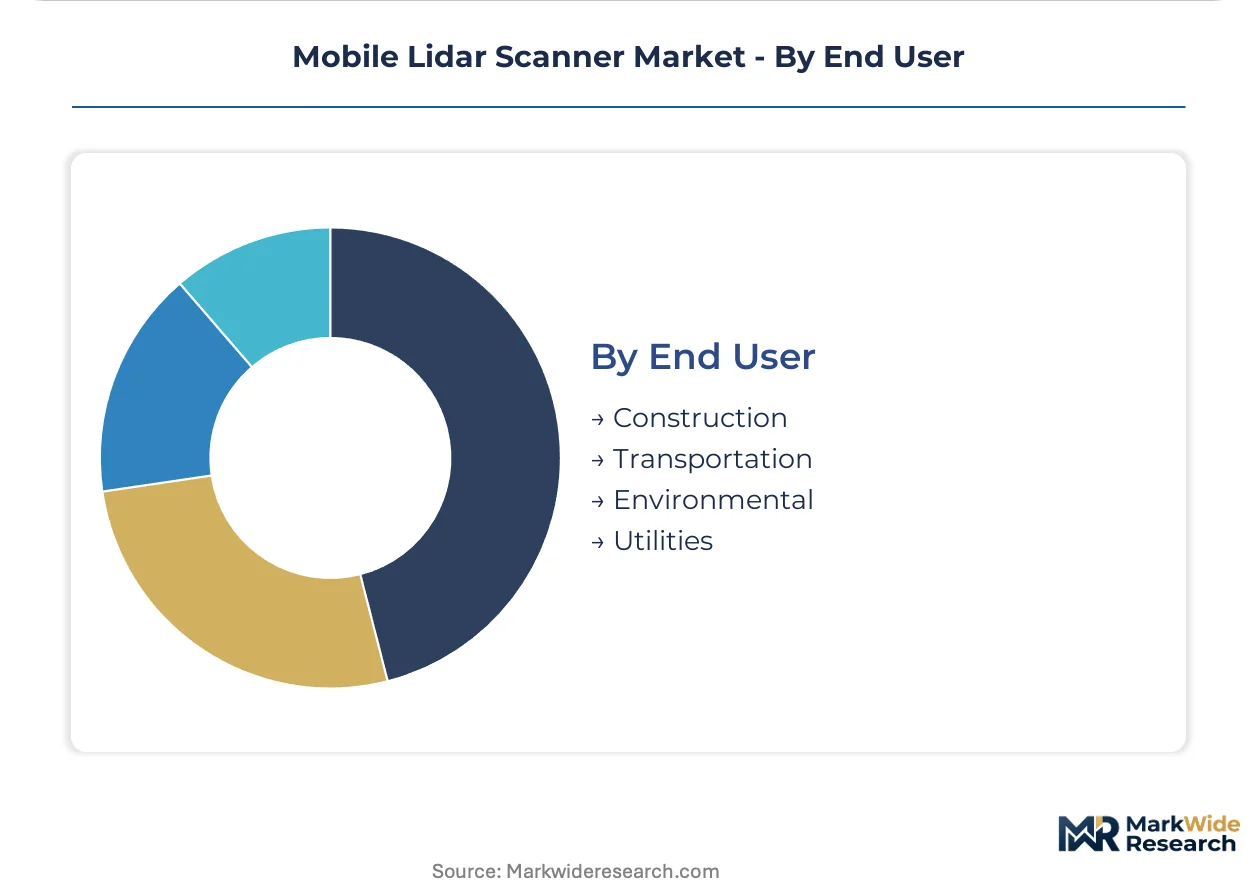
End User:
Customer type determines procurement modality, with municipal programs favoring subscription bundling and private operators retaining capital purchase structures.
- Construction:Civil engineering firms phase out static tripod deployments in favor of mobile units integrated with Autodesk and Bentley Systems workflows. Trimble's SaaS-embedded hardware subscriptions concentrate visibly in North American municipal budget cycles.
- Transportation:State departments of transportation specify mobile scanning for highway corridor documentation with FAA unmanned aircraft rules harmonization enabling drone-integrated aerial supplementation.
- Environmental:Contamination mapping and coastal erosion monitoring drive demand for waterproof portable units with rapid deployment protocols.
- Utilities:Electric transmission and pipeline operators mandate aerial scanner deployment for right-of-way vegetation management and thermal anomaly detection.
Construction absorbs the largest equipment volume, with utilities segments gaining traction fastest as corridor mapping specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as REACH compliance costs in Europe push component sourcing toward East Asian foundries with less stringent substance documentation requirements. Manufacturers now optimize supply chains around differential compliance burdens rather than pure labor arbitrage.
United States
EPA emissions thresholds for survey fleet vehicles accelerate battery-electric mobile platform adoption across Department of Transportation infrastructure programs. FAA unmanned aircraft rules harmonization with state surveying licensure boards enables drone-integrated corridor mapping for electric transmission lines. Procurement concentrates in California and Texas municipal engineering consortia deploying continuous mobile mapping for highway as-built documentation.
Germany
EU Green Deal national emissions frameworks pressure survey contractors to replace diesel-based static rigs with battery-electric mobile platforms, creating replacement demand in Bavaria and North Rhine-Westphalia. ECHA REACH restrictions on hazardous substances in laser diode assemblies elevate documentation burdens for component suppliers. Sensor manufacturing clusters in Baden-Württemberg rebalance output toward solid-state architectures with reduced hazardous material content.
China
Smart city infrastructure projects in the Yangtze River Delta require continuous mobile mapping coverage for digital twin construction, concentrating procurement in Shanghai and Jiangsu municipal engineering consortia. MIIT dual carbon goals accelerate electrified survey fleet mandates in Beijing-Tianjin-Hebei corridor. Semiconductor foundry capacity constraints in Taiwan and South Korea influence indium phosphide substrate pricing for domestic laser diode producers.
Australia
Mining operators in Western Australia and Queensland expand fleet deployments of mobile scanning units for open-pit operations, prioritizing dust-resistant solid-state designs with minimal calibration drift. The country's national emissions regulator enforces fleet electrification timelines for surface mining equipment. Procurement clusters in the Pilbara region where radar-augmented systems penetrate dust-heavy environments.
Chile
Underground mining operations in the Atacama and Antofagasta regions drive demand for backpack-portable solid-state units where vehicle mounting proves impractical. The national mining regulator mandates continuous geotechnical monitoring for slope stability compliance. Copper extraction consortia standardize on MEMS-based mobile scanners for million-point-per-second capture in confined-space infrastructure inspection.
Mobile Lidar Scanner Market Competitive Landscape
German producers anchor the precision-tier; US specialists hold the software-integrated subscription vector. The vendor base stratifies across three functional tiers: automotive-qualified component suppliers, construction-software ecosystem bundlers, and metrology-grade accuracy specialists. Two dominant competitive moves define current positioning: captive supply agreements with autonomous vehicle developers anchoring volume commitments, and construction software ecosystem bundling displacing capital purchase models.
Within the software-integrated tier, Trimble Inc. exemplifies the subscription-bundling archetype, embedding hardware access into annual SaaS commitments that align with municipal budget cycles. FARO Technologies, Inc. occupies the metrology-grade accuracy position, competing on factory automation inspection workflows where ISO 19130 certification governs tender eligibility. Velodyne LiDAR, Inc. anchors the automotive-spillover archetype, representing how captive supply agreements with autonomous vehicle developers compress cost curves for civil engineering adoption.
| Leading Market Players |
|---|
| Hexagon AB |
| Trimble Inc. |
| Velodyne LiDAR, Inc. |
| Leica Geosystems AG |
| FARO Technologies, Inc. |
| Sick AG |
| Teledyne Optech |
| Ibeo Automotive Systems GmbH |
| Topcon Corporation |
| Others |
Supply & Pricing Matrix
Indium phosphide substrate costs cascade from Taiwan and South Korean foundries through laser diode assemblies into three-tier pricing structures across premium, standard, and economy levels, with REACH compliance documentation burdens in Europe amplifying spreads between certified and uncertified supply tiers.
Pricing Analysis
Distributor margins compress as direct-to-OEM contracts expand, particularly for automotive-qualified MEMS units where volume commitments override spot-market premiums. Price differentiation hinges on ISO 19130 certification tier and after-sales calibration service bundling. Cost compression in standard-tier mechanical units intensifies because solid-state spillover from automotive timelines erodes residual value. Municipal engineering consortia exhibit highest price sensitivity, while metrology-grade factory automation buyers absorb premium tiers without volume negotiation.
Supply Chain Analysis
Freight costs for precision inertial measurement units from Bavaria and Massachusetts amplify landed costs in Australian mining corridors and Chilean underground operations. Laser diode production draws from Taiwan, South Korea, and China, with gallium arsenide wafer supply tethered to semiconductor foundry capacity cycles. Single-source vulnerability concentrates in high-precision IMU suppliers. Distribution runs through construction-software ecosystem bundlers and specialized geospatial equipment distributors serving surveying contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mobile Lidar Scanner Market represents a late-cycle quality story as procurement shifts from rental models toward owned fleet standardization, with buyers prioritizing solid-state durability and software integration over lowest-unit-cost alternatives.
For Market Incumbents: Cement captive supply agreements with autonomous vehicle developers to anchor volume commitments and compress cost curves ahead of MEMS commoditization. Defend against photogrammetry-LiDAR fusion entrants by deepening ISO 19130 certification moats in factory automation inspection workflows. Prioritize backward integration into laser diode assembly to offset indium phosphide price volatility.
For New Entrants and Emerging Players: Launch via subscription-embedded hardware models targeting mid-sized North American surveying contractors underserved by Trimble's construction software ecosystem. Heritage documentation in European conservation authorities offers the most penetrable white-space, with REACH compliance friction disadvantaging incumbent laser-heavy portfolios. Emphasize photogrammetry-first positioning with LiDAR augmentation for color-fidelity specifications.
For Investors and Strategic Acquirers: Consolidation pressure builds where software-integrated bundlers lack captive sensor supply and where metrology-grade specialists face automotive-spillover pricing erosion. Five-to-ten year viability favors vertically integrated platforms with construction SaaS ecosystems and solid-state MEMS sourcing control. Watch FAA-state surveying licensure harmonization progress as inflection indicator for drone-integrated aerial scanner demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Diode Assembly | Captive supply of indium phosphide components insulates margin compression from Taiwan foundry capacity constraints. |
| Construction Software Ecosystem Bundling | Trimble's SaaS-embedded hardware subscriptions align municipal procurement cycles with operational expenditure classification. |
| ISO 19130 Certification Investment | Sensor model encoding standardization governs tender eligibility in German automotive manufacturing and Japanese precision engineering. |
| Drone-Integrated Mobile Scanning Platform | FAA harmonization with state surveying licensure boards enables aerial corridor mapping for electric transmission lines. |
| Photogrammetry-LiDAR Fusion Development | European conservation authorities prioritize color-accurate point clouds for UNESCO site preservation procurement. |
Research Methodology
Bottom-up surveying contractor modeling reconciled against top-down sensor manufacturer production tracking forms the analytical core of this study. Primary interviews with geospatial engineering directors, municipal procurement officers, mining fleet managers, and laser diode component suppliers combined with secondary validation from SEC filings, ECHA REACH substance databases, FAA unmanned aircraft rulemaking dockets, and MIIT dual carbon policy disclosures. Construction software ecosystem subscription data and geospatial equipment distributor shipment records provided cross-reference points for triangulation.
Input-output matrices map laser rangefinding unit shipments through mounting configuration, technology architecture, and end-use application dimensions across the projection horizon. CAGRs derive from segment-level demand elasticity modeling against electrified fleet mandates and smart city infrastructure procurement timelines. Forecast inputs include semiconductor foundry capacity utilization rates for indium phosphide substrate availability and EU Green Deal national emissions framework implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Taiwan semiconductor export restriction scenarios or accelerated FAA-state licensure harmonization. Forecasts reflect assumptions regarding solid-state MEMS cost curve compression and REACH compliance documentation burden stability. A model refresh is warranted upon material change in EU Green Deal enforcement timelines or MIIT dual carbon goal acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Robot Sensor Market
Sensors
Global Weather Monitoring Solutions and Services Market
Sensors
Sensor Landscape in Robotics and ADAS Vehicle Market
Sensors
Fixed RFID Readers Market
Sensors
Micro Location Technology Market
Sensors
In-Counter Barcode Scanners Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market
Sensors
Beacon Technology Market
Sensors
Bluetooth Photo Capture Device Market
Sensors
Lidar in Construction Market
Sensors
Vision Positioning System Market
Sensors
Eye Tracking Solutions Market
Sensors
Asia Pacific Container Monitoring Market
Sensors
Personal Navigation Devices Market
Sensors
Vibration Monitoring Market