
 In-Counter Barcode Scanners Market | 2026-2036
In-Counter Barcode Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
In-Counter Barcode Scanners Market Foresight
China is tilting toward domestic production of image-based scanning modules, reducing reliance on imported laser engines. Honeywell International Inc. leverages captive semiconductor foundry partnerships to control sensor supply chains. Zebra Technologies Corporation anchors North American distribution through direct enterprise sales teams. Cognex Corporation specializes in machine-vision algorithms that differentiate its units in high-speed grocery environments.
In-counter barcode scanners are stationary point-of-sale devices embedded within checkout counters, typically employing image sensors with megapixel resolution and decode rates exceeding sixty frames per second to capture one-dimensional and two-dimensional symbologies at varied angles. These units serve retail and hospitality operators seeking throughput maximization with minimal cashier intervention. Omni-directional configurations lead unit shipments due to their tolerance for random barcode orientation, while image-based technology captures the fastest expansion as retailers phase out laser diodes for solid-state alternatives. Fixed-mount installations dominate margin pools because they require custom counter fabrication and recurring service contracts.
The FCC governs electromagnetic emissions for scanners deployed in US retail environments, while the EU RoHS directive restricts hazardous substances in circuit assemblies sold across European member states. REACH compliance adds material disclosure burdens for manufacturers sourcing specialty plastics and coatings. Stakeholders must monitor how FDA Unique Device Identification rules for healthcare point-of-care workflows reshape scanner hygiene specifications and enclosure material requirements.
Market Dynamics
Self-checkout lane proliferation at grocery chains is compressing replacement cycles for legacy laser units while EU F-Gas Regulation pressures manufacturers toward solid-state image sensors with lower thermal footprints.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants and cooling gases is compelling scanner manufacturers to abandon thermal-intensive laser diodes for solid-state CMOS image sensors.
- German digital payment mandates:Retailers in Germany are modernizing point-of-sale infrastructure ahead of regulatory deadlines, concentrating demand for omni-directional in-counter units.
- Image sensor decode rates:Megapixel-resolution sensors exceeding sixty frames per second now capture two-dimensional symbologies at varied angles without cashier intervention.
Market Restraints
- Semiconductor foundry concentration:Captive partnerships with Taiwan-based foundries create supply vulnerability for sensor-dependent manufacturers during geopolitical friction.
- Custom counter fabrication costs:Fixed-mount installations require bespoke retail counter modifications that extend deployment timelines and inflate total cost of ownership.
- Laser diode phaseout friction:Legacy laser engine inventories in North American distribution channels delay full transition to solid-state alternatives despite regulatory pressure.
Strategic Opportunities
- China domestic module production:Local manufacturing of image-based scanning modules is reducing import dependency and creating captive supply ecosystems for Asia-Pacific retailers.
- Healthcare point-of-care workflows:FDA Unique Device Identification rules are reshaping scanner hygiene specifications, opening demand for antimicrobial enclosure materials in hospital pharmacies.
- Machine-vision algorithm convergence:Integration of high-speed decode engines with edge-computing inference is enabling real-time inventory verification at self-checkout stations.
Industry Challenges
- REACH material disclosure burdens:Manufacturers sourcing specialty plastics and coatings face escalating documentation requirements for European chemical compliance.
- Legacy POS integration complexity:Retailers operating mixed estates of Windows-based and cloud-native point-of-sale systems encounter protocol mismatches during scanner deployment.
- RF emission certification timelines:FCC electromagnetic compliance testing for new sensor architectures adds six-to-nine month delays to product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Counter Barcode Scanners Market |
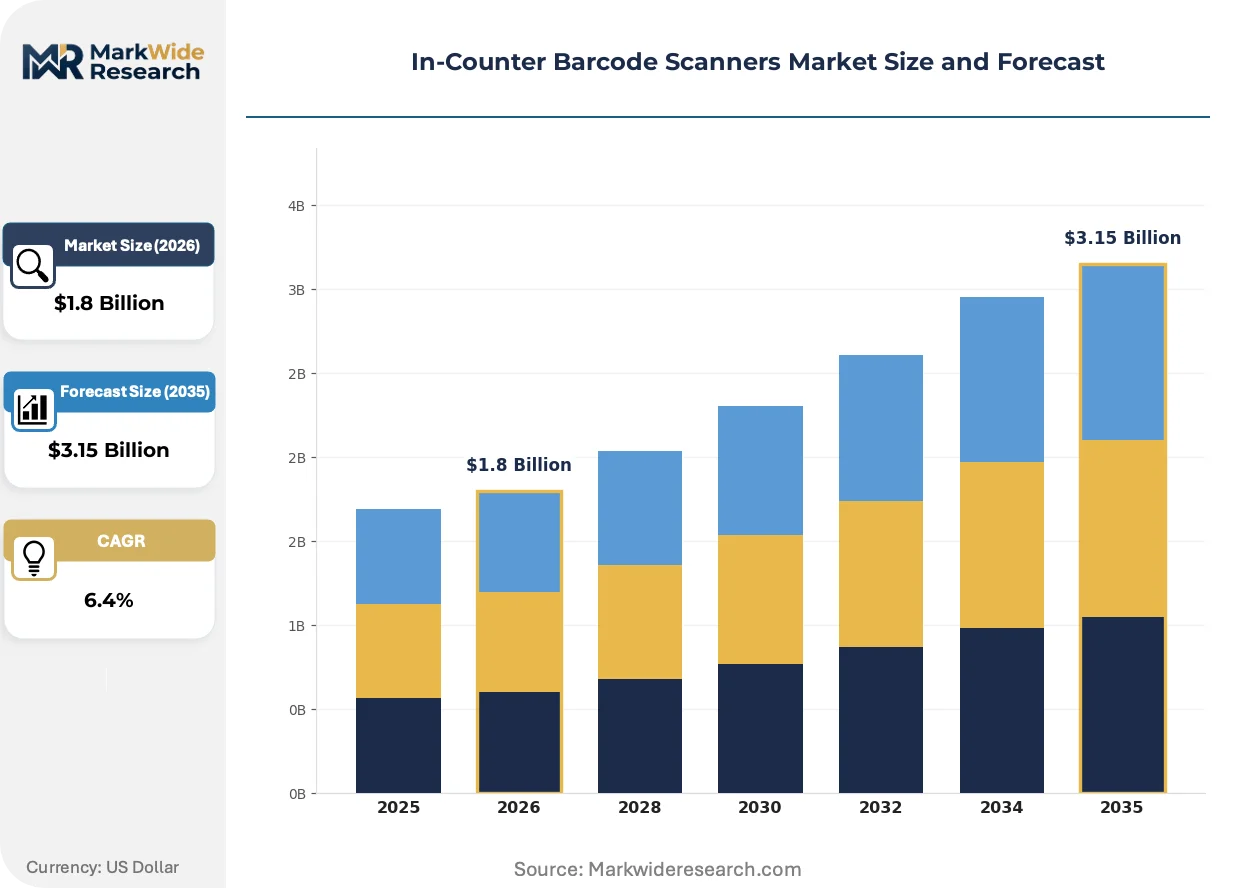
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Fixed Mount, Omni-Directional, Mobile Technology: Laser, CCD, Image-Based, 2D Barcode End User: Retail, Hospitality, Manufacturing, Healthcare Installation: Surface-Mounted, Integrated, Stand-Alone, Temporary |
| Companies Covered | Honeywell International Inc., Zebra Technologies Corporation, Cognex Corporation, Datalogic S.P.A, Toshiba TEC Corporation, SATO Holdings Corporation, NCR Corporation, Wasp Barcode Technologies, Opticon Sensors Europe B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Counter Barcode Scanners Market Shifts & Advancements
Three simultaneous shifts—solid-state sensor maturation, chemical compliance tightening, and procurement centralization—are restructuring how scanner capabilities are specified, priced, and deployed across retail formats.
CMOS image sensors with megapixel resolution are digitizing the capture of one-dimensional and two-dimensional symbologies at decode rates exceeding sixty frames per second. Grocery chains operating high-throughput self-checkout lanes are adopting these units at accelerated replacement cycles. The technology is digitizing barcode orientation tolerance, eliminating the mechanical sweep mechanisms that previously constrained laser-based designs.
The EU F-Gas Regulation is prohibiting refrigerants and thermal management fluids with high global-warming potential in electronic equipment sold across member states. Scanner manufacturers must redesign thermal architectures around passive cooling or solid-state alternatives. German retailers facing simultaneous digital payment mandates are prioritizing compliant image-based units in infrastructure modernization programs.
Enterprise procurement teams at grocery chains are consolidating scanner specifications across banner portfolios to extract volume pricing and simplify service contracting. Direct enterprise sales relationships are displacing distributor-mediated transactions for chains operating more than five hundred locations. This concentration is most visible in North American markets where banner consolidation has reduced the number of independent buying centers by nearly half over the past decade.
In-Counter Barcode Scanners Market Segmentation
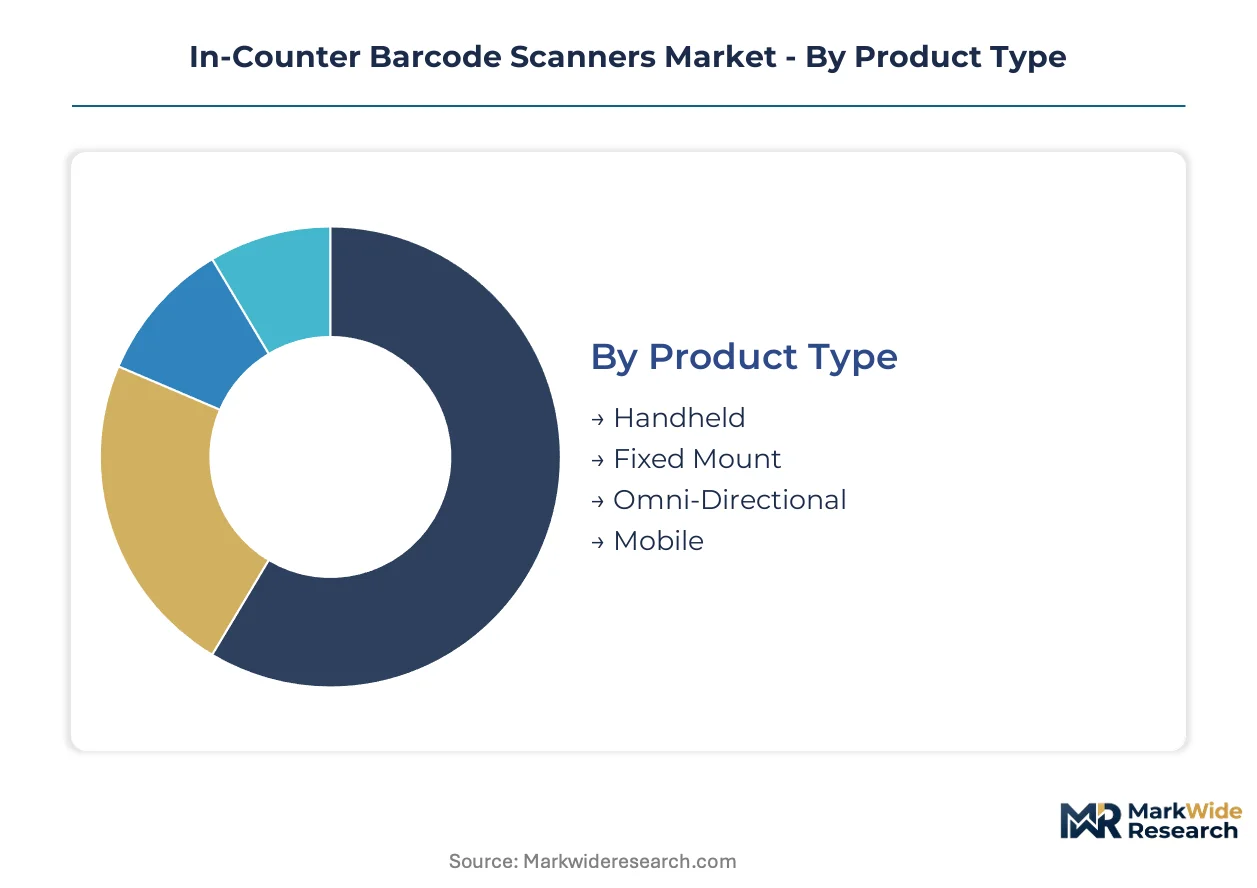
Scanner deployment patterns diverge sharply across retail formats, with grocery chains prioritizing throughput-optimized configurations while healthcare and hospitality operators emphasize hygiene ratings and spatial flexibility. Segmentation reveals how specification requirements cascade from end-use workflows through technology selection and mounting decisions.
Product Type:
Retail checkout lanes span a functional spectrum from high-volume fixed installations to flexible handheld backup units for exception handling.
- Omni-Directional:These units employ multi-angle sensor arrays that eliminate barcode orientation constraints, capturing symbologies from any presentation angle at decode rates exceeding sixty frames per second. German supermarket chains modernizing for digital payment mandates are specifying these units for self-checkout lane retrofits, prioritizing throughput over hardware cost.
- Fixed Mount:Stationary units embedded within custom-fabricated checkout counters dominate margin pools through recurring service contracts and integration fees. North American grocery banners operating more than five hundred locations are consolidating procurement around fixed-mount specifications to standardize service agreements across banner portfolios.
- Handheld:Portable units serve exception-handling workflows at self-checkout stations and mobile point-of-sale deployments in hospitality environments.
- Mobile:Battery-powered scanners support temporary checkout configurations and pop-up retail formats requiring rapid deployment without counter modifications.
The dominant share belongs to Omni-Directional units, while Fixed Mount configurations are closing the gap fastest through enterprise procurement consolidation.
Technology:
Cost tiers separate legacy thermal-intensive designs from solid-state alternatives commanding premium positioning under tightening chemical regulations.
- Image-Based:CMOS sensors with megapixel resolution digitize one-dimensional and two-dimensional symbologies without mechanical sweep mechanisms, eliminating the thermal footprints that laser diodes require. The EU F-Gas Regulation is accelerating retailer phaseout of cooling-dependent architectures, concentrating demand for these units in German infrastructure modernization programs.
- 2D Barcode:Dedicated decode engines optimized for matrix symbologies capture QR codes and Data Matrix patterns at healthcare point-of-care workflows subject to FDA Unique Device Identification rules.
- Laser:Diode-based scanning retains installed base presence in North American distribution channels where legacy inventory delays full transition timelines.
- CCD:Linear image sensors occupy economy positioning for low-throughput hospitality and small-format retail applications.
Image-Based technology holds the dominant position, while 2D Barcode specialization is expanding most quickly through healthcare compliance requirements.
End User:
Application-specific workflows dictate hygiene specifications, throughput requirements, and integration complexity across sector boundaries.
- Retail:Grocery chains operating high-throughput self-checkout lanes specify omni-directional image-based units with passive cooling architectures to satisfy EU F-Gas compliance while maximizing item-per-minute rates.
- Healthcare:Hospital pharmacies require antimicrobial enclosure materials and FDA-compliant hygiene specifications under Unique Device Identification rules for point-of-care medication administration.
- Hospitality:Hotels and restaurants prioritize compact form factors and mobile compatibility for flexible counter configurations.
- Manufacturing:Industrial environments demand ruggedized enclosures resistant to dust, moisture, and temperature variation for shop-floor inventory tracking.
Retail commands the dominant share, with Healthcare demonstrating the steepest expansion trajectory through regulatory-driven specification upgrades.
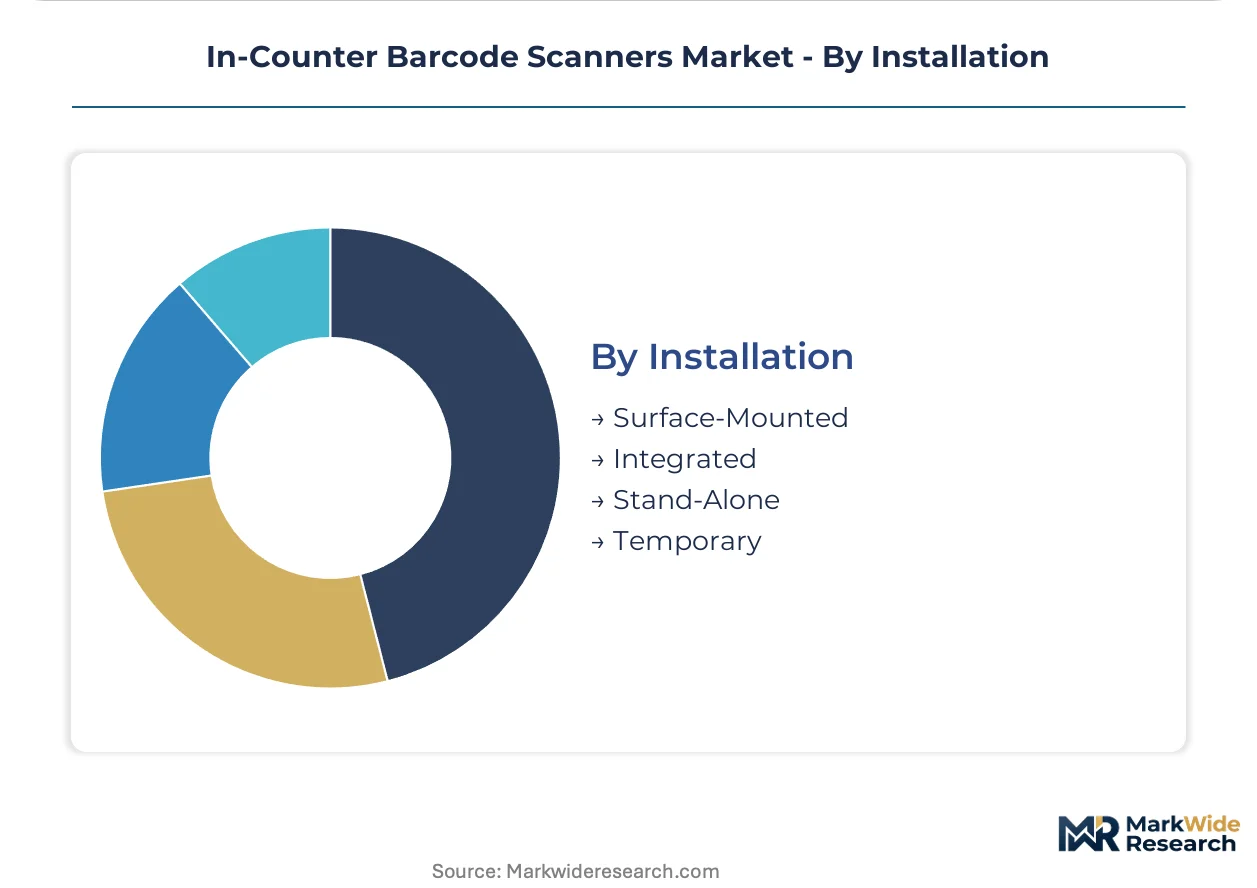
Installation:
Customer type separates enterprise banners with capital budgets for custom fabrication from operators requiring rapid deployment without construction timelines.
- Integrated:Flush-mounted units requiring bespoke counter fabrication capture premium pricing and extended service contracts from enterprise grocery chains.
- Surface-Mounted:Above-counter configurations reduce deployment complexity for mid-size retailers avoiding construction timelines.
- Stand-Alone:Self-contained units on pedestal mounts serve temporary and seasonal retail formats.
- Temporary:Rapid-deployment configurations support event retail and pop-up formats with minimal infrastructure investment.
Integrated installations dominate revenue contribution, while Surface-Mounted alternatives are gaining share fastest among cost-constrained operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated cargo handling systems anchor Europe's scanner distribution networks, while the Shenzhen-Dongguan manufacturing corridor underwrites Asia-Pacific module production capacity.
United States
Grocery chains operating over five hundred locations are consolidating procurement around fixed-mount specifications for self-checkout lane retrofits. FCC electromagnetic emission standards govern sensor architecture approvals, adding six-to-nine month certification delays. The Midwest industrial corridor spanning Illinois and Michigan hosts distribution centers supplying omni-directional units to banner retailers.
Germany
Supermarket operators are modernizing point-of-sale infrastructure ahead of digital payment mandates concentrating demand in Hesse and Bavaria. EU F-Gas Regulation prohibits thermal-intensive laser diodes, accelerating phaseout timelines for legacy cooling-dependent architectures. The Rhine-Main logistics cluster around Frankfurt facilitates rapid deployment of compliant image-based units to retail banners.
China
Domestic production of image-based scanning modules is reducing import dependency for Asia-Pacific retailers. MIIT standards for electronic equipment interoperability shape sensor interface specifications. The Yangtze River Delta manufacturing belt spanning Shanghai and Jiangsu province anchors captive supply ecosystems for CMOS image sensor assembly.
Japan
Precision manufacturing workflows demand high-decode-rate units for industrial point-of-care tracking applications. METI energy efficiency guidelines influence passive cooling architecture adoption in retail deployments. The Kansai industrial corridor around Osaka concentrates module fabrication for hospitality and healthcare scanner variants.
United Kingdom
Mid-size retail banners are adopting surface-mounted configurations to avoid bespoke counter fabrication costs. RoHS restrictions on hazardous substances in circuit assemblies add material disclosure burdens for specialty plastic sourcing. The Midlands logistics hub facilitates distribution of omni-directional units to grocery cooperatives modernizing checkout infrastructure.
In-Counter Barcode Scanners Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor modules and decode engines. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive semiconductor partnerships, pure-play imaging specialists leveraging machine-vision algorithms, and regional fabricators serving cost-constrained mid-market operators. Consolidation pressures are intensifying as enterprise procurement teams at grocery chains reduce supplier counts to extract volume pricing and standardize service contracting.
Among diversified industrial conglomerates, Honeywell International Inc. and Zebra Technologies Corporation exemplify the platform-integrator archetype with direct enterprise sales capabilities spanning North American distribution. Cognex Corporation occupies a specialist position anchored in machine-vision algorithm development for high-speed decode applications. These three entities represent distinct competitive vectors: captive supply chain control, distribution scale, and software differentiation.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Zebra Technologies Corporation |
| Cognex Corporation |
| Datalogic S.P.A |
| Toshiba TEC Corporation |
| SATO Holdings Corporation |
| NCR Corporation |
| Wasp Barcode Technologies |
| Opticon Sensors Europe B.V. |
| Others |
Supply & Pricing Matrix
Taiwanese foundry concentration creates dual exposure for sensor-dependent manufacturers, compressing mid-tier margins while amplifying premium-tier pricing power through captive semiconductor partnerships. This single-source vulnerability for CMOS image sensors shapes a bifurcated supply structure where volume buyers extract阶梯定价 concessions and specialty producers absorb scarcity premiums.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement, with grocery chains operating over five hundred locations commanding standard-tier unit economics through consolidated banner specifications. Price differentiation hinges on decode-rate performance tiers and EU F-Gas compliance certification levels, separating passive-cooled image-based units from legacy laser architectures. Pricing pressure stems from Chinese domestic module production scaling, which erodes import-premium positioning for non-captive suppliers. Mid-size retail banners exhibit highest price sensitivity due to bespoke counter fabrication cost burdens, while integrated healthcare systems demonstrate lowest sensitivity given FDA UDI-mandated specification floors.
Supply Chain Analysis
Taiwan-based foundries anchor CMOS sensor wafer capacity, with Yangtze River Delta assembly clusters and Japanese precision-optics fabricators completing the tier-one supplier map. Raw material dependencies center on silicon wafer substrates, specialty optical-grade plastics, and RoHS-compliant solder alloys. Single-source vulnerability concentrates in Taiwan semiconductor fabrication, where geopolitical friction threatens sensor supply continuity for manufacturers lacking captive partnerships. Distribution runs through direct enterprise sales teams for North American grocery banners, displacing distributor-mediated transactions as procurement centralizes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The in-counter barcode scanner market functions as a defensive-moat arena where switching costs lock enterprise grocery chains into integrated service ecosystems. Regulatory entrenchment around EU F-Gas compliance and FDA UDI specifications creates certification barriers that favor incumbents with established testing relationships.
For Market Incumbents: Build switching-cost moats through embedded service contracts that bundle counter fabrication, installation, and multi-year maintenance into single-source agreements. Deepen captive semiconductor partnerships to insulate sensor supply from Taiwan foundry concentration risk. Prioritize FDA UDI pre-certification for healthcare variants to preempt emerging entrants in hospital pharmacy workflows. For New Entrants and Emerging Players: Pursue surface-mounted configuration segments among UK mid-size retail banners avoiding integrated installation costs. Target German supermarket cooperatives outside the top-five banner concentration, where digital payment mandate deadlines create urgent demand without incumbent lock-in. Lead with RoHS REACH documentation transparency to differentiate against legacy suppliers burdened by material disclosure gaps. For Investors and Strategic Acquirers: EU F-Gas Regulation phaseout deadlines reshape the acquisition landscape toward solid-state image sensor specialists with compliant thermal architectures. Five-to-ten year viability favors platform integrators with direct enterprise sales capabilities over component module pure-plays. Signal to watch: German retail infrastructure modernization program acceleration rates as digital payment mandate enforcement clarifies.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Partnership | Taiwan foundry alliances insulate sensor supply against geopolitical friction for platform integrators. |
| Healthcare UDI Pre-Certification | FDA Unique Device Identification compliance opens hospital pharmacy demand with antimicrobial enclosure specifications. |
| Enterprise Sales Team Expansion | Direct relationships with grocery banners displace distributor channels as procurement centralizes across five-hundred-plus location operators. |
| Surface-Mounted Product Line Launch | Above-counter configurations capture UK mid-size retailers avoiding bespoke counter fabrication timelines. |
| REACH Documentation Automation | Streamlined material disclosure systems reduce compliance burden for European chemical regulations. |
Research Methodology
A standing panel of point-of-sale hardware procurement directors, retail systems integrators, semiconductor supply chain managers, and healthcare biomedical engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from FCC equipment authorization databases, EU ECHA REACH registration filings, SEC 10-K disclosures from listed platform integrators, and German retail association infrastructure surveys. Bottom-up unit shipment estimates triangulated against top-down enterprise procurement spend analysis.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling spanning product type, technology architecture, end-use vertical, and installation complexity dimensions. CAGRs derived from weighted average of historical replacement cycle compression rates and regulatory phaseout timeline enforcement probability. Industry-specific inputs included self-checkout lane deployment schedules at top-twenty grocery banners and EU F-Gas Regulation compliance certification velocity.
Sensitivities concentrate around Taiwan foundry utilization rates, German digital payment mandate enforcement timing, and FDA UDI rule expansion to additional healthcare settings. Quarterly review of enterprise procurement consolidation announcements, REACH substance restriction updates, and MIIT domestic production subsidy programs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Connected Smart Thermostats Market
Sensors
Industrial Automation Sensors Market
Sensors
APAC Wireless Sensors Market
Sensors
NB-IoT Smart Gas Meter Market
Sensors
Temperature Data Loggers Market
Sensors
Underground Utility Mapping Market
Sensors
India Asset Tracking Market
Sensors
Vibration Monitoring Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Digital Olfaction Products Market
Sensors
Europe Remote Sensing Technology Market
Sensors
Global Weather Monitoring Solutions and Services Market
Sensors
Eye Tracking Market
Sensors
Global Load Monitoring System (LMS) Market
Sensors
Automated Weather Observation System Market
Sensors
Global Position Tracking System Market