
 Connected Motorcycle Market | 2026-2036
Connected Motorcycle Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Motorcycle Market Intelligence
Modular bundling of connectivity hardware with subscription-based software services is hardening as the dominant commercial model. BMW Motorrad leverages its integrated ecosystem architecture to capture recurring revenue streams beyond initial vehicle sales. Yamaha Motor Company anchors its competitive position through deep manufacturing scale in Asian production clusters. Continental AG differentiates by supplying Tier-1 connectivity modules across multiple OEM platforms rather than captive brand exclusivity.
A connected motorcycle integrates embedded telematics, cellular or short-range wireless transceivers, and cloud-linked ECUs to enable real-time data exchange between the vehicle, rider devices, and backend infrastructure, typically operating on 4G or Bluetooth protocols with diagnostic sampling rates exceeding 100 Hz for critical safety parameters. The primary commercial purpose centers on fleet visibility, rider safety intervention, and predictive maintenance scheduling for high-utilization vehicles. Ride Assistance Systems command the deepest margin pools due to sensor fusion complexity and liability-critical validation requirements. Cloud Computing represents the fastest-expanding technology layer as edge-to-cloud architectures enable over-the-air firmware updates and usage-based insurance models. Fleet Operators constitute the most structurally attractive end-user segment because volume procurement contracts and standardized deployment protocols reduce customer acquisition costs relative to fragmented consumer markets.
The European Union's ECE R10 electromagnetic compatibility framework and the U.S. NHTSA vehicle safety standards collectively shape product certification pathways, while India's BIS telecom equipment mandates govern local module approval and network interoperability. These regulatory layers increase compliance expenditure but simultaneously erect barriers against low-specification imports. Stakeholders must monitor evolving data localization requirements and cybersecurity certification timelines across target deployment geographies.
Market Dynamics
Fleet operators now dominate procurement volume as last-mile logistics platforms mandate real-time visibility into two-wheeler location, battery state, and rider behavior. This demand compression is forcing module suppliers to prioritize telematics integration over standalone consumer-facing features.
Growth Catalysts
- ECE R10 Compliance Mandate:Europe's electromagnetic compatibility framework compels manufacturers to redesign connectivity modules, creating upgrade cycles across existing fleets.
- Predictive Maintenance Algorithms:Machine learning models analyzing ECU diagnostic streams at 100 Hz sampling rates reduce unplanned downtime for high-utilization commercial vehicles.
- India BIS Telecom Certification:India's equipment approval requirements for cellular modules accelerate local production partnerships and reduce import dependency for domestic fleet deployments.
Market Restraints
- Semiconductor Supply Concentration:Cellular modem and GNSS chip fabrication concentrates in Taiwan and South Korea, exposing module assemblers to allocation volatility.
- Lithium-Ion Battery Cost Exposure:Electric two-wheeler connectivity integration depends on battery management systems whose cell costs fluctuate with cobalt and nickel spot markets.
- Cellular Protocol Obsolescence Risk:2G network sunsets across multiple jurisdictions force hardware redesigns before depreciation cycles complete.
Strategic Opportunities
- Usage-Based Insurance Models:Telematics data streams enable pay-per-mile underwriting for gig economy riders in Southeast Asian urban corridors.
- Over-the-Air Firmware Distribution:Edge-to-cloud architectures allow remote feature activation, creating recurring revenue from hardware already deployed in the field.
- EU Battery Passport Requirements:Upcoming traceability mandates position connected battery management systems as compliance infrastructure for electric motorcycle imports.
Industry Challenges
- Embedded Systems Security Certification:ISO/SAE 21434 automotive cybersecurity standards impose validation timelines that delay product launches by 8-14 months.
- Legacy Fleet Integration Complexity:Older two-wheeler ECU architectures lack CAN bus bandwidth for supplemental sensor fusion, requiring hardware retrofit kits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Motorcycle Market |
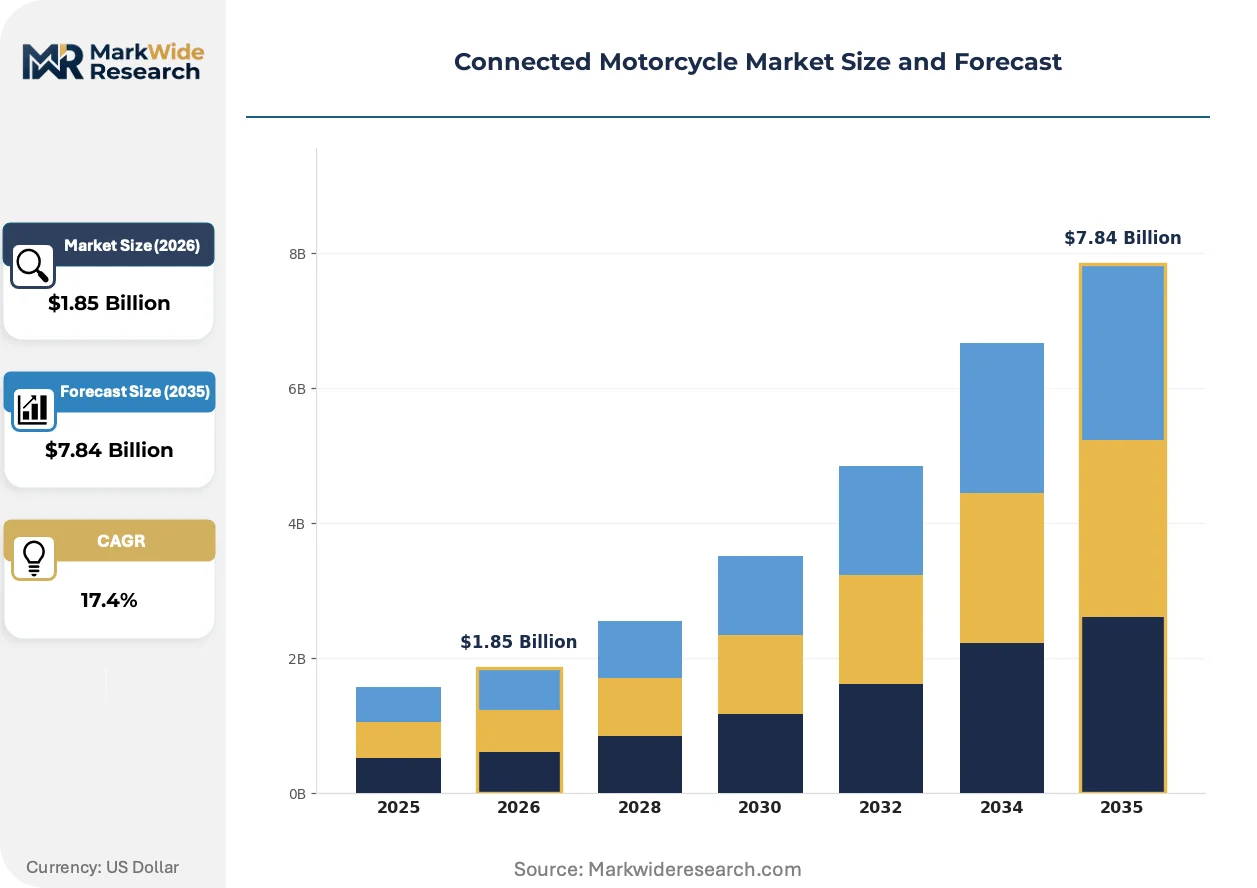
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Helmets, Diagnostic Tools, Connectivity Modules, Ride Assistance Systems Technology: Bluetooth, Wi-Fi, 4G, Cloud Computing Application: Navigation, Safety Monitoring, Performance Tracking, Theft Prevention End User: Recreational Riders, Fleet Operators, Delivery Services, Riding Schools |
| Companies Covered | Yamaha Motor Company, BMW Motorrad, Kawasaki Heavy Industries, Honda Motor Company, Robert Bosch GmbH, Continental AG, Suzuki Motor Corporation, Panasonic Corporation, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Motorcycle Market Strategic Shifts & Innovations
Sensor fusion architectures are migrating from premium motorcycles to mid-tier commercial vehicles as fleet operators demand lane-departure and collision warnings. This capability diffusion is compressing the feature gap between consumer and industrial segments.
Sensor fusion technology is absorbing computational workloads previously handled by standalone advanced driver-assistance chips. Fleet operators in India and Brazil are specifying camera-plus-radar configurations for delivery motorcycles operating in dense urban traffic. This hardware integration is absorbing margin from discrete component suppliers while shifting value capture to module integrators capable of calibration and validation.
Europe's ECE R10 electromagnetic compatibility framework now extends to aftermarket connectivity devices, not just factory-installed systems. Module manufacturers must redesign shielding and filtering circuits to achieve type approval for retrofit installations. Commercial fleet operators in Germany and France are selecting only pre-certified hardware, eliminating uncertified competitors from procurement shortlists.
Subscription billing for software-enabled features is displacing perpetual licensing in fleet procurement contracts. Logistics platforms in India now negotiate per-vehicle monthly fees covering telematics, predictive maintenance alerts, and stolen-vehicle recovery. This pricing model compresses upfront capital requirements while locking in multi-year revenue commitments for connectivity providers.
Connected Motorcycle Market Segmentation
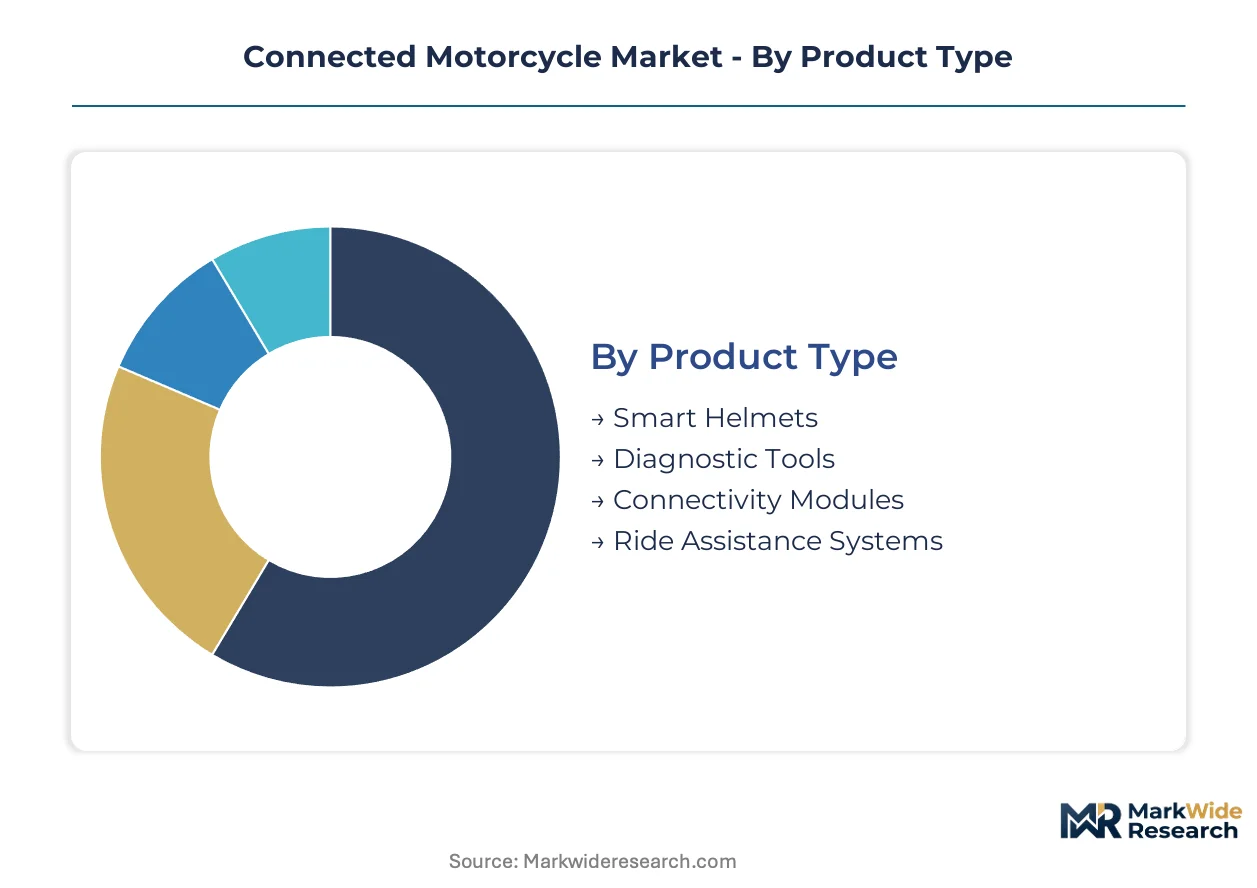
Segmentation in the connected motorcycle market reveals how hardware suppliers, software platforms, and service providers partition value capture across distinct technical and commercial boundaries. Understanding these divisions exposes where procurement power concentrates and which integration points command premium positioning.
Product Type:
Supply concentration in ride assistance and connectivity modules tilts procurement leverage toward integrated platform vendors over discrete component suppliers.
- Ride Assistance Systems:Sensor fusion architectures combining radar, camera, and IMU data at 100 Hz sampling rates enable collision warnings and lane departure alerts. Demand concentrates among Indian and Brazilian fleet operators specifying camera-plus-radar configurations for dense urban delivery corridors, driven by liability reduction and insurance premium discounts.
- Connectivity Modules:Embedded telematics units with cellular transceivers and cloud-linked ECUs form the backbone of real-time data exchange. European logistics platforms under ECE R10 compliance mandates are driving redesign cycles for electromagnetic compatibility certification, creating upgrade demand across existing fleet installations.
- Smart Helmets:Integrated headgear combining Bluetooth audio, heads-up displays, and biometric monitoring for rider status tracking.
- Diagnostic Tools:Portable or docked interfaces for ECU fault code retrieval and predictive maintenance scheduling.
Today's leader: Ride Assistance Systems. Tomorrow's challenger: Connectivity Modules.
Technology:
Cellular protocol transitions and cloud architecture maturity are redistributing value from hardware transmission layers toward data processing and software service tiers.
- Cloud Computing:Edge-to-cloud architectures enable over-the-air firmware updates, usage-based insurance underwriting, and predictive maintenance algorithm deployment. Indian last-mile delivery platforms are adopting cloud-native fleet management stacks, driven by scalability requirements and multi-tenant operational efficiency.
- 4G:Cellular connectivity providing wide-area coverage for real-time telematics and stolen-vehicle recovery services. Fleet procurement contracts in Germany and France specify 4G-enabled modules exclusively, eliminating 2G-dependent hardware from certified supplier shortlists due to network sunset timelines.
- Bluetooth:Short-range wireless protocol for rider-to-vehicle pairing and helmet-to-dashboard communication.
- Wi-Fi:Local area connectivity for service bay diagnostics and firmware batch updates.
Cloud Computing commands the steepest expansion trajectory as edge processing costs decline and fleet operators demand centralized visibility.
Application:
Commercial use cases are absorbing development resources as consumer-facing features face procurement compression from fleet volume buyers.
- Safety Monitoring:Real-time rider behavior analysis, crash detection, and emergency response triggering. Brazilian and Indian delivery platforms mandate hard braking and cornering alerts, driven by accident liability exposure and driver retention metrics.
- Theft Prevention:Geofencing, unauthorized movement alerts, and remote immobilization capabilities. Urban mobility startups in Indian metropolitan corridors specify integrated stolen-vehicle recovery, driven by high asset utilization rates and insurance policy requirements.
- Navigation:Turn-by-turn routing optimized for motorcycle maneuverability and traffic conditions.
- Performance Tracking:Lap timing, lean angle logging, and engine telemetry for enthusiast riders.
Safety Monitoring dominates current procurement specifications. Theft Prevention is gaining share fastest as electric two-wheeler values rise.
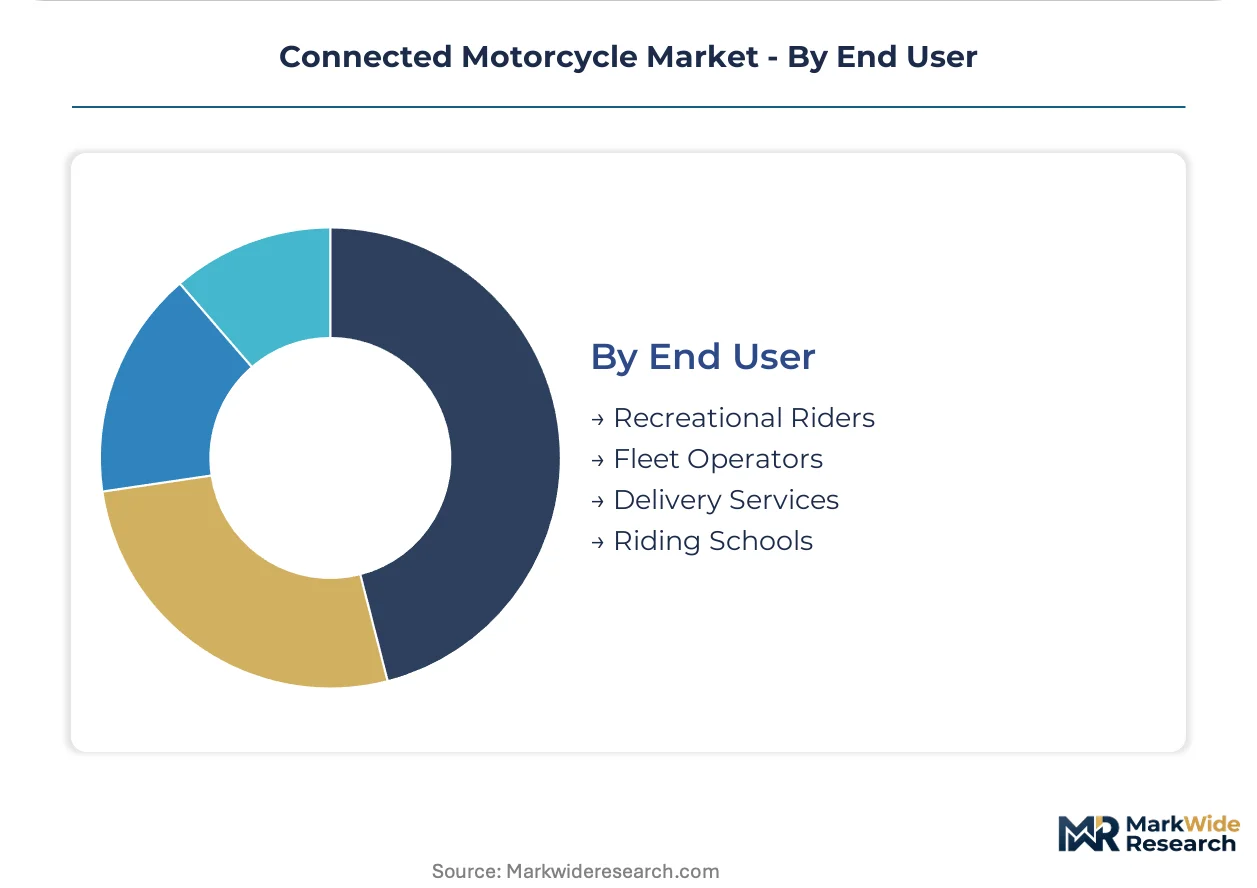
End User:
Volume concentration in commercial logistics is restructuring go-to-market economics toward enterprise sales cycles and standardized deployment protocols.
- Fleet Operators:Commercial logistics platforms managing hundreds to thousands of two-wheelers under centralized telematics. Indian last-mile delivery companies and Brazilian urban freight networks are driving the largest procurement volumes, drawn by predictive maintenance ROI and real-time visibility into battery state and rider behavior.
- Delivery Services:Gig economy platforms and food delivery aggregators requiring pay-per-mile insurance integration and route optimization. Southeast Asian urban corridors are adopting usage-based underwriting models, driven by variable rider income structures and insurer data appetite.
- Recreational Riders:Individual consumers purchasing connectivity features for touring, social connectivity, and enthusiast data logging.
- Riding Schools:Training institutions utilizing performance tracking for curriculum development and student progress monitoring.
Fleet Operators anchor current revenue concentration. Delivery Services represent the most aggressive expansion profile as platform economics scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Connected motorcycle technology originated in European premium motorcycle manufacturing, where BMW Motorrad and other German engineers first integrated telematics systems for rider safety and vehicle diagnostics. The industry has since diffused to Asian production clusters and Indian commercial logistics markets.
Germany
Fleet operators in the Rhine-Ruhr industrial corridor specify ECE R10-certified connectivity modules for electromagnetic compliance. The KBA enforces type approval requirements that eliminate uncertified aftermarket hardware from procurement shortlists. Stuttgart-based automotive suppliers are redesigning shielding architectures to capture retrofit upgrade cycles across existing commercial fleets.
India
Last-mile delivery platforms in Mumbai and Bangalore mandate real-time battery monitoring and rider behavior tracking for electric two-wheeler fleets. TRAI governs cellular module certification under BIS telecom equipment mandates, accelerating local production partnerships. The Delhi-NCR logistics corridor hosts the densest concentration of connected vehicle deployments, driven by urban freight electrification targets.
United States
NHTSA vehicle safety standards shape product certification pathways for collision warning and emergency response systems. California-based mobility startups integrate stolen-vehicle recovery and usage-based insurance models into gig economy rider platforms. The Southwest manufacturing belt attracts module assembly investment due to proximity to Mexican component supply chains.
Brazil
Urban freight networks in São Paulo specify camera-plus-radar sensor fusion for dense traffic collision avoidance. ANVISA coordinates with transport regulators on commercial vehicle safety equipment standards. The Minas Gerais industrial zone hosts assembly operations serving Latin American fleet operator demand for predictive maintenance systems.
Japan
Domestic motorcycle manufacturers anchor sensor fusion development for premium ride assistance systems. METI promotes connected vehicle standards harmonization across ASEAN export markets. The Nagoya industrial cluster concentrates ECU calibration expertise for high-frequency diagnostic sampling architectures.
Connected Motorcycle Market Key Industry Players
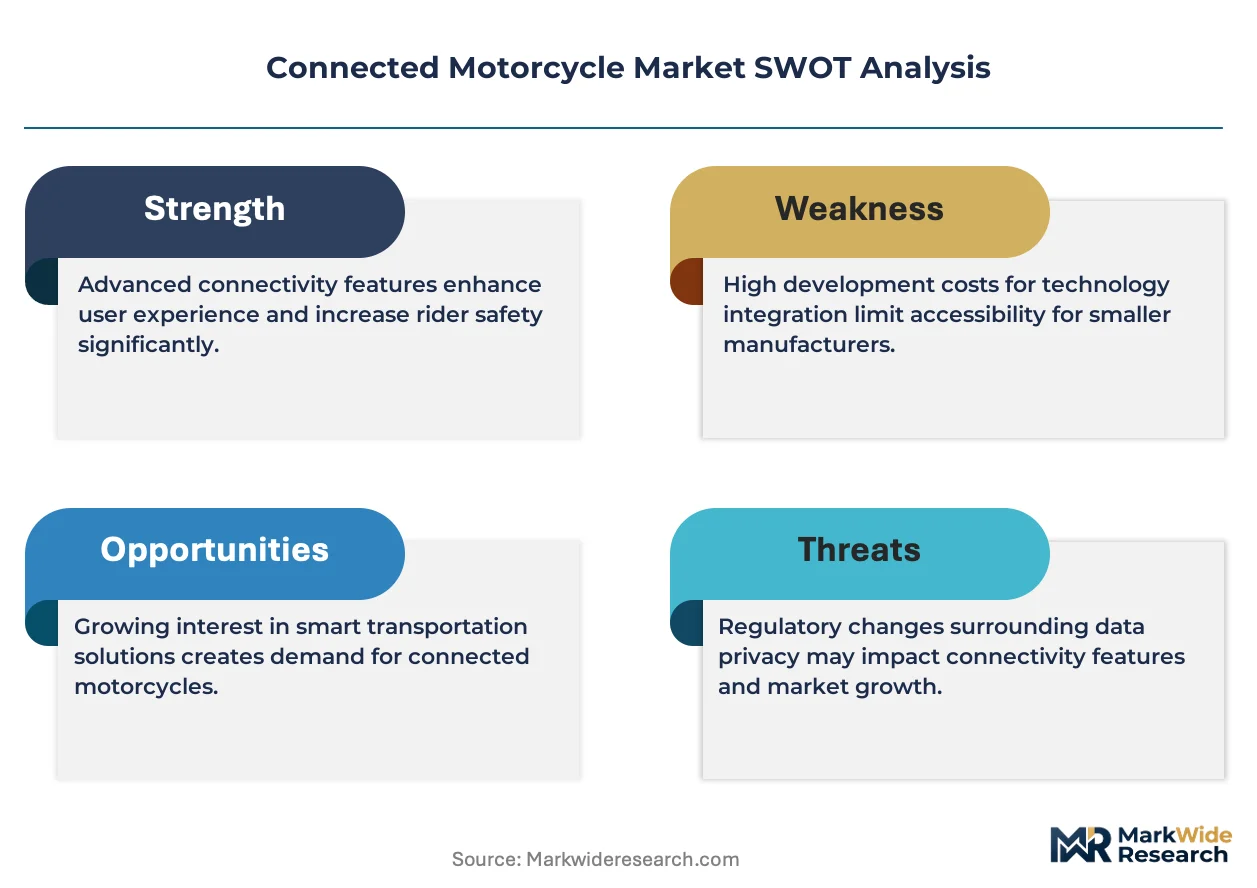
Premium-margin players sit above commodity-margin players across integration depth and certification complexity. The vendor base organizes into three tiers: captive OEM systems divisions, independent Tier-1 module suppliers, and discrete component specialists. Consolidation pressure concentrates in the module integration layer, where electromagnetic compliance and cybersecurity validation erect barriers against low-specification entrants. Dominant competitive moves include strategic partnerships between automotive electronics suppliers and motorcycle OEMs, plus geographic expansion into Indian and Brazilian fleet procurement channels.
Within the integrated OEM tier, BMW Motorrad and Yamaha Motor Company exemplify divergent strategic positions. BMW Motorrad represents the ecosystem-architecture approach, bundling hardware with recurring software subscriptions. Yamaha Motor Company anchors the manufacturing-scale archetype, leveraging Asian production clusters for cost-optimized module supply. Continental AG occupies the independent Tier-1 position, supplying connectivity platforms across multiple OEM brands without captive exclusivity.
| Leading Market Players |
|---|
| Yamaha Motor Company |
| BMW Motorrad |
| Kawasaki Heavy Industries |
| Honda Motor Company |
| Robert Bosch GmbH |
| Continental AG |
| Suzuki Motor Corporation |
| Panasonic Corporation |
| TE Connectivity |
| Others |
Cost & Logistics Intelligence
Fleet procurement mandates for ECE R10-certified modules in Germany and France are forcing module suppliers to absorb electromagnetic compatibility redesign costs, compressing margins on retrofit hardware while subscription pricing for software layers captures recurring value upstream.
Pricing Analysis
Subscription-based bundling of connectivity hardware with recurring software services dominates fleet procurement contracts. Three-tier pricing structure across premium ECE R10-certified modules, standard 4G-enabled units, and economy Bluetooth-only configurations separates procurement tiers by certification grade and sensor fusion complexity. Pricing pressure stems from semiconductor allocation volatility in cellular modem sourcing. Delivery services in Southeast Asia exhibit highest price sensitivity due to gig economy rider income variability, while European logistics platforms prioritize compliance over unit cost.
Supply Chain Analysis
Engineering talent scarcity in Taiwan and South Korea constrains cellular modem and GNSS chip fabrication capacity for connectivity module assemblers. Semiconductor lithography equipment draws from Dutch and Japanese capital goods suppliers, while cobalt and nickel feedstock for battery management systems rests on African and Indonesian mining operations. Single-source vulnerability concentrates in Taiwan foundry allocation. Distribution runs through Tier 1 automotive electronics suppliers serving multiple OEM platforms rather than captive brand channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with Europe's ECE R10 electromagnetic compatibility mandate forcing upgrade cycles across installed fleet bases and creating captive demand for certified module suppliers.
For Market Incumbents: To counter margin erosion from semiconductor supply concentration, deepen captive production of connectivity module shielding architectures in Stuttgart and Nagoya industrial clusters, while accelerating ISO/SAE 21434 cybersecurity certification pipelines to extend compliance moats against uncertified competitors. For New Entrants and Emerging Players: India's BIS telecom certification opens a window for local assembly partnerships targeting Mumbai and Bangalore last-mile delivery platforms, with white-space concentration in retrofit diagnostic tools for legacy fleet CAN bus integration and cloud-native fleet management stacks for multi-tenant operators. For Investors and Strategic Acquirers: Asymmetric upside sits with independent Tier 1 module suppliers possessing cross-OEM platform relationships and electromagnetic compliance validation infrastructure. Long-term viability hinges on edge-to-cloud architecture ownership. Watch for inflection when Indian logistics platforms consolidate procurement under standardized deployment protocols.| Strategic Initiative | Industry Significance |
|---|---|
| ECE R10 Certification Investment | Electromagnetic compliance validation eliminates uncertified competitors from German and French fleet procurement shortlists. |
| Local Production Partnership | TRAI-governed BIS telecom mandates accelerate Indian assembly operations reducing import dependency for domestic deployments. |
| Cloud-Native Fleet Platform | Edge-to-cloud architectures enable over-the-air firmware distribution and usage-based insurance underwriting for Southeast Asian gig riders. |
| Sensor Fusion Integration | Camera-plus-radar configurations capture margin from discrete component suppliers in Brazilian and Indian urban freight networks. |
| Cybersecurity Pipeline Buildout | ISO/SAE 21434 validation timelines erect barriers against low-specification entrants in liability-critical ride assistance systems. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors, Tier 1 supplier procurement leads, cellular module engineering heads, and logistics platform CTOs with secondary validation against ECE R10 type approval databases, TRAI equipment certification registries, and automotive electronics SEC disclosures. Bottom-up segment sizing triangulated against top-down fleet deployment estimates.
Segment-weighted modeling distributed value across ride assistance systems, connectivity modules, and diagnostic tools by technology layer, end-user procurement volume, and regional regulatory cluster. CAGRs derived from installed base growth, replacement cycle compression, and subscription revenue conversion rates across the projection horizon. Forecast inputs incorporated cellular protocol transition timelines and battery management system integration density for electric two-wheeler platforms.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated 2G network sunset schedules or lithium-ion cobalt price spikes. Material deviation in ECE R10 enforcement stringency or Indian BIS certification timeline delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Germany E-Bike Market
Bikes and Motorcycles
Australia E- Bike Market
Bikes and Motorcycles
UAE Motorcycle ADAS Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Bike Computer Market
Bikes and Motorcycles
Bicycle Mechanical Disc Brake Market
Bikes and Motorcycles
Smart Electric Bikes Market
Bikes and Motorcycles
Motorcycle Drivetrain Market
Bikes and Motorcycles
Motorcycle Airbag Market
Bikes and Motorcycles
Aluminum Alloy Bicycle Crankset Market
Bikes and Motorcycles
Cargo Bicycles Market
Bikes and Motorcycles
Europe Two-Wheeler Market
Bikes and Motorcycles
Motorcycle Tubeless Tire Market
Bikes and Motorcycles
Maxi Scooter Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Cruiser Bikes Market