
 Germany E-Bike Market | 2026-2036
Germany E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Germany E-Bike Market Foresight
Modular battery subscription bundling is consolidating buyer choice around service-inclusive ownership models rather than upfront hardware purchases. Riese & Müller GmbH leverages premium frame manufacturing to dominate high-performance cargo configurations. Cube Bikes anchors its position through broad retail distribution across German specialist dealers. Kalkhoff Werke GmbH specializes in integrated mid-drive systems for urban commuter segments.
An e-bike combines a pedal-assisted bicycle with an electric motor rated up to 250 watts and a rechargeable lithium-ion battery pack, governed by EU EN 15194 standards that cap motor assistance at 25 km/h for standard pedelecs. The primary commercial purpose is to extend cycling accessibility across hilly terrain, longer distances, and older demographics while reducing automotive dependency in dense urban environments. City E-Bike configurations lead unit volumes due to daily commuter reliance on weather-protected frame designs and rack-integrated battery placement. Mountain E-Bike demand accelerates fastest among sports enthusiasts seeking torque-rich mid-drive motors for alpine trail access. Cargo E-Bike applications command the strongest margin pools as commercial fleet operators prioritize payload-rated frames and dual-battery architectures.
The KBA enforces type-approval protocols for S-pedelecs exceeding 25 km/h, while EU REACH regulations restrict hazardous substances in battery chemistries and frame coatings. Germany's Federal Ministry for Digital and Transport allocates infrastructure funding through the National Cycling Plan, mandating protected lane standards that directly expand addressable ridership. Stakeholders must monitor pending amendments to motor insurance requirements and battery recycling quotas under the EU Battery Regulation.
Market Dynamics
Modular battery subscription bundling is consolidating buyer choice around service-inclusive ownership models rather than upfront hardware purchases, compressing traditional retail financing structures across German metropolitan corridors.
Growth Catalysts
- KBA Type-Approval Evolution:The Kraftfahrt-Bundesamt's evolving framework for speed pedelecs is accelerating product certification standardization, enabling faster S-pedelec commercialization across urban delivery fleets.
- State Transport Ministry Infrastructure Investment:Cycling infrastructure investments by German state transport ministries have expanded protected lane networks, directly extending addressable ridership in metropolitan commuting corridors.
- Cargo E-Bike Fleet Conversion:Urban delivery operators in Berlin, Hamburg, and Munich are replacing vans with cargo e-bikes to navigate congestion zones, creating sustained commercial demand for payload-rated dual-battery architectures.
Market Restraints
- Lithium-Ion Cell Supply Concentration:Battery cell manufacturing concentrates in East Asian supply bases, exposing German assemblers to input cost volatility and logistics disruption risks.
- EU REACH Compliance Burden:REACH restrictions on hazardous substances in battery chemistries and frame coatings impose material substitution costs and extended qualification timelines for domestic manufacturers.
- Speed Pedelec Insurance Friction:Pending amendments to motor insurance requirements for S-pedelecs create regulatory uncertainty, dampening consumer adoption in the high-performance commuter segment.
Strategic Opportunities
- Battery Recycling Mandate Preparation:The EU Battery Regulation's forthcoming recycling quotas incentivize early investment in closed-loop material recovery infrastructure by German battery system integrators.
- Service-Subscription Channel Expansion:Direct-to-fleet subscription platforms bypass traditional specialist dealer networks, capturing recurring revenue from commercial operators in Bavaria and Baden-Württemberg.
- Integrated Mid-Drive System Convergence:Torque sensor and mid-drive motor technology convergence enables premium positioning in alpine-accessible Mountain E-Bike configurations for sports enthusiasts.
Industry Challenges
- Specialized Technician Shortage:The shortage of certified e-bike diagnostic technicians limits after-sales service capacity expansion across specialist dealer networks in eastern German states.
- Dual Certification Timeline Compression:Simultaneous KBA type-approval and EU EN 15194 conformity assessment processes extend product launch windows for speed pedelec variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany E-Bike Market |
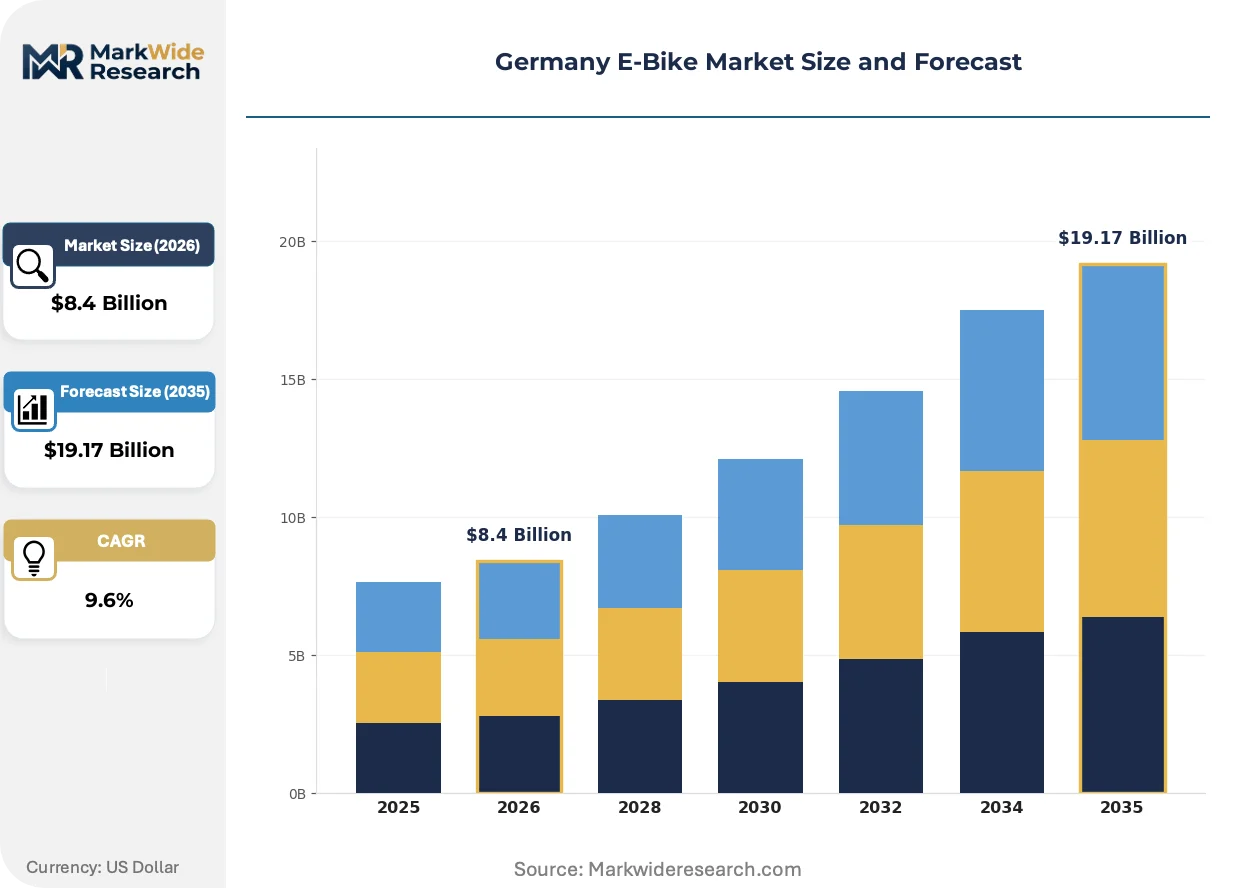
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.17 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bike, Mountain E-Bike, Folding E-Bike, Cargo E-Bike, Road E-Bike Technology: Mid-Drive Motor, Hub Motor, Friction Drive, Geared Hub Motor, Direct Drive Motor Application: Commuting, Leisure Cycling, Delivery Services, Fitness & Training, Tourism End User: Daily Commuters, Sports Enthusiasts, Delivery Operators, Rental Agencies, Fitness Centers |
| Companies Covered | Riese & Müller GmbH, Prophete GmbH & Co. KG, Cube Bikes, Fischer Bikes, Winora Staiger GmbH, Kalkhoff Werke GmbH, Canyon Bicycles GmbH, KTM Bike Industries, Haibike, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany E-Bike Market Shifts & Advancements
Rack-integrated battery placement and weather-protected frame architectures are converging with connected fleet management systems, reshaping how urban commuters and commercial operators evaluate total cost of ownership.
Smart battery management systems with cellular connectivity are unifying real-time diagnostics, geofencing, and predictive maintenance alerts into single-platform fleet oversight tools. Municipal logistics operators in Cologne and Frankfurt are deploying these systems at scale. This convergence is compressing service response times and enabling usage-based subscription pricing models that displace traditional capital expenditure structures.
The EU Battery Regulation is mandating carbon footprint disclosure and recycled content minimums for industrial batteries sold in member states. German manufacturers must requalify supply chains and establish material provenance documentation systems. The Cargo E-Bike segment faces the steepest compliance curve due to dual-battery architectures and commercial duty cycles.
Leasing and subscription contracts are displacing outright purchase as the dominant transaction structure among fleet procurement officers. Specialist dealers in North Rhine-Westphalia report compressed sales cycles as buyers prioritize operational flexibility over asset ownership. This behavioral pivot is most pronounced in last-mile delivery verticals where vehicle utilization rates and uptime guarantees determine contract awards.
Germany E-Bike Market Segmentation
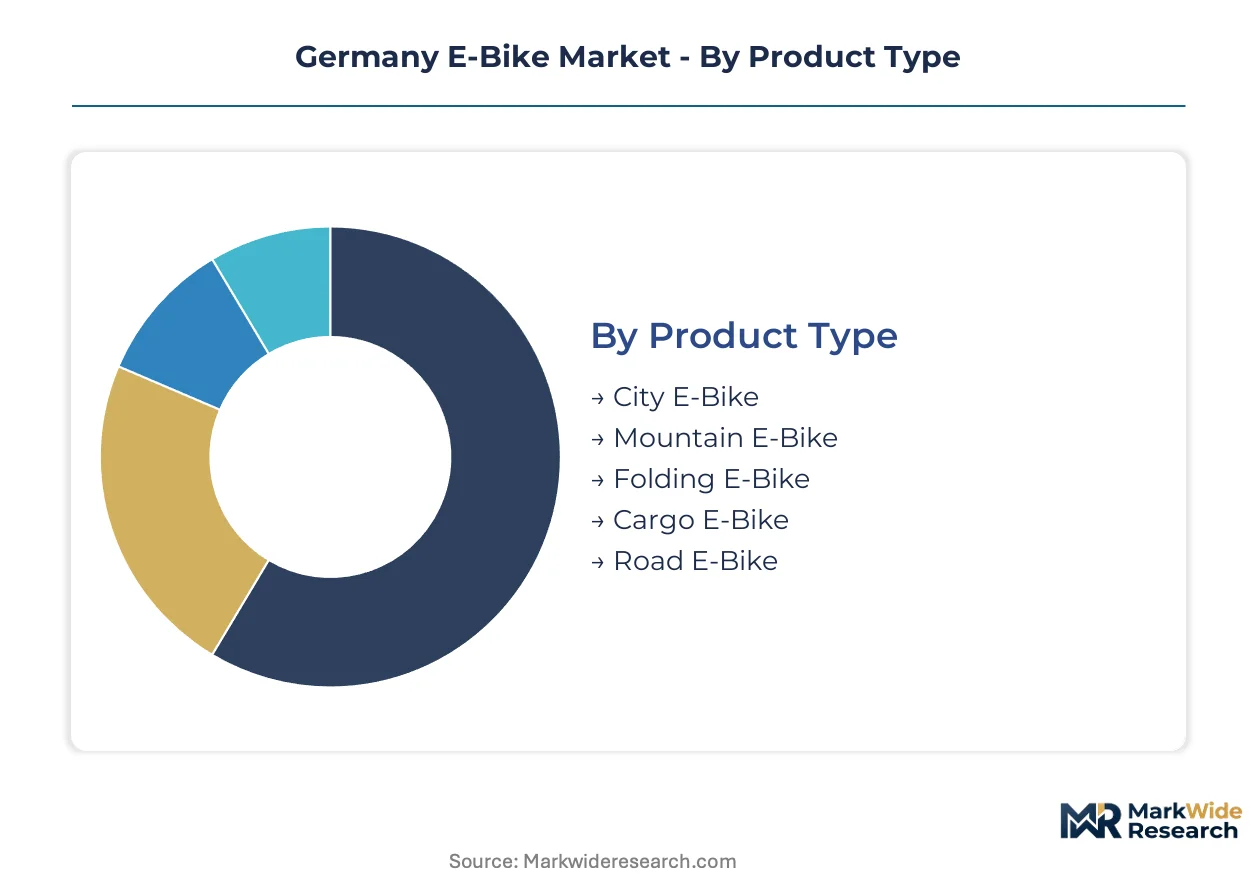
Segmentation in the Germany E-Bike Market reveals how distinct rider profiles, technical architectures, and use-case economics fragment demand across metropolitan corridors and alpine-adjacent regions. Understanding these fault lines enables manufacturers to align motor specifications, battery configurations, and distribution channels with the precise performance thresholds each buyer segment demands.
Product Type:
Frame geometry and payload capacity drive the initial purchase decision, with urban density and terrain access determining which configuration commands household budgets.
- City E-Bike:Step-through frames with rack-integrated batteries and fender-protected drivetrains dominate daily commuting across Berlin, Hamburg, and Munich. Protected lane expansion by state transport ministries has concentrated ridership in metropolitan corridors where weather-resistant designs extend seasonal usage.
- Cargo E-Bike:Dual-battery architectures and payload-rated frames command the strongest margin pools as Berlin-based delivery fleets replace diesel vans for last-mile logistics. Commercial operators prioritize uptime guarantees and service contracts over upfront hardware costs.
- Mountain E-Bike:Torque-rich mid-drive motors enable alpine trail access for sports enthusiasts in Bavaria and Baden-Württemberg.
- Folding E-Bike:Compact hinge mechanisms and reduced battery weight target multimodal commuters combining rail and cycling segments.
- Road E-Bike:Drop-bar configurations with minimal motor drag appeal to fitness-oriented riders seeking assisted endurance training.
Volume sits with City E-Bike configurations; growth tilts toward Cargo E-Bike applications as fleet electrification accelerates.
Technology:
Motor placement and torque delivery characteristics determine system efficiency, maintenance intervals, and the rider's biomechanical experience across varying terrain grades.
- Mid-Drive Motor:Centralized weight distribution and gear-ratio optimization deliver superior hill-climbing torque for alpine-accessible Mountain E-Bike configurations. Kalkhoff Werke GmbH and Riese & Müller GmbH have consolidated market position around integrated mid-drive architectures for urban commuter and cargo segments.
- Hub Motor:Direct-drive and geared variants offer simplified maintenance and lower unit costs for high-volume City E-Bike production. Cube Bikes leverages hub motor sourcing flexibility to maintain broad retail distribution across German specialist dealer networks.
- Friction Drive:Retrofit-friendly roller mechanisms target secondary bike conversions and rental fleet standardization.
- Geared Hub Motor:Internal planetary gears multiply torque output for compact frame clearances in Folding E-Bike designs.
- Direct Drive Motor:Regenerative braking capability and silent operation suit flat-terrain commuting in northern German states.
Hub motor configurations retain volume leadership; mid-drive systems are gaining share fastest in premium and commercial segments.
Application:
Use-case intensity and duty-cycle requirements differentiate procurement criteria between individual consumers and commercial fleet operators.
- Commuting:Daily ridership across metropolitan corridors depends on protected lane infrastructure and weather-protected frame architectures. State transport ministry investments in cycling networks have expanded addressable ridership in North Rhine-Westphalia and Bavaria.
- Delivery Services:Urban logistics operators in Cologne, Frankfurt, and Berlin prioritize dual-battery uptime and cellular-connected fleet management platforms. Subscription pricing models are displacing capital expenditure structures in this vertical.
- Leisure Cycling:Weekend recreational use concentrates in lake and forest districts surrounding major metropolitan areas.
- Fitness & Training:Power-meter integration and training app connectivity attract performance-oriented riders.
- Tourism:Rental agencies in alpine and wine-growing regions deploy hardtail Mountain E-Bike fleets for guided trail experiences.
Commuting applications anchor unit volumes; Delivery Services represent the steepest expansion trajectory as congestion zones tighten van access.
End User:
Procurement authority and total cost of ownership sensitivity fragment the buyer base between individual households and institutional fleet managers.
- Daily Commuters:Individual purchasers in metropolitan corridors evaluate purchase price, theft protection, and service network proximity. Modular battery subscription bundling is consolidating buyer choice around service-inclusive ownership models.
- Delivery Operators:Fleet procurement officers in Berlin, Hamburg, and Munich negotiate utilization-based contracts prioritizing vehicle uptime over asset ownership. Direct-to-fleet subscription platforms bypass traditional specialist dealer networks.
- Sports Enthusiasts:Torque and battery range specifications dominate purchase criteria for alpine trail access.
- Rental Agencies:Standardized maintenance protocols and cellular diagnostics enable fleet oversight at scale.
- Fitness Centers:Commercial gym operators deploy Road E-Bike configurations for indoor training studio integration.
Individual Daily Commuters generate the highest unit volumes; Delivery Operators are driving the fastest margin expansion through recurring service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's e-bike production concentrates in southern and western industrial clusters, while consumption spreads across metropolitan corridors where state cycling infrastructure investments have expanded protected lane networks. The market exhibits strong north-south variation in adoption intensity tied to topography and urban density.
Bavaria
Alpine terrain and Munich's dense urban core drive demand for torque-rich mid-drive configurations across both commuter and sports segments. The Bavarian State Ministry for Housing, Construction and Transport funds protected lane expansion along the Isar corridor. Industrial concentration centers on Rosenheim and Nuremberg, where frame fabricators and motor system integrators maintain assembly operations.
North Rhine-Westphalia
The Ruhr metropolitan network and Cologne-Düsseldorf corridor generate the highest unit volumes for city e-bike configurations serving multimodal commuters. State transport ministry investments in the Radschnellweg network prioritize protected arterial connections. Last-mile delivery operators in Cologne and Düsseldorf are deploying cargo e-bike fleets at scale to navigate tightening congestion zones.
Baden-Württemberg
Stuttgart's hilly topography and the Neckar Valley industrial belt sustain demand for high-torque commuter configurations. The state's Ministry of Transport supports e-bike integration with regional rail through station-based charging infrastructure. Manufacturing clusters around Stuttgart and Friedrichshafen host precision frame engineering and component system suppliers.
Berlin-Brandenburg
Flat terrain and extensive cycling infrastructure have normalized e-bike commuting across socioeconomic strata. The Senate Department for Environment, Transport and Climate Protection administers congestion zone exemptions for commercial cargo e-bike operators. Urban delivery fleets in Berlin-Mitte and Prenzlauer Berg are replacing diesel vans with dual-battery cargo configurations.
Hamburg
The port city's compact urban structure and Elbe tunnel congestion sustain strong commuter adoption. The Free and Hanseatic City of Hamburg's transport authority prioritizes cycling bridge connections and ferry integration. Cargo e-bike logistics operators serve the HafenCity and Sternschanze districts with payload-rated fleet configurations.
Germany E-Bike Market Competitive Landscape
The competitive structure tilts toward specialist frame manufacturers with integrated motor system capabilities rather than pure assemblers. Premium positioning dominates in cargo and mountain configurations, while volume production concentrates in urban commuter segments. Two strategic archetypes define the field: vertically integrated frame-engineering specialists and broad-distribution platform players. Competitive moves center on retail network consolidation and subscription-based ownership model development.
Among German-based GmbH-structured specialists, Riese & Müller GmbH, Kalkhoff Werke GmbH, and Cube Bikes occupy distinct positioning tiers. Riese & Müller exemplifies the premium-engineering archetype through its frame manufacturing depth. Kalkhoff represents integrated mid-drive system specialization for urban commuter demand. Cube Bikes anchors broad retail distribution across specialist dealer networks. These three entities collectively illustrate how German market structure rewards manufacturing depth over pure brand marketing.
| Leading Market Players |
|---|
| Riese & Müller GmbH |
| Prophete GmbH & Co. KG |
| Cube Bikes |
| Fischer Bikes |
| Winora Staiger GmbH |
| Kalkhoff Werke GmbH |
| Canyon Bicycles GmbH |
| KTM Bike Industries |
| Haibike |
| Others |
Supply & Pricing Matrix
Lithium-ion cell costs cascade through German e-bike pricing tiers, with East Asian cathode and anode materials feeding assembly operations in Bavaria and Baden-Württemberg before reaching fleet procurement officers and metropolitan commuters through subscription or outright purchase structures.
Pricing Analysis
Margin tightening in mid-tier commuter configurations reflects hub motor commoditization and aggressive retail financing competition. Three-tier pricing structure across premium, standard, and economy levels separates Riese & Müller's frame-engineering depth from Cube's distribution scale and entry-level Asian imports. Cost-down pressure on standard pedelecs accelerates because state transport ministry bulk procurement programs prioritize unit economics over feature depth. Fleet operators exhibit lowest price sensitivity due to total cost of ownership calculations; individual commuters in eastern German states show highest elasticity.
Supply Chain Analysis
Technician certification bottlenecks in Saxony and Thuringia constrain final assembly expansion despite strong frame fabrication capacity in southern industrial clusters. Battery cell manufacturing concentrates in China, South Korea, and Japan, exposing German assemblers to maritime logistics disruption and EU Battery Regulation compliance timelines. Frame alloys and rare-earth magnet materials draw from established European and Asian metallurgical suppliers. Single-source vulnerability in motor controller chipsets poses the dominant structural risk. Distribution runs through specialist dealer networks in North Rhine-Westphalia and Bavaria, with direct-to-fleet platforms gaining share in Berlin and Hamburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German e-bike manufacturing is consolidating around captive battery system production and in-house mid-drive motor development as the decisive competitive moat.
For Market Incumbents: Anchor service network density in eastern German states where certified technician scarcity limits aftermarket capacity expansion. Deepen backward integration into battery pack assembly to offset East Asian cell supply volatility and meet EU Battery Regulation recycling quota timelines. Defend against subscription-platform disintermediation by embedding fleet management software into hardware sales. For New Entrants and Emerging Players: Capture cargo e-bike fleet subscription white space in Cologne, Frankfurt, and Stuttgart where utilization-based contracts displace capital expenditure structures. Target last-mile delivery verticals in congestion-zone municipalities with uptime-guaranteed service bundling. Enter through direct-to-fleet platforms bypassing established specialist dealer gatekeepers. For Investors and Strategic Acquirers: KBA type-approval backlog clearance for S-pedelec variants is the leading indicator that premium commuter segment growth will accelerate. Frame-engineering specialists with integrated motor system capabilities represent the optimal acquisition archetype over pure brand marketers. Watch for EU Battery Regulation carbon footprint disclosure enforcement as the inflection signal for supply chain requalification investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Assembly | Captive cell sourcing mitigates East Asian supply concentration and accelerates EU Battery Regulation compliance documentation. |
| Specialist Dealer Network Consolidation | Channel control in Bavaria and North Rhine-Westphalia secures service capacity and locks out subscription-platform competitors. |
| Fleet Management Platform Development | Cellular-connected diagnostics enable recurring revenue from Cologne and Berlin delivery operators prioritizing uptime guarantees. |
| KBA Type-Approval Investment | Accelerated S-pedelec certification unlocks premium commuter segment growth before pending motor insurance amendments stabilize. |
| Technician Certification Program Expansion | Workforce pipeline development in Saxony and Thuringia removes aftermarket service bottlenecks constraining volume growth. |
Research Methodology
Multi-period observation of KBA registration data, state transport ministry infrastructure commitments, and fleet operator procurement patterns anchored the trend analysis, supplemented by interviews with e-bike product development directors, specialist dealer network managers, fleet procurement officers at logistics operators, and KBA type-approval technical assessors. Secondary validation drew from EU EN 15194 conformity assessment databases, Federal Ministry for Digital and Transport cycling infrastructure disbursement records, and EU Battery Regulation implementation guidance. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Segment-weighting across product type, motor technology, application intensity, and end-user procurement authority structured the analytical framework throughout the forecast period. CAGRs were derived from fitted growth curves calibrated to historical KBA registration trajectories and infrastructure investment elasticity models. Key inputs included state-level protected lane completion schedules and commercial fleet electrification mandates in congestion-zone municipalities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Battery Regulation recycling quota enforcement timelines and KBA motor insurance requirement amendments. Forecasts reflect documented assumptions regarding infrastructure investment continuity and cell supply chain stability. Material deviation in KBA type-approval processing speed or lithium-ion cell logistics disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
UAE Motorcycle ADAS Market
Bikes and Motorcycles
Global Motorcycle Airbag System Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Trike Market
Bikes and Motorcycles
Saudi Arabia Motorcycle ADAS Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
Used Bike Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Motorcycle Fairings Market
Bikes and Motorcycles
South America Two-Wheeler Market
Bikes and Motorcycles
Netherlands E-Bike Market
Bikes and Motorcycles
On-Road Motorcycles Market
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
Asia-Pacific Two-Wheeler Taxi Market
Bikes and Motorcycles
Electric Cargo Bikes Market