
 Europe Two-Wheeler Market | 2026-2036
Europe Two-Wheeler Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Two-Wheeler Market Intelligence
Electrification of powertrains is rewriting the engineering priorities for European two-wheeler manufacturers. Honda Motor Co., Ltd. leverages its established hybrid-electric expertise to anchor its position in commuter scooters across Southern Europe. BMW Motorrad differentiates through in-house battery architecture and premium segment positioning. KTM AG specializes in performance-oriented electric mobility concepts that extend its motorsport heritage into street-legal applications.
A two-wheeler encompasses any motorized or pedal-assisted vehicle with two aligned wheels, typically featuring steel or aluminum frame construction, internal combustion or electric propulsion systems generating up to 100 kW, and braking configurations ranging from drum to dual-channel ABS. These vehicles serve personal transportation, commercial logistics, and recreational riding functions across European road networks. The vehicle type dimension shows e-bikes and scooters capturing urban commuter preference while motorcycles above 400cc retain enthusiast loyalty and higher per-unit margins. Engine capacity segmentation reveals the under 125cc bracket dominating unit volume through moped and scooter sales, though the 251cc-400cc middleweight category attracts riders upgrading from entry-level machines.
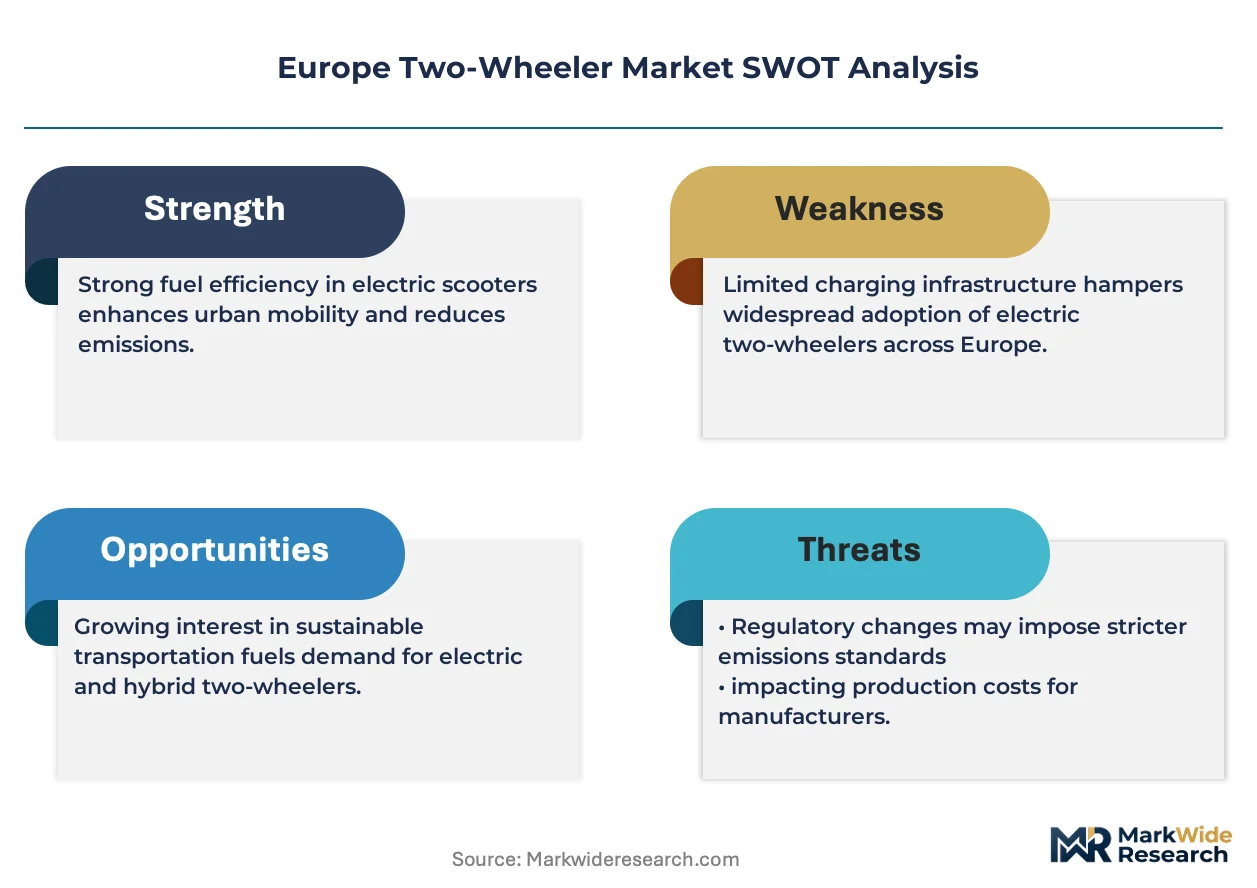
The EU Green Deal framework and national ICE restrictions in France, Italy, and Germany are mandating zero-emission powertrains for new urban vehicle registrations. ECHA chemical compliance and CE marking requirements govern battery composition, frame metallurgy, and electronics integration across the European Economic Area. REACH substance regulations constrain coating and plating processes used in exhaust and chassis manufacturing. Stakeholders must weigh subsidy dependency against the capital intensity of cell production and charging infrastructure buildout as the regulatory window for combustion-powered new sales narrows.
Market Dynamics
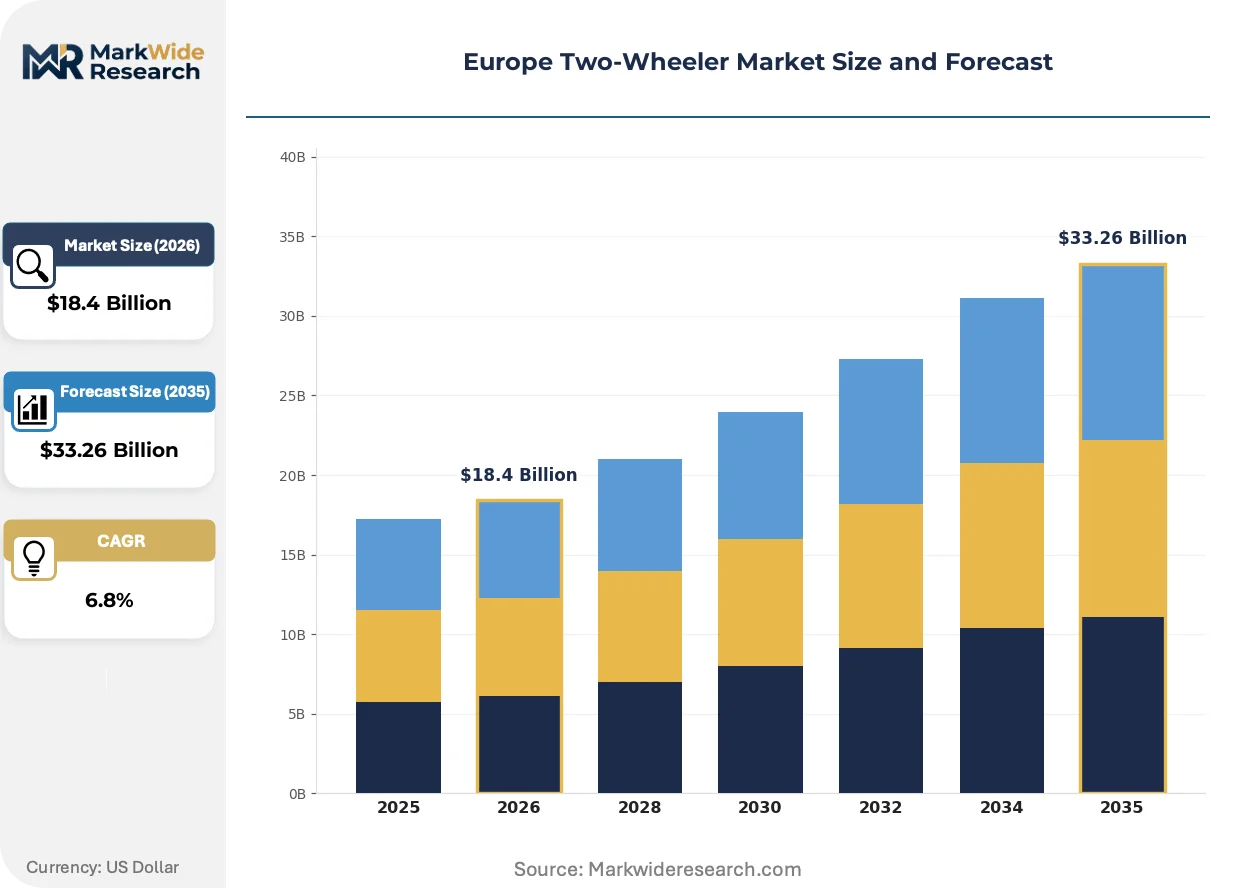
The EU Green Deal's ICE phase-out mandates are compressing manufacturer transition timelines while urban delivery electrification accelerates fleet procurement across European capitals. This regulatory-engineering collision is forcing simultaneous powertrain redesign and supply chain reconfiguration.
Growth Catalysts
- Last-mile logistics electrification:Urban delivery fleets in Paris, Milan, and Berlin are expanding electric scooter procurement as congestion charges and low-emission zones tighten operational economics for combustion vehicles.
- National subsidy frameworks:France's ecological bonus, Italy's ecobonus mobilità, and Germany's environmental bonus are compressing electric two-wheeler price premiums and accelerating consumer uptake.
- Battery energy density gains:Cell chemistry improvements are extending electric motorcycle range toward parity with 125cc-250cc ICE equivalents, removing the primary barrier to commuter adoption.
Market Restraints
- Lithium cell supply concentration:European manufacturers remain dependent on Asian cell suppliers, exposing production schedules to geopolitical friction and shipping bottlenecks.
- Charging infrastructure gaps:Residential charging access remains uneven across Southern European apartment-dense cities, constraining urban market penetration.
- REACH compliance costs:ECHA substance regulations governing battery composition and frame coatings are adding certification overhead and extending product development cycles.
Strategic Opportunities
- Swappable battery standardization:The Gogoro-style battery exchange model offers fleet operators in Barcelona and Amsterdam route flexibility without charging downtime.
- Commercial leasing channels:B2B subscription models for delivery fleets bypass upfront capital barriers and capture recurring revenue streams.
- CE marking harmonization:Unified conformity assessment across the European Economic Area simplifies multi-country market entry for specialized electric motorcycle entrants.
Industry Challenges
- Power electronics talent scarcity:European engineering pools lack sufficient embedded systems and thermal management specialists for high-voltage motorcycle architectures.
- Legacy dealer network retraining:Traditional motorcycle retailers require capability upgrades for electric powertrain diagnostics and battery servicing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Two-Wheeler Market |
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $33.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Motorcycles, Scooters, Mopeds, E-Bikes Engine Capacity: Under 125cc, 126cc-250cc, 251cc-400cc, Above 400cc End User: Commuters, Tourists, Delivery Services, Enthusiasts Brand: Honda, Yamaha, Harley-Davidson, KTM |
| Companies Covered | Piaggio & C. SpA, KTM AG, BMW Motorrad, Suzuki Motor Corporation, Triumph Motorcycles, Honda Motor Co., Ltd., Ducati, Husqvarna Motorcycles, Yamaha Motor Co., Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Two-Wheeler Market Strategic Shifts & Innovations
Digital integration and powertrain electrification are converging to redefine vehicle architecture and ownership models across the European two-wheeler segment.
Over-the-air software updates are virtualizing traditional hardware-dependent features. Premium manufacturers are deploying cloud-connected ECUs that enable post-purchase performance mapping and feature activation. Urban commuter segments are adopting subscription-unlocked functionality at accelerating rates. This capability is virtualizing the historical separation between vehicle specification tiers and aftermarket modification markets.
EU Green Deal national implementation timelines are mandating zero-emission new registrations in urban centers. France's 2035 ICE phase-out for new motorcycles and Italy's corresponding mobility transition framework are forcing powertrain portfolio restructuring. The 125cc scooter segment faces the most compressed transition window and is responding with accelerated platform electrification.
Fleet procurement is consolidating around total-cost-of-ownership contracting. Large delivery operators in Madrid and Lisbon are shifting from unit purchase to per-kilometer service agreements with maintenance and battery replacement bundled. This restructuring is most visible in food delivery and parcel logistics verticals where vehicle utilization rates justify operational expenditure models over capital deployment.
Europe Two-Wheeler Market Segmentation
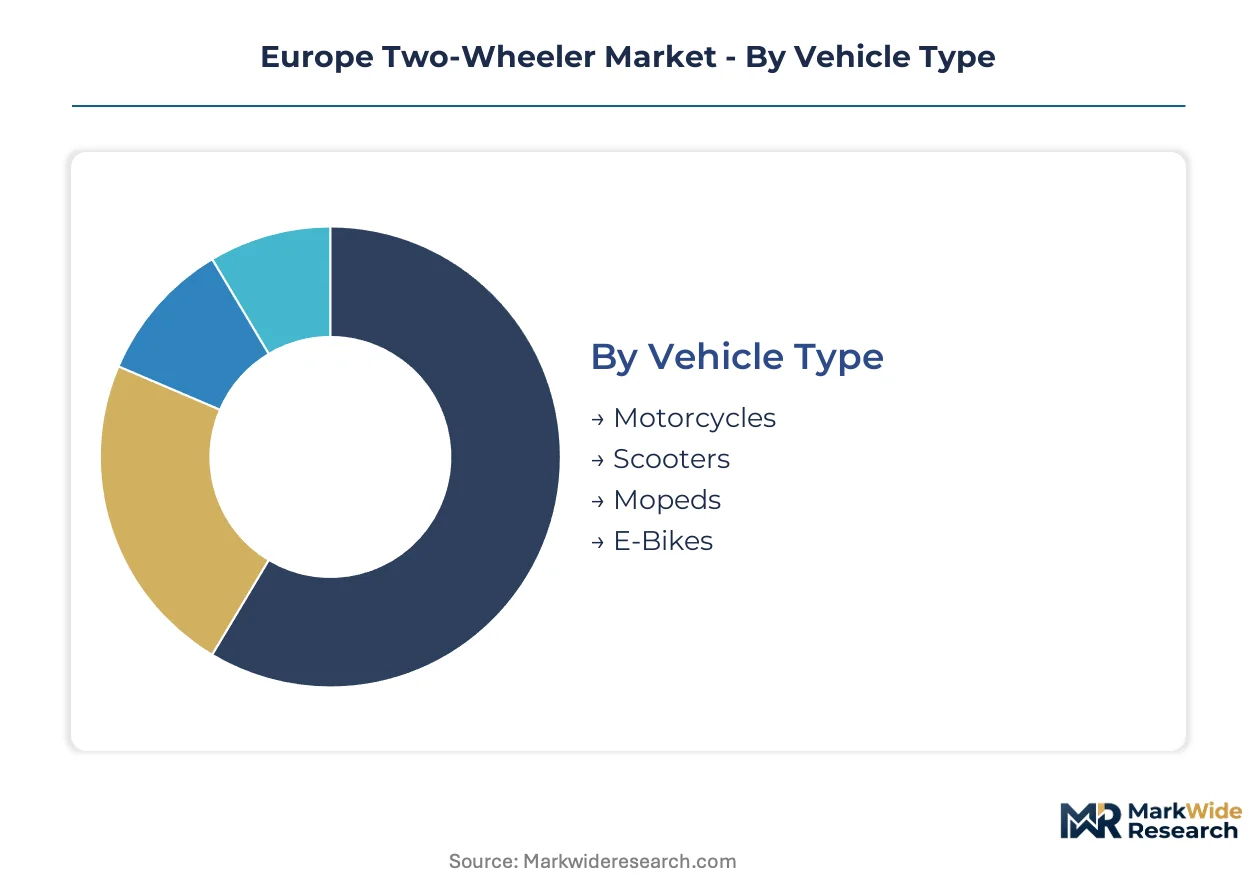
Segmentation reveals how EU Green Deal compliance pressures and urban mobility electrification are reshaping procurement patterns across vehicle classes. Manufacturers must align powertrain portfolios with divergent end-use economics and national subsidy eligibility criteria.
Vehicle Type:
Mature internal combustion platforms coexist with emerging electric architectures as fleet operators and consumers navigate transition timelines.
- Motorcycles:Internal combustion and electric powertrains from 125cc to 1000cc+ serve touring, sport, and commuter functions. French and German riders above 400cc demonstrate strong loyalty to premium displacement segments despite electrification pressure.
- Scooters:Step-through frames with automatic transmissions dominate Southern European urban cores. Milan and Barcelona delivery fleets are electrifying this category fastest due to congestion zone exemptions and per-kilometer operating cost advantages.
- Mopeds:50cc-equivalent machines with speed restrictions address license-accessible mobility for younger riders. Italian and Spanish markets retain significant moped volume through graduated licensing frameworks.
- E-Bikes:Pedal-assist bicycles with 250W-750W motors occupy the micromobility spectrum below full motorcycle regulation. German and Dutch consumers are adopting speed pedelecs for suburban-urban commuting as cycle infrastructure expands.
Motorcycles retain volume leadership; E-Bikes hold the steepest expansion curve.
Engine Capacity:
Cost tier stratification separates subsidy-eligible urban commuters from premium displacement enthusiasts.
- Under 125cc:Entry-level scooters and mopeds face the most compressed ICE phase-out timelines under EU Green Deal national implementations. French ecological bonus eligibility concentrates demand in electric variants of this bracket.
- 126cc-250cc:Light motorcycles and maxi-scooters bridge urban commuting and intercity travel. Italian riders upgrading from 125cc restrictions drive replacement demand in this segment.
- 251cc-400cc:Middleweight machines attract experienced commuters and entry-level enthusiasts seeking versatility. German touring riders favor this displacement for Alpine route accessibility.
- Above 400cc:Premium motorcycles with advanced electronics and performance mapping serve enthusiast and touring markets. KTM AG and BMW Motorrad concentrate R&D investment here to defend margin structures against electrification pressure.
Under 125cc captures unit volume concentration; Above 400cc maintains margin leadership.
End User:
Application-specific utilization patterns dictate powertrain selection and ownership model preferences.
- Commuters:Daily urban travelers prioritize total cost of ownership and parking convenience. Paris and Berlin residents are shifting toward electric scooters as low-emission zones tighten combustion vehicle access.
- Tourists:Seasonal rental demand concentrates in Mediterranean coastal regions and Alpine corridors. Italian and Croatian rental fleets are adding electric scooters to comply with historic center access restrictions.
- Delivery Services:High-utilization commercial operators in Madrid and Lisbon favor swappable-battery scooters for route flexibility. Per-kilometer service contracts are displacing unit purchases in this vertical.
- Enthusiasts:Recreation-focused riders prioritize performance characteristics and brand heritage. German and Austrian markets sustain premium motorcycle demand through motorsport culture and touring infrastructure.
Commuters represent the largest addressable base; Delivery Services are expanding most quickly.
Brand:
Customer type segmentation separates mass-market volume players from premium positioning specialists.
- Honda:Japanese manufacturer with hybrid-electric expertise anchoring commuter scooter segments across Southern Europe. Italian and Spanish urban riders favor Honda for reliability and service network density.
- Yamaha:Diversified powertrain portfolio spanning 50cc mopeds to 1000cc+ sport-touring machines. French consumers demonstrate strong brand affinity in the 125cc-400cc commuter categories.
- Harley-Davidson:American heritage brand concentrating on above 400cc cruiser and touring segments. German enthusiasts sustain European volume despite demographic aging challenges.
- KTM AG:Austrian specialist leveraging motorsport heritage for performance-oriented street-legal applications. Italian and Austrian riders favor KTM for off-road capability and premium middleweight sport platforms.
Honda retains volume leadership; KTM AG holds the steepest expansion curve in premium electric mobility concepts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's two-wheeler trade flows reveal a structural deficit in electric powertrain components, with battery cell imports dominating supply chains while finished vehicle exports concentrate in premium internal combustion segments. Import dependency on Asian lithium-ion suppliers shapes manufacturing strategies across the continent.
Germany
Motorcycle enthusiasts in Bavaria and Baden-Württemberg sustain demand for above 400cc touring machines despite electrification pressure. The KBA enforces stringent type-approval standards that extend homologation timelines for new electric entrants. Munich's urban delivery operators are piloting swappable-battery scooter fleets to navigate congestion zone restrictions.
France
Parisian commuters are shifting toward electric scooters as the capital's low-emission zone tightens combustion vehicle access. The ecological bonus subsidizes electric two-wheeler purchases, compressing price premiums against ICE equivalents. Lyon and Marseille harbor logistics clusters where food delivery fleets are consolidating procurement around per-kilometer service contracts.
Italy
Milan's historic center access restrictions are accelerating rental fleet electrification for tourist and commuter segments. The ecobonus mobilità program channels subsidies toward 125cc-equivalent electric scooters. Bologna and Turin anchor manufacturing corridors where legacy scooter producers are restructuring powertrain portfolios toward zero-emission platforms.
Spain
Madrid's delivery services sector is adopting swappable-battery architectures to eliminate charging downtime on high-utilization routes. Municipal low-emission ordinances in Barcelona and Valencia are phasing out combustion scooter registrations in central districts. Andalusian coastal tourism zones are adding electric scooters to rental fleets to comply with historic access regulations.
Netherlands
Amsterdam's dense cycling infrastructure supports speed pedelec adoption for suburban-urban commuting. The national environmental bonus intersects with municipal parking incentives to accelerate electric two-wheeler uptake. Eindhoven's technology corridor hosts battery system integrators serving Nordic and German export markets.
Europe Two-Wheeler Market Key Industry Players
On the supply side, the industry is consolidating around heritage manufacturers with established dealer networks and emerging electric specialists with direct-to-fleet distribution models. Tiered competitive dynamics separate mass-market volume players from premium displacement specialists and urban mobility technology providers. Strategic archetypes include legacy internal combustion incumbents defending margin structures, electric-native entrants capturing subsidy-driven urban demand, and diversified powertrain conglomerates leveraging hybrid expertise. Dominant competitive moves encompass portfolio electrification investments and B2B fleet service contract expansion.
Within the heritage European motorcycle tier, KTM AG and BMW Motorrad exemplify premium positioning strategies that extend motorsport and touring credibility into emerging electric architectures. Honda Motor Co., Ltd. represents the diversified conglomerate archetype, leveraging hybrid-electric expertise across commuter scooter segments. These three entities anchor distinct competitive vectors—performance specialization, premium engineering, and mass-market reliability—that structure rivalry dynamics as regulatory phase-out timelines compress.
| Leading Market Players |
|---|
| Piaggio & C. SpA |
| KTM AG |
| BMW Motorrad |
| Suzuki Motor Corporation |
| Triumph Motorcycles |
| Honda Motor Co., Ltd. |
| Ducati |
| Husqvarna Motorcycles |
| Yamaha Motor Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Bologna's manufacturing corridor anchors European scooter production capacity, with legacy Italian producers restructuring toward zero-emission platforms. This geographic concentration of final assembly feeds downstream pricing power toward established brands while compressing margins for component suppliers locked into long-term supply agreements.
Pricing Analysis
Current-generation electric powertrains command substantial premiums over prior-generation internal combustion equivalents, while next-generation solid-state architectures threaten further price disruption. Three-tier pricing structure across premium, standard, and economy levels separates BMW Motorrad's battery-integrated platforms from Honda's commuter scooters and entry-level Chinese imports. Price differentiation hinges on CE certification tier and after-sales service bundling. Cost compression in the standard tier is intensifying because subsidy eligibility windows are narrowing across France, Italy, and Germany. Delivery fleet operators exhibit the highest price sensitivity due to total-cost-of-ownership scrutiny, while enthusiast segments above 400cc demonstrate the lowest sensitivity.
Supply Chain Analysis
Magna Steyr and Foxconn hold contract-manufacturing capacity for electric two-wheeler final assembly, with Bosch and Continental dominating power electronics integration. Geographic supply concentration centers on China for lithium-ion cells, South Korea for cathode materials, and Germany for precision motor components. Raw material dependencies include cobalt from the DRC, lithium from Chile and Australia, and rare earth elements from China. Single-source vulnerability in Asian cell suppliers exposes European manufacturers to geopolitical friction and shipping bottlenecks. Distribution runs through heritage dealer networks for consumer sales and direct-to-fleet contracting for commercial operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a substitution defense against micromobility-as-a-service platforms and shared electric scooter fleets that threaten private vehicle ownership economics in urban cores.
For Market Incumbents: Pre-empt platform commoditization by securing exclusive battery supply agreements with Korean cell producers and embedding over-the-air revenue streams into vehicle architectures. KTM AG and BMW Motorrad must defend premium positioning against electric-native entrants by accelerating motorsport-derived performance mapping. Vertical integration into thermal management systems offers margin protection as power electronics become the primary value driver. For New Entrants and Emerging Players: Establish a beachhead in the swappable-battery delivery fleet segment where per-kilometer service contracts bypass upfront capital barriers. Southern European capitals with congestion zone exemptions represent the most penetrable geography. A direct-to-fleet go-to-market angle bypasses heritage dealer network dependencies and captures recurring revenue streams from high-utilization operators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors power electronics specialists and battery system integrators over legacy frame manufacturers. Long-term viability hinges on software-defined vehicle architecture ownership rather than mechanical assembly competency. Acquisition targets should demonstrate embedded systems capability and fleet management platform traction. Watch battery chemistry cost curves as the inflection indicator for electric motorcycle price parity with 125cc ICE equivalents.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Korean cell producer partnerships secure capacity ahead of EU Green Deal phase-out deadlines. |
| Swappable Battery Standardization | Gogoro-style exchange networks unlock fleet operator route flexibility across Barcelona and Amsterdam. |
| Software-Defined Vehicle Investment | Over-the-air feature activation virtualizes historical tier separation and extends revenue per unit. |
| Direct-to-Fleet Distribution | Bypassing heritage dealers captures high-utilization delivery verticals with subscription economics. |
| Power Electronics Talent Acquisition | Embedded systems specialists remain scarce as high-voltage architectures proliferate across portfolios. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across OEM platform engineers, Tier 1 supplier procurement leads, fleet operations managers at delivery services, and heritage dealership principals. Secondary validation drew from KBA type-approval filings, EU Green Deal national implementation documents, ECHA REACH substance registrations, and vehicle production databases. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Calibration against historical registration data and subsidy uptake rates anchored the projection framework across the analysis window. Segmentation dimensions modeled include vehicle type, engine capacity tier, end-user application, and propulsion architecture. CAGRs were derived from regression analysis of adoption curve inflection points and regulatory deadline proximity. Forecast inputs incorporated battery energy density improvement trajectories and charging infrastructure deployment schedules.
Stress conditions across lithium price volatility, subsidy program continuity, and cell supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology cost curves and regulatory enforcement timelines. Quarterly review of fleet electrification procurement announcements and national ICE phase-out policy adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
China Two Wheeler Market
Bikes and Motorcycles
Two-Wheeler Lighting Market
Bikes and Motorcycles
Motorcycle Drive Chain Market
Bikes and Motorcycles
Emission Control Catalyst for Motorcycle Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
Motorsport Components Market
Bikes and Motorcycles
Global Two Wheeler Accessories Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
Global Carbon Fiber Bike Market
Bikes and Motorcycles
Carbon Fiber Bicycle Market
Bikes and Motorcycles
Motorcycle Seat Market
Bikes and Motorcycles
Motorcycle Headlight Bracket Market
Bikes and Motorcycles
Sweden Electric Bike Market
Bikes and Motorcycles
Switzerland E-Bike Market