
 Motorcycle Drivetrain Market | 2026-2036
Motorcycle Drivetrain Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Drivetrain Market Analysis
Dealer and distributor networks across Southeast Asia and Latin America are being redrawn as OEMs consolidate channel partners and direct-to-workshop programs gain share. This channel restructuring is reshaping how aftermarket drivetrain components reach independent repair shops and custom builders. Honda Motor Co., Ltd. leverages its integrated manufacturing base in Thailand to sustain cost advantages across chain and sprocket production. Yamaha Motor Co., Ltd. anchors premium drivetrain supply through its race-derived product lines and controlled distribution to authorized service centers. Schaeffler Group competes in the high-end shaft drive segment with specialized bearing and gear solutions for touring motorcycles.
Motorcycle drivetrain encompasses the complete power transmission system from engine output shaft to rear wheel, comprising chains with O-ring or X-ring sealing, shaft drives with hypoid gearing, toothed belts with aramid reinforcement, and final drive gears typically case-hardened to 58-62 HRC for wear resistance. Its primary function is to transfer torque efficiently across varying load conditions while minimizing power loss, maintenance intervals, and acoustic emissions. Chain systems dominate volume across 125cc and 250cc commuter segments where cost sensitivity and repair accessibility shape purchasing decisions. Carbon fiber reinforced components are gaining traction in the 1000cc superbike category where unsprung mass reduction directly impacts handling performance. Steel remains the margin pool anchor due to its scale economics across OEM and aftermarket channels.
Euro 5 standards enforced by the European Commission, EPA emission regulations in the United States, and India's PLI scheme administered by the Department of Heavy Industry collectively dictate material selection, sealing technology requirements, and local content thresholds for drivetrain suppliers. These frameworks create divergent compliance costs that fragment product architectures across regulatory zones rather than converging on global platforms. Stakeholders must monitor how tightening particulate and noise standards in key production countries will force earlier-than-expected transitions in lubrication systems and chain sealing designs.
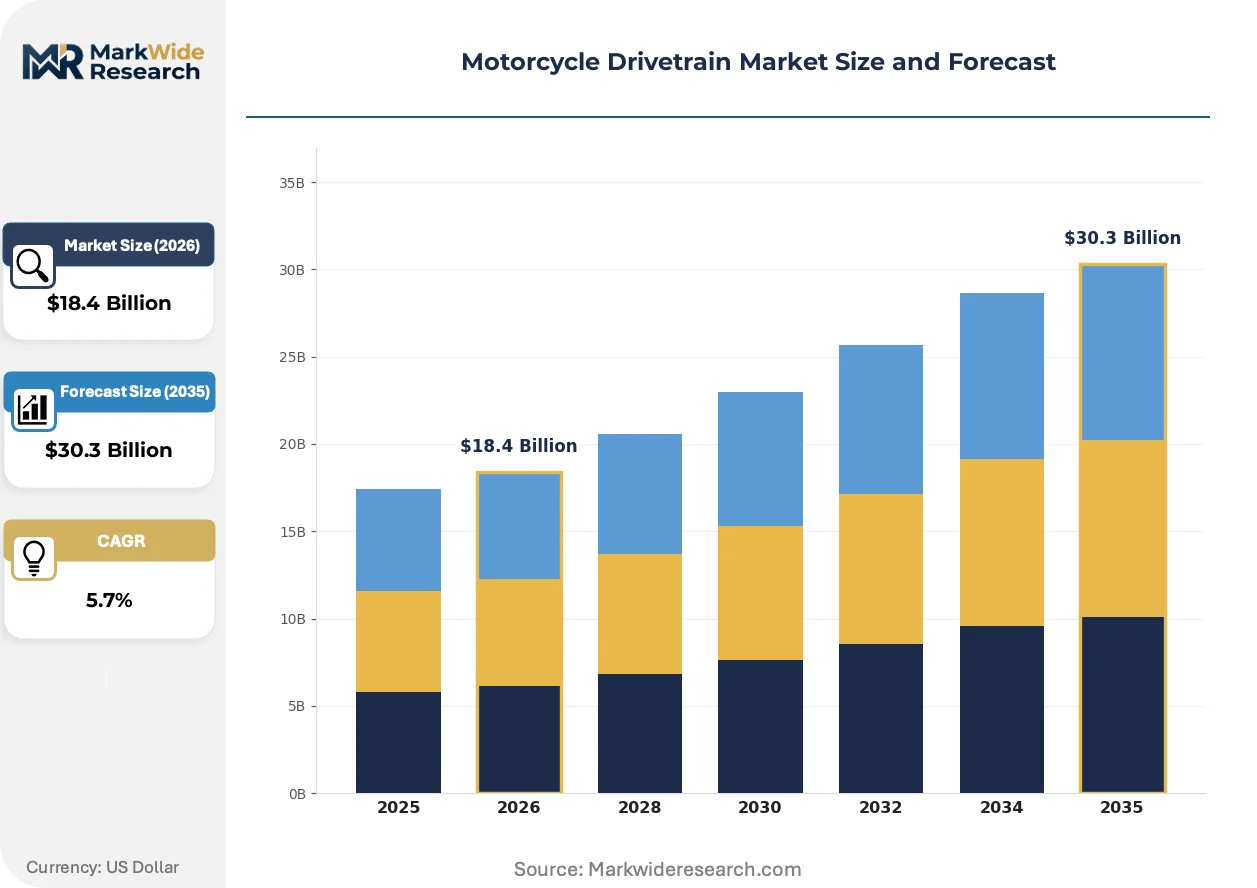
Market Dynamics
The Motorcycle Drivetrain Market is being restructured by Euro 5 emission standards and noise regulations that compel manufacturers to redesign chain sealing architectures and lubrication systems for acoustic compliance and efficiency gains.
Growth Catalysts
- PLI scheme localization mandates:India's Production Linked Incentive scheme administered by the Department of Heavy Industry requires domestic component sourcing, expanding local supply chains for chain and sprocket production.
- Carbon fiber reinforced materials:Aramid-reinforced toothed belts and carbon fiber sprockets are gaining traction in 1000cc superbike segments where unsprung mass reduction directly impacts handling performance.
- Shaft drive premiumization:Hypoid gearing systems with case-hardened final drive gears are penetrating touring motorcycle categories for reduced maintenance intervals and cleaner operation.
Market Restraints
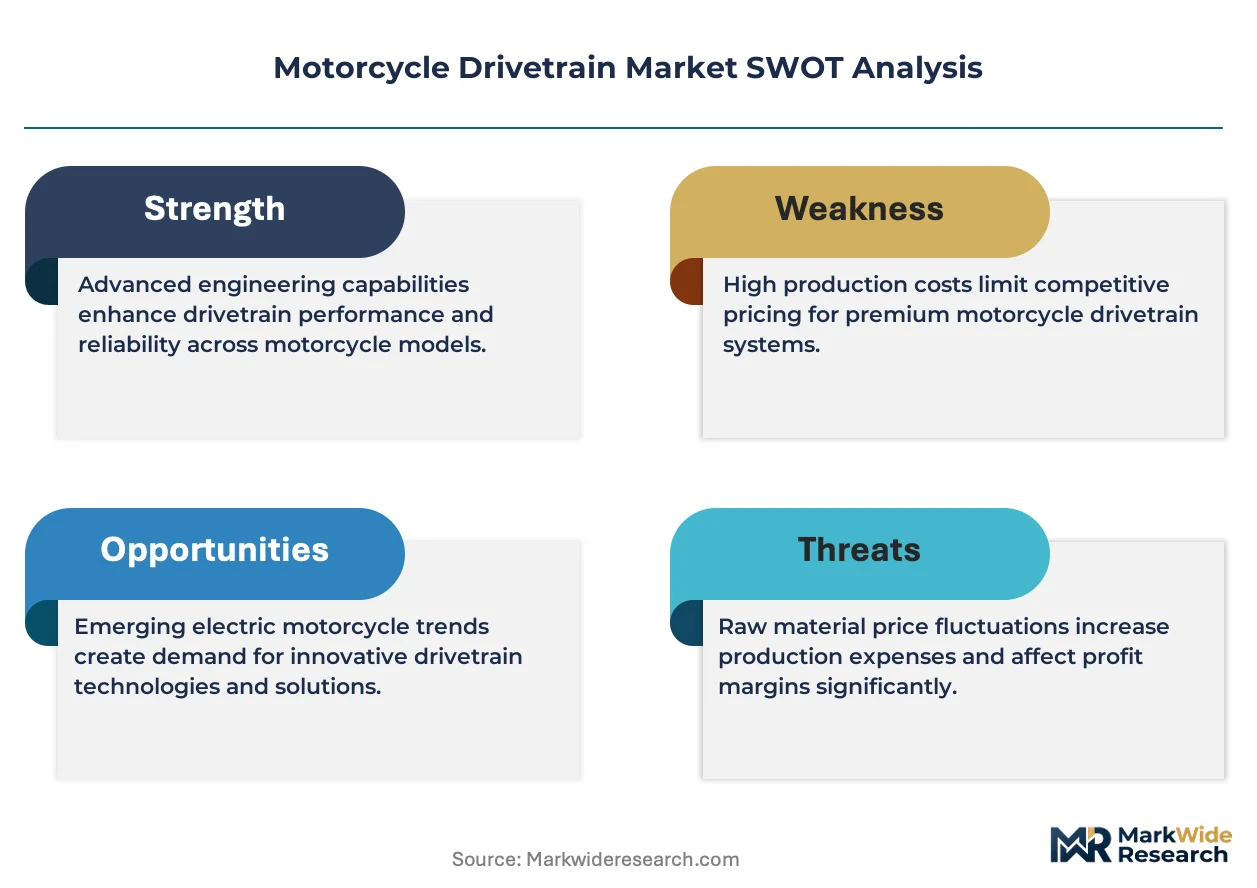
- Steel price volatility:Input cost fluctuations for alloy steel used in case-hardened sprockets compress margin pools across OEM and aftermarket channels.
- Thailand production concentration:Integrated manufacturing bases in Southeast Asia create geographic supply risk for chain systems serving global premium motorcycle categories.
- X-ring sealing technical limits:Current elastomer formulations face temperature thresholds that constrain adoption in high-displacement performance engines exceeding thermal design envelopes.
Strategic Opportunities
- Direct-to-workshop distribution:Channel disintermediation programs are bypassing traditional dealer networks to reach independent repair shops and custom builders in Latin America.
- EPA emission alignment:United States regulatory convergence with Euro 5 standards creates product platform commonality for suppliers serving transatlantic OEMs.
- Belt-versus-chain substitution:Aramid-reinforced synchronous belts are penetrating cruiser and urban mobility segments previously dominated by roller chain systems.
Industry Challenges
- Hypoid gear machining skill scarcity:Precision grinding and lapping capabilities for shaft drive systems require specialized workforce development that outpaces training pipeline output.
- Euro 5 certification timeline compression:Accelerated redesign cycles for acoustic testing and particulate compliance strain engineering bandwidth at mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Drivetrain Market |
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $30.3 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
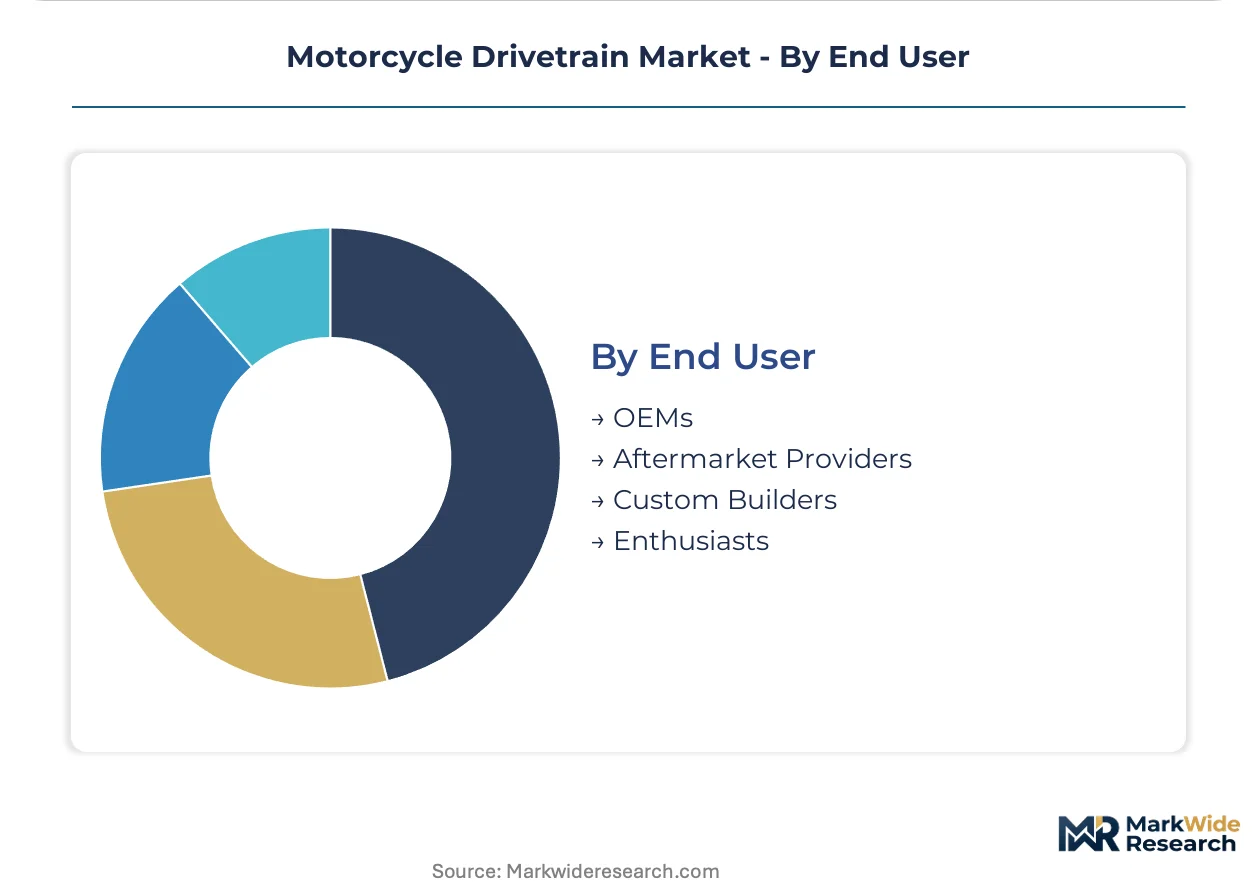
| Segmentation | Component Type: Chain, Shaft, Belt, Gear Material: Steel, Aluminum, Carbon Fiber, Plastic Engine Capacity: 125cc, 250cc, 500cc, 1000cc End User: OEMs, Aftermarket Providers, Custom Builders, Enthusiasts |
| Companies Covered | Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., KMC International Inc., Daido Kogyo Co., Ltd., Schaeffler Group, Tsubakimoto Chain, RK Japan, D.I.D Chain, Regina Catene Calibrate Spa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Drivetrain Market Emerging Trajectories
Active redesign of drivetrain architectures is compressing development cycles as acoustic emission targets and material performance requirements converge. Sealing technology, power transmission efficiency, and distribution access are simultaneously transforming.
Self-lubricating X-ring chains with advanced elastomer compounds are rendering obsolete conventional O-ring designs in premium commuter segments. OEMs in Italy and Germany are specifying these systems for 250cc-500cc urban motorcycles to extend service intervals beyond prior generation capabilities. The shift is compressing aftermarket replacement revenue for basic chain kits while elevating sealed-system attach rates.
REACH restrictions on perfluorinated compounds are forcing reformulation of chain lubrication chemistries across European supply chains. The European Chemicals Agency enforcement is accelerating water-based and bio-synthetic alternatives through industrial consequence. Italian and German OEMs are responding by qualifying new lubricant portfolios for factory-fill and service applications.
Authorized service center networks are capturing an expanding share of drivetrain component transactions previously flowing through independent distributors. Yamaha Motor's controlled distribution to race-derived product lines exemplifies this channel consolidation. Southeast Asia and Latin America are experiencing the most visible restructuring as OEMs consolidate channel partners and redraw territorial assignments.
Motorcycle Drivetrain Market Segmentation

Drivetrain component selection varies sharply by replacement frequency and unit economics. Chain systems turn over fastest with 8,000-15,000 kilometer service intervals, while shaft drives persist across entire vehicle lifecycles. Material grade and engine displacement further stratify purchasing patterns across OEM and aftermarket channels.
Component Type:
Replacement cycle timing separates high-frequency consumables from capital-intensive permanent installations.
- Chain:O-ring and X-ring sealed roller chains dominate 125cc-500cc commuter motorcycles where cost sensitivity and roadside repair accessibility shape specification. India's PLI scheme localization requirements are expanding domestic forging and heat-treatment capacity for 428 and 520 pitch chains serving Hero MotoCorp and Bajaj Auto production lines.
- Shaft:Hypoid gear final drive systems with case-hardened spiral bevel gearing penetrate touring motorcycles above 800cc where maintenance elimination justifies 3-4x cost premium over chain alternatives. BMW Motorrad and Honda Gold Wing platforms specify these architectures for 100,000+ kilometer service intervals.
- Belt:Aramid-reinforced synchronous toothed belts with carbon fiber tensile cords are displacing chains in cruiser segments where clean operation and zero lubrication appeal to urban riders.
- Gear:Direct mesh spur and helical gear sets serve niche electric motorcycle applications where single-speed reduction eliminates multi-stage transmission complexity.
Chain anchors the volume base while belt gains share at the steepest rate across premium cruiser conversions.
Material:
Cost tier positioning determines procurement patterns from commodity steel to aerospace-grade composites.
- Steel:Case-hardened alloy steels with 58-62 HRC surface hardness remain the margin pool anchor across OEM and aftermarket channels due to scale economics in forging, machining, and induction heat treatment.
- Aluminum:7075-T6 and 6061-T6 alloys machine sprocket carriers and belt pulleys where 40-60% mass reduction justifies material cost premium in 250cc-500cc performance segments.
- Carbon Fiber:Prepreg autoclave-cured sprockets and belt pulleys penetrate 1000cc superbike racing homologation specials where unsprung mass reduction of 200-400 grams per corner directly impacts lap times.
- Plastic:Glass-filled nylon and PEEK compounds form belt guide plates and chain rollers in electric motorcycles where torque loads permit polymer substitution.
Steel commands the installed base while carbon fiber expands most quickly at the performance frontier.
Engine Capacity:
Displacement brackets align with distinct regulatory, pricing, and usage contexts across national markets.
- 125cc:Entry commuter motorcycles governed by India's BS6 and Europe's Euro 5 emission limits specify low-cost unstamped chains with basic O-ring sealing and 428 pitch dimensions.
- 250cc:Premium commuter and light sport segments in Southeast Asia and Latin America drive demand for X-ring sealed chains with extended 20,000 kilometer service intervals.
- 500cc:Mid-displacement adventure and standard motorcycles specify heavy-duty 520 or 525 pitch chains with reinforced side plates for off-road load tolerance.
- 1000cc:Superbike and hyper naked categories specify racing-derived 525 or 530 pitch chains with gold-coated corrosion protection and rivet master links for track-day serviceability.
125cc motorcycles generate the highest unit volumes while 1000cc platforms drive the steepest technology premium capture.
End User:
Channel structure and technical sophistication separate factory installation from post-sale specification authority.
- OEMs:Original equipment manufacturers in Japan, India, and Italy specify drivetrain architectures during vehicle development with 3-5 year platform lock-in periods and volume commitments to tier-one suppliers.
- Aftermarket Providers:Distributor and dealer networks in Brazil, Mexico, and Indonesia stock replacement chain kits and sprocket sets for independent workshops serving 3-7 year old vehicle parc.
- Custom Builders:Small-batch fabricators in California, Germany, and Thailand specify belt-drive conversions and extended swingarm kits for cruiser and chopper modifications.
- Enthusiasts:Track-day riders and amateur racers purchase direct-to-consumer premium chains and quick-change sprocket carriers through specialized e-commerce channels.
OEMs anchor procurement volume while custom builders climb fastest as cruiser modification culture spreads through social media channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Department of Heavy Industry in India anchors regulatory momentum through PLI scheme localization mandates that reshape supply chain geography for motorcycle drivetrain components.
India
Domestic two-wheeler production volumes exceeding twenty million units annually drive demand for 428 and 520 pitch chains. The PLI scheme administered by the Department of Heavy Industry requires component sourcing thresholds that expand forging and heat-treatment capacity in Gujarat and Tamil Nadu. Hero MotoCorp and Bajaj Auto production lines in Manesar and Chakan now specify locally manufactured sealed chains.
Thailand
Integrated manufacturing bases serving premium motorcycle categories concentrate chain and sprocket production for Southeast Asian export markets. Board of Investment incentives support precision machining clusters in the Eastern Economic Corridor. Honda leverages its Rayong facility to sustain cost advantages across roller chain output destined for global OEM assembly lines.
Germany
Touring motorcycle manufacturers specify hypoid gear shaft drive systems for 100,000+ kilometer service intervals. The KBA enforces acoustic emission testing that compels redesign of final drive architectures for BMW Motorrad platforms. Stuttgart and Munich engineering centers develop case-hardened spiral bevel gearing for adventure and touring segments above 800cc displacement.
Italy
Superbike racing homologation specials demand carbon fiber reinforced sprockets and gold-coated corrosion protection chains. ECHA REACH restrictions on perfluorinated compounds force reformulation of factory-fill lubricants specified by Ducati and Aprilia. Bologna and Modena motorsport clusters drive specification authority for 525 and 530 pitch racing chains.
United States
Custom builders and track-day enthusiasts purchase direct-to-consumer premium chains through specialized e-commerce channels. EPA emission regulations converge with Euro 5 standards to create product platform commonality for transatlantic OEMs. California fabrication shops and Arizona distribution centers anchor aftermarket supply for cruiser modification culture spreading through social media.
Motorcycle Drivetrain Market Vendor Landscape
Vertically integrated Japanese conglomerates and specialized European component suppliers split the market across volume and premium tiers. The vendor base concentrates around three strategic archetypes: integrated motorcycle OEMs with captive drivetrain production, independent chain specialists with forging and heat-treatment mastery, and diversified industrial manufacturers leveraging bearing and gear expertise. Competitive moves center on channel disintermediation programs and localization partnerships under India's PLI scheme.
Among Japanese industrial conglomerates, Honda Motor Co., Ltd. and Yamaha Motor Co., Ltd. represent the integrated OEM archetype with controlled distribution to authorized service centers. Schaeffler Group occupies a position within the diversified industrial tier, applying specialized bearing and gear solutions to high-end shaft drive segments. These three entities exemplify how scale, vertical integration, and technology specialization stratify competitive positioning across commuter, touring, and superbike categories.
| Leading Market Players |
|---|
| Honda Motor Co., Ltd. |
| Yamaha Motor Co., Ltd. |
| KMC International Inc. |
| Daido Kogyo Co., Ltd. |
| Schaeffler Group |
| Tsubakimoto Chain |
| RK Japan |
| D.I.D Chain |
| Regina Catene Calibrate Spa |
| Others |
Supply Flow & Price Mechanics
Rayong Province's integrated manufacturing clusters in Thailand concentrate precision forging and heat-treatment capacity for O-ring and X-ring sealed chains, granting incumbent suppliers asymmetric leverage over pricing negotiations with European and Japanese OEMs seeking cost-competitive sourcing for 125cc-500cc commuter platforms.
Pricing Analysis
Price spreads between Indian domestic supply and Thai export channels reach 15-25% for equivalent 520 pitch chain specifications, reflecting divergent labor cost structures and PLI scheme subsidy offsets. Three-tier pricing structure across premium, standard, and economy levels separates racing-derived 530 pitch systems with gold-coated corrosion protection from basic unstamped chains for emerging market commuters. Pricing pressure stems from alloy steel input cost volatility compressing margin pools at mid-tier forging operations serving aftermarket distributors. OEM procurement teams exhibit lowest price sensitivity for shaft drive hypoid gear systems where 100,000 kilometer service intervals justify 3-4x premiums over chain alternatives.
Supply Chain Analysis
Contract manufacturing concentration rests with Thai Board of Investment-supported precision machining clusters and Indian PLI scheme beneficiaries in Gujarat and Tamil Nadu, which collectively anchor global capacity for roller chain and sprocket production. Raw material dependencies draw from Japanese specialty steel mills for case-hardened alloys, German elastomer suppliers for X-ring sealing compounds, and Chinese rare earth processors for induction heat-treatment equipment. Single-source vulnerability concentrates in Thai Eastern Economic Corridor facilities serving Honda and Yamaha captive production requirements. Distribution runs through authorized service center networks capturing share from independent distributors across Southeast Asia and Latin America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as Euro 5 emission standards and EPA regulatory convergence force product architecture commonality across transatlantic OEM supply chains, compressing development cycle differentiation and elevating ecosystem interoperability as the decisive capability.
For Market Incumbents: Entrench control over authorized service center networks to capture aftermarket replacement revenue streams threatened by direct-to-workshop disintermediation programs. Deepen backward integration into specialty steel forging and advanced elastomer compounding to insulate margin pools from raw material volatility and REACH-driven lubricant reformulation costs.
For New Entrants and Emerging Players: Establish a beachhead in carbon fiber reinforced sprocket production for 1000cc superbike racing homologation specials, where unsprung mass reduction commands technology premiums and incumbent capacity constraints create white-space. Target Indian PLI scheme localization partnerships with Hero MotoCorp and Bajaj Auto supply chains as the most penetrable entry vector, leveraging domestic content thresholds to displace Thai-sourced chain systems.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming motorcycle drivetrain divisions lacking scale alignment with platform standardization trends. Long-term viability hinges on positioning within electrification-adjacent gear reduction architectures for single-speed electric motorcycles. Monitor EPA-Euro 5 regulatory convergence velocity as the critical inflection signal for product platform consolidation investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| PLI Scheme Localization Partnership | Indian domestic content thresholds expand forging capacity in Gujarat and Tamil Nadu for Hero MotoCorp and Bajaj Auto supply chains. |
| X-Ring Sealing Technology Investment | Advanced elastomer compounds extend service intervals beyond 20,000 kilometers for 250cc-500cc urban motorcycle platforms. |
| Direct-to-Workshop Distribution Buildout | Bypassing traditional dealer networks captures aftermarket share from independent repair shops across Latin America and Southeast Asia. |
| Carbon Fiber Sprocket Production Scale-Up | Prepreg autoclave-cured components penetrate 1000cc superbike segments where unsprung mass reduction directly impacts lap times. |
| Hypoid Gear Machining Capability Expansion | Precision grinding and lapping investments address workforce scarcity constraining shaft drive penetration in touring motorcycles above 800cc. |
Methodological Framework
Desk research of customs trade databases, OEM production filings, and regulatory submission documents preceded structured interviews with tier-one supplier procurement directors, aftermarket distributor network managers, and PLI scheme administrative officials at India's Department of Heavy Industry. Primary fieldwork with chain and sprocket forging plant managers in Thailand's Eastern Economic Corridor and heat-treatment facility operators in Gujarat validated secondary data on capacity utilization and localization progress. Bottom-up volume estimates from national vehicle production databases were triangulated against top-down market size assessments derived from supplier revenue disclosures.
Assumptions held fixed across the modeling period include Euro 5 and EPA regulatory enforcement timelines, PLI scheme localization threshold percentages, and Thai Board of Investment incentive continuity. Variables stress-tested encompass alloy steel price volatility bands, X-ring elastomer temperature threshold improvements, and belt-versus-chain substitution rates in cruiser segments. Segmentation dimensions modeled span component type, material grade, engine displacement bracket, end-user channel, and regional production cluster. CAGRs were derived from regression analysis of historical volume trends against projected OEM platform lifecycles and aftermarket replacement cycle compression.
Stress conditions across steel input costs, regulatory certification timelines, and channel disintermediation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions regarding technology adoption curves and supply chain reconfiguration dynamics. Quarterly review of PLI scheme beneficiary announcements, EPA emission standard alignment progress, and Thai manufacturing cluster capacity expansion permits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
300cc Motorcycle Market
Bikes and Motorcycles
Global Carbon Fiber Bike Market
Bikes and Motorcycles
On-Road Motorcycles Market
Bikes and Motorcycles
Motorcycle Seat Market
Bikes and Motorcycles
Motorcycle Cooling Helmets Market
Bikes and Motorcycles
UAE Electric Bike Market
Bikes and Motorcycles
Global Motorcycle Handlebar Control Switch Market
Bikes and Motorcycles
Italy E-Bike Market
Bikes and Motorcycles
Latin America Two-Wheeler Market
Bikes and Motorcycles
Motorcycle Filter Market
Bikes and Motorcycles
E-Mountain Bike Market
Bikes and Motorcycles
Kids Bicycle Market
Bikes and Motorcycles
Latin America Fuel Cell Bikes Market
Bikes and Motorcycles
Automotive Chain Sprockets Market
Bikes and Motorcycles
Asia-Pacific Ride on Bikes Market
Bikes and Motorcycles
Cruiser Bikes Market