

Bicycle Mechanical Disc Brake Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Mechanical Disc Brake Market Insights
The EU Green Deal is decoupling urban mobility policy from car-centric infrastructure across member states, redirecting public investment toward cycling networks that require reliable braking hardware. Shimano leverages its manufacturing scale to supply OEM channels across European and Asian bicycle assemblers. SRAM competes through technology leadership in cable-actuated systems designed for mountain biking and gravel applications. Tektro Technology anchors the mid-market segment with cost-optimized caliper designs for commuter and urban cycling platforms.
Bicycle mechanical disc brakes employ cable-actuated calipers that compress brake pads against a metal rotor mounted to the wheel hub, generating friction through mechanical advantage rather than hydraulic fluid pressure; typical systems specify rotor diameters from 140 mm to 203 mm and pad compositions ranging from organic resin to sintered metallic compounds. The primary commercial purpose is to deliver consistent, all-weather stopping performance for bicycles where hydraulic systems prove cost-prohibitive or maintenance-intensive. Caliper and rotor segments dominate value capture due to replacement frequency and wear-driven aftermarket demand, while cable technology exhibits structural growth as manufacturers refine housing compression ratios and corrosion resistance. Mountain biking and commuter applications concentrate volume, with touring bikes representing a margin-rich niche where durability specifications command premium positioning.
Regulatory frameworks including REACH in Europe, GB standards administered by SAMR in China, and CPSC guidelines in the United States govern material composition, corrosion resistance, and minimum performance thresholds for bicycle brake components. These standards shape market access by mandating specific pad formulations and rotor metallurgy that manufacturers must certify before distribution. Stakeholders must monitor evolving friction-material regulations and supply-chain documentation requirements that determine competitive eligibility across major bicycle-producing regions.
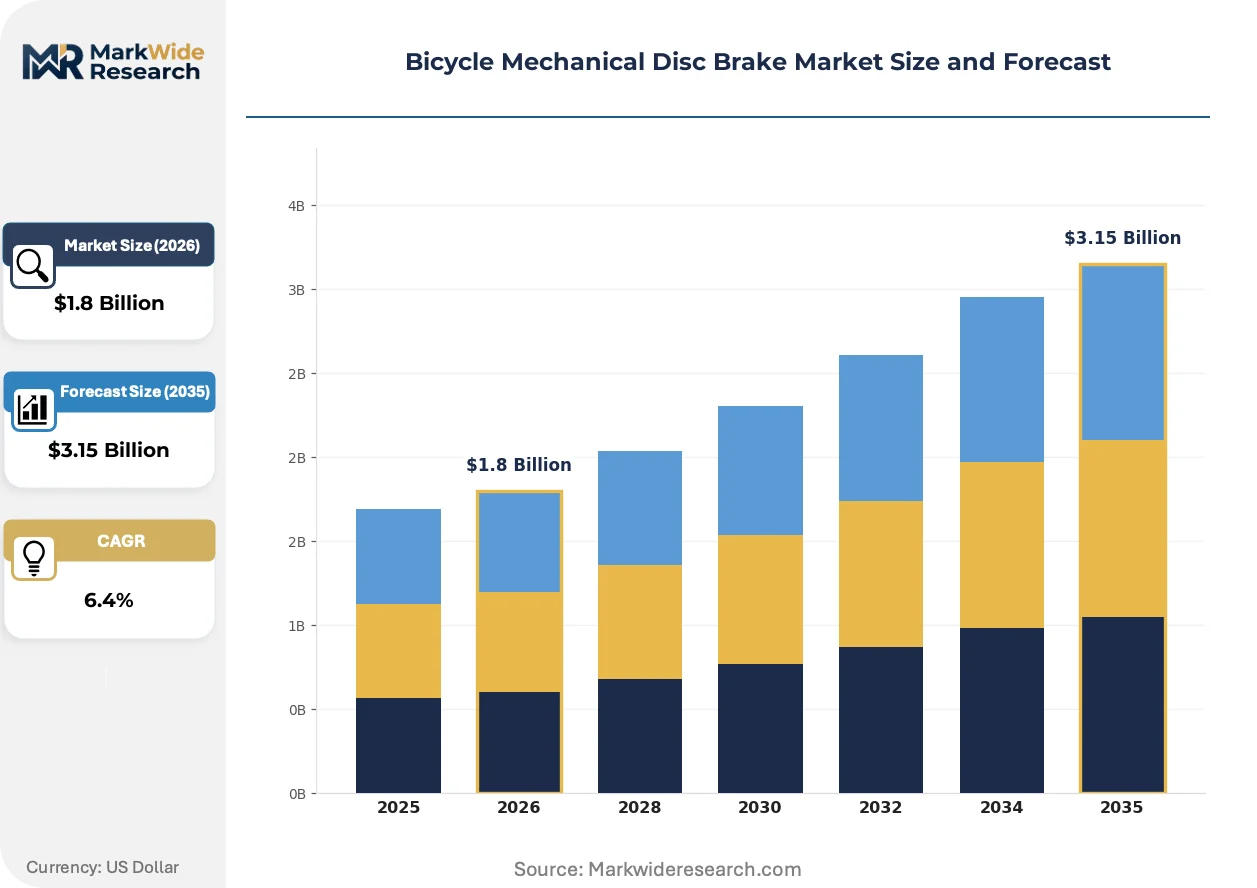
Market Dynamics
Aftermarket lifecycle extension is restructuring revenue flows as riders replace worn pads and rotors rather than complete brake systems, compressing OEM attachment rates while expanding recurring service revenue for independent bicycle shops.
Growth Catalysts
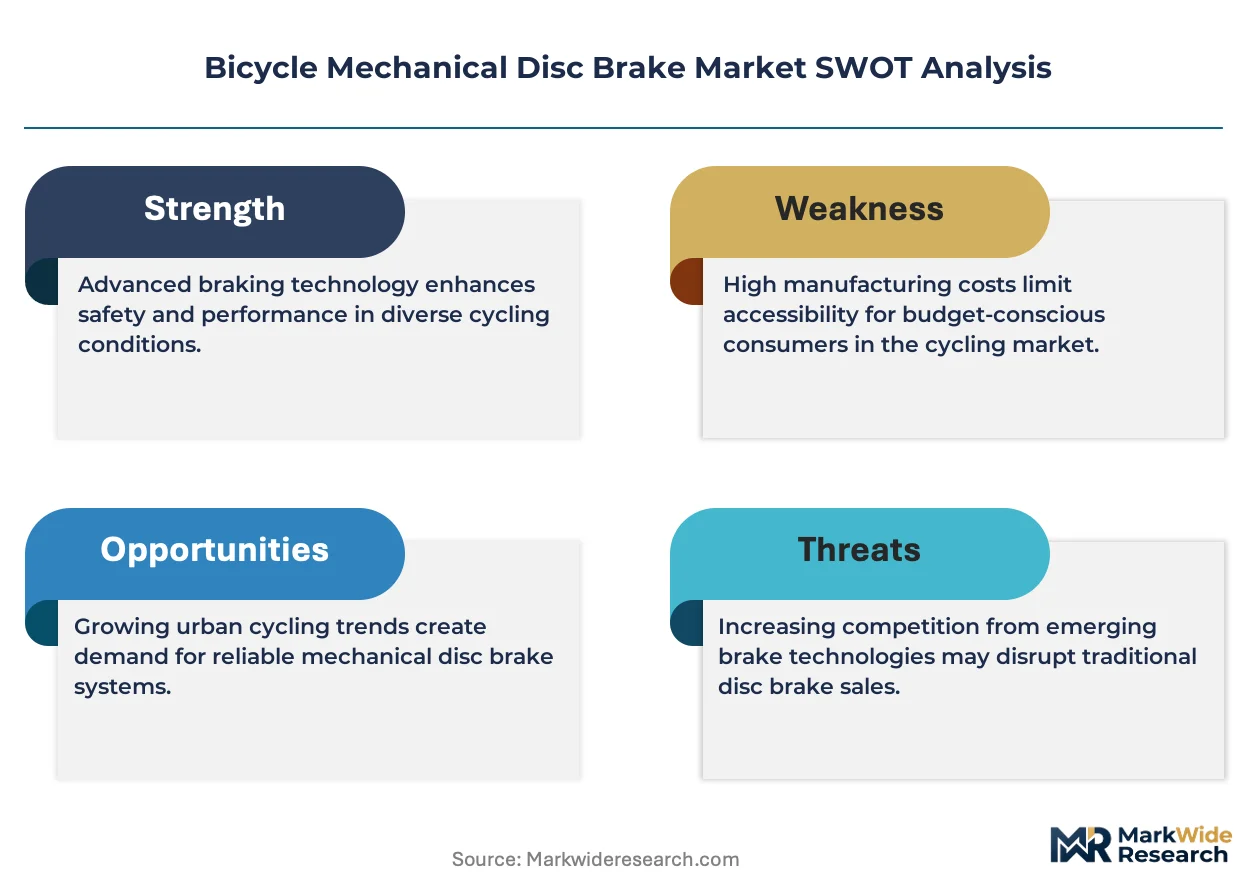
- REACH material mandates:ECHA enforcement of restricted substance lists for brake pad binders is accelerating reformulation toward copper-free and low-VOC friction materials across European supply chains.
- Gravel cycling expansion:Unpaved road racing formats are displacing rim brakes on drop-bar bicycles, creating specification pull for cable-actuated disc systems that balance modulation with field-serviceability.
- China GB standard evolution:SAMR-administered updates to bicycle component safety protocols are mandating corrosion-resistant rotor metallurgy, forcing upgrade cycles among domestic manufacturers seeking export certification.
Market Restraints
- Aluminum alloy cost volatility:Caliper housing production depends on 6061-T6 extrusion pricing, which fluctuates with energy-intensive smelting economics in Yunnan and Guangxi provinces.
- Hydraulic substitution ceiling:Entry-level hydraulic disc systems from Tektro and Shimano are compressing mechanical system pricing power in the sub-$400 bicycle retail segment.
- Rotor supply concentration:Stainless steel blank manufacturing clusters in Taichung and Shenzhen create geographic vulnerability to trade-route disruptions or regional energy rationing.
Strategic Opportunities
- E-bike integration protocols:Mechanical disc systems with motor-cutoff switches are capturing specification on European pedelec platforms where hydraulic maintenance complexity deters fleet operators.
- India cycling infrastructure:Smart Cities Mission funding for non-motorized transport in Pune, Bangalore, and Delhi is generating tender demand for durable commuter braking hardware.
- Modular pad architecture:Tool-free quick-change pad designs are opening aftermarket attachment through direct-to-consumer channels, bypassing traditional distributor markups.
Industry Challenges
- Friction material certification timelines:ECE R90 bicycle brake homologation and independent lab testing cycles extend 14-18 months, delaying product launches behind competitive hydraulic alternatives.
- Cable housing quality variance:Inconsistent compression ratios across OEM and aftermarket housing suppliers degrade lever feel consistency, complicating brand positioning around modulation precision.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Mechanical Disc Brake Market Trends and Innovations
Cable-actuated braking architecture is experiencing convergent pressure from smart material integration, regulatory material bans, and channel restructuring that favors serviceable over sealed systems.
Self-adjusting caliper mechanisms using ratcheting pad wear compensators are automating maintenance intervals for fleet and shared bicycle operators. Transit authorities in Copenhagen and Amsterdam specify these systems on station-based bike-share fleets to reduce field-service labor. The technology is automating specification decisions away from traditional fixed-pad designs in high-utilization commercial applications.
EU Green Deal implementation through national cycling infrastructure budgets is mandating extended producer responsibility for brake component recyclability. France and the Netherlands now require documented material recovery pathways for metallic brake pads. The policy is forcing reformulation of sintered compounds toward separable steel-backing designs that dismantlers can process through existing automotive friction recycling streams.
Direct-to-rider education content is displacing shop-mediated purchase decisions for replacement components. YouTube tutorial viewership for pad replacement procedures has concentrated brand preference around manufacturers with visual technical documentation. This behavioral shift is most pronounced in Germany and Austria, where cycling club membership correlates with high willingness to perform home maintenance.
Bicycle Mechanical Disc Brake Market Segmentation
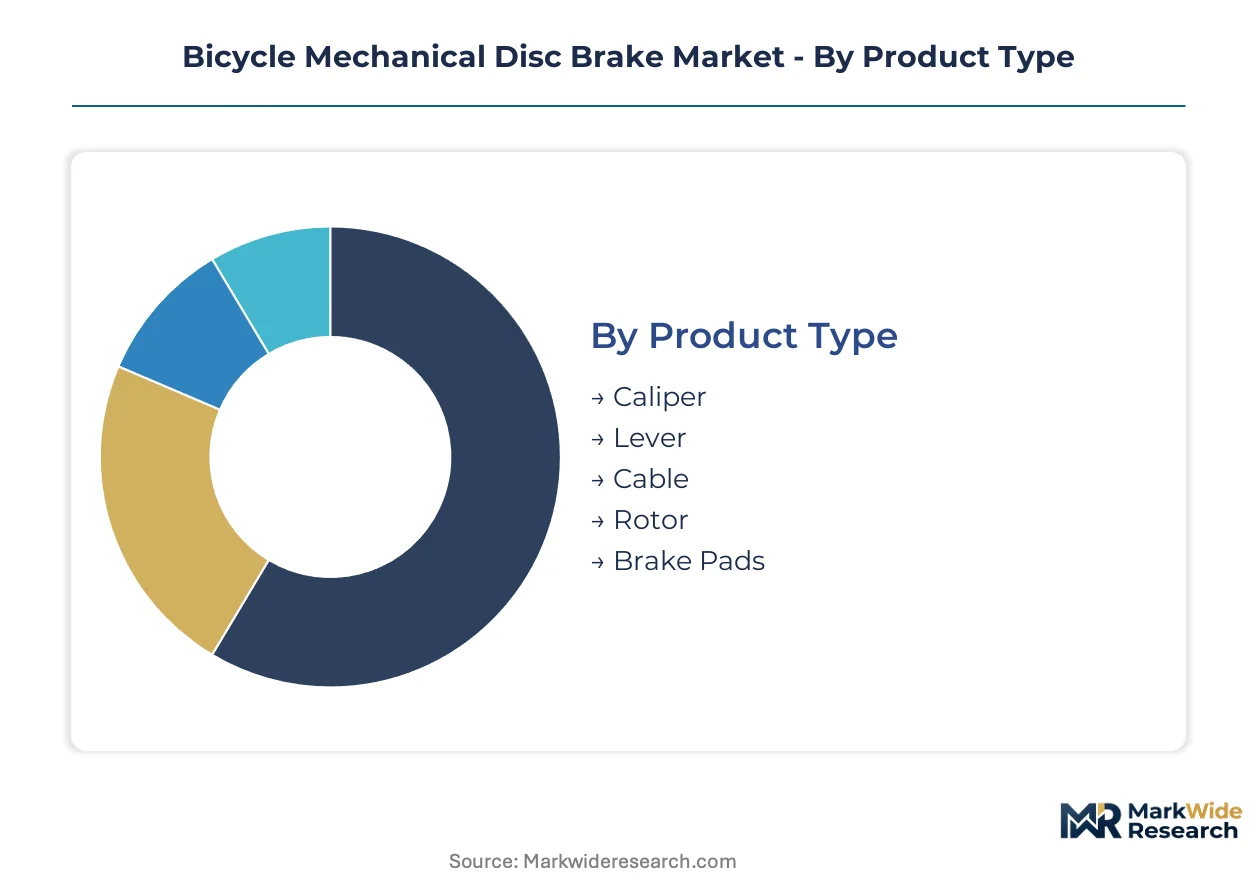
Mechanical disc brake segmentation reveals how certification burdens concentrate differently across hardware categories. Component-level material mandates from ECHA and SAMR create divergent compliance costs that reshape competitive positioning within each segment cluster.
Product Type:
REACH substance restrictions and GB corrosion standards impose asymmetric certification timelines across hardware categories, with friction-bearing components facing extended homologation cycles.
- Caliper:Cast or forged aluminum housings using 6061-T6 alloy specify piston bore diameters from 19 mm to 22 mm. OEM demand concentrates in Taichung and Shenzhen manufacturing clusters where vertical integration into forging operations controls cost position.
- Rotor:Stainless steel blanks in 140 mm to 203 mm diameters require martensitic grades meeting SAMR corrosion protocols. German commuter bicycle assemblers drive premium specifications for heat-treated 420-grade steel with laser-etched wear indicators.
- Lever:Die-cast aluminum or carbon-reinforced polymer bodies with indexed reach adjustment.
- Cable:Stainless steel inner wires with compression-resistant housing assemblies.
- Brake Pads:Organic resin or sintered metallic compounds with steel backing plates.
Caliper assemblies sit at the top of the volume ranking, with rotor specifications climbing the fastest as wear-driven replacement cycles accelerate.
Technology:
Actuation mechanisms differentiate primarily through maintenance complexity and field-serviceability, with fleet operators prioritizing self-adjusting architectures over precision-tuned alternatives.
- Cable Actuated:Bowden cable transmission with 1.5 mm to 1.6 mm diameter inner wires and compression-resistant housing delivers force multiplication through lever geometry. Copenhagen bike-share fleets specify corrosion-resistant stainless assemblies with sealed ferrules to minimize seasonal maintenance.
- Spring-Loaded:Return-spring mechanisms automate pad retraction to reduce drag. Dutch urban bicycle manufacturers specify these systems for station-based fleets where consistent lever feel outweighs absolute modulation precision.
- Linear Pull:Long-arm lever geometry optimized for rim brake retrofit compatibility.
- Dual-Pivot:Centering adjustment via opposing pivot bolts for even pad contact.
- Mechanical Advantage:Variable leverage ratios optimized for specific rotor diameters.
Cable-actuated systems dominate unit economics, while spring-loaded configurations gain share fastest in commercial fleet procurement.
Application:
Discipline-specific duty cycles determine durability specifications, with gravity-oriented formats demanding heat-dissipation capacity that commuter platforms rarely require.
- Mountain Biking:Downhill and enduro formats specify 180 mm to 203 mm rotors with metallic pad compounds for sustained thermal load. Austrian and Swiss alpine bike parks drive replacement volume through accelerated wear rates on lift-served descents.
- Commuter Bicycles:Urban utility platforms prioritize 160 mm rotors with organic pads for silent operation and reduced rim contamination. German cycling infrastructure investment sustains premium mechanical specification where hydraulic maintenance deters non-technical riders.
- Touring Bikes:Long-distance load-carrying applications favor field-serviceable cable systems over sealed hydraulics.
- BMX:Compact 140 mm rotors with reinforced caliper mounts for freestyle impact resistance.
- Urban Cycling:Mixed-traffic platforms balancing all-weather reliability with theft-deterrent simplicity.
Commuter applications anchor production volume, with mountain biking segments commanding the steepest expansion trajectory as gravel-adjacent formats proliferate.
End User:
Channel structure determines margin capture, with direct-to-rider content reshaping traditional shop-mediated purchase patterns for replacement components.
- Bicycle Shops:Independent retailers combine installation labor with parts margin on brake system overhauls. German Fahrradhandwerk workshops leverage technical certification to justify premium mechanical disc brake specification over entry-level hydraulic alternatives.
- Repair Services:Mobile and depot-based maintenance operations prioritize rapid pad replacement protocols. Amsterdam fleet maintenance contractors specify tool-free pad architectures to minimize per-bike service time.
- Cycling Clubs:Member-organized bulk purchasing for group maintenance events.
- Sports Retailers:Mass-market distribution with limited technical service integration.
Bicycle shops retain the highest transaction value per brake system, while repair services expand most quickly as fleet outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized bicycle component engineers concentrate in Stuttgart, Taichung, and Shenzhen, anchoring design-to-manufacturing corridors that supply regional assemblers with calibrated braking hardware.
Germany
Cycling infrastructure budgets from the National Cycling Plan drive specification of corrosion-resistant mechanical systems for year-round commuters. REACH enforcement through ECHA mandates copper-free pad formulations, forcing reformulation cycles among friction material suppliers. The Baden-Württemberg manufacturing cluster around Stuttgart hosts precision forging operations that supply caliper housings to European OEMs.
China
Domestic e-bike production exceeding forty million units annually generates specification pull for cable-actuated systems with motor cutoff integration. SAMR-administered GB standard updates mandate martensitic stainless grades for export-bound rotors, accelerating metallurgical upgrades in Shenzhen and Taichung supplier networks. The Pearl River Delta concentration of aluminum extrusion and forging capacity controls cost position for caliper housing production.
United States
Gravel cycling participation growth displaces rim brakes on drop-bar platforms, creating aftermarket demand for field-serviceable mechanical alternatives. CPSC guidelines govern minimum performance thresholds for brake components distributed through domestic retail channels. The Pacific Northwest corridor from Portland to Seattle anchors independent bicycle shop density that sustains premium mechanical disc brake service revenue.
Netherlands
Station-based bike-share fleet procurement prioritizes self-adjusting caliper mechanisms to minimize field-service labor across municipal contracts. Extended producer responsibility frameworks under EU Green Deal implementation require documented material recovery pathways for metallic brake pads. The Randstad urban agglomeration concentrates fleet operator headquarters that specify durable commuter braking hardware for high-utilization deployments.
India
Smart Cities Mission funding for non-motorized transport generates tender demand for durable commuter braking hardware in Pune, Bangalore, and Delhi. The national standards body administers bicycle component safety protocols that shape import certification requirements for brake assemblies. The Maharashtra industrial corridor around Pune hosts emerging bicycle assembly operations that source mechanical disc systems for domestic utility platforms.
Bicycle Mechanical Disc Brake Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the mechanical disc brake value chain, with integrated forging and extrusion operations controlling cost position against specialized assemblers sourcing housings from third-party foundries. Market structure tilts toward consolidated supply at the OEM tier, where scale-driven manufacturers anchor specification decisions for major bicycle brands, while fragmented competition characterizes the aftermarket pad and rotor replacement segment. Three archetypes dominate: vertically integrated component conglomerates with captive forging capacity; specialized brake system houses focusing on cable-actuated architectures; and regional fabricators serving domestic bicycle assemblers with cost-optimized designs. Competitive dynamics center on backward integration into aluminum forging and strategic partnerships with fleet operators seeking reduced total cost of ownership.
Within the integrated conglomerate tier, Shimano and SRAM occupy positions that exemplify divergent strategic postures toward mechanical disc technology—one leveraging manufacturing scale across complementary component categories, the other concentrating engineering resources on cable-actuated modulation systems for technical riding disciplines. Tektro Technology represents the mid-market specialist archetype, with corporate structure indicating concentrated focus on cost-optimized caliper designs rather than diversification across unrelated hardware categories.
| Leading Market Players |
|---|
| Shimano |
| SRAM |
| Tektro Technology |
| Campagnolo |
| Magura |
| Hayes Performance Systems |
| Jagwire |
| Cane Creek Cycling Components |
| Formula |
| Others |
Pricing and Supply Chain Analysis
Captive forging operations in Taichung and Shenzhen anchor cost position for caliper housing production while compressing margin capture for assemblers sourcing from third-party foundries. Aluminum extrusion economics in Guangxi and Yunnan provinces transmit directly into OEM pricing power, with energy-intensive smelting costs filtering through 6061-T6 alloy quotations that determine competitive floor pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and rotor metallurgy quality. Price differentiation stems from SAMR corrosion-resistance certification for export-bound rotors and REACH-compliant copper-free pad formulations for European distribution. Cost compression in the economy tier is intensifying because entry-level hydraulic alternatives from major suppliers are eroding mechanical system attachment rates on sub-premium bicycles. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership procurement models, while German commuter assemblers demonstrate lowest sensitivity where durability specifications override unit cost considerations.
Supply Chain Analysis
Stainless steel rotor blank manufacturing rests on Taichung, Shenzhen, and Dongguan production clusters where martensitic grade heat-treatment capacity concentrates. Raw material dependencies include 420-grade stainless steel from Korean and Japanese mills, 6061-T6 aluminum extrusions from domestic Chinese smelters, and organic resin binders from European specialty chemical suppliers. Single-source vulnerability characterizes the rotor segment where laser-etching equipment manufacturers number fewer than five globally. Distribution runs through Taichung-based component distributors serving European and North American OEM assemblers with consolidated freight arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bicycle mechanical disc brake market functions as a stable compounder where aftermarket pad and rotor replacement cycles generate recurring revenue streams independent of new bicycle sales volatility.
For Market Incumbents: Anchor specification decisions through backward integration into aluminum forging operations that control 6061-T6 housing cost position against specialized assemblers. Invest in ECE R90 homologation capacity to compress 14-18 month certification timelines that currently delay product launches behind hydraulic alternatives. Defend against hydraulic substitution by emphasizing field-serviceability advantages in fleet procurement channels where maintenance complexity deters sealed system adoption. For New Entrants and Emerging Players: Municipal fleet operators in Indian Smart Cities represent an underserved buyer archetype with tender-based procurement protocols that favor durable mechanical specifications over premium hydraulic alternatives. Target modular pad architecture with tool-free quick-change designs that bypass traditional distributor markups through direct-to-rider channels. Establish technical documentation capabilities that match German and Austrian cycling club expectations for visual maintenance content. For Investors and Strategic Acquirers: Roll-up economics work for regional brake system fabricators because fragmented aftermarket pad and rotor production lacks scale advantages that consolidated procurement and shared certification infrastructure could capture. Five-to-ten year viability hinges on e-bike motor-cutoff integration protocols that mechanical systems are capturing from hydraulic alternatives in European pedelec fleet deployments. Monitor ECHA substance restriction enforcement timelines as the critical signal for friction material reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging | Captive 6061-T6 housing production insulates margin position from Guangxi energy rationing volatility. |
| REACH-Compliant Pad Reformulation | Copper-free friction material certification unlocks European aftermarket access under ECHA enforcement. |
| Fleet Operator Partnership | Copenhagen and Amsterdam bike-share specifications establish reference architectures for global municipal procurement. |
| Direct-to-Rider Channel Development | YouTube technical documentation builds brand preference among German and Austrian home maintenance practitioners. |
| E-Bike Motor-Cutoff Integration | Pedelec platform specification captures replacement cycles in European markets exceeding forty million annual units. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to calibrate supply-side capacity assessments against demand-pull signals from bicycle assemblers and fleet operators. Primary engagement included component procurement managers at European and Asian OEMs, technical directors at friction material suppliers, fleet maintenance contractors in Dutch and Danish municipal systems, and independent bicycle shop owners in German urban centers. Secondary validation drew from SAMR GB standard filings, ECHA substance restriction updates, customs trade data for bicycle component imports, and SEC disclosures from publicly traded bicycle component manufacturers. Bottom-up segment sizing triangulated against top-down bicycle production forecasts to constrain variance bounds.
Comparable-period anchoring tied projection assumptions to historical replacement cycle data and infrastructure investment trajectories across the analysis window. Segmentation modeling incorporated product type, actuation technology, application discipline, and end-user channel dimensions alongside regional regulatory cluster differentiation. CAGRs derived from fitted growth curves applied to segment-level baseline values, with cross-validation against bicycle production forecasts and aftermarket attachment rate assumptions. Industry-specific inputs included e-bike motor integration protocol adoption curves and gravel cycling participation growth indices.
Underlying measurement precision varies by segment; commuter and mountain biking applications carry tighter precision than touring and BMX niches where sample depth thins. Forecasts embed assumptions around REACH enforcement intensity and aluminum smelting economics that could revise trajectory if regulatory timelines or energy policy shifts accelerate. A small set of triggers—ECHA substance ban expansion, hydraulic system cost curves, and Indian municipal tender awards—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.