
 Flying Bikes Market | 2026-2036
Flying Bikes Market Size, Share, and Industry Trends Forecast 2026-2036
Flying Bikes Market Foresight
Aftermarket service revenue is rewriting how flying bike OEMs capture lifetime value from hardware deployments. Coolfly leverages its tilt-wing engineering heritage to anchor premium positioning in the vertical-lift segment. RICTOR competes through aggressive R&D intensity on hybrid propulsion architectures. Giant controls manufacturing scale advantages that sustain cost competitiveness across multi-seat platform variants.
Flying bikes are electrically or hybrid-powered aerial vehicles combining bicycle-scale chassis design with vertical takeoff capability, typically employing multiple ducted fans or tilt-wing rotors generating lift-to-weight ratios exceeding conventional rotorcraft. These platforms serve urban mobility, emergency response, and cargo transport applications where ground infrastructure constraints limit conventional vehicle deployment. Electric Vertical Takeoff configurations currently dominate unit shipments due to simpler battery-electric architectures, while Hybrid Propulsion systems command superior margins where extended range requirements govern procurement decisions. Urban Mobility applications attract the majority of development capital, though Military Operations segments offer higher unit economics where defense contractors prioritize jet propulsion performance parameters.
The FAA's powered-lift aircraft certification standards shape product development timelines for manufacturers targeting US airspace entry. EASA's concurrent framework development under the EU Green Deal accelerates environmental compliance integration into European type-certification pathways. Japan's METI urban air mobility corridor designations create regulated operational envelopes that de-risk early commercial deployment. Stakeholders must monitor how divergent national certification timelines fragment addressable market access before harmonization mechanisms mature.
Market Dynamics
The FAA's powered-lift aircraft certification framework is compressing type-approval timelines while fragmenting market access across jurisdictions with divergent standards. This regulatory acceleration is pulling capital toward early-mover platforms that can secure multi-jurisdiction operational clearances before harmonization mechanisms mature.
Growth Catalysts
- Urban Air Mobility Corridors:Japan's METI corridor designations in Osaka and Tokyo are creating regulated operational envelopes that de-risk commercial deployment for vertical-lift platforms.
- Emergency Response Procurement:Fire departments and medical transport agencies in Japan are expanding fleet procurement of electric vertical takeoff configurations for rapid urban deployment.
- Hybrid Propulsion Maturation:Advances in turbine-electric architectures are extending operational range beyond battery-electric limitations, opening inter-city cargo routes previously inaccessible to flying bikes.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell manufacturing concentrates in East Asian supply chains, exposing OEMs to input cost volatility and geopolitical sourcing risk.
- Certification Timeline Asymmetry:EASA's environmental compliance integration under the EU Green Deal is diverging from FAA powered-lift timelines, forcing dual-track development costs.
- Helicopter Substitution Economics:Mature rotorcraft fleets in emergency response sectors present incumbent equipment with established maintenance infrastructure and trained pilot pools.
Strategic Opportunities
- UAE Cargo Corridor Expansion:Dubai's operational pilot programs for urban air mobility are establishing regulatory precedents that adjacent Gulf Cooperation Council markets can adopt.
- Aftermarket Service Unbundling:Predictive maintenance platforms and battery lifecycle management services create recurring revenue streams independent of hardware shipment cycles.
- Military Operations Segment:Defense procurement parameters prioritizing jet propulsion performance are opening higher-margin contract structures for hybrid-electric platforms with extended range specifications.
Industry Challenges
- Power Electronics Talent Scarcity:The specialized workforce for high-voltage motor controller design and thermal management system integration remains concentrated in aerospace and automotive incumbents.
- Type-Certification Capital Intensity:FAA powered-lift validation requires extensive flight envelope testing and failure-mode analysis, demanding sustained R&D expenditure before revenue recognition.
- Airspace Integration Complexity:Unmanned traffic management system interoperability with legacy radar infrastructure creates operational friction for beyond-visual-line-of-sight missions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flying Bikes Market |
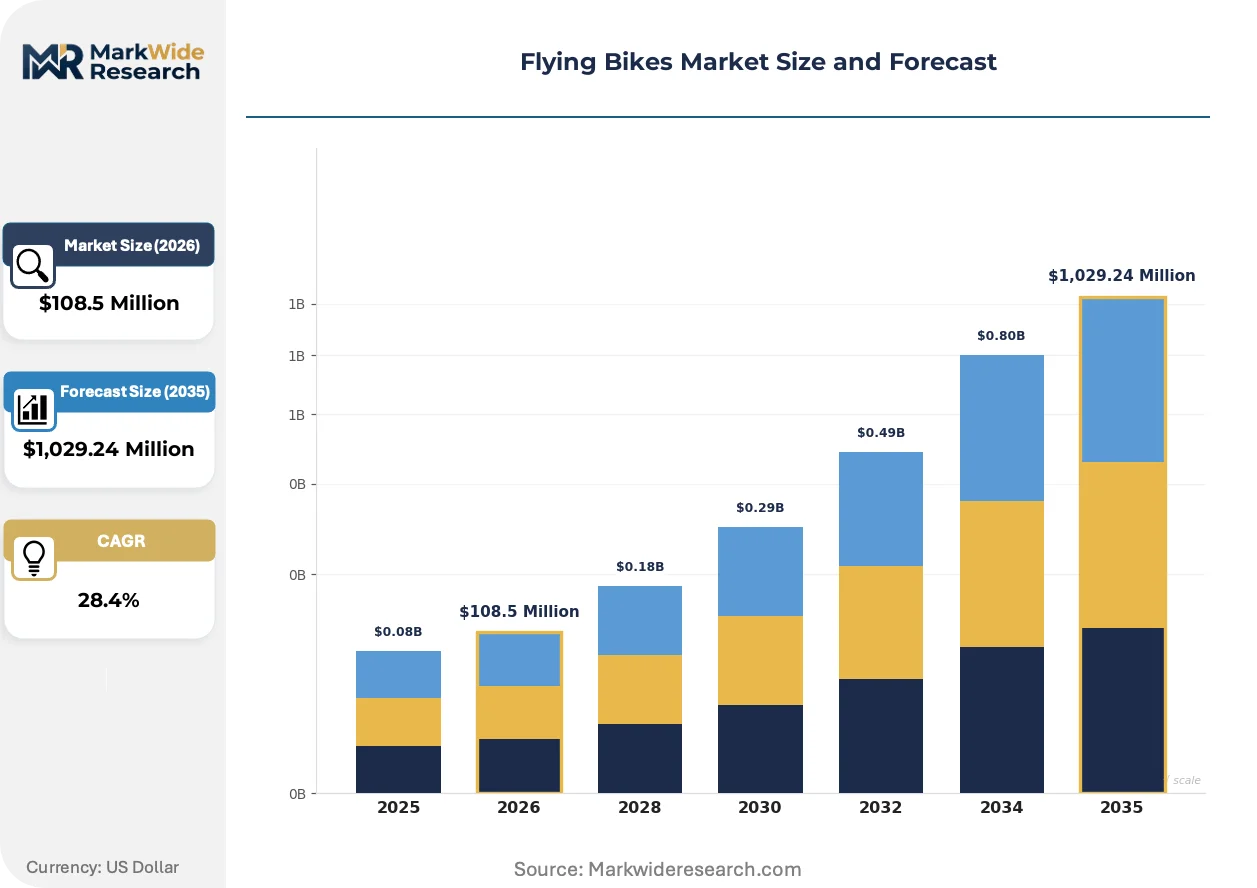
| Market Size in 2026 | $108.5 Million |
| Market Size in 2035 | $1,029.24 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Vertical Takeoff, Hybrid Propulsion, Single-Seat Models, Multi-Seat Models Technology: Vertical Lift, Tilt-Wing, Ducted Fan, Jet Propulsion, Hybrid Engines Application: Urban Mobility, Emergency Response, Military Operations, Aerial Surveying, Cargo Transport End User: Individual Consumers, Government Agencies, Defense Contractors, Logistics Providers |
| Companies Covered | Coolfly, Cervelo, RICTOR, Ridley, Giant, LEO, Verge Motorcycles, Canyon, Kuickwheel Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flying Bikes Market Shifts & Advancements
Propulsion architecture convergence and regulatory framework maturation are reshaping competitive positioning around range-performance tradeoffs. Platform developers are prioritizing modular designs that can adapt to divergent certification requirements without airframe redesign.
Tilt-wing rotor systems are hybridizing with fixed-wing cruise configurations to capture vertical-lift efficiency during takeoff while reducing energy consumption during transit flight. Emergency response agencies are piloting these platforms for medical evacuation missions where landing zone constraints prohibit conventional rotorcraft deployment. This architecture is hybridizing the market segmentation between pure multirotor designs and complex tilt-rotor systems, compressing the addressable space for intermediate configurations.
EASA's concurrent framework development under the EU Green Deal is embedding environmental compliance metrics directly into European type-certification pathways. Manufacturers targeting EU airspace must now integrate life-cycle carbon accounting and noise footprint thresholds into initial design phases. Battery-electric platforms with ducted fan configurations are most affected, as they face stricter acoustic standards than open-rotor alternatives in urban deployment scenarios.
Aftermarket service contracts are displacing traditional hardware-plus-maintenance procurement models in fleet operator segments. Dubai-based cargo transport pilot programs are unbundling battery lifecycle management and predictive maintenance from platform acquisition, shifting supplier relationships toward performance-guarantee structures. This behavior is most visible in Middle Eastern urban air mobility corridors where operational uptime metrics govern contract renewal decisions.
Flying Bikes Market Segmentation
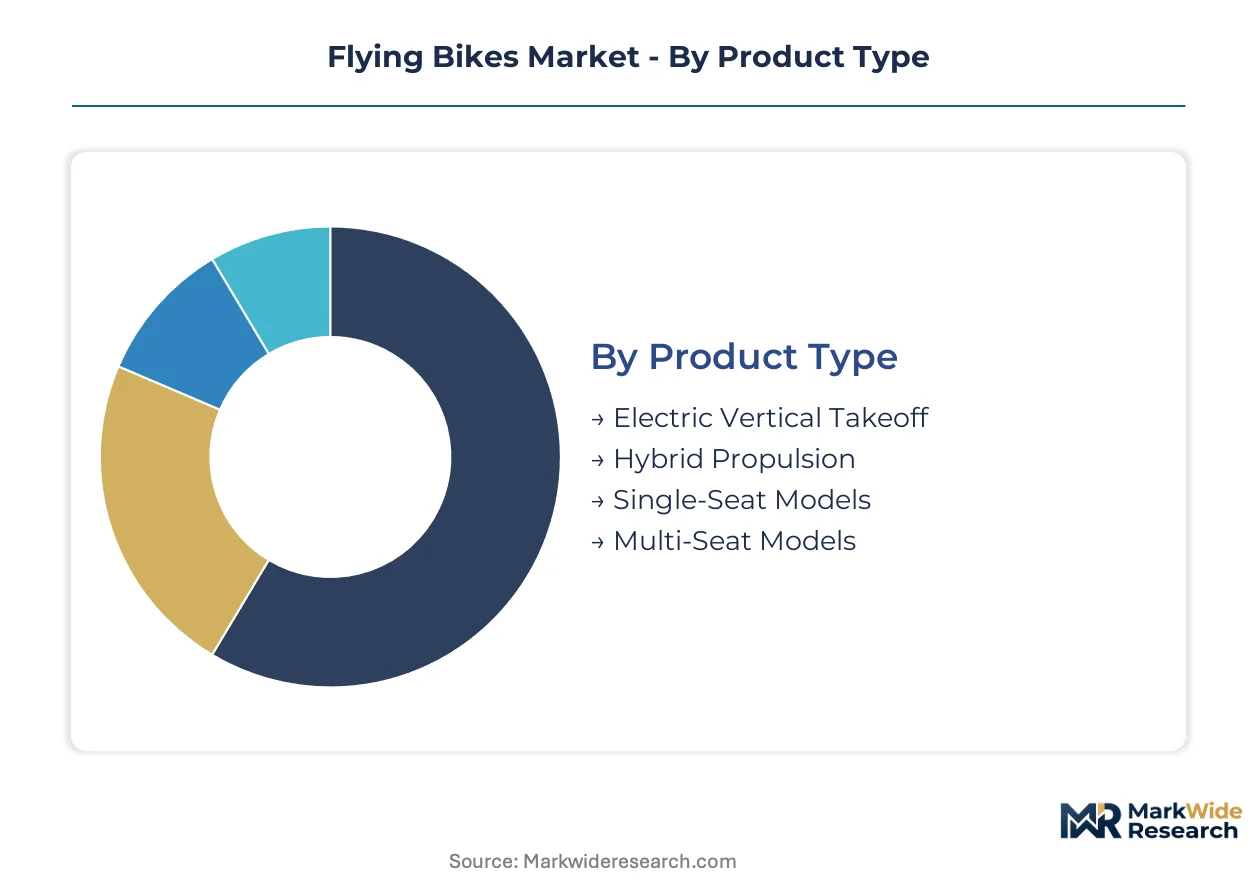
Segmentation in flying bikes reveals how propulsion architecture, operational mission, and procurement authority fragment addressable revenue pools. Each dimension carries distinct certification pathways, margin structures, and competitive entry barriers that shape platform development priorities.
Product Type:
Cost tier differentiation separates battery-electric entry points from hybrid-electric premium positioning across payload and range specifications.
- Electric Vertical Takeoff:Battery-electric architectures with distributed rotor arrays dominate unit shipments through simpler powertrain integration and reduced mechanical complexity. Demand concentrates in Dubai's urban air mobility corridors where METI-designated operational envelopes favor zero-emission platforms for intra-city cargo routes.
- Hybrid Propulsion:Turbine-electric systems extend operational range beyond battery limitations while retaining vertical-lift capability. Procurement from Japan's emergency response agencies prioritizes these configurations for medical evacuation missions requiring extended loiter times.
- Single-Seat Models:Compact chassis designs target individual consumer segments with reduced certification burden and lower price points.
- Multi-Seat Models:Expanded payload capacity serves government fleet procurement and logistics provider contracts with higher unit economics.
Electric Vertical Takeoff commands the established base. The steepest expansion runs through Hybrid Propulsion.
Technology:
Engineering heritage and manufacturing complexity determine which lift mechanisms capture development capital versus niche positioning.
- Vertical Lift:Multirotor configurations with fixed rotor orientation provide mechanical simplicity and redundant failure modes. Japan's fire departments specify these platforms for rapid urban deployment where landing zone constraints prohibit conventional rotorcraft.
- Tilt-Wing:Rotor pivot mechanisms transition from vertical lift to forward cruise flight, reducing energy consumption during transit. Coolfly's engineering investments anchor premium positioning in this segment for inter-city cargo corridors.
- Ducted Fan:Enclosed rotor systems reduce acoustic footprint and improve safety in dense urban environments. EASA's noise footprint thresholds under EU Green Deal compliance favor these configurations for European airspace entry.
- Jet Propulsion:Turbofan architectures deliver speed-performance parameters prioritized by defense contractors in military operations segments.
- Hybrid Engines:Combined thermal-electric powertrains balance range extension with partial electrification for transitional certification pathways.
Tilt-Wing captures premium margin concentration. Vertical Lift maintains volume leadership through simpler manufacturing scale.
Application:
Mission profile dictates platform specifications ranging from passenger comfort to payload ruggedness and electromagnetic signature control.
- Urban Mobility:Passenger transport applications attract majority development capital through fleet operator contracts and infrastructure integration investments. Dubai's operational pilot programs establish regulatory precedents for adjacent Gulf Cooperation Council markets.
- Emergency Response:Medical evacuation and fire suppression missions require rapid deployment capabilities and landing zone flexibility. Japan's METI corridor designations in Osaka and Tokyo de-risk commercial deployment for these specialized platforms.
- Military Operations:Defense procurement prioritizes jet propulsion performance and extended range specifications with higher-margin contract structures.
- Aerial Surveying:Sensor payload integration for infrastructure inspection and environmental monitoring serves government agency procurement.
- Cargo Transport:Unmanned payload delivery for logistics providers concentrates in Middle Eastern urban air mobility corridors where operational uptime metrics govern contract renewal.
Urban Mobility anchors development capital allocation. Cargo Transport is gaining share fastest through aftermarket service unbundling.
End User:
Procurement authority and budget cycles create distinct sales motion requirements from consumer financing to defense contracting vehicles.
- Individual Consumers:Personal mobility purchases face regulatory uncertainty and insurance market immaturity limiting near-term addressable demand.
- Government Agencies:Fire departments and medical transport authorities in Japan expand fleet procurement through designated urban air mobility corridors.
- Defense Contractors:Military specifications prioritize performance parameters over unit cost with extended development timelines and specialized certification requirements.
- Logistics Providers:Fleet operators in Dubai unbundle battery lifecycle management and predictive maintenance from platform acquisition, shifting supplier relationships toward performance-guarantee structures.
Government Agencies represent the established procurement base. Logistics Providers are climbing the fastest through operational pilot program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply chains for flying bike components cluster in East Asian manufacturing hubs while regulatory momentum concentrates in Japan and the UAE. The analysis tracks five countries where certification frameworks and procurement programs are operationalizing commercial deployment.
United States
FAA's powered-lift aircraft certification framework is compressing type-approval timelines for manufacturers targeting US airspace entry. The agency's evolving standards accelerate multi-jurisdiction operational clearances before harmonization mechanisms mature. California-based development clusters concentrate tilt-wing engineering talent for inter-city cargo corridor applications.
Japan
METI urban air mobility corridor designations in Osaka and Tokyo de-risk early commercial deployment for vertical-lift platforms. Fire departments and medical transport agencies expand fleet procurement of electric vertical takeoff configurations through regulated operational envelopes. Manufacturing partnerships in the Chubu region supply ducted fan assemblies for acoustic-sensitive urban deployments.
United Arab Emirates
Dubai's operational pilot programs for urban air mobility establish regulatory precedents that adjacent Gulf Cooperation Council markets adopt. Logistics providers unbundle battery lifecycle management and predictive maintenance from platform acquisition, shifting supplier relationships toward performance-guarantee structures. The emirate's cargo transport corridors concentrate demand for hybrid propulsion systems with extended range specifications.
Germany
EASA's framework development under the EU Green Deal embeds environmental compliance metrics into European type-certification pathways. Manufacturers targeting EU airspace must integrate life-cycle carbon accounting and noise footprint thresholds into initial design phases. Bavaria-based engineering clusters specialize in turbine-electric architectures for hybrid propulsion maturation.
China
MIIT standards development for low-altitude aerial vehicles shapes domestic certification timelines parallel to Western frameworks. Battery cell manufacturing concentration exposes OEMs to input cost volatility and geopolitical sourcing risk. Shenzhen-Guangzhou industrial corridors dominate lithium-ion supply chain integration for electric vertical takeoff configurations.
Flying Bikes Market Competitive Landscape
Tilt-wing specialists and hybrid propulsion developers split the market along range-performance tradeoffs. The vendor base concentrates around three strategic archetypes: established cycle manufacturers extending into aerial platforms, aerospace contractors repurposing vertical-lift engineering heritage, and battery-electric mobility startups scaling from ground-based precedents. Competitive moves center on type-certification pre-positioning across FAA and EASA timelines, plus aftermarket service contract unbundling to capture recurring revenue independent of hardware cycles.
Among the named players, Coolfly anchors premium positioning in tilt-wing configurations through engineering investments in rotor pivot mechanisms. RICTOR occupies a position within the hybrid propulsion tier, representing aggressive R&D intensity on turbine-electric architectures. Giant exemplifies manufacturing scale advantages that sustain cost competitiveness across multi-seat platform variants for government fleet procurement.
| Leading Market Players |
|---|
| Coolfly |
| Cervelo |
| RICTOR |
| Ridley |
| Giant |
| LEO |
| Verge Motorcycles |
| Canyon |
| Kuickwheel Technology |
| Others |
Supply & Pricing Matrix
Shenzhen-Guangzhou industrial corridors concentrate lithium-ion cell manufacturing capacity that translates directly into input cost leverage for downstream flying bike OEMs. Battery pack pricing volatility propagates through electric vertical takeoff configurations faster than hybrid propulsion systems with turbine-electric buffers.
Pricing Analysis
FAA's powered-lift aircraft certification dictates the pricing tier structure across the flying bike market. Three-tier pricing structure across premium tilt-wing, standard multirotor, and economy single-seat levels separates platforms by certification grade and range performance. Cost compression in battery-electric tiers is intensifying because lithium-ion supply concentration exposes OEMs to East Asian sourcing risk. Logistics providers in Dubai demonstrate lowest price sensitivity due to performance-guarantee contract structures, while individual consumer segments face regulatory uncertainty that amplifies budget constraints.
Supply Chain Analysis
High-grade lithium carbonate, permanent magnet rare earths, and aerospace-grade aluminum alloys feed into flying bike manufacturing from concentrated upstream sources. China, South Korea, and Japan anchor battery cell production. Single-source vulnerability in rare earth processing creates procurement exposure for ducted fan motor assemblies. Distribution runs through government fleet procurement channels and logistics provider direct contracts rather than retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among Japan's emergency response agencies and Dubai's logistics providers is shifting bargaining power toward fleet operators with volume scale. Buyer fragmentation in individual consumer segments leaves that tier exposed to margin pressure.
For Market Incumbents: Build certification moats through dual-track FAA and EASA type-approval investments before harmonization mechanisms mature. Secure captive supply of lithium-ion cells through backward integration into East Asian manufacturing partnerships. Defend against emerging battery-electric mobility startups by anchoring aftermarket service contracts with predictive maintenance platforms. For New Entrants and Emerging Players: Pursue white-space positioning in ducted fan configurations for EASA noise compliance corridors where established multirotor players face redesign costs. Target Japan's METI-designated emergency response procurement as the most penetrable government segment with landing zone flexibility requirements. Lead with battery lifecycle management service bundling to differentiate from hardware-centric incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid propulsion specialists with turbine-electric architectures that bridge battery limitations and jet performance. Long-term viability rests on platforms capable of military operations segment entry with extended range specifications. Watch FAA-EASA timeline convergence as the inflection signal for multi-jurisdiction revenue scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Jurisdiction Certification Investment | FAA-EASA parallel track approvals compress time-to-revenue for tilt-wing platforms targeting US and EU airspace. |
| Battery Lifecycle Management Unbundling | Dubai logistics providers shift supplier relationships toward performance-guarantee structures independent of hardware cycles. |
| Hybrid Propulsion R&D Intensification | Turbine-electric architectures extend operational range for Japan emergency response medical evacuation missions. |
| Aftermarket Predictive Maintenance Platform | Operational uptime metrics in Middle Eastern cargo corridors govern contract renewal decisions for fleet operators. |
| Military Operations Segment Entry | Defense procurement parameters prioritize jet propulsion performance with higher-margin contract structures. |
Research Methodology
A spread of perspectives from platform engineering directors, FAA certification consultants, fleet procurement managers at Dubai logistics providers, and METI urban air mobility coordinators converged on the working assumptions. Primary interview insights combined with secondary validation from FAA powered-lift aircraft filings, EASA environmental compliance documentation, Japan METI corridor designation records, and customs trade data for lithium-ion cell imports. Bottom-up unit shipment modeling and top-down addressable market sizing triangulated volume estimates.
Demand-supply balance framing anchored the forecast framework across the analysis window. Segmentation dimensions modeled include propulsion architecture, lift mechanism technology, operational mission profile, and procurement authority tier. CAGRs derived from growth driver elasticity analysis against regulatory timeline acceleration and battery cost curve assumptions. Forecast inputs incorporated METI corridor operationalization schedules and EASA EU Green Deal compliance integration timelines.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate spot prices and rare earth export restrictions would shift the trajectory. Forecasts reflect documented assumptions about certification harmonization progress and airspace integration infrastructure deployment. Cross-checking against FAA type-approval pipeline disclosures and EASA environmental compliance certification queues is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Netherlands E-Bike Market
Bikes and Motorcycles
Motorsports Motorcycle Market
Bikes and Motorcycles
Cargo Bike Market
Bikes and Motorcycles
UAE Electric Bike Market
Bikes and Motorcycles
North America Bicycle Market
Bikes and Motorcycles
Two-Wheeler Market
Bikes and Motorcycles
Folding Bicycle Market
Bikes and Motorcycles
GPS Bike Computers Market
Bikes and Motorcycles
Japan Motorcycle ADAS Market
Bikes and Motorcycles
South Africa E-Bike Market
Bikes and Motorcycles
Motorcycle ADAS Market
Bikes and Motorcycles
Austria E-Bike Market
Bikes and Motorcycles
Automotive Chain Sprockets Market
Bikes and Motorcycles
United Arab Emirates E-Bike Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Global Motorcycle Handlebar Control Switch Market