
 Cargo Bicycles Market | 2026-2036
Cargo Bicycles Market Size, Share, and Industry Trends Forecast 2026-2036
Cargo Bicycles Market Intelligence
Urban logistics procurement is decoupling from traditional fleet van contracts as small businesses and delivery platforms diversify across multiple cargo bike vendors. Rad Power Bikes leverages direct-to-consumer channels to sustain volume in North American metropolitan markets. Riese & Müller GmbH anchors premium positioning through German engineering standards and extended-range battery systems. Urban Arrow dominates the front-loader segment in Dutch commercial fleets through specialized box-frame designs optimized for parcel density.
Cargo bicycles are human-electric hybrid vehicles engineered to transport payloads exceeding standard bicycle capacity, typically featuring reinforced frames, extended wheelbases, and integrated cargo platforms rated for loads between 100 and 400 kilograms. Electric variants incorporate mid-drive or hub motors with torque sensors to maintain stability under asymmetric loads during urban navigation. Electric cargo bikes lead product type revenue as municipal zero-emission zones expand across European city centers, while utility cargo bikes retain cost advantages in emerging markets where motorization premiums deter adoption. Aluminum frames command material preference for weight-to-strength ratios in commercial delivery applications, though steel persists in heavy-duty cargo bikes where payload rating supersedes efficiency optimization.
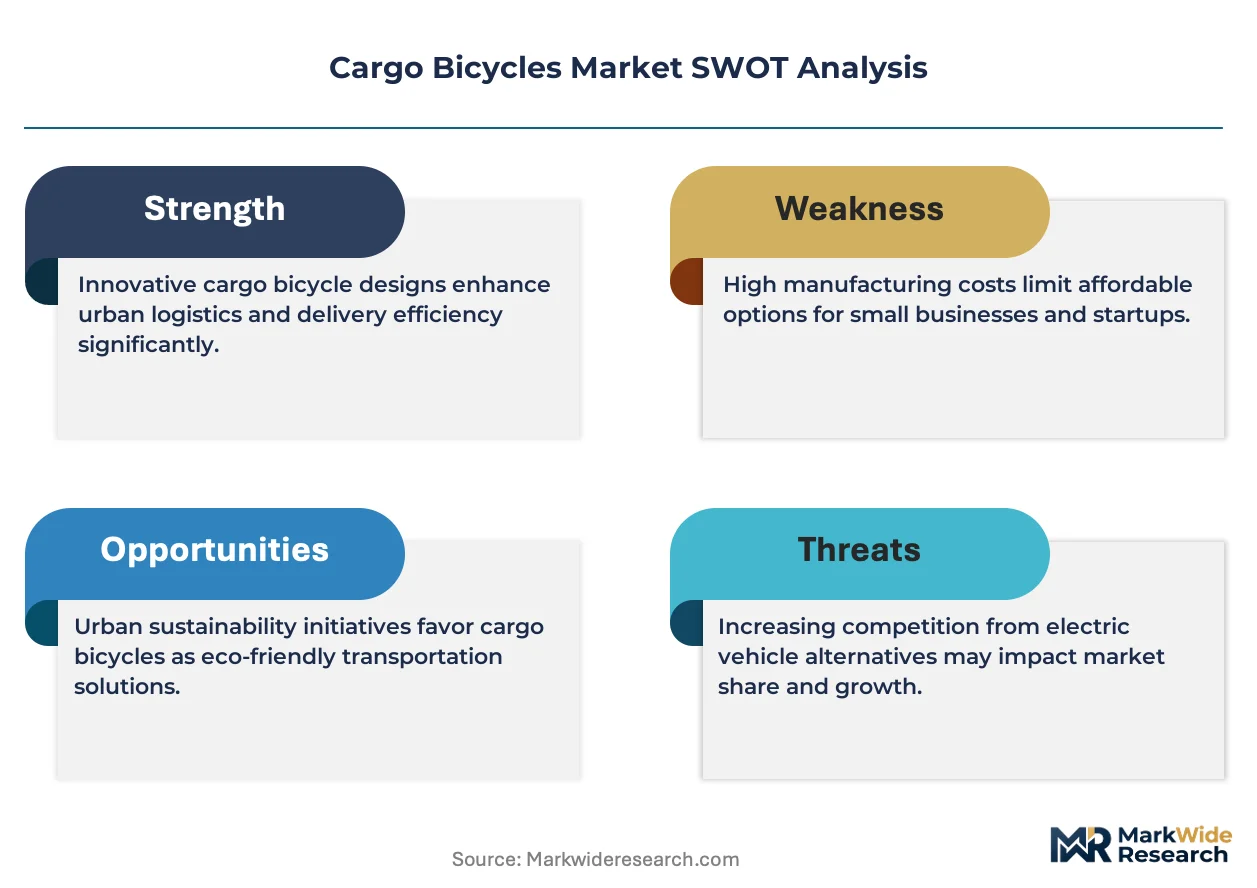
European regulators including the EU Green Deal framework and national transport ministries are mandating carbon reduction in urban freight, directly accelerating fleet electrification requirements for last-mile operators. The F-Gas Regulation and REACH compliance standards shape battery thermal management material selection and frame coating chemistries for manufacturers accessing EU markets. Stakeholders must monitor how municipal curb-access permits and lane infrastructure investments determine which vehicle formats achieve operational viability in priority cities.
Market Dynamics
Urban zero-emission zones are forcing commercial fleet operators to abandon diesel vans for electric cargo bikes, creating a structural demand pull that reshapes vehicle procurement across European logistics networks.
Growth Catalysts
- EU Green Deal framework:National transport ministries in Germany, Denmark, and the Netherlands mandate carbon reduction targets for urban freight operators, directly accelerating fleet electrification requirements.
- Battery energy density improvements:Lithium-ion cell chemistry advances have extended electric cargo bike range to 100+ kilometers per charge, eliminating range anxiety for last-mile delivery routes.
- Last-mile delivery consolidation:E-commerce volume concentration in Amsterdam, Copenhagen, and Berlin creates route density that justifies dedicated cargo bike fleet investments over van contracts.
Market Restraints
- Lithium carbonate price volatility:Battery pack input costs fluctuate with raw material spot markets, compressing manufacturer margins and creating pricing uncertainty for fleet buyers.
- Frame welding automation concentration:Robotic welding equipment suppliers cluster in German and Chinese industrial centers, creating supply bottleneck risks for new market entrants.
- Payload-to-efficiency tradeoffs:Steel-reinforced frames rated above 300 kilograms add 40% weight penalty versus aluminum, limiting electric range and requiring larger battery packs.
Strategic Opportunities
- Indian urban logistics:Utility cargo bikes without motorization face minimal regulatory barriers in dense cities where motorization premiums deter electric adoption, creating cost-driven volume potential.
- Mid-drive torque sensor convergence:Integration of load-compensating motor control with hydraulic disc braking systems enables safer operation on hilly terrain, opening new geographic markets.
- Direct-to-consumer channel expansion:Bypassing traditional bicycle retail networks through online configuration tools captures margin and accelerates replacement cycles in North American metropolitan markets.
Industry Challenges
- Certification timeline compression:EU type-approval procedures for electric cargo bikes under the Machinery Directive and EN 15194 standards create 6-12 month market entry delays for new models.
- Asymmetric load stability engineering:Front-loader designs require specialized frame geometry and steering dampers to prevent oscillation under uneven parcel distribution, demanding scarce mechanical engineering talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cargo Bicycles Market |
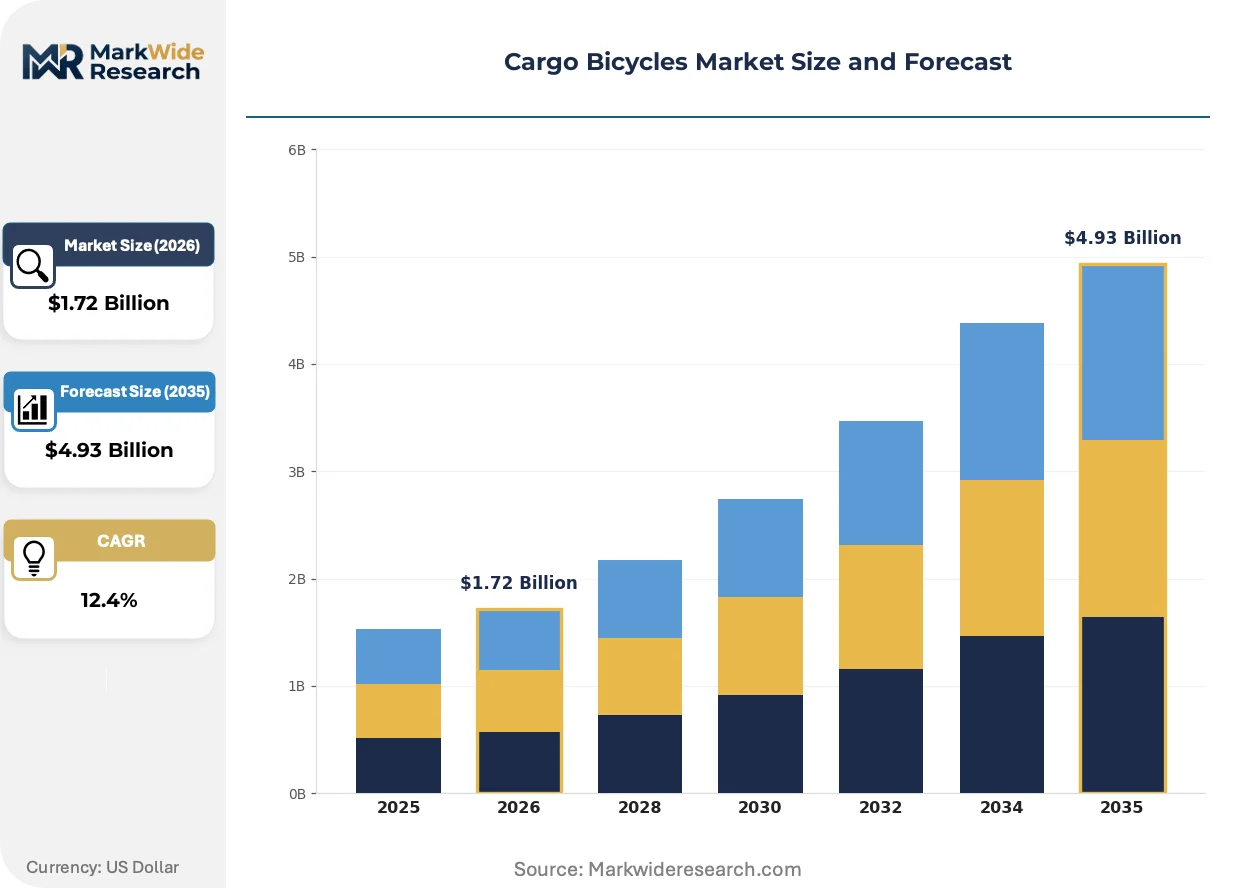
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $4.93 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Cargo Bikes, Utility Cargo Bikes, Family Cargo Bikes, Heavy-Duty Cargo Bikes Application: Urban Transport, Delivery Services, Recreational Use, Food Transportation End User: Small Businesses, Families, Retailers, Logistics Companies Material: Aluminum, Steel, Carbon Fiber, Composite |
| Companies Covered | Rad Power Bikes, Riese & Müller GmbH, Yuba Bicycles, CERO, Babboe, Urban Arrow, Tern, Accell Group, Butchers & Bicycles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cargo Bicycles Market Strategic Shifts & Innovations
Active reshaping of the cargo bicycle market centers on powertrain sophistication, regulatory compliance automation, and procurement model disintermediation that together redefine competitive positioning.
Mid-drive motor systems with integrated torque sensing are absorbing the functional role previously served by hub motors in premium commercial applications. Dutch and German last-mile operators specify these units for routes exceeding 50 kilometers daily, where load-compensating power delivery prevents battery depletion under heavy parcel stacks. The technology is absorbing market share from simpler hub-motor configurations as fleet managers prioritize range predictability over upfront unit cost.
REACH compliance and F-Gas Regulation standards in Europe now govern battery thermal management material selection and frame coating chemistries for manufacturers accessing EU markets. Industrial consequence includes mandatory substitution of certain flame-retardant additives and refrigerants in battery cooling systems. Component suppliers serving Riese & Müller GmbH and Urban Arrow must maintain dual material inventories to satisfy divergent regulatory requirements between European and North American product lines.
Fleet procurement patterns now favor multi-vendor diversification over single-source van contracts, with small businesses and delivery platforms splitting orders across specialized cargo bike vendors. Traditional bicycle retail channels lose volume to direct manufacturer relationships as buyers seek configuration flexibility and faster replacement parts access. This behavioral shift concentrates in Netherlands and Denmark municipalities where cycling infrastructure density supports operational confidence in cargo bike reliability.
Cargo Bicycles Market Segmentation
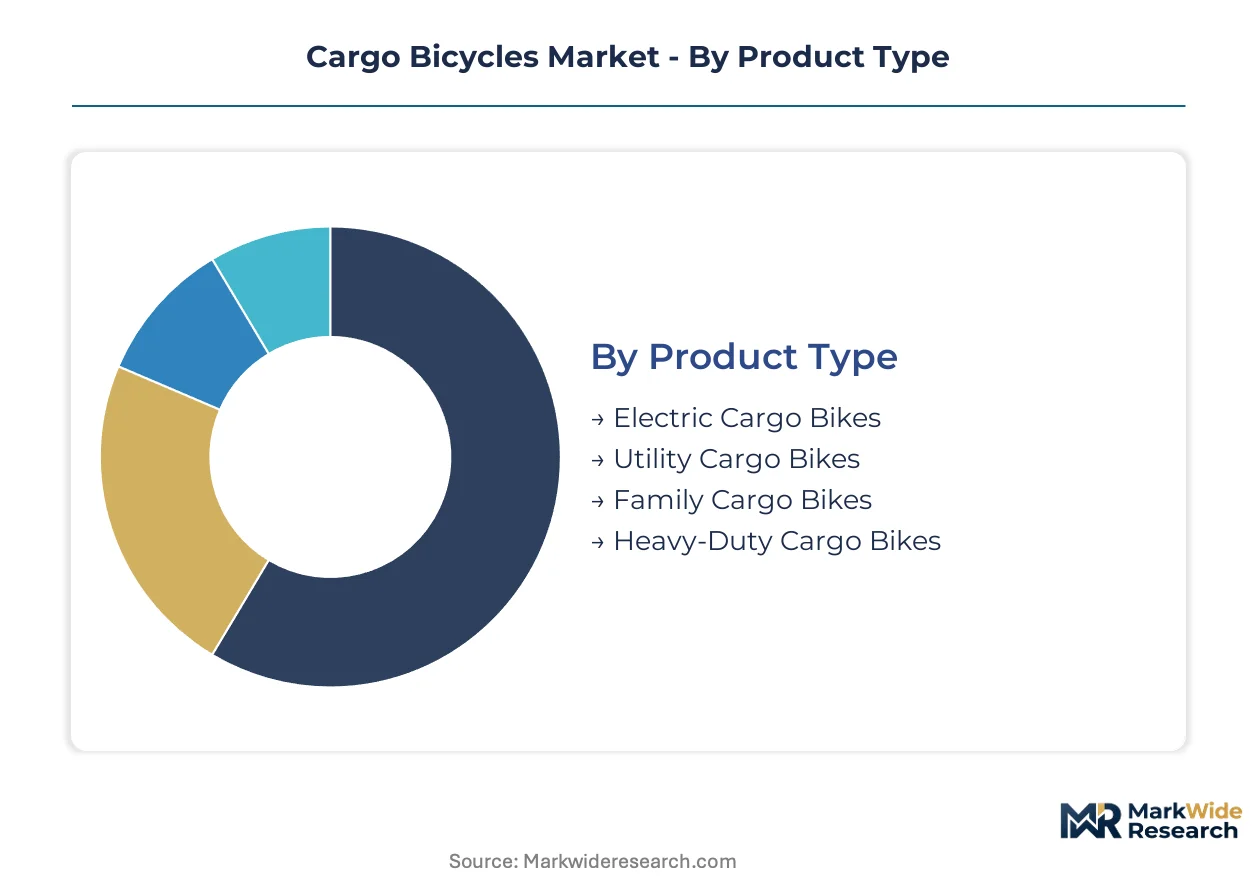
Cargo bicycle segmentation reflects divergent certification burdens across powertrain technologies and frame materials. Fleet procurement decisions hinge on which segments clear EU type-approval under EN 15194 and Machinery Directive standards versus utility variants that face minimal regulatory barriers.
Product Type:
EN 15194 certification requirements and Machinery Directive compliance create tiered approval timelines that segment market entry costs and fleet procurement cycles.
- Electric Cargo Bikes:Mid-drive and hub motor configurations require EU type-approval under EN 15194 standards, with battery thermal management systems governed by REACH and F-Gas Regulation compliance. Demand concentrates in Amsterdam, Copenhagen, and Berlin where municipal zero-emission zones mandate electrification for commercial last-mile operators.
- Utility Cargo Bikes:Human-powered variants bypass motorization certification entirely, enabling faster market entry and lower procurement costs. Volume clusters in Indian urban logistics corridors where motorization premiums deter electric adoption and dense traffic favors lightweight maneuverability.
- Family Cargo Bikes:Child-carrying configurations prioritize safety certification for passenger restraint systems and rollover protection.
- Heavy-Duty Cargo Bikes:Reinforced frames rated above 300 kilograms require structural load testing under specialized commercial vehicle standards.
Electric Cargo Bikes sits at the top of the volume ranking, with Utility Cargo Bikes climbing the fastest.
Application:
Route density and payload requirements determine which applications justify dedicated fleet investment versus shared-use models.
- Delivery Services:Parcel density in metropolitan cores creates route economics that favor electric cargo bikes over diesel vans for last-mile fulfillment. Amsterdam and Berlin have emerged as reference deployments where delivery platforms consolidate multi-vendor cargo bike fleets.
- Urban Transport:Municipal procurement for shared mobility schemes favors standardized configurations that simplify maintenance networks.
- Recreational Use:Direct-to-consumer channels bypass traditional retail markups for leisure-oriented buyers in North American metropolitan markets.
- Food Transportation:Cold-chain requirements drive specification of insulated cargo boxes and battery systems rated for extended duty cycles.
Delivery Services commands the largest installed base, with Food Transportation expanding most quickly.
End User:
Procurement scale and replacement cycle frequency separate enterprise fleet operators from household acquisition patterns.
- Logistics Companies:Enterprise fleet operators negotiate multi-year service contracts with direct manufacturer relationships, bypassing traditional bicycle retail networks entirely. German and Dutch last-mile specialists specify extended-range battery systems and standardized component architectures to minimize downtime.
- Small Businesses:Independent retailers and service providers prioritize upfront cost minimization over configuration flexibility.
- Families:Household acquisition concentrates in cycling infrastructure-dense municipalities where operational confidence supports premium positioning.
- Retailers:Commercial buyers favor front-loader designs optimized for parcel density and curb-access efficiency.
Logistics Companies holds the dominant share, with Small Businesses gaining share fastest.
Material:
Weight-to-strength tradeoffs and welding automation availability shape material selection across payload tiers.
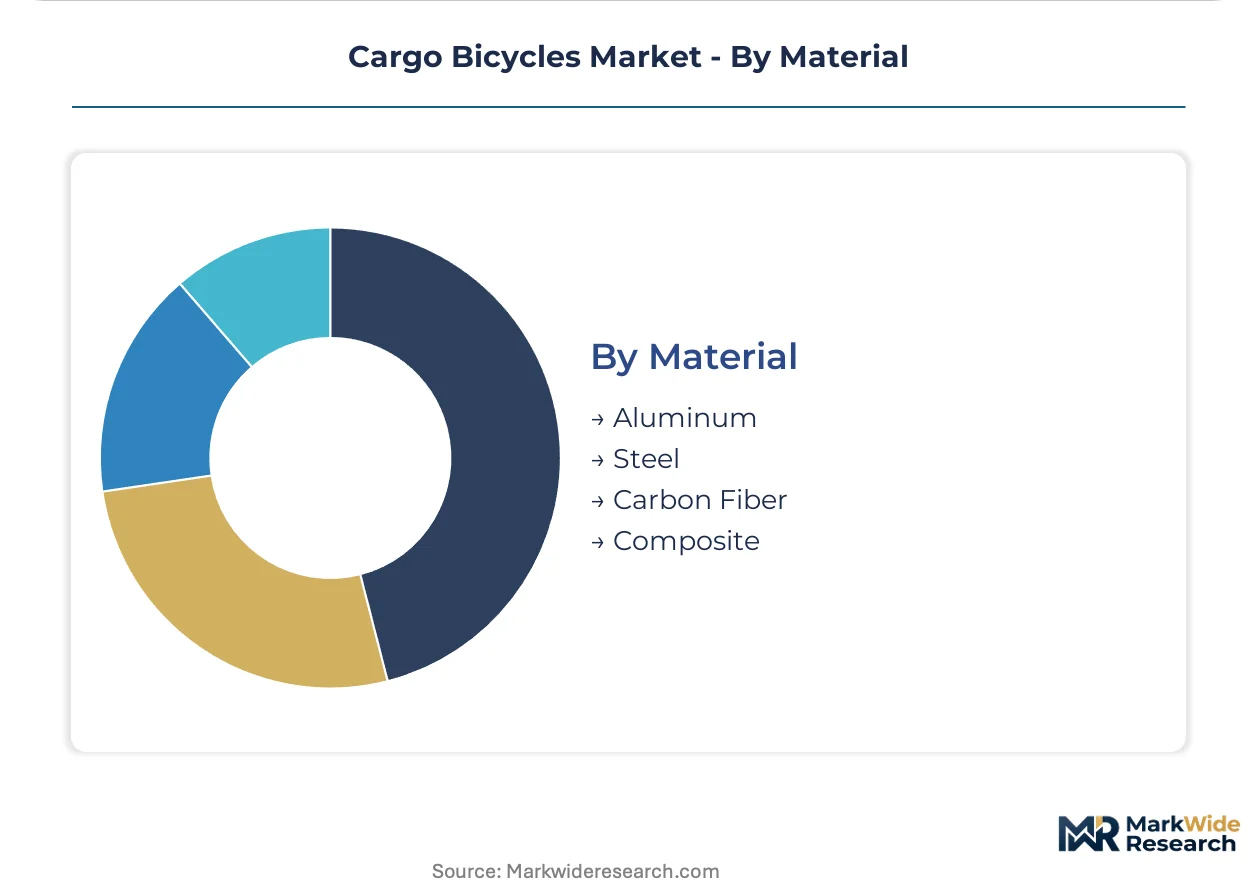
- Aluminum:Extruded and hydroformed frames deliver optimal weight-to-strength ratios for commercial delivery applications where range efficiency determines battery sizing. Frame welding automation clusters in German industrial centers, creating supply concentration for premium European manufacturers.
- Steel:Heavy-duty applications rated above 300 kilograms accept 40% weight penalties in exchange for structural durability and repairability.
- Carbon Fiber:High-performance recreational variants prioritize stiffness-to-weight ratios over cost minimization.
- Composite:Hybrid material constructions target niche applications requiring corrosion resistance or electromagnetic shielding.
Aluminum leads material procurement volumes, with Composite posting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mechanical engineering talent and frame welding automation expertise cluster in German industrial centers, Dutch logistics corridors, and emerging Asian manufacturing hubs. This workforce distribution shapes where design innovation and production scale concentrate.
Germany
Last-mile delivery operators in Berlin and Hamburg specify extended-range electric cargo bikes for routes exceeding 50 kilometers daily. The EU Green Deal framework mandates carbon reduction targets for urban freight operators, accelerating fleet electrification procurement cycles. Manufacturing gravity centers on Baden-Württemberg and Bavaria, where robotic welding equipment suppliers serve premium frame fabricators.
Netherlands
Amsterdam's dense cycling infrastructure supports the highest commercial cargo bike penetration globally among delivery fleets. Municipal zero-emission zones in Rotterdam and Utrecht ban diesel vans from city cores, creating structural demand pull for electric variants. The Randstad corridor hosts specialized front-loader designers and battery system integrators serving Dutch and Belgian logistics networks.
Denmark
Copenhagen's municipal procurement for shared mobility schemes favors standardized cargo bike configurations that simplify maintenance networks. National transport ministry targets align with EU Green Deal carbon reduction mandates for urban freight. Odense and Aarhus emerge as testbed cities where mid-drive torque sensor integration opens hilly terrain routes previously unsuitable for hub-motor designs.
India
Utility cargo bikes without motorization face minimal regulatory barriers in dense urban logistics corridors where motorization premiums deter electric adoption. The Bureau of Indian Standards governs bicycle safety specifications, though human-powered variants bypass complex type-approval procedures. Manufacturing concentrates in Gujarat and Tamil Nadu industrial zones serving cost-driven volume demand from small business transporters.
United States
Direct-to-consumer channels bypass traditional bicycle retail networks in New York, San Francisco, and Seattle metropolitan markets. EPA tailpipe emission standards and municipal congestion pricing create indirect pressure on last-mile operators to diversify fleet composition. Pacific Northwest and Northeast corridor cities invest curb-access permits and protected lane infrastructure that determine cargo bike operational viability.
Cargo Bicycles Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base spans German engineering-centric premium manufacturers, Dutch front-loader specialists, and North American direct-to-consumer disruptors. Three strategic archetypes dominate: vertically integrated frame fabricators controlling welding automation, battery system integrators with thermal management expertise, and brand-led assemblers outsourcing production to contract manufacturers. Capacity expansion in automated frame welding and strategic partnerships for motor system sourcing represent the dominant competitive moves.
Within the premium engineering tier, Riese & Müller GmbH and Urban Arrow exemplify European manufacturers anchoring high-specification commercial fleet supply. Rad Power Bikes occupies a position among North American direct-to-consumer specialists leveraging online configuration tools to capture margin and accelerate replacement cycles. These three companies represent divergent geographic and channel strategies while collectively demonstrating how certification timelines and torque sensor integration capabilities separate viable competitors from aspirants.
| Leading Market Players |
|---|
| Rad Power Bikes |
| Riese & Müller GmbH |
| Yuba Bicycles |
| CERO |
| Babboe |
| Urban Arrow |
| Tern |
| Accell Group |
| Butchers & Bicycles |
| Others |
Cost & Logistics Intelligence
Lithium carbonate spot volatility feeds through battery pack input costs to compress manufacturer margins and create pricing uncertainty for fleet buyers negotiating multi-year service contracts. Frame welding automation concentration in German industrial centers shapes tiered cost structures downstream, with premium European manufacturers commanding price premiums over contract-manufactured alternatives.
Pricing Analysis
Bundled service contracts with multi-year maintenance agreements separate fleet procurement from unbundled direct-to-consumer transactions where buyers absorb replacement parts risk. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EN 15194 and Machinery Directive standards. Cost compression in mid-tier electric cargo bikes is intensifying because battery thermal management material substitution under REACH compliance adds input expense. Small business transporters in Indian urban logistics corridors exhibit highest price sensitivity, while German logistics companies prioritize range predictability over upfront unit cost.
Supply Chain Analysis
Mid-drive motor systems with integrated torque sensors draw from Japanese and German precision manufacturing clusters, while lithium-ion cell production rests on Chinese, South Korean, and Japanese chemical processing capacity. Robotic welding equipment for aluminum frame fabrication sources from German and Chinese industrial centers, creating geographic concentration for premium frame fabricators. Single-source vulnerability in semiconductor components for motor control systems threatens production continuity. Distribution runs through direct manufacturer relationships for enterprise fleet operators, bypassing traditional bicycle retail networks entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cargo bicycle procurement is shifting toward premium specifications as fleet managers prioritize range predictability and load-compensating power delivery over upfront cost minimization.
For Market Incumbents: Deepen backward integration into automated frame welding capacity in Baden-Württemberg and Bavaria to defend against contract-manufactured alternatives. Accelerate certification investment under EN 15194 and Machinery Directive standards to extend approval timeline advantages over emerging entrants. Channel control through direct-to-consumer configuration tools reinforces margin position against retail-dependent competitors. For New Entrants and Emerging Players: EU Green Deal framework in Germany, Denmark, and the Netherlands opens a window for utility cargo bike variants bypassing motorization certification entirely. Target Indian urban logistics corridors where motorization premiums deter electric adoption and minimal regulatory barriers enable faster market entry. Food transportation applications with cold-chain requirements represent the most penetrable segment for insulated cargo box specialization. For Investors and Strategic Acquirers: Consolidation pressure builds where robotic welding equipment suppliers cluster in German and Chinese industrial centers, creating supply bottleneck risks for fragmented assemblers. Long-term viability across the analysis window favors vertically integrated frame fabricators controlling welding automation and battery system integrators with thermal management expertise. Watch municipal curb-access permit expansion in Pacific Northwest and Northeast corridor cities as inflection indicator for North American operational viability.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Frame Welding Capacity Expansion | Baden-Württemberg and Bavaria manufacturing gravity secures supply continuity for premium European producers. |
| Battery Thermal Management Certification | REACH and F-Gas Regulation compliance enables EU market access for electric cargo bike variants. |
| Direct-to-Consumer Channel Development | Online configuration tools capture margin and accelerate replacement cycles in North American metropolitan markets. |
| Mid-Drive Torque Sensor Integration | Load-compensating motor control opens hilly terrain routes in Copenhagen, Odense, and Aarhus testbed cities. |
| Front-Loader Frame Geometry Patenting | Specialized steering dampers prevent oscillation under uneven parcel distribution in Dutch commercial fleets. |
Research Approach
Coverage spans Germany, Netherlands, Denmark, India, and United States markets, with primary inputs from each regional cluster combined with secondary validation. Fleet procurement managers at German and Dutch last-mile operators, battery system integrators serving Riese & Müller GmbH and Urban Arrow, robotic welding equipment suppliers in Baden-Württemberg, and municipal transport planners in Amsterdam and Copenhagen provided stakeholder perspectives. Secondary sources include EU Green Deal framework documentation, EN 15194 and Machinery Directive standards, Bureau of Indian Standards bicycle safety specifications, and EPA tailpipe emission standards. Bottom-up volume modeling triangulates against top-down market sizing across powertrain technologies and frame materials.
Rate-of-change decomposition separates volume growth from price movement across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and material grade tier. CAGRs derive from fitted growth curves calibrated to fleet electrification procurement cycles and municipal zero-emission zone implementation timelines. Industry-specific inputs incorporate battery energy density improvement trajectories and frame welding automation adoption curves.
Revisions become necessary when lithium carbonate spot markets experience sustained volatility, EU type-approval procedures extend beyond standard timelines, or municipal infrastructure investments diverge from planned curb-access permit expansion. Forecasts reflect documented assumptions about regulatory enforcement consistency and fleet replacement cycle frequency. A small set of named triggers warrants ongoing watch: F-Gas Regulation amendment scope, Indian Bureau of Standards motorization rule changes, and Pacific Northwest protected lane infrastructure commitment levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Aluminum Alloy Bicycle Crankset Market
Bikes and Motorcycles
Ride on Bikes Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Motorcycle Drivetrain Market
Bikes and Motorcycles
Sweden E-Bike Market
Bikes and Motorcycles
Motorbike Riding Gear Market
Bikes and Motorcycles
Motorcycles, Scooters and Mopeds Market
Bikes and Motorcycles
Global Motorcycle Market
Bikes and Motorcycles
Motorcycle Suspension System Market
Bikes and Motorcycles
Carbon Fiber Bicycle Market
Bikes and Motorcycles
Smart Electric Bikes Market
Bikes and Motorcycles
Motorcycle Headlight Bracket Market
Bikes and Motorcycles
China Motorcycle ADAS Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Global Motorcycle Handlebar Control Switch Market
Bikes and Motorcycles
Asia-Pacific Motorcycle Market