
 Europe Motorcycle Airbag Market | 2026-2036
Europe Motorcycle Airbag Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Motorcycle Airbag Market Analytics
CE certification under the EU's Personal Protective Equipment Regulation is rotating market access, forcing smaller suppliers toward third-party testing partnerships. Dainese leverages its in-house D-Air laboratory network to sustain rapid homologation cycles. Alpinestars anchors premium positioning through MotoGP-derived electronic deployment algorithms. Helite competes on mechanical simplicity, navigating lower price tiers with tether-activated vest systems.
A motorcycle airbag system integrates crash sensors, inflation canisters, and protective bladders into rider-worn garments, typically deploying within 25-80 milliseconds to stabilize the neck, torso, and coccyx upon impact detection. Electronic systems dominate value capture through gyroscopic and accelerometer-based trigger logic, while mechanical tether systems retain cost-sensitive touring and commuter segments. Jacket-integrated airbags command the largest product-type volume, though full-suit configurations for professional racers concentrate the highest margin pools.
The EU General Safety Regulation and ECE R22.06 helmet standards collectively shape product development timelines, with the former mandating vehicle-integrated rider assistance that indirectly elevates airbag compatibility requirements. France's ANSM and Germany's KBA enforce national type-approval protocols that extend beyond baseline CE marking. Stakeholders must monitor whether the EU AI Act's risk-classification framework will recategorize algorithmic crash-prediction systems as high-risk artificial intelligence, potentially triggering additional conformity assessment burdens.
Market Dynamics
The EU General Safety Regulation mandates advanced rider assistance systems, forcing motorcycle OEMs to engineer airbag-compatible chassis architectures and accelerating garment-airbag integration across the value chain.
Growth Catalysts
- EU General Safety Regulation:The mandate for vehicle-integrated rider assistance systems creates technical pathways for airbag-garment synchronization, expanding addressable rider populations.
- Professional racing homologation:MotoGP-derived electronic deployment algorithms filter into consumer-grade systems, legitimizing premium pricing tiers for track-day enthusiasts.
- Alpine touring corridors:Concentrated high-speed motorcycle traffic across Swiss, Austrian, and Italian mountain passes generates sustained replacement demand for protective equipment.
Market Restraints
- Helium and argon canister supply:Inflation gas procurement depends on industrial gas distributors concentrated in Germany and France, exposing manufacturers to energy-input volatility.
- CE certification timeline:The EU Personal Protective Equipment Regulation's conformity assessment cycles extend 12-18 months for novel electronic trigger architectures.
- Mechanical tether substitutes:Lower-cost vest systems without electronic components satisfy price-sensitive touring segments, compressing margins for algorithmic deployment systems.
Strategic Opportunities
- Eastern European touring growth:Underpenetrated markets in Poland, Czech Republic, and Romania present first-mover positioning for mid-tier electronic systems.
- EU AI Act classification:Algorithmic crash-prediction modules may trigger high-risk AI conformity pathways, creating compliance-service revenue streams for testing laboratories.
- Direct-to-rider digital channels:Motorcycle club subscription models and track-day event partnerships bypass traditional retail markup structures.
Industry Challenges
- Embedded software talent scarcity:Firmware engineering for millisecond-level sensor fusion competes with automotive ADAS programs for specialized developers.
- Multi-standard certification burden:France's ANSM and Germany's KBA maintain divergent national type-approval protocols beyond baseline CE marking.
- Garment-airbag integration complexity:Jacket manufacturers lack in-house pyrotechnic expertise, forcing dependency on tier-two inflator specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Motorcycle Airbag Market |
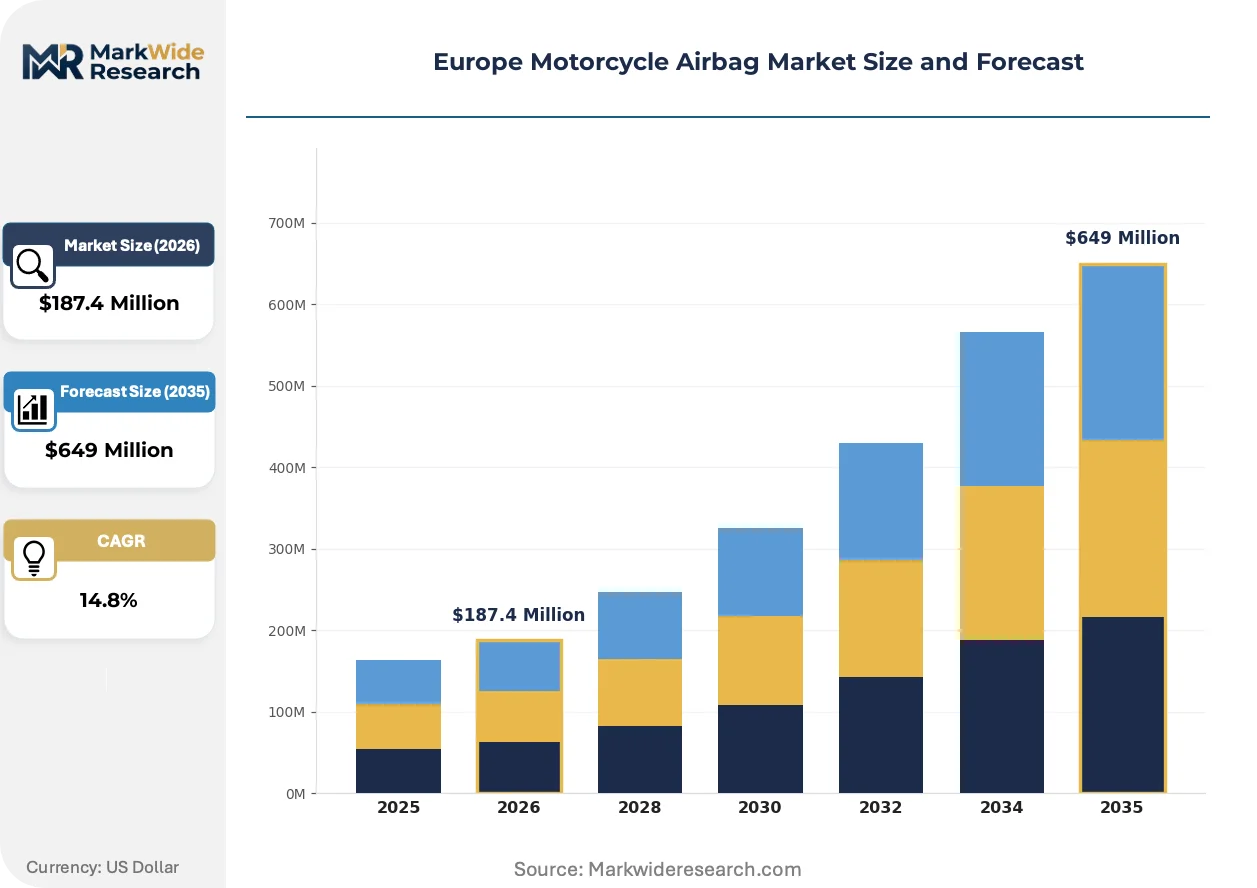
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $649 Million |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electronic Systems, Mechanical Systems, Hybrid Systems, Inflatable Systems Product Type: Vest, Jacket, Pants, Full Suit Deployment: On-Road, Off-Road, Racing, Touring End User: Recreational Riders, Commuters, Professional Racers, Safety Enthusiasts |
| Companies Covered | REV'IT!, Held GmbH, Dainese, Rukka, Furygan, Alpinestars, Spidi Sport, IXS, Helite, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Motorcycle Airbag Market Evolving Landscape
Electronic crash-detection architectures are displacing mechanical tether systems across premium motorcycle protective equipment, compressing deployment latency and expanding addressable use cases beyond track environments.
Gyroscopic sensor arrays paired with accelerometer clusters now enable predictive deployment algorithms that trigger inflation before ground contact. Professional racing teams in Italy and Germany validate these systems under extreme lean-angle and high-speed scenarios. The technology is displacing legacy tether-activated vests in the touring segment as riders demand protection during low-side crashes where tethers fail to activate.
The EU AI Act's risk-classification framework recategorizes algorithmic crash-prediction modules as potential high-risk artificial intelligence systems. This regulatory repositioning triggers additional conformity assessment burdens for electronic airbag manufacturers. French and German notified bodies are expanding technical documentation requirements for machine-learning-based trigger logic, compressing product development timelines.
Track-day event organizers and motorcycle touring clubs now aggregate rider purchases through group procurement schemes. These collective buying arrangements displace traditional retail channels for premium electronic systems. The pattern concentrates in Alpine markets where club membership correlates with high-frequency riding and elevated safety equipment replacement rates.
Europe Motorcycle Airbag Market Segmentation
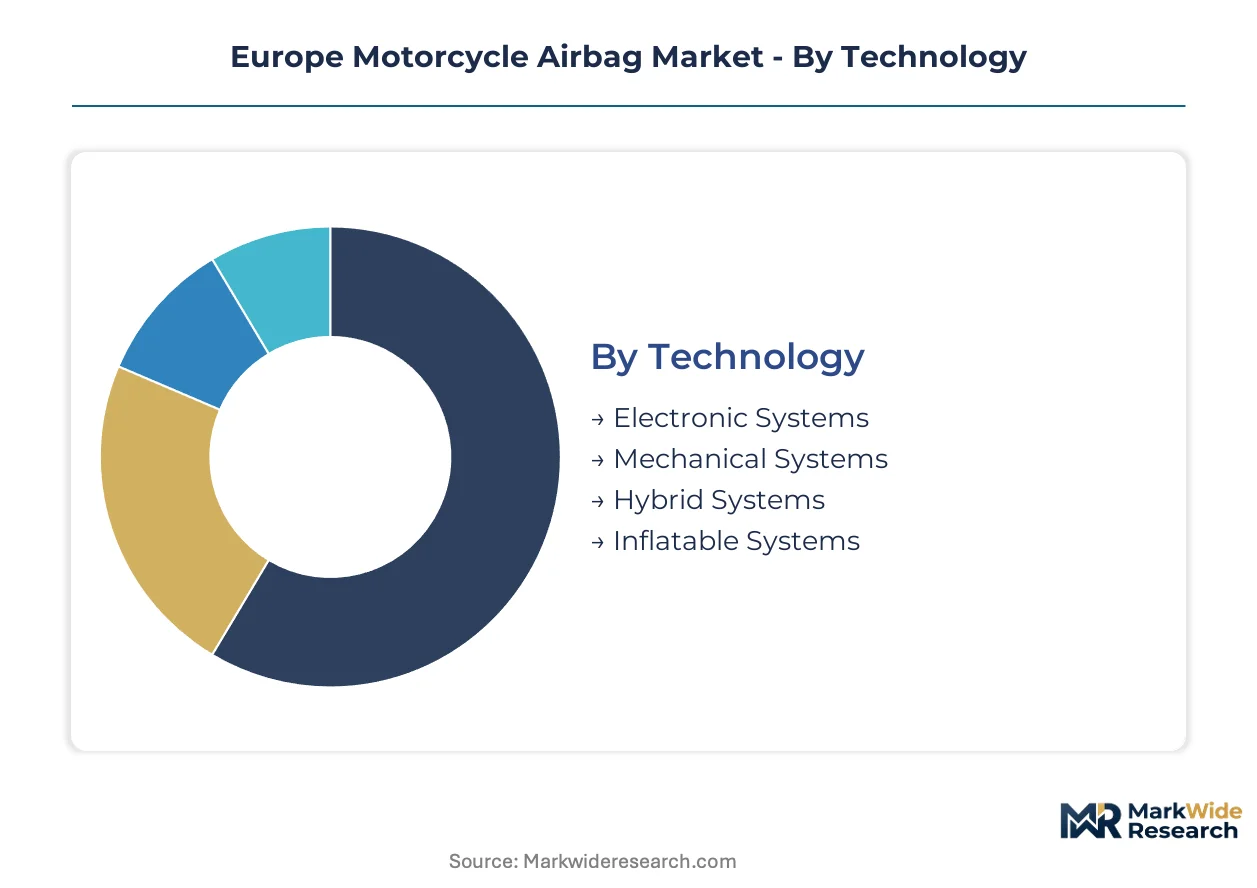
Segmentation in the Europe motorcycle airbag market reveals distinct channel pathways. Electronic systems flow through specialty motorsport retailers and direct-to-rider digital platforms, while mechanical tether products dominate mass-market touring outlets across Alpine corridors.
Technology:
Channel mix varies sharply by technology tier. Electronic systems command premium dealership networks and track-day event partnerships, while mechanical alternatives distribute through touring club aggregators and general motorcycle accessory retailers.
- Electronic Systems:Gyroscopic and accelerometer-based trigger logic deploys protective bladders within 25-80 milliseconds. Demand concentrates among professional racing teams in Italy and Germany, where MotoGP-derived algorithms legitimize premium positioning through track-day validation.
- Mechanical Systems:Tether-activated vest systems rely on physical cable pull mechanisms without electronic components. Touring riders across Swiss, Austrian, and Italian Alpine passes favor these for simplicity and lower replacement costs after deployment.
- Hybrid Systems:Combine electronic pre-arming with mechanical backup triggers for redundancy in extreme weather conditions.
- Inflatable Systems:Standalone bladder configurations without integrated garments, targeting aftermarket retrofit applications.
Electronic systems dominate installed base. Hybrid systems are where expansion concentrates as riders seek redundancy without full algorithmic complexity.
Product Type:
Cost tier stratification separates professional racing configurations from commuter-accessible alternatives. Full suits carry development costs that only professional racers and wealthy track-day enthusiasts absorb, while vests penetrate price-sensitive touring segments.
- Vest:Tether-activated or electronic torso protection worn over standard riding gear. Commuters in France and Germany favor these for workplace compatibility and lower entry pricing.
- Jacket:Integrated airbag bladders within motorcycle-specific outer shells. The largest volume category serves recreational riders across Mediterranean touring corridors seeking all-weather protection.
- Pants:Lower-body deployment systems protecting hips and coccyx, primarily adopted by off-road and adventure touring specialists.
- Full Suit:One-piece racing configurations with neck, torso, and limb stabilization. Professional racers in MotoGP and World Superbike championships drive specification standards that filter into consumer-grade systems.
Jackets capture broadest rider penetration. Full suits concentrate margin expansion as electronic deployment algorithms migrate from professional racing to wealthy amateur track-day participants.
Deployment:
Application context dictates sensor calibration and deployment thresholds. Racing systems prioritize lean-angle tolerance and high-speed trigger sensitivity, while touring configurations emphasize low-speed urban protection and false-positive avoidance.
- On-Road:Urban and highway configurations optimized for collision with vehicles or stationary objects. Safety enthusiasts in Germany and France drive replacement demand as CE certification cycles refresh product generations.
- Off-Road:Adventure and enduro systems with enhanced dust and moisture sealing for trail environments.
- Racing:Track-specific systems with predictive algorithms triggering before ground contact. Italian and German racing teams validate these under extreme lean angles and high-speed scenarios.
- Touring:Long-distance configurations balancing protection weight with all-day comfort across Alpine and Mediterranean corridors.
On-road systems dominate unit volume. Racing applications are climbing the fastest as track-day event participation expands across Northern Italy and Southern Germany.
End User:
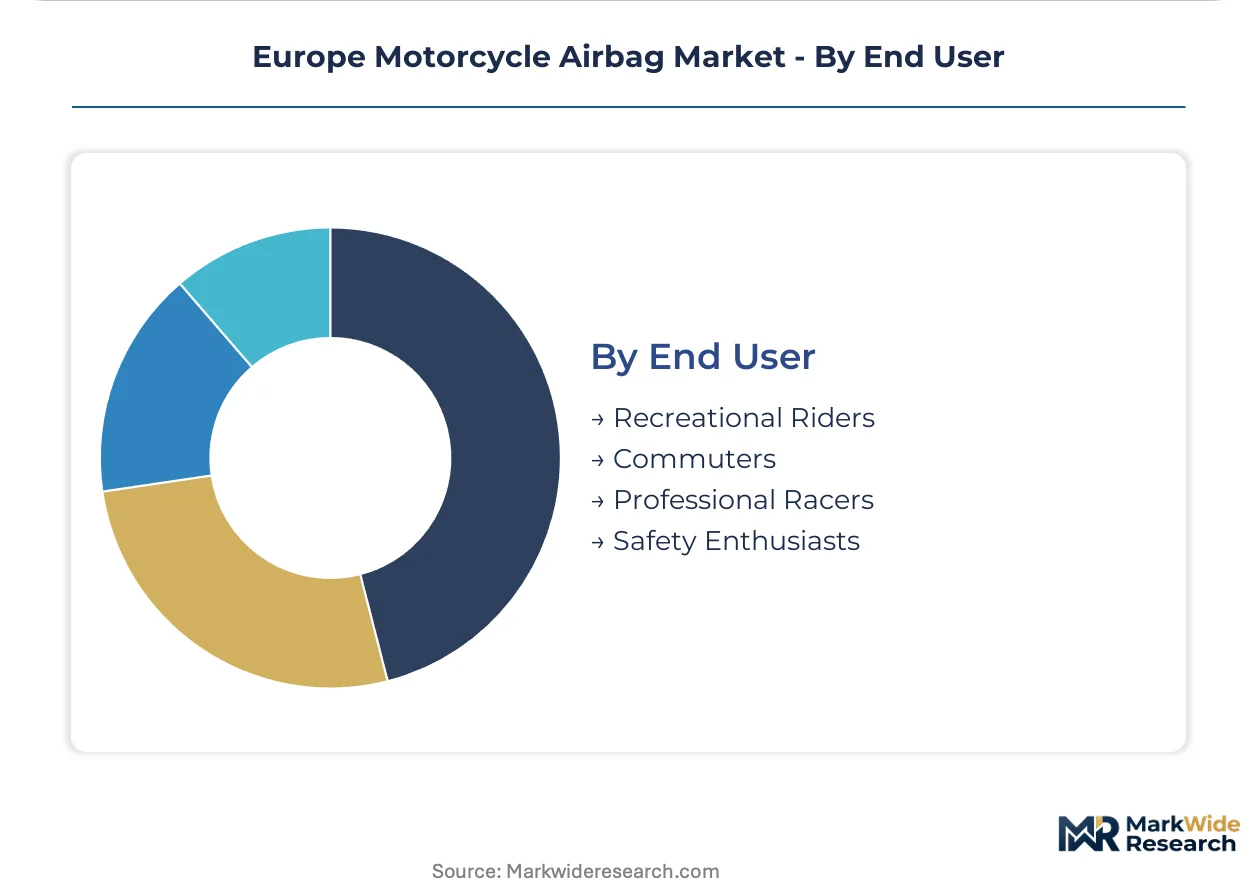
Customer type determines purchasing channel and replacement frequency. Professional racers procure through team sponsorship arrangements with annual refresh cycles, while recreational riders buy through retail with multi-year replacement intervals.
- Recreational Riders:Weekend and seasonal motorcyclists seeking protection without professional racing budgets. Club membership schemes in Alpine markets aggregate purchasing power for mid-tier electronic systems.
- Commuters:Daily urban riders prioritizing garment compatibility with workplace attire and rapid donning sequences.
- Professional Racers:Contracted athletes with manufacturer-sponsored equipment supplying the validation data that filters into consumer-grade algorithms.
- Safety Enthusiasts:Early adopters of predictive deployment technologies, often overlapping with track-day participants and touring club leadership.
Recreational riders represent the broadest installed base. Safety enthusiasts are gaining share fastest as predictive algorithms and group procurement schemes lower effective entry pricing for electronic systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Brenner Base Tunnel and Alpine rail corridors underpin Central Europe's dominance in high-performance motorcycle equipment distribution, connecting Italian manufacturing clusters with German and Austrian retail networks.
Germany
The KBA enforces national type-approval protocols extending beyond baseline CE marking, creating compliance barriers for non-EU suppliers. Track-day participation concentrates in Bavaria and Baden-Württemberg, where Nürburgring and Hockenheimring circuits drive replacement demand for electronic deployment systems. Stuttgart's automotive engineering ecosystem supplies embedded software talent for sensor fusion development.
Italy
MotoGP validation programs at Mugello and Misano World Circuits filter electronic deployment algorithms into consumer-grade systems. The ANSM coordinates with EU notified bodies on machine-learning trigger documentation. Manufacturing clusters in Veneto and Emilia-Romagna integrate Dainese and Alpinestars production with regional textile suppliers.
France
ANSM oversight of high-risk AI classification under the EU AI Act compresses product development timelines for algorithmic crash-prediction modules. Commuter demand concentrates in Île-de-France, where workplace-compatible vest systems penetrate price-sensitive urban segments. The Lyon-Grenoble corridor anchors testing laboratory capacity for CE conformity assessment.
Switzerland
Alpine touring traffic across Gotthard and San Bernardino passes sustains replacement cycles for protective equipment. Swissmedic maintains pharmaceutical-grade standards for inflation gas canister safety, exceeding baseline EU requirements. Zurich and Geneva retail networks serve as premium distribution gateways for Northern Italian manufacturers.
Austria
Grossglockner High Alpine Road and Arlberg Pass generate concentrated high-speed motorcycle traffic with elevated safety equipment turnover. National transport safety programs subsidize protective gear procurement for licensed touring operators. Innsbruck's proximity to Bavarian manufacturing clusters enables rapid inventory replenishment for Eastern Alpine retail channels.
Europe Motorcycle Airbag Market Competitive Landscape
Listed leaders compete with private specialists across certification velocity and algorithmic deployment capabilities. The vendor base stratifies into three tiers: integrated garment-airbag manufacturers, standalone electronic system suppliers, and mechanical tether specialists. Archetypes include racing-derived technology licensors, CE certification service providers, and touring-focused simplicity optimizers. Dominant competitive moves center on third-party testing partnerships and direct-to-rider digital channel development.
Among Italian-anchored racing technology providers, Dainese and Alpinestars exemplify the premium electronic deployment tier, while Helite occupies a position within mechanical simplicity archetypes. These three entities represent contrasting strategic postures: in-house laboratory networks versus MotoGP-derived validation versus tether-activated cost positioning.
| Leading Market Players |
|---|
| REV'IT! |
| Held GmbH |
| Dainese |
| Rukka |
| Furygan |
| Alpinestars |
| Spidi Sport |
| IXS |
| Helite |
| Others |
Value Network & Pricing Analysis
Fifteen-month CE certification timelines compress inventory turns for electronic airbag manufacturers, concentrating pricing power with Dainese and Alpinestars while forcing smaller suppliers toward third-party laboratory partnerships that erode margin capture across the value chain.
Pricing Analysis
Volume-discount tiering structures separate MotoGP-validated electronic systems from tether-activated mechanical alternatives, with certification grade and algorithmic complexity driving price differentiation. Premium electronic jackets command substantial markups in German and Italian track-day channels, while mechanical vest systems face pricing pressure from Eastern European touring club aggregators. Commuter segments in France exhibit highest price sensitivity, whereas professional racing teams absorb premium positioning with minimal negotiation leverage.
Supply Chain Analysis
Inbound logistics costs from German and French industrial gas distributors expose inflation canister procurement to energy-input volatility, compressing margins for manufacturers without captive helium and argon supply arrangements. Manufacturing clusters concentrate in Veneto and Emilia-Romagna for garment integration, Stuttgart for embedded software development, and Lyon-Grenoble for testing laboratory capacity. Single-source vulnerability runs through German KBA and French ANSM type-approval protocols that extend beyond baseline CE marking. Distribution feeds from specialty motorsport retailers in Alpine corridors and direct-to-rider digital platforms for track-day event procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's pending high-risk classification for algorithmic crash-prediction systems creates a regulatory inflection that will recalibrate competitive positioning across electronic deployment tiers.
For Market Incumbents: Compound certification velocity advantages by deepening in-house laboratory networks before the EU AI Act triggers additional conformity assessment burdens for machine-learning trigger logic. Acquire tier-two inflator specialists to resolve garment-airbag integration complexity that currently forces dependency on external pyrotechnic expertise. Lock track-day event partnerships to defend channel control against emerging direct-to-rider digital platforms. For New Entrants and Emerging Players: CE certification fast-tracks through notified body partnerships in the Lyon-Grenoble corridor offer entry pathways for mid-tier electronic systems targeting underpenetrated Polish and Czech touring markets. Mechanical tether substitutes retain viability in price-sensitive commuter segments where algorithmic deployment remains cost-prohibitive. Motorcycle club subscription models bypass traditional retail markup structures and aggregate rider purchasing power for collective procurement schemes. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive ADAS programs seeking to redeploy embedded software talent toward motorcycle-specific sensor fusion applications. Long-term viability hinges on regulatory compliance service revenue streams as the EU AI Act reshapes conformity assessment economics. Monitor French and German technical documentation requirements for machine-learning-based trigger logic as the inflection indicator for compliance-service market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Certification Fast-Track Partnership | Accelerates market access through Lyon-Grenoble laboratory capacity before EU AI Act enforcement. |
| Direct-to-Rider Digital Platform Launch | Bypasses traditional retail markup through track-day event and motorcycle club subscription aggregation. |
| In-House Inflator Specialist Acquisition | Resolves garment-airbag integration complexity that currently forces tier-two dependency. |
| Eastern European Touring Market Entry | Captures first-mover positioning in Poland and Czech Republic before incumbent channel saturation. |
| EU AI Act Compliance Service Development | Creates recurring revenue streams from high-risk AI conformity assessment documentation requirements. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with motorcycle OEM platform engineers, Tier 1 supplier procurement leads, track-day event organizers, and CE certification laboratory directors; alongside secondary validation through KBA type-approval filings, ANSM regulatory bulletins, EU General Safety Regulation implementation guidance, and Alpine touring club procurement records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the European motorcycle equipment value chain.
Across the projection horizon, the analytical framework modeled technology tier, product type, deployment context, and end-user archetype as core segmentation dimensions. CAGRs derived from historical replacement cycle analysis in Alpine and Mediterranean corridors, calibrated against professional racing homologation timelines and regulatory mandate implementation schedules. Forecast inputs incorporated inflation gas procurement cost trajectories and embedded software talent scarcity indices.
Underlying assumptions cover stable CE certification timeline continuity and EU AI Act risk-classification finalization, with deviation risk concentrated in helium and argon supply disruptions and machine-learning trigger documentation requirement expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Drivetrain Market
Bikes and Motorcycles
Hydrobike Market
Bikes and Motorcycles
Two-Wheeler Lighting Market
Bikes and Motorcycles
Australia E- Bike Market
Bikes and Motorcycles
United States E-Bike Market
Bikes and Motorcycles
Smart Electric Bikes Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
Bike Computer Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
India Two Wheeler Market
Bikes and Motorcycles
Bicycle Trip Market
Bikes and Motorcycles
Motorcycle Seat Market
Bikes and Motorcycles
UAE Electric Bike Market
Bikes and Motorcycles
Maxi Scooter Market
Bikes and Motorcycles
Motorcycle Exhaust Mounting Brackets Market