
 Motorcycle Airbag Market | 2026-2036
Motorcycle Airbag Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Airbag Market Outlook
Sensor fusion and algorithm-driven crash detection is reshaping motorcycle airbag engineering from mechanical tether systems toward predictive electronic architectures. Alpinestars leverages proprietary inertial measurement platforms to differentiate its wearable systems across premium racing channels. Dainese anchors European manufacturing scale through vertically integrated textile and electronics operations in Italy. Helite sustains mechanical activation expertise while navigating the transition toward hybrid electronic-mechanical trigger designs.
Motorcycle airbags are deployable restraint systems integrated into rider garments or vehicle structures, utilizing gas generators or compressed gas canisters to inflate protective chambers within milliseconds of crash detection, typically achieving full deployment in under 100 milliseconds to cushion impact zones including the thorax, neck, and spine. The primary commercial purpose centers on reducing fatal and serious injury outcomes in motorcycle collisions, where riders lack the enclosed protection of passenger vehicle occupant compartments. Wearable airbags and jacket-mounted configurations command the dominant share of current revenue as consumer familiarity and distribution through specialty stores and dealerships concentrates volume in established motorcycling markets. Electronic activation technology captures the fastest growth trajectory as semiconductor cost curves and battery energy density improvements enable standalone systems without tether dependencies, while mechanical activation retains cost-sensitive segments and regulatory acceptance in jurisdictions with slower electronics certification pathways.
The EU's CE marking requirements under the PPE Regulation and the F-Gas Regulation governing gas propellants establish mandatory compliance thresholds for market access across European member states. Japan's METI administers JIS standards that influence airbag garment certification across Asian export markets aligned with Japanese technical benchmarks. The US DOT and NHTSA maintain voluntary compliance frameworks rather than mandatory airbag standards, creating a bifurcated regulatory landscape where European certification often serves as the de facto global quality signal. Stakeholders must monitor whether emerging economies adopt European-style mandatory certification or retain permissive market entry regimes that could fragment product development roadmaps.
Market Dynamics
Sensor fusion and algorithm-driven crash detection is compressing deployment latency from tether-dependent mechanical systems to predictive electronic architectures, forcing incumbent manufacturers to reengineer activation platforms while defending installed base positions.
Growth Catalysts
- EU PPE Directive mandates:CE marking requirements under the updated personal protective equipment regulation create compulsory replacement cycles for non-compliant garments across all member states.
- Track-day organizers:Professional racing teams and amateur circuit participants drive volume for premium electronic-activation systems with sub-100-millisecond deployment specifications.
- German KBA certification:Stringent federal motor transport authority protocols establish quality benchmarks that radiate into adjacent European markets seeking regulatory equivalence.
Market Restraints
- Gas propellant costs:The EU F-Gas Regulation restricts hydrofluorocarbon-based inflation agents, forcing reformulation of gas generator chemistry and raising input material expenses.
- Electronics supply concentration:Inertial measurement unit fabrication clusters in Taiwan and South Korea expose airbag system assemblers to single-source dependencies for MEMS accelerometers.
- Mechanical tether legacy:Cost-sensitive commuter segments in Southern Europe retain preference for proven mechanical activation, slowing full-category transition to electronic platforms.
Strategic Opportunities
- India two-wheeler fleet:The country's central motor vehicle rules lack mandatory airbag standards, creating first-mover positioning for affordable mechanical-activation garments targeting 200 million registered motorcycles.
- Urban delivery couriers:Gig-economy last-mile logistics operators represent an untapped end-use vertical with high daily exposure and employer-funded equipment procurement models.
- ISO 13232 alignment:Motorcycle accident research data standards enable predictive algorithm training on regional crash kinematics, differentiating region-tuned detection sensitivity.
Industry Challenges
- Firmware validation timelines:Electronic-activation systems require extensive real-world and simulated crash testing, extending product development cycles before CE marking approval.
- Cross-border service networks:Compressed gas canister replacement and system reset capabilities demand localized technical infrastructure that fragmented distribution cannot yet support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Airbag Market |
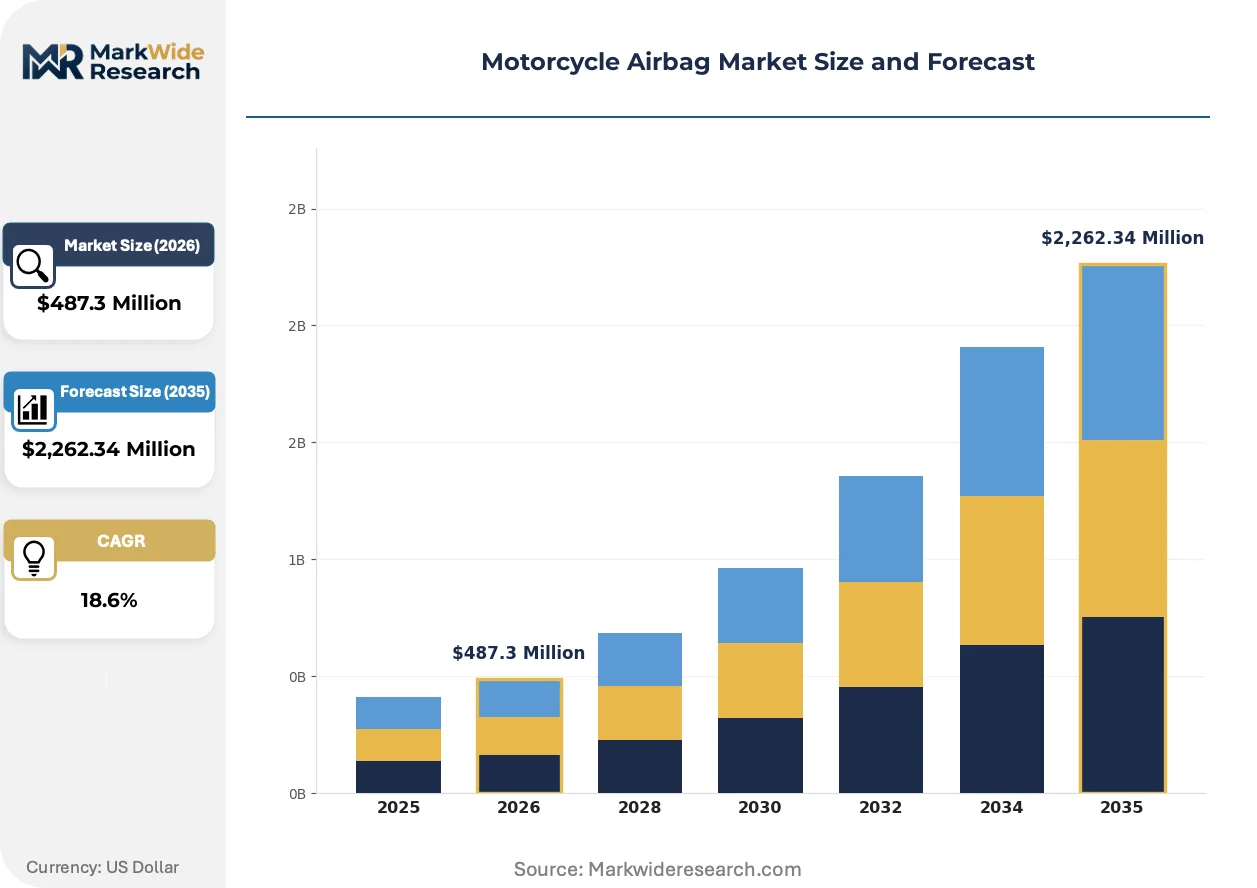
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Airbags, Jacket-mounted Airbags, Vest-mounted Airbags, Bike-mounted Airbags Technology: Mechanical Activation, Electronic Activation, Hybrid Systems, Gas Generator Systems End User: Casual Riders, Professional Racers, Tourists, Delivery Riders Distribution Channel: Online Retail, Specialty Stores, Dealerships, Direct Sales |
| Companies Covered | Autoliv, Honda Motor, Alpinestars, Dainese, Yamaha Motor, Helite, Klim, RST, Hit-Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Airbag Market Strategic Shifts
Crash detection engineering is bifurcating into predictive electronic architectures and refined mechanical hybrids, with algorithmic sophistication determining competitive positioning across premium and mass-market tiers.
Multi-axis inertial measurement platforms is digitizing rider kinematic analysis, enabling pre-impact deployment before physical contact occurs. Professional racing teams and track-day participants adopt these systems fastest, compressing the performance gap between tethered and standalone electronic configurations. This digitization is collapsing the historical latency advantage of mechanical systems.
The EU F-Gas Regulation constrains hydrofluorocarbon propellants in gas generators, forcing manufacturers toward compressed inert gas alternatives or chemical inflation systems. This chemical reformulation raises bill-of-material costs while requiring recertification under CE marking protocols. Racing garment suppliers absorb these adjustments first, given their price elasticity and shorter product lifecycles.
Direct-to-rider digital channels are displacing traditional specialty retail for initial system purchases and replacement canister fulfillment. Urban commuter segments in Germany and France lead this migration, seeking subscription-style maintenance bundles that bundle deployment insurance with hardware. This channel compression pressures dealership margins while rewarding brands with captive e-commerce infrastructure.
Motorcycle Airbag Market Segmentation
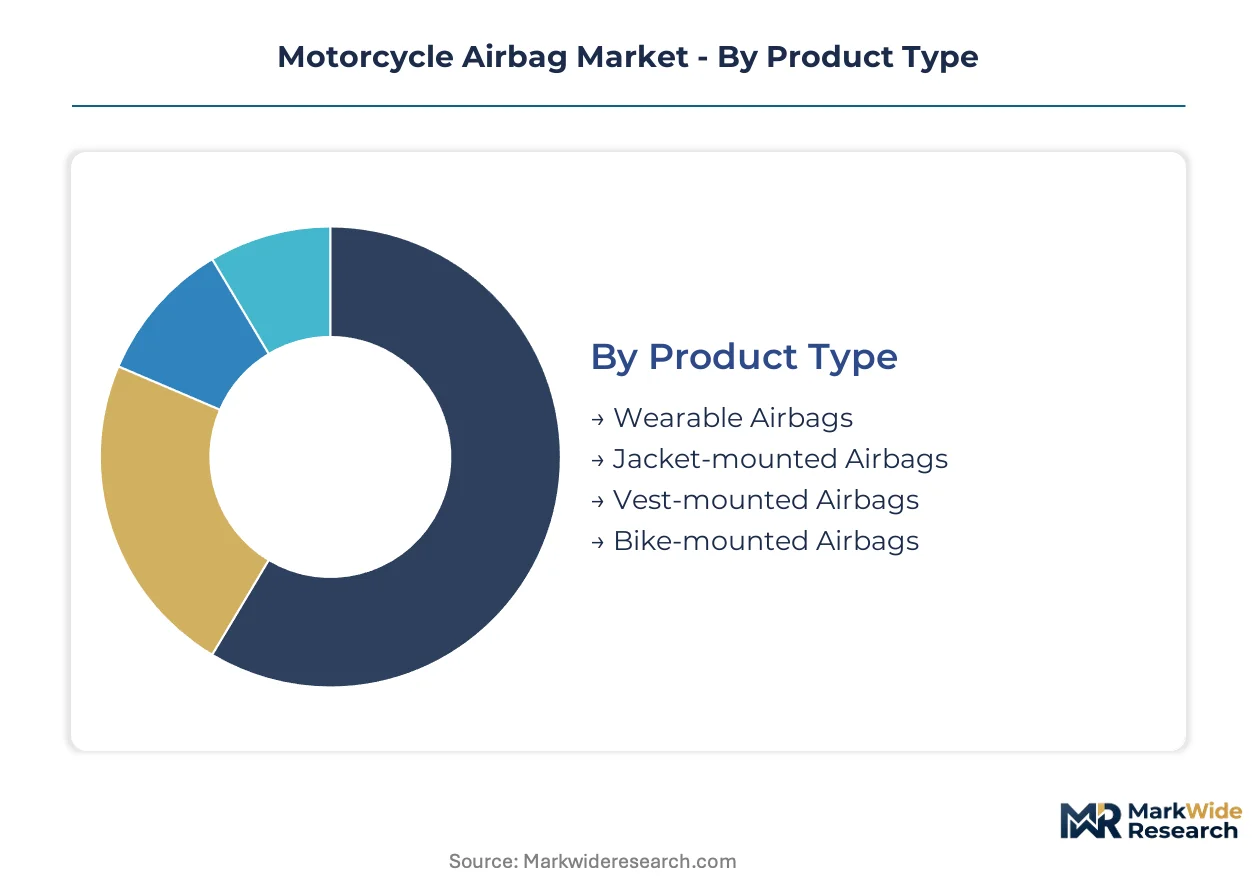
Segmentation in motorcycle airbags reveals divergent service intensity requirements across product configurations. Wearable systems demand recurring canister replacement and firmware updates, while bike-mounted units require integration with vehicle diagnostics. Understanding these maintenance profiles shapes go-to-market economics and channel selection.
Product Type:
After-sales service intensity varies dramatically across mounting configurations, with wearable garments requiring garment-specific refurbishment protocols.
- Wearable Airbags:Integrated into rider jackets or standalone vests, these systems combine textile durability with electronic sensor modules. German KBA certification protocols drive replacement part standardization across European service networks. By volume, wearable configurations lead. By growth pace, vest-mounted variants are ahead.
- Jacket-mounted Airbags:Factory-integrated into protective outerwear, these units embed gas canisters and trigger mechanisms within seam-sealed compartments. Professional racing teams in Italy and France specify these for track-day compliance where CE marking under PPE Regulation is mandatory.
- Vest-mounted Airbags:Standalone protective layers worn over standard riding gear, offering modular upgrade paths for cost-sensitive commuters. India's central motor vehicle rules absence of mandatory standards creates positioning flexibility for affordable mechanical-activation models.
- Bike-mounted Airbags:Vehicle-integrated systems deployed from handlebar or fuel tank housings, requiring OEM partnership channels and dealership technical training. These configurations carry lower garment refurbishment intensity but higher initial installation complexity.
By installed base, wearable systems dominate. By margin contribution, jacket-integrated units lead.
Technology:
Cost tier stratification separates premium electronic architectures from mechanical systems serving price-sensitive segments.
- Mechanical Activation:Tether-dependent systems triggering inflation via physical displacement, proven in commuter applications across Southern Europe. These retain regulatory acceptance in jurisdictions with slower electronics certification pathways.
- Electronic Activation:Algorithm-driven crash detection using multi-axis inertial measurement platforms, achieving sub-100-millisecond deployment. Japanese METI-administered JIS standards influence certification across Asian export markets aligned with Japanese technical benchmarks.
- Hybrid Systems:Dual-trigger architectures combining electronic pre-impact detection with mechanical backup activation, bridging reliability and predictive performance. These configurations expand most quickly as manufacturers navigate transition risks.
- Gas Generator Systems:Chemical inflation mechanisms utilizing constrained propellant formulations under EU F-Gas Regulation, forcing reformulation toward compressed inert gas alternatives. Racing garment suppliers absorb these adjustments first given shorter product lifecycles.
By revenue concentration, electronic activation leads. By adoption velocity, hybrid configurations are climbing the fastest.
End User:
Application context determines performance specifications, with daily exposure hours directly correlating to equipment procurement models.
- Casual Riders:Weekend and recreational motorcyclists prioritizing cost accessibility over sub-100-millisecond deployment specifications. These users concentrate in Germany and France where direct-to-rider digital channels displace traditional specialty retail.
- Professional Racers:Track-day participants and competitive riders demanding predictive electronic architectures with algorithmic crash detection. This segment specifies premium systems with ISO 13232-aligned algorithm training on regional crash kinematics.
- Tourists:Rental fleet users and international travelers requiring standardized fit and multilingual instruction protocols. These users favor mechanical activation for simplicity and reduced maintenance dependencies during multi-country itineraries.
- Delivery Riders:Gig-economy last-mile logistics operators with high daily exposure and employer-funded equipment procurement. Urban delivery couriers in dense metropolitan zones represent an untapped vertical with subscription-style maintenance bundle potential.
By unit volume, casual riders dominate. By value per user, professional racers lead.
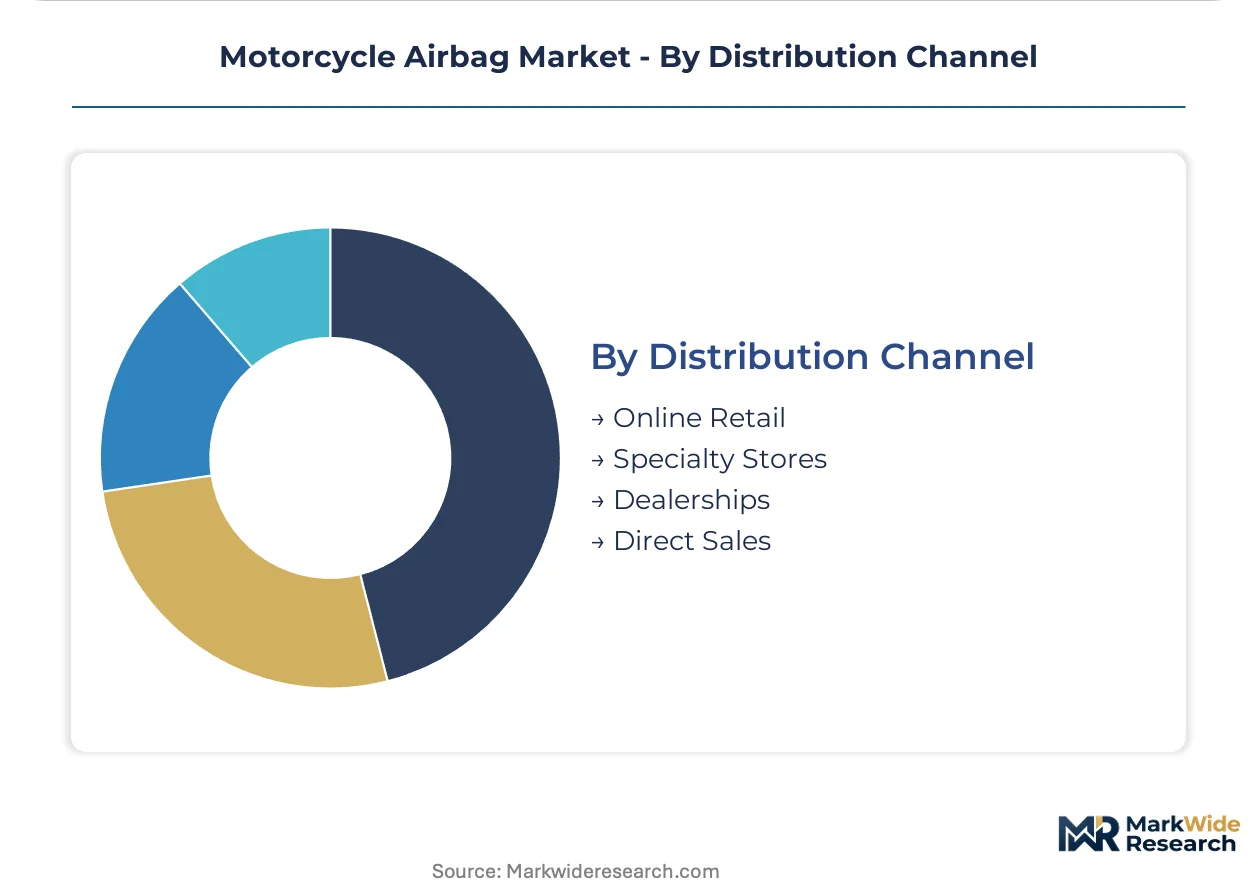
Distribution Channel:
Customer type stratification separates initial purchase behavior from recurring service requirements across digital and physical touchpoints.
- Online Retail:Direct-to-rider platforms capturing urban commuter segments seeking subscription-style maintenance bundles that combine deployment insurance with hardware replacement. This channel pressures dealership margins while rewarding brands with captive e-commerce infrastructure.
- Specialty Stores:Independent motorcycle equipment retailers providing fitting services and technical consultation, concentrating volume in established motorcycling markets with CE marking familiarity.
- Dealerships:OEM-aligned channels integrating airbag sales with vehicle purchase and service appointments, requiring localized technical infrastructure for compressed gas canister replacement.
- Direct Sales:Manufacturer-owned channels serving professional racing teams and fleet operators with customized volume agreements and dedicated technical support.
By transaction volume, specialty stores lead. By margin expansion, online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export certification flows from European testing laboratories dominate trade patterns, with CE marking serving as the de facto quality passport into adjacent markets lacking indigenous airbag standards. Import demand concentrates in jurisdictions where motorcycle fleet expansion outpaces domestic protective equipment manufacturing.
Germany
The KBA enforces federal motor transport authority protocols that radiate into neighboring markets seeking regulatory equivalence. CE marking under the EU PPE Directive mandates compulsory replacement cycles for non-compliant garments. Manufacturing clusters in Bavaria and Baden-Württemberg host vertically integrated textile-electronics operations serving premium racing channels.
France
Track-day organizers and professional racing teams drive volume for sub-100-millisecond electronic activation systems. The F-Gas Regulation restricts hydrofluorocarbon propellants, forcing reformulation of gas generator chemistry. Industrial concentration around Lyon and Grenoble supports algorithm-driven crash detection engineering for predictive architectures.
Italy
Dainese anchors European manufacturing scale through captive textile and electronics operations in the Veneto region. Italy's motorcycling culture sustains specialty retail channels that integrate fitting services with technical consultation. ANSM oversight of medical-grade protective equipment influences garment certification pathways for high-impact protection systems.
Japan
METI-administered JIS standards influence airbag garment certification across Asian export markets aligned with Japanese technical benchmarks. Domestic motorcycle OEMs integrate bike-mounted systems through dealership technical training networks. Manufacturing clusters in the Chubu region around Nagoya supply MEMS accelerometer components for inertial measurement platforms.
India
The central motor vehicle rules lack mandatory airbag standards, creating first-mover positioning for affordable mechanical-activation garments targeting 200 million registered motorcycles. BIS certification pathways remain permissive compared to European equivalents. Industrial concentration in Maharashtra and Tamil Nadu supports cost-sensitive commuter segment production.
Motorcycle Airbag Market Competitive Environment
On the supply side, the industry is consolidating around three strategic archetypes: European heritage protective equipment specialists with captive manufacturing, Japanese automotive OEMs leveraging vehicle integration capabilities, and emerging Asian fabricators serving cost-sensitive mechanical activation segments. Competitive positioning depends on algorithmic crash detection sophistication and CE marking certification speed. Dominant moves include backward integration into MEMS sensor supply chains and strategic partnerships with track-day organizers for fleet deployment trials.
Within the European heritage tier, Dainese and Alpinestars exemplify vertically integrated specialists combining textile engineering with proprietary inertial measurement platforms. Autoliv represents the automotive supplier archetype, occupying a position between motorcycle OEM system integration and aftermarket protective equipment channels. These three anchors demonstrate how geographic clustering around Italian and German regulatory expertise shapes competitive differentiation.
| Leading Market Players |
|---|
| Autoliv |
| Honda Motor |
| Alpinestars |
| Dainese |
| Yamaha Motor |
| Helite |
| Klim |
| RST |
| Hit-Air |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Taiwan and South Korea for MEMS accelerometer fabrication determines both pricing tier spreads and supply chain shape. The EU F-Gas Regulation's hydrofluorocarbon restrictions compress margins on gas generator chemistry while concentrating procurement leverage among vertically integrated European specialists.
Pricing Analysis
Current-generation electronic activation systems command three-to-fourfold premiums over prior-generation mechanical tether configurations. Pricing stratifies across premium, standard, and economy tiers based on deployment latency specifications and CE marking certification grade. Cost compression in mechanical-activation segments is intensifying because Indian and Southeast Asian fabricators are scaling production of simplified trigger mechanisms. Casual commuters in Southern Europe exhibit highest price sensitivity, while professional racing teams in Germany and Italy demonstrate lowest elasticity.
Supply Chain Analysis
Taiwan Semiconductor Manufacturing and South Korean MEMS foundries hold dominant capacity for inertial measurement unit components. Manufacturing clusters in Italy, Germany, and Japan draw from these upstream sources while maintaining captive textile finishing and garment assembly. Raw material dependencies span lithium-polymer battery cells, aramid fiber composites, and compressed inert gas canisters. Single-source vulnerability in semiconductor fabrication exposes airbag system assemblers to allocation risk during capacity constraints. Distribution runs through OEM dealership networks for bike-mounted configurations and direct-to-rider digital channels for wearable systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat. CE marking certification speed and KBA protocol compliance create switching costs that protect incumbent positions.
For Market Incumbents: Insulate algorithmic crash detection advantages through backward integration into MEMS sensor supply chains and accelerated firmware validation pipelines. Threat from emerging Asian mechanical-activation specialists in India demands defensive certification investments to maintain European market access. Priority lever rests on channel control through subscription-style maintenance bundles that lock in recurring revenue. For New Entrants and Emerging Players: Urban delivery courier fleets in dense metropolitan zones represent the most penetrable entry point for employer-funded procurement models. India's 200 million registered motorcycle fleet under permissive central motor vehicle rules offers white-space positioning for affordable mechanical-activation garments. Go-to-market angle should emphasize direct-to-rider digital channels with compressed gas canister replacement subscriptions. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors hybrid electronic-mechanical system specialists with proven CE marking pathways. Long-term viability across the projection horizon hinges on regulatory certification velocity rather than pure manufacturing scale. Acquisition target archetype includes Italian and German vertically integrated protective equipment specialists with captive textile-electronics operations. Signal to watch: JIS standard adoption rates across Asian export markets as inflection indicator for regional algorithm-tuning requirements.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | Compresses product development cycles before EU PPE Directive enforcement deadlines. |
| MEMS Supply Agreement | Secures inertial measurement unit allocation from Taiwan and South Korean foundries. |
| Track-Day Fleet Partnership | Generates real-world crash data for ISO 13232-aligned algorithm training. |
| Direct-to-Rider Platform Launch | Captures urban commuter segments seeking subscription maintenance bundles. |
| Hybrid System Development | Bridges reliability requirements of mechanical activation with predictive electronic performance. |
Study Parameters
A spread of perspectives from airbag system engineers, KBA certification specialists, track-day organizers, and motorcycle dealership operators converged on the working assumptions. Primary interviews combined with secondary validation from EU PPE Regulation filings, METI JIS standard documentation, and German federal motor transport authority protocols. Customs records from Italian and Japanese textile-electronics trade flows supplemented bottom-up and top-down triangulation.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled include mounting configuration, activation technology, end-user application context, and distribution channel structure. CAGRs derived from regression analysis against motorcycle fleet expansion rates and regulatory adoption curves. Forecast inputs incorporated CE marking approval timelines and F-Gas Regulation compliance cost trajectories.
Practitioners should monitor MEMS foundry capacity allocation, JIS standard harmonization progress, and Indian central motor vehicle rule amendments for early signals. Forecasts reflect assumptions about regulatory enforcement consistency and semiconductor supply normalization. Quarterly review of KBA certification queue lengths and track-day organizer procurement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Rider Assistance System Market
Bikes and Motorcycles
E-Cargo Bike Market
Bikes and Motorcycles
Two Wheeler Kick Lever Market
Bikes and Motorcycles
North America Bicycle Market
Bikes and Motorcycles
Asia-Pacific Ride on Bikes Market
Bikes and Motorcycles
Switzerland E-Bike Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Global Motorcycle Airbag System Market
Bikes and Motorcycles
Europe Bicycle Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
Bicycle Trip Market
Bikes and Motorcycles
GPS Bike Computers Market
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
Hydrobike Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market