
 Motorcycle Tubeless Tire Market | 2026-2036
Motorcycle Tubeless Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Tubeless Tire Market Insights
Adventure touring and dual-sport motorcycle adoption is restructuring replacement tire demand, shifting volume toward knobby-tread and all-terrain tubeless variants that handle unpaved surfaces. Bridgestone leverages its motorsport heritage to dominate high-performance sport bike fitments in Japan and Southeast Asia. Michelin sustains premium positioning through advanced silica compound R&D that extends wet-grip longevity. Pirelli competes aggressively in the supermoto and off-road segments with dedicated tread patterns for European and Latin American terrain.
A motorcycle tubeless tire is a pneumatic tire constructed with an airtight inner liner of halobutyl rubber laminated to the carcass, eliminating the need for an inner tube while maintaining inflation pressure through direct rim sealing; its primary purpose is to reduce sudden deflation risks and enable lower rolling resistance for fuel efficiency. Front tires occupy the highest replacement frequency due to steering load concentration and faster wear rates on commuter motorcycles. Off-road tires represent the fastest-growing product type as trail-accessible motorcycle registrations climb in North America and Australia. Synthetic fiber reinforcement in carcass plies is displacing traditional cotton and rayon in mid-tier product lines, concentrating margin pools with suppliers mastering aramid and nylon 6.6 integration.
EPA treadwear and fuel economy labeling requirements in the United States shape consumer comparison behavior and OEM fitment decisions for imported motorcycles. ECHA REACH restrictions on polycyclic aromatic hydrocarbons in tire oils force compound reformulation across European supply chains, raising compliance costs for Asian exporters. India's BIS certification mandates for two-wheeler tires under AIS standards create a technical barrier that favors domestic manufacturers with established testing infrastructure. Stakeholders must monitor how tightening carbon-border adjustment mechanisms and regional labeling schemes reshape sourcing economics for multi-country tire portfolios.
Market Dynamics
Adventure touring and dual-sport motorcycle adoption is restructuring fleet replacement cycles across emerging markets, compressing traditional 18-24 month intervals toward 12-15 month patterns as riders subject tires to mixed-terrain abrasion.
Growth Catalysts
- Highway infrastructure expansion:India's National Highways Authority is extending four-lane corridors into tier-2 cities, accelerating tubeless fitment rates as average speeds climb beyond inner tube safety thresholds.
- ECHA REACH compliance deadlines:Polycyclic aromatic hydrocarbon restrictions in tire oils are forcing compound reformulation, creating first-mover advantage for manufacturers with pre-certified halobutyl liner stocks.
- Silica compound R&D:Advanced wet-grip formulations are extending replacement intervals in monsoon climates, redirecting consumer preference toward premium tread architectures.
Market Restraints
- Aramid fiber supply concentration:Synthetic reinforcement supply chains cluster in East Asian chemical parks, exposing mid-tier manufacturers to input cost volatility when nylon 6.6 spot markets tighten.
- Rim compatibility limitations:Tubeless sealing requires cast or forged alloy wheel construction; spoked rims common in sub-150cc commuter segments block retrofit adoption without expensive rim replacement.
- BIS certification timelines:India's Automotive Research Association testing queues for AIS standard compliance create 4-6 month product launch delays for new market entrants.
Strategic Opportunities
- Underpenetrated Latin American trail markets:Brazil's expanding rural road network and Argentina's Patagonia tourism corridor present white space for all-terrain tubeless variants with reinforced sidewall carcasses.
- Direct-to-workshop distribution:Bypassing traditional multi-tier wholesale channels through fleet operator procurement platforms captures margin and captures replacement-cycle data.
- EU Green Deal carbon-border adjustments:Early alignment with embedded carbon tracking requirements positions exporters for preferential tariff treatment as CBAM phases in across tire categories.
Industry Challenges
- Compound formulation talent scarcity:Halobutyl liner lamination expertise concentrates among aging technical workforces in Japan and Germany, constraining knowledge transfer to emerging manufacturing hubs.
- Multi-certification complexity:Simultaneous EPA treadwear labeling, ECHA REACH substance restrictions, and BIS AIS testing create parallel compliance cost burdens without harmonized mutual recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Tubeless Tire Market |
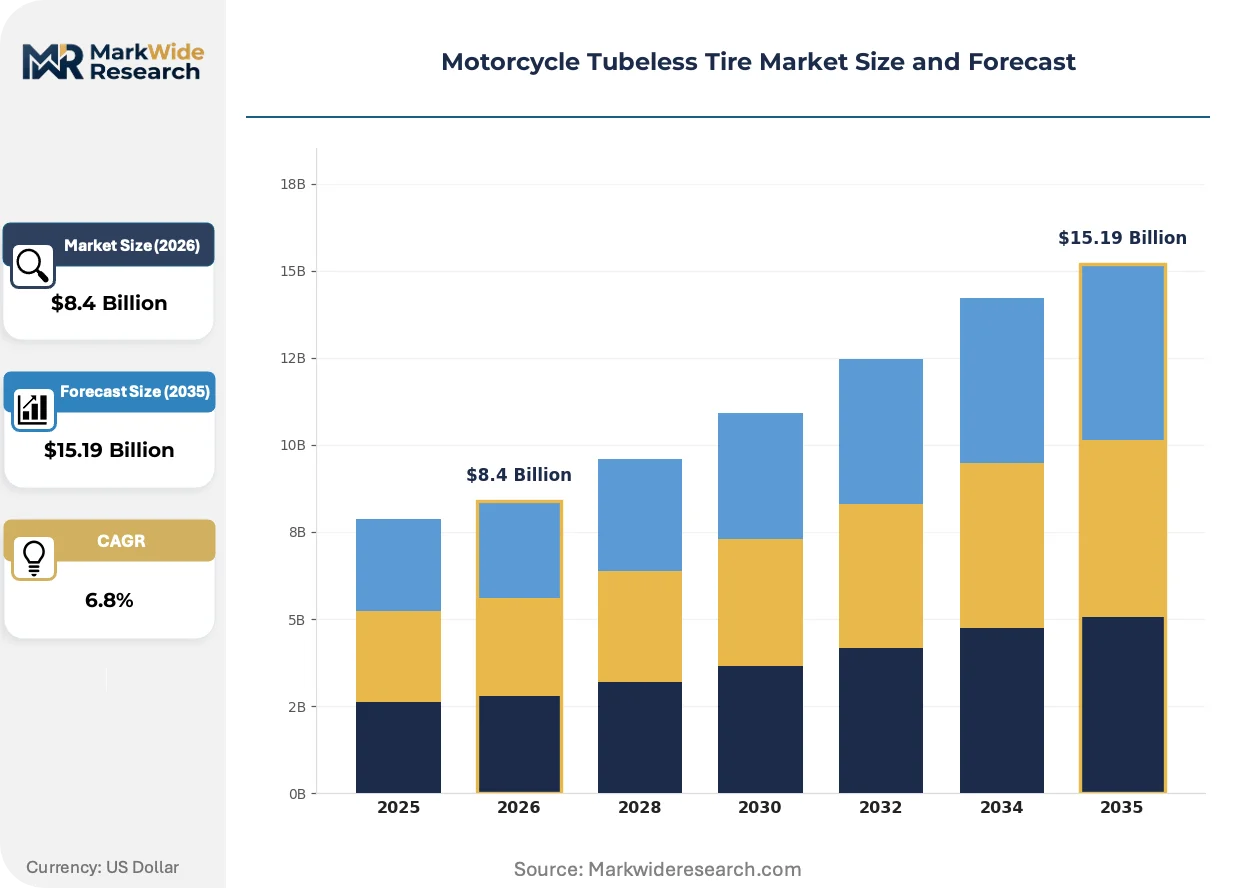
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Tires, Rear Tires, All-Season Tires, Off-Road Tires Material: Rubber, Synthetic Fiber, Steel, Fabric Vehicle Type: Cruiser Bikes, Sport Bikes, Touring Bikes, Dirt Bikes Brand: Dunlop, Michelin, Pirelli, Continental |
| Companies Covered | Bridgestone, Michelin, Pirelli, Continental, MRF, JK Tyre, TVS Srichakra, Goodyear, Kenda Tire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Tubeless Tire Market Trends and Innovations
Material science advances and regulatory stringency are converging to redefine tire architecture, with manufacturers racing to integrate sustainable inputs while maintaining performance thresholds established by motorsport heritage.
Synthetic aramid and nylon 6.6 fiber reinforcement is overtaking traditional cotton and rayon in carcass ply construction. OEM fitment specifications for 250cc-plus motorcycles now mandate synthetic-only architectures. This transition is compressing margin pools toward suppliers mastering high-tensile fiber integration and automated ply winding.
ECHA REACH restrictions on polycyclic aromatic hydrocarbons in tire oils force compound reformulation across European supply chains. Asian exporters face raised compliance costs for halobutyl liner certification. Premium sport-touring segments absorb these costs through pricing power; commuter tiers experience share erosion toward domestic European manufacturers.
Workshop-level procurement platforms are fragmenting traditional wholesale distribution. Fleet operators and ride-hail aggregators in India and Southeast Asia now contract directly with manufacturers for volume replacement programs. This channel compression is most visible in Bengaluru and Jakarta, where two-wheeler density exceeds 800 vehicles per kilometer of arterial road.
Motorcycle Tubeless Tire Market Segmentation
Motorcycle tubeless tire purchasing splits across performance requirements, vehicle duty cycles, and aftermarket loyalty patterns. Fleet operators prioritize replacement intervals and wet-grip certification; enthusiast buyers emphasize tread architecture and motorsport heritage alignment.
Product Type:
Replacement frequency and terrain exposure dictate product selection across commuter and leisure segments.
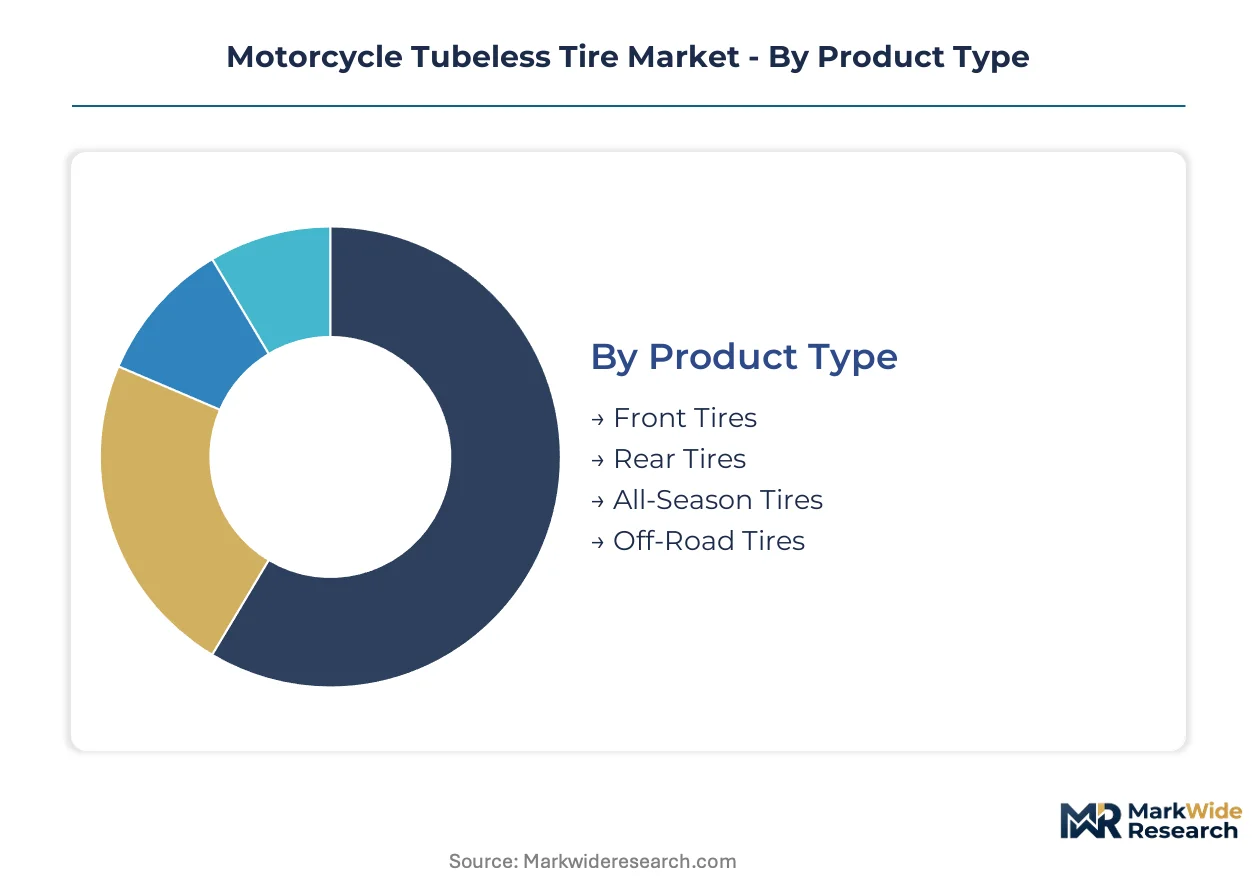
- Front Tires:Steering load concentration accelerates wear on commuter motorcycles, driving highest replacement frequency in urban density corridors like Mumbai and Jakarta. BIS AIS certification for tread depth retention shapes OEM procurement specifications for 110cc-150cc segments.
- Off-Road Tires:Knobby-tread architectures with reinforced sidewall carcasses gain traction as trail-accessible registrations climb in North America and Australia. Mixed-terrain abrasion compresses replacement cycles toward 12-15 month intervals versus traditional 18-24 month patterns.
- Rear Tires:Power transmission loads and braking torque concentrate wear on drive-wheel positions.
- All-Season Tires:Silica-dominant compounds address monsoon climates and temperature swing tolerance.
Front tires lead on scale; off-road tires lead on momentum.
Material:
Cost-performance positioning and supply chain resilience separate procurement tiers.
- Synthetic Fiber:Aramid and nylon 6.6 reinforcement displaces traditional cotton and rayon in 250cc-plus OEM specifications. East Asian chemical park concentration exposes mid-tier manufacturers to nylon 6.6 spot market volatility.
- Rubber:Halobutyl liner lamination expertise concentrates among aging technical workforces in Japan and Germany. ECHA REACH polycyclic aromatic hydrocarbon restrictions force compound reformulation across European supply chains.
- Steel:Bead wire and belt plies provide structural integrity for high-speed sport bike applications.
- Fabric:Legacy cotton and rayon architectures persist in sub-150cc commuter replacement markets.
Synthetic fiber leads on scale; rubber leads on reformulation urgency.
Vehicle Type:
Rider demographics and usage intensity segment demand across leisure and utility applications.
- Touring Bikes:Adventure and dual-sport adoption restructures fleet replacement cycles across emerging markets. Highway expansion in India accelerates tubeless fitment rates as average speeds exceed inner tube safety thresholds.
- Sport Bikes:Motorsport heritage drives premium positioning through advanced silica compound R&D. Wet-grip longevity extension redirects consumer preference toward premium tread architectures in monsoon climates.
- Cruiser Bikes:Long-haul highway duty cycles prioritize load-bearing capacity and thermal stability.
- Dirt Bikes:Trail and competition use cases demand puncture-resistant carcass construction.
Touring bikes lead on scale; sport bikes lead on technology premium capture.
Brand:
Distribution channel access and motorsport credentialing determine aftermarket capture rates.
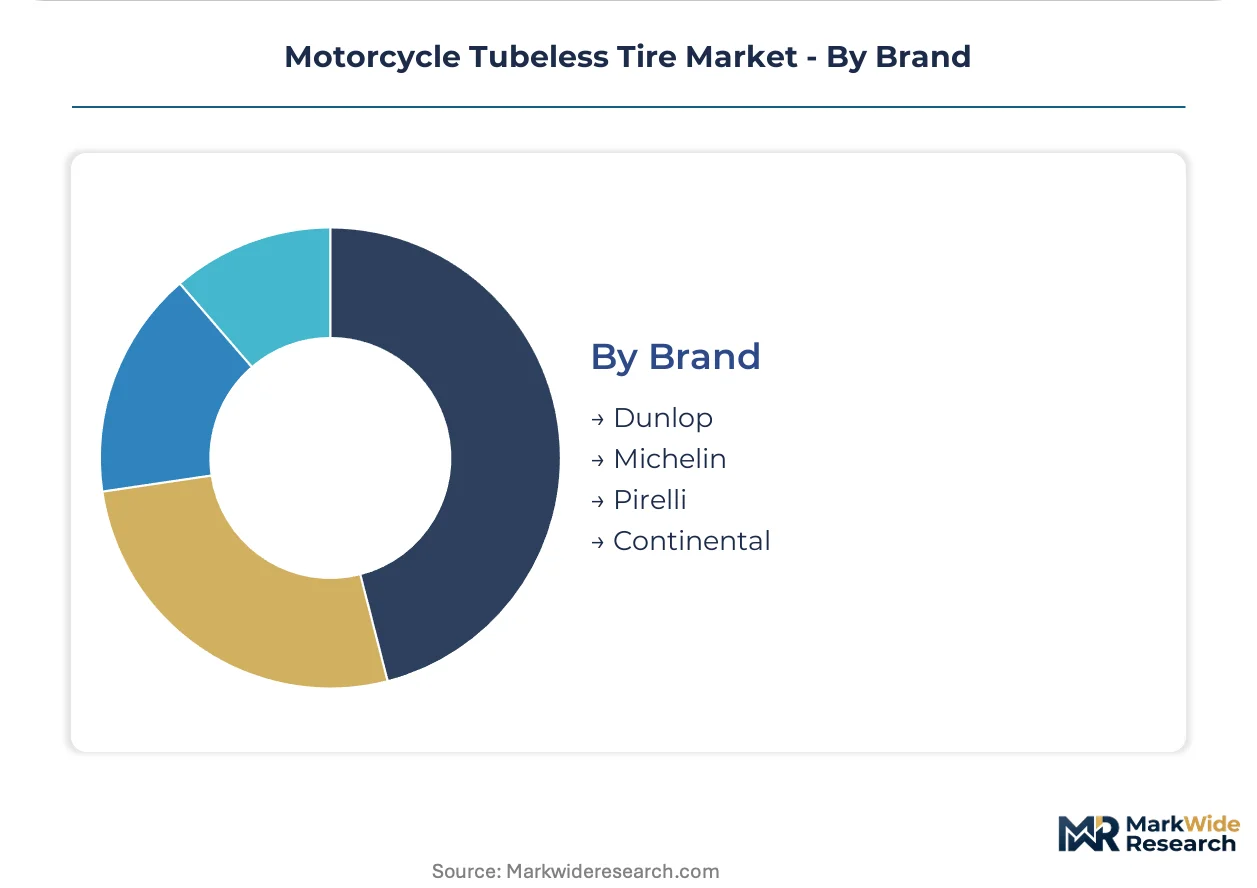
- Michelin:Advanced silica compound R&D sustains premium positioning through extended wet-grip longevity. Direct-to-workshop distribution platforms in India and Southeast Asia compress traditional wholesale channel margins.
- Pirelli:Aggressive supermoto and off-road segment focus targets European and Latin American terrain specificity. Dedicated tread patterns for Patagonia tourism corridor and Brazil rural road networks address underpenetrated trail markets.
- Dunlop:Motorsport heritage anchors sport-touring and cruiser fitment specifications.
- Continental:Automotive supplier scale supports R&D amortization across two-wheeler product lines.
Michelin leads on scale; Pirelli leads on terrain specialization momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chakan industrial corridor outside Pune anchors global motorcycle tire production capacity, concentrating halobutyl liner lamination expertise and synthetic fiber reinforcement supply chains for two-wheeler OEM fitments worldwide.
India
Two-wheeler density exceeding 800 vehicles per kilometer in Bengaluru and Mumbai accelerates replacement tire demand. BIS certification mandates under AIS standards create technical barriers favoring domestic manufacturers with established testing infrastructure. The Chakan-Talegaon belt near Pune hosts MRF, TVS Srichakra, and JK Tyre production facilities serving Maruti Suzuki and Bajaj Auto assembly plants.
Japan
High-performance sport bike fitments in Tokyo and Osaka sustain premium pricing for advanced silica compound architectures. METI industrial standards govern tire safety certification for domestic OEM supply. The Kanto region around Tokyo concentrates Bridgestone technical centers and motorsport heritage R&D operations.
Germany
ECHA REACH polycyclic aromatic hydrocarbon restrictions in tire oils force compound reformulation across European supply chains. KBA type-approval requirements shape treadwear labeling for imported motorcycle tires. The Stuttgart-Munich corridor houses Continental automotive supplier scale and advanced materials testing laboratories.
United States
EPA treadwear and fuel economy labeling requirements shape consumer comparison behavior for imported motorcycle fitments. Trail-accessible dirt bike registrations in Colorado and Utah drive knobby-tread demand. The Midwest manufacturing belt around Akron, Ohio retains legacy tire engineering expertise and materials research infrastructure.
Brazil
Expanding rural road networks and Patagonia tourism corridor traffic create white space for all-terrain tubeless variants. ANVISA and INMETRO certification requirements govern tire import standards for Mercosur markets. The São Paulo industrial zone concentrates Pirelli Latin American operations and regional distribution hubs for South American markets.
Motorcycle Tubeless Tire Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers retrofit lines for halobutyl liner lamination and synthetic fiber carcass integration. The vendor base stratifies across three tiers: integrated multinational suppliers with motorsport heritage, regional champions commanding domestic certification advantages, and specialized off-road tread pattern houses. Three strategic archetypes define competitive positioning: premium compound innovators, certification-optimized local producers, and terrain-specific niche specialists. Geographic expansion into underpenetrated trail markets and backward integration into aramid fiber supply chains represent the dominant competitive moves.
Among heritage multinational suppliers, Bridgestone, Michelin, and Pirelli exemplify distinct competitive vectors. Bridgestone anchors the motorsport-heritage archetype through technical center concentration in Japan. Michelin occupies the premium compound innovation position with direct-to-workshop distribution experiments in Indian urban density corridors. Pirelli represents terrain-specialist positioning through Latin American market development. These three names illustrate how competitive advantage separates across technology licensing, certification mastery, and regional channel control rather than converging on a single winning formula.
| Leading Market Players |
|---|
| Bridgestone |
| Michelin |
| Pirelli |
| Continental |
| MRF |
| JK Tyre |
| TVS Srichakra |
| Goodyear |
| Kenda Tire |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in India and Southeast Asia anchor regional pricing discipline through captive halobutyl liner production and workshop-direct distribution networks, compressing channel markups that multinational suppliers must absorb through compound R&D premiums.
Pricing Analysis
Distributor margin layers in traditional wholesale channels face compression from fleet-operator procurement platforms in Bengaluru and Jakarta. Three-tier pricing structure across premium, standard, and economy levels separates motorsport-credentialed silica compounds from BIS-certified commuter fitments and unbranded replacement tires. Pricing pressure stems from nylon 6.6 spot market volatility in East Asian chemical parks. Fleet operators exhibit highest price sensitivity; sport bike enthusiasts absorb premium tiers for wet-grip certification.
Supply Chain Analysis
Regional distribution centers in the Chakan-Talegaon belt near Pune feed workshop-level procurement platforms across Indian urban density corridors. Manufacturing concentrates in India, Thailand, and Indonesia for OEM fitment; Japan and Germany retain halobutyl liner lamination expertise. Aramid fiber supply draws from East Asian chemical parks, exposing mid-tier producers to input cost volatility. Tariff exposure runs through EU carbon-border adjustment mechanisms. Distribution runs through direct-to-workshop platforms and traditional multi-tier wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The motorcycle tubeless tire market functions as a stable compounder, with highway infrastructure expansion and fleet replacement cycle compression in emerging markets generating predictable volume trajectories.
For Market Incumbents: Anticipate margin erosion from synthetic fiber cost volatility by securing captive nylon 6.6 supply agreements with East Asian chemical producers. Deepen backward integration into aramid fiber supply chains before carbon-border adjustments phase in across EU tire categories. Prioritize BIS AIS certification maintenance to defend domestic Indian market share against new entrants facing 4-6 month testing queue delays. For New Entrants and Emerging Players: Workshop chains in tier-2 Indian cities offer the most penetrable channel entry point, bypassing traditional distributor markups through fleet-operator procurement platforms. Latin American trail markets present white space, particularly Brazil's rural road network and Argentina's Patagonia tourism corridor where all-terrain tubeless variants remain underdeveloped. Lead with terrain-specific tread pattern development rather than premium compound R&D to avoid direct confrontation with established silica formulation leaders. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier manufacturers with BIS certification infrastructure but limited synthetic fiber integration capability. The five-to-ten year viability window favors targets with established testing relationships and regional distribution density over pure technology plays. Watch ECHA REACH compliance timeline acceleration as the inflection signal for European market access premiums shifting toward pre-certified halobutyl liner stocks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Fiber Supply | Captive aramid and nylon 6.6 production insulates margin from East Asian chemical park volatility. |
| Direct-to-Workshop Distribution Platform Launch | Bypassing traditional wholesale channels captures replacement-cycle data in Bengaluru and Jakarta density corridors. |
| ECHA REACH Pre-Certification Investment | Early halobutyl liner compound alignment secures preferential EU market access before carbon-border adjustments phase in. |
| Latin American Terrain-Specific Product Development | Patagonia and Brazil rural road network fitments address underpenetrated trail market white space. |
| BIS AIS Certification Infrastructure Expansion | Domestic testing capacity in India compresses product launch timelines versus new entrant queue delays. |
Research Methodology
Direct dialogue with tire plant managers, OEM procurement leads at Bajaj Auto and TVS Motor, aftermarket distributors in Mumbai and São Paulo, and ECHA regulatory affairs specialists grounded qualitative findings. Secondary validation drew from BIS AIS certification databases, Automotive Research Association testing records, EPA treadwear labeling filings, and customs trade data for synthetic fiber imports. Bottom-up and top-down triangulation cross-checked volume estimates against production capacity disclosures and replacement cycle surveys.
Bottom-up modeling segmented demand across front tire, off-road, rear tire, and all-season product types, synthetic fiber versus rubber versus steel material tiers, and touring versus sport versus cruiser versus dirt bike vehicle categories. Top-down validation anchored on two-wheeler registration trends in India, highway infrastructure expansion timelines from the National Highways Authority, and fleet operator procurement platform adoption rates. CAGRs were derived from replacement interval compression patterns and tubeless fitment rate trajectories across the analysis window. Forecast inputs included ECHA REACH compliance deadline acceleration scenarios and carbon-border adjustment mechanism phase-in assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aramid fiber supply disruptions, BIS certification queue extensions, and EU carbon-border adjustment rate revisions. Outputs reflect documented assumptions regarding highway expansion pace and fleet operator platform adoption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Electric Motorsport Market
Bikes and Motorcycles
Motorcycle Fuel Hoses Market
Bikes and Motorcycles
Vietnam Bike-Sharing Market
Bikes and Motorcycles
Motorcycle Instrument Cluster Market
Bikes and Motorcycles
Global Motorcycle Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Global Motorcycle Airbag System Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Latin America Fuel Cell Bikes Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
Two Wheeler Seats Market
Bikes and Motorcycles
Emission Control Catalyst for Motorcycle Market
Bikes and Motorcycles
Motorcycle Airbag Market
Bikes and Motorcycles
Two-Wheeler Motorcycle Market