
 Bike Computer Market | 2026-2036
Bike Computer Market Size, Share, and Industry Trends Forecast 2026-2036
Bike Computer Market Analysis
CE marking under the EU Radio Equipment Directive is hardening compliance costs for wireless bike computer imports into European markets. Garmin leverages its proprietary ecosystem architecture to sustain premium positioning across GPS-enabled units. Bryton anchors its competitiveness through aggressive pricing in the Asian retail channel. Wahoo differentiates via deep integration with indoor training platforms and proprietary sensor protocols.
A bike computer is an electronic handlebar-mounted device that captures, displays, and transmits cycling performance data through integrated GPS receivers, accelerometers, and wireless transceivers operating on Bluetooth and ANT+ protocols. These units serve competitive and recreational riders by delivering real-time metrics including speed, cadence, power output, and navigational routing. GPS computers command the highest margin pools as riders prioritize mapping accuracy and third-party app connectivity. Smart computers represent the fastest-expanding category as voice integration and cellular-enabled safety features gain traction. Wired computers occupy a shrinking but defensible niche among price-sensitive commuter segments.
FCC certification governs radio frequency emissions for all bike computers sold in the United States, while Japan's METI enforces technical conformity standards on wireless telemetry devices. The EU Green Deal's cycling infrastructure commitments are channeling public investment toward commuter mobility, indirectly expanding the addressable base for navigation-focused units. Stakeholders must weigh whether to prioritize sensor hardware innovation or platform subscription revenue as the primary value capture mechanism.
Market Dynamics
Training data integration is compressing replacement cycles as competitive cyclists upgrade units to capture richer performance telemetry. Manufacturers must now architect hardware around subscription-ready platforms rather than standalone devices.
Growth Catalysts
- EU Green Deal cycling infrastructure commitments:Public investment in bicycle lanes across Germany, the Netherlands, and Denmark is expanding the commuter addressable base for navigation-focused units.
- Power meter protocol standardization:ANT+ and Bluetooth Smart convergence is eliminating sensor pairing friction, accelerating multi-device ecosystem adoption among amateur racers.
- Indoor training platform penetration:Zwift and TrainerRoad compatibility requirements are pulling hardware upgrades as riders seek seamless virtual-physical ride synchronization.
Market Restraints
- CE marking compliance cost escalation:EU Radio Equipment Directive testing requirements for wireless transceivers are adding three to six months to European market entry timelines.
- Display panel supply concentration:Transflective LCD and OLED module production clusters in Taiwan and South Korea create single-source vulnerability for mid-tier manufacturers.
- Smartphone navigation substitution:Handlebar phone mounts with waterproof cases are capturing price-sensitive recreational riders who prioritize cost over dedicated device accuracy.
Strategic Opportunities
- Cellular-enabled safety feature expansion:Automatic incident detection with emergency contact notification is opening premium upgrade paths as riders prioritize solo-ride security.
- India cycling infrastructure buildout:Metro rail bicycle integration schemes in Bangalore, Delhi, and Mumbai are creating first-time navigation device demand among urban commuters.
- Voice control integration:Hands-free route modification and metric queries during high-speed descents are differentiating premium units from smartphone alternatives.
Industry Challenges
- FCC certification timeline compression:Radio frequency emission testing backlogs for Bluetooth 5.3 and ANT+ dual-protocol devices are delaying North American product launches.
- Firmware-sensor compatibility maintenance:Legacy power meter and cadence sensor backward compatibility requirements are consuming engineering resources that could advance core platform features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bike Computer Market |
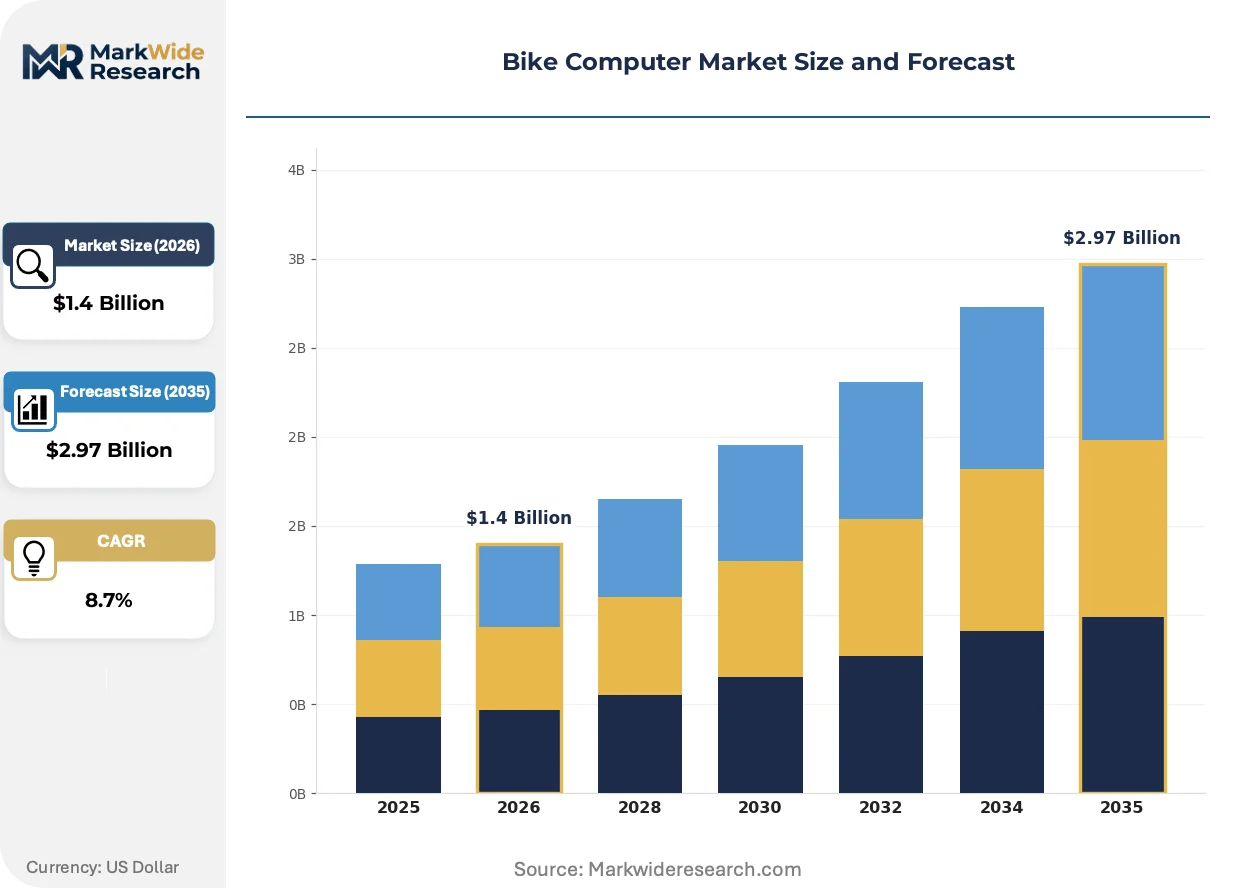
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Computers, Wireless Computers, GPS Computers, Smart Computers Technology: Bluetooth, ANT+, Wi-Fi, LCD End User: Recreational Cyclists, Competitive Cyclists, Commuters, Outdoor Enthusiasts Feature: Heart Rate Monitoring, Navigation, Route Tracking, Performance Analytics |
| Companies Covered | Bryton, Magene, Garmin, Coros, Cycplus, Wahoo, Lezyne, SRAM, Hammerhead, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bike Computer Market Emerging Trajectories
Sensor fusion architectures are redefining what riders expect from handlebar-mounted units, compressing the gap between professional training tools and consumer accessibility. Three developments are restructuring competitive positioning.
Dual-band GNSS chipsets are integrating L1 and L5 satellite signals to deliver sub-meter positional accuracy in urban canyon environments. Competitive cyclists and gran fondo participants are adopting these units fastest, replacing single-band GPS devices purchased within the past three years. This is integrating mapping precision into safety-critical features like lane-level navigation and crash reconstruction.
Japan's METI technical conformity standards for wireless telemetry devices are tightening electromagnetic compatibility testing for all bike computers sold through domestic retail channels. Domestic distributors must now submit updated documentation for firmware revisions that alter radio transmission profiles. High-end GPS computer imports face extended approval timelines, pushing manufacturers to pre-certify Japan-specific hardware variants.
Subscription service bundling is displacing perpetual-license software models across the premium segment. Riders now expect included route planning, structured training plans, and live tracking without additional fees. Germany and Switzerland show the fastest uptake of hardware-plus-subscription offerings, where annual service commitments reduce effective device purchase price sensitivity.
Bike Computer Market Segmentation
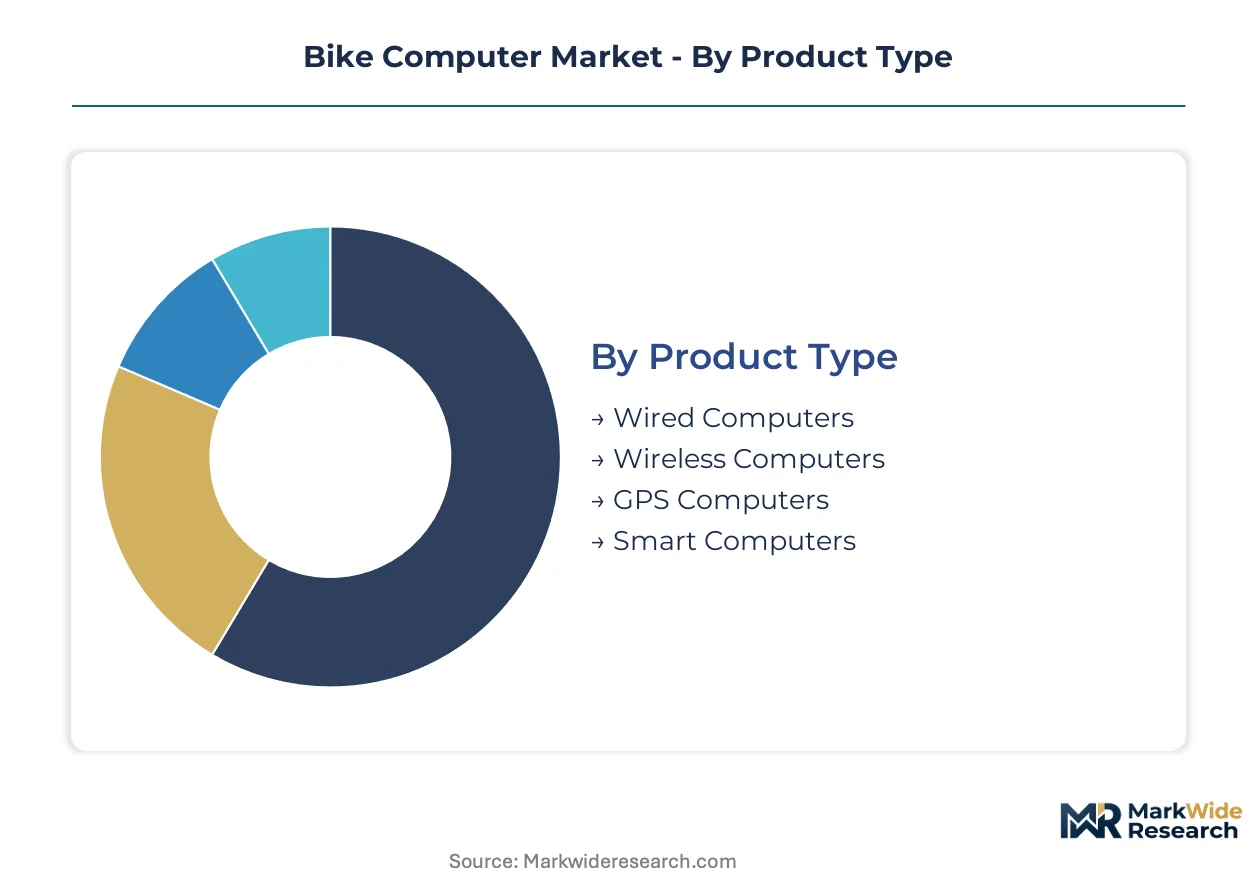
Bike computer segmentation reveals how hardware architecture choices determine integration depth with training platforms and sensor ecosystems. Manufacturers optimize around distinct connectivity protocols, display technologies, and user sophistication levels that reshape upgrade cycles and margin structures.
Product Type:
Standalone units serve casual riders seeking basic telemetry, while embedded-system designs dominate competitive cycling through deep platform integration.
- Wireless Computers:ANT+ and Bluetooth Smart transceivers enable seamless pairing with heart rate straps, cadence sensors, and power meters. Demand clusters among amateur racers in Germany and the Netherlands who prioritize multi-device ecosystem coherence over mapping capabilities.
- Smart Computers:Cellular-enabled units with voice control and automatic incident detection are gaining fastest among solo riders prioritizing safety features. These devices command premium positioning through subscription-bundled route planning and live tracking services.
- Wired Computers:Simple magnet-based wheel sensors with basic LCD readouts serve price-sensitive commuters in Indian metro regions where smartphone substitution pressure remains lowest.
- GPS Computers:Dual-band GNSS chipsets deliver sub-meter accuracy for navigation-focused gran fondo participants and bikepacking enthusiasts.
Volume placements concentrate in wireless configurations; the faster expansion belongs to smart computers with cellular safety features.
Technology:
Connectivity protocol choices determine sensor interoperability breadth and regulatory certification complexity across target markets.
- Bluetooth:Bluetooth 5.3 low-energy stacks dominate smartphone companion apps and indoor training platform synchronization. FCC certification backlogs for dual-protocol devices are compressing North American launch timelines for manufacturers.
- ANT+:Proprietary sensor protocol from Dynastream maintains entrenched position in power meter and cycling dynamics transmission. Legacy backward compatibility requirements consume substantial firmware engineering resources.
- Wi-Fi:Enables automatic ride upload and over-the-air firmware updates for connected units with minimal user intervention.
- LCD:Transflective displays balance sunlight readability against power consumption for extended battery life in remote touring applications.
Bluetooth captures the broadest install base; ANT+ retains strongest hold among competitive cyclists with legacy sensor investments.
End User:
Rider sophistication tiers separate occasional recreational users from data-intensive competitive athletes with structured training demands.
- Competitive Cyclists:Power meter integration and structured workout execution drive replacement cycles as training data granularity becomes non-negotiable. Zwift and TrainerRoad compatibility requirements pull hardware upgrades across Germany, Switzerland, and Denmark.
- Commuters:Navigation-focused demand from EU Green Deal infrastructure investments in bicycle lanes across German and Dutch urban centers. Handlebar phone mounts with waterproof cases capture price-sensitive riders prioritizing cost over dedicated device accuracy.
- Recreational Cyclists:Weekend riders seeking basic speed, distance, and time metrics with minimal configuration complexity.
- Outdoor Enthusiasts:Bikepacking and touring riders requiring extended battery life and offline mapping for remote route exploration.
Competitive cyclists generate highest per-unit revenue; commuters represent the fastest-expanding addressable base through public infrastructure investment.
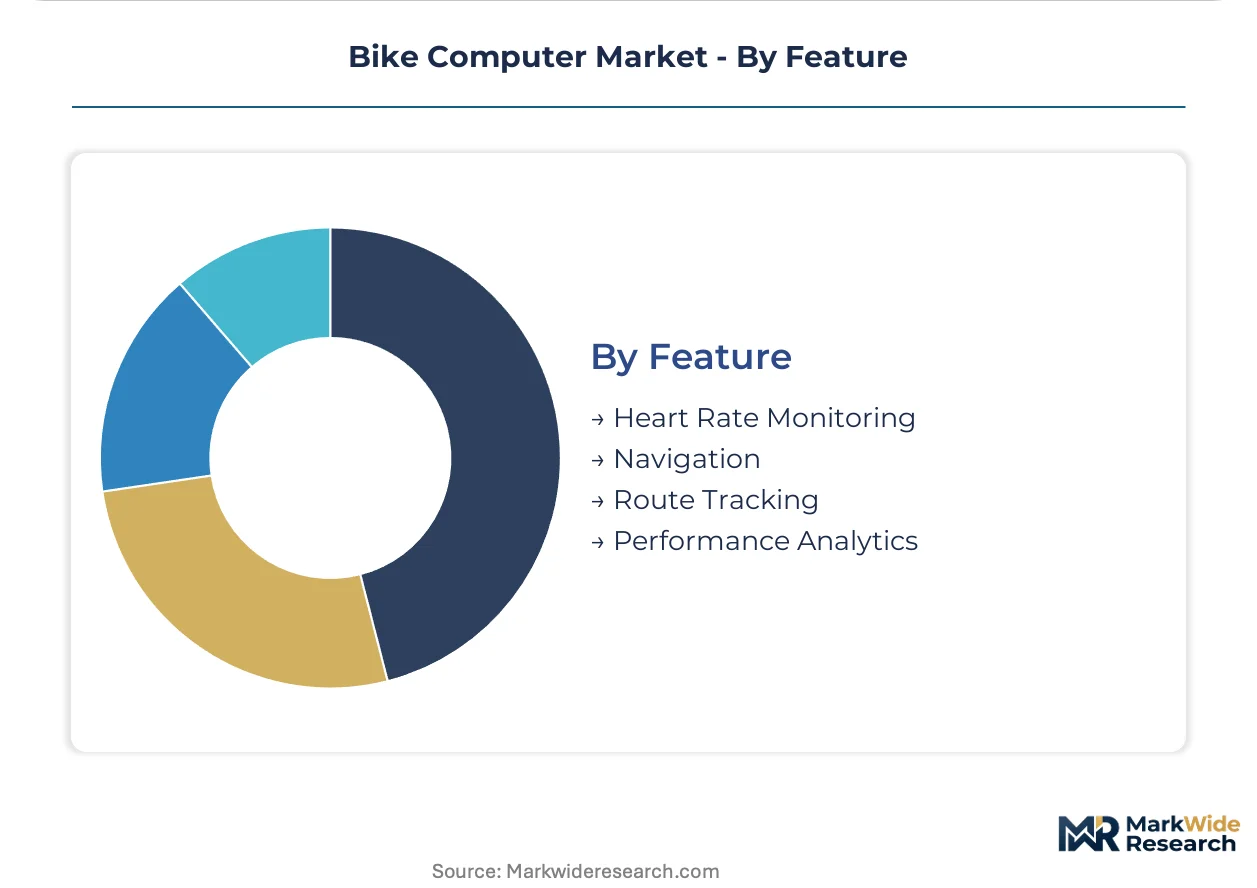
Feature:
Capability bundling strategies separate premium positioning from entry-level alternatives as subscription models displace perpetual software licenses.
- Navigation:Turn-by-turn routing with lane-level guidance and offline map storage serves gran fondo participants and bike touring segments. Dual-band GNSS adoption is compressing replacement cycles for single-band devices purchased within recent years.
- Performance Analytics:Structured training plans, recovery metrics, and training load balancing integrate with coaching platforms. Germany and Switzerland show fastest uptake of hardware-plus-subscription offerings where annual service commitments reduce purchase price sensitivity.
- Heart Rate Monitoring:Chest strap and optical wrist sensor compatibility for training zone compliance and recovery tracking.
- Route Tracking:Automatic ride logging with elevation profiles and social sharing integration for recreational rider engagement.
Navigation capabilities anchor premium tier differentiation; performance analytics features are climbing the fastest through subscription service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hsinchu Science Park special economic zone concentrates Taiwan's display panel and semiconductor fabrication capacity, anchoring supply-side gravity for bike computer OEMs sourcing transflective LCD modules and GNSS chipsets.
Germany
Federal Transport Ministry cycling infrastructure subsidies under the National Cycling Plan are expanding dedicated bicycle lane networks in Berlin, Munich, and Hamburg. CE marking compliance with the EU Radio Equipment Directive governs all wireless device imports. The Baden-Württemberg industrial cluster around Stuttgart hosts precision sensor manufacturers supplying power meter and cadence module ecosystems.
United States
Competitive cycling participation in Colorado, California, and Arizona is driving demand for dual-band GNSS units with structured training platform integration. FCC certification governs radio frequency emissions for Bluetooth 5.3 and ANT+ dual-protocol devices. The Boulder-Denver corridor concentrates specialty cycling retailers and indoor training software development operations.
Japan
METI technical conformity standards for wireless telemetry devices are tightening electromagnetic compatibility testing requirements for handlebar-mounted electronics. Domestic distributors must submit updated documentation for firmware revisions altering radio transmission profiles. The Chubu region around Nagoya maintains precision manufacturing capacity for optical sensor and accelerometer components.
Netherlands
EU Green Deal cycling infrastructure commitments are channeling public investment toward bicycle highway networks connecting Amsterdam, Rotterdam, and Utrecht. National cycling participation rates exceed 25 percent of daily commuters. The Eindhoven Brainport technology corridor hosts embedded systems engineering firms developing low-power wireless transceiver architectures.
India
Metro rail bicycle integration schemes in Bangalore, Delhi, and Mumbai are creating first-time navigation device demand among urban commuters. BIS certification requirements govern electronic product safety standards for domestic market entry. The Karnataka industrial belt around Bangalore is emerging as an assembly location for entry-level wired computer units serving price-sensitive segments.
Bike Computer Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered positioning bands. Market structure fragments across three strategic archetypes: ecosystem-integrated platform owners, sensor-protocol specialists, and price-anchored volume manufacturers. Consolidation pressure is mounting as training data integration requirements favor players with proprietary software infrastructure. Dominant competitive moves include strategic partnerships with indoor training platforms and geographic expansion through distributor network acquisition.
Within the ecosystem-integrated tier, Garmin and Wahoo occupy positions defined by proprietary platform architecture and deep indoor training software compatibility. Bryton anchors the price-competitive vector through Asian retail channel penetration. These three exemplify how hardware-plus-subscription bundling is displacing perpetual-license software models across premium positioning bands.
| Leading Market Players |
|---|
| Bryton |
| Magene |
| Garmin |
| Coros |
| Cycplus |
| Wahoo |
| Lezyne |
| SRAM |
| Hammerhead |
| Others |
Supply Flow & Price Mechanics
EU Green Deal cycling infrastructure commitments gate qualified supply for premium-tier bike computer manufacturers while compressing margin pools for non-compliant entrants. Public procurement standards for navigation devices in German and Dutch bicycle highway projects now embed CE marking under the EU Radio Equipment Directive as a baseline qualification, forcing component sourcing toward certified display and transceiver vendors.
Pricing Analysis
Short lead-time premiums now separate urgent replacement orders from standard procurement cycles in the bike computer channel. Three-tier pricing structure across premium, standard, and economy levels stratifies by sensor protocol breadth and subscription bundling intensity. Garmin and Wahoo command brand premiums through proprietary ecosystem lock-in, while price differentiation stems from certification grade and after-sales service depth. Cost compression in the wired computer tier is intensifying because Indian and Southeast Asian manufacturers are scaling assembly capacity without equivalent firmware investment. Commuters in emerging metro rail integration schemes show highest price sensitivity; competitive cyclists with structured training demands exhibit least.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for transflective LCD and OLED display modules. GNSS chipset fabrication draws from Taiwan's Hsinchu Science Park and select South Korean foundries, while accelerometer and optical sensor components feed from Japan's Chubu region around Nagoya. Regulatory restriction risk concentrates in FCC certification backlogs for Bluetooth 5.3 and ANT+ dual-protocol devices, delaying North American launches. Distribution runs through specialty cycling retailers in Germany and the Netherlands, direct-to-consumer platforms in North America, and mass-market electronics channels across Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around subscription-ready platform owners as training data integration requirements force hardware-centric competitors toward exit or acquisition. Firmware-sensor compatibility maintenance burdens and cellular certification costs are accelerating this filtration.
For Market Incumbents: Anchor defensibility through backward integration into GNSS chipset customization and captive route planning infrastructure. Acquire distributor networks in German and Dutch cycling corridors to lock navigation-focused commuter demand ahead of EU Green Deal buildout completion. Threat substitution from smartphone navigation mounts demands counter-positioning via dual-band accuracy and automatic incident detection as non-replicable differentiators. For New Entrants and Emerging Players: The mid-tier price-point gap between cellular-enabled smart computers and basic wireless units offers white-space entry. Target India's metro rail bicycle integration schemes in Bangalore, Delhi, and Mumbai with simplified navigation-first devices omitting power meter complexity. Go-to-market angle: partner with transit authorities for co-branded first-mile/last-mile commuter solutions. For Investors and Strategic Acquirers: METI technical conformity standard revisions in Japan extending firmware documentation requirements is the leading indicator that regulatory compliance scale advantages are hardening. Long-term viability favors platform-integrated hardware owners with recurring subscription revenue over transactional device vendors. Acquisition target archetype: sensor-protocol specialists with entrenched ANT+ power meter compatibility and engineering teams capable of dual-band GNSS integration. Signal to watch: indoor training platform exclusive partnership announcements as hardware pull-through mechanisms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration Partnership | Exclusive Zwift or TrainerRoad compatibility pulls hardware upgrades among competitive cyclists. |
| Cellular Safety Feature Expansion | Automatic incident detection with emergency notification opens premium upgrade paths in Germany. |
| Geographic Distributor Acquisition | Control of specialty retail channels in Netherlands and Denmark locks commuter navigation demand. |
| Dual-Band GNSS Pre-Certification | Japan-specific hardware variants bypass METI extended approval timelines for high-end imports. |
| Subscription Service Bundling | Hardware-plus-annual-commitment models reduce effective purchase price sensitivity in Switzerland. |
Methodological Framework
Document review covered customs and trade data, FCC equipment authorization databases, EU Radio Equipment Directive guidance documents, and METI technical conformity standards, complemented by interviews with product managers at GPS computer manufacturers, procurement leads at specialty cycling retailers, firmware engineering directors, and indoor training platform partnership executives. Secondary validation drew from SEC filings of diversified electronics conglomerates, Taiwan's Hsinchu Science Park industrial output reports, and German Federal Transport Ministry cycling infrastructure subsidy disclosures. Bottom-up unit shipment estimates triangulated against top-down addressable market calculations.
Cross-referencing historical replacement cycle patterns with panel input from competitive cyclists and commuter segments shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, connectivity protocol, end user sophistication tier, and regional regulatory cluster. CAGRs were derived through trend extrapolation moderated by technology substitution risk and infrastructure investment schedules. Industry-specific forecast inputs incorporated EU Green Deal implementation timelines and indoor training platform penetration curves.
Inputs from distributor inventory data and manufacturer production schedules were available through the study window; gaps in real-time smartphone navigation substitution rates introduce uncertainty bands around recreational cyclist segment sizing. Deviation in EU cycling infrastructure commitment disbursement velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Three Wheeled Motorcycle Market
Bikes and Motorcycles
Two-Wheeler Services Market
Bikes and Motorcycles
Europe Two-Wheeler Market
Bikes and Motorcycles
Cargo Bike Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
China Motorcycle ADAS Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Bike Hub Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
Motorcycle Cooling Helmets Market
Bikes and Motorcycles
Latin America Two-Wheeler Market
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
Shock Absorber Market
Bikes and Motorcycles
Electric Cargo Bikes Market
Bikes and Motorcycles
Switzerland E-Bike Market