
 Aluminum Alloy Bicycle Crankset Market | 2026-2036
Aluminum Alloy Bicycle Crankset Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Alloy Bicycle Crankset Market Insights
OEM supply contracts is tilting toward forged and CNC-machined specialists as bike brands consolidate vendor lists around quality-certified suppliers. Shimano Inc. anchors volume through integrated drivetrain ecosystems that lock in crankset placement across tier-one frame builds. SRAM LLC competes via modular BB standards and broad aftermarket reach. Rotor Bike Components differentiates through Q-ring ovalization technology and pro-team validation.
An aluminum alloy bicycle crankset is a power-transmission component that converts reciprocal leg motion into rotational drive through a spindle-mounted arm-and-chainring assembly, typically fabricated from 6061-T6 or 7075-T6 aluminum via forging or precision CNC machining to achieve strength-to-weight ratios exceeding 250 MPa yield strength. Its primary purpose is to deliver efficient torque transfer while minimizing rotating mass for competitive and recreational cycling. Double crank configurations dominate road cycling procurement where gear range optimization commands premium positioning, while mountain biking applications drive single crank growth as 1x drivetrains displace front derailleurs across trail and enduro segments. CNC machined technology captures margin concentration due to tighter tolerance control and surface finish requirements from high-end OEMs.
ISO 4210 frame and component safety standards, REACH substance restrictions on anodizing chemicals, and CE marking for bicycle assemblies collectively shape material selection and finishing processes across European and export markets. The EPA oversees wastewater discharge from aluminum machining facilities in the United States, adding compliance cost layers to domestic forging operations. Stakeholders must monitor evolving alloy recycling mandates and BB standard fragmentation as compatibility decisions determine aftermarket access and inventory risk.
Market Dynamics
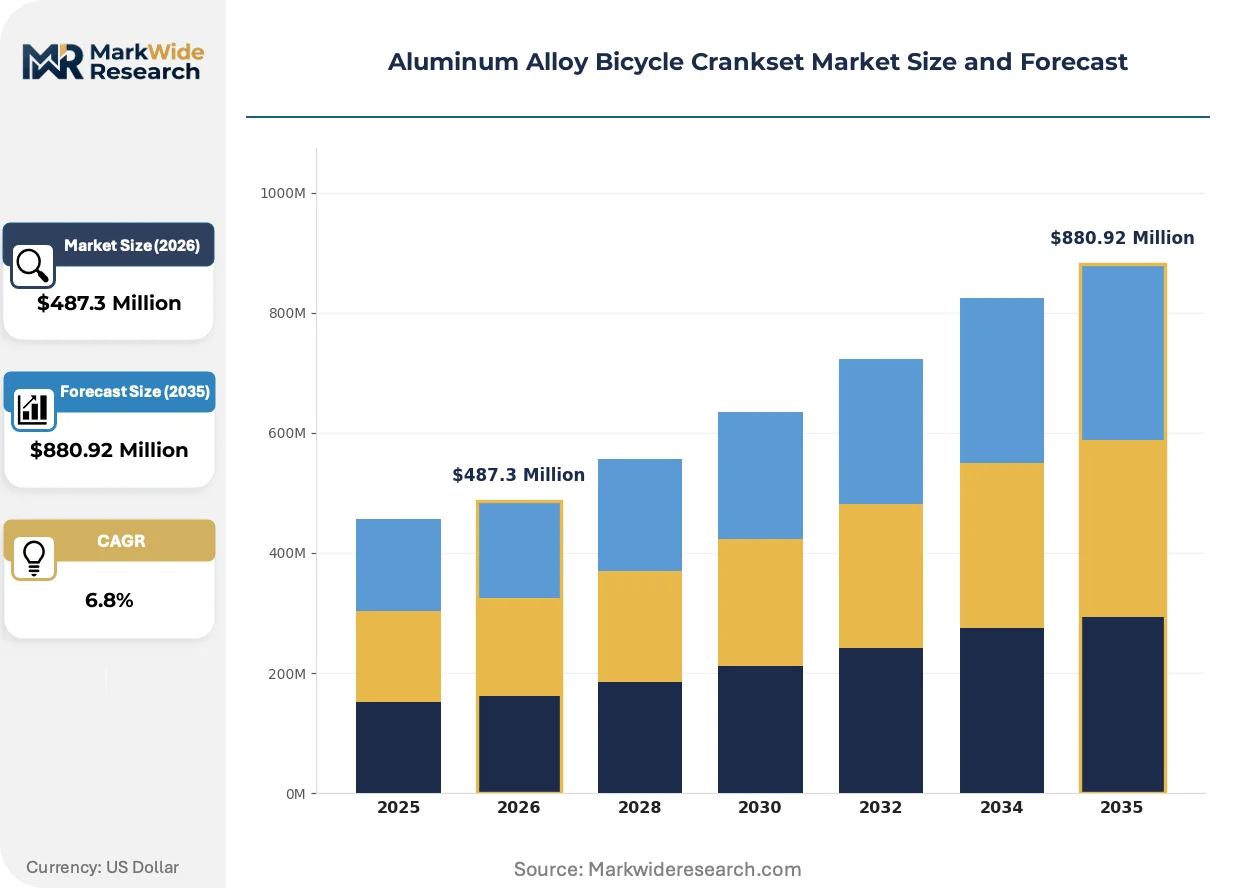
The aluminum alloy bicycle crankset market is experiencing a structural compression as 1x drivetrain architectures eliminate front derailleurs and reduce chainring counts, forcing suppliers to recalibrate forging capacity toward single-arm configurations while road cycling's double-crank heritage resists full displacement.
Growth Catalysts
- REACH substance restrictions:European anodizing chemical mandates are accelerating water-based finishing line conversions, creating first-mover advantages for certified suppliers in Germany and the Netherlands.
- Enduro racing segment:Gravity discipline cyclists specify 7075-T6 forged arms for impact resistance, pulling premium alloy volumes into mountain bike OEM specifications.
- Carbon-neutral manufacturing mandates:North American frame builders now require recycled-content aluminum certificates, tightening vendor qualification criteria toward closed-loop smelters.
Market Restraints
- Primary aluminum price volatility:LME ingot fluctuations compress forging margins when contracts lock in component pricing six months ahead.
- BB standard fragmentation:Threaded BSA, press-fit BB86, and T47 specifications fragment inventory requirements across OEM customer portfolios.
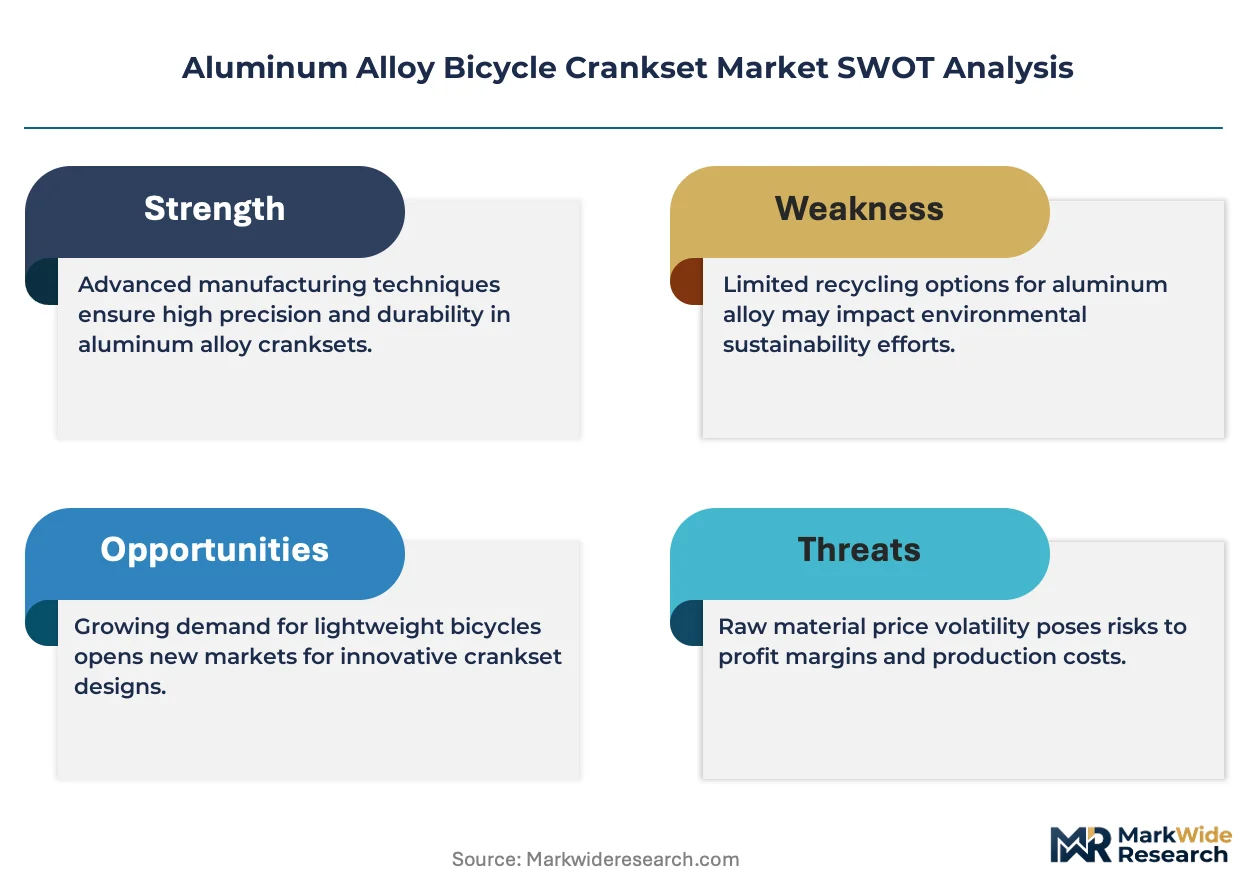
- Carbon fiber crank arm substitution:Molded composite alternatives capture ultralight road racing niches above the 250-gram threshold.
Strategic Opportunities
- E-bike motor integration:Mid-drive systems require reinforced spindle interfaces, opening specification windows for forged alloy torque arms.
- ISO 4210 certification arbitrage:Frame builders in emerging cycling markets seek pre-certified component suppliers to bypass lengthy homologation cycles.
- Direct-to-consumer channel expansion:Aftermarket crankset brands bypass distributor tiers through proprietary online fitment tools and spindle measurement apps.
Industry Challenges
- CNC programming talent scarcity:Five-axis machining centers require specialized CAM operators, constraining capacity expansion at mid-tier forges.
- REACH compliance timeline compression:Chemical substitution deadlines outpace anodizing line retrofit schedules, straining European finishing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Alloy Bicycle Crankset Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Crank, Double Crank, Triple Crank, Custom Crank End User: Professional Cyclists, Recreational Riders, Bike Manufacturers, Retail Consumers Technology: Forged, CNC Machined, Cast, Stamped Application: Mountain Biking, Road Cycling, Commuting, Freestyle Riding |
| Companies Covered | Shimano Inc., SRAM LLC, Rotor Bike Components, Praxis Works, Quarq, Truvativ, Race Face, Trickstuff, OneUp Components, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Alloy Bicycle Crankset Market Trends and Innovations
Manufacturing precision and regulatory chemistry are converging to redefine acceptable surface finish specifications and spindle tolerance bands across racing and recreational segments simultaneously.
Direct metal laser sintering prototyping is rendering obsolete traditional investment casting for complex spider-arm geometries, allowing SRAM and Rotor to iterate chainring bolt circle patterns in weeks rather than months, compressing product development cycles for limited-edition colorways and pro-team signature models.
REACH Annex XVII restrictions on chromium VI compounds in anodizing baths are forcing European finishing houses toward trivalent chromium and ceramic oxide alternatives, adding process steps that extend lead times by ten to fourteen days for CE-marked assemblies destined for German and French OEMs.
Frame builders now specify cranksets through integrated drivetrain ecosystem contracts rather than standalone component procurement, consolidating purchasing power with Shimano and SRAM while marginalizing standalone aftermarket brands that lack bottom-bracket and cassette bundling leverage, a pattern most visible in North American premium road bike assembly plants.
Aluminum Alloy Bicycle Crankset Market Segmentation
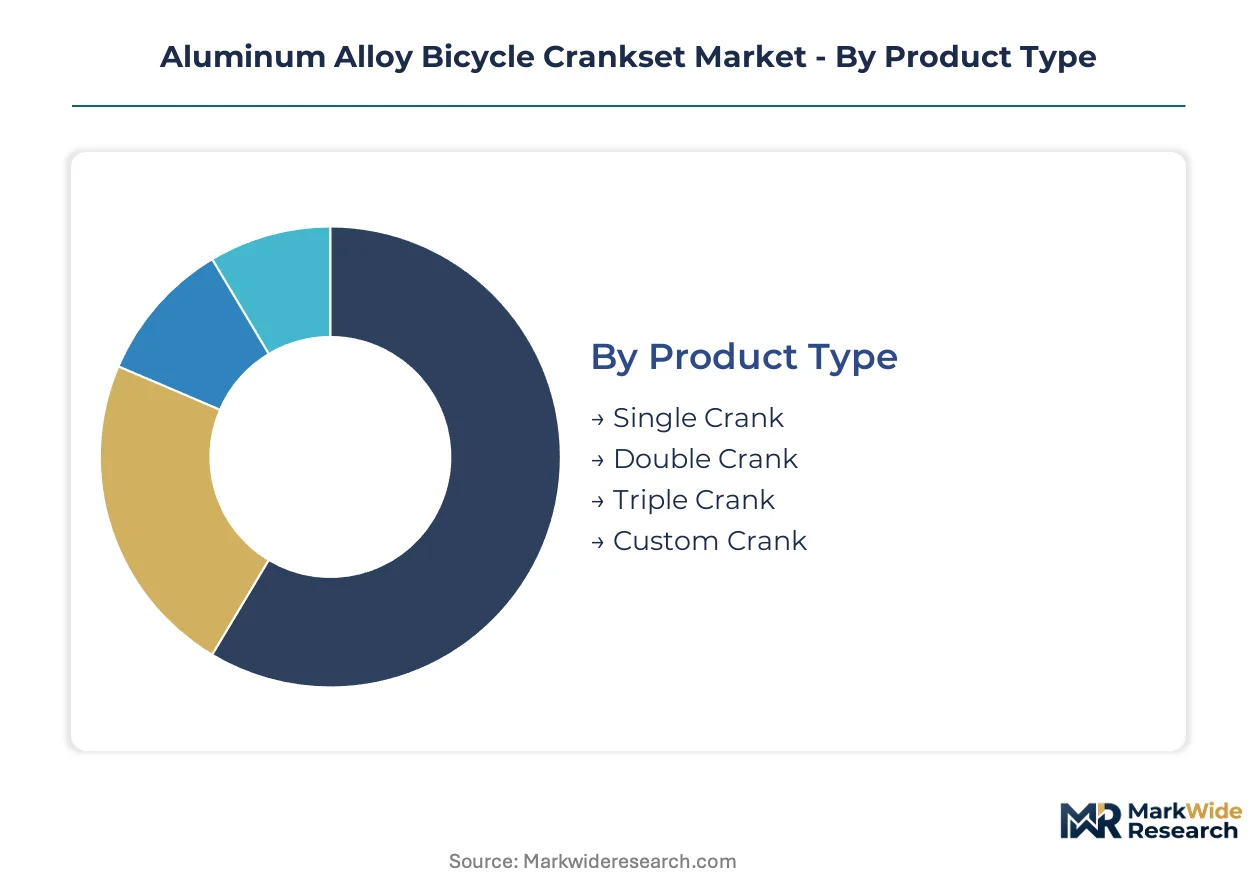
Crankset segmentation determines aftermarket service requirements and warranty exposure across cycling disciplines. Product architecture choices cascade through spindle interface standards, chainring replacement intervals, and bearing service protocols that define dealer margin structures.
Product Type:
After-sales-service intensity varies sharply by arm configuration, with double and triple cranksets demanding more frequent front derailleur adjustment and chainring bolt torque checks than simplified single-arm designs.
- Single Crank:1x drivetrain architecture eliminates the front derailleur and reduces chainring count to one, simplifying maintenance schedules and lowering total cost of ownership for trail and enduro riders. Demand concentrates in Germany and the United States where mountain bike OEMs specify 7075-T6 forged arms for impact resistance in gravity disciplines. The configuration shifts service revenue toward bottom bracket and chainring replacement rather than front shifting system overhauls.
- Double Crank:Road racing heritage maintains this configuration's dominance in premium frame builds where gear range optimization commands specification priority. Professional cyclists and domestic frame builders in Italy and France specify 6061-T6 or hybrid carbon-aluminum constructions for weight-critical stage racing applications. Front derailleur integration preserves higher service touchpoint frequency at authorized dealers.
- Triple Crank:Touring and entry-level road segments retain this configuration for maximum gear range, though OEM procurement is contracting as 1x and compact double alternatives capture specification share.
- Custom Crank:Boutique frame builders and pro-team technical partnerships commission spindle length and arm geometry modifications, generating project-based engineering revenue rather than recurring service streams.
By volume, Single Crank leads. By growth pace, Custom Crank is ahead.
End User:
Cost tier stratification separates specification authority from purchasing execution, with bike manufacturers and professional cyclists driving technical requirements while retail consumers and recreational riders respond to price-positioned finished goods.
- Professional Cyclists:UCI WorldTour teams and elite amateur racers specify cranksets through direct manufacturer sponsorship agreements, bypassing retail channels entirely. Rotor Bike Components and SRAM LLC capture this tier through pro-team validation and signature model programs.
- Recreational Riders:Weekend enthusiasts purchase cranksets as replacement components or upgrade paths through independent bicycle dealers, prioritizing compatibility verification over marginal weight savings.
- Bike Manufacturers:OEM procurement contracts consolidate around quality-certified suppliers with ISO 4210 pre-certification, locking in crankset placement through integrated drivetrain ecosystem agreements with Shimano Inc. and SRAM LLC.
- Retail Consumers:Direct-to-consumer aftermarket brands bypass distributor tiers through proprietary online fitment tools, capturing margin from spindle measurement and bottom bracket standard matching.
Procurement volume concentrates with Bike Manufacturers. Margin expansion concentrates with Retail Consumers.
Technology:
Manufacturing process selection determines tolerance control, surface finish requirements, and regulatory compliance exposure across European and North American supply chains.
- Forged:Closed-die forging aligns aluminum grain structure along stress paths, delivering yield strength exceeding 250 MPa for enduro and downhill applications where impact resistance outweighs absolute weight minimization. German and Austrian forging houses supply European OEMs while domestic operations serve North American frame builders.
- CNC Machined:Five-axis machining centers achieve tighter tolerance control and superior surface finish for high-end OEM specifications, though CAM operator scarcity constrains capacity expansion at mid-tier forges. REACH Annex XVII compliance adds process steps that extend lead times for CE-marked assemblies.
- Cast:Investment casting for complex spider-arm geometries is rendering obsolete as direct metal laser sintering prototyping compresses product development cycles.
- Stamped:Entry-level crank arms for mass-market bicycles employ this lower-cost process, sacrificing fatigue life and stiffness for price-positioned finished goods.
Forged dominates absolute volume. CNC Machined commands premium positioning.
Application:
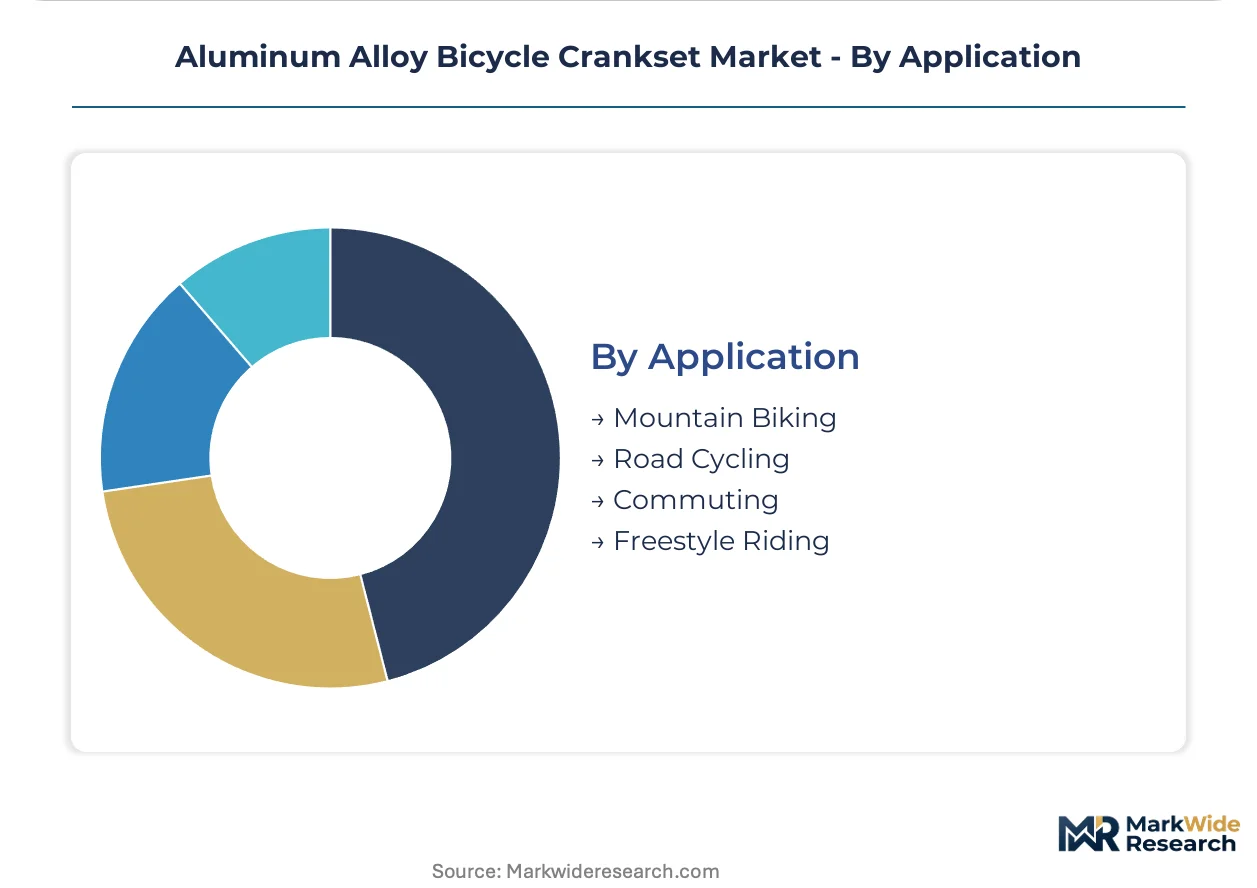
Geographic clustering of cycling culture shapes demand composition, with alpine terrain favoring mountain bike specifications and flat-to-rolling regions maintaining road cycling procurement.
- Mountain Biking:Trail, enduro, and downhill disciplines drive 1x drivetrain adoption and 7075-T6 alloy specification for impact resistance. Colorado and British Columbia frame builders concentrate procurement with forged specialists.
- Road Cycling:Stage racing and gran fondo culture in Italy, France, and Belgium sustains double-crank heritage and weight-critical engineering priorities.
- Commuting:Urban mobility programs in the Netherlands and Denmark specify durable, low-maintenance crankset configurations with enclosed chain cases.
- Freestyle Riding:BMX and dirt jump applications prioritize spindle strength and arm impact resistance over rotational mass, favoring overbuilt forged constructions.
Road Cycling retains revenue concentration. Mountain Biking shows steepest specification shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEMs command pricing premiums through REACH-certified finishing lines while Chinese forging houses compete on scale, creating a transatlantic value chain split where European suppliers capture margin and Asian producers dominate volume.
Germany
Enduro racing teams and premium frame builders in Baden-Württemberg specify 7075-T6 forged cranksets for impact resistance. REACH Annex XVII restrictions on chromium VI compounds force Stuttgart-area finishing houses toward trivalent chromium alternatives. The Black Forest cluster around Freiburg concentrates gravity-bike OEM procurement with closed-loop smelters.
United States
Colorado and Pacific Northwest frame builders expand procurement of lightweight forged cranksets as EPA wastewater discharge rules tighten machining compliance costs. The IRA's domestic content provisions incentivize recycled-aluminum certificate programs. Boulder and Fort Collins host concentrated enduro specification activity with domestic forging operations.
Japan
Keirin racing culture and road cycling heritage in the Kanto region sustain demand for double-crank configurations with tight tolerance specifications. METI's carbon-neutral manufacturing guidelines pressure suppliers toward renewable-energy smelting partnerships. Osaka-based component distributors consolidate procurement around JIS-certified quality tiers.
Italy
Stage racing and gran fondo culture in Lombardy and Veneto preserve double-crank dominance among domestic frame builders. CE marking requirements for bicycle assemblies shape anodizing process selection across Emilia-Romagna finishing networks. The Milan-Treviglio corridor anchors pro-team technical partnerships with bespoke crank geometry programs.
China
Zhejiang and Guangdong forging houses supply global OEM volume through cost-optimized 6061-T6 production. MIIT's dual carbon goals accelerate renewable-energy smelter conversions in the Yangtze River Delta. Shenzhen-area CNC machining clusters serve aftermarket brands with rapid spindle customization turnaround.
Aluminum Alloy Bicycle Crankset Market Competitive Landscape
Integrated drivetrain ecosystems and standalone forging specialists split the market between bundled specification power and component-level agility. The structure tilts toward consolidation as frame builders reduce vendor counts around quality-certified suppliers. Three archetypes dominate: full-system integrators with bottom-bracket and cassette bundling leverage; forged-component specialists with closed-loop aluminum certificates; and CNC-machined precision houses serving boutique builders. Competitive moves center on ISO 4210 pre-certification investments and direct-to-consumer channel expansion through proprietary fitment tools.
Among the integrated-system tier, Shimano Inc. and SRAM LLC anchor specification power through drivetrain ecosystem contracts that lock in crankset placement. Rotor Bike Components occupies a distinct position within the precision-specialist archetype, with its Q-ring ovalization technology representing an alternative engineering path. These three entities exemplify the strategic divergence between bundled procurement leverage and component-level technical differentiation.
| Leading Market Players |
|---|
| Shimano Inc. |
| SRAM LLC |
| Rotor Bike Components |
| Praxis Works |
| Quarq |
| Truvativ |
| Race Face |
| Trickstuff |
| OneUp Components |
| Others |
Pricing and Supply Chain Analysis
Zhejiang forging clusters anchor global crankset volume, with their capacity scale translating into downstream pricing leverage for OEM contract negotiations. Cost compression in entry-tier stamped components intensifies as Chinese 6061-T6 production scales, while REACH-certified European finishing houses capture premium positioning through trivalent chromium anodizing compliance.
Pricing Analysis
Configured-to-order spindle geometry and arm length modifications command 40-60% premiums over standard catalog configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 4210 certification grade and surface finish tolerance. Pricing pressure stems from primary aluminum LME volatility compressing forging margins on six-month locked contracts. Recreational riders through independent bicycle dealers exhibit highest price sensitivity, while professional team sponsorship agreements show lowest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for North American frame builders sourcing forged blanks. Germany, China, and Austria concentrate closed-die forging capacity for 7075-T6 and 6061-T6 alloy grades. Raw material dependencies rest on primary aluminum ingot, trivalent chromium finishing chemicals, and precision bearing assemblies. Single-source vulnerability concentrates in five-axis CNC machining centers where CAM operator scarcity constrains spindle customization turnaround. Distribution runs through integrated drivetrain ecosystem contracts with Shimano and SRAM, alongside direct-to-consumer aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber crank arm substitution above the 250-gram threshold threatens aluminum alloy incumbents in ultralight road racing segments, demanding active material-positioning defense.
For Market Incumbents: Insulate specification position through backward integration into closed-loop aluminum smelting with recycled-content certificates. Lock in OEM procurement via ISO 4210 pre-certification investments that elongate rival homologation cycles. Carbon fiber substitution in sub-250g road racing tiers represents the core threat requiring material-performance narrative reinforcement. For New Entrants and Emerging Players: Pursue direct-to-consumer aftermarket white space through proprietary spindle measurement apps and bottom bracket standard matching tools. E-bike mid-drive torque arm specifications offer the most penetrable growth vector given reinforced interface engineering requirements. Target boutique frame builders in Colorado and British Columbia with rapid CNC customization turnaround. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors forged-component specialists with REACH-certified finishing lines and OEM quality certification. Long-term viability hinges on e-bike motor integration specification wins and closed-loop aluminum certificate programs. Watch for BB standard consolidation signals as inflection indicators for aftermarket inventory risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Finishing Line Conversion | Trivalent chromium anodizing certification unlocks German and French OEM procurement. |
| Closed-Loop Aluminum Smelter Partnership | Recycled-content certificates satisfy North American carbon-neutral manufacturing mandates. |
| E-Bike Torque Arm Specification | Mid-drive motor integration opens reinforced spindle interface engineering contracts. |
| Direct-to-Consumer Fitment Tool Launch | Proprietary spindle measurement apps bypass distributor margin extraction. |
| Five-Axis CNC Capacity Expansion | CAM operator training programs alleviate mid-tier forge capacity constraints. |
Research Methodology
The analysis maps forged crankset production, CNC machining precision tiers, and finishing compliance segments, each validated through component procurement directors at frame builders, regulatory affairs leads at anodizing houses, and aftermarket distribution managers. Primary interviews with OEM specification engineers, five-axis CAM operators, and professional team technical liaiasions combined with secondary validation from EPA wastewater discharge filings, REACH Annex XVII substance restriction databases, and ISO 4210 certification registries. Bottom-up unit shipment estimates triangulated against top-down aluminum alloy consumption data across the analysis window.
Assumptions held fixed include REACH chemical substitution timelines and BB standard fragmentation persistence, while aluminum price volatility and e-bike penetration rates were modeled as sensitivity variables. Segmentation dimensions span crank configuration architecture, manufacturing process technology, cycling discipline application, and end-user procurement authority. CAGRs derived from curve-fitting historical specification shifts against projected OEM contract renewal cycles. Forecast inputs incorporated forging capacity expansion announcements and anodizing line retrofit completion schedules.
Sensitivities concentrate around primary aluminum price spike magnitude, REACH enforcement acceleration, and carbon fiber crank arm weight threshold breakthroughs. Forecasts reflect documented assumptions regarding OEM vendor consolidation pace and e-bike motor interface standardization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Malaysia Bicycle Market
Bikes and Motorcycles
Motorcycle Tubeless Tire Market
Bikes and Motorcycles
Conventional Motorcycles and Scooters Market
Bikes and Motorcycles
Motorcycle Headlight Bracket Market
Bikes and Motorcycles
Global Bicycle Derailleur Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
E-Cargo Bike Market
Bikes and Motorcycles
Motorbike Riding Gear Market
Bikes and Motorcycles
Motorcycle Shock Absorbers Market
Bikes and Motorcycles
Electric Cargo Bikes Market
Bikes and Motorcycles
Two-Wheeler Lighting Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
Cargo Bicycles Market
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
Global Motorcycles Brake Caliper Market