
 Australia E- Bike Market | 2026-2036
Australia E- Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Australia E- Bike Market Outlook
Mid-drive motor integration with torque-sensing pedal assist is reconfiguring how Australian e-bikes deliver power and handle varied terrain. Giant Manufacturing Co. leverages its vertical manufacturing scale to control component costs across the Asia-Pacific supply chain. Trek Bicycle Corporation anchors its position through specialty store distribution networks in Sydney and Melbourne. Specialized Bicycle Components differentiates via R&D intensity in custom motor firmware and battery management systems.
An e-bike is a bicycle equipped with an integrated electric motor providing supplemental propulsion, typically powered by a rechargeable lithium-ion battery pack with energy densities between 400-700 watt-hours and governed to 250 watts continuous output under Australian Design Rules. The primary commercial purpose spans personal mobility, commercial fleet logistics, and tourism operations where pedal assist reduces rider fatigue over distance. Commuter e-bikes dominate unit volume as urban Australians substitute car trips for electric-assisted cycling, while fleet operators represent the fastest-growing end user category driven by last-mile delivery contract expansion. Mountain e-bikes occupy premium margin pools through advanced suspension integration and high-torque motor specifications demanded by recreational riders in Queensland and Tasmania.
The Australian Competition and Consumer Commission enforces product safety standards for e-bike electrical systems, while state-level road authorities including Transport for NSW and VicRoads administer registration exemptions and infrastructure access rules that directly shape purchase incentives. Standards Australia publishes AS/NZS 2063 helmet requirements and AS 1518 for cycleway design, creating compliance benchmarks that manufacturers must satisfy for market access. Stakeholders must monitor pending revisions to maximum assisted speed thresholds and battery recycling mandates that will determine product configuration requirements and aftermarket service obligations.
Market Dynamics
The Australian e-bike market is being restructured by state-level active transport funding programs that subsidize cycling infrastructure and directly influence purchase decisions across metropolitan corridors.
Growth Catalysts
- VicRoads Cycling Infrastructure Grants:Victorian state funding for protected cycleways reduces perceived safety barriers and accelerates commuter adoption in Melbourne's inner suburbs.
- Last-mile delivery fleet electrification:Food delivery platforms and postal contractors are standardizing e-bike procurement to reduce fuel costs and access restricted urban zones.
- Mid-drive torque sensing:Advanced pedal-assist systems improve hill-climbing capability for riders in Brisbane and Sydney's undulating terrain, expanding addressable user base.
Market Restraints
- Lithium-ion battery cell supply concentration:Australian assemblers depend on cylindrical cell imports from Northeast Asian suppliers, exposing margins to freight volatility and currency fluctuation.
- AS/NZS 2063 helmet compliance costs:Mandatory certification for integrated lighting and communication systems adds testing overhead for premium urban commuter models.
- 25 km/h assisted speed ceiling:The Australian Design Rules throttle provision caps utility for time-sensitive commercial couriers compared to unassisted cycling on downhill gradients.
Strategic Opportunities
- Tasmanian tourism e-bike circuits:Underdeveloped rental infrastructure around Cradle Mountain and Wineglass Bay presents first-mover positioning for experience-focused operators.
- Battery recycling mandate anticipation:Proactive collection network development ahead of projected state-level e-waste regulations secures aftermarket service revenue streams.
- Specialty retail-service integration:Melbourne and Sydney independent dealers are consolidating repair capacity with direct-to-consumer brands seeking physical service presence.
Industry Challenges
- Certified e-bike technician shortage:Vocational training programs for lithium battery diagnostics and motor controller repair lag behind fleet operator maintenance demand in Perth and Adelaide.
- Multi-jurisdictional compliance mapping:Variation between Transport for NSW path access rules and Queensland road authority interpretations complicates national product specification standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia E- Bike Market |
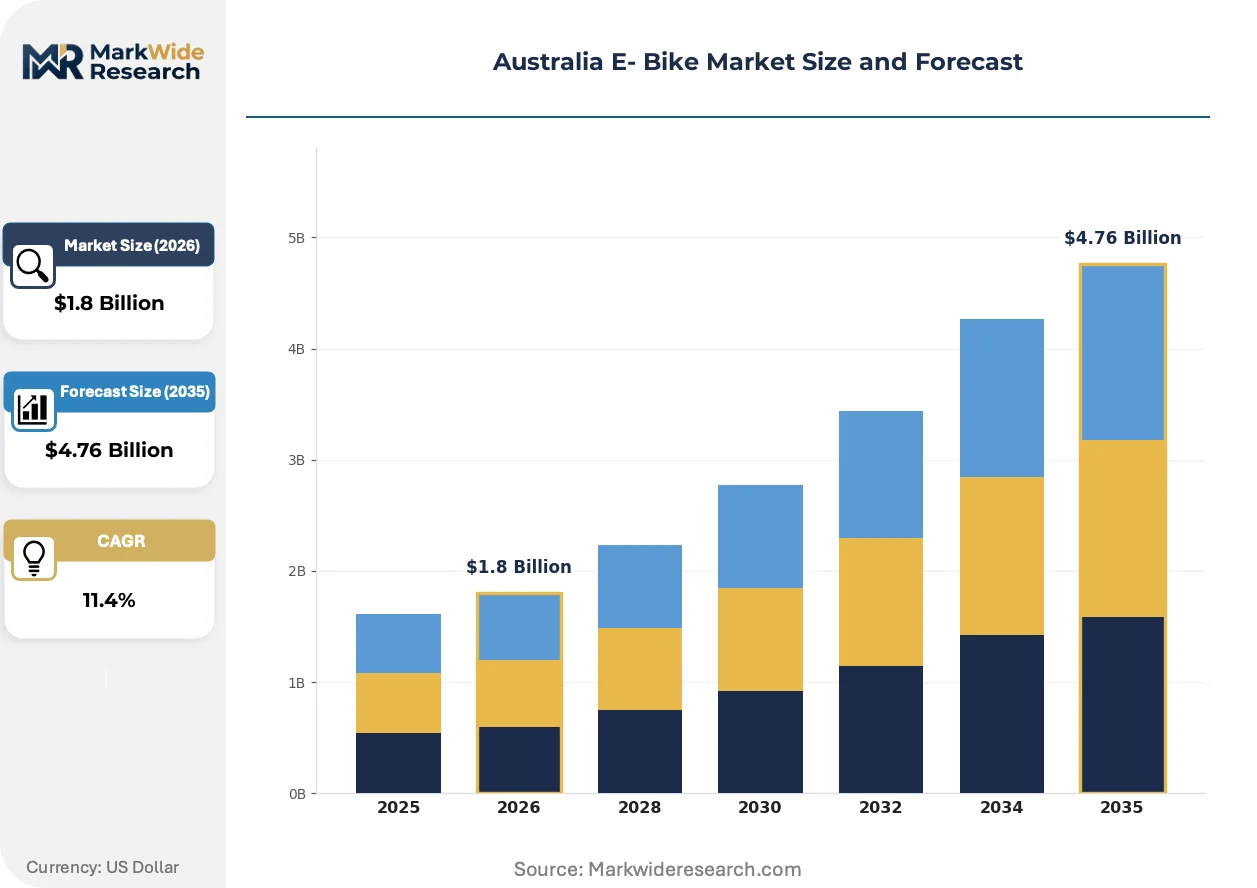
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain E-Bikes, Commuter E-Bikes, Folding E-Bikes, Cruiser E-Bikes End User: Individuals, Fleet Operators, Municipalities, Tour Companies Battery Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Lithium Polymer Sales Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Giant Manufacturing Co., Trek Bicycle Corporation, Specialized Bicycle Components, VelectriX, Zoomo, Smartmotion, Bolzzen, Kalkhoff, Tern, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia E- Bike Market Strategic Shifts
Powertrain architecture and distribution economics are undergoing simultaneous recalibration as torque-sensing systems mature and direct sales channels erode traditional retail margins.
Mid-drive motor systems with integrated torque sensors are migrating from European premium imports to Asia-Pacific sourced commuter platforms. Australian distributors are specifying these units for sub-AUD 3,000 price brackets to capture price-sensitive urban riders. This migration from hub-motor dominance is compressing service intervals and elevating aftermarket parts revenue for authorized repair networks.
The Australian Design Rules amendment permitting throttle-assisted operation up to 25 km/h is reshaping product eligibility and insurance classification. Manufacturers are reconfiguring controller firmware to satisfy both pedal-assist and throttle modes under single type approvals. This regulatory flexibility most affects commercial fleet procurement in Sydney and Melbourne, where mixed-mode operation reduces rider training costs.
Subscription-based fleet management platforms are displacing outright purchase models among last-mile delivery contractors. These arrangements bundle maintenance, battery swap access, and insurance into per-kilometer charges that align costs with revenue generation. The shift is most visible in Brisbane and Adelaide, where gig-economy logistics density supports shared asset utilization models.
Australia E- Bike Market Segmentation
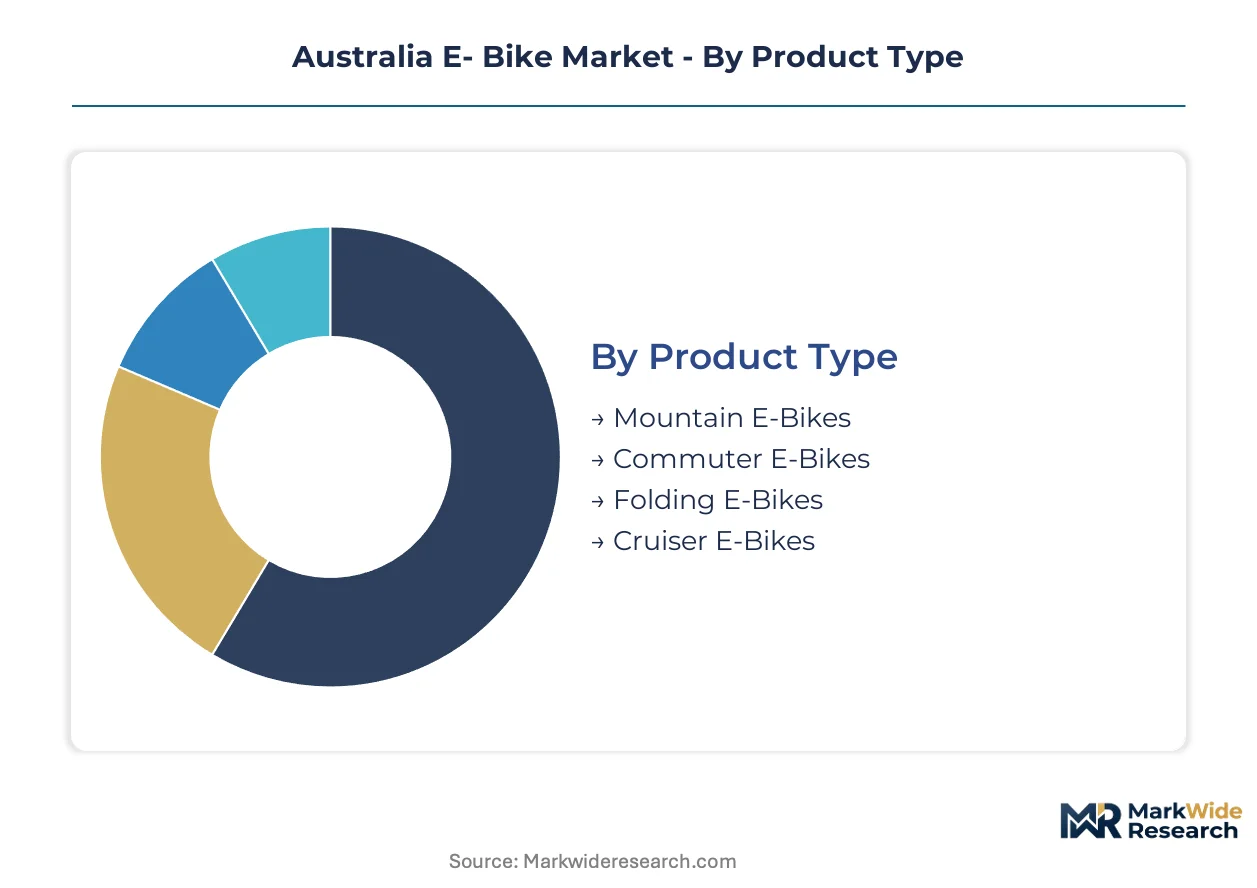
E-bike segmentation in Australia reveals distinct service intensity profiles across product architectures. Battery chemistry and motor integration complexity directly determine warranty claim frequency and technician certification requirements for each segment.
Product Type:
After-sales service intensity varies sharply across frame geometries and motor mounting positions, with full-suspension platforms demanding specialized diagnostic equipment.
- Commuter E-Bikes:Step-through frames with hub-mounted motors dominate Melbourne and Sydney urban corridors. Integrated lighting and rack systems reduce field repair complexity while rack battery configurations simplify swap logistics for fleet operators in Brisbane.
- Mountain E-Bikes:Full-suspension frames with mid-drive torque sensors command premium service margins in Queensland and Tasmania recreational markets. High-impact terrain exposure drives accelerated drivetrain wear and seasonal maintenance spikes.
- Folding E-Bikes:Hinge mechanisms and compact hub motors suit multi-modal Sydney commuters with limited storage.
- Cruiser E-Bikes:Upright geometry and throttle-dominant operation appeal to coastal retirement communities in Queensland.
By volume, Commuter E-Bikes leads. By growth pace, Mountain E-Bikes is ahead.
End User:
Procurement patterns diverge across customer categories, with fleet standardization reducing per-unit service overhead versus individual owner unpredictability.
- Fleet Operators:Food delivery platforms and postal contractors in Melbourne and Sydney standardize on single-specification procurement with centralized maintenance depots. Predictable utilization profiles enable preventive battery swap scheduling and bulk parts inventory.
- Individuals:Owner-operators across Australian capital cities drive fragmented service demand with irregular maintenance intervals and diverse product age distributions.
- Municipalities:Shared bike schemes in Perth and Adelaide specify ruggedized frames with vandal-resistant components for public dock systems.
- Tour Companies:Tasmanian and Victorian rental fleets prioritize battery range consistency over performance specifications for guided circuit operations.
Fleet Operators capture the steepest expansion trajectory. Individuals retain the largest installed base.
Battery Type:
Cell chemistry determines recycling pathway economics and fire safety protocol stringency for Australian handlers.
- Lithium-Ion:Cylindrical 18650 and 21700 cells from Northeast Asian suppliers power the majority of Australian-assembled packs. Energy density between 400-700 watt-hours supports 50-120 kilometer range ratings under AS/NZS testing protocols.
- Lithium Polymer:Pouch cell configurations enable frame-integrated battery shapes for premium Melbourne-designed commuter platforms.
- Lead-Acid:Sealed AGM variants persist in price-sensitive regional markets with lower cycle life tolerance.
- Nickel-Metal Hydride:Legacy chemistry remains in limited municipal fleet deployments with established disposal contracts.
Lithium-Ion dominates unit volume. Lithium Polymer is gaining share fastest in premium tiers.
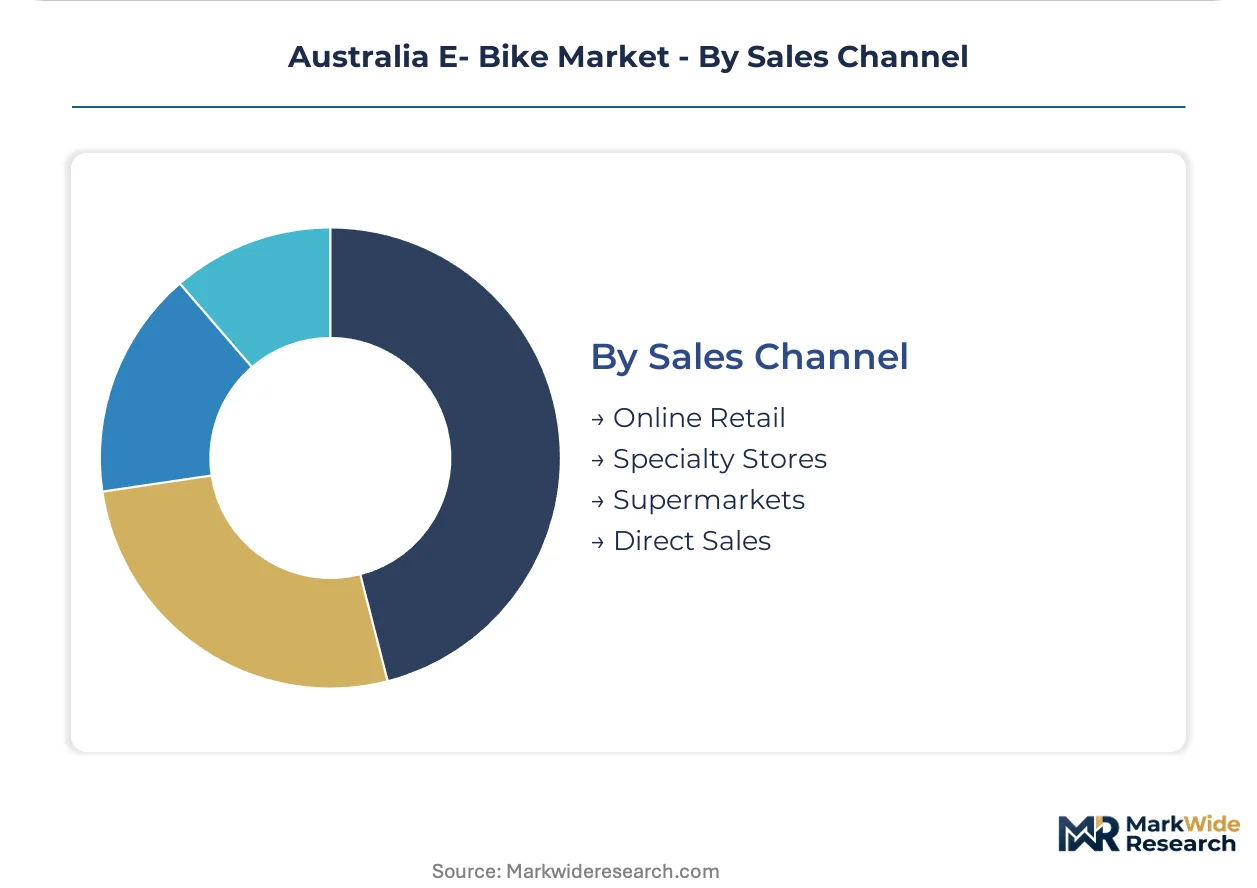
Sales Channel:
Channel selection directly shapes margin capture and customer acquisition cost structures across Australian metropolitan markets.
- Specialty Stores:Independent dealers in Sydney and Melbourne anchor test-ride conversion and authorized service relationships. Technical staff certification requirements under Transport for NSW guidelines reinforce channel stickiness for complex mid-drive platforms.
- Direct Sales:Brand-owned showrooms and mobile demo fleets in Brisbane reduce distributor margin extraction while capturing first-party customer data.
- Online Retail:Direct-to-consumer platforms with third-party assembly partnerships expand reach into Perth and Adelaide peripheral suburbs.
- Supermarkets:Mass retail distribution concentrates on sub-AUD 1,500 hub-motor models with minimal service support.
Specialty Stores leads by revenue per unit. Direct Sales is climbing the fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese component manufacturers supply motor systems to Australian assemblers, while Chinese battery cell producers dominate upstream lithium-ion supply. This trade corridor shapes regional procurement economics and service network development.
New South Wales
Sydney's dense urban core and harbor bridge cycleway expansion drive commuter e-bike procurement. Transport for NSW administers registration exemptions and shared path access rules that reduce ownership friction. Inner-west precincts including Newtown and Marrickville concentrate specialty retail and fleet operator depots.
Victoria
Melbourne's flat topography and extensive tram network integration support multi-modal e-bike adoption. VicRoads Cycling Infrastructure Grants fund protected lane construction through the inner north and CBD. Brunswick and Fitzroy host the densest concentration of independent dealers and subscription fleet services.
Queensland
Brisbane's subtropical climate and hilly terrain amplify demand for torque-sensing mid-drive systems. The Queensland Department of Transport and Main Roads maintains consistent path access rules with Victoria. Gold Coast retirement communities and Noosa tourism operators represent distinct coastal demand pools.
Western Australia
Perth's sprawling metropolitan layout and limited rail coverage position e-bikes for first-and-last-mile connectivity. The Western Australian Department of Transport oversees trial programs for commercial fleet lane access in the CBD. Fremantle port precinct and inner-suburban corridors concentrate early adoption.
South Australia
Adelaide's compact city design and mild Mediterranean climate suit year-round cycling utilization. The Department for Infrastructure and Transport coordinates with local councils on shared micromobility schemes. The Adelaide Hills recreational market and Barossa Valley tourism circuits represent premium segment opportunities.
Australia E- Bike Market Competitive Environment
On the supply side, the industry is bifurcated between vertically integrated multinational bicycle manufacturers and specialized e-bike assemblers sourcing Asia-Pacific components. The competitive terrain separates players by distribution channel control rather than manufacturing scale alone. Three archetypes dominate: global brand owners with captive retail networks, direct-to-consumer specialists with third-party service partnerships, and fleet-focused operators with subscription business models. Dominant competitive moves include exclusive distribution agreements with independent dealers and backward integration into battery pack assembly.
Within the global brand tier, Giant Manufacturing Co. and Trek Bicycle Corporation exemplify scale-driven positioning through established Asia-Pacific supply chains and Australian retail presence. Specialized Bicycle Components occupies a differentiated position emphasizing proprietary motor firmware development. These three entities anchor the premium segment while regional specialists including VelectriX and Zoomo represent fleet-service and direct-sales archetypes respectively.
| Leading Market Players |
|---|
| Giant Manufacturing Co. |
| Trek Bicycle Corporation |
| Specialized Bicycle Components |
| VelectriX |
| Zoomo |
| Smartmotion |
| Bolzzen |
| Kalkhoff |
| Tern |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Sydney container freight corridors transmit cost volatility directly into Australian e-bike landed pricing, amplifying margin compression for hub-motor commuter platforms while enabling premium-tier price differentiation for torque-sensing mid-drive systems that absorb logistics overhead through higher unit economics.
Pricing Analysis
Hub-motor commuter platforms occupy the prior-generation pricing tier below AUD 2,500, mid-drive torque-sensing systems command the current-generation band between AUD 2,500-4,500, and integrated frame-battery prototypes with custom firmware sit in the next-generation preview segment above AUD 5,000. Three-tier pricing structure across premium, standard, and economy levels segments buyer archetypes, with fleet operators driving standard-tier volume and individual enthusiasts anchoring premium-tier margins. Cost compression in the economy tier is intensifying because supermarket channel expansion sources direct-from-factory hub-motor units. Fleet operators exhibit highest price sensitivity due to per-kilometer unit economics, while tourism rental operators show lowest sensitivity given experience-bundling revenue models.
Supply Chain Analysis
Extended payment terms from Taiwanese motor suppliers and supply-chain finance facilities from Chinese battery cell producers enable Australian assemblers to manage working capital across 90-day component procurement cycles. Manufacturing concentrates in Taiwan for mid-drive motor systems, China for cylindrical lithium-ion cells, and Vietnam for frame welding and finishing. Australian assemblers draw from 18650 and 21700 cell formats, permanent magnet motor rotors, and aluminum alloy frame tubing. Single-source vulnerability persists around proprietary motor controller firmware from European suppliers. Distribution runs through Melbourne and Sydney specialty dealers with authorized service credentials under Transport for NSW guidelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian e-bike market fragmentation creates niche formation opportunity as state-level infrastructure investment divergence produces distinct procurement preferences across Victoria, New South Wales, and Queensland.
For Market Incumbents: Harden dealer network exclusivity in Melbourne and Sydney corridors against direct-to-consumer brand encroachment by securing multi-year service contracts with fleet operators. Secure captive supply of 21700 battery cells through backward integration into pack assembly partnerships with Taiwanese cell suppliers. Prioritize certification investment for AS/NZS 2063 integrated lighting compliance ahead of pending helmet mandate revisions.
For New Entrants and Emerging Players: Pursue Tasmanian tourism circuit rental infrastructure as the most penetrable geography, where Cradle Mountain and Wineglass Bay experience operators lack established e-bike fleet partnerships. Target subscription-based fleet management platforms for last-mile delivery contractors in Brisbane and Adelaide as the fastest-scaling application. Deploy mobile demo fleets with third-party assembly partnerships to bypass specialty dealer channel barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial parent companies with underperforming micromobility divisions seeking portfolio rationalization. Long-term viability favors fleet-service operators with recurring revenue models over pure retail distribution plays. Watch battery recycling mandate legislative progress across Victorian and New South Wales parliaments as the signal for aftermarket service revenue inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Exclusivity Agreements | Secures service revenue streams against direct-to-consumer erosion in Melbourne and Sydney. |
| Battery Pack Assembly Partnership | Reduces cell import cost exposure through Taiwanese supplier captive supply arrangements. |
| Fleet Subscription Platform Launch | Aligns per-kilometer pricing with gig-economy logistics demand in Brisbane and Adelaide. |
| Tourism Circuit Rental Expansion | Captures first-mover positioning in Tasmanian experience economy infrastructure gaps. |
| Certified Technician Training Program | Addresses Vocational Education and Training shortfall in Perth and Adelaide maintenance capacity. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of Australian Bureau of Statistics trade data, Department of Infrastructure transport statistics, and Standards Australia technical publications. Primary interviews engaged e-bike retail dealership owners, fleet operator procurement managers, state transport authority planning officers, and lithium battery recycling facility operators. Secondary validation incorporated Australian Design Rules amendment notices, VicRoads infrastructure grant disclosures, and Taiwan Bicycle Association export statistics. Bottom-up unit shipment estimates from specialty dealer channels triangulate against top-down market value reconstruction from import customs records.
Forecast inputs span product type segmentation across commuter, mountain, folding, and cruiser platforms; end-user categories including fleet operators, individuals, municipalities, and tour companies; and battery chemistry distinctions between lithium-ion cylindrical and lithium-polymer pouch configurations. CAGRs derive from regression analysis against state-level active transport funding trajectories and fleet electrification contract announcements. Motor system technology migration curves and subscription service adoption rates inform platform-level growth differentials across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in Australian dollar exchange rates against the New Taiwan dollar and Chinese yuan, or freight rate volatility on Asia-Pacific container corridors, would shift the trajectory. Forecasts reflect assumptions around continued state infrastructure funding and stable Australian Design Rules regulatory parameters. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Asia-Pacific Motorcycle Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
Bike Kickstand Market
Bikes and Motorcycles
Global Motorcycle Market
Bikes and Motorcycles
Maxi Scooter Market
Bikes and Motorcycles
Conventional Motorcycles and Scooters Market
Bikes and Motorcycles
Hydrobike Market
Bikes and Motorcycles
Brazil E-Bike Market
Bikes and Motorcycles
On-Road Motorcycles Market
Bikes and Motorcycles
GPS Bike Computers Market
Bikes and Motorcycles
Latin America Fuel Cell Bikes Market
Bikes and Motorcycles
China E-Bike Market
Bikes and Motorcycles
Global Carbon Fiber Bike Market
Bikes and Motorcycles
Motorbike Carburetor Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Two Wheeler Handlebars Market