
 Electric Motorcycle Market | 2026-2036
Electric Motorcycle Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Motorcycle Market Analysis
Modular battery-swappable configurations is expanding buyer choice across commuter and commercial segments. Zero Motorcycles leverages integrated powertrain design to sustain technology leadership in premium street platforms. Harley Davidson anchors brand equity among legacy riders transitioning to electric propulsion. SUR RON dominates lightweight off-road segments through aggressive pricing and direct-to-consumer channel control.
An electric motorcycle is a two-wheeled motor vehicle propelled by one or more electric motors drawing energy from rechargeable battery packs, typically achieving 0-60 mph acceleration in under four seconds with operating ranges spanning 80-300 miles depending on battery capacity and aerodynamic efficiency. Its primary commercial purpose centers on zero-tailpipe-emission urban mobility and last-mile logistics. Sportbike configurations command the highest margin pools due to performance premiumization and component intensity. Fleet operator demand within the end user dimension is growing fastest as delivery services electrify two-wheeler logistics. Solid-state battery technology remains pre-commercial but attracts disproportionate R&D allocation from established cell suppliers.
EPA tailpipe standards and NHTSA safety classifications in the United States shape product homologation timelines and import eligibility for international manufacturers. EU Green Deal mobility targets and F-Gas Regulation refrigerant constraints indirectly accelerate electric two-wheeler adoption by tightening internal-combustion alternatives. India's PLI scheme for advanced chemistry cell manufacturing reduces battery cost barriers for domestic assemblers. Stakeholders must monitor regulatory divergence between jurisdictions with divergent charging standards and subsidy eligibility rules.
Market Dynamics
Battery energy density improvements above 300 Wh/kg are compressing range anxiety and enabling platform consolidation across commuter and commercial segments. Fleet electrification mandates from logistics operators now pull forward manufacturing scale faster than consumer adoption curves.
Growth Catalysts
- India's PLI scheme for advanced chemistry cells:Domestic battery production incentives reduce import dependency and lower pack costs for assemblers in Mumbai and Chennai manufacturing clusters.
- Last-mile delivery electrification:E-commerce fulfillment networks in Jakarta, Bangkok, and Ho Chi Minh City consolidate two-wheeler procurement around swappable-battery configurations.
- Lithium-ion platform standardization:Cell-to-pack architectures eliminate redundant module housings and simplify thermal management across multiple OEM lineups.
Market Restraints
- Cobalt and lithium price volatility:Raw material input swings destabilize cell pricing contracts and compress assembler margins during commodity spikes.
- Charging infrastructure gaps:Rural India and secondary Indonesian cities lack reliable grid access for overnight fleet charging, constraining deployment outside megacity rings.
- Homologation timeline friction:Divergent NHTSA and EU type-approval requirements force parallel certification tracks that delay platform launches by 8-14 months.
Strategic Opportunities
- Vietnam's manufacturing cost base:Labor arbitrage and free-trade agreements position Ho Chi Minh City as an export hub for Southeast Asian and European markets.
- Vehicle-to-grid integration:Bidirectional charging protocols allow fleet operators to monetize stationary battery assets during peak demand windows.
- EU Green Deal mobility targets:Internal-combustion phase-out timelines create guaranteed demand pull for electric two-wheeler substitutions through 2035.
Industry Challenges
- Power electronics talent scarcity:Motor controller firmware engineers and battery management system specialists command premium wages that strain mid-tier OEM R&D budgets.
- Thermal runaway certification:UN 38.3 and UL 2271 testing protocols require destructive validation cycles that extend product development timelines.
- Dealer network retraining:Traditional internal-combustion service infrastructure lacks high-voltage safety certification and diagnostic equipment for electric powertrain maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Motorcycle Market |
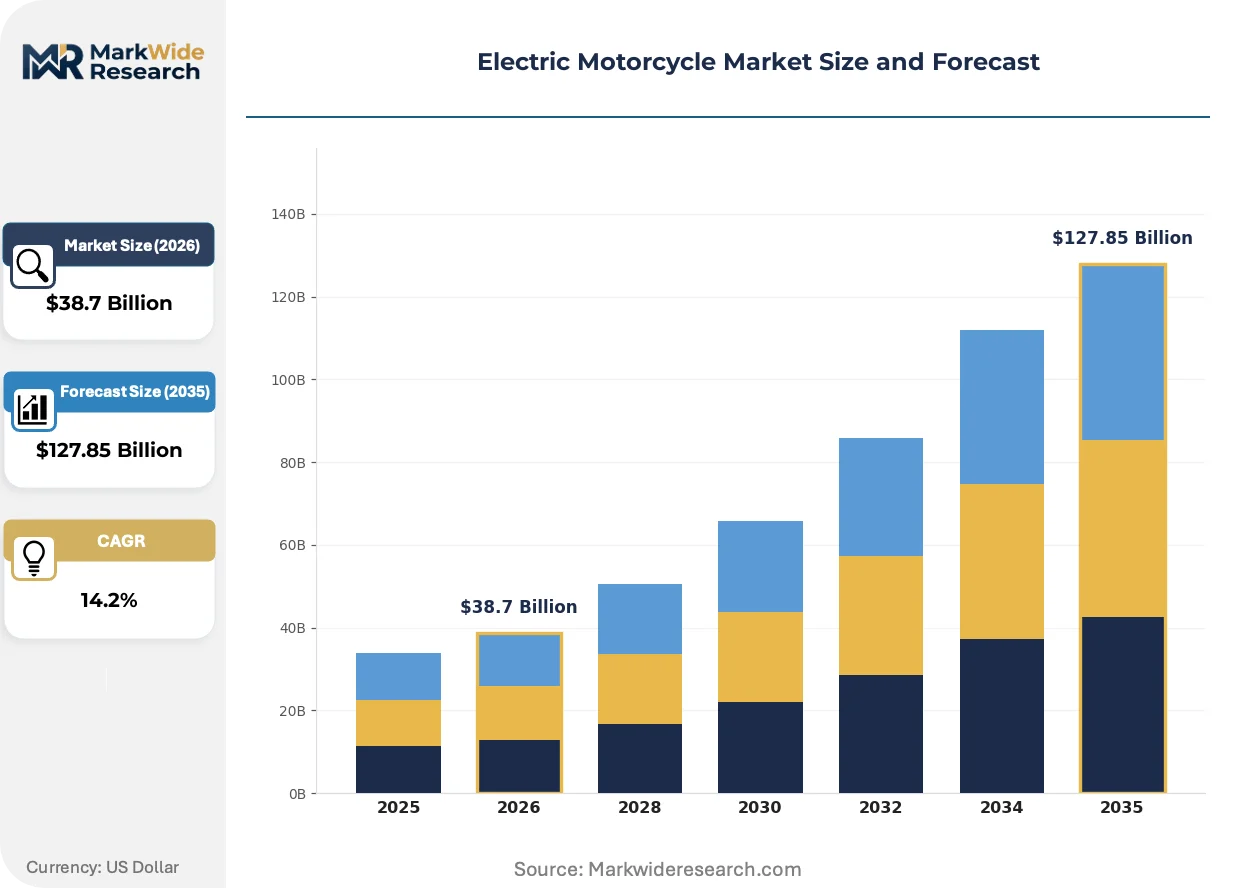
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cruiser, Sportbike, Touring, Off-road Battery Technology: Lithium-ion, Nickel-metal Hydride, Lead-acid, Solid-state End User: Individual Consumers, Fleet Operators, Delivery Services, Government Agencies Sales Channel: Online Retail, Dealerships, Distributors, Direct Sales |
| Companies Covered | LiveWire, SUR RON, Zero Motorcycles, REZON, Can-Am, Harley Davidson, Verge Motorcycles, CAOFEN, Lightning Motorcycles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Motorcycle Market Emerging Trajectories
Silicon-anode chemistries and solid-state prototyping are compressing the performance gap between electric and combustion motorcycles. These material shifts reshape competitive positioning around energy density rather than engine displacement.
Silicon-dominant anode formulations are overtaking graphite architectures in premium platform development. Cell manufacturers in South Korea and Japan now qualify 500-cycle silicon-blend cells for sportbike applications. This chemistry transition is overtaking incumbent graphite supply contracts and forcing cathode suppliers to recalibrate matching formulations.
The EU F-Gas Regulation constrains refrigerant choices for battery thermal management systems. Manufacturers must redesign cooling loops around CO2 or hydrocarbon alternatives before 2027 enforcement windows. Sportbike and touring segments face the steepest redesign costs due to higher continuous power dissipation requirements.
Fleet procurement now favors battery-as-a-service subscriptions over upfront pack purchases. Logistics operators in Bengaluru and São Paulo shift capital expenditure to operating expenditure models. This financing rotation concentrates negotiating power with swap-network providers and decouples vehicle margins from energy storage economics.
Electric Motorcycle Market Segmentation
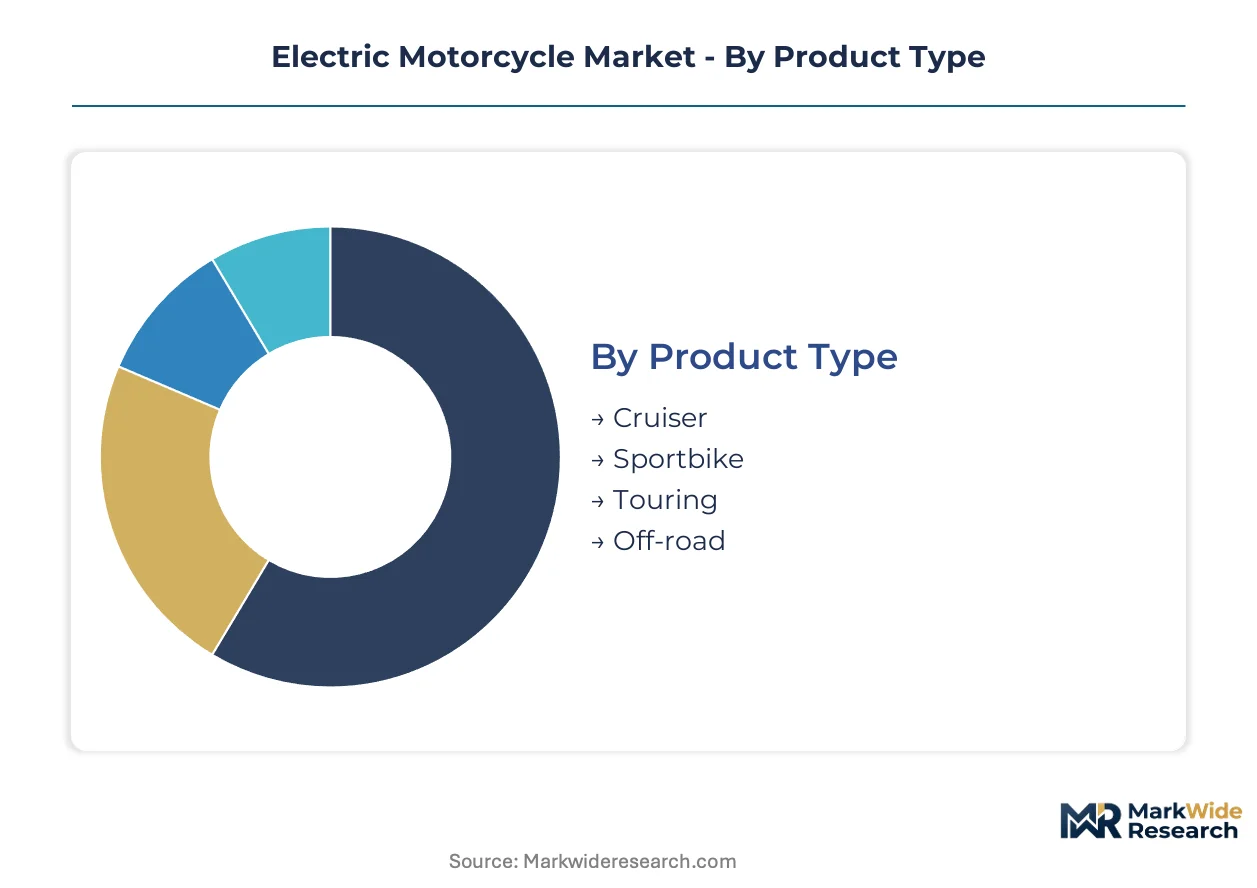
Electric motorcycle segmentation reveals divergent technology requirements across use cases. Battery chemistry and powertrain configuration choices cascade through product positioning, procurement economics, and service infrastructure investments.
Product Type:
Performance specifications and range requirements vary sharply across riding disciplines and duty cycles.
- Cruiser:Low-slung frame geometry prioritizes torque delivery at urban speeds over aerodynamic efficiency. Harley Davidson and legacy marques target aging rider demographics in the United States transitioning from internal-combustion heritage models.
- Sportbike:Aggressive ergonomics and continuous power dissipation demands strain thermal management architectures. Cell-to-pack designs with silicon-anode chemistry dominate premium platform development for track-day and canyon-carving applications.
- Touring:Extended-range configurations require 15+ kWh packs that challenge chassis weight distribution. Highway-focused aerodynamics and fast-charging compatibility shape battery supplier selection for cross-country routes.
- Off-road:Lightweight construction favors removable battery packs for trailhead swapping. SUR RON and Chinese direct-to-consumer brands concentrate volume in European and North American recreational markets through aggressive pricing.
Cruiser leads on scale; Sportbike leads on momentum.
Battery Technology:
Cell chemistry selection determines energy density, cycle life, and thermal runaway risk profiles.
- Lithium-ion:NMC and LFP formulations dominate current production with 250-300 Wh/kg energy density. South Korean and Japanese cell suppliers qualify 500-cycle silicon-blend variants for high-discharge sportbike applications.
- Solid-state:Ceramic electrolyte prototypes promise 400+ Wh/kg density with reduced fire risk. Toyota and QuantumScape attract disproportionate R&D allocation despite pre-commercial manufacturing scale.
- Nickel-metal Hydride:Mature chemistry persists in cost-sensitive commuter segments with lower energy density tolerance. Legacy hybrid vehicle supply chains provide residual volume for emerging market assemblers.
- Lead-acid:Heavy, low-cycle-life technology occupies replacement markets and ultra-low-cost conversions. India's secondary cities and rural Indonesia retain residual demand for retrofit applications.
Lithium-ion leads on scale; Solid-state leads on momentum.
End User:
Procurement economics and utilization patterns reshape vehicle specification and financing structures.
- Fleet Operators:Battery-as-a-service subscriptions convert capital expenditure to operating expenditure. Logistics networks in Bengaluru and São Paulo consolidate procurement around swappable-battery configurations with standardized pack dimensions.
- Delivery Services:High-utilization duty cycles demand rapid charging or hot-swappable architectures. Grab, Gojek, and regional platforms in Jakarta and Ho Chi Minh City electrify two-wheeler fleets under urban emissions mandates.
- Individual Consumers:Range anxiety and charging infrastructure gaps constrain adoption outside megacity cores. Premium positioning focuses on acceleration performance and connected features rather than total cost of ownership.
- Government Agencies:Municipal police and postal services drive standardization through volume procurement. India's state transport utilities pilot electric two-wheeler integration into public mobility networks.
Fleet Operators lead on scale; Delivery Services lead on momentum.
Sales Channel:
Channel structure determines margin capture, customer education burden, and aftermarket service attachment.
- Direct Sales:Manufacturer-controlled experience centers bypass dealer markups in premium segments. Zero Motorcycles and Rivian-style entrants invest in high-voltage safety training for direct service staff.
- Dealerships:Traditional motorcycle retail networks require extensive retraining for electric powertrain diagnostics. Harley Davidson leverages existing floor traffic for LiveWire transition while subsidizing charger installation.
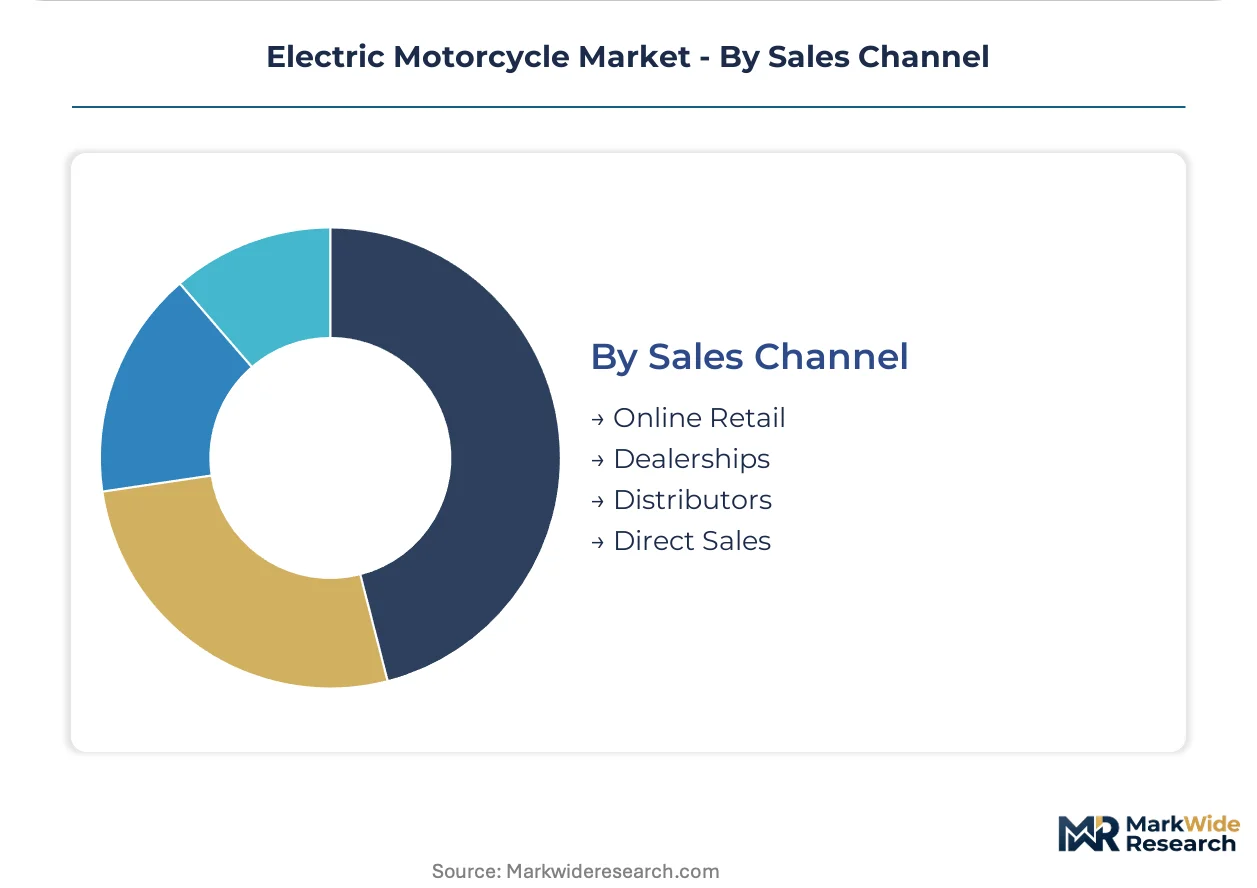
- Online Retail:Direct-to-consumer platforms enable aggressive pricing for lightweight off-road segments. SUR RON and Chinese brands dominate this channel with minimal physical presence in target markets.
- Distributors:Regional wholesalers manage import logistics and homologation compliance for smaller OEMs. Southeast Asian markets rely on distributor networks to navigate fragmented national type-approval requirements.
Dealerships lead on scale; Direct Sales leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric motorcycle manufacturing first scaled in Japan and Italy through internal-combustion heritage brands experimenting with electric powertrains. Production now concentrates in four countries spanning regulatory environments from subsidy-heavy emerging markets to emissions-constrained developed economies.
India
Fleet electrification mandates from delivery platforms and logistics operators drive procurement volume. The PLI scheme for advanced chemistry cell manufacturing reduces import dependency for battery packs. Manufacturing clusters in Mumbai and Chennai assemble swappable-battery platforms for urban commercial deployment.
United States
EPA tailpipe standards and NHTSA safety classifications shape product homologation timelines for international entrants. Premium positioning targets aging rider demographics transitioning from heritage internal-combustion brands. California's ZEV program and state-level incentives accelerate coastal adoption ahead of national curves.
Germany
EU Green Deal mobility targets and the F-Gas Regulation constrain refrigerant choices for battery thermal management. KBA type-approval requirements force parallel certification tracks with NHTSA protocols. Industrial concentration in Baden-Württemberg hosts power electronics suppliers serving premium sportbike platforms.
Vietnam
Ho Chi Minh City anchors Southeast Asian manufacturing cost advantages through labor arbitrage and free-trade agreement access. Domestic logistics operators consolidate procurement around swappable-battery configurations for last-mile delivery. Export positioning targets European and regional Southeast Asian markets with tariff-advantaged production.
Indonesia
Jakarta's urban emissions mandates accelerate two-wheeler fleet electrification for ride-hailing and delivery platforms. Secondary cities outside Java lack reliable grid access for overnight fleet charging, constraining deployment geography. Government procurement pilots for postal and municipal services drive standardization through volume commitments.
Electric Motorcycle Market Vendor Landscape
The competitive structure tilts toward heritage motorcycle manufacturers and direct-to-consumer specialists rather than consolidated volume players. Tiered positioning separates premium performance platforms from cost-optimized commuter segments. Two strategic archetypes dominate: legacy marques leveraging brand equity for rider transition, and lightweight specialists controlling channel economics through online retail. Competitive moves concentrate on battery-as-a-service financing rotation and geographic expansion through distributor networks.
Within the heritage-transition archetype, Harley Davidson and Zero Motorcycles occupy positions bridging internal-combustion loyalty with electric propulsion adoption. SUR RON exemplifies the direct-to-consumer specialist model, anchoring lightweight off-road segments through aggressive pricing and minimal physical retail presence. These three represent contrasting paths to market access without overlapping customer segments or distribution infrastructure.
| Leading Market Players |
|---|
| LiveWire |
| SUR RON |
| Zero Motorcycles |
| REZON |
| Can-Am |
| Harley Davidson |
| Verge Motorcycles |
| CAOFEN |
| Lightning Motorcycles |
| Others |
Supply Flow & Price Mechanics
Battery-as-a-service financing specialists backed by private-equity rollups now control pricing discipline across fleet procurement channels. Their ownership concentration compresses assembler margins while redirecting value capture toward swap-network operators and cell suppliers.
Pricing Analysis
Subscription-based battery leasing dominates commercial segments while three-tier pricing structure across premium, standard, and economy levels governs consumer sales. Price differentiation hinges on certification grade—UN 38.3 and UL 2271 validation carries material premiums—and volume scale for fleet contracts. Cost compression in economy commuter tiers is intensifying because Chinese direct-to-consumer brands bypass dealer markups. Delivery services exhibit highest price sensitivity; sportbike buyers tolerate premium positioning for silicon-anode performance.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles manage hub-and-spoke patterns for battery pack logistics. Manufacturing concentrates in China, South Korea, and Japan for cell production, with Vietnam and India expanding final assembly. Raw material dependencies span lithium carbonate, cobalt sulfate, and rare-earth magnets for motor assemblies. Single-source vulnerability in refined cobalt processing from the Democratic Republic of Congo elevates disruption risk. Distribution runs through distributor networks in Southeast Asia and direct-to-consumer platforms for off-road segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric motorcycle market functions as a stable compounder anchored by fleet electrification mandates that institutionalize replacement demand across logistics networks.
For Market Incumbents: Acquire battery management system firmware capabilities to defend against silicon-anode specialists eroding thermal management advantages. Secure captive lithium supply through offtake agreements with Australian and Chilean miners. Expand Chennai and Ho Chi Minh City assembly capacity to match delivery-service procurement consolidation. For New Entrants and Emerging Players: India's PLI scheme for advanced chemistry cells opens a window for domestic pack assembly without import tariff exposure. Target Bengaluru and Jakarta fleet operators with swappable-battery platforms priced below legacy OEM service bundles. Pursue distributor partnerships rather than direct retail buildout to accelerate homologation compliance. For Investors and Strategic Acquirers: Valuations sit cheapest among power electronics specialists with motor controller IP and limited brand recognition. Five-to-ten-year viability favors asset-light battery-as-a-service platforms over capital-intensive manufacturing. Monitor silicon-anode cycle-life announcements from South Korean cell suppliers as inflection signal for chemistry transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cell offtakes with LG Energy Solution or Samsung SDI secure NMC supply for sportbike platforms. |
| Swappable-Battery Network Partnership | Alliances with Gogoro or Sun Mobility accelerate fleet deployment in Indian and Southeast Asian megacities. |
| Solid-State R&D Investment | QuantumScape and Toyota partnerships position premium OEMs for post-lithium-ion energy density leaps. |
| Direct-to-Consumer Channel Launch | SUR RON's online retail model demonstrates margin capture without dealer infrastructure overhead. |
| Vehicle-to-Grid Integration Program | Bidirectional charging protocols with FERC-compliant utilities monetize fleet battery assets during peak demand. |
Methodological Framework
Coverage spans India, Vietnam, Indonesia, Germany, and the United States, with primary inputs from each market cluster. The research combines interviews with fleet procurement managers, battery supplier commercial leads, OEM platform engineers, and thermal management specialists with secondary validation. Sources include EPA homologation filings, EU type-approval databases, India's PLI scheme disclosures, and customs trade records for lithium-ion cell imports. Bottom-up unit economics triangulate against top-down mobility electrification targets.
Granularity extends to product-type level for cruiser, sportbike, touring, and off-road configurations, with battery technology and end-user segmentation modeled separately. CAGRs derive from logistic-operator procurement curves, consumer adoption elasticity, and cell cost decline trajectories. Forecast inputs incorporate silicon-anode qualification timelines and F-Gas Regulation thermal system redesign costs.
Revisions become necessary when solid-state manufacturing scale accelerates, cobalt supply disruptions exceed six-month duration, or NHTSA-EU regulatory divergence widens homologation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Brazil Electrically Powered Hydraulic Steering Market
Electric Motor
Implant Motors Market
Electric Motor
Motor Gear Unit Market
Electric Motor
Brush Motor Control Unit Market
Electric Motor
Automotive Hub Motors Market
Electric Motor
Automotive Wiper Motor Market
Electric Motor
EV Traction Motor Control Unit Market
Electric Motor
Traction Motor Core Market
Electric Motor
Automotive Power Steering Motor Market
Electric Motor
Large Synchronous Motor Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
Global Automotive Onboard Charger Market
Electric Motor
Europe Alternating Current (AC) Motor Market
Electric Motor
Global Automotive Motor Market
Electric Motor
UAE Electric Motor Market
Electric Motor
Trolling Motor Market